
 Retinal Surgery Devices Market | 2026-2036
Retinal Surgery Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Retinal Surgery Devices Market Intelligence
High-definition 3D visualization capability is redrawing competitive benchmarks in retinal surgery devices. Alcon Inc. leverages its integrated surgical platform to dominate premium ophthalmology suites across North America. Carl Zeiss Meditec AG anchors its position through precision optics and digital workflow integration. Bausch + Lomb competes aggressively on cost-engineered consumables and broad distribution reach.
Retinal surgery devices encompass precision instruments, laser systems, and visualization platforms engineered for sub-millimeter manipulation of vitreoretinal tissue under microscopic guidance, typically operating at resolutions below 10 microns with integrated illumination and image-guided navigation. These systems enable therapeutic intervention for retinal detachment, diabetic retinopathy, macular hole, and vitreous hemorrhage through minimally invasive transconjunctival approaches. Laser systems command the largest revenue pool due to recurring disposable attachments and service contracts, while microincision technology generates the fastest procedural growth as surgeons transition from 20-gauge to 25- and 27-gauge instrument platforms. Visualization systems concentrate margin capture among manufacturers with proprietary heads-up display ecosystems that lock in hospital capital budgets.
FDA 510(k) premarket notification requirements govern device clearance timelines and clinical evidence standards for US market entry, while EU MDR technical documentation and post-market surveillance obligations extend compliance costs for European commercialization. Japan's PMDA enforces stringent quality management system audits that filter out smaller entrants. Stakeholders must weigh regulatory capital requirements against the procedural volume upside from aging-related retinal disease prevalence.
Market Dynamics
The transition from 20-gauge to 25- and 27-gauge microincision platforms is compressing procedure times and recovery windows, forcing capital equipment refresh cycles across hospital ophthalmology departments and ambulatory surgical centers.
Growth Catalysts
- EU MDR compliance deadlines:Post-market surveillance obligations are accelerating product standardization and consolidating vendor relationships among European hospital procurement consortia.
- Diabetic retinopathy procedural volumes:Rising diabetes prevalence in aging populations across the United States, Germany, and Japan is expanding addressable patient pools for vitrectomy and laser photocoagulation.
- Heads-up display ecosystems:Proprietary visualization platforms are locking in hospital capital budgets through integrated surgical workflow software and disposable attachment recurring revenue.
Market Restraints
- Single-source precision optics:German and Japanese optical component suppliers concentrate supply for high-resolution surgical microscopes, creating vulnerability to regional production disruptions.
- FDA 510(k) clinical evidence thresholds:Premarket notification requirements for novel laser wavelengths extend clearance timelines and inflate regulatory capital deployment for US market entry.
- Reusable instrument reprocessing:Hospital sterilization departments favor reprocessed 20-gauge instrument sets over single-use 27-gauge disposables, compressing per-procedure revenue for manufacturers.
Strategic Opportunities
- India's tier-2 city hospital networks:Underpenetrated retinal surgery infrastructure in secondary metropolitan centers offers first-mover positioning for portable laser systems.
- Tele-ophthalmology pre-screening integration:Remote diagnostic platforms are funneling confirmed surgical candidates into ambulatory centers, shortening patient acquisition cycles.
- Japan PMDA quality management incentives:Streamlined audit pathways for manufacturers with ISO 13485 certification reduce time-to-market for next-generation visualization modules.
Industry Challenges
- Vitreoretinal surgeon training pipelines:Fellowship program capacity constraints in the United States and Germany limit qualified operator supply relative to installed base expansion.
- Legacy 20-gauge instrument compatibility:Hybrid operating rooms require dual-format equipment stocking, inflating inventory carrying costs and sterilization logistics complexity.
- Interoperability certification delays:Proprietary data formats between laser systems and electronic health record platforms extend hospital IT integration timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Retinal Surgery Devices Market |
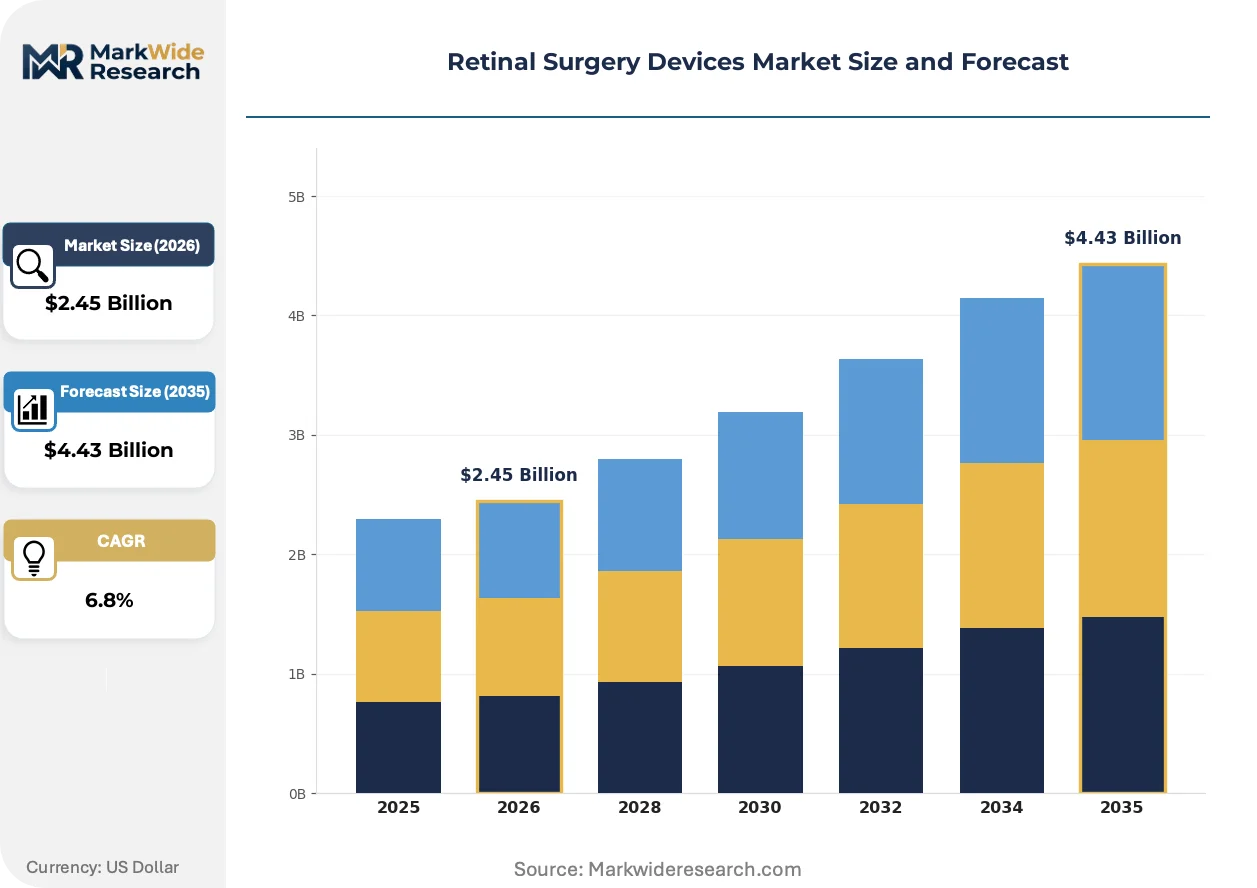
| Market Size in 2026 | $2.45 Billion |
| Market Size in 2035 | $4.43 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Laser Systems, Visualization Systems, Surgical Instruments, Assisting Devices End User: Ophthalmology Clinics, Hospitals, Research Institutions, Ambulatory Surgical Centers Technology: Microincision, Vitrectomy, Cryotherapy, Phacoemulsification Application: Retinal Detachment, Diabetic Retinopathy, Macular Hole, Vitreous Hemorrhage |
| Companies Covered | Alcon Inc., Carl Zeiss Meditec AG, Bausch + Lomb, Topcon Corporation, IRIDEX Corporation, Lumenis Be Ltd., Leica Microsystems, NIDEK CO., LTD., Lumibird Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Retinal Surgery Devices Market Strategic Shifts & Innovations
Digital surgical workflows are redrawing competitive boundaries in retinal intervention, compressing the gap between diagnostic imaging and therapeutic execution while elevating software-integrated platforms over standalone instrument sales.
3D heads-up visualization systems are decomposing the traditional microscope ocular interface by projecting stereoscopic imagery to surgeon-facing displays. Academic medical centers in the United States and Japan are adopting these platforms for trainee observation and surgical education. The technology is decomposing capital equipment procurement patterns as hospitals prioritize integrated digital ecosystems over modular component purchasing.
EU MDR technical documentation requirements are extending post-market surveillance obligations to Class IIa laser accessories previously governed by lighter touch directives. Manufacturers must now maintain clinical follow-up registries for disposable laser probes, inflating compliance staffing. European ambulatory surgical centers are responding by consolidating vendor panels to reduce audit surface area.
Surgeon preference is pivoting toward single-use disposable instrument sets that eliminate reprocessing variability and operating room turnover delays. Ambulatory centers in Germany and Japan are capturing this shift through consignment inventory models that shift capital burden to manufacturers. The behavioral change is most visible in high-volume cataract-retina combination practices where case throughput determines facility economics.
Retinal Surgery Devices Market Segmentation
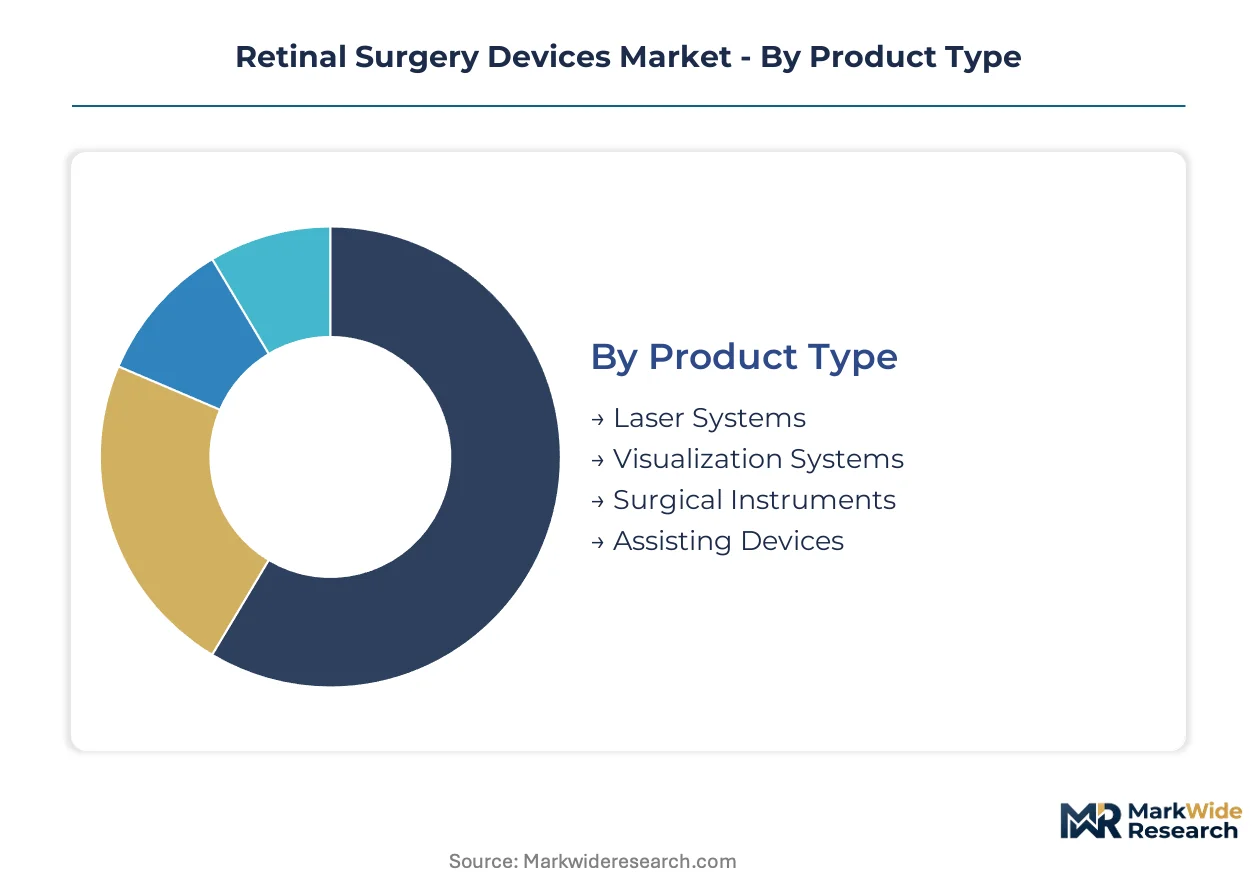
Retinal surgery devices fragment across four intersecting dimensions that determine procurement patterns, regulatory pathways, and margin structures. Product type governs capital intensity and disposable revenue recurrence. End user concentration shapes distribution channel economics and service contract terms.
Product Type:
FDA 510(k) clearance timelines diverge sharply across this category, with laser systems facing extended clinical evidence requirements compared to mechanical instruments.
- Laser Systems:Solid-state and diode laser platforms delivering photocoagulation and photodisruption at specified wavelengths. Demand concentrates in hospital ophthalmology departments across the United States and Germany, driven by recurring disposable probe revenue and long-term service agreements that lock in vendor relationships.
- Visualization Systems:Integrated surgical microscopes with heads-up 3D displays and digital image injection capabilities. Adoption accelerates in academic medical centers in Japan and the United States where trainee observation requirements favor screen-based over ocular interfaces.
- Surgical Instruments:Precision forceps, scissors, and cannulas engineered for sub-millimeter vitreoretinal manipulation.
- Assisting Devices:Peristaltic pumps, illumination probes, and accessory platforms supporting core surgical workflows.
Established volume favors Laser Systems; emerging adoption favors Visualization Systems.
End User:
Procurement authority and reimbursement pathways create distinct equipment specifications across facility types.
- Hospitals:Integrated health systems with centralized capital budgeting and preference for vendor-agnostic device compatibility. Demand concentrates in the United States and Germany where DRG-based reimbursement supports high-cost platform acquisition.
- Ambulatory Surgical Centers:Physician-owned facilities prioritizing case throughput and rapid instrument turnover. These centers in Germany and Japan are expanding fastest as regulatory frameworks align outpatient retina procedures with inpatient reimbursement parity.
- Ophthalmology Clinics:Private practice settings with limited capital budgets and preference for portable or leased equipment configurations.
- Research Institutions:Academic centers driving preclinical validation and early technology assessment for subsequent commercial translation.
Capital deployment scale peaks at Hospitals; procedural volume growth concentrates at Ambulatory Surgical Centers.
Technology:
Instrumentation gauge and energy delivery modality determine operative invasiveness and recovery profiles.
- Microincision:25-gauge and 27-gauge transconjunctival platforms enabling sutureless vitrectomy. Surgeon adoption in the United States and Japan is displacing legacy 20-gauge systems as operating room turnover economics favor reduced case times.
- Vitrectomy:Core pars plana procedures for membrane peeling, fluid-air exchange, and tamponade placement. Demand concentrates in hospital settings across Germany where complex diabetic pathology requires combined surgical approaches.
- Cryotherapy:Trans-scleral freezing applications for retinal break sealing and prophylactic treatment.
- Phacoemulsification:Cataract extraction technology integrated in combined cataract-retina surgical workflows.
Installed base concentration remains with Vitrectomy; Microincision platforms are expanding most quickly across high-volume practices.
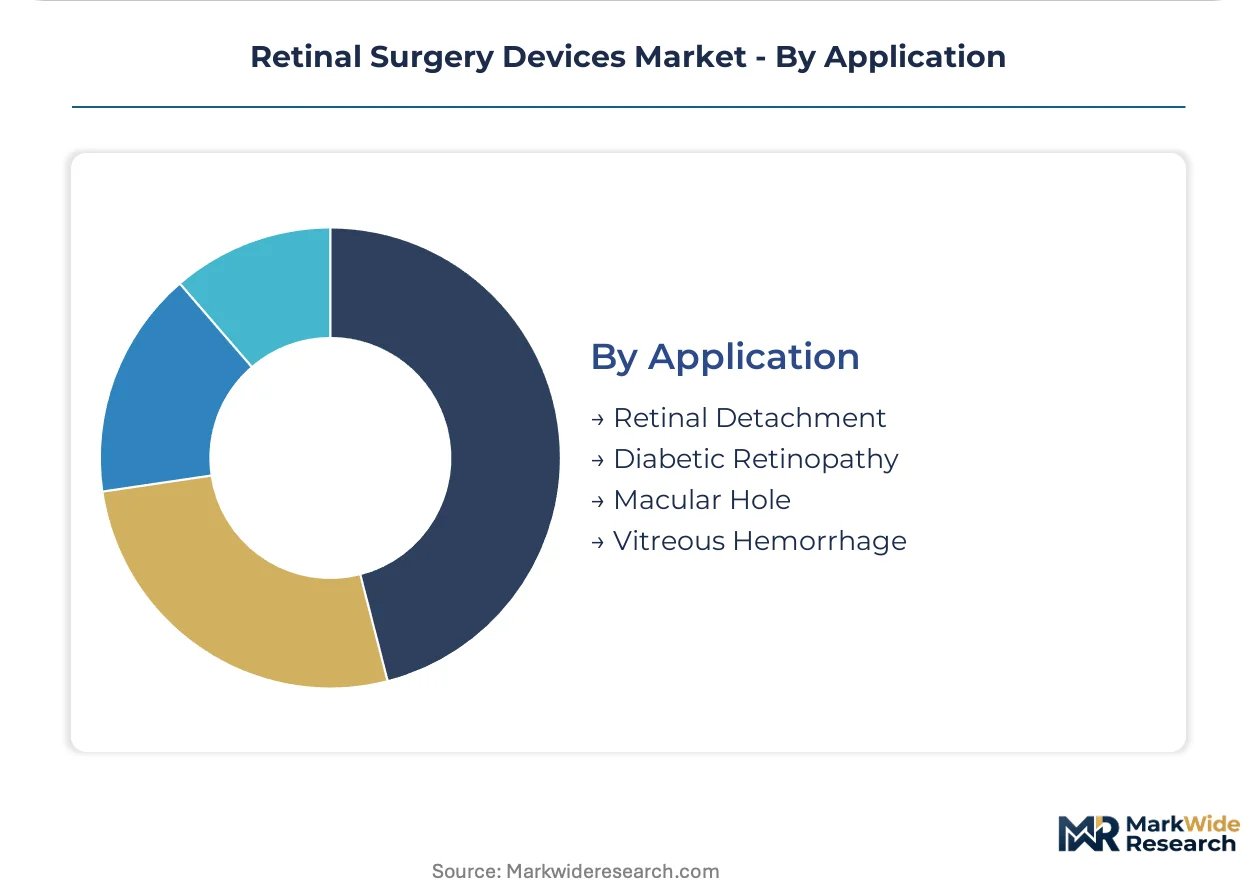
Application:
Disease prevalence and treatment algorithm evolution reshape addressable procedure volumes.
- Diabetic Retinopathy:Proliferative and non-proliferative manifestations requiring pan-retinal photocoagulation or vitrectomy for tractional detachment. Patient volumes in the United States, Germany, and Japan are expanding as diabetes prevalence rises in aging demographics.
- Retinal Detachment:Rhegmatogenous and tractional detachments requiring urgent surgical intervention. Demand concentrates in emergency-capable hospital settings where 24-hour surgical availability determines referral patterns.
- Macular Hole:Full-thickness foveal defects requiring vitrectomy with internal limiting membrane peeling.
- Vitreous Hemorrhage:Bleeding into the vitreous cavity from diabetic, vascular, or traumatic etiologies.
Procedural volume leadership sits with Diabetic Retinopathy; Retinal Detachment commands premium urgency pricing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German and Japanese optical component suppliers concentrate precision supply chains for high-resolution surgical microscopes. FDA 510(k) pathways in the United States and MDR compliance frameworks in Europe shape divergent market entry timelines. Aging demographics across developed economies expand procedural volumes for diabetic retinopathy and macular degeneration interventions.
United States
DRG-based reimbursement supports high-cost platform acquisition in integrated health systems. FDA 510(k) premarket notification requirements govern device clearance timelines and clinical evidence standards for laser system market entry. Academic medical centers in Boston and the Research Triangle anchor adoption of heads-up 3D visualization systems for trainee observation.
Germany
Hospital procurement consortia consolidate vendor relationships under EU MDR post-market surveillance obligations. The country's national medical device regulator enforces technical documentation requirements that extend compliance costs for laser accessory manufacturers. The Baden-Württemberg precision optics cluster around Stuttgart supplies high-resolution surgical microscope components to global OEMs.
Japan
PMDA quality management system audits filter out smaller entrants while streamlining pathways for ISO 13485-certified manufacturers. METI industrial policy incentivizes domestic production of next-generation visualization modules. The Kanto region surrounding Tokyo concentrates academic medical center demand for screen-based surgical interfaces.
India
Tier-2 city hospital networks in secondary metropolitan centers offer first-mover positioning for portable laser systems. The country's national pharmaceutical regulator enforces quality standards for imported ophthalmic devices while expanding domestic manufacturing incentives. The Maharashtra-Gujarat corridor anchors emerging distribution infrastructure for retinal surgery capital equipment.
United Kingdom
NHS procurement frameworks prioritize vendor-agnostic device compatibility in centralized capital budgeting decisions. MHRA post-Brexit regulatory alignment maintains CE marking recognition while establishing independent conformity assessment pathways. The London-Oxford-Cambridge triangle concentrates private ophthalmology clinic demand for leased portable equipment configurations.
Retinal Surgery Devices Market Key Industry Players
Concentration sits with diversified ophthalmology conglomerates possessing integrated surgical platforms and recurring disposable revenue streams. The vendor base stratifies across three tiers: premium platform integrators commanding hospital capital budgets, mid-scale instrument specialists competing on cost-engineered consumables, and regional distributors capturing ambulatory center volume. Strategic moves center on proprietary visualization ecosystem lock-in and consignment inventory models that shift capital burden to manufacturers.
Within the premium platform tier, Alcon Inc. and Carl Zeiss Meditec AG exemplify divergent approaches to market positioning. The Swiss-American conglomerate anchors integrated surgical suite dominance through bundled capital equipment and disposable attachment ecosystems. The German optics specialist occupies a position defined by precision engineering heritage and digital workflow integration. Bausch + Lomb represents the cost-competitive vector, leveraging broad distribution reach and consumables-focused portfolios to capture ambulatory surgical center procurement decisions.
| Leading Market Players |
|---|
| Alcon Inc. |
| Carl Zeiss Meditec AG |
| Bausch + Lomb |
| Topcon Corporation |
| IRIDEX Corporation |
| Lumenis Be Ltd. |
| Leica Microsystems |
| NIDEK CO., LTD. |
| Lumibird Medical |
| Others |
Cost & Logistics Intelligence
Minimum efficient scale in precision optical component manufacturing concentrates production among German and Japanese suppliers, creating dual-source dependency that elevates price floors for high-resolution surgical microscopes while compressing margin flexibility for downstream device integrators.
Pricing Analysis
FDA 510(k) clearance tiers dictate the pricing structure across retinal surgery platforms, separating premium integrated visualization ecosystems from standard laser systems and economy-grade mechanical instruments. Price differentiation rests on CE marking certification level and proprietary software integration depth. Cost compression in the standard tier is intensifying because hospital procurement consortia are consolidating vendor panels under EU MDR compliance pressures. Ambulatory surgical centers exhibit highest price sensitivity due to case-throughput economics, while academic medical centers absorb premium pricing for trainee-compatible heads-up display systems.
Supply Chain Analysis
Consignment inventory models are extending manufacturer working capital cycles to ninety-day-plus horizons as German and Japanese ambulatory centers shift capital burden upstream. Precision optics manufacturing concentrates in Germany, Japan, and Switzerland, drawing from specialized glass substrates, rare-earth laser crystals, and sub-micron polishing compounds. Single-source vulnerability sits with Stuttgart-area optical component suppliers serving global OEM microscope assembly. Distribution runs through hospital procurement consortia in Germany, GPO contracts in the United States, and regional distributor networks in Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among European hospital procurement consortia and United States group purchasing organizations, fragmenting vendor relationships as compliance costs filter out smaller equipment suppliers.
For Market Incumbents: Compound ecosystem lock-in through proprietary heads-up display software integration and disposable attachment recurring revenue streams. Defend against portable laser system entrants by anchoring hospital capital budgets with long-term service agreements. Prioritize backward integration into precision optical component supply to mitigate Stuttgart-cluster disruption risk. For New Entrants and Emerging Players: Differentiate on portable laser system configurations targeting India's tier-2 city hospital networks where installed base saturation remains low. Penetrate the consignment inventory model segment in German ambulatory surgical centers by absorbing capital burden through equipment-as-a-service structures. Lead with tele-ophthalmology pre-screening integration to shorten patient acquisition cycles. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors visualization module specialists with ISO 13485 certification and streamlined Japan PMDA audit pathways. Five-to-ten-year viability hinges on software-integrated platform capture versus standalone instrument commoditization. Monitor FDA 510(k) clearance velocity for novel laser wavelengths as inflection signal for regulatory capital efficiency.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR technical documentation requirements extend compliance timelines for laser accessory manufacturers entering European hospital procurement frameworks. |
| Hospital System Partnership | Integrated health systems in the United States prioritize vendor-agnostic device compatibility under DRG-based reimbursement structures. |
| Software Companion Development | Proprietary surgical workflow platforms lock in capital budgets through disposable attachment ecosystems and recurring service contracts. |
| Reimbursement Strategy | Alignment with outpatient retina procedure reimbursement parity in Germany and Japan accelerates ambulatory surgical center equipment refresh cycles. |
| FDA Submission | Premarket notification pathways for microincision platforms require clinical evidence thresholds that filter out undercapitalized entrants. |
Research Approach
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, EU MDR technical documentation databases, hospital procurement contract registries, and CMS Medicare reimbursement schedules. Primary interviews engaged vitreoretinal surgeons, hospital purchasing committee members, biomedical engineers, GPO contracts managers, and ambulatory surgical center operators. Secondary validation drew from PMDA audit disclosures, ISO 13485 certification registries, and trade data on precision optical component flows. Bottom-up procedure volume estimates triangulated against top-down capital equipment shipment tracking.
Segmentation dimensions modeled span product type, end user facility category, instrumentation gauge technology, and disease application across the projection horizon. CAGRs derive from installed base expansion rates, procedural volume trajectories, and equipment replacement cycle analysis. Forecast inputs incorporate diabetic retinopathy prevalence projections, fellowship program capacity constraints, and regulatory clearance velocity assumptions.
Material uncertainties — PMDA audit timeline variability, EU MDR post-market surveillance obligation evolution, and vitreoretinal surgeon training pipeline constraints — sit outside the modeled envelope. Forecasts reflect documented assumptions subject to revision from regulatory framework shifts or supply chain disruption events. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Enteral Feeding Devices Market
Medical Devices
Americas Wearable Medical Device Market
Medical Devices
Patient Warming Devices Market
Medical Devices
Surgical Display Market
Medical Devices
GCC Organ Preservation Market
Medical Devices
Japan Contraceptive Devices Market
Medical Devices
Global Dry Powder Inhaler (DPI) Market
Medical Devices
Intra-Abdominal Pressure Measurement Devices (IPMD) Market
Medical Devices
Portable Medical Devices Market
Medical Devices
Neurointerventional Devices Market
Medical Devices
ECG Patch and Holter Monitor Market
Medical Devices
Global Oxygen Conservation Devices Market
Medical Devices
Australia Respiratory Devices Market
Medical Devices
Engine-Driven Endodontic File Market
Medical Devices
3D Printed Hip and Knee Implants Market
Medical Devices
Cervical Implants Market