
 Medical Device Cros Market | 2026-2036
Medical Device Cros Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Device Cros Market Foresight
Cardiology application demand is consolidating as hospitals and device sponsors expand outsourcing of complex electrophysiology and structural heart trials. NAMSA leverages integrated laboratory and clinical capabilities to anchor preclinical-to-market pathways for high-risk devices. IQVIA competes through real-world evidence platforms that extend traditional CRO value into post-market surveillance. Medpace specializes in cardiac rhythm management trials, sustaining differentiation through therapeutic depth rather than scale alone.
Medical device CROs deliver outsourced clinical trial management, regulatory strategy, and quality assurance services spanning preclinical validation through post-market compliance. These organizations manage investigational device exemption filings, good clinical practice adherence, and biostatistical analysis for hardware-bound therapeutics subject to stringent safety benchmarks. Electrophysiology devices and robotic surgery technology command premium service margins due to trial complexity and specialized investigator networks. Wearable technology trials are expanding fastest as ambulatory endpoints reshape traditional site-based models. Diagnostic imaging equipment represents a mature segment where standardization compresses pricing but volume sustains participant economics.
FDA premarket approval pathways and EU MDR notified body requirements shape service demand by elevating documentation rigor and clinical data thresholds for market access. ISO 14155 and GCP standards govern trial conduct across jurisdictions, creating compliance infrastructure that CROs must maintain as a baseline credential. Stakeholders should monitor how decentralized trial technologies and evolving FDA digital health guidance reshape site selection and patient recruitment economics.
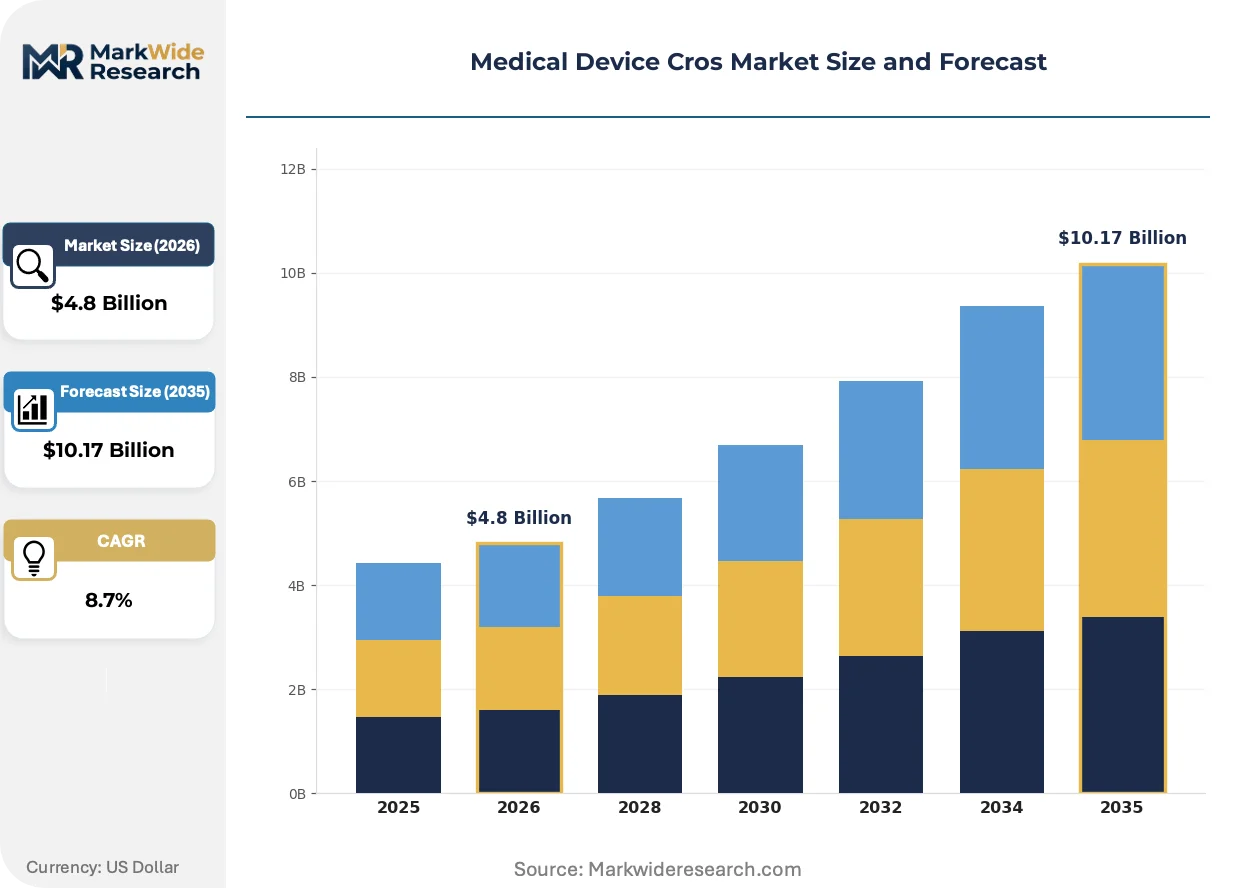
Market Dynamics
Decentralized clinical trial technologies are restructuring site selection economics and patient recruitment workflows across medical device development, compressing traditional geographic constraints on investigator access.
Growth Catalysts
- EU MDR notified body requirements:Device sponsors face expanded clinical data thresholds for CE marking, elevating demand for specialized regulatory navigation services.
- Wearable ambulatory endpoints:Continuous monitoring capabilities enable remote trial participation, expanding addressable patient populations beyond traditional site boundaries.
- Class III device innovation clusters:United States concentration of high-risk cardiovascular and neuromodulation developers sustains premium CRO engagement for complex premarket approval pathways.
Market Restraints
- Investigator site concentration:Top-tier academic medical centers with electrophysiology expertise command premium pricing, limiting sponsor negotiating leverage.
- FDA premarket approval documentation rigor:Extended review timelines for novel devices compress sponsor cash runway and delay CRO revenue recognition.
- Specialized talent scarcity:Biostatisticians with ISO 14155 and GCP expertise command compensation premiums, inflating service delivery costs.
Strategic Opportunities
- Asia-Pacific regulatory harmonization:Japan's PMDA and Australia's TGA are aligning quality system requirements, creating scalable trial infrastructure across the region.
- Real-world evidence integration:Post-market surveillance mandates under FDA digital health guidance enable CROs to extend contracts beyond traditional clinical endpoints.
- Robotic surgery trial expansion:Minimally invasive platform developers require specialized investigator networks that generalist CROs cannot replicate.
Industry Challenges
- Legacy data system interoperability:Electronic data capture platforms must integrate with hospital EHR systems that lack standardized APIs, delaying study startup.
- Certification timeline volatility:Notified body capacity constraints under EU MDR extend quality management system audit queues, disrupting sponsor milestone planning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Device Cros Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electrophysiology Devices, Surgical Instruments, Diagnostic Imaging Equipment, Patient Monitoring Systems Technology: Wearable Technology, Minimally Invasive Techniques, Robotic Surgery, Telemedicine Solutions End User: Hospitals, Ambulatory Surgical Centers, Home Care Providers, Diagnostic Laboratories Application: Cardiology, Orthopedics, Neurology, Gastroenterology |
| Companies Covered | NAMSA, Parexel, MCRA, Avania, ICON, Medpace, IQVIA, Premier Research, Quanticate, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Device Cros Market Shifts & Advancements
Digital biomarker validation and remote patient monitoring are dissolving the physical boundaries of clinical evidence generation, forcing CROs to reconfigure site networks and data infrastructure around decentralized models.
Artificial intelligence-enabled adverse event detection is absorbing signal identification workloads previously handled by manual clinical data review teams. Mid-size device sponsors with limited pharmacovigilance infrastructure are adopting these platforms fastest. The technology is absorbing routine safety monitoring tasks while compressing headcount requirements for traditional medical monitoring roles.
REACH substance restrictions and EU MDR biocompatibility requirements are elevating material characterization documentation for implantable devices. Manufacturers must demonstrate chemical safety profiles across extended supply chains. Cardiovascular and orthopedic implant segments are responding by embedding toxicology assessment earlier into preclinical planning, extending CRO engagement timelines.
Site-less trial models are fragmenting traditional investigator site economics. Device sponsors now contract directly with home health nursing networks and telemedicine platforms, bypassing established academic medical center relationships. This behavioral shift is most visible in diabetes technology and sleep apnea device trials where ambulatory endpoints dominate regulatory submissions.
Medical Device Cros Market Segmentation
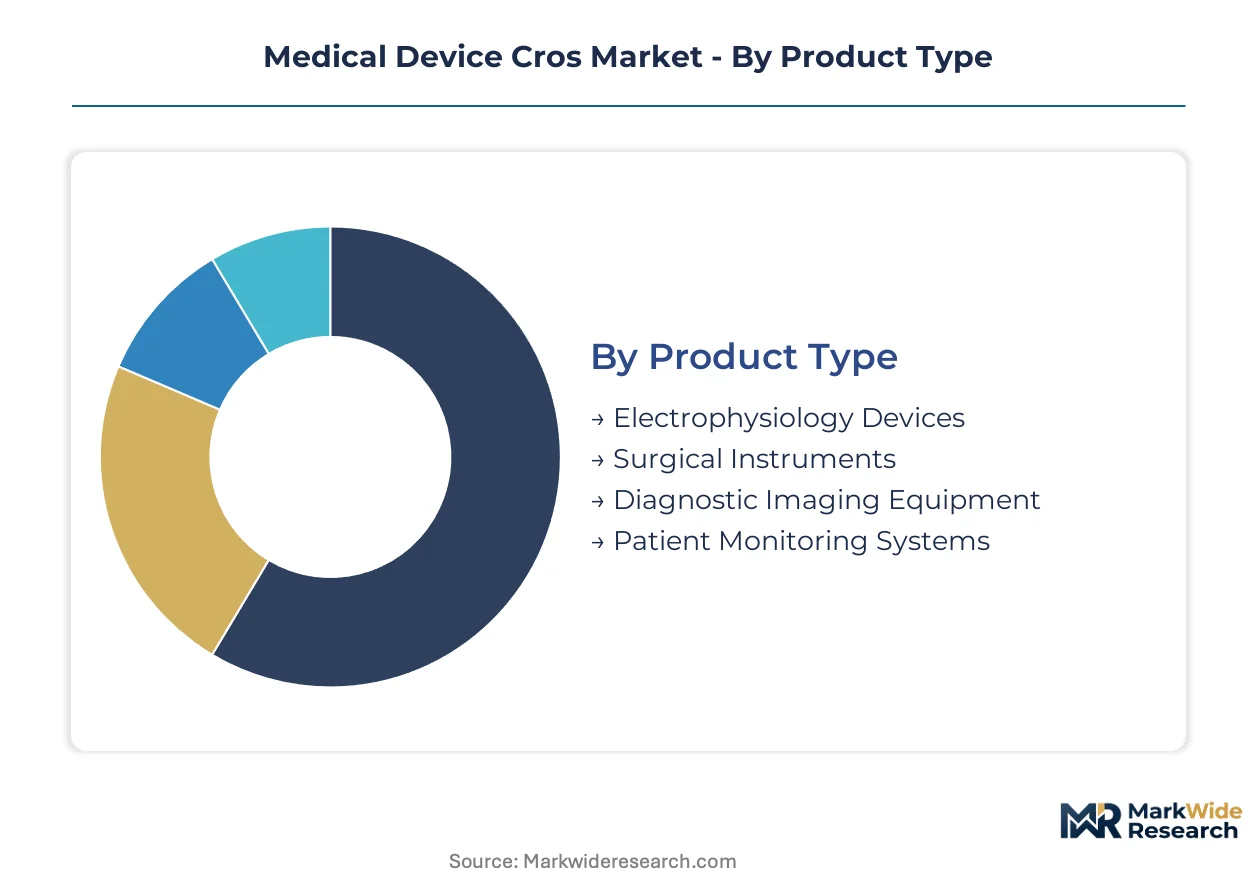
Medical device CROs configure service portfolios around distinct technology-platform and customer-type boundaries. Segmentation clarity determines which trial-management capabilities sponsors prioritize when outsourcing complex regulatory pathways.
Product Type:
Standalone trial programs dominate electrophysiology and imaging segments, while surgical instruments frequently embed within broader therapeutic-area contracts.
- Electrophysiology Devices:These systems map cardiac electrical activity and deliver ablation therapy, requiring specialized investigator networks with catheter-lab expertise. Demand concentrates in United States academic medical centers where complex arrhythmia trials command premium service margins due to FDA premarket approval documentation requirements.
- Surgical Instruments:Handheld and powered instruments for open and laparoscopic procedures span diverse therapeutic areas. Orthopedic and general surgery sponsors in Germany and Japan drive standardization of ISO 14155-compliant trial protocols across mid-size device portfolios.
- Diagnostic Imaging Equipment:MRI, CT, and ultrasound systems require large patient cohorts and extended follow-up periods. Mature regulatory pathways in established markets compress pricing, though volume sustains participant economics for full-service CROs.
- Patient Monitoring Systems:Continuous vital-sign tracking devices increasingly incorporate wearable form factors. Trials for these systems leverage ambulatory endpoints that reduce site-visit frequency and expand geographic recruitment reach.
Volume placements concentrate in Diagnostic Imaging Equipment; the faster expansion belongs to Electrophysiology Devices.
Technology:
Cost-tier stratification separates capital-intensive robotic platforms from lightweight wearable implementations that reduce per-patient trial expenditure.
- Wearable Technology:Biosensors and ambulatory monitors enable remote data capture outside traditional clinical sites. Cardiology and diabetes technology sponsors in the United States and Netherlands adopt decentralized models fastest, bypassing academic medical center overhead.
- Minimally Invasive Techniques:Catheter-based and laparoscopic approaches reduce recovery time and expand eligible patient populations. Gastroenterology and interventional cardiology trials in Japan and Australia demonstrate strong protocol uptake for these modalities.
- Robotic Surgery:Computer-assisted platforms demand specialized investigator training and proctored case requirements. High capital costs and limited installed base constrain trial expansion to premium-tier CRO engagements with dedicated surgical networks.
- Telemedicine Solutions:Virtual visit platforms and remote monitoring software support hybrid trial designs. Sleep apnea and diabetes device sponsors integrate these tools to maintain patient engagement between in-person assessments.
Revenue concentration sits with Robotic Surgery; Wearable Technology gains share fastest as regulatory acceptance of ambulatory endpoints broadens.
End User:
Customer-type segmentation reflects divergent procurement authority and trial-sponsorship patterns across institutional settings.
- Hospitals:Academic medical centers and large health systems sponsor the majority of Class III device trials. These institutions maintain internal research infrastructure but outsource complex electrophysiology and structural heart studies to specialized CROs.
- Ambulatory Surgical Centers:Outpatient facilities increasingly participate in minimally invasive device trials. United States ASC networks expand recruitment access for lower-acuity procedures with shorter recovery windows.
- Home Care Providers:Home health nursing organizations and remote monitoring services enable site-less trial participation. Diabetes technology and sleep therapy sponsors contract directly with these networks to bypass traditional investigator sites.
- Diagnostic Laboratories:Central lab services support biomarker validation and companion diagnostic development. These providers function as subcontractors rather than primary trial sponsors within the CRO value chain.
Contract value concentrates in Hospitals; Home Care Providers represent the steepest expansion trajectory as decentralized models mature.
Application:
Therapeutic-area maturity shapes trial complexity and regulatory pathway selection across device categories.
- Cardiology:Structural heart and electrophysiology trials dominate high-value CRO engagements. FDA premarket approval requirements for left atrial appendage closure and transcatheter valve devices sustain specialized regulatory navigation demand.
- Orthopedics:Joint replacement and spine device trials follow established predicate pathways. Large patient cohorts and standardized endpoints compress per-study margins while sustaining volume economics.
- Neurology:Deep brain stimulation and vagus nerve therapy trials require extended follow-up and specialized outcome assessment. United States and European neuromodulation developers concentrate in clustered innovation hubs.
- Gastroenterology:Endoscopic and implantable device trials for obesity and motility disorders expand as minimally invasive techniques gain adoption. Japan's PMDA and Australia's TGA demonstrate increasing protocol harmonization in this segment.
Revenue concentration remains in Cardiology; Neurology climbs fastest as neuromodulation platforms address expanded indications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States generates disproportionate CRO demand through its concentration of Class III device innovators, while Germany and Japan anchor European and Asian regulatory expertise respectively. Production of clinical trial services remains tethered to investigator site density rather than manufacturing geography.
United States
FDA premarket approval pathways for electrophysiology and neuromodulation devices sustain premium CRO engagement across Massachusetts and California innovation clusters. The agency's digital health guidance evolution reshapes trial design requirements for wearable endpoints. Minneapolis and Irvine host dense concentrations of cardiovascular device sponsors outsourcing complex structural heart trials.
Germany
EU MDR notified body capacity constraints extend quality management system audit timelines, elevating demand for regulatory navigation support among mid-size device manufacturers. BfArM and notified body coordination determines CE marking velocity for orthopedic and surgical instrument portfolios. Baden-Württemberg and Bavaria maintain Europe's deepest networks of ISO 14155-compliant clinical investigators.
Japan
PMDA alignment with IMDRF standards accelerates foreign device sponsor market entry, expanding CRO service scope beyond traditional domestic trial management. The Sakigake designation system prioritizes review resources for breakthrough device categories. Tokyo and Osaka academic medical centers concentrate electrophysiology expertise that attracts multinational trial sponsorship.
China
NMPA innovation pathway reforms compress review timelines for domestically developed high-risk devices, intensifying sponsor demand for bilingual regulatory strategy support. Hainan Boao Lecheng pilot zones enable real-world data collection for imported device registration. Shanghai and Suzhou device innovation parks anchor CRO regional headquarters serving Asia-Pacific trial expansion.
Australia
TGA priority review pathways and provisional approval mechanisms attract early-stage device sponsors seeking clinical data generation outside United States FDA jurisdiction. The country's therapeutic goods administration maintains mutual recognition arrangements with European notified bodies. Melbourne and Sydney academic hospitals participate in multinational electrophysiology trials through streamlined ethics approval frameworks.
Medical Device Cros Market Competitive Landscape
Top-tier vendors anchor full-service regulatory-to-commercial pathways, while mid-size specialists capture therapeutic-area depth through investigator network control. The market structure stratifies across three tiers: integrated laboratory-clinical hybrids, real-world evidence platform operators, and boutique regulatory boutiques. Two dominant competitive moves are reshaping positioning: acquisition of decentralized trial technology capabilities and vertical integration into preclinical testing infrastructure.
Within the integrated laboratory-clinical tier, NAMSA and IQVIA occupy positions that exemplify divergent scale strategies. NAMSA anchors preclinical-to-market pathways through captive laboratory capacity. IQVIA represents the data platform archetype, extending traditional CRO value through real-world evidence infrastructure. Medpace sits within the therapeutic-specialist vector, sustaining differentiation through cardiac rhythm management depth rather than geographic coverage alone.
| Leading Market Players |
|---|
| NAMSA |
| Parexel |
| MCRA |
| Avania |
| ICON |
| Medpace |
| IQVIA |
| Premier Research |
| Quanticate |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up CRO specialists have consolidated investigator network ownership across United States academic medical centers, concentrating supply-side control while enforcing pricing discipline through long-term hospital system contracts.
Pricing Analysis
Margin tightening in electrophysiology trial services reflects investigator site scarcity and EU MDR documentation complexity. Three-tier pricing structure across premium, standard, and economy levels separates full-service regulatory navigation from modular protocol support. Price differentiation traces to ISO 14155 certification tier and geographic investigator density. Small-device sponsors exhibit highest price sensitivity; multinational cardiovascular innovators absorb premium positioning.
Supply Chain Analysis
Refurbishment flows for clinical trial equipment concentrate service asset redeployment from United States academic centers to Asia-Pacific expansion sites. Supply anchors in United States, Germany, and Japan through specialized investigator training infrastructure. Raw material dependencies span biocompatibility testing reagents, EDC software licenses, and GCP-trained biostatistician labor pools. Single-source vulnerability sits with electrophysiology catheter-lab capacity at tier-one hospitals. Distribution runs through direct sponsor-CRO contracting with limited intermediary presence.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a cost-of-compliance story where EU MDR notified body requirements erect barrier-to-entry moats favoring CROs with established quality management system audit navigation capabilities.
For Market Incumbents: Cement preclinical-to-market pathway control through captive laboratory acquisition and ISO 14155 certification depth. Threat from decentralized trial technology vendors demands backward integration into remote monitoring platform capabilities. Priority lever centers on investigator network exclusivity in electrophysiology hubs. For New Entrants and Emerging Players: Australia's TGA priority review pathway opens a window for early-stage device sponsors seeking clinical data generation outside FDA jurisdiction. Most penetrable segment spans home care provider trial networks for diabetes technology. Go-to-market angle targets direct contracting with telemedicine platforms bypassing academic medical center overhead. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-size therapeutic specialists with concentrated neuromodulation or structural heart expertise in United States innovation clusters. Long-term viability framing emphasizes post-market surveillance contract extension under FDA digital health guidance. Signal to watch is notified body capacity relief under EU MDR implementation maturation.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Notified Body Partnership | Accelerates CE marking velocity for orthopedic and surgical instrument portfolios through dedicated audit queue access. |
| Decentralized Trial Technology Acquisition | Absorbs remote patient monitoring capabilities that bypass traditional site-based recruitment economics. |
| Real-World Evidence Platform Development | Extends contract value beyond clinical endpoints into FDA-mandated post-market surveillance engagements. |
| Asia-Pacific Regulatory Harmonization Investment | Captures scalable trial infrastructure across Japan PMDA and Australia TGA aligned quality systems. |
| Preclinical Testing Infrastructure Integration | Anchors full-service value proposition through captive biocompatibility and toxicology assessment capacity. |
Research Methodology
FDA premarket submission databases, EU MDR notified body audit records, and ClinicalTrials.gov protocol registries formed the secondary backbone, cross-referenced against primary interviews with clinical research directors, regulatory affairs leads at device sponsors, hospital purchasing committee members, and GPO contracts managers. Bottom-up service revenue modeling triangulated against top-down market sizing from trade association disclosures.
Historical trendline analysis across service delivery cost components and contract value trajectories informed projection mechanics. Segmentation dimensions spanned product type, technology platform, end-user institution category, and therapeutic application area. CAGRs derived from weighted average of segment growth rates calibrated to regulatory filing volume trends and investigator site expansion patterns.
The model assumes a particular technology adoption path for decentralized trial platforms; alternative pathways for wearable ambulatory endpoints would alter the outlook. Practitioners should monitor FDA digital health guidance evolution and notified body capacity constraints for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Surgical Robotics Performance and Safety Validation Test Platforms Market
Medical Devices
Asia-Pacific Wearable Medical Devices Market
Medical Devices
Global Traumatic Brain Injury Assessment and Management Devices Market
Medical Devices
China Anesthesia Devices Market
Medical Devices
North America Ultrasound Devices Market
Medical Devices
Adsorption Apheresis Devices Market
Medical Devices
Global Gait Analysis System Market
Medical Devices
Neuromuscular Transmission Monitor Market
Medical Devices
Neurovascular Devices Market
Medical Devices
Bowel Irrigation System Market
Medical Devices
Russia Massage Equipment Market
Medical Devices
Artificial Eye Market
Medical Devices
Osteosynthesis Devices Market
Medical Devices
Deflectable Catheters Market
Medical Devices
Smart Wheelchairs Market
Medical Devices
Expandable Interbody Fusion System Market