
 Myasthenia Gravis Treatment Market | 2026-2036
Myasthenia Gravis Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Myasthenia Gravis Treatment Market Analysis
Good Manufacturing Practice certification for biologic active pharmaceutical ingredients is reorganizing competitive access in the myasthenia gravis treatment landscape. Alexion Pharmaceuticals leverages its rare disease infrastructure to sustain leadership in complement inhibition therapies. argenx anchors European development with its FcRn antagonist platform, while UCB competes through neurology-specialized commercial operations.
Myasthenia gravis treatment encompasses pharmacological and procedural interventions targeting autoimmune neuromuscular transmission failure, with biologic therapies requiring cold-chain distribution and parenteral administration. Monoclonal antibodies command the fastest expansion within product type segments, reflecting payer willingness to cover high-cost biologics for refractory patients. Intravenous immunoglobulin occupies a mature but structurally constrained position due to plasma collection bottlenecks and fractionation capacity limits. Within treatment approach segments, pharmacological management leads in volume while combination therapy captures disproportionate clinical investment for seropositive generalized cases.
FDA orphan drug designation and EMA PRIME eligibility shape development economics by granting market exclusivity and protocol assistance for novel mechanism therapies. The EU AI Act and FDA guidance on real-world evidence are converging to redefine acceptable endpoints for accelerated approval in antibody-mediated autoimmune indications. Stakeholders must monitor how CMS coverage determinations for subcutaneous versus intravenous administration will reshape site-of-care economics and patient access pathways.
Market Dynamics
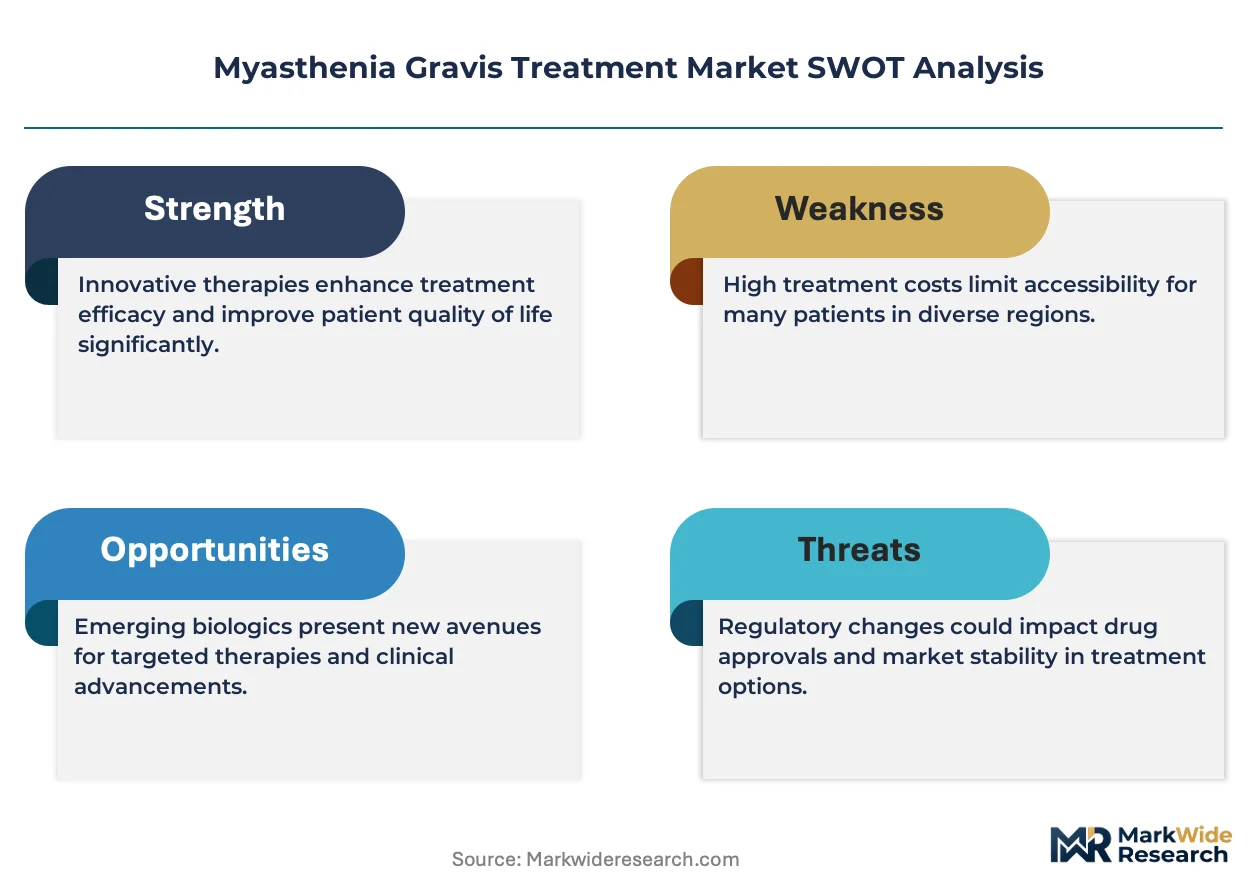
FDA orphan drug designation and EMA PRIME eligibility are compressing development timelines for novel complement inhibitors while reshaping competitive entry economics across the myasthenia gravis treatment landscape.
Growth Catalysts
- Accelerated Approval Pathways:FDA's breakthrough therapy designation shortens clinical trial duration for FcRn antagonists and reduces time-to-market for refractory patient populations.
- Plasma Collection Infrastructure:Specialized immunoglobulin fractionation facilities in the United States and Germany are expanding capacity to address chronic supply-demand imbalances for IVIG therapies.
- Neurology Clinic Biologics Investment:Outpatient infusion centers are deploying cold-chain infrastructure and trained nursing staff to capture site-of-care revenue from parenteral biologic administration.
Market Restraints
- Plasma Supply Concentration:Dependence on US-based plasma collection networks creates geographic vulnerability for immunoglobulin manufacturers facing donor recruitment constraints.
- Biologic Cold-Chain Costs:Temperature-controlled distribution requirements for monoclonal antibodies impose logistics premiums that compress margins in price-sensitive reimbursement environments.
- Diagnostic Delay Friction:Average time from symptom onset to seropositive confirmation exceeds 18 months in many health systems, delaying therapy initiation and compressing addressable patient windows.
Strategic Opportunities
- Subcutaneous Administration Shift:Self-injection formulations for FcRn antagonists enable home-based therapy delivery, reducing infusion center dependency and expanding rural patient access.
- Real-World Evidence Integration:FDA guidance on electronic health record-derived endpoints allows sponsors to supplement registrational trials with observational data from specialty neurology networks.
- Pediatric Indication Expansion:Juvenile myasthenia gravis represents an underserved population with no approved biologic therapies, creating first-mover advantage for mechanism-validated platforms.
Industry Challenges
- Specialized Immunology Talent Scarcity:Clinical development teams with antibody-mediated autoimmune expertise command premium compensation, constraining mid-cap sponsor expansion timelines.
- Reimbursement Evidence Requirements:CMS and commercial payers are demanding head-to-head comparator data against established IVIG regimens, extending Phase III program complexity.
- Manufacturing Scale-Up Validation:Cell culture capacity constraints for complement inhibitors require 18-24 month facility qualification timelines that lag behind clinical enrollment curves.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Myasthenia Gravis Treatment Market |
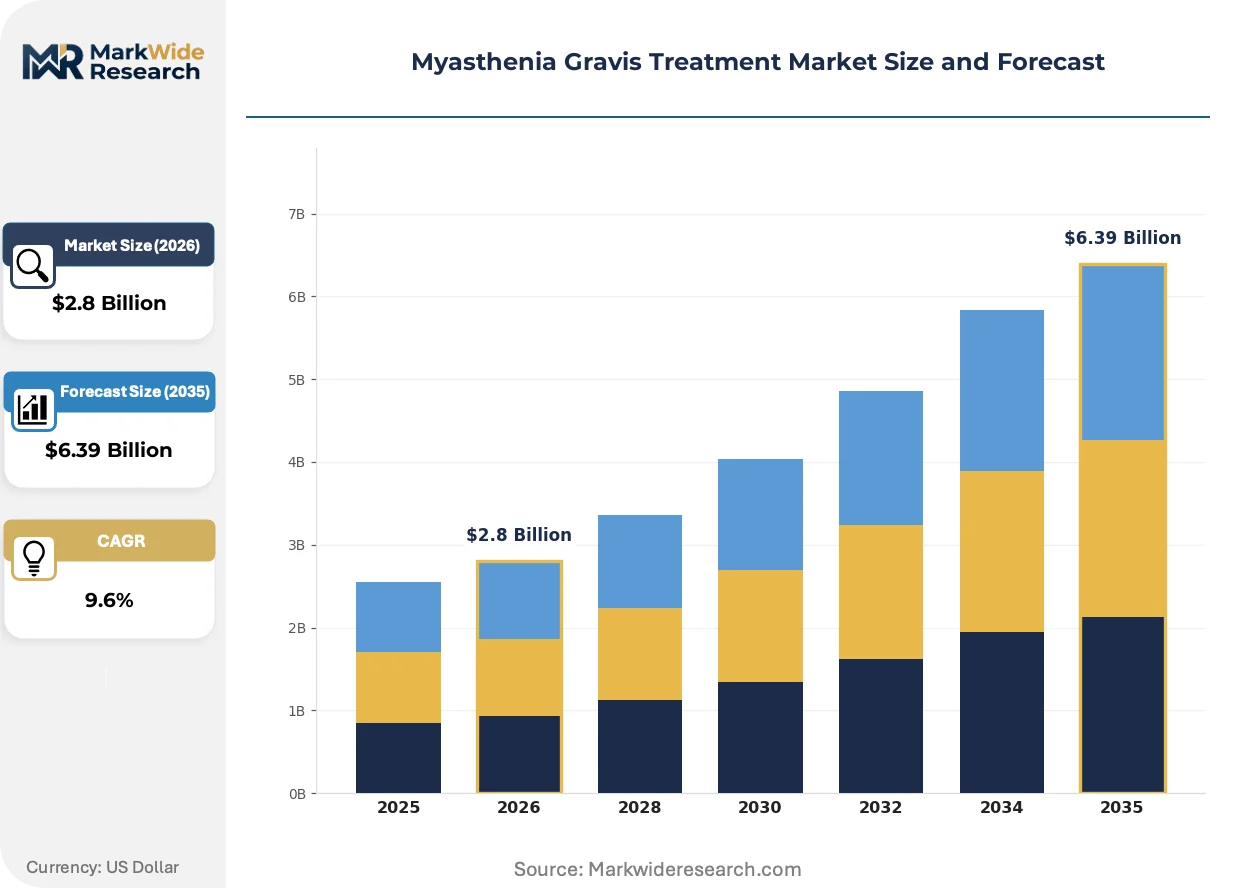
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $6.39 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cholinesterase Inhibitors, Immunosuppressants, Monoclonal Antibodies, Intravenous Immunoglobulin End User: Hospitals, Clinics, Homecare, Research Institutions Treatment Approach: Pharmacological Management, Plasmapheresis, Surgery, Combination Therapy Route of Administration: Oral, Intravenous, Subcutaneous, Intramuscular |
| Companies Covered | Alexion Pharmaceuticals, Grifols, Avadel Pharmaceuticals, Novartis, Pfizer, AbbVie, F. Hoffmann-La Roche, argenx, UCB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Myasthenia Gravis Treatment Market Emerging Trajectories
Biologic administration modalities are fragmenting across sites of care while regulatory frameworks converge on real-world evidence acceptance, fundamentally restructuring how therapies reach seropositive generalized patients.
Subcutaneous monoclonal antibody delivery systems are fragmenting traditional infusion center economics. Neurology practices in the United States and Germany are adopting patient-administered injection platforms that displace intravenous administration for maintenance therapy. This shift compresses site-of-service revenue for hospital outpatient departments while enabling pharmaceutical sponsors to capture adherence data through connected device integration.
EMA's PRIME eligibility criteria now explicitly incorporate patient-reported outcome measures for rare disease indications, accelerating protocol alignment discussions between sponsors and European national health technology assessment bodies. This regulatory evolution pressures clinical trial designers to embed quality-of-life endpoints earlier in development programs. France's ANSM and Germany's BfArM are piloting parallel scientific advice procedures that reduce sequential regulatory consultation delays.
Specialty pharmacy distribution is displacing wholesale channels for high-cost biologics as manufacturers seek direct patient relationship management. Payers in the United States are mandating specialty pharmacy lock-in for complement inhibitors exceeding $15,000 per infusion, consolidating fulfillment through CVS Specialty and Accredo. This channel concentration enables outcomes-based contracting frameworks where reimbursement ties to six-month clinical response thresholds.
Myasthenia Gravis Treatment Market Segmentation
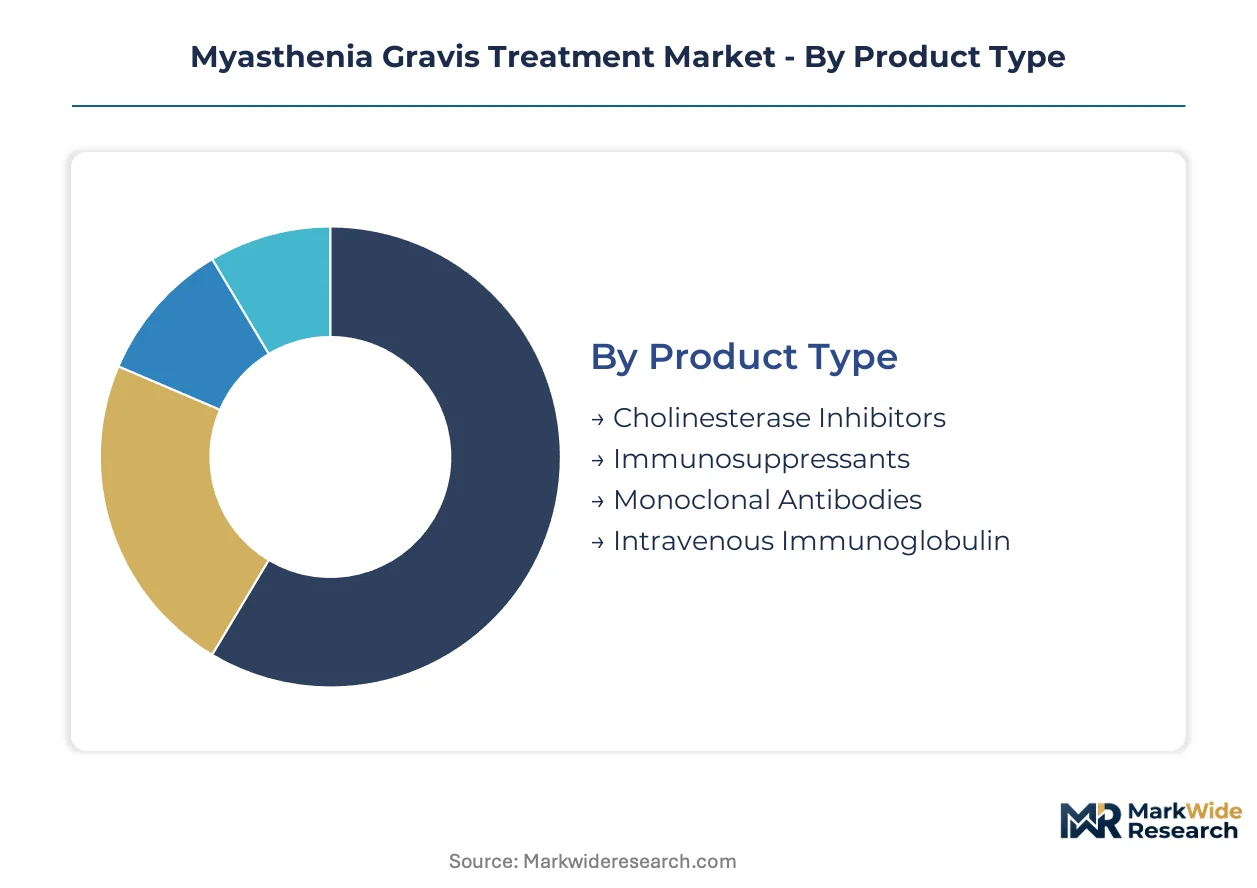
Myasthenia gravis treatment channels fragment sharply across acute versus chronic care settings. Each segment carries distinct cold-chain requirements, reimbursement codes, and site-of-care economics that determine commercial viability.
Product Type:
Distribution channels diverge sharply — hospital outpatient departments capture infusion-based biologics while retail pharmacies handle oral maintenance therapies.
- Monoclonal Antibodies:Engineered immunoglobulins targeting FcRn or complement pathways require continuous cold-chain distribution at 2-8°C. Neurology clinics in the United States are expanding infusion capacity to capture administration revenue from these high-value therapies.
- Intravenous Immunoglobulin:Polyclonal antibody preparations derived from pooled human plasma demand specialized fractionation and viral inactivation. Supply concentrates in US and German plasma collection networks facing donor recruitment constraints that limit volume expansion.
- Cholinesterase Inhibitors:Small-molecule acetylcholinesterase blockers including pyridostigmine distribute through standard pharmaceutical wholesale channels without temperature restrictions.
- Immunosuppressants:Corticosteroids and steroid-sparing agents such as azathioprine flow through retail pharmacy networks with established generic substitution protocols.
Monoclonal antibodies dominate revenue concentration. IVIG represents the largest installed patient base where supply constraints create pricing volatility.
End User:
Site-of-care economics reshape competitive access as reimbursement differentials between settings widen.
- Hospitals:Academic medical centers anchor clinical trial enrollment and manage acute myasthenic crisis interventions requiring ICU-level monitoring and mechanical ventilation support.
- Clinics:Neurology-specialized ambulatory infusion centers capture maintenance biologic administration with lower overhead than hospital outpatient departments.
- Homecare:Subcutaneous FcRn antagonist delivery enables patient self-administration, displacing traditional infusion center dependency for stable generalized cases.
- Research Institutions:Academic centers with NIH funding concentration drive biomarker discovery and early-phase mechanism validation studies.
Hospitals retain acute episode management. Clinics are where biologic volume expansion concentrates.
Treatment Approach:
Cost tiers stratify sharply — procedural interventions command premium reimbursement while chronic pharmacological management spreads across generic and branded tiers.
- Pharmacological Management:First-line cholinesterase inhibition and immunosuppression form the chronic maintenance backbone, with generic penetration compressing margins in price-sensitive markets.
- Combination Therapy:Stacked biologic and small-molecule regimens for refractory seropositive generalized patients capture disproportionate clinical investment despite higher adverse event monitoring costs.
- Plasmapheresis:Extracorporeal antibody removal procedures require specialized apheresis units concentrated in tertiary referral centers.
- Surgery:Thymectomy for thymomatous and non-thymomatous generalized cases demands cardiothoracic surgical capacity with neuromuscular anesthesia expertise.
Pharmacological management spans the broadest patient population. Combination therapy is climbing the fastest as biologic access expands.
Route of Administration:
Patient convenience preferences and site-of-service economics drive formulation innovation toward self-administered delivery systems.
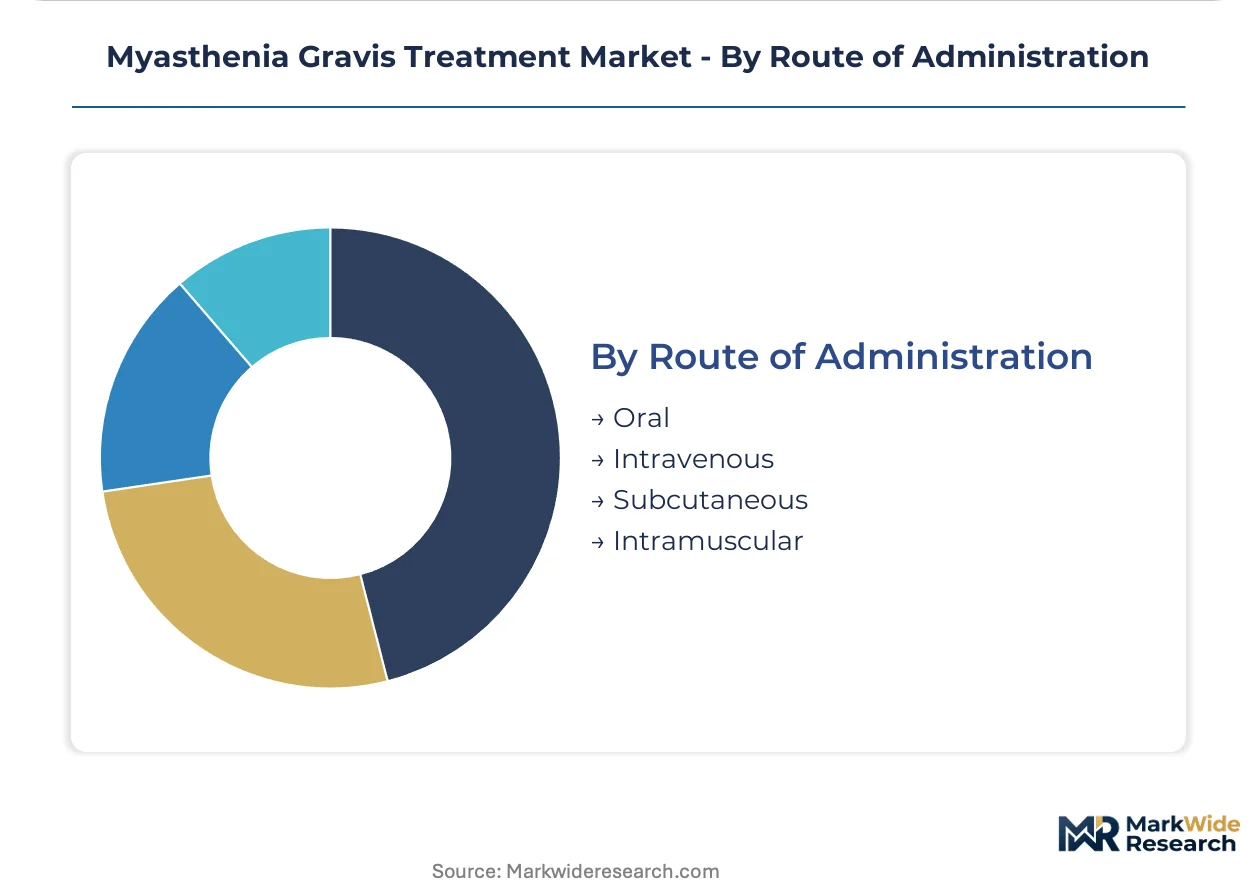
- Intravenous:Infusion-based biologics require healthcare professional administration with adverse event monitoring, concentrating utilization in certified infusion centers.
- Subcutaneous:Patient-administered injection platforms for FcRn antagonists enable home-based therapy, reducing facility fees and expanding rural access.
- Oral:Cholinesterase inhibitors and immunosuppressants distribute through standard retail pharmacy channels with established adherence monitoring programs.
- Intramuscular:Depot corticosteroid formulations serve niche applications requiring prolonged anti-inflammatory effect with reduced dosing frequency.
Intravenous routes anchor current biologic revenue. Subcutaneous delivery is gaining share fastest through patient preference and payer cost containment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Orphan drug incentives in the United States sustain premium pricing for advanced therapies, while European regulators accelerate approval timelines through PRIME eligibility. Japan and Australia expand reimbursement for biologics as diagnostic rates improve.
United States
FDA breakthrough therapy designation compresses clinical trial duration for FcRn antagonists and complement inhibitors. The Orphan Drug Act grants seven-year market exclusivity for novel mechanism therapies targeting refractory patient populations. Neurology clinics in Boston and the Research Triangle are expanding infusion capacity to capture site-of-care revenue from parenteral biologic administration.
Germany
Plasma collection networks in Bavaria and North Rhine-Westphalia anchor European immunoglobulin fractionation capacity amid donor recruitment constraints. BfArM pilot programs for parallel scientific advice reduce sequential regulatory consultation delays for rare disease sponsors. Heidelberg and Munich academic medical centers drive biomarker discovery and early-phase mechanism validation studies for antibody-mediated autoimmune indications.
Japan
PMDA Sakigake designation accelerates review timelines for first-in-class biologics addressing unmet need in generalized myasthenia gravis. The Ministry of Health, Labour and Welfare expands reimbursement for subcutaneous administration formulations under the national health insurance price listing. Tokyo and Osaka neurology-specialized centers concentrate clinical trial enrollment for complement inhibitor development programs.
United Kingdom
NICE technology appraisals for rare disease therapies increasingly incorporate patient-reported outcome measures under evolving real-world evidence guidance. The MHRA operates independent accelerated approval pathways post-Brexit, maintaining alignment with FDA breakthrough criteria. London and Cambridge academic networks anchor NIH-funded biomarker research and specialty neurology referral patterns.
France
ANSM pilot programs for parallel EMA scientific advice streamline protocol alignment with national health technology assessment bodies. Temporary authorization for use pathways enable early patient access to biologics before formal reimbursement listing. Paris and Lyon hospital networks concentrate thymectomy surgical capacity and apheresis units for acute myasthenic crisis management.
Myasthenia Gravis Treatment Market Vendor Landscape
Listed leaders compete with private specialists across rare disease infrastructure and neurology commercial operations. The market structure concentrates around three to five dominant players with established biologic manufacturing and cold-chain distribution capabilities. Strategic archetypes include complement inhibition specialists, FcRn antagonist platform developers, and diversified neurology portfolio operators. Competitive moves center on subcutaneous formulation development and pediatric indication expansion.
Within the complement inhibition tier, Alexion Pharmaceuticals and argenx exemplify platform-based rare disease specialists with differentiated mechanism approaches. UCB occupies a position among neurology-diversified pharmaceutical operators with specialized commercial infrastructure. Grifols represents plasma-derived therapy incumbents facing structural constraints from collection network dependence. These three anchors illustrate how competitive positioning fragments across mechanism validation, manufacturing scale, and site-of-care access capabilities.
| Leading Market Players |
|---|
| Alexion Pharmaceuticals |
| Grifols |
| Avadel Pharmaceuticals |
| Novartis |
| Pfizer |
| AbbVie |
| F. Hoffmann-La Roche |
| argenx |
| UCB |
| Others |
Supply Flow & Price Mechanics
Eighteen-month facility qualification timelines for complement inhibitor cell culture capacity compress pricing power for manufacturers racing to match clinical enrollment curves against fixed cold-chain infrastructure costs. This lead-time constraint concentrates margin pressure on biologic developers while reinforcing premium capture for plasma fractionators with established US and German collection networks.
Pricing Analysis
Certification level creates the primary spread across myasthenia gravis therapies, with FDA-breakthrough-designated biologics commanding substantial premiums over EMA-PRIME-eligible equivalents and unenhanced standard-of-care regimens. Three-tier pricing structure separates orphan-designated monoclonal antibodies from plasma-derived immunoglobulins and generic cholinesterase inhibitors, with cost compression intensifying in the IVIG tier due to donor recruitment bottlenecks. Hospital outpatient departments exhibit lowest price sensitivity given pass-through reimbursement mechanics, while homecare channels face acute payer scrutiny on subcutaneous administration cost offsets.
Supply Chain Analysis
The United States and Germany anchor plasma collection and immunoglobulin fractionation capacity for myasthenia gravis therapies, with Switzerland and Belgium hosting complementary active pharmaceutical ingredient manufacturing for monoclonal antibodies. Production draws from specialized donor recruitment networks, viral inactivation infrastructure, and temperature-controlled distribution fleets. Single-source vulnerability concentrates in US-based plasma collection networks facing geographic donor density constraints. Distribution runs through specialty pharmacy lock-in arrangements mandated by commercial payers for high-cost biologics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among US commercial payers and CMS through specialty pharmacy mandates and site-of-care reimbursement differentials, fragmenting traditional hospital outpatient department capture of infusion revenue.
For Market Incumbents: Shield complement inhibition franchises by deepening captive plasma supply relationships and accelerating subcutaneous formulation transitions that displace infusion center dependency. Secure manufacturing scale-up validation ahead of clinical enrollment curves to avoid eighteen-month facility qualification gaps that cede position to FcRn antagonist competitors with faster cell culture capacity expansion. For New Entrants and Emerging Players: Pediatric indication expansion represents the most penetrable white-space target, with no approved biologic therapies for juvenile myasthenia gravis and established mechanism validation from adult generalized populations. Target academic medical centers with NIH-funded biomarker research infrastructure for early-phase enrollment leverage, then migrate to community neurology clinics through nurse educator deployment for self-injection training programs. For Investors and Strategic Acquirers: Long-term, this sits as a rare disease infrastructure play because orphan drug exclusivity mechanics and accelerated approval pathways create durable margin structures for platform-validated mechanisms. Monitor FDA coverage determinations for subcutaneous versus intravenous administration as the critical signal for site-of-care economics inflection and specialty pharmacy channel consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Subcutaneous Formulation Development | Enables home-based administration that reduces infusion center dependency and expands rural patient access pathways. |
| Pediatric Indication Expansion | Addresses underserved juvenile myasthenia gravis population with no approved biologic therapies and first-mover validation potential. |
| Plasma Collection Network Investment | Secures fractionation capacity against donor recruitment constraints that limit IVIG volume expansion and create pricing volatility. |
| Real-World Evidence Integration | Leverages FDA guidance on electronic health record endpoints to supplement registrational trials with specialty neurology network data. |
| Specialty Pharmacy Partnership | Consolidates fulfillment through CVS Specialty and Accredo for outcomes-based contracting tied to clinical response thresholds. |
Methodological Framework
Initial hypotheses were tested against primary input from drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers and refined through secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Bottom-up patient volume estimates across seropositive generalized, seronegative, and ocular myasthenia gravis segments were triangulated with top-down revenue aggregation from disclosed orphan drug pricing and reimbursement schedules.
Variance decomposition across the projection horizon isolates contribution from treatment line expansion, administration route shifts, and regional regulatory cluster adoption curves. Segmentation dimensions modeled include product type, end user site-of-care, treatment approach intensity, and route of administration, with CAGRs derived from epidemiology-adjusted penetration curves and payer access timeline assumptions. Forecast inputs incorporate plasma collection network capacity constraints and neurology clinic infusion infrastructure expansion rates.
Underlying assumptions cover FDA breakthrough therapy designation velocity, CMS coverage determination timelines, and EMA PRIME eligibility conversion rates, with deviation risk concentrated in diagnostic delay friction exceeding eighteen months and manufacturing scale-up validation bottlenecks. Recalibration cycles align with material shifts in orphan drug exclusivity awards, subcutaneous administration reimbursement rulings, and plasma donor recruitment network expansion announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Liver Transplantation Market
Medical Treatment
Disseminated Intravascular Coagulation (DIC) Treatment Market
Medical Treatment
Mercury Poisoning Treatment Market
Medical Treatment
Pompe Disease Treatment Market
Medical Treatment
Cytokine Release Syndrome Management Market
Medical Treatment
Sepsis Treatment Market
Medical Treatment
Polycystic Ovary Syndrome (PCOS) Treatment Market
Medical Treatment
Ligament Repair and Reconstruction Market
Medical Treatment
Tendonitis Treatment Market
Medical Treatment
Birch Allergy Treatment Market
Medical Treatment
Onchocerciasis Treatment Market
Medical Treatment
Factor XIII Deficiency Treatment Market
Medical Treatment
Europe Platelet Rich Plasma (PRP) Market
Medical Treatment
Histiocytosis Treatment Market
Medical Treatment
Diphtheria Treatment Market
Medical Treatment
Post-Operative Nausea and Vomiting (PONV) Market