
 Selective Serotonin Reuptake Inhibitors Market | 2026-2036
Selective Serotonin Reuptake Inhibitors Market Size, Share, and Industry Trends Forecast 2026-2036
Selective Serotonin Reuptake Inhibitors Market Analytics
India's active pharmaceutical ingredient manufacturing base is tilting toward SSRI bulk production as Western buyers seek supply diversification. Pfizer Inc. leverages its established cardiovascular-metabolic franchise to cross-promote mental health portfolios in integrated care settings. Eli Lilly and Co. sustains R&D intensity in neuroscience through dedicated psychiatric drug discovery programs. H. Lundbeck AS anchors its commercial presence in European markets where reimbursement for depression therapies remains favorable.
Selective serotonin reuptake inhibitors constitute a class of psychotropic compounds that functionally inhibit the serotonin transporter SERT, thereby elevating synaptic serotonin concentrations to modulate mood regulation. These agents serve primarily as first-line pharmacotherapy for major depressive disorder and generalized anxiety conditions across outpatient and institutional settings. Escitalopram and sertraline formulations command the largest prescription volumes within the product type dimension, reflecting established efficacy profiles and broad payer coverage. Hospital and clinic channels within the end user segment concentrate the highest margin pools due to institutional procurement scale, while retail pharmacies maintain volume leadership in maintenance therapy dispensing.
The FDA governs SSRI approval pathways through stringent antidepressant suicidality labeling mandates and post-market surveillance requirements under REMS frameworks. The EMA's PRAC coordinates European pharmacovigilance for psychiatric medicines, influencing formulation standards and risk management plans across member states. India's CDSCO enforces bioequivalence protocols for generic SSRI registrations, shaping export competitiveness for domestic manufacturers. Stakeholders must monitor evolving FDA guidance on digital therapeutics co-therapy, as software-based cognitive behavioral interventions may alter reimbursement and prescribing hierarchies for traditional pharmaceutical interventions.

Market Dynamics
Hospital procurement consolidation and the FDA's updated antidepressant suicidality labeling mandates are compressing development timelines while expanding institutional purchasing power for escitalopram and sertraline formulations. These structural forces are redistributing margin pools toward high-volume contract channels.
Growth Catalysts
- Medicare reimbursement expansion:Depression management protocols in the United States now cover SSRI maintenance therapy, institutionalizing prescription volumes through federal payment structures.
- EU MDR pharmacovigilance standards:Tighter adverse-event reporting requirements for psychiatric medicines are accelerating quality differentiation among compliant manufacturers.
- Active pharmaceutical ingredient diversification:Western pharmaceutical buyers are redirecting bulk SSRI sourcing toward Indian manufacturing clusters to reduce supply concentration risk.
Market Restraints
- Raw material input volatility:Serotonin precursor chemical supplies face price instability due to concentrated production in specific Asian chemical manufacturing zones.
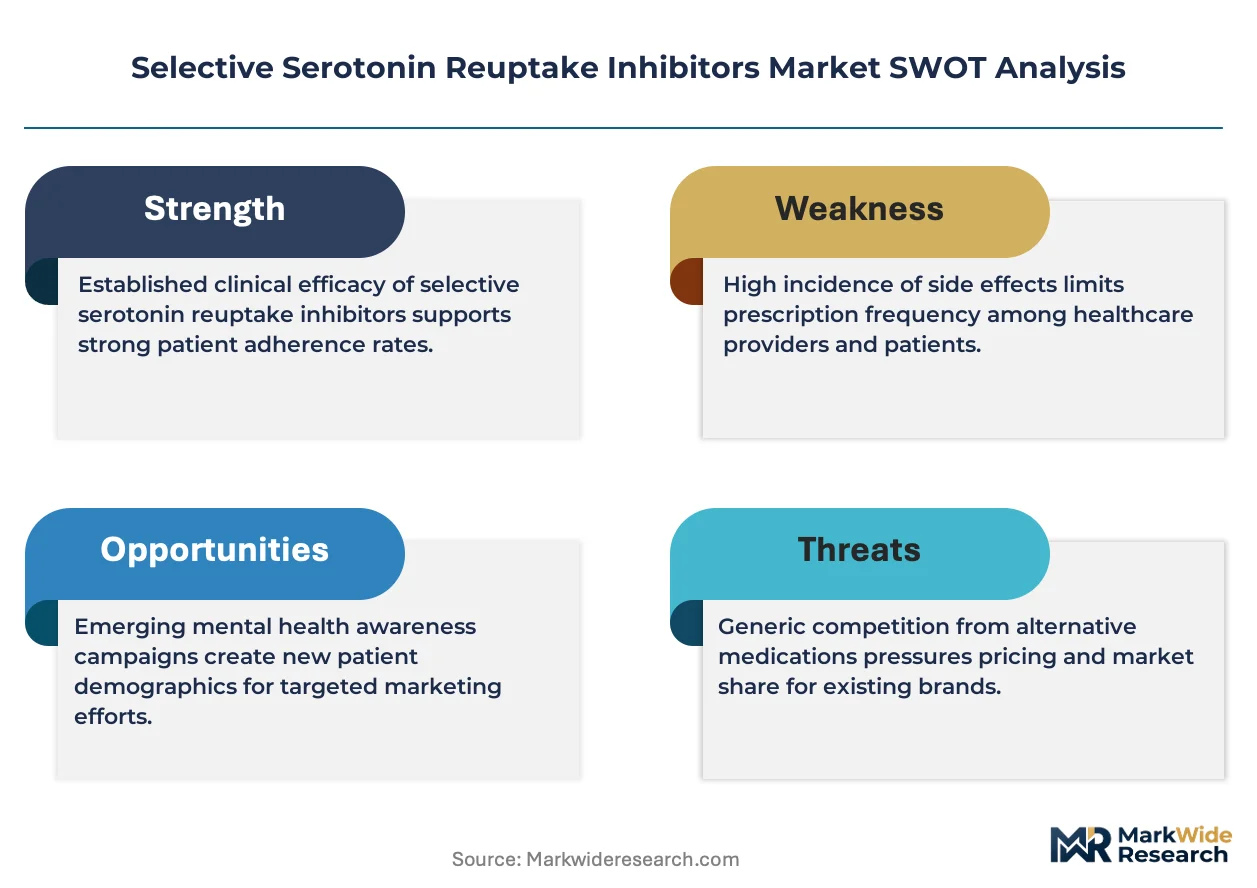
- Generic substitution saturation:Bioequivalent SSRI formulations from multiple suppliers are compressing branded pricing power in retail pharmacy channels.
- REMS compliance burden:The FDA's Risk Evaluation and Mitigation Strategies impose ongoing surveillance costs that disproportionately affect smaller market entrants.
Strategic Opportunities
- Digital therapeutics integration:Software-based cognitive behavioral interventions are creating combination therapy protocols that preserve SSRI anchoring in treatment hierarchies.
- European reimbursement stability:Depression therapy payment frameworks in Germany, France, and the Nordic markets sustain favorable pricing environments for established agents.
- Hospital formulary consolidation:Institutional procurement scale in United States health systems enables long-term supply agreements with volume guarantees.
Industry Challenges
- Specialized pharmacovigilance talent scarcity:Post-market surveillance for psychiatric medicines requires rare expertise in neuropsychiatric adverse-event assessment.
- Legacy manufacturing equipment retooling:CDSCO bioequivalence protocol updates demand capital-intensive facility upgrades for Indian API exporters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Selective Serotonin Reuptake Inhibitors Market |
| Market Size in 2026 | $15.8 Billion |
| Market Size in 2035 | $22.88 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fluoxetine, Sertraline, Citalopram, Escitalopram End User: Clinics, Hospitals, Online Pharmacies, Retail Pharmacies Delivery Mode: Oral Tablets, Liquid Solutions, Injectable Formulations, Extended-Release Capsules Indication: Depression, Anxiety Disorders, OCD, PTSD |
| Companies Covered | GlaxoSmithKline Plc, Teva, Pfizer Inc., Sandoz, Sun Pharmaceutical, Eli Lilly and Co., H. Lundbeck AS, Mylan, Allergan Plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Selective Serotonin Reuptake Inhibitors Market Evolving Landscape
Continuous manufacturing technologies and real-world evidence requirements are compressing traditional batch production cycles while elevating pharmacokinetic precision standards across SSRI formulation development. These shifts favor capital-intensive producers with integrated quality systems.
Continuous direct compression technology is collapsing the traditional granulation-drying-milling sequence for SSRI tablet production into a single integrated flow. Contract manufacturing organizations serving European markets are adopting these systems to meet EMA quality-by-design expectations. The technology is collapsing capital recovery timelines by reducing batch failure rates and accelerating regulatory filing preparation.
The EU Medical Device Regulation's tightened pharmacovigilance standards are extending post-market surveillance obligations to combination products incorporating drug-device delivery systems. Pharmaceutical manufacturers must now maintain device-quality management systems alongside pharmaceutical GMP compliance. European psychiatric medicine sponsors are responding by consolidating device partnerships with established respiratory and injectable delivery specialists.
Institutional buyers in United States health systems are consolidating SSRI procurement through centralized pharmacy and therapeutics committees. Volume-based contracting with sole-source or dual-source arrangements is displacing fragmented physician-level prescribing autonomy. This concentration is most visible in integrated delivery networks covering multiple states, where formulary standardization reduces inventory complexity and leverages purchasing scale.
Selective Serotonin Reuptake Inhibitors Market Segmentation
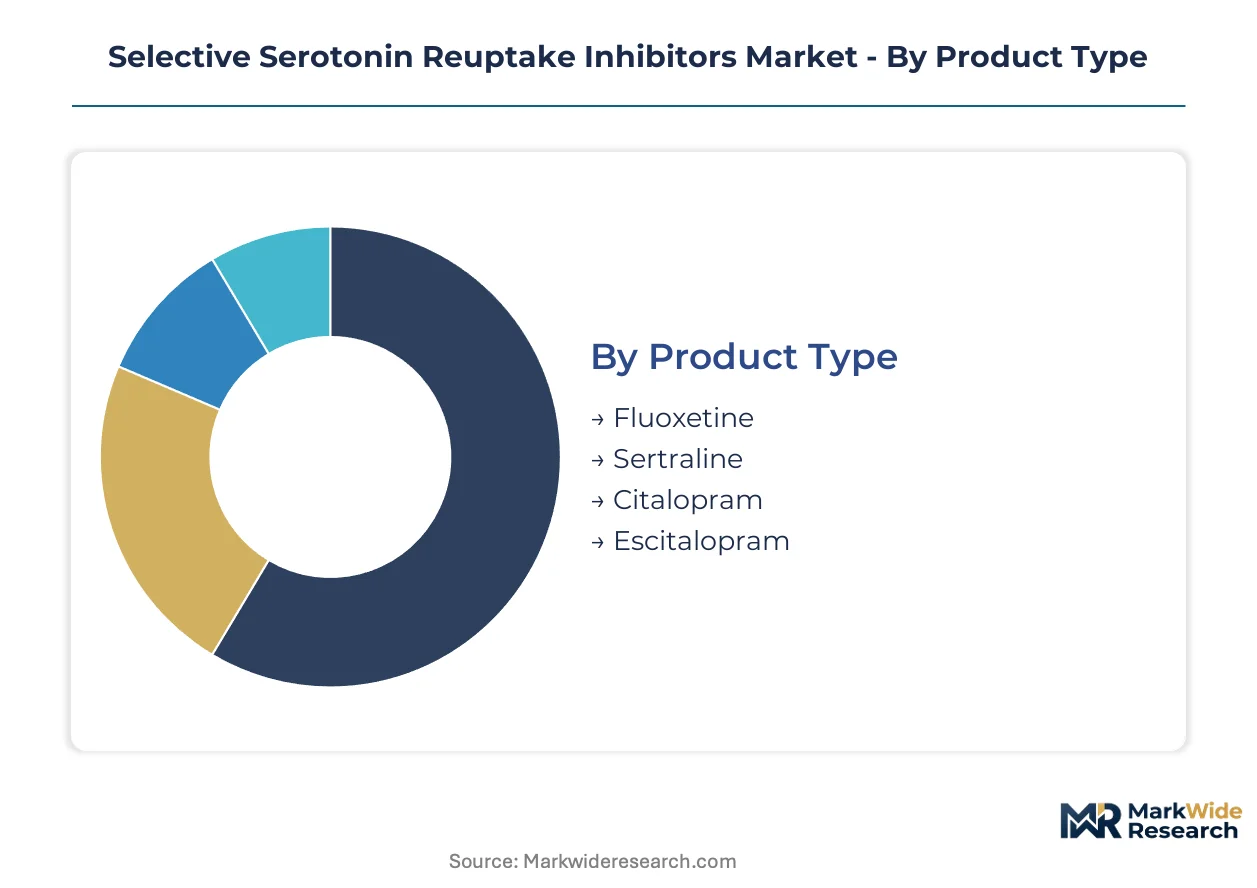
SSRI market segmentation reveals divergent procurement rhythms across institutional and retail channels, with hospital formularies cycling annually while retail pharmacy demand follows patient refill patterns. Understanding these temporal dynamics helps manufacturers align production scheduling with channel-specific purchasing windows.
Product Type:
Prescription refill cycles vary dramatically across molecular entities, with established agents turning over predictably and newer formulations experiencing volatile demand swings as payer coverage evolves.
- Fluoxetine:The longest-acting SSRI with active metabolite norfluoxetine extending half-life to days, creating distinctive once-weekly dosing options. Demand concentrates in United States Medicaid programs where generic pricing and established prior authorization pathways sustain volume. The FDA's suicidality labeling mandates have compressed new patient initiation protocols, slowing cycle times for first prescriptions.
- Sertraline:A dibenzothiepine derivative with favorable drug-drug interaction profile compared to earlier agents. Hospital procurement in United States integrated delivery networks anchors the highest-margin contracts, with formulary committees standardizing on this agent for depression protocols. Medicare reimbursement expansion for maintenance therapy institutionalizes repeat prescribing through federal payment structures.
- Citalopram:A racemic mixture with established bioequivalence pathways supporting robust generic competition. Retail pharmacy channels in Germany and France sustain volume through favorable depression therapy reimbursement frameworks.
- Escitalopram:The S-enantiomer of citalopram with refined serotonin transporter selectivity. Institutional procurement scale in United States health systems enables long-term supply agreements with volume guarantees.
Sertraline anchors the volume base while escitalopram gains share at the steepest rate.
End User:
Margin structures stratify sharply across purchasing entities, with consolidated institutional buyers extracting price concessions unavailable to fragmented retail operators.
- Clinics:Outpatient mental health settings with direct prescriber influence over formulary selection. United States community mental health centers concentrate demand through state-level procurement consortia.
- Hospitals:Institutional pharmacy and therapeutics committees drive centralized SSRI procurement through volume-based contracting. The EU MDR's tightened pharmacovigilance standards accelerate quality differentiation among compliant manufacturers serving European hospital systems.
- Online Pharmacies:Digital dispensing platforms with automated refill management and direct-to-patient logistics. India's CDSCO bioequivalence protocols shape export competitiveness for domestic manufacturers supplying cross-border e-pharmacy channels.
- Retail Pharmacies:Fragmented dispensing infrastructure with generic substitution saturation compressing branded pricing power. Maintenance therapy volumes sustain cash flow despite margin pressure.
Hospitals command the pricing power while online pharmacies expand most quickly.
Delivery Mode:
Manufacturing complexity and regulatory burden create tiered competitive barriers, with conventional oral formats permitting commodity competition and specialized delivery systems protecting niche margins.
- Oral Tablets:The dominant dispensing format with established USP dissolution specifications and broad manufacturing capacity. Continuous direct compression technology is collapsing traditional production sequences into integrated flows for high-volume sertraline and escitalopram manufacturing.
- Liquid Solutions:Pediatric and geriatric formulations with taste-masking requirements and stability challenges. Concentrated demand in United States long-term care facilities where swallowing difficulties elevate alternative format preference.
- Injectable Formulations:Hospital-controlled administration with REMS compliance burden disproportionately affecting smaller market entrants. Emergency department protocols in United States academic medical centers anchor specialized use cases.
- Extended-Release Capsules:Modified-release technology with polymer matrix or osmotic pump systems commanding formulation premiums. European reimbursement stability in Germany and Nordic markets sustains favorable pricing for advanced delivery systems.
Oral tablets anchor the volume base while extended-release capsules gain share at the steepest rate.
Indication:
Clinical evidence requirements and prescriber specialization patterns fragment addressable markets, with depression protocols permitting broad prescribing and anxiety subtypes demanding targeted expertise.
- Depression:The foundational indication with broad prescriber eligibility and established screening protocols. Medicare reimbursement for depression management in the United States drives prescription volumes through federal payment structures.
- Anxiety Disorders:Generalized anxiety and panic indications with diagnostic specificity requirements. Hospital-based procurement expands as mental health screening protocols broaden in United States health systems.
- OCD:Obsessive-compulsive disorder with higher dosing requirements and longer titration periods. Specialized psychiatric practice concentration in urban United States markets creates prescriber loyalty effects.
- PTSD:Post-traumatic stress disorder with Department of Veterans Affairs formulary influence in the United States and emerging digital therapeutics integration creating combination therapy protocols.
Depression anchors the volume base while PTSD applications gain share at the steepest rate.

Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's pharmaceutical cold-chain infrastructure underwrites Western Europe's distribution dominance for temperature-sensitive psychotropic compounds. This logistics backbone channels SSRI formulations into German hospital networks and Dutch wholesale distribution hubs.
United States
Medicare Part D reimbursement expansion for depression management protocols institutionalizes prescription volumes through federal payment structures. The FDA's REMS framework imposes ongoing surveillance costs that reshape competitive dynamics among manufacturers. New Jersey's pharmaceutical corridor concentrates formulation capacity for escitalopram and sertraline production serving domestic hospital procurement.
Germany
Statutory health insurance reimbursement for depression therapies sustains favorable pricing environments for established SSRI agents. The EMA's PRAC pharmacovigilance coordination influences risk management plans across member states. The Rhine-Main region anchors commercial operations for psychiatric medicine sponsors targeting European hospital formularies.
India
Western pharmaceutical buyers redirect bulk SSRI sourcing toward Indian manufacturing clusters to reduce supply concentration risk. CDSCO bioequivalence protocols shape export competitiveness for domestic API manufacturers. Hyderabad's active pharmaceutical ingredient base tilts toward serotonin precursor chemical production serving global generic formulation demand.
United Kingdom
NICE clinical guidelines for depression treatment standardize SSRI first-line prescribing across NHS trust formularies. MHRA post-Brexit regulatory autonomy maintains alignment with EMA pharmacovigilance standards while preserving distinct national approval pathways. The Golden Triangle biotech cluster between London, Oxford, and Cambridge hosts specialized pharmacovigilance service providers supporting psychiatric medicine sponsors.
Japan
PMDA approval pathways for antidepressants incorporate distinctive cultural adaptation requirements for clinical trial endpoints. METI industrial policy supports domestic pharmaceutical manufacturing capacity for central nervous system agents. The Kansai region's Osaka pharmaceutical hub maintains formulation expertise for extended-release SSRI technologies targeting aging-population demand.
Selective Serotonin Reuptake Inhibitors Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in API supply and niche formulation segments. The SSRI market structures around three tiers: research-intensive originators with psychiatric drug discovery programs, high-volume generic manufacturers with bioequivalence capabilities, and specialized CMOs with continuous manufacturing installations. Consolidation pressures concentrate among mid-scale generic producers facing REMS compliance burdens. Dominant competitive moves include backward integration into active pharmaceutical ingredient supply and strategic partnerships with digital therapeutics developers.
Among Danish-origin research-intensive developers, H. Lundbeck AS occupies a position exemplifying neuroscience-focused portfolio architecture. Pfizer Inc. and Eli Lilly and Co. represent the integrated pharmaceutical conglomerate archetype, leveraging cardiovascular-metabolic franchises to cross-promote mental health portfolios in institutional care settings. These three anchors illustrate divergent strategic postures: specialized psychiatric focus versus diversified therapeutic platform breadth.
| Leading Market Players |
|---|
| GlaxoSmithKline Plc |
| Teva |
| Pfizer Inc. |
| Sandoz |
| Sun Pharmaceutical |
| Eli Lilly and Co. |
| H. Lundbeck AS |
| Mylan |
| Allergan Plc |
| Others |
Value Network & Pricing Analysis
Raw material input volatility in serotonin precursor chemicals determines both the spread between branded and generic pricing tiers and the geographic redistribution of active pharmaceutical ingredient sourcing. Western pharmaceutical buyers now demand supply diversification from Indian manufacturing clusters to mitigate single-source concentration risk in Asian chemical zones.
Pricing Analysis
Volume-discount tiering structures dominate institutional procurement, with United States health systems extracting steepest concessions through centralized pharmacy and therapeutics committees. Three-tier pricing structure across premium, standard, and economy levels separates patented extended-release formulations from bioequivalent generics and commodity oral tablets. Price differentiation hinges on FDA REMS compliance certification and hospital formulary inclusion status. Cost compression in the generic tier is intensifying because Indian API manufacturers compete aggressively on CDSCO bioequivalence credentials. Retail pharmacy channels exhibit highest price sensitivity due to fragmented dispensing infrastructure, while hospital procurement demonstrates lowest sensitivity given volume guarantees and sole-source contracting.
Supply Chain Analysis
Export-control regime restrictions on specialized manufacturing equipment limit technology transfer to emerging API production zones, constraining supply expansion outside established hubs. Geographic supply concentration centers on India, China, and the United States for serotonin precursor chemicals and finished formulations. Raw material dependencies include tryptophan derivatives, specialized solvents, and polymer matrix materials for extended-release technologies. Single-source vulnerability persists in concentrated Asian chemical manufacturing zones for precursor inputs. Distribution runs through Rotterdam's pharmaceutical cold-chain infrastructure into German hospital networks and Dutch wholesale hubs serving European markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital therapeutics integration threatens traditional SSRI anchoring in treatment hierarchies, forcing incumbents to defend substitution risk through combination therapy protocols that preserve pharmaceutical relevance.
For Market Incumbents: Entrench formulary position through backward integration into Indian API supply and REMS compliance infrastructure that smaller competitors cannot replicate. Secure long-term volume agreements with United States integrated delivery networks before procurement consolidation peaks. Digital CBT platforms threaten prescription volumes; co-development partnerships with software-based intervention developers preserve SSRI anchoring in stepped-care protocols.
For New Entrants and Emerging Players: Establish a beachhead in liquid solution formulations for pediatric and geriatric indications where swallowing difficulties create underserved demand. Target United States long-term care facilities with taste-masked alternatives to oral tablets. Penetrate through specialized CMO relationships with continuous direct compression capabilities rather than capital-intensive facility buildouts.
For Investors and Strategic Acquirers: FDA digital therapeutics guidance reshapes the acquisition landscape by elevating combination product valuations over standalone pharmaceutical assets. Five-to-ten year viability favors targets with integrated pharmacovigilance capabilities and European MDR compliance infrastructure. Monitor EMA PRAC risk management plan enforcement as signal for quality differentiation premiums among compliant manufacturers.
| Strategic Initiative | Industry Significance |
|---|---|
| API Backward Integration | Captive supply of serotonin precursors from Indian manufacturing clusters reduces tariff exposure and raw material volatility. |
| Digital Therapeutics Partnership | Software-based CBT integration preserves SSRI anchoring in stepped-care protocols against substitution risk. |
| Continuous Manufacturing Scale-Up | Adoption of direct compression technology meets EMA quality-by-design expectations and collapses batch failure rates. |
| Hospital System Partnership | Long-term formulary agreements with United States integrated delivery networks lock in volume guarantees. |
| Pharmacovigilance Infrastructure Investment | REMS compliance capabilities and neuropsychiatric adverse-event expertise create defensive moats against smaller entrants. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases to establish baseline market sizing. Drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists provided qualitative input through structured interviews. Bottom-up prescription volume modeling triangulates against top-down manufacturer revenue aggregation across the analysis window.
Forecast inputs include treatment line positioning, dosage form complexity, administration route, and regional regulatory cluster differentiation. Segmentation dimensions span molecular entity, end-user channel, delivery mode, and indication severity. CAGRs derive from fitted growth curves calibrated to Medicare reimbursement expansion trajectories and EU MDR compliance cost absorption patterns. Pricing dynamics incorporate volume-discount tiering and generic substitution saturation effects.
Stress conditions across raw material input volatility, digital therapeutics substitution velocity, and hospital procurement consolidation pace were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory timeline adherence and reimbursement stability. Material shifts in FDA digital therapeutics guidance or Medicare depression management protocol revisions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Motilium Market
Pharmaceuticals
Global Androgen Deprivation Therapy Market
Pharmaceuticals
Paclitaxel Injection Market
Pharmaceuticals
Global Eylea Market
Pharmaceuticals
Oral Anticoagulant Market
Pharmaceuticals
US Pharmaceutical CMO Market
Pharmaceuticals
Sitagliptin Market
Pharmaceuticals
Nicotine Replacement Therapy (NRT) Market
Pharmaceuticals
Oral Solid Dosage Contract Manufacturing Market
Pharmaceuticals
Mild Laxatives Market
Pharmaceuticals
Methylphenidate Hydrochloride Market
Pharmaceuticals
Traumatic Brain Injury Drugs Market
Pharmaceuticals
Anthelmintic Drugs Market
Pharmaceuticals
Europe Generic Drug Market
Pharmaceuticals
Global Antiemetics Market
Pharmaceuticals
Fibroblast Activation Protein Inhibitors Market