
 Global Lambert-Eaton Myasthenic Syndrome Treatment Market | 2026-2036
Global Lambert-Eaton Myasthenic Syndrome Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Lambert-Eaton Myasthenic Syndrome Treatment Market Foresight
Neurology clinics is restructuring care delivery for Lambert-Eaton myasthenic syndrome patients, shifting from general neurology hubs to dedicated autoimmune neuromuscular centers. Catalyst Pharmaceuticals leverages its amifampridine specialization to dominate the symptomatic treatment segment. argenx SE sustains competitive presence through its FcRn antagonist pipeline targeting autoimmune neuromuscular indications.
Lambert-Eaton myasthenic syndrome treatment encompasses pharmacologic interventions that enhance presynaptic acetylcholine release and modulate autoimmune activity against voltage-gated calcium channels, with amifampridine functioning as a potassium channel blocker that prolongs nerve terminal depolarization to improve neuromuscular transmission. Oral administration occupies the largest volume share due to patient convenience and chronic disease management requirements, while intravenous immunoglobulin concentrates margin pools through hospital-based infusion protocols and premium reimbursement structures.
FDA orphan drug exclusivity and EMA's PRIME scheme shape competitive entry timelines for novel Lambert-Eaton myasthenic syndrome therapies, compressing regulatory review periods and accelerating conditional approval pathways. The EU AI Act introduces algorithmic scrutiny for diagnostic tools used in autoimmune neuromuscular disease identification, affecting companion diagnostic development strategies. Stakeholders must monitor evolving HTA assessment criteria across Germany's G-BA and England's NICE as these bodies refine value frameworks for ultra-rare neurological conditions.
Market Dynamics
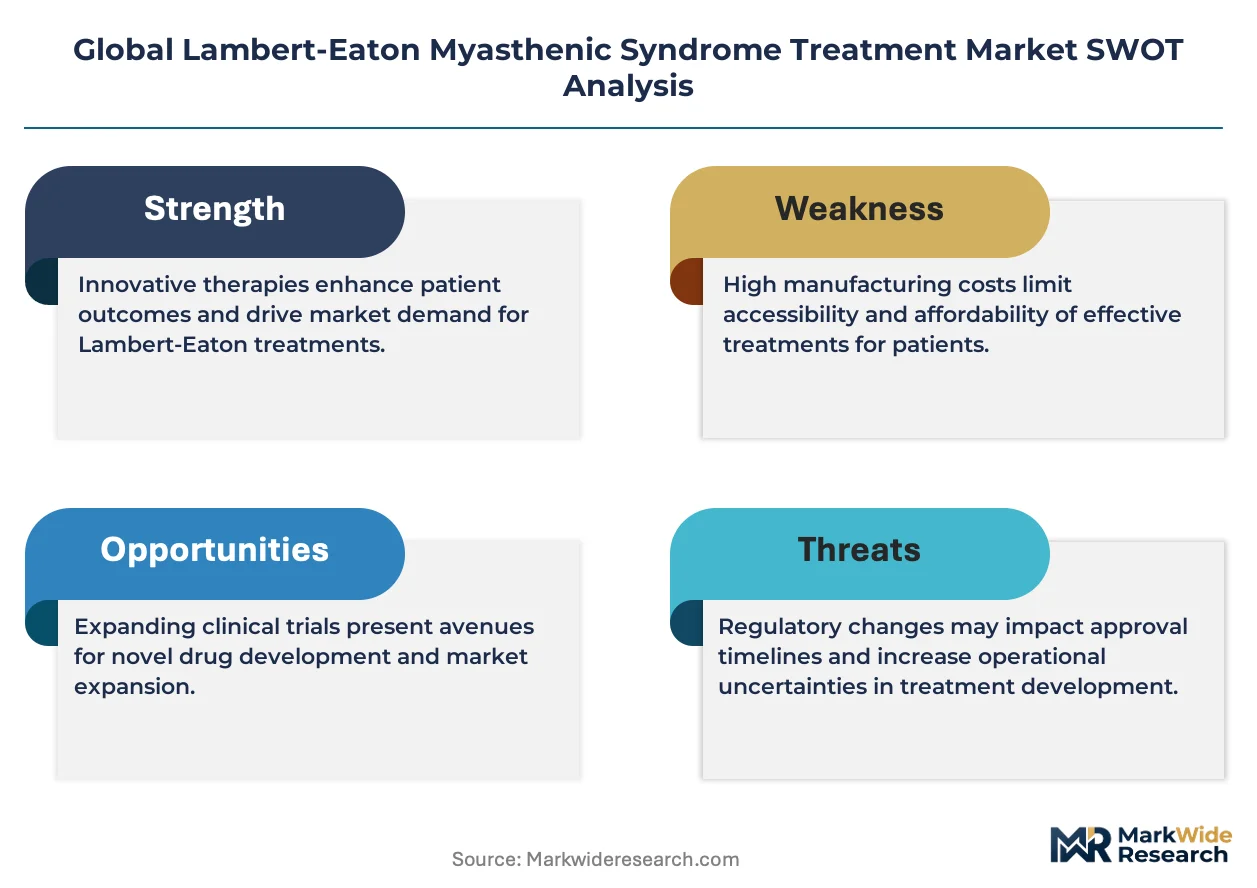
Orphan drug incentives from FDA and EMA are compressing development timelines for autoimmune neuromuscular therapies, while specialty hospital consolidation reshapes patient access pathways across developed markets.
Growth Catalysts
- FDA Orphan Drug Exclusivity:Seven-year market exclusivity provisions accelerate investment in voltage-gated calcium channel-targeted therapies by de-risking commercialization timelines.
- Specialty Hospital Networks:Dedicated autoimmune neuromuscular centers in the United States, Germany, and Japan concentrate diagnostic expertise and streamline referral pathways.
- EMA PRIME Designation:Priority medicines status grants enhanced regulatory support and accelerated assessment pathways for novel LEMS therapeutics entering European markets.
Market Restraints
- Plasma Supply Volatility:Intravenous immunoglobulin production depends on fractionated human plasma, creating input cost instability and supply security concerns.
- Specialist Neurologist Scarcity:Limited autoimmune neuromuscular expertise concentrates diagnostic capacity in tertiary academic centers, restricting patient throughput.
- Reimbursement Complexity:Germany's G-BA and England's NICE maintain divergent value assessment frameworks for ultra-rare neurological conditions, creating market access friction.
Strategic Opportunities
- Companion Diagnostic Integration:Voltage-gated calcium channel antibody testing convergence with automated immunoassay platforms enables point-of-care diagnostic expansion.
- Japan's Sakigake Pathway:Pioneering review designation offers priority consultation and shortened approval timelines for innovative LEMS therapies.
- Home Infusion Services:Subcutaneous immunoglobulin formulations and specialized nursing networks shift administration from hospital to outpatient settings.
Industry Challenges
- Electrophysiology Training Gaps:Repetitive nerve stimulation expertise and single-fiber electromyography proficiency remain concentrated in aging specialist cohorts.
- Multicenter Trial Coordination:Ultra-rare disease prevalence necessitates international site activation across dispersed academic medical centers, complicating patient recruitment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Lambert-Eaton Myasthenic Syndrome Treatment Market |
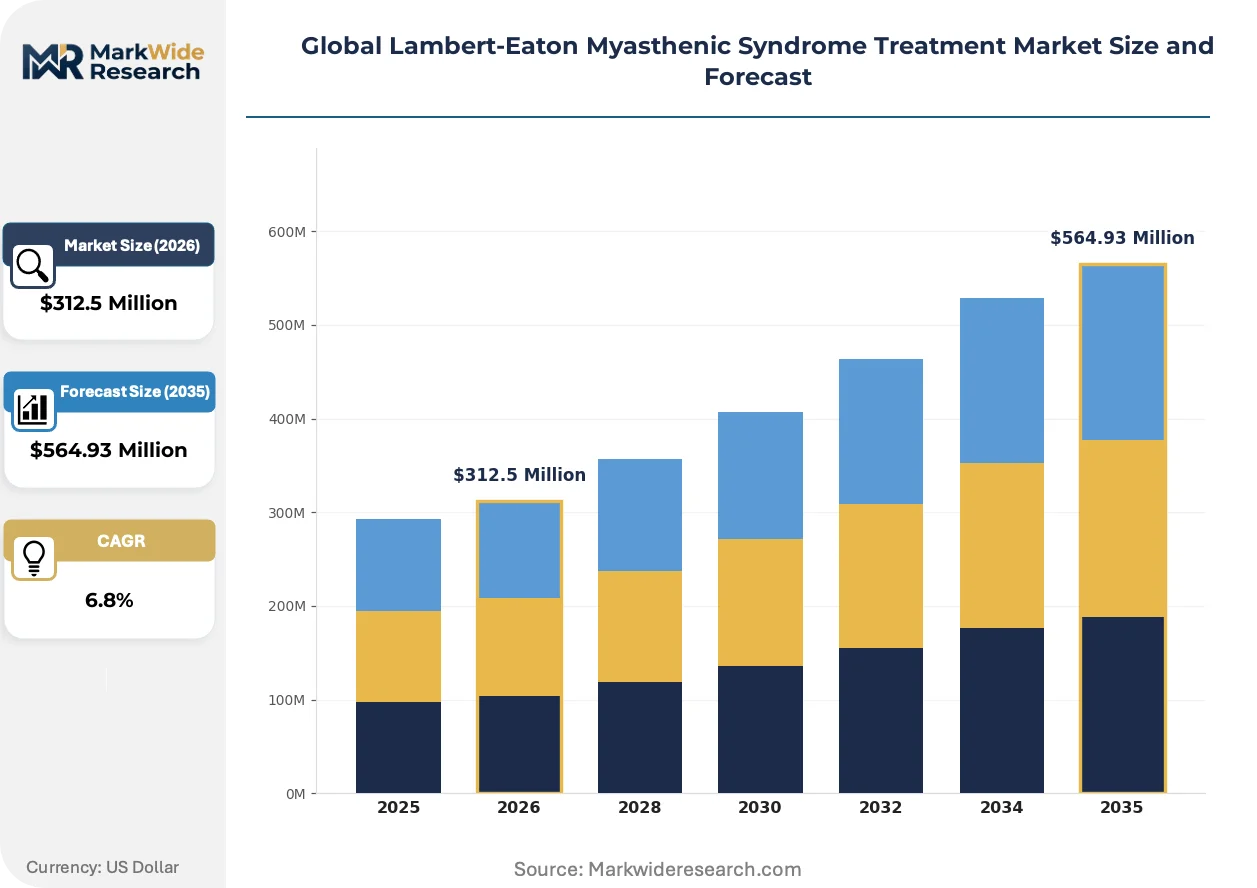
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $564.93 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Amifampridine, Immunoglobulins, Corticosteroids, Azathioprine, Rituximab Therapy Area: Neuromuscular Disorders, Autoimmune Disorders, Rare Diseases, Neurodegenerative Conditions End User: Neurology Clinics, Specialty Hospitals, Research Institutes, Outpatient Care Centers Delivery Mode: Oral Administration, Intravenous Injection, Subcutaneous Injection, Intramuscular Injection |
| Companies Covered | Catalyst Pharmaceuticals, Inc., Jacobus Pharmaceutical Company, Inc., Grifols, S.A., Alexion Pharmaceuticals, Inc., Takeda Pharmaceutical Company Limited, argenx SE, CSL Behring, BioMarin Pharmaceutical Inc., Merck & Co., Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Lambert-Eaton Myasthenic Syndrome Treatment Market Shifts & Advancements
Diagnostic automation and regulatory pathway optimization are converging to reshape competitive positioning in autoimmune neuromuscular therapeutics, while care delivery models fragment across institutional and home-based settings.
Automated immunoassay platforms for voltage-gated calcium channel antibody detection are automating diagnostic workflows previously dependent on specialized reference laboratory capacity. Community neurology practices in the United States and Western Europe are adopting these systems to reduce referral delays. This automation is compressing time-to-diagnosis intervals and expanding addressable patient identification beyond academic center catchment areas.
The EU AI Act introduces conformity assessment requirements for algorithmic diagnostic tools deployed in autoimmune neuromuscular disease identification. Manufacturers of machine-learning-assisted electromyography interpretation systems must now demonstrate clinical validation and post-market monitoring protocols. Neurology device developers are restructuring quality management systems to accommodate these algorithmic transparency mandates ahead of 2025 enforcement timelines.
Hospital-based infusion centers face displacement from home healthcare nursing networks capable of administering subcutaneous immunoglobulin and potassium channel blocker therapies. Payers in Germany and Japan are expanding reimbursement for domiciliary administration, reducing institutional overhead capture. This channel shift is most pronounced among stabilized chronic patients seeking to minimize travel burden to tertiary centers.
Global Lambert-Eaton Myasthenic Syndrome Treatment Market Segmentation
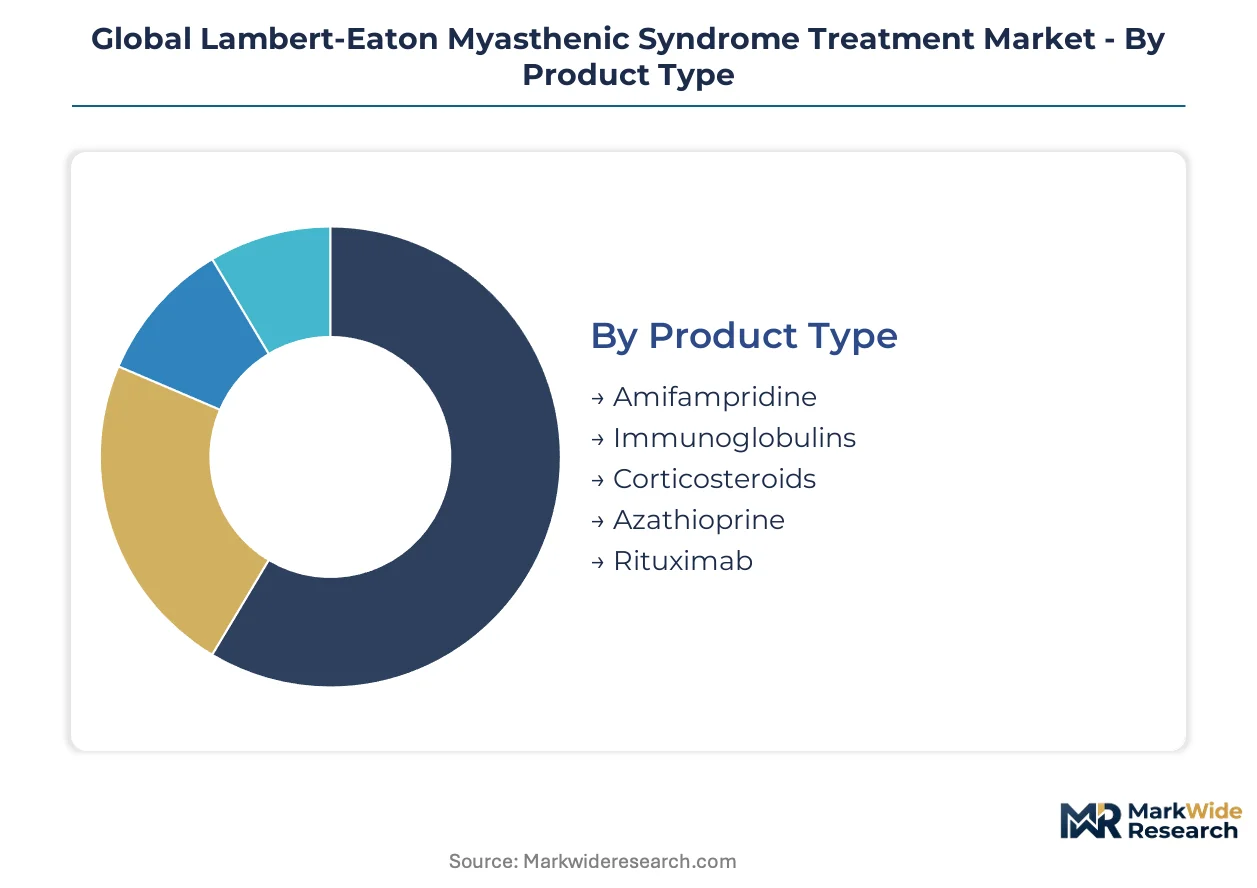
Segmentation in the Lambert-Eaton myasthenic syndrome treatment market reflects divergent regulatory pathways and reimbursement frameworks across therapeutic modalities. Each category carries distinct certification burdens from FDA, EMA, and national health technology assessment bodies that shape commercial viability and patient access trajectories.
Product Type:
FDA orphan drug exclusivity and EMA PRIME designation requirements concentrate certification complexity on novel molecular entities versus generic immunosuppressants. Voltage-gated calcium channel-targeted therapies face enhanced pharmacovigilance obligations compared to repurposed agents.
- Amifampridine:Potassium channel blocker prolonging nerve terminal depolarization to enhance acetylcholine release. Demand concentrates in the United States and Germany where Catalyst Pharmaceuticals maintains regulatory exclusivity and streamlined reimbursement through specialty pharmacy networks.
- Immunoglobulins:Polyclonal antibody preparations derived from fractionated human plasma that modulate autoantibody-mediated pathophysiology. Hospital-based infusion centers in Japan and academic medical centers in Germany capture volume through premium reimbursement for intravenous administration protocols.
- Corticosteroids:Broad immunosuppressants with established corticosteroid-sparing protocols in autoimmune neuromuscular practice.
- Azathioprine:Purine antimetabolite requiring TPMT enzyme testing before initiation per FDA labeling.
- Rituximab:Anti-CD20 monoclonal antibody administered in refractory cases under off-label protocols with biosimilar competition intensifying.
Leading the category by volume: Amifampridine. Expanding most quickly: Immunoglobulins through subcutaneous formulation adoption.
Therapy Area:
Cost tier stratification separates premium orphan-designated therapies from commodity immunosuppression, with pricing power correlating to indication specificity and regulatory exclusivity duration.
- Neuromuscular Disorders:Encompasses presynaptic transmission defects including Lambert-Eaton myasthenic syndrome and overlapping myasthenia gravis presentations. Tertiary referral networks in the United States concentrate diagnostic expertise and infusion capacity.
- Autoimmune Disorders:Broad category capturing voltage-gated calcium channel antibody-mediated pathogenesis alongside other autoantibody-driven conditions. Germany's G-BA assessment frameworks prioritize comparative effectiveness evidence for reimbursement.
- Rare Diseases:Orphan indication status triggering FDA seven-year exclusivity and EMA protocol assistance.
- Neurodegenerative Conditions:Adjacent category with differential diagnostic overlap requiring electromyography discrimination.
Volume concentration: Neuromuscular Disorders. Steepest expansion trajectory: Rare Diseases through regulatory incentive capture.
End User:
Customer type fragmentation reflects care delivery migration from institutional settings toward ambulatory and home-based administration models.
- Neurology Clinics:Dedicated autoimmune neuromuscular centers consolidating diagnostic workflows and long-term management. United States academic medical centers and German university hospitals anchor referral networks with electromyography proficiency.
- Specialty Hospitals:Tertiary institutions housing infusion pharmacies and intensive monitoring capabilities for immunoglobulin loading doses. Japan's designated rare disease hospitals concentrate eligible patient pools.
- Research Institutes:Clinical trial sites for novel FcRn antagonists and complement inhibitors.
- Outpatient Care Centers:Community-based settings adopting subcutaneous immunoglobulin and oral potassium channel blocker protocols.
Patient volume leader: Neurology Clinics. Gaining share fastest: Outpatient Care Centers through home infusion reimbursement expansion.
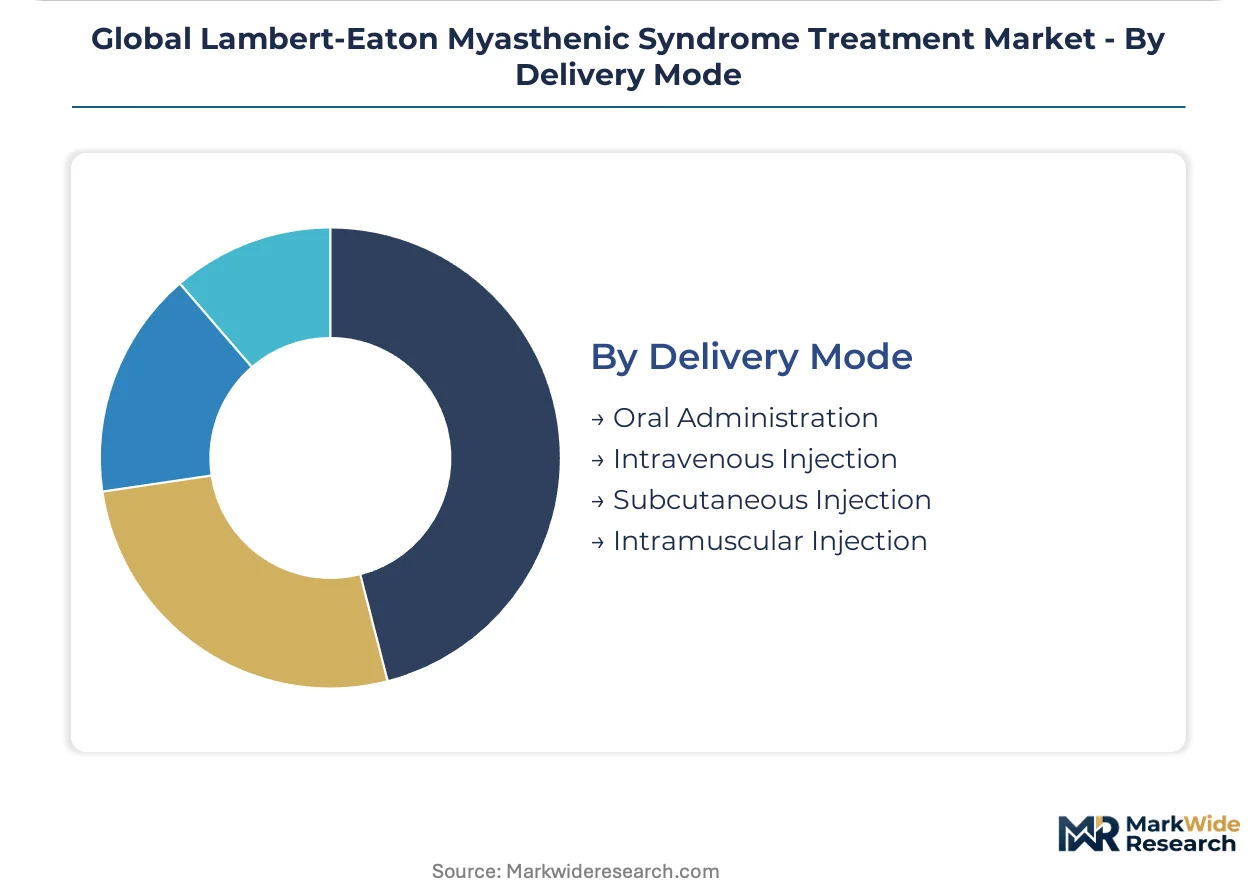
Delivery Mode:
Supply concentration dynamics favor oral and subcutaneous routes as plasma fractionation capacity constraints and hospital overhead costs reshape channel economics.
- Oral Administration:Amifampridine tablets and corticosteroid regimens enabling chronic disease self-management. Patient convenience drives preference in the United States and Western Europe where pharmacy benefit structures support oral specialty drug coverage.
- Intravenous Injection:Immunoglobulin concentrates and rituximab requiring infusion center supervision. Hospital-based administration in Germany and Japan maintains margin capture through DRG-based reimbursement.
- Subcutaneous Injection:Immunoglobulin formulations shifting toward home nursing networks.
- Intramuscular Injection:Limited application for corticosteroid depot preparations in acute exacerbation management.
Volume dominance: Oral Administration. Climbing the fastest: Subcutaneous Injection through payer cost-containment initiatives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Diagnostic expertise concentrates in the United States, Germany, and Japan where referral networks for rare autoimmune neuromuscular conditions are most developed. Consumption of amifampridine and immunoglobulin therapies outpaces manufacturing capacity in these markets, creating import dependence for plasma-derived products.
United States
Specialty pharmacy networks and academic medical centers in Boston, New York, and San Francisco anchor patient access pathways. FDA orphan drug exclusivity provisions accelerate investment timelines for voltage-gated calcium channel-targeted therapies. Catalyst Pharmaceuticals maintains regulatory exclusivity for amifampridine through streamlined reimbursement structures.
Germany
Germany's G-BA assessment frameworks prioritize comparative effectiveness evidence for ultra-rare neurological condition reimbursement. University hospitals in Munich and Heidelberg concentrate electromyography proficiency and diagnostic workflows. The country's plasma fractionation sector supplies regional immunoglobulin demand through CSL Behring and Grifols facilities.
Japan
Japan's PMDA Sakigake pathway offers priority consultation and shortened approval timelines for innovative LEMS therapies. Designated rare disease hospitals in Tokyo and Osaka concentrate eligible patient pools for clinical trial recruitment. Subcutaneous immunoglobulin reimbursement expansion is shifting administration from hospital to home settings.
United Kingdom
NICE value assessment frameworks for ultra-rare conditions create market access friction distinct from continental European pathways. London and Oxford academic centers house specialized autoimmune neuromuscular diagnostic capacity. England's NHS England specialized commissioning processes concentrate treatment authorization in tertiary referral networks.
Switzerland
Swissmedic maintains accelerated assessment pathways for orphan-designated therapies targeting autoimmune neuromuscular indications. Basel and Zurich host clinical research organizations coordinating multicenter trials across dispersed European sites. The country's health technology assessment body evaluates premium pricing for therapies with demonstrated quality-adjusted life year gains.
Global Lambert-Eaton Myasthenic Syndrome Treatment Market Competitive Landscape
Top-tier vendors anchor the symptomatic treatment segment through regulatory exclusivity, while mid-tier plasma fractionators and emerging biologics developers occupy distinct competitive positions. The market structure reflects consolidation around potassium channel blockers and fragmentation across immunomodulatory approaches. Three archetypes dominate: orphan drug specialists with regulatory capture, plasma-derived product manufacturers with supply chain control, and FcRn antagonist developers with novel mechanisms. Competitive moves center on companion diagnostic integration and home infusion service expansion.
Among orphan drug specialists, Catalyst Pharmaceuticals, Inc. occupies a position exemplifying regulatory exclusivity strategy in the symptomatic treatment space. argenx SE and Alexion Pharmaceuticals, Inc. represent the emerging biologics tier targeting autoimmune neuromuscular indications through novel immunomodulatory mechanisms. Grifols, S.A. and CSL Behring anchor the plasma-derived segment where fractionation capacity and supply security determine competitive standing.
| Leading Market Players |
|---|
| Catalyst Pharmaceuticals, Inc. |
| Jacobus Pharmaceutical Company, Inc. |
| Grifols, S.A. |
| Alexion Pharmaceuticals, Inc. |
| Takeda Pharmaceutical Company Limited |
| argenx SE |
| CSL Behring |
| BioMarin Pharmaceutical Inc. |
| Merck & Co., Inc. |
| Others |
Supply & Pricing Matrix
Plasma protein pricing indices cascade through immunoglobulin manufacturing into three-tier pricing structure across premium, standard, and economy levels for LEMS therapeutics. Fractionation capacity constraints in the United States and Germany amplify cost volatility, while oral potassium channel blockers anchor stable pricing tiers through synthetic chemistry supply security.
Pricing Analysis
Margin tightening in plasma-derived immunoglobulins reflects fractionation capacity bottlenecks and donor plasma collection volatility. Pricing stratifies across premium, standard, and economy tiers based on FDA orphan drug exclusivity status and EMA PRIME designation certification level. Cost-down pressure on intravenous immunoglobulin intensifies as subcutaneous formulations capture payer preference for home administration. Hospital procurement committees demonstrate highest price sensitivity, while specialty pharmacy networks absorb premium pricing for amifampridine through exclusive distribution arrangements.
Supply Chain Analysis
Return flows of unused immunoglobulin vials from hospital infusion centers to plasma fractionators enable batch reallocation and waste reduction programs. Manufacturing concentrates in the United States, Germany, and Spain where CSL Behring and Grifols operate fractionation campuses. Raw material supply draws from regulated donor plasma collection networks, sodium chloride excipient sourcing, and sterile packaging components. Single-source vulnerability permeates the plasma supply base where pandemic-disrupted donation patterns created persistent inventory imbalances. Distribution runs through cold-chain logistics providers serving hospital pharmacies and specialty pharmacy home delivery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automated immunoassay platforms for voltage-gated calcium channel antibody detection are displacing manual reference laboratory workflows, compressing diagnostic timelines and expanding addressable patient identification beyond academic centers.
For Market Incumbents: Cement regulatory exclusivity for amifampridine through pediatric indication extensions and formulation patent strategies. Deepen backward integration into plasma collection networks to secure immunoglobulin supply security against emerging FcRn antagonist competition. Prioritize companion diagnostic partnerships with automated immunoassay manufacturers to lock in testing algorithm standardization. For New Entrants and Emerging Players: Capture white-space in subcutaneous immunoglobulin home nursing networks across Japan and Germany where payer reimbursement expansion outpaces service infrastructure deployment. Target outpatient care centers adopting oral potassium channel blocker protocols in community neurology practices underserved by academic referral networks. Pursue licensing arrangements with established plasma fractionators to bypass capital-intensive manufacturing barriers. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap autoimmune neuromuscular specialists with EMA PRIME designations and phase-ready FcRn antagonist pipelines in Switzerland and the Netherlands. Long-term viability hinges on regulatory exclusivity duration and companion diagnostic integration depth. Monitor FDA orphan drug exclusivity expiration timelines and EMA accelerated assessment pathway award rates as inflection indicators for portfolio rebalancing.| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Integration | Automated voltage-gated calcium channel antibody testing platforms streamline referral pathways for Catalyst Pharmaceuticals. |
| Home Infusion Service Expansion | Subcutaneous immunoglobulin nursing networks in Germany reduce hospital overhead capture and shift site of care economics. |
| Regulatory Approval Pathway | Japan's PMDA Sakigake designation accelerates market entry timelines for novel potassium channel modulators. |
| Manufacturing Scale-Up | Plasma fractionation capacity additions in Spain and the United States address immunoglobulin supply security concerns. |
| Pipeline Diversification | FcRn antagonist development at argenx SE targets overlapping autoimmune neuromuscular indications beyond LEMS monotherapy. |
Research Methodology
Independent corroboration across FDA orphan drug filing databases, EMA PRIME designation registries, and ClinicalTrials.gov protocol disclosures underwrites the qualitative findings on competitive positioning. Primary interviews with drug development executives at orphan disease specialists, regulatory affairs leads navigating EMA protocol assistance, and hospital procurement managers at German university hospitals combined with secondary validation from formulary databases and GPO contracts. Bottom-up patient volume estimates and top-down revenue triangulation anchored segmentation outputs.
Comparable-period anchoring to historical amifampridine prescription volumes and immunoglobulin infusion claims established the forecast window baseline across the analysis window. Segmentation modeling incorporated therapy area, delivery mode, and regional regulatory cluster dimensions. CAGRs derived from spline interpolation between diagnosed prevalence projections and treatment penetration assumptions. Forecast inputs included voltage-gated calcium channel antibody testing automation adoption curves and subcutaneous immunoglobulin reimbursement policy shifts.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to plasma supply disruptions and competitive entry from FcRn antagonists. Forecasts reflect documented assumptions regarding orphan drug exclusivity maintenance and HTA body value assessment criteria evolution. Practitioners should monitor FDA breakthrough therapy designation awards and Japan's Sakigake pathway utilization rates for early signals of competitive timeline compression.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Neurology
Lewy Body Dementia Treatment Market
Neurology
Spasticity Treatment Market
Neurology
Hydrocephalus Market
Neurology
Occipital Nerve Block Treatment Market
Neurology
Neurological Biomarkers Market
Neurology
Tourette Syndrome Market
Neurology
Europe Pediatric Neurology Device Market
Neurology
Central Nervous System Lymphoma Treatment Market
Neurology
Asia-Pacific Neurology Monitoring Market
Neurology
Global Diabetic Neuropathy Treatment Market
Neurology
Nerve Repair Market
Neurology
North America Neurology Devices Market
Neurology
Multiple Sclerosis Treatment Market
Neurology
Sweden Neurology Devices Market
Neurology
Multiple Sclerosis Therapies Market
Neurology
Global Sciatica Treatment Market