
 Sepsis Treatment Market | 2026-2036
Sepsis Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Sepsis Treatment Market Outlook
Intensivist staffing shortages across major hospital systems is collapsing timely sepsis intervention capacity, forcing institutions toward automated decision-support platforms. Pfizer Inc. leverages its broad-spectrum antibiotic manufacturing scale to sustain supply security for hospital formularies. GSK plc anchors its position through R&D intensity in immune modulation pathways. F. Hoffmann-La Roche Ltd differentiates via diagnostics integration with therapeutic monitoring protocols.
Sepsis treatment encompasses the clinical management of life-threatening organ dysfunction caused by dysregulated host response to infection, typically involving intravenous antibiotic administration within one hour of recognition alongside hemodynamic support. Antibiotics occupy the largest product segment due to established protocols and broad-spectrum coverage requirements, while immune modulators represent the fastest-expanding category as novel biologics target cytokine storm pathways. Intravenous delivery dominates hospital settings, though oral step-down therapies gain traction in long-term care facilities seeking reduced readmission rates.
FDA's Breakthrough Therapy and Fast Track designations compress development timelines for novel sepsis therapeutics, while the EU MDR imposes stricter clinical evidence requirements on combination device-drug products. EMA's parallel scientific advice with FDA harmonizes multinational trial designs, though post-market surveillance obligations intensify compliance costs. Stakeholders must weigh early-stage biomarker investments against the risk of protocol shifts toward host-directed rather than pathogen-directed therapy paradigms.
Market Dynamics
The sepsis treatment market is pivoting toward host-directed immunomodulation as pathogen-directed antibiotic efficacy plateaus against multidrug-resistant organisms. This therapeutic reorientation is compressing traditional antimicrobial development pipelines while accelerating biologics investment.
Growth Catalysts
- FDA Breakthrough Therapy designation:Compressed approval timelines for novel immunomodulators targeting cytokine storm pathways are pulling venture capital into late-stage sepsis trials.
- Intensive care infrastructure:Hospital systems in Germany and Japan are deploying automated sepsis surveillance algorithms that trigger earlier therapeutic intervention.
- Biomarker validation:Procalcitonin-guided antibiotic stewardship protocols are expanding reimbursable diagnostic panels across Medicare and commercial payers.
Market Restraints
- Antibiotic development economics:Narrow profit margins on generic broad-spectrum agents are deterring pharmaceutical manufacturers from novel antimicrobial R&D.
- Diagnostic reimbursement fragmentation:Inconsistent CMS coding for multiplex PCR sepsis panels creates revenue uncertainty for hospital laboratories.
- Clinical trial design complexity:Heterogeneous patient phenotypes and endpoint variability are prolonging Phase III enrollment timelines.
Strategic Opportunities
- Long-term acute care facilities:Oral step-down antibiotic protocols are reducing 30-day readmission penalties in post-acute settings.
- EU MDR harmonization:Streamlined conformity assessment for combination device-drug products is lowering regulatory entry costs for diagnostic-therapeutic platforms.
- Machine learning integration:Real-time electronic health record analytics are enabling preemptive sepsis alerts before clinical recognition.
Industry Challenges
- Intensivist workforce scarcity:Critical care physician shortages in the United States are forcing hospitals toward nurse practitioner-led sepsis protocols.
- Legacy EHR interoperability:Fragmented data architectures are impeding seamless biomarker-to-treatment workflow integration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sepsis Treatment Market |
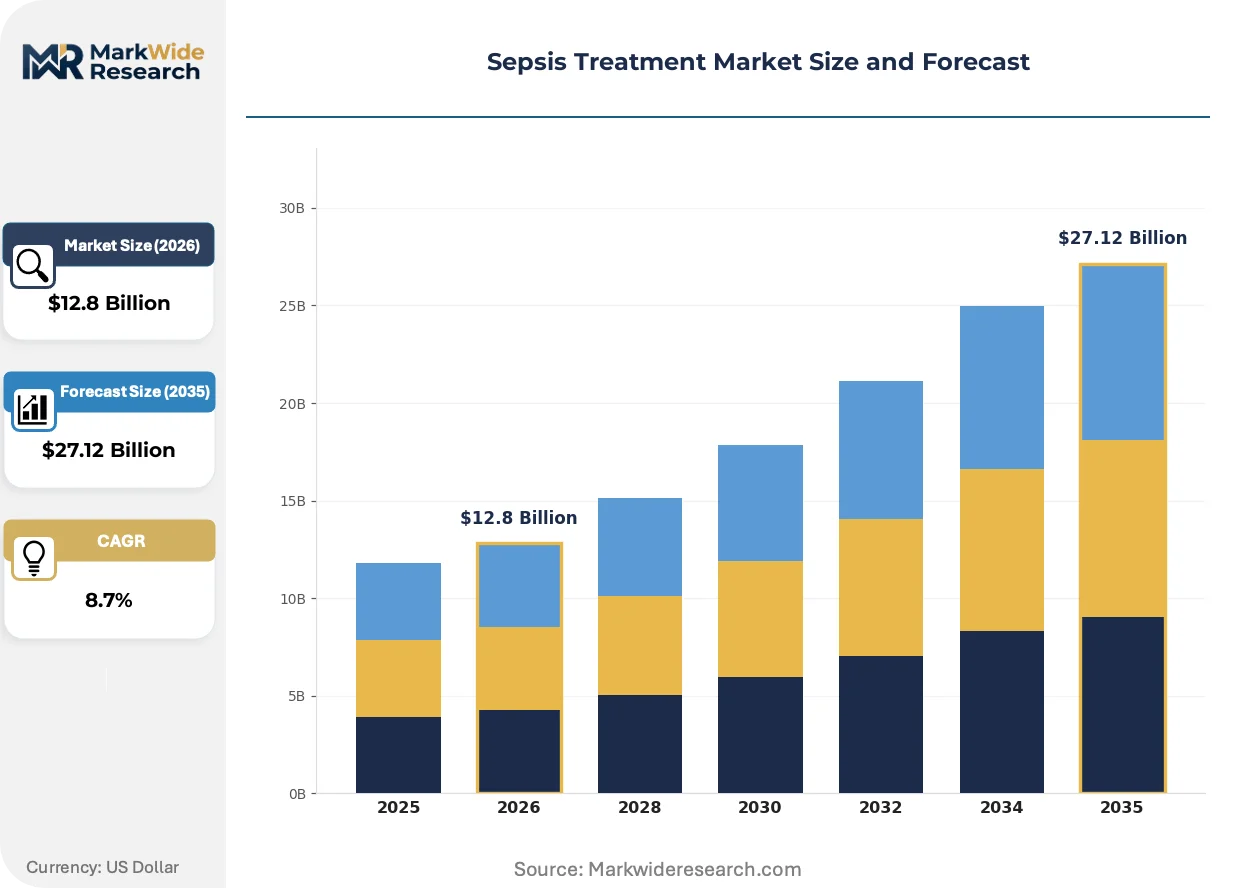
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $27.12 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antibiotics, Antifungals, Supportive Care, Immune Modulators Delivery Mode: Intravenous, Oral, Inhalation, Topical End User: Hospitals, Clinics, Homecare Settings, Long-term Care Facilities Therapy Area: Cardiovascular, Respiratory, Infectious Diseases, Gastrointestinal |
| Companies Covered | Pfizer Inc., GSK plc, AstraZeneca plc, Eli Lilly and Company, F. Hoffmann-La Roche Ltd, AbbVie Inc., Merck & Co., Inc., Asahi Kasei Corporation, Adrenomed AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sepsis Treatment Market Strategic Shifts
Artificial intelligence is penetrating sepsis care pathways at the point of clinical suspicion, compressing the diagnostic-to-treatment interval from hours to minutes. This computational layer is restructuring competitive advantage around data integration rather than molecule exclusivity.
Next-generation sequencing platforms for rapid blood pathogen identification are displacing conventional culture-based diagnostics in tertiary care centers. Hospital microbiology laboratories in the United States are adopting these systems to shorten empiric antibiotic exposure. The technology is displacing revenue from traditional susceptibility testing while creating new service lines for antimicrobial stewardship programs.
EMA's parallel scientific advice mechanism with FDA is harmonizing multinational sepsis trial designs for immunomodulator candidates. This regulatory convergence reduces redundant clinical evidence generation for sponsors pursuing simultaneous US and EU approvals. Combination product manufacturers are responding by consolidating regulatory strategy functions under single cross-functional teams.
Hospital procurement committees are bundling diagnostic and therapeutic contracts under single vendor relationships to simplify formulary management. This consolidation is marginalizing standalone antibiotic suppliers in favor of integrated platform providers. The shift is most pronounced in German hospital networks seeking unified accountable care contracts with regional insurers.
Sepsis Treatment Market Segmentation
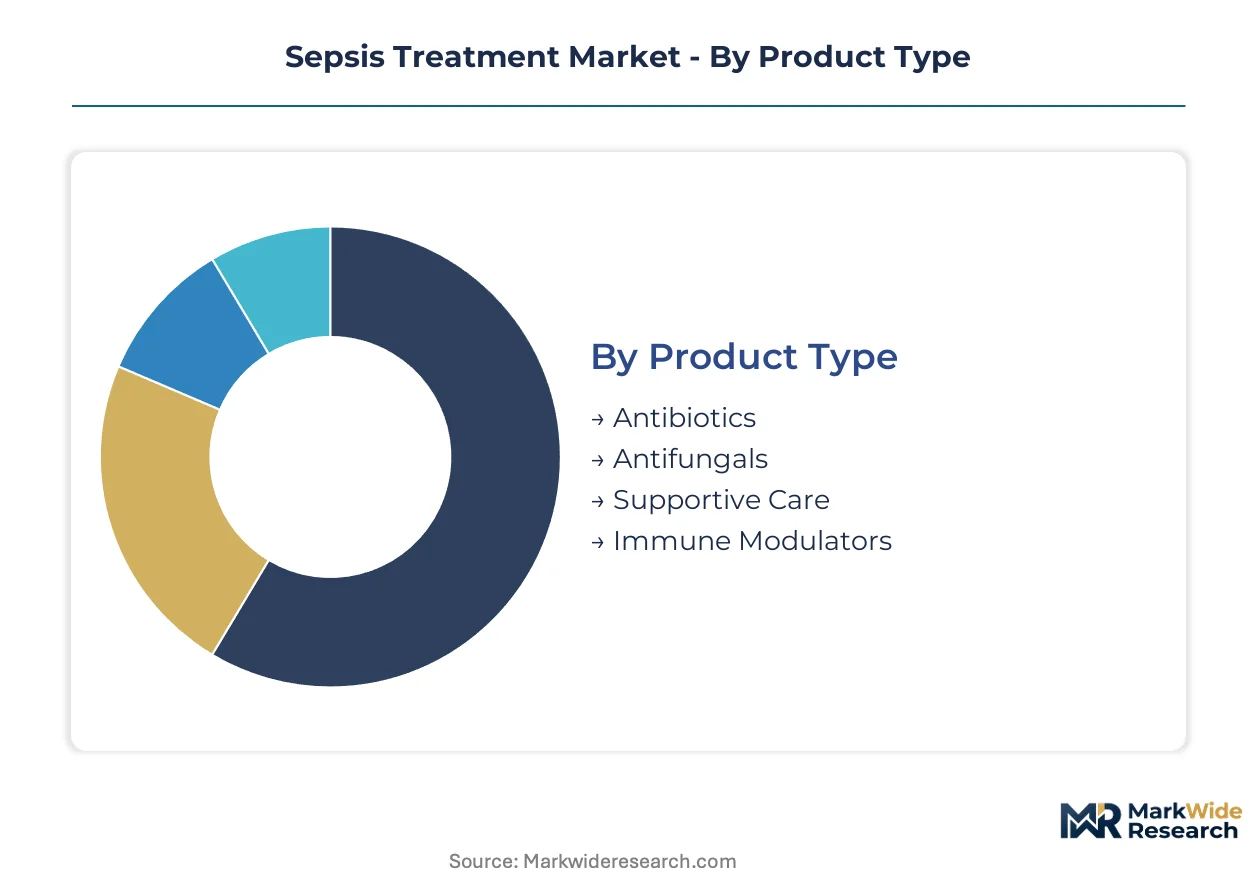
Sepsis treatment segmentation reflects divergent reimbursement pathways and clinical protocols across acute and post-acute settings. Product type and delivery mode classifications determine FDA breakthrough eligibility and CMS billing codes, while end-user categories map directly to intensivist availability and infrastructure investment levels.
Product Type:
FDA's Breakthrough Therapy designation and EMA's adaptive pathway create divergent commercialization timelines across therapeutic categories, with immune modulators accessing accelerated review unavailable to generic antibiotics.
- Antibiotics:Broad-spectrum agents including carbapenems, cephalosporins, and combination beta-lactam/beta-lactamase inhibitors constitute the clinical backbone of sepsis protocols. Demand concentrates in United States tertiary centers where Medicare's sepsis core measures mandate one-hour administration windows, though narrow margins on generic formulations deter manufacturer investment in novel antimicrobial development.
- Immune Modulators:Biologics targeting cytokine storm pathways—IL-6 inhibitors, TNF-alpha antagonists, and complement system modulators—represent the therapeutic frontier. German hospital networks are deploying these agents in academic medical centers with established immunology protocols, driven by EMA's parallel scientific advice harmonizing trial designs with FDA.
- Antifungals:Echinocandins and azoles address candidemia and invasive mold infections in immunocompromised sepsis patients.
- Supportive Care:Vasopressors, corticosteroids, and fluid resuscitation products stabilize hemodynamics during source control.
Antibiotics handle the majority of throughput; immune modulators are expanding most quickly on share.
Delivery Mode:
Route selection tracks patient acuity transitions, with reimbursement incentives in post-acute settings favoring cost-reducing shifts from parenteral to enteral administration.
- Intravenous:Direct bloodstream delivery ensures rapid therapeutic levels in hemodynamically unstable patients, dominating hospital-based sepsis care. Japanese intensive care units maintain near-universal IV dependence due to PMDA's stringent bioequivalence requirements for alternative routes in critical illness.
- Oral:Step-down protocols enable discharge to long-term acute care facilities, reducing 30-day readmission penalties under Medicare's Hospital Readmissions Reduction Program. United States skilled nursing facilities are expanding oral antibiotic formularies to capture bundled payment savings.
- Inhalation:Nebulized antimicrobial delivery targets ventilator-associated pneumonia as a sepsis source.
- Topical:Localized infection control in surgical site sepsis and catheter-related infections.
Intravenous dominates acute-phase revenue; oral delivery is gaining share fastest in post-acute transitions.
End User:
Workforce availability and capital equipment requirements stratify adoption capacity across care settings, with intensivist density determining protocol sophistication.
- Hospitals:Tertiary and community hospitals deploy comprehensive sepsis bundles including rapid diagnostics, broad-spectrum antibiotics, and hemodynamic monitoring. United States health systems face intensivist shortages that automate decision-support platforms into standard workflow.
- Long-term Care Facilities:Post-acute settings manage oral step-down therapy and infection surveillance, with German networks integrating these facilities into regional accountable care contracts.
- Clinics:Outpatient parenteral antimicrobial therapy programs stabilize patients avoiding admission.
- Homecare Settings:Infusion nursing services support prolonged IV courses in stable patients.
Hospitals command the majority of therapeutic expenditure; long-term care facilities are climbing the fastest as readmission penalties intensify.
Therapy Area:
Organ system targeting aligns with comorbidity prevalence and diagnostic biomarker availability, influencing protocol standardization.
- Infectious Diseases:Source-directed therapy against bacterial, viral, and fungal pathogens remains the foundational paradigm, with next-generation sequencing displacing culture-based diagnostics in United States academic centers.
- Cardiovascular:Septic shock management through vasopressor optimization and perfusion monitoring addresses the most lethal sepsis phenotype. Japanese emergency medical systems prioritize cardiovascular resuscitation protocols given aging demographics.
- Respiratory:Ventilator-associated pneumonia and acute respiratory distress syndrome drive mechanical ventilation adjuncts.
- Gastrointestinal:Intra-abdominal source control and gut barrier protection strategies.
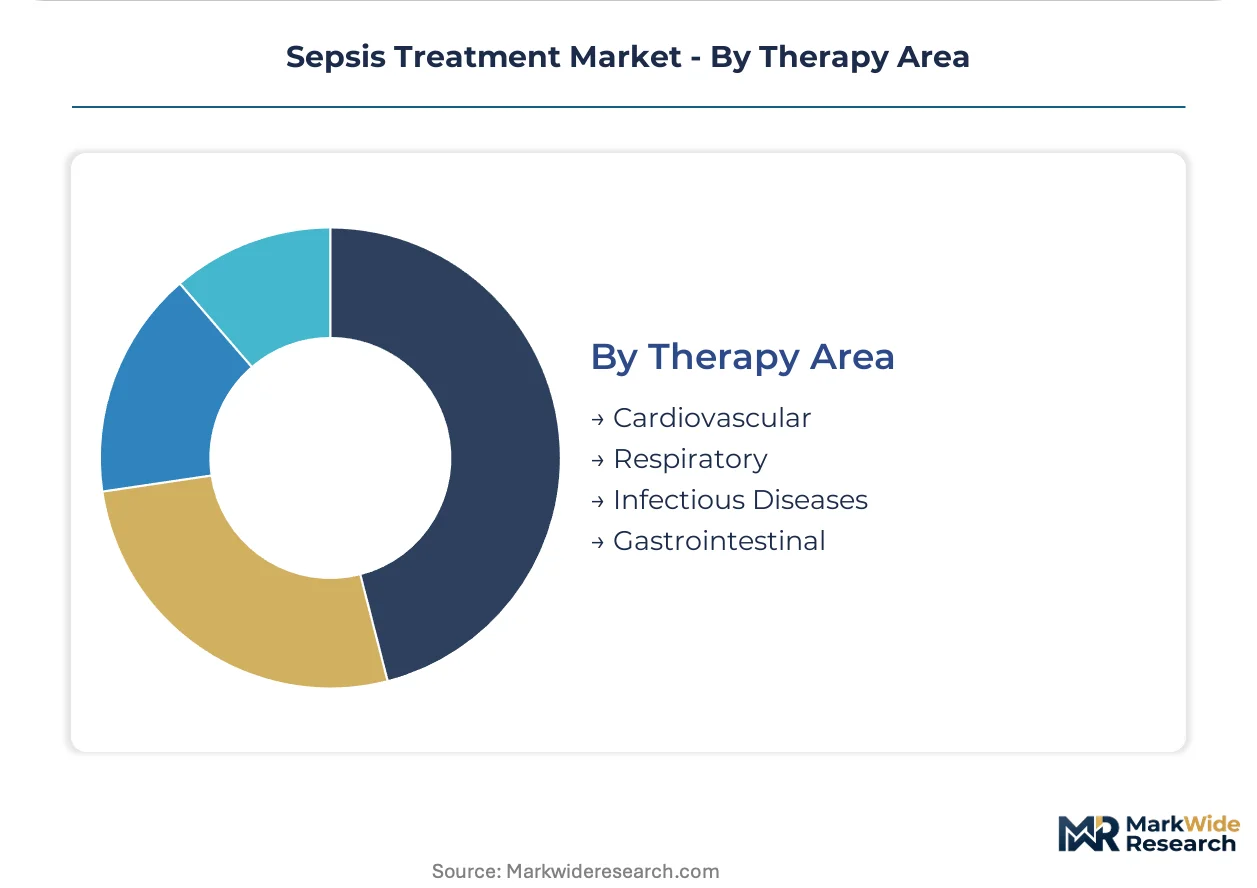
Infectious diseases anchors protocol development; cardiovascular intervention shows the steepest expansion trajectory as shock mortality drives innovation investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in sepsis therapeutics concentrates in German hospital networks, while Japanese procurement maintains premium cost structures through PMDA's stringent bioequivalence requirements. This asymmetry shapes divergent investment patterns across developed markets.
United States
Intensivist workforce scarcity automates sepsis surveillance into hospital workflows, with Medicare's sepsis core measures mandating one-hour antibiotic administration windows. FDA's Breakthrough Therapy designation accelerates novel immunomodulator trials. Boston's academic medical centers deploy machine learning platforms for preemptive sepsis alerts.
Germany
Regional accountable care contracts bundle diagnostic and therapeutic procurement under single vendor relationships, consolidating formulary management. EU MDR harmonization streamlines conformity assessment for combination device-drug products. North Rhine-Westphalia hospital networks integrate long-term care facilities into unified sepsis protocols.
Japan
Aging demographics prioritize cardiovascular resuscitation protocols in emergency medical systems, sustaining near-universal intravenous delivery dependence. PMDA's stringent bioequivalence requirements for alternative routes protect established supply chains. Tokyo's intensive care units maintain conservative adoption curves for oral step-down therapies.
United Kingdom
NHS sepsis improvement programs standardize rapid diagnostic deployment across acute trusts, though post-Brexit regulatory divergence from EMA creates parallel submission burdens. NICE technology appraisals determine reimbursable biomarker panels. London's tertiary centers pilot next-generation sequencing for blood pathogen identification.
India
CDSCO's accelerated approval pathways for critical care antibiotics address rising multidrug-resistant organism prevalence in tertiary hospitals. Private hospital chains in Maharashtra and Karnataka invest in automated decision-support platforms to compensate for critical care physician shortages. Mumbai's corporate hospitals attract immunomodulator trials through adaptive trial designs.
Sepsis Treatment Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. Large-cap pharmaceutical manufacturers with broad-spectrum antibiotic portfolios anchor the cost-competitive segment, while biologics specialists occupy the innovation frontier. Three archetypes dominate: integrated platform providers bundling diagnostics with therapeutics, pure-play immunomodulator developers, and diversified critical care suppliers. M&A activity concentrates on diagnostic-therapeutic convergence, with capacity expansion targeting automated manufacturing for biologics.
Among diversified pharmaceutical manufacturers, Pfizer Inc., GSK plc, and F. Hoffmann-La Roche Ltd exemplify contrasting strategic positions. Pfizer represents the scale-driven antibiotic supplier archetype, GSK occupies the immunomodulation R&D intensity tier, and Roche anchors the diagnostics-therapeutic integration model. These three structures illustrate how regulatory pathway selection—FDA Breakthrough Therapy versus EU MDR conformity assessment—shapes competitive positioning without requiring identical resource commitments.
| Leading Market Players |
|---|
| Pfizer Inc. |
| GSK plc |
| AstraZeneca plc |
| Eli Lilly and Company |
| F. Hoffmann-La Roche Ltd |
| AbbVie Inc. |
| Merck & Co., Inc. |
| Asahi Kasei Corporation |
| Adrenomed AG |
| Others |
Value Chain & Pricing Dynamics
Manufacturing scale in broad-spectrum antibiotics anchors cost floors across hospital formularies, with Pfizer's production volume creating price benchmarks that compress margins for secondary suppliers. This concentration of active pharmaceutical ingredient capacity in India and China simultaneously shapes procurement bargaining power and inventory risk exposure for finished dose manufacturers.
Pricing Analysis
Configured-to-order pricing for rapid diagnostic-therapeutic platforms commands substantial premiums over standard antibiotic vial pricing. Three-tier pricing structure across premium, standard, and economy levels stratifies by FDA Breakthrough Therapy designation status and biomarker integration depth. Price differentiation hinges on certification tier and after-sales service bundling. Cost compression in generic broad-spectrum agents is intensifying because of Indian CDSCO accelerated approval pathways flooding comparable molecules. Long-term acute care facilities exhibit highest price sensitivity; academic medical centers with dedicated immunology protocols show lowest.
Supply Chain Analysis
Just-in-time inventory strategies dominate hospital antibiotic procurement, though strategic stockpiling of immune modulators persists in German academic centers facing EMA supply continuity requirements. Active pharmaceutical ingredient production concentrates in India, China, and the United States. Finished dose formulation draws from specialized sterile manufacturing facilities in Germany, Japan, and Ireland. Single-source vulnerability for cytokine inhibitor cell lines creates structural risk. Distribution runs through regional hospital procurement consortia and GPO contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
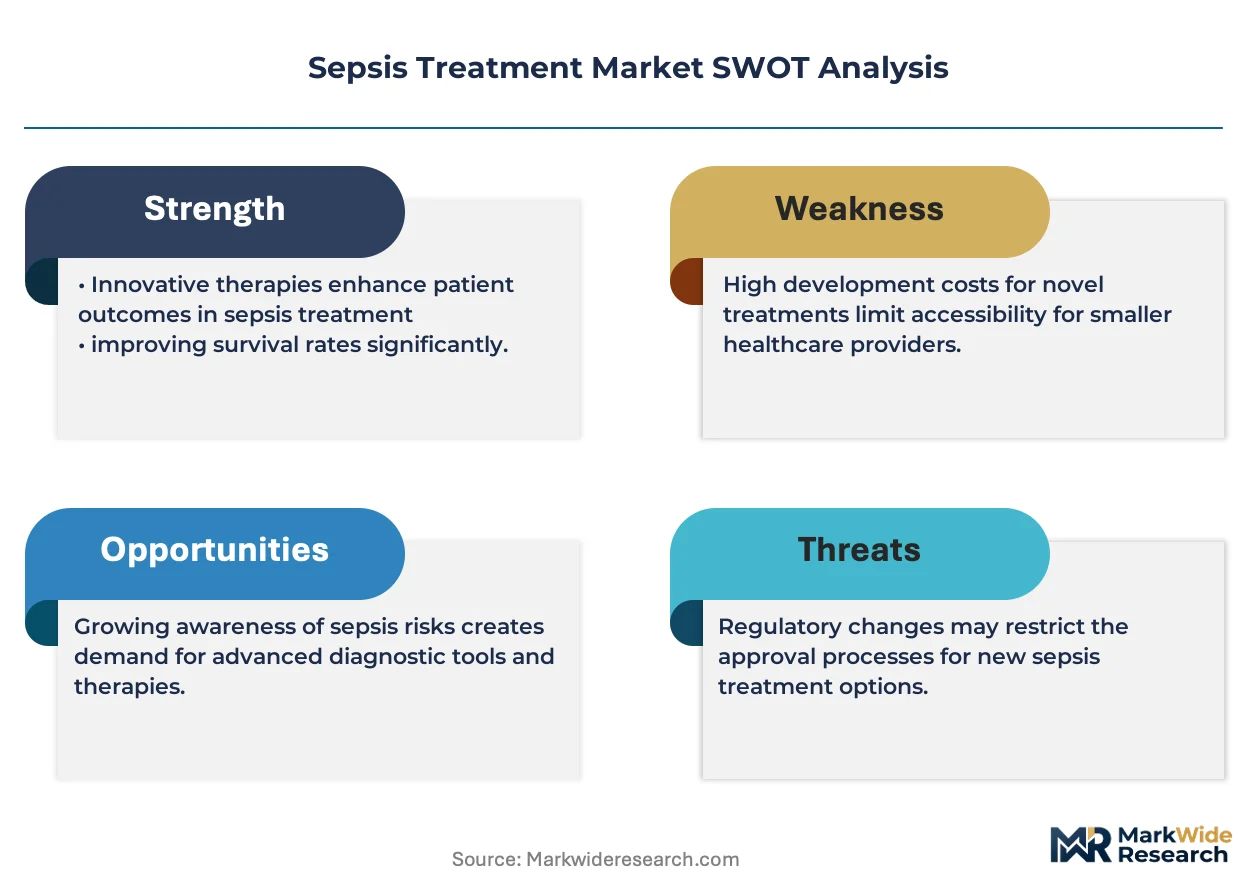
Host-directed immunomodulation threatens pathogen-directed antibiotic incumbents with therapeutic substitution as multidrug-resistant organism prevalence accelerates protocol shifts.
For Market Incumbents: Consolidate diagnostic-therapeutic platform capabilities through backward integration into rapid blood pathogen identification technologies. Lock in hospital system formulary control via bundled procurement contracts spanning antibiotics, immune modulators, and surveillance algorithms. Pfizer's manufacturing scale and Roche's diagnostics integration illustrate divergent consolidation paths against emerging biologics specialists. For New Entrants and Emerging Players: Differentiate on machine learning-enabled preemptive sepsis alerts that compress diagnostic-to-treatment intervals. White-space concentrates in long-term acute care oral step-down protocols and Japanese PMDA bioequivalence-compliant alternative delivery formats. Target skilled nursing facility procurement committees with readmission penalty reduction value propositions. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated platform providers over standalone antibiotic manufacturers across the analysis window. Acquisition archetypes center on diagnostic-therapeutic convergence plays with FDA Breakthrough Therapy designation momentum. Monitor EMA-FDA parallel scientific advice harmonization velocity as inflection signal for immunomodulator portfolio viability.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | FDA Breakthrough Therapy designation compresses timelines for cytokine storm-targeting biologics. |
| Hospital System Partnership | Bundled accountable care contracts in German networks consolidate formulary access. |
| Manufacturing Scale-Up | Automated biologics production addresses intensivist shortage-driven demand surges. |
| Software Companion Development | Electronic health record analytics integration enables preemptive sepsis intervention alerts. |
| Reimbursement Strategy | Procalcitonin-guided stewardship protocol validation expands Medicare diagnostic panel coverage. |
Study Parameters
Desk research of FDA Breakthrough Therapy designations, EMA parallel scientific advice records, and CMS sepsis core measure documentation preceded structured interviews with hospital procurement managers, intensive care unit directors, formulary committee chairs, and regulatory affairs leads at immunomodulator developers. Secondary validation drew from ClinicalTrials.gov enrollment data, GPO contract databases, and hospital accreditation records. Bottom-up therapeutic volume estimates triangulated against top-down healthcare expenditure flows.
Variance decomposition across product type, delivery mode, end-user setting, and regional regulatory cluster shaped the analytical framework over the projection horizon. CAGRs derived from segmented growth rate blending with intensity-of-use adjustments. Forecast inputs incorporated intensivist workforce density projections and biomarker reimbursement trajectory modeling.
Material uncertainties — regulatory pathway shifts toward host-directed therapy, diagnostic reimbursement coding fragmentation, and antimicrobial stewardship protocol standardization — sit outside the modeled envelope. Forecasts reflect assumptions about EMA-FDA harmonization persistence and Medicare sepsis core measure stability. Revision becomes warranted when immune modulator clinical trial failure rates cross thresholds that alter venture capital allocation patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Hypogonadism Treatment Market
Medical Treatment
Surgical Procedures Volume Market
Medical Treatment
Thyroid Deficiency Treatment Market
Medical Treatment
Lysosomal Acid Lipase (LAL) Deficiency Treatment Market
Medical Treatment
Hypothermia Management Market
Medical Treatment
Rotator Cuff Injury Treatment Market
Medical Treatment
Peri-Implantitis Treatment Market
Medical Treatment
Hepatocellular Carcinoma (HCC) Treatment Market
Medical Treatment
Hyperammonemia Treatment Market
Medical Treatment
Europe Lysosomal Disease Treatment Market
Medical Treatment
Global Premenstrual Syndrome Treatment Market
Medical Treatment
Infertility Treatment Market
Medical Treatment
Beta Thalassemia Treatment Market
Medical Treatment
US and Japan Platelet Rich Plasma Market
Medical Treatment
Europe Chronic Disease Management Market
Medical Treatment
Myasthenia Gravis Treatment Market