
 Tendonitis Treatment Market | 2026-2036
Tendonitis Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Tendonitis Treatment Market Intelligence
The specialization of orthopedic surgeons in minimally invasive procedures is rotating clinical practice toward faster recovery options. Pfizer leverages its extensive portfolio of anti-inflammatory drugs to serve a broad patient base. Bayer AG competes through its strong presence in over-the-counter topical analgesics. Meanwhile, Stryker specializes in advanced orthopedic devices and surgical solutions for severe tendon injuries.
Tendonitis treatment encompasses medical interventions designed to manage inflammation and repair damaged collagen fibers within tendons. Its primary goal is to restore mobility and alleviate pain associated with overuse or injury. Within the product landscape, Nonsteroidal Anti-Inflammatory Drugs constitute a mature, high-volume category. In contrast, emerging options like Platelet-Rich Plasma Therapy represent a faster-growing segment associated with premium pricing and specialized orthopedic clinics.
Regulatory frameworks established by bodies like the US FDA and the European EMA govern market access. These agencies mandate rigorous clinical trials for new drugs and medical devices, ensuring safety and efficacy standards. The key decision for providers and manufacturers will be navigating the evolving reimbursement policies for regenerative and biologic-based treatments.
Market Dynamics
The central structural force shaping the tendonitis treatment market is the clinical rotation from palliative pain management toward regenerative medicine. This shift prioritizes therapies like Platelet-Rich Plasma that aim for tissue repair over symptomatic relief with traditional pharmaceuticals.
Growth Catalysts
- Advanced Therapeutic Adoption:The integration of Platelet-Rich Plasma therapy and other biologics into mainstream sports medicine and orthopedic practices provides a significant catalyst for market value expansion.
- Aging Demographics in Developed Nations:Countries with advanced healthcare systems, such as Japan, face a growing prevalence of degenerative tendon conditions among their aging populations, increasing the patient base for both conservative and advanced treatments.
- Public Health Investment in Athletics:Government-backed initiatives in the UK and Australia to promote physical activity and amateur sports are expanding the network of sports medicine facilities, which are primary consumers of tendonitis treatment products.
Market Restraints
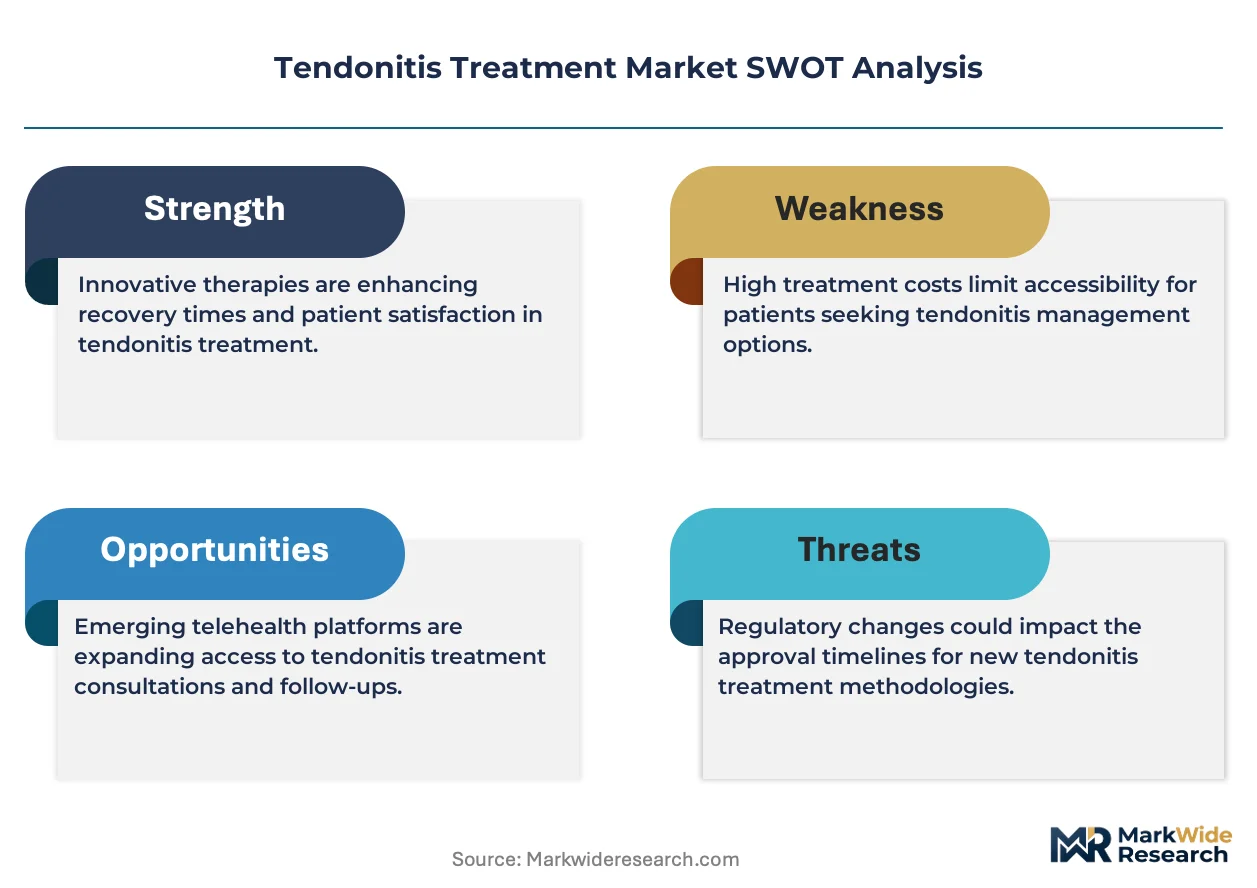
- Reimbursement Ambiguity:Inconsistent or absent reimbursement codes from private and public payers for emerging regenerative therapies creates a significant financial barrier for patient access and provider adoption.
- Stringent Regulatory Pathways:The rigorous clinical evidence requirements mandated by regulatory bodies like the US FDA and the European EMA for new biologic agents create long and costly development cycles, slowing innovation.
- Dominance of OTC Analgesics:The widespread availability, low cost, and established use of over-the-counter Nonsteroidal Anti-Inflammatory Drugs (NSAIDs) for self-managed pain relief can delay or prevent patients from seeking more definitive medical intervention.
Strategic Opportunities
- Emerging Market Penetration:Healthcare infrastructure development in Southeast Asian nations presents an opportunity to introduce advanced tendonitis treatments to a growing middle class with increasing access to private healthcare.
- Technology Convergence for Precision:Combining biologic therapies with real-time ultrasound guidance systems offers a pathway to improve treatment accuracy, enhance patient outcomes, and justify premium pricing.
- Development of Topical Biologics:Research into novel topical drug delivery systems for anti-inflammatory and regenerative agents could open a new, non-invasive treatment category that bridges the gap between oral NSAIDs and injections.
Industry Challenges
- Clinical Training Gaps:A deficit exists in specialized training for clinicians on the proper preparation and administration protocols for regenerative treatments, leading to variability in efficacy and patient outcomes. *Lack of Protocol Standardization: The absence of universally accepted standards for the formulation and application of therapies like Platelet-Rich Plasma complicates the comparison of clinical trial data and hinders wider acceptance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tendonitis Treatment Market |
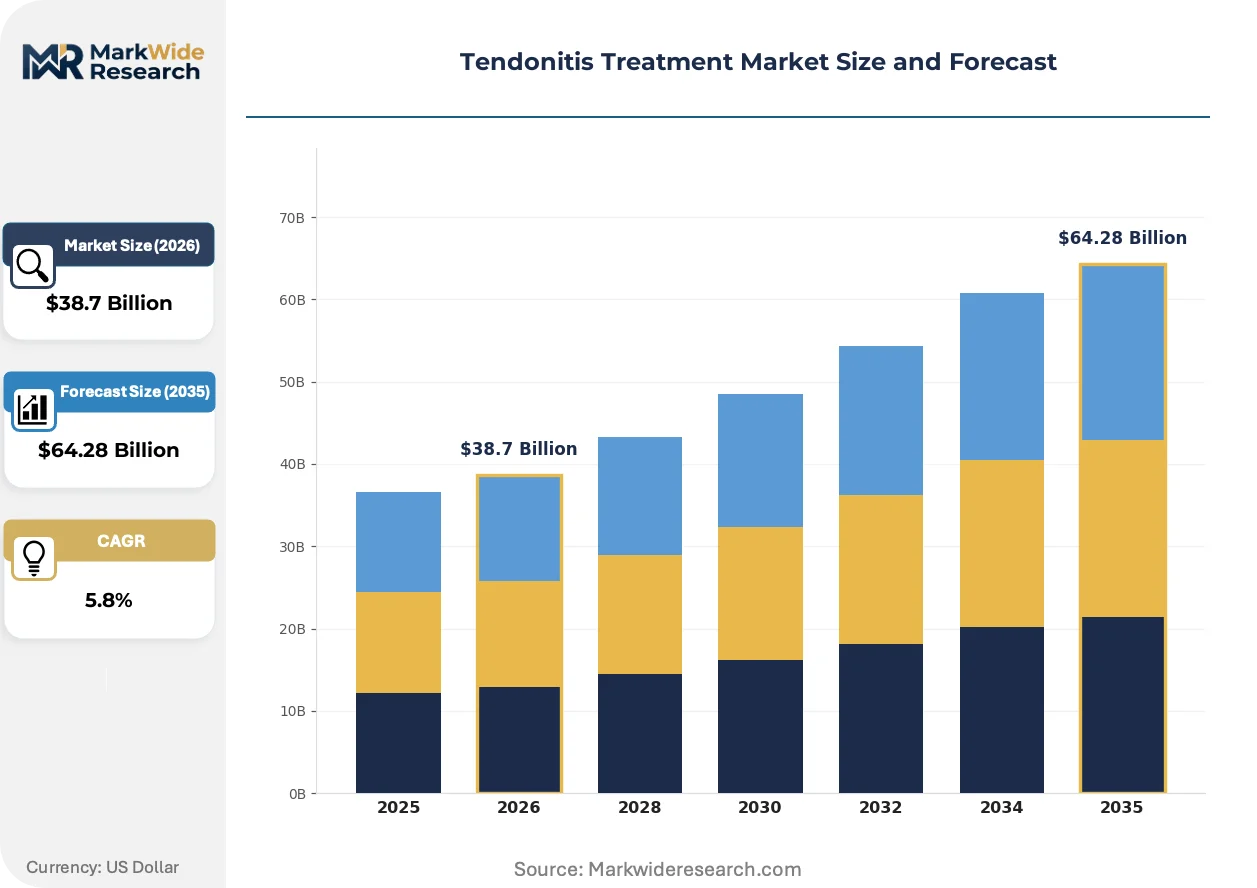
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $64.28 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nonsteroidal Anti-Inflammatory Drugs, Corticosteroid Injections, Physical Therapy Devices, Platelet-Rich Plasma Therapy, Topical Analgesics, Orthopedic Supports Therapy Area: Achilles Tendonitis, Tennis Elbow, Rotator Cuff Tendonitis, Patellar Tendonitis, De Quervain’s Tenosynovitis, Flexor Tendonitis End User: Orthopedic Clinics, Physical Rehabilitation Centers, Sports Medicine Facilities, Ambulatory Surgical Centers, Chiropractic Practices, Physiotherapy Centers Delivery Mode: Injections, Oral Medication, Topical Application, Physiotherapy Sessions, Extracorporeal Shockwave Therapy, Ultrasound Therapy |
| Companies Covered | Abbott, Pfizer, Bayer AG, AstraZeneca, Boehringer Ingelheim Pharmaceuticals, Inc., GlaxoSmithKline PLC, Merck and Co., Inc., Stryker, Zimmer Biomet Holdings, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tendonitis Treatment Market Strategic Shifts & Innovations
Personalized medicine principles are beginning to influence treatment selection, with patient-specific factors like activity level and injury severity guiding the choice between pharmaceuticals, biologics, and surgical intervention. This tailoring of care is moving the market beyond one-size-fits-all protocols.
Biologic scaffolds represent a key innovation, offering a bio-absorbable framework to guide tissue regeneration in severe tendon injuries. Specialized orthopedic centers are the primary adopters for complex reconstruction cases. This technology is decomposing the traditional reliance on synthetic grafts or palliative care by enabling the body to rebuild its own functional tissue.
Regulatory harmonization efforts, such as those promoted by the International Council for Harmonisation of Technical Requirements for Pharmaceuticals for Human Use (ICH), aim to streamline drug approval processes across regions. These guidelines influence how multinational clinical trials are designed and executed. Pharmaceutical developers targeting markets in the US, EU, and Japan benefit most by being able to use a common data package for submissions.
Patient expectations are shifting toward treatments that minimize recovery time and facilitate a rapid return to daily activities. This preference disrupts the traditional, lengthy physiotherapy-first model, as patients actively seek clinics offering minimally invasive procedures with faster outcomes. The trend is most visible within sports medicine and occupational health in North America, where downtime carries significant personal and economic consequences.
Tendonitis Treatment Market Segmentation
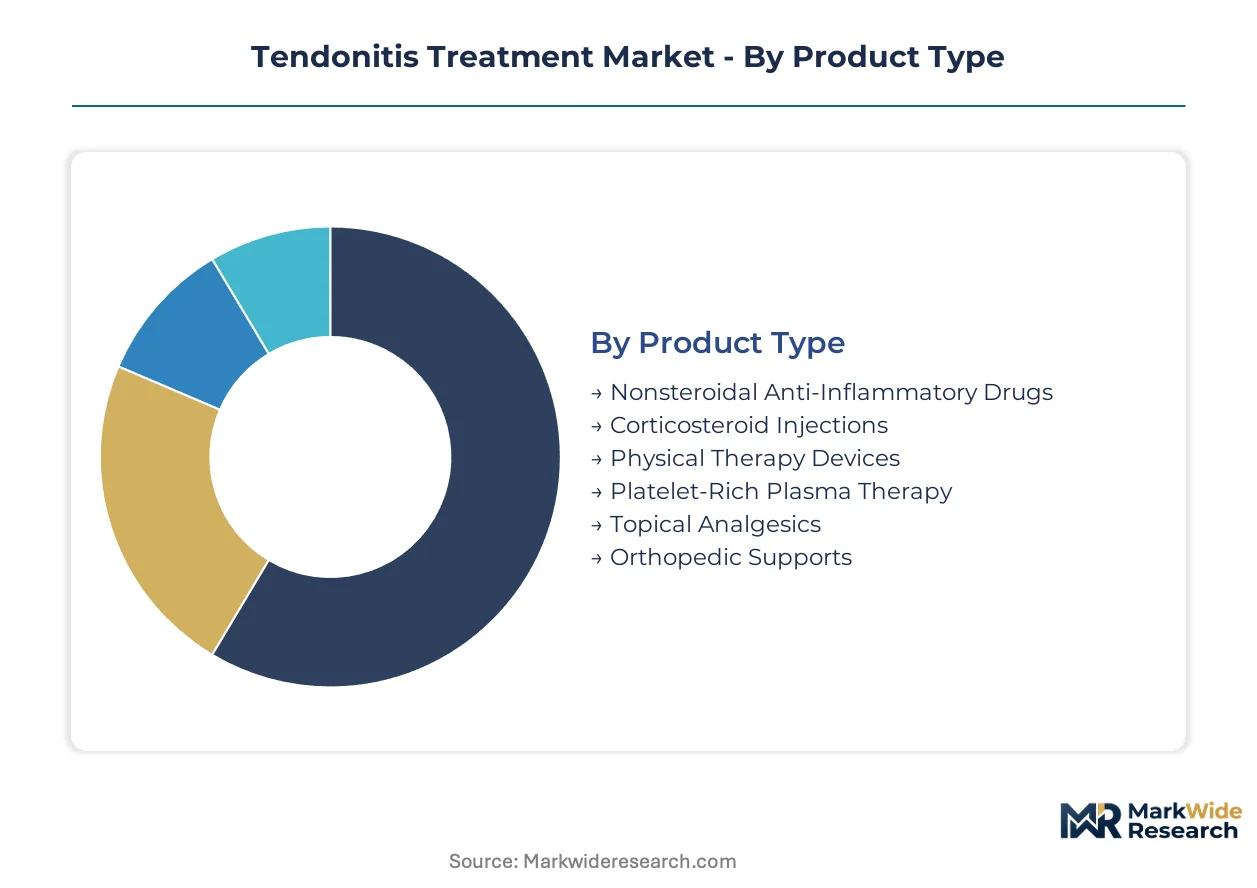
Understanding the Tendonitis Treatment Market through segmentation reveals how diverse patient needs and clinical practices influence product adoption and service provision. This granular analysis distinguishes between established therapeutic approaches and emerging regenerative solutions, highlighting areas of concentrated demand and specialized care. Segment performance also reflects regional healthcare infrastructure and regulatory environments.
Product Type:
Regulatory bodies like the US FDA and European EMA classify product types differently, influencing market access and clinical adoption. These classifications dictate the rigor of clinical trials and post-market surveillance for various treatments.
- Nonsteroidal Anti-Inflammatory Drugs:These pharmaceutical agents reduce pain and inflammation by inhibiting cyclooxygenase enzymes, forming the first-line treatment for acute tendonitis. High volume demand concentrates in primary care settings and pharmacies across North America and Europe.
- Platelet-Rich Plasma Therapy:This biologic treatment uses concentrated platelets derived from the patient's own blood to stimulate tissue repair, primarily adopted in specialized orthopedic clinics. Demand for this premium therapy is accelerating in sports medicine facilities in Germany and Australia.
- Corticosteroid Injections:Potent anti-inflammatory medications delivered directly into the affected tendon sheath offer localized pain relief.
- Physical Therapy Devices: Equipment such as ultrasound machines, electrotherapy units, and exercise tools support rehabilitation and strengthen affected tendons.
- Topical Analgesics:Creams, gels, and patches provide localized pain relief through transdermal absorption of active pharmaceutical ingredients.
- Orthopedic Supports:Braces, splints, and wraps offer immobilization and support to injured tendons, aiding in recovery and preventing further strain.
Nonsteroidal Anti-Inflammatory Drugs handle the majority of throughput; Platelet-Rich Plasma Therapy is the fastest mover on share.
Therapy Area:
The clinical burden and patient volume associated with specific therapy areas significantly influence product development and service allocation. Each area presents unique anatomical challenges and recovery protocols.
- Rotator Cuff Tendonitis:This condition affects the shoulder tendons, often requiring complex rehabilitation and sometimes surgical intervention, particularly prevalent among athletes and manual laborers. Treatment volumes are high in countries with aging populations like Japan.
- Achilles Tendonitis:Inflammation of the Achilles tendon is common in runners and athletes, demanding effective pain management and structured physical therapy to restore mobility. Sports medicine facilities in the UK see significant patient numbers for this injury.
- Tennis Elbow:Lateral epicondylitis involves inflammation of tendons on the outside of the elbow, frequently linked to repetitive arm and wrist movements.
- Patellar Tendonitis:Also known as "jumper's knee," this condition affects the tendon connecting the kneecap to the shinbone, common in sports involving jumping.
- De Quervain’s Tenosynovitis:This involves inflammation of tendons on the thumb side of the wrist, often associated with repetitive hand and wrist movements.
- Flexor Tendonitis:Affects the tendons that bend the fingers or toes, often seen in occupations requiring repetitive gripping or fine motor skills.
Rotator Cuff Tendonitis exhibits the steepest expansion trajectory, while Patellar Tendonitis maintains a stable treatment base.
End User:
Different end-user types cater to distinct patient cohorts, each requiring tailored treatment modalities and equipment. The specialization of these facilities drives procurement patterns for specific tendonitis treatments.
- Orthopedic Clinics:These specialized medical facilities provide comprehensive diagnosis, treatment, and rehabilitation for musculoskeletal conditions, including advanced surgical options. Orthopedic clinics in the US are primary purchasers of surgical devices and biologics.
- Sports Medicine Facilities:Dedicated to treating athletic injuries, these centers offer a range of services from prevention to rehabilitation, often incorporating advanced regenerative therapies. Demand for rapid recovery solutions is high among sports medicine facilities in Australia.
- Physical Rehabilitation Centers:These centers focus on restoring function and mobility through structured exercise programs and therapeutic interventions.
- Ambulatory Surgical Centers:Facilities performing outpatient surgical procedures, including minimally invasive interventions for severe tendon injuries.
- Chiropractic Practices:Offer non-pharmacological approaches focusing on spinal manipulation and musculoskeletal adjustments to alleviate pain.
- Physiotherapy Centers:Provide exercise-based therapies, manual techniques, and patient education to improve strength, flexibility, and function.
Demand for Orthopedic Clinics services drives significant equipment procurement, with Sports Medicine Facilities expanding their patient outreach.
Delivery Mode:
The maturity of various delivery modes dictates their market penetration and the level of clinical evidence required for widespread acceptance. Each mode offers distinct advantages in terms of patient comfort, efficacy, and invasiveness.
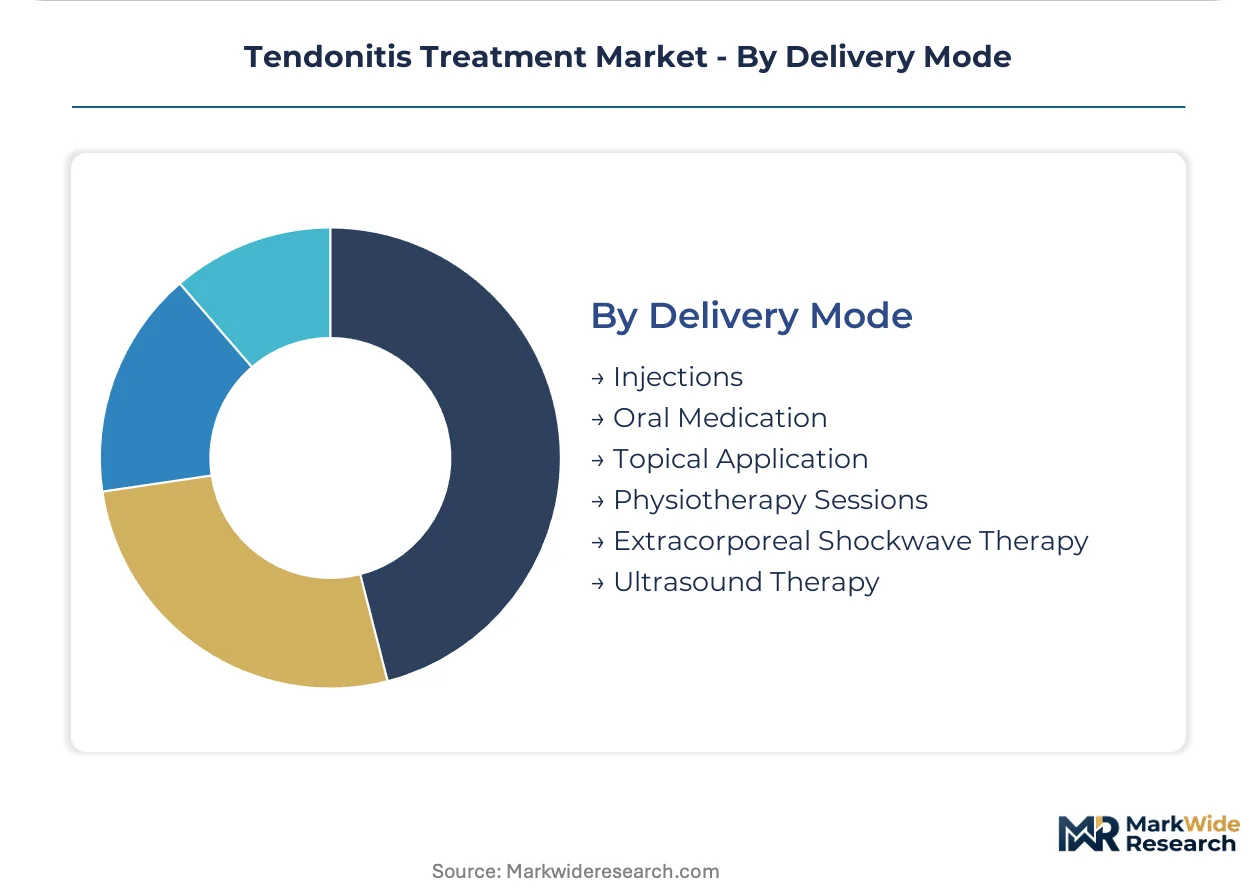
- Injections:This mode involves direct administration of medication, such as corticosteroids or Platelet-Rich Plasma, into the affected area for targeted relief. Injections are a common delivery method in orthopedic clinics for immediate symptom management.
- Physiotherapy Sessions:Structured therapeutic exercises and manual techniques delivered by trained professionals aim to restore strength, flexibility, and function over time. These sessions form a foundational recovery pathway in rehabilitation centers globally.
- Oral Medication:Systemic delivery of drugs like NSAIDs through pills or capsules provides widespread anti-inflammatory and pain-relieving effects.
- Topical Application:Creams, gels, and patches deliver active ingredients through the skin for localized treatment with minimal systemic side effects.
- Extracorporeal Shockwave Therapy:Non-invasive treatment using acoustic waves to stimulate healing and reduce pain in chronic tendon conditions.
- Ultrasound Therapy:Therapeutic ultrasound uses high-frequency sound waves to promote tissue healing and reduce inflammation in affected tendons.
Traditional Physiotherapy Sessions methods remain foundational, as Extracorporeal Shockwave Therapy gains traction for its precision.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power for advanced tendonitis treatments varies significantly between regions, with North American markets often supporting premium biologics while European nations like Germany emphasize cost-effectiveness and broader access. This asymmetry influences investment in research and development across different geographies. Healthcare infrastructure development in emerging economies also impacts the adoption rates for novel therapies.
Germany
Demand for Platelet-Rich Plasma therapy is accelerating in sports medicine facilities across Germany, driven by its advanced orthopedic and athletic care infrastructure. The European Medicines Agency (EMA) governs market access for new drugs and devices within the country. Major orthopedic and sports medicine clusters in cities like Munich and Berlin are primary centers for advanced treatment adoption.
Japan
Japan faces a growing prevalence of degenerative tendon conditions among its aging population, creating a consistent patient base for both conservative and advanced treatments. The Pharmaceuticals and Medical Devices Agency (PMDA) regulates the approval and post-market surveillance of therapeutic products. Metropolitan areas such as Tokyo and Osaka serve as key hubs for specialized orthopedic and rehabilitation services.
United States
Orthopedic clinics in the United States are primary purchasers of surgical devices and biologics, reflecting a preference for advanced interventions. The US Food and Drug Administration (FDA) mandates rigorous clinical trials for new medical technologies. Innovation clusters in Boston and San Francisco drive the development and early adoption of novel biotech and medtech solutions.
Australia
Sports medicine facilities in Australia exhibit high demand for rapid recovery solutions, integrating advanced regenerative therapies into mainstream practice. The Therapeutic Goods Administration (TGA) ensures the safety and efficacy of medical products available in the market. Sydney and Melbourne are significant centers for sports injury treatment and rehabilitation.
Singapore
Singapore's healthcare infrastructure development presents an opportunity to introduce advanced tendonitis treatments to a growing middle class with increasing access to private healthcare. The Ministry of Health (MOHAP) oversees health policies and regulations for medical services. The Biopolis research park in Singapore City fosters biotech innovation, supporting specialized treatment development.
Tendonitis Treatment Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes within the tendonitis treatment market, creating a tiered competitive structure. The market exhibits a blend of consolidation among pharmaceutical giants and fragmentation among specialized device and biologic firms. Established pharmaceutical companies, specialized orthopedic device manufacturers, and emerging regenerative therapy providers represent the primary strategic archetypes. Competitive moves include portfolio diversification and strategic partnerships to expand treatment offerings.
Established pharmaceutical companies like US-based Pfizer and German-headquartered Bayer AG represent the broad-spectrum medication archetype, leveraging extensive anti-inflammatory drug portfolios and over-the-counter topical analgesics. These firms benefit from wide distribution networks and established brand recognition among general practitioners. Meanwhile, US-based Stryker occupies a position within the specialized orthopedic device and surgical solutions segment, catering to severe tendon injuries through advanced instrumentation and implants for complex reconstruction cases.
| Leading Market Players |
|---|
| Abbott |
| Pfizer |
| Bayer AG |
| AstraZeneca |
| Boehringer Ingelheim Pharmaceuticals, Inc. |
| GlaxoSmithKline PLC |
| Merck and Co., Inc. |
| Stryker |
| Zimmer Biomet Holdings, Inc. |
| Others |
Cost & Logistics Intelligence
The six-month lead time for specialized biologic components significantly influences pricing power, particularly for advanced regenerative therapies, due to the intricate manufacturing processes and stringent regulatory approvals required.
Pricing Analysis
Geographic price spreads are notable, with North American markets supporting premium pricing for advanced biologics, while European nations like Germany emphasize cost-effectiveness for broader access. Value-based pricing models dominate for Platelet-Rich Plasma therapy, reflecting patient outcomes and specialized clinical delivery. Price differentiation stems from FDA/EMA certification tiers and after-sales support for complex orthopedic devices. Pricing softness in Nonsteroidal Anti-Inflammatory Drugs stems from widespread generic competition. Public health systems exhibit high price sensitivity for pharmaceuticals, whereas private orthopedic clinics are less price-sensitive for advanced regenerative treatments.
Supply Chain Analysis
Germany and the United States anchor advanced orthopedic device manufacturing and biologic research within the tendonitis treatment market. The supply chain draws from specialized medical-grade polymers and pharmaceutical excipients as key raw material dependencies. Single-source vulnerability for rare biologics represents a structural supply chain risk. Downstream distribution runs through established hospital procurement networks and specialized medical distributors, reaching orthopedic clinics and sports medicine facilities globally.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The tendonitis treatment market shows early-cycle expansion, driven by increasing adoption of regenerative therapies like Platelet-Rich Plasma and a global rise in sports-related injuries.
For Market Incumbents:Fortify existing anti-inflammatory drug portfolios through lifecycle management and expanded clinical trial investment. Strategic partnerships with specialized orthopedic clinics can mitigate the threat from emerging biologic entrants. Invest in R&D for next-generation biologic scaffolds to maintain technology leadership. Leverage established distribution networks to counter reimbursement ambiguity for newer therapies.
For New Entrants and Emerging Players:Service-layer gaps in personalized treatment protocols offer significant entry points for specialized providers. Target under-served regional markets in Southeast Asia and Latin America, where healthcare infrastructure is developing. A go-to-market angle should highlight superior patient outcomes and faster recovery times for minimally invasive procedures. Focus on niche applications within sports medicine facilities seeking advanced diagnostics.
For Investors and Strategic Acquirers:Long-term, this sits as a high-growth medical technology play because of aging demographics and increasing sports participation. Target innovative regenerative therapy developers or specialized orthopedic device manufacturers with strong intellectual property portfolios. The consistent expansion of reimbursement policies for biologics in key markets serves as a critical inflection signal to watch. Evaluate companies offering integrated diagnostics with treatment solutions.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Accelerates regulatory approval for novel biologic therapies, enhancing market access. |
| Manufacturing Scale-Up | Reduces per-unit costs for regenerative treatments, improving affordability. |
| Platform Integration | Combines diagnostic imaging with treatment delivery, improving procedural accuracy. |
| Geographic Expansion | Introduces advanced therapies to emerging markets, broadening patient reach. |
| Hospital System Partnership | Secures preferred vendor status for devices and biologics within large networks. |
Research Approach
The analysis maps pharmaceutical treatments, biologic therapies, and orthopedic devices, each validated through primary interviews with orthopedic surgeons and regulatory affairs specialists. Secondary data sources, including US FDA filings, European EMA guidelines, and medical journal databases, informed the market landscape. Bottom-up and top-down triangulation ensured data accuracy and comprehensive market coverage.
Outputs were rigorously validated against external benchmarks like national health expenditure data and industry association reports across the projection horizon. Segmentation dimensions modeled included product type, therapy area, end user, delivery mode, and regional healthcare spending. Compound annual growth rates were derived from historical trends and projected market drivers, incorporating new product launch pipelines and prevalence of musculoskeletal conditions.
Material uncertainties — unforeseen regulatory changes or major technological breakthroughs — sit outside the modeled envelope. Forecasts reflect assumptions regarding evolving reimbursement policies and clinical trial outcomes for emerging therapies. Recalibration cycles align with material shifts in named drivers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
CINV Treatment Market
Medical Treatment
Global Uterine Fibroids Treatment Market
Medical Treatment
Myotonic Dystrophy Treatment Market
Medical Treatment
Systemic Mastocytosis Treatment Market
Medical Treatment
Liver Fluke Treatment Market
Medical Treatment
Thyroid Deficiency Treatment Market
Medical Treatment
Rett Syndrome Treatment Market
Medical Treatment
Anti-Rickettsial Treatment Market
Medical Treatment
Nasopharyngeal Carcinoma Treatment Market
Medical Treatment
Global Hyperhidrosis Treatment Market
Medical Treatment
Pelvic Organ Prolapse Repair Market
Medical Treatment
Refsum Disease Treatment Market
Medical Treatment
Facial Spasm Treatment Market
Medical Treatment
Middle Ear Infection Treatment Market
Medical Treatment
Porphyria Treatment Market
Medical Treatment
Transarterial Chemoembolization (TACE) Market