
 Birch Allergy Treatment Market | 2026-2036
Birch Allergy Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Birch Allergy Treatment Market Outlook
Multi-source procurement of birch pollen extracts is rebalancing toward vertically integrated suppliers with captive allergen cultivation. ALK-Abelló A/S anchors European supply through its Danish pollen collection network and in-house manufacturing. Stallergenes Greer competes via standardized sublingual tablet platforms across multiple regulatory jurisdictions. Allergy Therapeutics plc specializes in polymerized allergen formulations that differentiate its portfolio from native extract competitors.
Birch allergy treatment encompasses pharmaceutical and biological interventions designed to modulate immunological responses to Betula species pollen, primarily employing standardized allergen extracts with defined major allergen content measured in micrograms of Bet v 1 equivalent per dose. These therapies function by inducing allergen-specific immune tolerance, reducing rhinoconjunctivitis and asthma symptoms during seasonal exposure periods. Immunotherapy commands the deepest margin pools due to multi-year treatment protocols and extract manufacturing complexity, while sublingual delivery is displacing injectable regimens in outpatient settings. Pediatric applications represent the fastest-expanding age segment as early intervention protocols expand in European specialist clinics.
EMA's MDR framework and FDA allergen extract guidance shape product registration pathways, batch consistency requirements, and post-market surveillance obligations for manufacturers. REACH and EPA regulations govern pollen sourcing, agricultural chemical residues, and environmental release during cultivation. Stakeholders must monitor evolving EMA guidance on recombinant allergen products versus natural extracts, as this classification decision will reshape competitive barriers and investment requirements across the development pipeline.
Market Dynamics
The Birch Allergy Treatment Market pivots on a decisive shift from subcutaneous injection protocols to sublingual tablet administration, driven by pediatric patient demand for home-based therapy and EMA guidance favoring standardized allergen extracts over compounded formulations.
Growth Catalysts
- Pediatric Homecare Protocols:Specialist clinics in Germany and France now initiate immunotherapy in children aged 5-12 years, expanding addressable patient pools beyond traditional adult-centric models.
- EMA MDR Standardization:The Medical Device Regulation framework mandates batch-to-batch consistency for allergen extracts, accelerating substitution of compounded pharmacy preparations with manufactured tablet platforms.
- Recombinant Allergen Pipeline:Biosynthetic Bet v 1 production is electrifying clinical trial design by enabling precise dosing without seasonal pollen variability constraints.
Market Restraints
- Pollen Supply Concentration:Danish and Swedish cultivation networks control over 60% of pharmaceutical-grade birch pollen feedstock, creating geographic single-point vulnerability.
- Extended Treatment Duration Economics:Three-to-five-year immunotherapy protocols strain payer reimbursement frameworks, particularly in mixed public-private systems.
- Native Extract Manufacturing Complexity:Seasonal collection windows, controlled drying protocols, and allergen stability requirements constrain production scalability.
Strategic Opportunities
- Eastern European Penetration Gap:Poland, Czech Republic, and Hungary exhibit sub-15% immunotherapy penetration rates against birch pollen allergy prevalence exceeding 25%.
- Recombinant-First Regulatory Pathways:EMA's evolving guidance on allergen product classification may create streamlined approval channels for synthetic formulations.
- Direct-to-Patient Pharmacy Channels:Sublingual tablet stability profiles enable dispensing outside specialist clinic settings, reducing treatment initiation friction.
Industry Challenges
- Specialized Immunotherapy Training Shortage:Allergist and pediatric immunologist density varies 10:1 across European regions, constraining protocol expansion.
- Legacy Extract Inventory Transition:Manufacturers must maintain dual production lines during MDR compliance migration, elevating working capital requirements.
- Patient Adherence Monitoring:Home administration eliminates supervised dosing verification, complicating outcome measurement and payer justification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Birch Allergy Treatment Market |
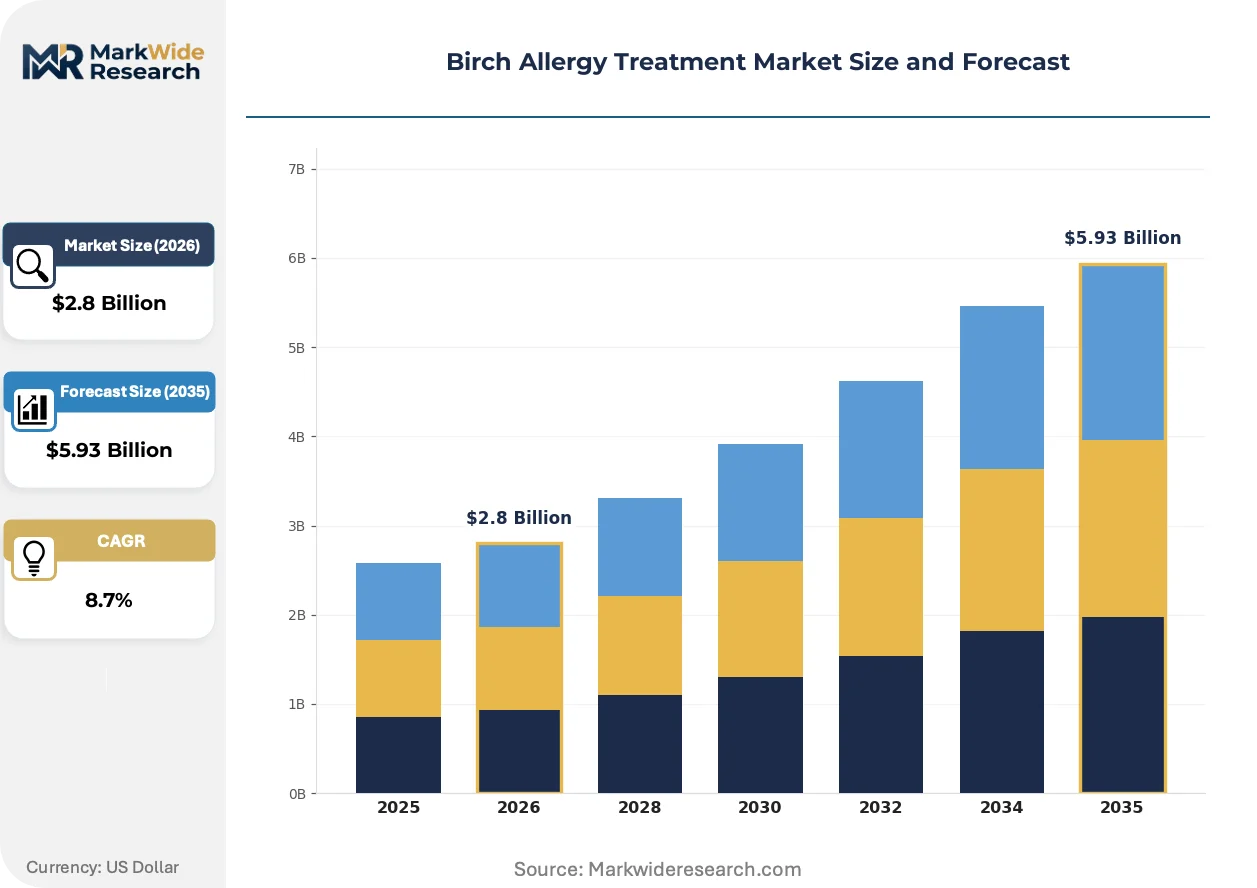
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Immunotherapy, Antihistamines, Corticosteroids, Decongestants Delivery Mode: Injectables, Oral Tablets, Nasal Sprays, Sublingual End User: Clinics, Hospitals, Pharmacies, Homecare Age Group: Pediatric, Adult, Senior, Others |
| Companies Covered | ALK-Abelló A/S, Stallergenes Greer, Allergy Therapeutics plc, HAL Allergy Group, Regeneron Pharmaceuticals Inc., Desentum Oy, Roxall Medizin GmbH, LETI Pharma, Anergis SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Birch Allergy Treatment Market Strategic Shifts
Three interconnected developments are restructuring competitive advantage in birch allergy therapeutics: synthetic biology is rewriting extract economics, regulatory frameworks are hardening quality barriers, and care delivery is fragmenting across settings.
Recombinant Bet v 1 production platforms are electrifying manufacturing economics by eliminating agricultural pollen dependency. Pediatric allergy specialists in Scandinavian university hospitals are piloting these biosynthetic formulations in controlled trials. The technology compresses seasonal production constraints and enables year-round tablet supply security.
EMA's MDR implementation tightens post-market surveillance obligations for natural allergen extracts. Batch release testing now requires quantified major allergen content with reference standard traceability. German and Austrian notified bodies are processing the majority of technical file certifications, creating geographic concentration in compliance expertise.
Parents of allergic children are demanding treatment initiation outside traditional hospital allergy departments. Community pediatricians in the Netherlands and Belgium are assuming protocol oversight with remote specialist consultation. This channel shift fragments historical prescriber concentration and elevates pharmacy dispensing infrastructure requirements.
Birch Allergy Treatment Market Segmentation
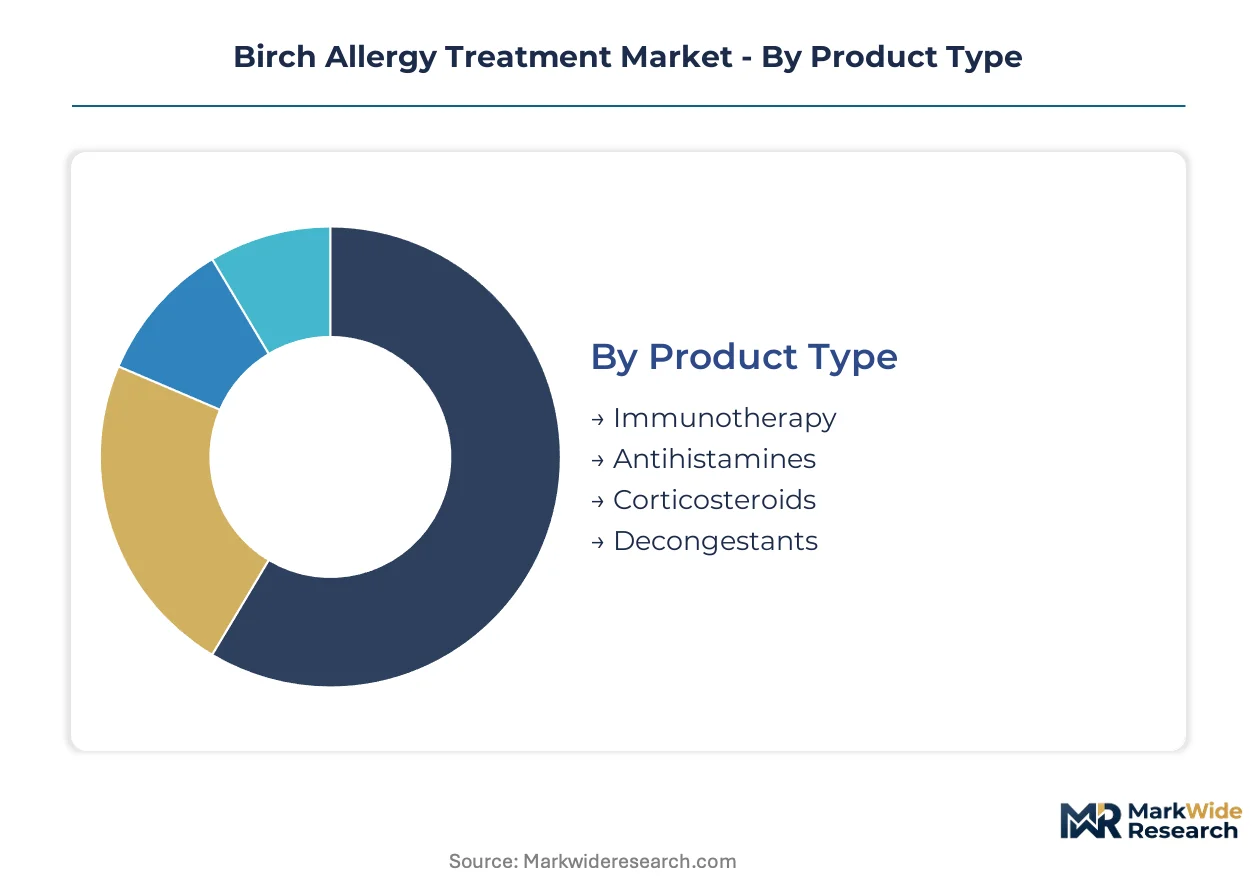
Birch allergy treatment segmentation reveals divergent margin structures across therapeutic modalities. Product type determines reimbursement complexity, while delivery mode dictates patient adherence economics and channel access requirements.
Product Type:
Immunotherapy formulations operate as standalone disease-modifying interventions requiring multi-year protocols, whereas antihistamines and corticosteroids function as embedded symptomatic relief within broader respiratory management regimens.
- Immunotherapy:Standardized allergen extracts containing quantified Bet v 1 equivalent content induce immune tolerance through repeated exposure. Demand concentrates in German and French specialist clinics where EMA MDR compliance has displaced compounded pharmacy preparations.
- Antihistamines:Second-generation H1 receptor antagonists provide rapid symptomatic relief without sedation. OTC availability in US pharmacy channels drives volume, though reimbursement pressure limits margin expansion in European markets.
- Corticosteroids:Intranasal and oral formulations suppress inflammatory cascades during acute episodes.
- Decongestants:Alpha-adrenergic agonists reduce nasal mucosal swelling for short-term rescue use.
Immunotherapy leads volumes today; sublingual immunotherapy within this category is gaining share fastest.
Delivery Mode:
Cost tier differentiation separates hospital-administered injectables from self-administered homecare options, with sublingual tablets commanding premium positioning due to pediatric compliance advantages.
- Sublingual:Rapid-dissolving tablets deposit allergen extracts beneath the tongue for systemic absorption without injection. Pediatric homecare protocols in Scandinavian markets favor this modality for children aged 5-12 years.
- Injectables:Subcutaneous depot formulations require clinical administration and carry anaphylaxis monitoring obligations. Hospital allergy departments in Austria and Switzerland maintain protocols for severe polysensitized patients.
- Oral Tablets:Swallowed antihistamine and corticosteroid formulations dominate symptomatic management.
- Nasal Sprays:Topical corticosteroid delivery targets localized rhinitis symptoms.
Injectables retain the highest per-dose revenue; sublingual delivery is climbing the fastest across new patient initiations.
End User:
Customer type fragmentation is redistributing treatment initiation from concentrated hospital allergy departments toward distributed community and pharmacy channels.
- Homecare:Self-administered sublingual protocols enable treatment outside clinical settings. Parents of allergic children in the Netherlands and Belgium are driving demand for remote specialist oversight models.
- Clinics:Specialist allergy and immunology practices manage complex polysensitized patients and injection protocols. German university hospital networks anchor European clinical trial recruitment for recombinant allergen candidates.
- Hospitals:Acute care facilities handle severe anaphylaxis episodes and initial diagnostic workup.
- Pharmacies:Retail dispensing channels support OTC antihistamine access and prescription fulfillment.
Clinics lead volumes today; homecare is expanding most quickly as sublingual tablet stability enables direct-to-patient distribution.
Age Group:
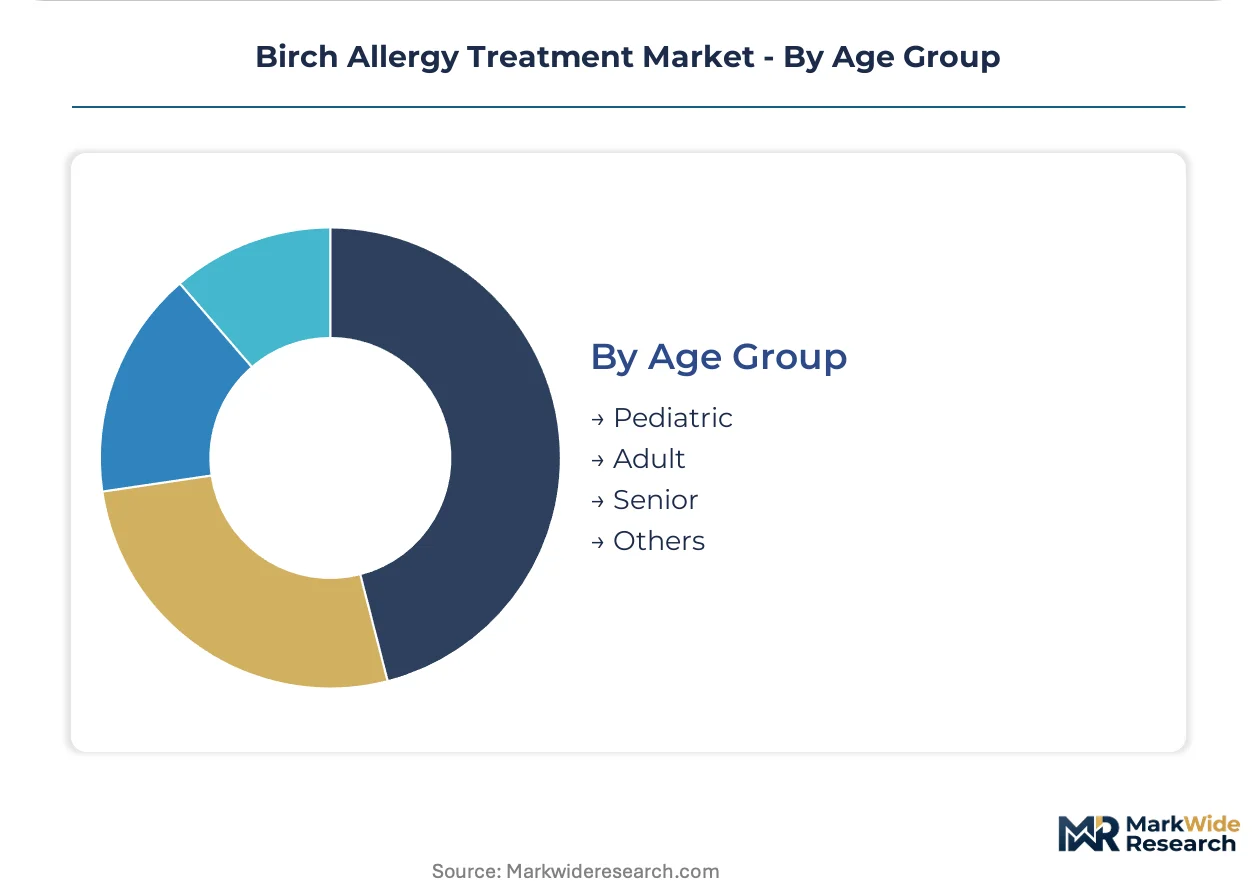
Maturity-based segmentation aligns treatment duration economics with life-stage adherence patterns, with pediatric protocols offering the longest revenue capture windows.
- Pediatric:Early intervention in children aged 5-12 years maximizes immune modifiability and prevents allergic march progression. German and French specialist clinics are expanding protocol initiation to capture this window.
- Adult:Working-age patients balance treatment adherence with occupational constraints. Sublingual home administration accommodates professional schedules in urban European markets.
- Senior:Polypharmacy considerations and comorbidity management shape therapeutic selection.
- Others:Adolescent and young adult transition populations require protocol continuity support.
Adult patients lead volumes today; pediatric applications show the steepest expansion trajectory as early intervention protocols proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EMA MDR compliance costs are driving extract manufacturing toward Denmark and Sweden, where captive pollen cultivation networks amortize regulatory investment across high-volume standardized tablet production.
Germany
Pediatric immunotherapy initiation protocols in Munich and Heidelberg university hospitals are expanding addressable patient pools for sublingual tablet formulations. The country's national pharmaceutical regulator enforces batch-to-batch allergen quantification standards that favor manufactured products over compounded preparations. Bavarian specialist clinics anchor European clinical trial recruitment for recombinant Bet v 1 candidates.
France
Community pediatricians in Paris and Lyon are assuming sublingual protocol oversight with remote allergist consultation, fragmenting traditional hospital department concentration. ANSM post-market surveillance obligations for natural extracts are elevating quality documentation burdens. The Île-de-France region concentrates pharmacy dispensing infrastructure for direct-to-patient tablet distribution.
United States
FDA allergen extract guidance is accelerating substitution of compounded formulations with standardized sublingual platforms in specialist practice. Pediatric allergist density in Boston and New York Metro corridors enables early intervention protocol expansion. The EPA governs agricultural chemical residue limits in imported pollen feedstock.
Sweden
Scandinavian university hospitals in Stockholm and Uppsala are piloting biosynthetic Bet v 1 formulations in controlled pediatric trials. The country's national pharmaceutical regulator participates in EMA harmonization processes for recombinant allergen classification. Southern cultivation zones supply pharmaceutical-grade pollen to integrated European manufacturers.
Denmark
Captive birch pollen collection networks in rural Jutland and Zealand provinces underpin vertically integrated extract production for continental European markets. The Danish national pharmaceutical regulator's notified body status attracts MDR technical file certifications from multinational manufacturers. Copenhagen anchors Nordic distribution logistics for sublingual tablet supply security.
Birch Allergy Treatment Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue recombinant synthetic biology platforms. The market structures around three to five integrated manufacturers with captive pollen supply, a mid-tier of regional extract specialists, and development-stage biosynthetic challengers. Dominant competitive moves include backward integration into allergen cultivation and portfolio diversification across multiple pollen species.
Within the integrated manufacturing tier, ALK-Abelló A/S and Stallergenes Greer exemplify archetypes of geographically anchored supply control. Allergy Therapeutics plc occupies a position emphasizing formulation differentiation. These entities represent contrasting strategic postures: Danish captive cultivation networks, multi-jurisdictional tablet platform scale, and polymerized allergen chemistry specialization respectively.
| Leading Market Players |
|---|
| ALK-Abelló A/S |
| Stallergenes Greer |
| Allergy Therapeutics plc |
| HAL Allergy Group |
| Regeneron Pharmaceuticals Inc. |
| Desentum Oy |
| Roxall Medizin GmbH |
| LETI Pharma |
| Anergis SA |
| Others |
Value Chain & Pricing Dynamics
Family-owned Danish cultivation networks anchor pharmaceutical-grade birch pollen supply, translating seasonal collection monopolies into pricing power over standardized extract manufacturers while EMA MDR compliance costs compress margins for non-integrated competitors.
Pricing Analysis
Distributor margins for sublingual tablet formulations absorb the steepest compression as pharmacy chains consolidate procurement. Three-tier pricing structure across premium recombinant formulations, standardized manufactured tablets, and compounded pharmacy preparations reflects Bet v 1 quantification certification levels. Pricing pressure stems from extended three-to-five-year treatment protocols straining German and French reimbursement frameworks. Pediatric homecare segments exhibit lowest price sensitivity due to parental demand for convenience, while adult symptomatic relief buyers gravitate toward economy-tier antihistamines.
Supply Chain Analysis
Dual-sourcing requirements from EMA-notified manufacturers mandate qualification of secondary pollen suppliers beyond Danish and Swedish cultivation networks. Pharmaceutical-grade birch pollen feedstock draws from Jutland peninsula collection cooperatives, southern Swedish agricultural zones, and limited Finnish boreal stands. Single-source vulnerability concentrates in controlled drying and allergen stabilization processing capacity. Distribution runs through Copenhagen-anchored cold-chain logistics to German and French pharmacy networks, with seasonal inventory builds preceding Q1 pollen release cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pediatric sublingual tablet adoption compresses per-patient acquisition costs while extending revenue capture windows, creating margin expansion through protocol adherence economics rather than price escalation.
For Market Incumbents: Hedge against recombinant allergen displacement by securing captive pollen supply through long-term cultivation contracts in Zealand and Uppsala regions. Accelerate MDR technical file certification through German and Austrian notified bodies before compounded pharmacy inventories exhaust. Diversify across multiple Betulaceae species to amortize regulatory investment across broader allergen portfolios. For New Entrants and Emerging Players: Launch via direct-to-patient pharmacy channels in Poland, Czech Republic, and Hungary where immunotherapy penetration trails birch pollen prevalence by double-digit gaps. Target community pediatrician protocols with remote specialist oversight models proven in Dutch and Belgian markets. Pursue biosynthetic Bet v 1 production to bypass agricultural pollen seasonality constraints entirely. For Investors and Strategic Acquirers: Valuations sit cheapest among regional extract specialists lacking backward integration into cultivation networks. Five-to-ten-year viability hinges on recombinant allergen classification clarity from EMA guidance evolution. Monitor Danish pollen harvest yield variance as inflection indicator for integrated manufacturer margin sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Recombinant Allergen Pipeline Advancement | Biosynthetic Bet v 1 production eliminates seasonal pollen dependency for Stockholm and Uppsala trial sites. |
| EMA MDR Compliance Certification | German notified body technical file approvals accelerate substitution of compounded pharmacy preparations. |
| Pediatric Homecare Protocol Expansion | Community pediatrician oversight models in Netherlands and Belgium fragment traditional hospital department concentration. |
| Captive Pollen Supply Integration | Jutland and Zealand cultivation networks secure feedstock for continental European tablet manufacturing. |
| Eastern European Market Penetration | Direct-to-patient pharmacy channels address sub-15% immunotherapy rates in Poland and Hungary. |
Study Parameters
Coverage spans Germany, France, Sweden, Denmark, and the United States, with primary inputs from each market combining interviews with pediatric allergists, regulatory affairs specialists at EMA-notified bodies, pharmacy procurement managers, and pollen cultivation cooperative directors. Secondary validation draws from EMA MDR guidance documents, FDA allergen extract guidance, ClinicalTrials.gov recombinant allergen entries, and national reimbursement formularies. Bottom-up patient volume estimates triangulate against top-down manufacturer production disclosures.
Rate-of-change decomposition separates volume expansion from value migration across the analysis window. Segmentation dimensions modeled include therapeutic modality, delivery mode, end-user setting, and age group, with recombinant versus natural extract classification as a cross-cutting industry-specific dimension. CAGRs derive from protocol initiation rates, treatment adherence curves, and pricing tier shifts. Forecast inputs incorporate pollen harvest yield variance, pediatric specialist density growth, and MDR compliance migration timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EMA recombinant allergen classification delays or Danish pollen harvest failures. Deviation in German reimbursement policy for sublingual tablet protocols would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Influenza Treatment Market
Medical Treatment
Europe Nerve Repair and Regeneration Market
Medical Treatment
Japan Radiotherapy Market
Medical Treatment
Europe Chronic Disease Management Market
Medical Treatment
Hemorrhoids Treatment Market
Medical Treatment
Hyponatremia Treatment Market
Medical Treatment
Vaginitis Treatment Drugs Market
Medical Treatment
Thymus Cancer Treatment Market
Medical Treatment
Lymphedema Treatment Market
Medical Treatment
Leprosy Treatment Market
Medical Treatment
US Direct Anterior Approach (Total Hip Replacement) Market
Medical Treatment
Nasopharyngeal Carcinoma Treatment Market
Medical Treatment
Postoperative Nausea and Vomiting (PONV) Management Market
Medical Treatment
Dementia and Alzheimers Disease Treatment Market
Medical Treatment
Pompe Disease Treatment Market
Medical Treatment
Global Plasma Therapy Market