
 Myasthenia Gravis Market | 2026-2036
Myasthenia Gravis Market Size, Share, and Industry Trends Forecast 2026-2036
Myasthenia Gravis Market Outlook
Biologics-grade manufacturing standards are redrawing competitive boundaries in the Myasthenia Gravis Market. Alexion Pharmaceuticals leverages its complement inhibition expertise to sustain leadership in refractory patient segments. argenx anchors European commercialization through its FcRn blocker portfolio, while UCB competes via differentiated subcutaneous dosing formulations that reduce hospital dependency.
Myasthenia gravis constitutes an autoimmune neuromuscular disorder characterized by autoantibody-mediated destruction of acetylcholine receptors at the neuromuscular junction, with diagnostic confirmation requiring serological testing and repetitive nerve stimulation studies. The condition impairs voluntary muscle contraction, creating chronic therapeutic need across symptomatic and disease-modifying interventions. Monoclonal antibodies command the highest margin pool within product type segmentation due to manufacturing complexity and orphan drug pricing authority. Disease modifying therapy represents the fastest-growing application category as clinicians shift from chronic corticosteroid exposure toward targeted immunologic intervention. Hospital end users retain the largest volume share, though home care settings are capturing incremental subcutaneous administration volume.
FDA orphan drug designation and EMA PRIME eligibility frameworks shape development economics by conferring market exclusivity and protocol assistance for novel entrants. REACH compliance and ISO 13485 quality management standards govern biologic manufacturing and medical device components for infusion delivery systems. Stakeholders must monitor evolving payer evidence requirements for FcRn inhibitor positioning against established B-cell depletion protocols.
Market Dynamics
FcRn inhibitor commercialization is compressing treatment paradigms across the Myasthenia Gravis Market, forcing incumbent corticosteroid protocols into retreat while biologics manufacturing scales to serve chronic autoimmune maintenance therapy.
Growth Catalysts
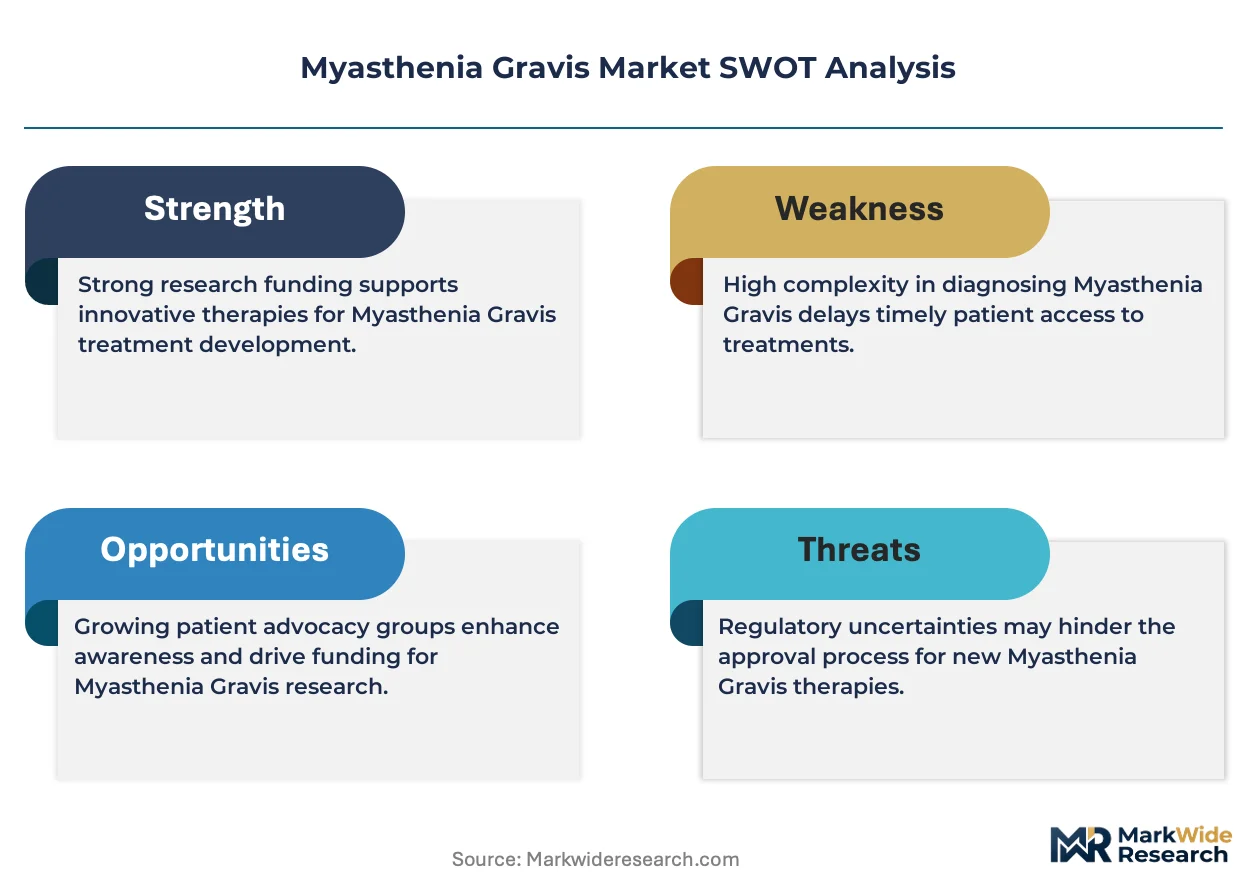
- Subcutaneous administration migration:Hospital-based infusion centers are expanding ambulatory capacity to capture outpatient monoclonal antibody volume, reducing inpatient bed utilization while maintaining reimbursement integrity.
- EMA PRIME eligibility acceleration:Rare disease biologics receive protocol assistance and accelerated assessment, compressing development timelines for novel immunologic interventions targeting refractory patient populations.
- Serological diagnostic penetration:Acetylcholine receptor antibody testing is expanding beyond academic medical centers into community neurology practices, shortening diagnostic delays and expanding addressable patient pools.
Market Restraints
- Biologics manufacturing concentration:Single-source contract manufacturing organizations in Switzerland and Belgium control critical fill-finish capacity for FcRn inhibitors, creating geographic supply vulnerability.
- Orphan drug pricing authority limits:Payer evidence requirements for FcRn inhibitor positioning against established B-cell depletion protocols are tightening, constraining pricing flexibility for novel entrants.
- Plasma-derived immunoglobulin substitution:Intravenous immunoglobulin remains entrenched in generalized myasthenia gravis maintenance, displacing biologic uptake in cost-sensitive health systems.
Strategic Opportunities
- Home infusion channel development:Subcutaneous therapy delivery is creating direct-to-patient distribution infrastructure, bypassing hospital-based infusion center dependency for maintenance dosing.
- Japan's PMDA Sakigake designation:Early approval pathways for rare disease biologics are attracting development investment targeting the Asia-Pacific's second-largest pharmaceutical market.
- Real-world evidence integration:Electronic health record data lakes are enabling post-market outcome tracking that satisfies FDA accelerated approval confirmatory study requirements.
Industry Challenges
- Bioprocess engineering talent scarcity:Cell culture optimization and biosimilar analytical characterization expertise concentrates at a handful of contract development organizations, constraining manufacturing scale-up velocity.
- Cold chain integrity assurance:Temperature excursion risk during last-mile distribution of temperature-sensitive monoclonal antibodies requires redundant monitoring infrastructure and contingency protocol investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Myasthenia Gravis Market |
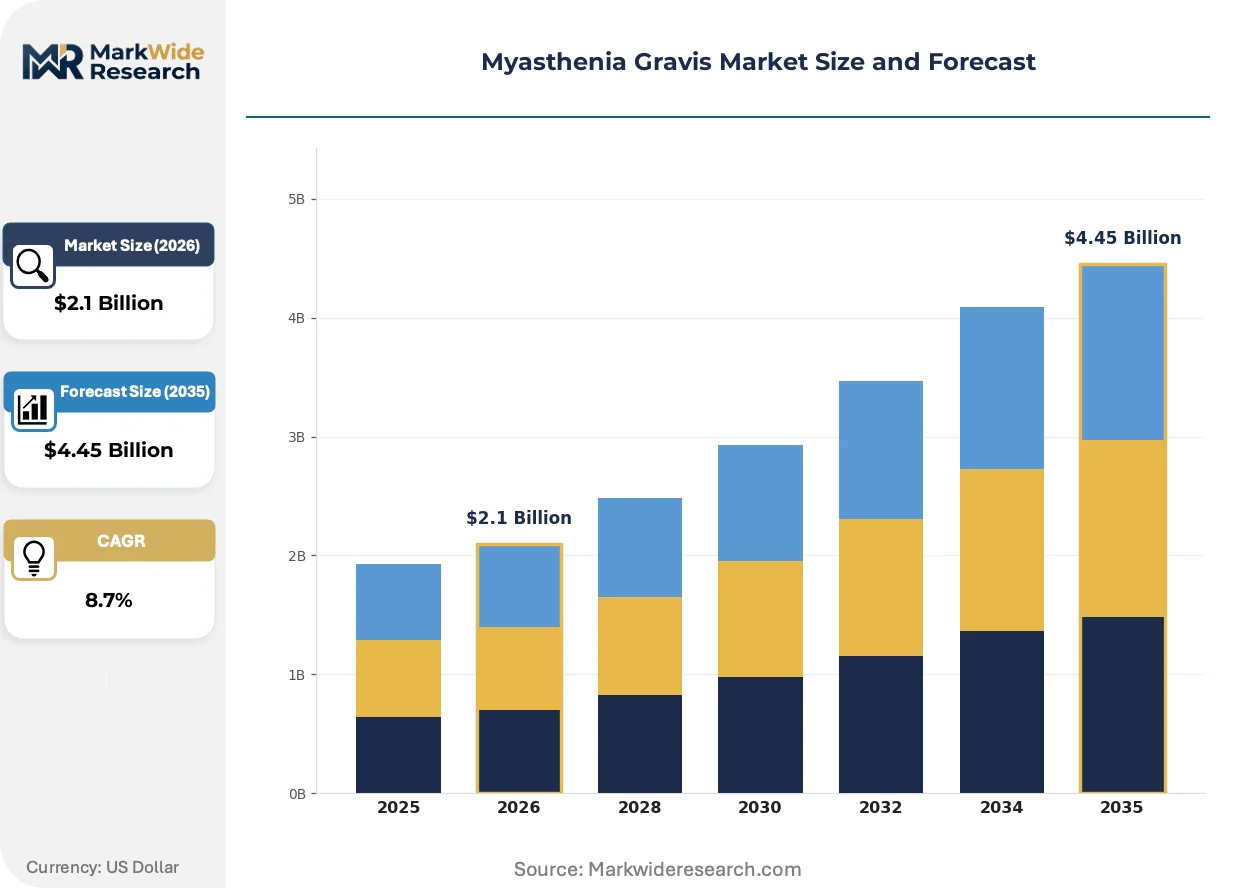
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.45 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoclonal Antibodies, Immunosuppressants, Corticosteroids, Cholinesterase Inhibitors Application: Symptomatic Treatment, Disease Modifying Therapy, Supportive Care, Clinical Trials End User: Hospitals, Clinics, Research Institutions, Home Care Settings Delivery Mode: Intravenous, Subcutaneous, Oral, Intramuscular |
| Companies Covered | Alexion Pharmaceuticals, Novartis, argenx, UCB, Pfizer, AbbVie, F. Hoffmann-La Roche, Grifols, Johnson & Johnson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Myasthenia Gravis Market Strategic Shifts
Neonatal Fc receptor biology is redefining therapeutic targets in autoimmune neuromuscular disease, with engineering advances enabling subcutaneous delivery and chronic administration models that displace episodic hospital-based care.
Subcutaneous FcRn inhibitor formulations are fragmenting traditional infusion center economics. argenx and UCB have pioneered皮下 dosing regimens that reduce hospital dependency while maintaining therapeutic exposure. Community neurology practices are adopting these protocols to retain patient volume previously referred to academic infusion centers. The shift is compressing site-of-care revenue for hospital systems while expanding pharmacy benefit management complexity.
FDA's accelerated approval pathway for rare disease biologics is reshaping confirmatory evidence standards. The agency now accepts intermediate clinical endpoints and real-world data streams for post-market verification, reducing pivotal trial burden. EMA's parallel PRIME scheme offers similar protocol assistance, though HTA body divergence on value assessment creates European launch sequencing complexity. Manufacturers must navigate divergent payer evidence requirements across Germany's G-BA, France's HAS, and England's NICE.
Patient advocacy organizations are consolidating diagnostic referral pathways. The Myasthenia Gravis Foundation of America and comparable European patient groups are building certified center networks that steer newly diagnosed patients toward academic medical centers with clinical trial access. This concentration is fragmenting community neurology's historical role in chronic disease management while accelerating trial enrollment velocity for novel mechanism sponsors.
Myasthenia Gravis Market Segmentation
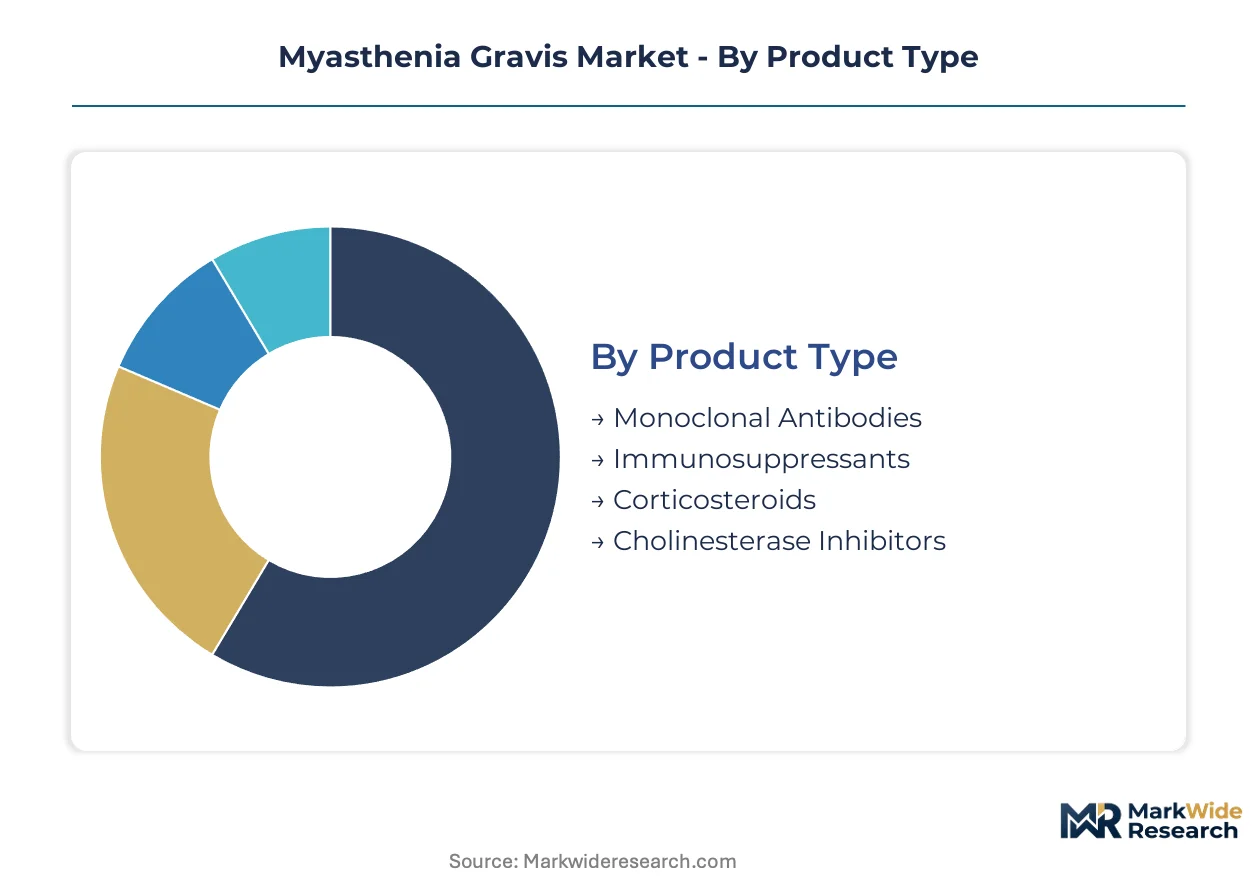
Channel economics in myasthenia gravis therapy hinge on administration complexity and reimbursement site-of-care rules. Each segment category carries distinct distribution logic that shapes margin capture and patient access.
Product Type:
Hospital infusion centers and specialty pharmacy channels split volume based on biologic handling requirements and cold chain infrastructure.
- Monoclonal Antibodies:Engineered immunoglobulins targeting FcRn or complement pathways require temperature-controlled distribution and certified infusion nursing. Demand concentrates in academic medical centers with clinical trial access and prior authorization expertise, though subcutaneous formulations are shifting volume toward home infusion channels.
- Immunosuppressants:Small-molecule agents including azathioprine and mycophenolate mofetil function through lymphocyte proliferation inhibition. Community neurology practices in the United States and Germany drive prescription volume for maintenance immunosuppression, constrained by hepatotoxicity monitoring requirements and teratogenic risk counseling.
- Corticosteroids:Prednisone and methylprednisolone remain first-line induction therapy distributed through retail pharmacy networks.
- Cholinesterase Inhibitors:Pyridostigmine bromide provides symptomatic relief via acetylcholinesterase inhibition at the neuromuscular junction.
Monoclonal antibodies dominate installed base value. Immunosuppressants are where expansion concentrates as steroid-sparing protocols gain adoption.
Application:
Therapeutic intent determines prescriber specialty, with neurologists managing chronic immunomodulation and emergency physicians handling acute exacerbation protocols.
- Symptomatic Treatment:Acetylcholinesterase inhibitors and plasmapheresis address immediate muscle weakness without altering autoimmune pathology. Demand flows through emergency departments and ambulatory infusion centers in metropolitan hospital systems, driven by myasthenic crisis prevention and pre-operative stabilization requirements.
- Disease Modifying Therapy:Biologic and small-molecule immunosuppressants target underlying autoantibody production and complement-mediated muscle damage. Academic medical centers with multidisciplinary neuromuscular clinics in the United States, France, and Japan concentrate prescribing authority, supported by FDA and EMA accelerated approval pathways for novel mechanism agents.
- Supportive Care:Respiratory monitoring, nutritional support, and physical therapy address comorbidity burden.
- Clinical Trials:Investigational therapies for refractory populations generate site revenue and patient access to pre-commercial mechanisms.
Disease modifying therapy dominates installed base. Symptomatic treatment is where volume concentrates given crisis intervention frequency.
End User:
Site-of-care migration is reshaping reimbursement capture, with hospital systems defending infusion revenue against home-based subcutaneous alternatives.
- Hospitals:Inpatient units and hospital-based infusion centers retain complex biologic administration requiring adverse event monitoring infrastructure. United States health systems with dedicated neuromuscular centers capture biologic margin through 340B pricing advantages and specialty pharmacy integration.
- Clinics:Community neurology practices and multispecialty groups manage stable patients on oral immunosuppression.
- Research Institutions:Academic medical centers with NIH or EMA trial networks enroll refractory patients.
- Home Care Settings:Subcutaneous FcRn inhibitor delivery enables patient self-administration with nursing oversight.
Hospitals dominate installed base. Home care settings are climbing the fastest as subcutaneous formulations reduce site-of-care dependency.
Delivery Mode:
Administration route dictates supply chain configuration, with intravenous requiring cold chain integrity and oral demanding compliance packaging.
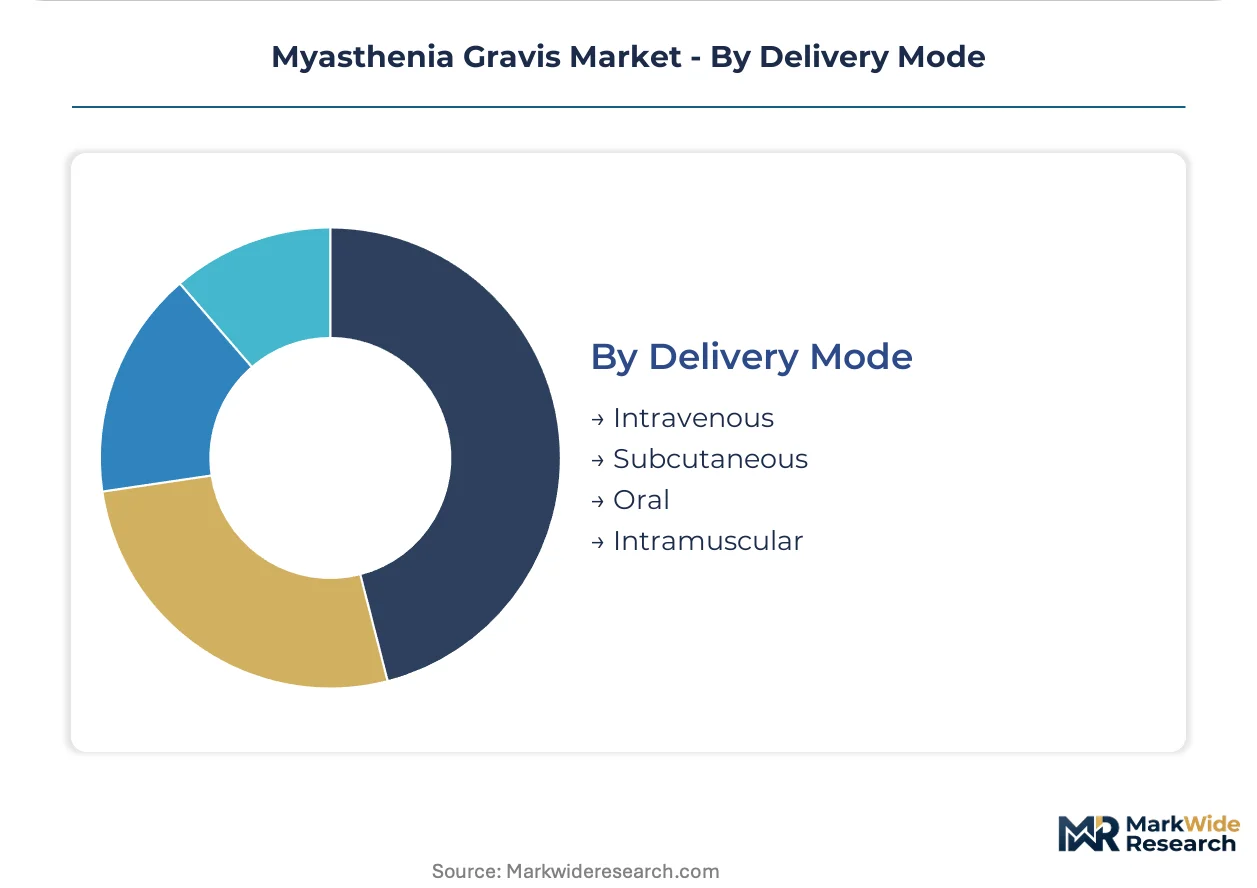
- Intravenous:Infusion-dependent biologics and immunoglobulin require healthcare facility administration with anaphylaxis preparedness. United States hospital outpatient departments and German academic infusion centers concentrate volume, though reimbursement compression is driving site-of-care migration.
- Subcutaneous:FcRn inhibitors and immunoglobulin formulations enable ambulatory or home administration with reduced infusion reaction risk.
- Oral:Cholinesterase inhibitors and corticosteroids distribute through retail pharmacy networks with generic substitution pressure.
- Intramuscular:Rescue corticosteroid protocols for crisis management utilize emergency department administration.
Intravenous dominates installed base. Subcutaneous is gaining share fastest as manufacturers engineer patient-friendly dosing regimens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Biologics manufacturing capacity for FcRn inhibitors clusters in Switzerland and Belgium, creating geographic vulnerability for supply chains serving chronic autoimmune maintenance therapy. United States health systems with 340B pricing advantages capture disproportionate biologic margin through specialty pharmacy integration. Regulatory divergence across major markets shapes launch sequencing and evidence generation requirements for novel mechanism sponsors.
United States
FDA accelerated approval pathways for rare disease biologics compress development timelines for novel FcRn inhibitors targeting refractory patient populations. The IRA's Medicare price negotiation provisions create uncertainty for orphan drug pricing authority in maintenance therapy segments. Hospital systems in Boston and San Francisco anchor clinical trial enrollment through NIH-funded neuromuscular center networks.
Germany
G-BA health technology assessment requirements for FcRn inhibitor positioning against established B-cell depletion protocols constrain pricing flexibility for novel entrants. REACH compliance governs biologic manufacturing standards for contract development organizations in the Rhine-Ruhr cluster. Heidelberg and Munich academic medical centers concentrate prescribing authority for disease-modifying immunologic interventions.
Japan
PMDA Sakigake designation for rare disease biologics attracts development investment targeting the Asia-Pacific's second-largest pharmaceutical market. METI industrial policy supports domestic bioprocess engineering capacity for monoclonal antibody production. Tokyo and Osaka metropolitan areas host the majority of certified neuromuscular clinics managing generalized myasthenia gravis maintenance therapy.
Switzerland
Swissmedic regulatory frameworks align with EMA standards while offering streamlined assessment for orphan indications. Contract manufacturing organizations in Basel and Zurich control critical fill-finish capacity for temperature-sensitive monoclonal antibodies. The country's biologics-grade manufacturing infrastructure serves as primary supply source for European FcRn inhibitor commercialization.
United Kingdom
NICE value assessment divergence from continental HTA bodies creates European launch sequencing complexity for novel mechanism sponsors. MHRA post-Brexit regulatory autonomy enables accelerated access pathways for innovative immunologic interventions. London and Manchester academic medical centers retain clinical trial access networks for refractory patient populations.
Myasthenia Gravis Market Competitive Environment
Concentration sits with complement inhibition specialists and FcRn blocker developers who have secured accelerated regulatory designations. The market structure reflects tiered competition between integrated biopharmaceutical conglomerates and focused rare disease biotechnology firms. Three archetypes dominate: legacy complement pathway leaders, subcutaneous formulation innovators, and plasma-derived immunoglobulin incumbents. Capacity expansion in biologics manufacturing and strategic partnerships for distribution infrastructure represent the dominant competitive moves.
Among FcRn blocker developers, argenx anchors European commercialization through its subcutaneous portfolio, while UCB competes via differentiated dosing regimens that reduce hospital dependency. Alexion Pharmaceuticals exemplifies the complement inhibition archetype with sustained positioning in refractory patient segments. These three entities represent distinct strategic vectors in the migration from corticosteroid protocols toward targeted immunologic intervention.
| Leading Market Players |
|---|
| Alexion Pharmaceuticals |
| Novartis |
| argenx |
| UCB |
| Pfizer |
| AbbVie |
| F. Hoffmann-La Roche |
| Grifols |
| Johnson & Johnson |
| Others |
Value Chain & Pricing Dynamics
Subcutaneous FcRn inhibitor substitution for intravenous biologics is redrawing supply geography toward decentralized distribution while compressing pricing premiums previously captured through hospital-based infusion center markups. This shift simultaneously fragments manufacturing concentration in Swiss and Belgian fill-finish facilities and intensifies payer scrutiny of site-of-care differentials.
Pricing Analysis
FDA orphan drug designation dictates the pricing tier structure across the Myasthenia Gravis Market, stratifying value capture between first-line corticosteroid protocols and disease-modifying biologics with accelerated approval pathways. Price differentiation hinges on manufacturing complexity certification and administration setting, with hospital outpatient departments commanding premium reimbursement against home infusion alternatives. Cost compression in maintenance therapy tiers is intensifying as pharmacy benefit managers consolidate formulary control over chronic autoimmune indications. Community neurology practices exhibit highest price sensitivity due to prior authorization burden, while academic medical centers with 340B pricing advantages demonstrate lowest sensitivity.
Supply Chain Analysis
Single-source fill-finish capacity in Switzerland and Belgium underwrites critical monoclonal antibody supply for European and United States markets, creating structural vulnerability to temperature excursion events during cross-border distribution. Raw material dependencies center on Chinese-sourced recombinant protein media, German-engineered bioreactor components, and plasma-derived immunoglobulin feedstock from Grifols and CSL Behring collection networks. Tariff exposure on cell culture media imports threatens margin stability for contract manufacturing organizations serving orphan biologic production. Distribution runs through temperature-controlled specialty pharmacy channels with redundant cold chain monitoring infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among United States pharmacy benefit managers and European health technology assessment bodies, consolidating price-setting authority that previously fragmented across hospital procurement committees and individual prescriber discretion.
For Market Incumbents: Shield biologic margin position by securing backward integration into fill-finish capacity in the Swiss Rhine corridor, insulating against single-source contract manufacturing organization vulnerability while accelerating subcutaneous formulation development to preempt site-of-care reimbursement compression. Prioritize FDA breakthrough therapy designation maintenance to sustain orphan pricing authority against emerging FcRn inhibitor competition. For New Entrants and Emerging Players: EMA PRIME eligibility fast-tracks market access for novel mechanism agents targeting refractory generalized myasthenia gravis populations underserved by established complement inhibition protocols. White-space opportunity concentrates in Japan's PMDA Sakigake pathway for rare disease biologics and home infusion channel development for maintenance dosing regimens. Go-to-market positioning should emphasize real-world evidence generation partnerships with academic medical center electronic health record data lakes. For Investors and Strategic Acquirers: The market sits at a paradigm-shift phase that favors subcutaneous formulation specialists with differentiated delivery technology and established payer contracting infrastructure. Long-term viability over the next decade hinges on chronic autoimmune maintenance therapy positioning rather than acute crisis intervention. Acquisition target archetype: mid-cap biotechnology firms with FcRn inhibitor pipelines and European commercialization capabilities. Signal to watch: Medicare price negotiation provisions implementation for orphan drug categories.| Strategic Initiative | Industry Significance |
|---|---|
| Subcutaneous Formulation Development | Reduces hospital dependency and expands pharmacy benefit management channel capture for argenx and UCB portfolios. |
| EMA PRIME Pathway Pursuit | Accelerates protocol assistance and market access for novel FcRn inhibitors targeting refractory patient populations. |
| Fill-Finish Capacity Expansion | Addresses single-source vulnerability in Swiss and Belgian contract manufacturing organization networks. |
| Real-World Evidence Partnerships | Satisfies FDA accelerated approval confirmatory study requirements through electronic health record data integration. |
| Japan PMDA Sakigake Engagement | Unlocks early approval pathways for rare disease biologics in Asia-Pacific's second-largest pharmaceutical market. |
Study Parameters
The analysis maps FcRn inhibitor development pipelines, complement pathway therapeutics, and corticosteroid-sparing protocols, each validated through regulatory affairs specialists, hospital formulary directors, and neuromuscular clinic administrators. Primary interviews with payer access strategists and contract manufacturing organization executives combined with secondary validation against FDA orphan drug designations, EMA PRIME eligibility records, ClinicalTrials.gov enrollment data, and hospital 340B pricing disclosures. Bottom-up patient flow modeling and top-down biologics revenue triangulation anchored volume estimates across the analysis window.
Consistency checks validated outputs against external benchmarks including CMS Medicare Part B spending data, European hospital procurement database trends, and Japanese Ministry of Health reimbursement filings. Segmentation dimensions encompassed treatment line positioning, administration route, patient severity classification, and regional regulatory cluster. CAGRs derived from epidemiological prevalence projections cross-referenced with biologic penetration assumptions and pricing trajectory modeling. Forecast inputs incorporated serological diagnostic expansion rates and subcutaneous formulation adoption curves.
Decision-makers should treat outputs as directional under stable regulatory pathway assumptions and sustained orphan drug pricing authority; material deviation in Medicare negotiation scope or EMA HTA convergence would warrant model refresh. Practitioners should keep alternative scenarios live as payer evidence requirements for FcRn inhibitor positioning against B-cell depletion protocols evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Malignant Pleural Effusion Market
Specialty Medicine
Paronychia Treatment Market
Specialty Medicine
Liver Fibrosis Treatment Market
Specialty Medicine
Radiation-Induced Fibrosis Treatment Market
Specialty Medicine
Combined Immune Deficiency (CID) Market
Specialty Medicine
Idiopathic Short Stature Market
Specialty Medicine
Ankylosing Spondylitis Treatment Market
Specialty Medicine
Complement 3 Glomerulopathy (C3G) Market
Specialty Medicine
Small Molecule Targeted Cancer Therapy Market
Specialty Medicine
Microcephaly Market
Specialty Medicine
Skin Cancer Therapeutics Market
Specialty Medicine
Global Acute Agitation and Aggression Treatment Market
Specialty Medicine
Polycystic Kidney Disease Treatment Market
Specialty Medicine
Systemic Lupus Erythematosus (SLE) Market
Specialty Medicine
Ragweed Pollen Allergy Treatment Market
Specialty Medicine
Stuttering Therapeutics Market