
 Cholinesterase Inhibitors Market | 2026-2036
Cholinesterase Inhibitors Market Size, Share, and Industry Trends Forecast 2026-2036
Cholinesterase Inhibitors Market Analysis
Japanese pharmaceutical manufacturing is pivoting toward higher-purity cholinesterase inhibitor production to serve export markets. Eisai Co., Ltd. leverages its deep R&D heritage in neurology to sustain competitive positioning across multiple therapy areas. Pfizer Inc. anchors North American distribution through established hospital and long-term care channels. Novartis AG differentiates via formulation science capabilities that extend product lifecycles beyond patent expiry.
Cholinesterase inhibitors are reversible or irreversible compounds that block acetylcholinesterase or butyrylcholinesterase enzymes, thereby prolonging acetylcholine activity at synaptic junctions with typical dosing in the milligram range for therapeutic effect. These agents serve primarily to manage cognitive decline in neurodegenerative conditions where cholinergic transmission is compromised. Donepezil formulations occupy the largest revenue pool due to once-daily oral convenience and extensive generic availability, while transdermal delivery of rivastigmine represents the fastest-growing segment as caregivers seek adherence-friendly alternatives for homecare patients. Alzheimer's Disease therapy area dominates prescription volumes, though myasthenia gravis applications command premium pricing due to smaller patient populations and specialized clinical monitoring requirements.
FDA reviews govern new drug approvals and label expansions in the United States, while EMA centralized procedures shape market access across European Union member states and the European Economic Area. The EU AI Act and GDPR increasingly influence digital biomarker integration into clinical trial designs for cholinesterase inhibitor development programs. Stakeholders must monitor how pharmacovigilance requirements for generic formulations evolve as regulators tighten post-market surveillance expectations across multiple jurisdictions.
Market Dynamics
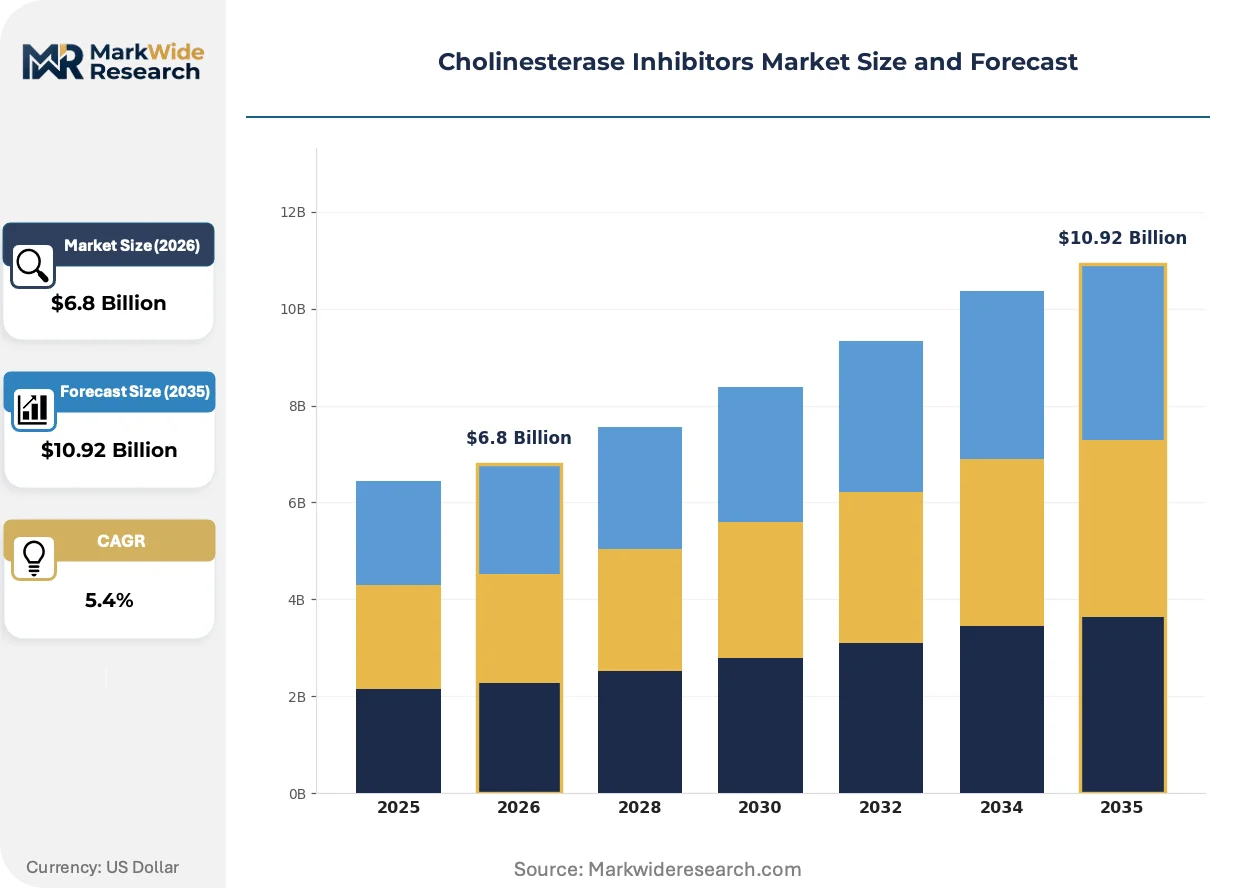
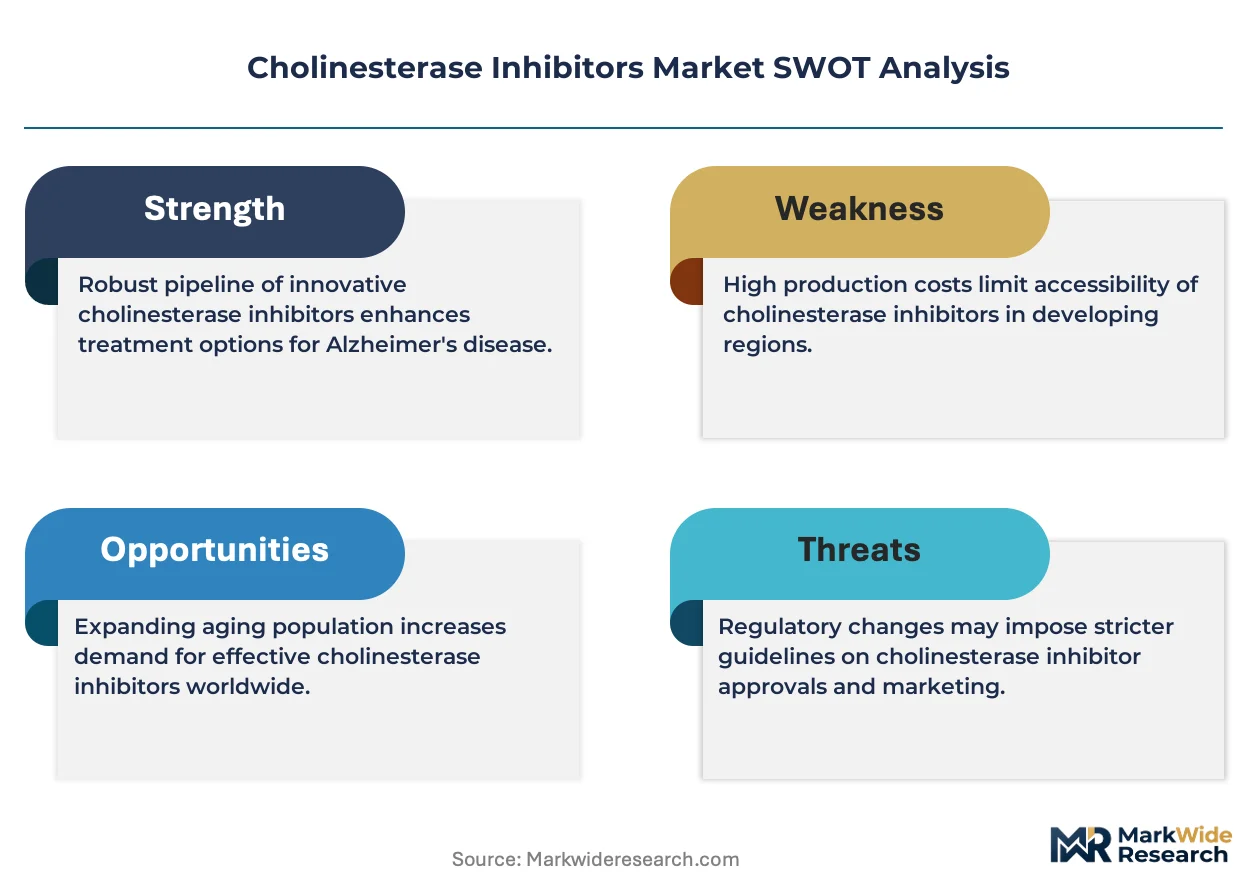
The cholinesterase inhibitor market faces mounting pressure from caregiver preference shifts toward adherence-friendly administration routes, forcing reformulation investments across oral, transdermal, and depot delivery platforms.
Growth Catalysts
- EMA centralized procedure harmonization:Streamlined market access across EU member states accelerates product launches for novel formulations, reducing regulatory duplication costs.
- Transdermal delivery technology:Rivastigmine patches reduce caregiver burden in homecare settings, expanding addressable patient populations beyond hospital-centric prescribing.
- Japan's super-aged demographic trajectory:Prescription volumes for cognitive therapeutics expand as the 75-plus population cohort drives sustained demand for maintenance therapy.
Market Restraints
- Active pharmaceutical ingredient concentration:High-purity cholinesterase inhibitor manufacturing clusters in limited Japanese and Swiss facilities, creating supply vulnerability.
- Generic substitution mechanics:Extensive donepezil generic availability compresses branded pricing power and limits R&D recovery windows.
- Clinical trial endpoint rigidity:FDA cognitive assessment requirements for Alzheimer's Disease indications demand lengthy, expensive trials with high failure rates.
Strategic Opportunities
- Digital biomarker integration:EU AI Act-compliant sensor technologies enable remote cognitive monitoring, opening decentralized trial designs and real-world evidence generation.
- Myasthenia gravis orphan positioning:Smaller patient populations permit premium pricing and specialized clinical support services with limited generic threat.
- Germany's long-term care insurance expansion:Reimbursement pathways for home-based cognitive therapy broaden addressable market beyond acute hospital settings.
Industry Challenges
- Pharmacovigilance workforce scarcity:Post-market surveillance requirements for generic cholinesterase inhibitors outstrip qualified safety data analysts across multiple jurisdictions.
- Legacy formulation facility retrofit costs:Transdermal patch manufacturing demands specialized coating and lamination equipment incompatible with standard oral solid dose lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cholinesterase Inhibitors Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.92 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Donepezil, Rivastigmine, Galantamine, Tacrine Therapy Area: Alzheimer's Disease, Parkinson's Disease, Myasthenia Gravis, Dementia End User: Hospitals, Long-term Care Facilities, Homecare, Clinics Delivery Mode: Oral, Injection, Transdermal, Intravenous |
| Companies Covered | Eisai Co., Ltd., Pfizer Inc., Novartis AG, F. Hoffmann-La Roche Ltd., Teva Pharmaceutical Industries Ltd., Eli Lilly and Company, Allergan Plc., Merck & Co., Inc., Daiichi Sankyo Company, Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cholinesterase Inhibitors Market Emerging Trajectories
Reformulation science is redirecting competitive investment toward patient-centric delivery systems that bypass gastrointestinal metabolism and reduce dosing frequency burdens.
Transdermal patch technology is decentralizing administration authority from clinical settings to family caregivers, enabling home-based therapy management for Alzheimer's Disease patients. Geriatric care facilities in Germany and Japan are adopting patch-based rivastigmine as standard protocol, reducing nursing time per patient. This shift is compressing hospital pharmacy dispensing volumes while expanding retail and mail-order channel importance.
FDA's emphasis on patient-reported outcome measures in neurodegenerative drug development is forcing endpoint innovation in cholinesterase inhibitor trials. Sponsors must now incorporate caregiver burden scales and quality-of-life metrics alongside traditional cognitive batteries. Early-phase programs targeting mild cognitive impairment are most affected, with protocol amendments adding months to study timelines.
Specialty pharmacy networks are capturing cholinesterase inhibitor distribution from traditional hospital outpatient channels, particularly for high-cost combination therapies. Payer consolidation in the United States drives this channel migration through exclusive formulary arrangements and prior authorization centralization. Medicare Part D plans increasingly mandate mail-order fulfillment for maintenance cognitive prescriptions, displacing community pharmacy relationships established over decades.
Cholinesterase Inhibitors Market Segmentation
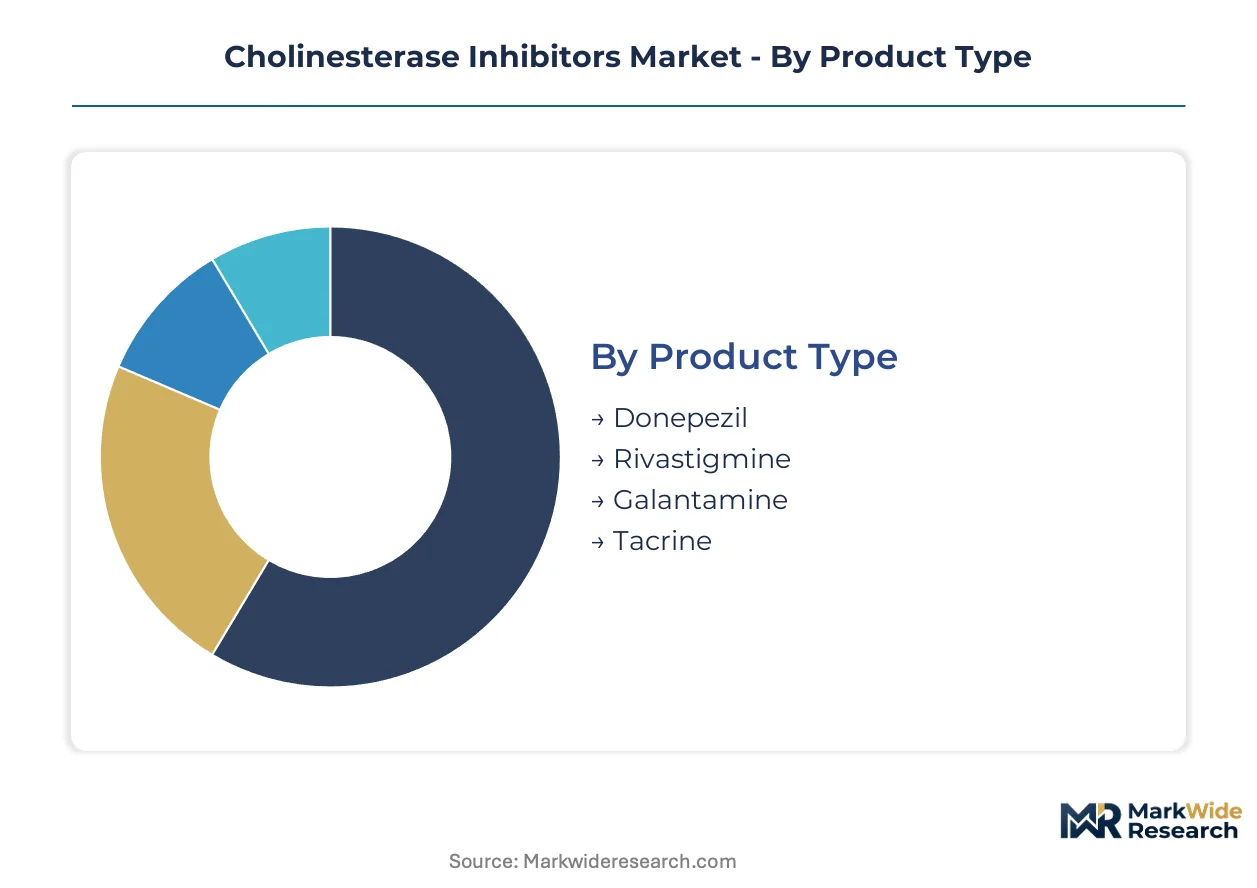
Cholinesterase inhibitor commercialization demands precise segment alignment between formulation technology, clinical setting, and reimbursement pathway. Manufacturers configure supply chains differently for hospital-centric injectables versus homecare-oriented transdermal systems.
Product Type:
Reversible acetylcholinesterase inhibition potency varies across molecular structures, shaping prescriber preferences for daily versus multi-daily dosing regimens.
- Donepezil:Piperidine-derived compound with 70-hour plasma half-life enables once-daily oral administration. United States Medicare Part D plans favor this agent for maintenance therapy in long-term care settings due to generic cost positioning and established efficacy documentation.
- Rivastigmine:Carbamate structure permits dual cholinesterase inhibition with shorter half-life requiring twice-daily oral or continuous transdermal delivery. Germany's long-term care insurance expansion drives patch formulation demand as caregivers seek adherence solutions for home-based Alzheimer's Disease management.
- Galantamine:Tertiary alkaloid with nicotinic receptor modulating properties extracted from Amaryllidaceae species. Prescription volumes concentrate in Japan where PMDA-approved formulations serve mild-to-moderate cognitive impairment protocols.
- Tacrine:First-generation aminoacridine with hepatotoxicity liability limiting contemporary utilization. Specialized compounding pharmacies in Switzerland maintain limited supply for myasthenia gravis patients with contraindications to newer agents.
Mature deployment sits with donepezil oral tablets. Newer deployment is concentrated in rivastigmine transdermal patches.
Therapy Area:
Regulatory indication breadth determines pricing power and clinical trial investment requirements across neurological conditions.
- Alzheimer's Disease:Progressive neurodegeneration with cholinergic deficit as primary pharmacological target. FDA cognitive assessment requirements mandate lengthy trials, compressing development timelines for novel formulations seeking label expansion into mild cognitive impairment stages.
- Parkinson's Disease:Dementia as late-stage complication creates secondary cholinesterase inhibitor application. EMA centralized procedures govern European market access for combination therapies addressing both motor and cognitive symptoms.
- Myasthenia Gravis:Autoimmune neuromuscular junction disorder with orphan disease designation permitting premium pricing. Smaller patient populations enable specialized clinical support services with limited generic substitution threat.
- Dementia:Broad syndrome classification encompassing vascular and Lewy body subtypes beyond Alzheimer's pathology. Prescription patterns in Japan's super-aged demographic cohorts extend maintenance therapy duration beyond Western markets.
Volume concentration aligns with Alzheimer's Disease. Value concentration is shifting toward myasthenia gravis orphan indications.
End User:
Care setting determines administration authority, monitoring intensity, and channel economics for cholinesterase inhibitor distribution.
- Hospitals:Acute care institutions manage diagnostic workup and initial titration under specialist supervision. United States hospital outpatient departments retain high-cost combination therapy dispensing despite specialty pharmacy network encroachment.
- Long-term Care Facilities:Nursing homes and assisted living centers administer maintenance therapy with structured medication management protocols. German geriatric care facilities adopt patch-based rivastigmine as standard to reduce nursing time per patient.
- Homecare:Family-directed administration with caregiver burden as critical adherence determinant. Transdermal delivery technology enables this shift by bypassing gastrointestinal metabolism and reducing dosing frequency.
- Clinics:Outpatient neurology and geriatric practices manage stable patients with periodic cognitive assessment. Japan's community-based care integration programs expand clinic-based prescribing for early-stage intervention.
Institutional dispensing dominates injectable formulations. Home-based administration is expanding fastest for transdermal and oral maintenance therapies.
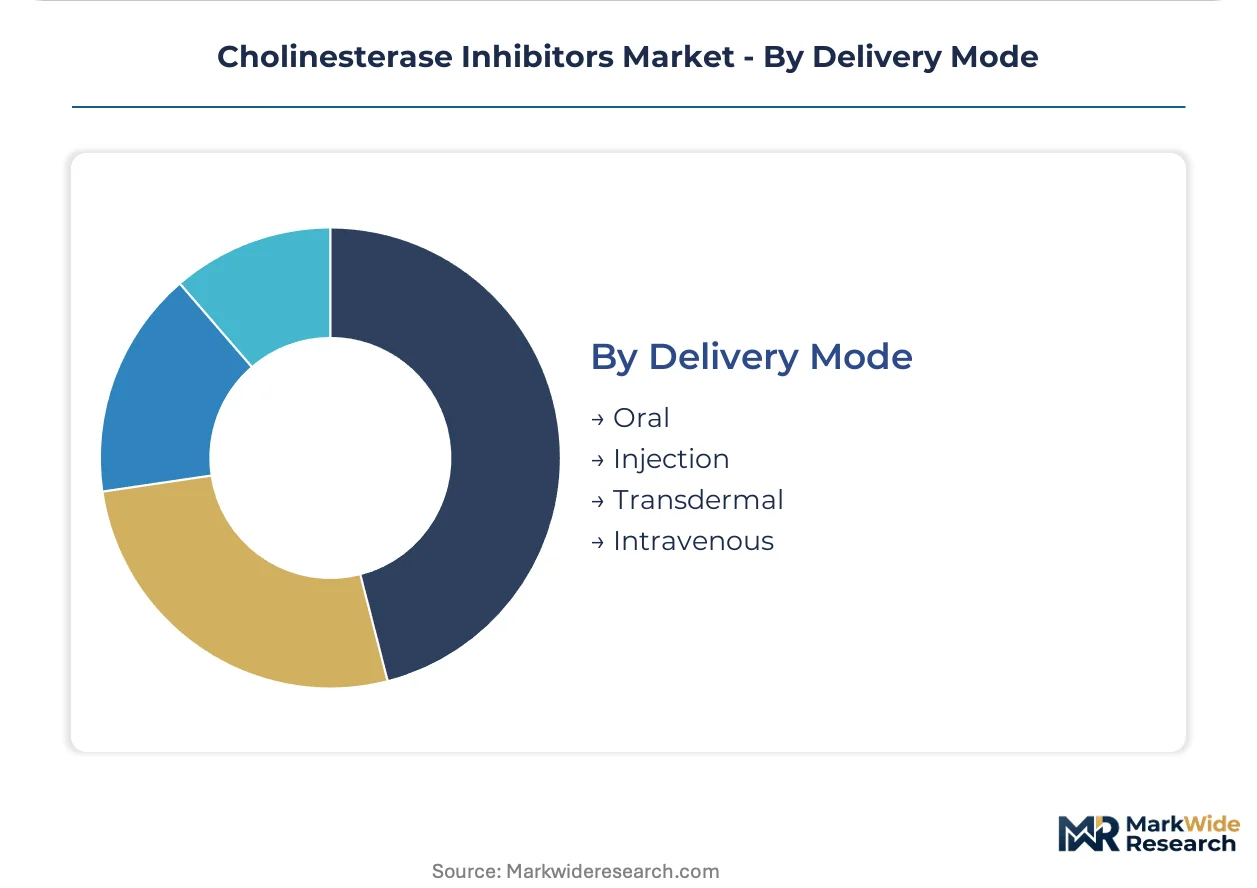
Delivery Mode:
Route of administration dictates manufacturing complexity, bioavailability characteristics, and patient compliance profiles.
- Oral:Immediate-release and extended-release tablet formulations dominate prescription volumes with established bioequivalence pathways for generic substitution. Donepezil oral convenience sustains largest revenue pool despite pricing compression.
- Transdermal:Adhesive patch systems provide continuous drug delivery with reduced caregiver burden. Manufacturing demands specialized coating and lamination equipment incompatible with standard oral solid dose production lines.
- Injection:Intramuscular and subcutaneous routes serve acute exacerbation management and patients with swallowing difficulties. Hospital pharmacy dispensing volumes concentrate this channel despite home healthcare nursing expansion.
- Intravenous:Parenteral administration reserved for perioperative myasthenia gravis crisis management in intensive care settings. Swiss and Japanese facilities maintain concentrated manufacturing capabilities for high-purity API requirements.
Oral tablets command volume leadership. Transdermal patches are climbing the fastest as caregiver preference shifts toward adherence-friendly alternatives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
High-purity active pharmaceutical ingredient manufacturing concentrates in Swiss and Japanese facilities, creating geographic dependencies that shape regional market development and supply security calculations across therapeutic distribution networks.
United States
Medicare Part D plans drive prescription volumes for maintenance cognitive therapy in long-term care settings. FDA cognitive assessment requirements for Alzheimer's Disease indications extend clinical trial timelines and inflate development costs. Boston and San Francisco biotech clusters host decentralized trial platforms integrating digital biomarker technologies.
Germany
Long-term care insurance expansion broadens reimbursement for home-based cognitive therapy beyond acute hospital settings. EMA centralized procedures govern market access for novel formulations across EU member states. Bavarian geriatric care facilities adopt transdermal patch protocols to reduce per-patient nursing time.
Japan
Super-aged demographic trajectory sustains prescription volume expansion for cholinesterase inhibitors among 75-plus population cohorts. PMDA-approved galantamine formulations serve mild-to-moderate cognitive impairment protocols. Tokyo-Osaka pharmaceutical corridor pivots toward higher-purity production for export market supply.
Switzerland
Specialized compounding pharmacies maintain limited tacrine supply for myasthenia gravis patients with contraindications to newer agents. Swissmedic oversees pharmacovigilance requirements for high-purity API manufacturing. Basel-Zurich pharmaceutical cluster retains concentrated capabilities for parenteral formulation production.
United Kingdom
NHS England commissioning frameworks shape prescribing patterns for cost-effective generic donepezil versus branded alternatives. MHRA post-Brexit regulatory autonomy influences divergence from EMA centralized procedures. London-Southeast research triangle hosts patient-reported outcome measure development for neurodegenerative trials.
Cholinesterase Inhibitors Market Vendor Landscape
Global majors compete with regional champions across formulation technology and distribution channel depth. Market structure tilts toward consolidated leadership in oral solid dose manufacturing alongside fragmented specialty capabilities in transdermal and parenteral delivery systems. Three archetypes dominate: diversified pharmaceutical conglomerates with neurology franchises, mid-cap specialists in CNS therapeutics, and generic manufacturers exploiting bioequivalence pathways. Competitive moves concentrate on strategic partnerships for digital biomarker integration and geographic licensing arrangements to bypass direct manufacturing investment.
Within the diversified pharmaceutical tier, Eisai Co., Ltd. and Pfizer Inc. exemplify contrasting geographic anchoring strategies, with the former representing Japanese R&D heritage in neurology and the latter occupying North American distribution infrastructure. Novartis AG sits within the formulation science specialist archetype, its position reflecting lifecycle management capabilities that extend product relevance beyond patent expiry. These three entities collectively illustrate how competitive advantage derives from regulatory relationship depth, channel control, or technological differentiation rather than scale alone.
| Leading Market Players |
|---|
| Eisai Co., Ltd. |
| Pfizer Inc. |
| Novartis AG |
| F. Hoffmann-La Roche Ltd. |
| Teva Pharmaceutical Industries Ltd. |
| Eli Lilly and Company |
| Allergan Plc. |
| Merck & Co., Inc. |
| Daiichi Sankyo Company, Limited |
| Others |
Supply Flow & Price Mechanics
Hospital outpatient departments and Medicare Part D plans anchor procurement volumes for cholinesterase inhibitors, locking in a contract-based pricing structure where formulary placement determines market access more than spot-market dynamics. This buyer concentration forces manufacturers to absorb service-bundling costs for adherence monitoring and caregiver support programs.
Pricing Analysis
Warranty and service-bundling arrangements separate branded formulations from commodity generics, with donepezil oral tablets commanding premium positioning through FDA-approved cognitive assessment protocols and caregiver training modules. Price differentiation rests on formulation complexity and regulatory certification tier, with transdermal patches extracting higher margins due to specialized manufacturing requirements. Pricing pressure intensifies from generic substitution mechanics in oral solid doses, compressing branded recovery windows. Long-term care facilities exhibit highest price sensitivity due to per-patient reimbursement caps, while myasthenia gravis specialists tolerate premium positioning for orphan-designated therapies.
Supply Chain Analysis
Direct-to-hospital channels handle acute care demand for injectable formulations, while specialty pharmacy networks capture maintenance therapy distribution for transdermal and oral products. High-purity active pharmaceutical ingredient production concentrates in Japan and Switzerland, with Swiss facilities maintaining parenteral-grade capabilities and Japanese manufacturers pivoting toward export-quality output. Raw material dependencies include carbamate intermediates for rivastigmine, piperidine derivatives for donepezil, and Amaryllidaceae alkaloid extracts for galantamine. Single-source vulnerability in high-purity API manufacturing creates supply risk, as limited facilities meet FDA and EMA pharmacovigilance standards for neurodegenerative therapeutics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Generic substitution mechanics and caregiver preference shifts toward adherence-friendly delivery systems are forcing consolidation among formulation-dependent players lacking transdermal or parenteral capabilities.
For Market Incumbents: Lock in transdermal manufacturing capacity through facility retrofit or strategic partnership before caregiver protocol standardization solidifies around patch-based rivastigmine. Secure backward integration into high-purity API supply through Japanese or Swiss facility investment to defend against single-source vulnerability. EMA centralized procedure harmonization offers regulatory leverage for lifecycle extension beyond patent expiry. For New Entrants and Emerging Players: Begin with digital biomarker integration services for decentralized trial designs, exploiting EU AI Act compliance requirements that incumbent sponsors struggle to meet. Target myasthenia gravis orphan indications where smaller patient populations permit premium pricing and limited generic threat. Go-to-market positioning should emphasize specialized clinical support services rather than commodity formulation competition. For Investors and Strategic Acquirers: The window for entry favors mid-cap CNS specialists with existing neurology franchises and regulatory relationship depth across FDA and EMA pathways. Long-term viability hinges on formulation science capabilities that extend product relevance through delivery system innovation. Watch for PMDA approval timelines for mild cognitive impairment label expansions as inflection indicator for Japanese market trajectory.| Strategic Initiative | Industry Significance |
|---|---|
| Transdermal Manufacturing Scale-Up | Specialized coating and lamination equipment enables caregiver-friendly adherence solutions for homecare expansion. |
| Digital Biomarker Integration | EU AI Act-compliant sensor technologies open decentralized trial designs and real-world evidence generation pathways. |
| Orphan Indication Development | Myasthenia gravis positioning permits premium pricing with limited generic substitution threat. |
| High-Purity API Backward Integration | Captive supply from Japanese or Swiss facilities reduces single-source vulnerability for parenteral formulations. |
| Specialty Pharmacy Network Partnership | Exclusive formulary arrangements with Medicare Part D plans displace traditional hospital outpatient dispensing. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers. FDA filings, EMA submissions, ClinicalTrials.gov protocols, and CMS Medicare Part D claims databases provided validation layers. Bottom-up prescription volume modeling and top-down therapeutic category sizing were reconciled through iterative triangulation.
Data-stream reconciliation across patient population estimates, pricing benchmarks, and channel economics informed the analytical framework across the projection horizon. Segmentation dimensions included therapy area, formulation technology, delivery mode, end-user setting, and regional regulatory cluster. CAGRs were derived from patient volume trajectories, generic penetration curves, and reimbursement pathway evolution. Forecast inputs incorporated Japan's super-aged demographic projections and Germany's long-term care insurance expansion mechanics.
Underlying measurement precision varies by segment; Alzheimer's Disease prescription volumes carry tighter precision than myasthenia gravis orphan populations due to claims data availability. Forecasts reflect assumptions regarding regulatory approval timelines, generic entry sequencing, and caregiver protocol adoption rates. Periodic stress-testing of base assumptions is recommended given pharmacovigilance requirement evolution and potential API manufacturing disruption.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Urticaria Drugs Market
Pharmaceuticals
Fucosidosis Therapeutics Market
Pharmaceuticals
Global Compounding Pharmacy Market
Pharmaceuticals
Cerumenolytic Agents Market
Pharmaceuticals
Myocardial Infarction Drugs Market
Pharmaceuticals
Acetaminophen Injection Market
Pharmaceuticals
Chronic Obstructive Pulmonary Disease Drugs Market
Pharmaceuticals
North America Analgesics Market
Pharmaceuticals
Europe FMD Vaccine Market
Pharmaceuticals
Antidiarrhoeal Market
Pharmaceuticals
Global Liver Diseases Therapeutics Market
Pharmaceuticals
Europe Novel Drug Delivery System (NDDS) Market
Pharmaceuticals
Global Nizatidine Market
Pharmaceuticals
Anticonvulsants Market
Pharmaceuticals
Europe Meglitinide Market
Pharmaceuticals
Global Atosiban Market