
 Post-Operative Nausea and Vomiting (PONV) Market | 2026-2036
Post-Operative Nausea and Vomiting (PONV) Market Size, Share, and Industry Trends Forecast 2026-2036
Post-Operative Nausea and Vomiting (PONV) Market Analytics
North American pharmaceutical manufacturing capacity for perioperative therapies is rewriting competitive dynamics across the PONV landscape. Merck and Co., Inc. anchors its position through deep R&D investment in NK1 receptor antagonists. Heron Therapeutics, Inc. differentiates via extended-release formulations that reduce rescue medication needs. Acacia Pharma specializes in intravenous prophylaxis delivered at induction, capturing high-compliance surgical workflows.
Post-operative nausea and vomiting constitutes a multifactorial physiological response triggered by anesthetic agents, opioid analgesics, and surgical manipulation of the gastrointestinal tract, typically graded on a four-point severity scale and prophylactically managed through multimodal anti-emetic regimens targeting serotonergic, neurokinin, and dopaminergic pathways. The primary clinical purpose centers on reducing aspiration risk, preventing wound dehiscence, shortening post-anesthesia care unit stays, and improving patient-reported recovery metrics. 5-HT3 antagonists dominate current prescribing patterns due to established efficacy profiles and broad formulary inclusion, while NK1 antagonists represent the fastest-expanding margin pool as payers recognize their superior control in high-risk surgical populations. Intravenous administration retains the largest volume share, though transdermal delivery is gaining traction in ambulatory settings where vascular access discontinuation drives protocol efficiency.
FDA guidelines on perioperative drug safety, EMA's MDR requirements for combination therapies, and the EU Green Deal's pharmaceutical manufacturing sustainability mandates collectively elevate compliance costs while accelerating substitution toward greener synthesis routes. These frameworks compel manufacturers to validate supply chain transparency and environmental impact metrics alongside clinical endpoints. Stakeholders must monitor evolving payer evidence requirements for multimodal prophylaxis bundles versus standalone agent reimbursement.
Market Dynamics
The FDA's enhanced perioperative drug safety guidance is compressing development timelines while forcing manufacturers to validate multimodal prophylaxis protocols against standalone agent benchmarks. This regulatory pressure is reshaping how anti-emetic therapies gain formulary inclusion and reimbursement authorization across hospital systems.
Growth Catalysts
- Outpatient Surgical Volume Expansion:Ambulatory surgical centers in the United States are mandating PONV prophylaxis for all moderate-to-high risk cases, creating standardized demand for intravenous anti-emetics at induction.
- REACH Compliance Incentives:European manufacturers adopting greener synthesis routes for 5-HT3 antagonists qualify for accelerated EMA review pathways, rewarding environmental investment with faster market access.
- Multimodal Protocol Adoption:Anesthesiology societies are embedding NK1 receptor antagonists into perioperative care bundles, expanding addressable patient populations beyond traditional serotonin-targeting regimens.
Market Restraints
- Active Pharmaceutical Ingredient Concentration:Synthesis of aprepitant and fosaprepitant relies on a limited supplier base concentrated in China and India, exposing manufacturers to geopolitical supply interruptions.
- Reimbursement Compression:CMS bundled payment models for surgical episodes cap anti-emetic spend per procedure, constraining uptake of premium-priced extended-release formulations.
- Generic Erosion of 5-HT3 Antagonists:Ondansetron patent expiry has commoditized first-line prophylaxis, collapsing margins for originator products and redirecting R&D investment toward NK1 mechanisms.
Strategic Opportunities
- Transdermal Delivery White Space:Patch-based scopolamine formulations for PONV remain underdeveloped relative to intravenous alternatives, offering first-mover advantage in ambulatory settings where vascular access discontinuation is prioritized.
- EU Green Deal Manufacturing Subsidies:Pharmaceutical producers investing in solvent-free synthesis or continuous flow chemistry for anti-emetics qualify for EU Innovation Fund support, offsetting capital costs of facility retooling.
- Pediatric Indication Expansion:Current PONV prophylaxis labels predominantly cover adult populations, leaving significant unmet need in pediatric surgical protocols where weight-based dosing complexity has delayed entry.
Industry Challenges
- Biostatistical Talent Scarcity:Designing non-inferiority trials for multimodal anti-emetic bundles requires specialized expertise in adaptive trial design that sits outside traditional CRO capabilities.
- Legacy EHR Integration Friction:Embedding PONV risk scoring algorithms into hospital information systems demands custom API development, prolonging sales cycles and implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Post-Operative Nausea and Vomiting (PONV) Market |
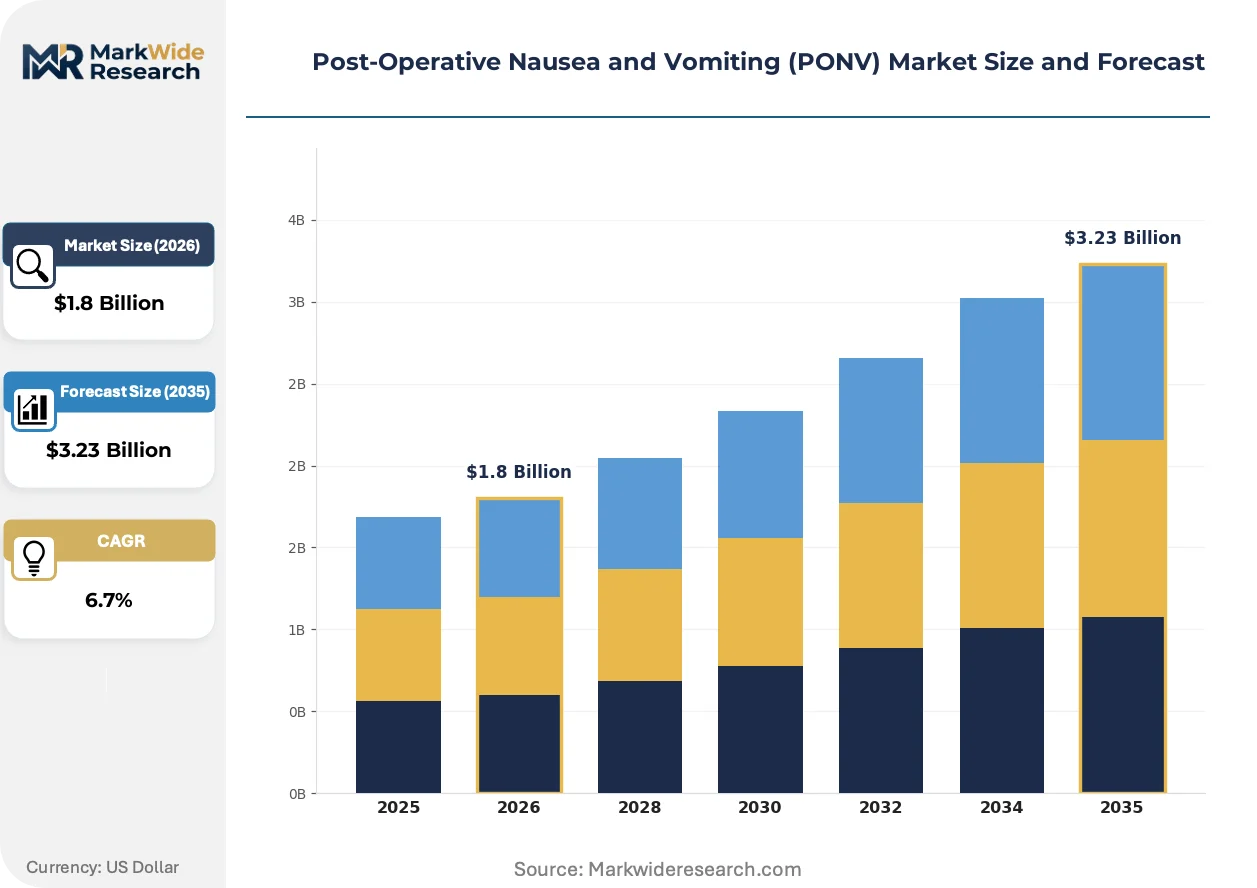
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Drug Type: 5-HT3 Antagonists, NK1 Antagonists, Corticosteroids, Antihistamines Administration Route: Oral, Intravenous, Transdermal, Sublingual End User: Hospitals, Ambulatory Surgical Centers, Home Care, Clinics Therapeutic Category: Anti-emetics, Analgesics, Sedatives, Neuromodulators |
| Companies Covered | Acacia Pharma, Novartis AG, F. Hoffmann-La Roche AG, Merck and Co., Inc., GlaxoSmithKline plc, Eisai Corporation, Heron Therapeutics, Inc., Sanofi S.A., Teva Pharmaceutical Industries Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Post-Operative Nausea and Vomiting (PONV) Market Evolving Landscape
Perioperative anti-emetic development is converging on patient-specific risk stratification tools and delivery mechanisms that extend prophylactic coverage without prolonging recovery unit stays. These innovations are compressing the gap between induction and discharge protocols.
Extended-release injectable formulations combining 5-HT3 and NK1 receptor antagonism are hybridizing prophylaxis delivery. Academic medical centers in the United States are piloting these combination depot injections for high-risk bariatric and gynecologic procedures. This hybridization is collapsing the distinction between intraoperative prophylaxis and post-discharge rescue medication markets.
EMA's Medical Device Regulation is reclassifying drug-device combination products for transdermal PONV prophylaxis, requiring clinical evidence packages that exceed historical pharmaceutical-only submissions. Manufacturers with existing patch delivery platforms face retrospective conformity assessments. German and French notified bodies are processing these applications with eighteen-month backlogs, delaying EU market entry for novel transdermal scopolamine products.
Hospital purchasing consortiums are consolidating anti-emetic procurement through sole-source contracts tied to perioperative bundle compliance. Integrated delivery networks in the United States are replacing decentralized pharmacy purchasing with system-wide formulary mandates. This concentration is most visible in the southeastern United States, where hospital consolidation has reduced viable supplier slots from six to two dominant vendors per therapeutic class.
Post-Operative Nausea and Vomiting (PONV) Market Segmentation
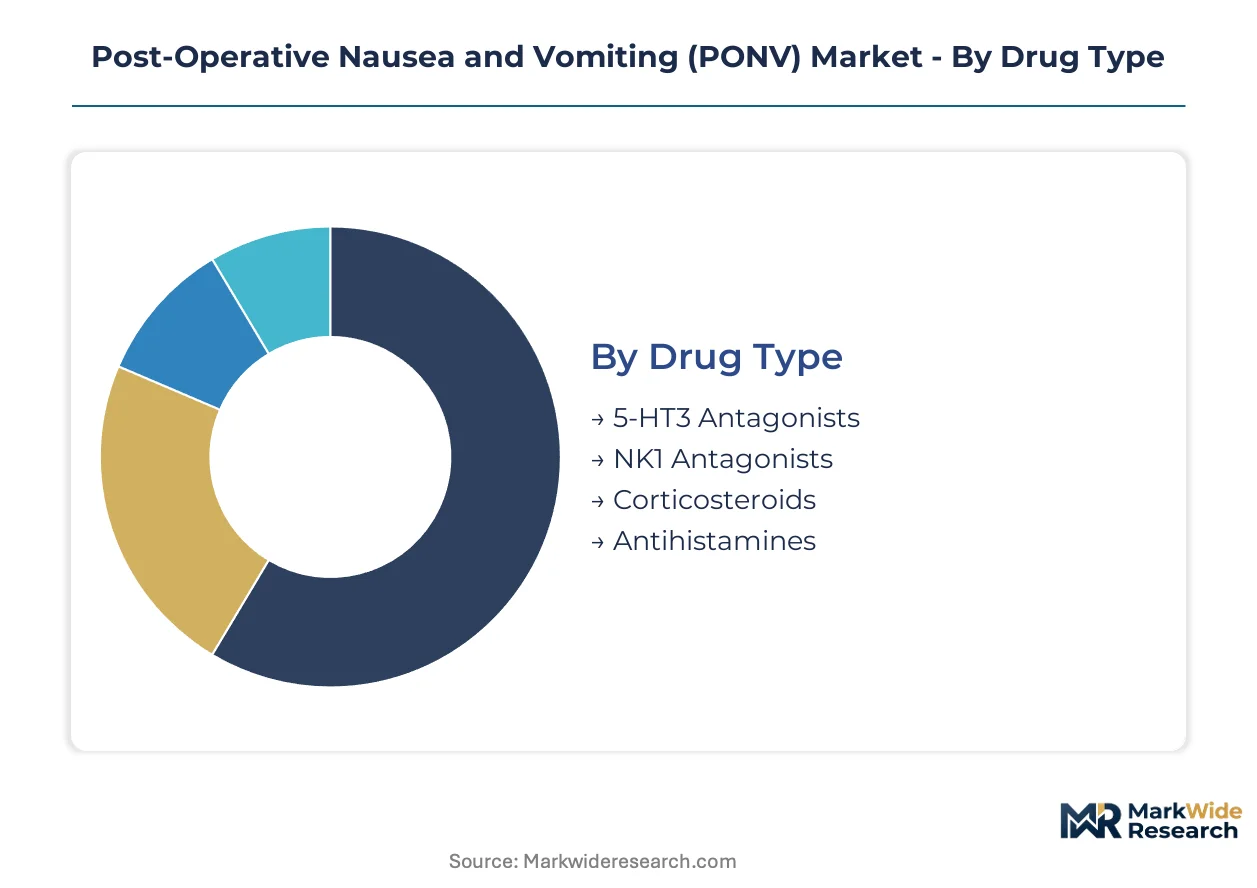
PONV market segmentation reveals distinct velocity profiles across therapeutic modalities and delivery channels. Cycle-time variation between intravenous induction protocols and extended-release formulations directly shapes inventory positioning and contract negotiation strategies for hospital procurement teams.
Drug Type:
Turnover velocity diverges sharply across mechanism classes, with serotonin antagonists cycling through formulary reviews annually while neurokinin-targeting therapies command multi-year commitment structures due to bundled pricing complexity.
- 5-HT3 Antagonists:Ondansetron, granisetron, and palonosetron block serotonin receptor activation in the chemoreceptor trigger zone and gastrointestinal tract. United States hospital systems concentrate demand here due to decades of outcome data and aggressive generic pricing that fits CMS bundled payment ceilings.
- NK1 Antagonists:Aprepitant and fosaprepitant disrupt substance-P mediated emetic signaling through central nervous system receptor blockade. Academic medical centers in Germany and France drive adoption for high-risk surgical populations where serotonin monotherapy fails, though API supply concentration in Asian manufacturing clusters creates procurement vulnerability.
- Corticosteroids:Dexamethasone provides cost-effective prophylaxis through anti-inflammatory and central anti-emetic mechanisms, dominating resource-constrained settings.
- Antihistamines:Dimenhydrinate and meclizine serve rescue scenarios and pediatric applications where first-line agents prove insufficient.
5-HT3 antagonists anchor the volume base while NK1 antagonists gain share at the steepest rate.
Administration Route:
Cost tier stratification separates capital-intensive infusion infrastructure from disposable patch economics, with reimbursement differentials driving site-of-care migration.
- Intravenous:Direct vascular delivery at anesthesia induction ensures rapid onset and predictable bioavailability. United States ambulatory surgical centers mandate IV prophylaxis for moderate-to-high risk cases, creating standardized demand clusters in Texas, Florida, and California outpatient facilities.
- Oral:Preoperative tablet administration suits elective procedures with extended fasting protocols, though absorption variability limits reliability in emergency contexts.
- Transdermal:Scopolamine patches offer continuous prophylaxis without vascular access maintenance, expanding most quickly in same-day discharge protocols where line removal accelerates throughput.
- Sublingual:Rapid mucosal absorption bypasses first-pass metabolism for breakthrough emesis rescue, occupying niche positioning in post-discharge settings.
Intravenous delivery commands the revenue concentration while transdermal formats climb the fastest as ambulatory volumes displace inpatient procedures.
End User:
Customer-type fragmentation creates divergent purchasing modalities, from centralized hospital system tenders to individual clinic stock-and-bill arrangements.
- Hospitals:Integrated delivery networks negotiate sole-source contracts spanning multiple therapeutic classes, consolidating supplier relationships.
- Ambulatory Surgical Centers:Freestanding facilities prioritize rapid-turnover formulations that minimize recovery unit stays and support same-day discharge metrics.
- Home Care:Post-acute settings demand patient-administered rescue medications with simplified dosing regimens.
- Clinics:Office-based surgical practices concentrate in ophthalmology and dermatology segments with lower baseline PONV risk profiles.
Hospitals retain the procurement volume leadership while ambulatory surgical centers expand their share most aggressively.
Therapeutic Category:
Application focus separates pure anti-emetic positioning from multimodal bundles that address nausea, pain, and anxiety through single-agent or combination protocols.
- Anti-emetics:Dedicated prophylaxis and rescue agents dominate formulary spend across all surgical settings.
- Analgesics:Opioid-sparing multimodal regimens incorporate anti-emetic properties to reduce PONV incidence while managing postoperative pain.
- Sedatives:Preoperative anxiolysis with secondary anti-emetic effects supports patient comfort and reduces anesthesia-related nausea.
- Neuromodulators:Emerging agents targeting gut-brain axis signaling represent developmental-stage positioning with unproven commercial trajectory.
Anti-emetics maintain the installed base concentration while analgesic-anti-emetic combinations advance most rapidly in enhanced recovery after surgery protocols.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns for PONV therapies diverge sharply across geographies. United States hospital systems prioritize intravenous prophylaxis at induction, while European markets emphasize extended-release formulations aligned with ambulatory discharge protocols.
United States
Hospital consolidation in the Southeast and Texas has compressed supplier slots from six to two vendors per therapeutic class. FDA's enhanced perioperative drug safety guidance forces manufacturers to validate multimodal protocols against standalone benchmarks. The Greater Boston cluster anchors clinical trial activity for NK1 receptor antagonists in high-risk bariatric populations.
Germany
Academic medical centers in Bavaria and Baden-Württemberg drive adoption of neurokinin-targeting therapies where serotonin monotherapy fails. EMA's Medical Device Regulation reclassifies drug-device combination products, requiring clinical evidence packages that exceed historical pharmaceutical-only submissions. The Rhine-Ruhr industrial corridor concentrates API synthesis facilities for 5-HT3 antagonists.
France
Hospital purchasing consortiums in Île-de-France consolidate anti-emetic procurement through sole-source contracts tied to perioperative bundle compliance. ANSM oversight of combination therapies elevates documentation requirements for multimodal regimens. The Lyon-Grenoble medical technology cluster pilots transdermal scopolamine delivery for same-day discharge protocols.
Japan
PMDA review timelines for extended-release injectable formulations lag FDA approvals by 18-24 months, delaying market entry for hybrid 5-HT3/NK1 depot products. The Kanto region around Tokyo concentrates demand from aging surgical populations with elevated PONV risk profiles. Osaka-based anesthesia societies embed risk stratification algorithms into perioperative care standards.
India
CDSCO accelerated approval pathways for generic ondansetron formulations have commoditized first-line prophylaxis, collapsing originator margins. Maharashtra and Gujarat host concentrated manufacturing of active pharmaceutical ingredients for export to European and North American formulators. Hyderabad's contract research organizations support bioequivalence studies for transdermal delivery platforms.
Post-Operative Nausea and Vomiting (PONV) Market Competitive Landscape
Capability concentration sits with specialized developers of extended-release and combination formulations; scale advantage sits with diversified pharmaceutical conglomerates with established anesthesia portfolios. The market structures around three tiers: originator firms with NK1 receptor patent estates, generic manufacturers exploiting 5-HT3 antagonist commoditization, and drug-device combination specialists. Dominant competitive moves include strategic partnerships for API supply security and portfolio diversification into transdermal delivery platforms.
Among diversified pharmaceutical conglomerates, Novartis AG and Merck and Co., Inc. occupy positions anchored by deep R&D investment in receptor antagonist mechanisms. Heron Therapeutics, Inc. exemplifies the specialized developer archetype, with its corporate structure signaling focus on extended-release formulation science. These three entities represent distinct strategic postures: broad anesthesia portfolio leverage, targeted mechanism-class dominance, and delivery-innovation specialization respectively.
| Leading Market Players |
|---|
| Acacia Pharma |
| Novartis AG |
| F. Hoffmann-La Roche AG |
| Merck and Co., Inc. |
| GlaxoSmithKline plc |
| Eisai Corporation |
| Heron Therapeutics, Inc. |
| Sanofi S.A. |
| Teva Pharmaceutical Industries Ltd. |
| Others |
Value Network & Pricing Analysis
Shanghai-to-Rotterdam container freight corridors impose cost volatility that amplifies price stratification between originator NK1 antagonists and generic 5-HT3 alternatives, while API sourcing concentration in Asian manufacturing clusters forces European formulators to absorb logistics premiums or pivot to regional contract manufacturing partnerships.
Pricing Analysis
Long-term offtake agreements between hospital purchasing consortiums and NK1 antagonist suppliers anchor premium pricing tiers, while spot-market generic ondansetron transactions collapse margins through commoditized per-unit economics. Price differentiation hinges on FDA tier certification and volume scale commitments from integrated delivery networks. Cost compression in the serotonin antagonist segment intensifies because CMS bundled payment ceilings cap reimbursable spend per surgical episode. Ambulatory surgical centers exhibit highest price sensitivity due to throughput-dependent margin structures, whereas academic medical centers prioritize clinical efficacy over acquisition cost.
Supply Chain Analysis
Contract manufacturing concentration for aprepitant and fosaprepitant API rests with facilities in India, China, and select European sites, creating geographic supply concentration that exposes formulators to geopolitical friction. Raw material dependencies include specialized amino acid precursors, palladium catalysts, and high-purity solvents for chiral synthesis. Single-source vulnerability pervades the NK1 antagonist intermediate market, where two suppliers control critical synthesis steps. Distribution runs through pharmaceutical wholesalers serving hospital systems and direct-to-ambulatory-center arrangements for high-volume accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA's enhanced perioperative drug safety guidance accelerates market disruption by elevating evidence requirements for multimodal prophylaxis, compressing development timelines and forcing portfolio restructuring across the competitive landscape.
For Market Incumbents: Harden formulary position through backward integration into API synthesis for NK1 receptor antagonists, eliminating exposure to Asian supply concentration. Expand manufacturing footprint in the Rhine-Ruhr corridor to capture EU Green Deal subsidies while insulating against REACH compliance cost escalation. Prioritize R&D investment in extended-release combination depot formulations that collapse the distinction between prophylaxis and rescue medication markets. For New Entrants and Emerging Players: Transdermal scopolamine delivery for same-day discharge protocols in United States ambulatory surgical centers represents the most penetrable entry point, with EMA backlog delays creating eighteen-month competitive whitespace for first movers. Pediatric PONV prophylaxis indications offer unmet need where weight-based dosing complexity has delayed incumbent entry. Pursue hospital system pilot programs tied to enhanced recovery after surgery bundle compliance as the primary go-to-market angle. For Investors and Strategic Acquirers: Drug-device combination specialists with existing patch delivery platforms and retrospective MDR conformity assessments command premium positioning as transdermal formats gain ambulatory share. Long-term viability over a multi-year horizon favors acquisition targets with validated EU manufacturing capabilities and solvent-free synthesis credentials. Monitor EMA review pathway acceleration for green chemistry adopters as the critical inflection signal for competitive repositioning.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Adaptive trial designs for multimodal prophylaxis bundles satisfy FDA enhanced guidance requirements. |
| Regulatory Approval Pathway | EMA accelerated review for REACH-compliant green synthesis routes rewards environmental capital investment. |
| Manufacturing Scale-Up | Solvent-free continuous flow chemistry expansion captures EU Innovation Fund subsidies. |
| Pipeline Diversification | Pediatric indication development addresses unmet need in weight-based dosing protocols. |
| Strategic Partnership | API supply security agreements with Indian and Chinese manufacturers mitigate geopolitical risk. |
Research Methodology
A spread of perspectives from anesthesiology department chairs, hospital formulary directors, GPO contracts managers, and regulatory affairs specialists converged on the working assumptions underlying this analysis. Primary interviews with these stakeholders combined with secondary validation against FDA filings, EMA submission databases, ClinicalTrials.gov records, and hospital procurement contract repositories. Bottom-up patient-volume modeling and top-down pharmaceutical spend analysis triangulated on segment-level estimates.
Demand-supply-balance framing anchored the analytical framework across the analysis window, with segmentation dimensions spanning drug mechanism class, administration route, end-user facility type, and regional regulatory cluster. CAGRs derived from procedure volume elasticity to anti-emetic adoption rates, adjusted for generic erosion curves and bundled payment penetration. Forecast inputs incorporated ambulatory surgical center expansion trajectories and NK1 antagonist share gain assumptions in high-risk bariatric populations.
Macroeconomic conditions sit as an overlay; deviation in surgical procedure volumes, healthcare reimbursement policy, or API trade flows would shift the trajectory materially. Forecasts reflect documented assumptions about regulatory timeline adherence and supply chain continuity. Quarterly review of EMA backlog clearance rates, CMS bundled payment rulemaking, and Asian API facility inspection outcomes is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Rabies Treatment Market
Medical Treatment
Phototherapy Treatment Market
Medical Treatment
Influenza Treatment Market
Medical Treatment
Asthma Treatment Market
Medical Treatment
Familial Hypercholesterolemia Treatment Market
Medical Treatment
Hypogonadism Treatment Market
Medical Treatment
Cholera Treatment Market
Medical Treatment
Nose Reconstruction Market
Medical Treatment
Hemorrhagic Shock Treatment Market
Medical Treatment
Hemorrhoids Treatment Market
Medical Treatment
Global Leukapheresis Market
Medical Treatment
Neglected Tropical Disease Treatment Market
Medical Treatment
Seropositive Rheumatoid Arthritis Treatment Market
Medical Treatment
Factor XIII Deficiency Treatment Market
Medical Treatment
Middle Ear Infection Treatment Market
Medical Treatment
Secondary Hyperparathyroidism Treatment Market