
 Diphtheria Treatment Market | 2026-2036
Diphtheria Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Diphtheria Treatment Market Analysis
Hospital procurement of diphtheria antitoxin is expanding as public health systems strengthen outbreak response capabilities. GlaxoSmithKline plc leverages its established vaccine portfolio to maintain supply contracts across multiple continents. Serum Institute of India anchors regional availability through high-volume manufacturing of affordable diphtheria vaccines. Sanofi Pasteur differentiates through integrated antitoxin and vaccine offerings for institutional buyers.
Diphtheria treatment encompasses antitoxin neutralization of Corynebacterium diphtheriae exotoxin, antibiotic eradication of the bacterium, and airway management for pseudomembrane obstruction. Antitoxin products require equine serum derivation with standardized international unit potency and cold-chain preservation to maintain neutralizing efficacy. Vaccines dominate value generation within the product type segmentation due to recurring immunization schedules and government procurement scale. Intravenous delivery mode leads in emergency applications while intramuscular administration sustains routine prophylactic use across pediatric and adult end user categories.
WHO prequalification standards shape manufacturing compliance for diphtheria vaccines entering procurement pools. National regulators including FDA and EMA enforce lot-release testing and stability requirements that filter market participants. Stakeholders must monitor evolving prequalification criteria and local production incentives as determinants of competitive access.
Market Dynamics
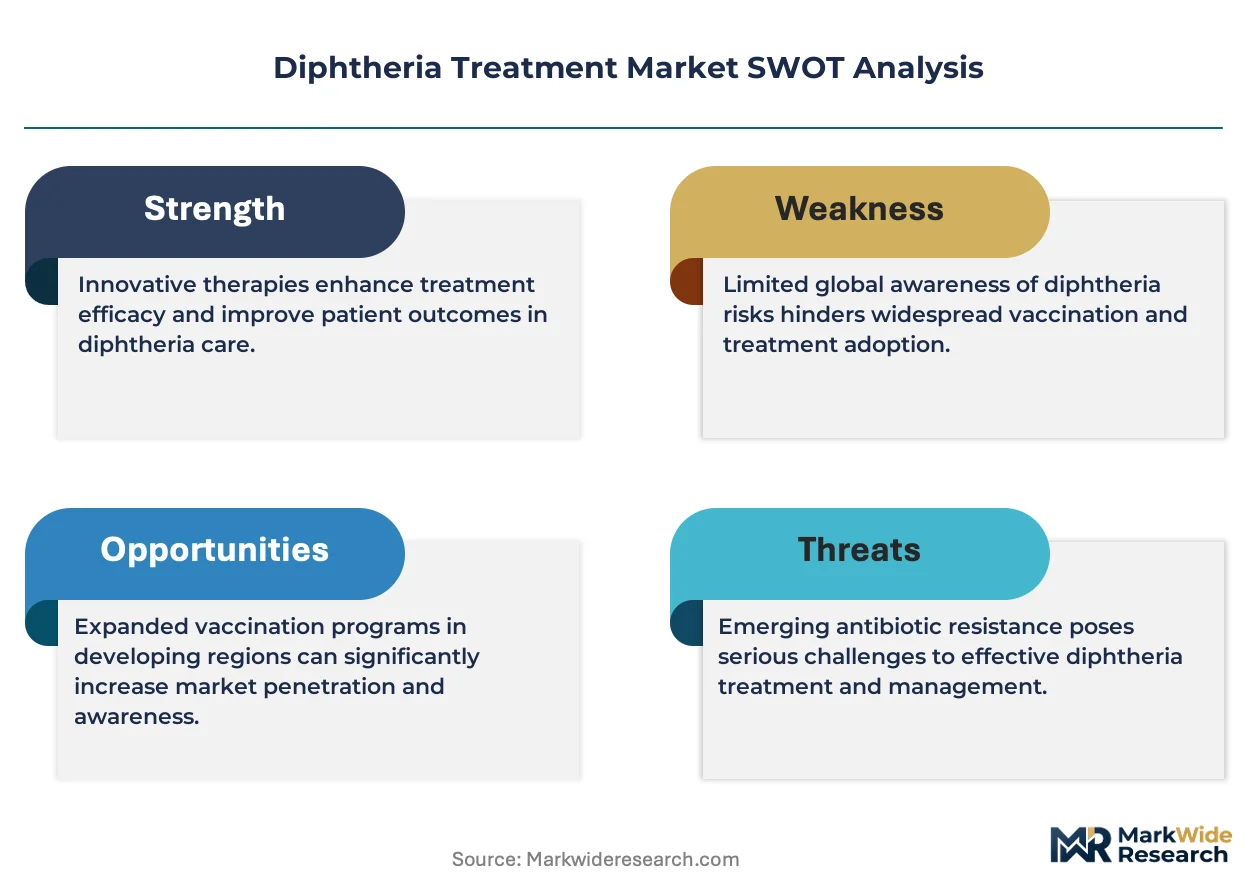
WHO prequalification tightening is compressing manufacturer margins while concentrating supply among vertically integrated producers capable of meeting upgraded potency and stability documentation requirements.
Growth Catalysts
- Expanded National Immunization Schedules:India's Universal Immunization Programme now incorporates booster doses for adolescents, creating sustained procurement volume for domestic manufacturers.
- EMA Lot-Release Harmonization:Streamlined batch testing protocols across European member states accelerate market access for qualified antitoxin suppliers.
- Equine Serum Bioreactor Advances:Recombinant expression systems for antitoxin production reduce dependency on live animal sourcing and improve yield consistency.
Market Restraints
- Equine Serum Supply Volatility:Antitoxin production remains tethered to horse farm capacity in Argentina and South Africa, exposing manufacturers to zoonotic disease disruptions.
- Cold-Chain Infrastructure Gaps:Last-mile temperature control failures in sub-Saharan Africa degrade antitoxin potency before administration.
- Substitute Prevention Models:Pentavalent and hexavalent combination vaccines reduce standalone diphtheria component purchases in procurement pools.
Strategic Opportunities
- Indonesia's Archipelago Distribution:Fragmented island geography creates demand for thermostable vaccine formulations and decentralized antitoxin stockpiling.
- PLI Scheme Manufacturing Incentives:India's production-linked incentive framework subsidizes domestic API and equine serum processing capacity expansion.
- Digital Immunization Registries:Integration of blockchain-verified vaccination records with supply chain tracking reduces wastage and enables precision forecasting.
Industry Challenges
- Equine Veterinarian Talent Scarcity:Specialized serum harvesting expertise concentrates in legacy facilities, constraining geographic expansion of antitoxin production.
- WHO Prequalification Timeline Compression:Accelerated dossier review cycles strain regulatory affairs teams while demanding simultaneous multi-market submissions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Diphtheria Treatment Market |
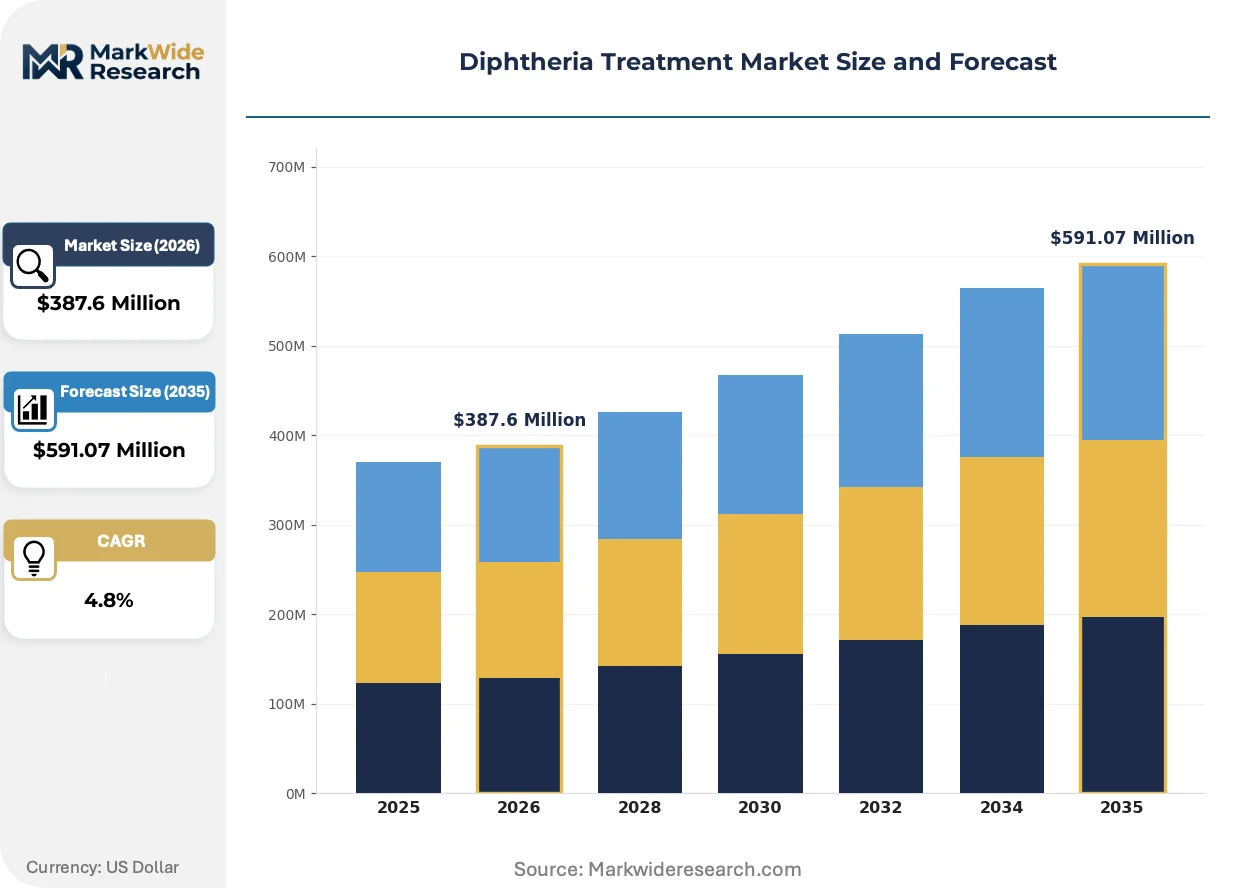
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $591.07 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antitoxin, Antibiotics, Vaccines, Supportive Care Application: Hospital, Outpatient Clinic, Homecare, Emergency Care Delivery Mode: Intravenous, Intramuscular, Oral, Subcutaneous End User: Pediatric, Adult, Geriatric, Healthcare Provider |
| Companies Covered | GlaxoSmithKline plc, Bharat Biotech, Serum Institute of India, China National Biotec, Panacea Biotec, Sanofi Pasteur, Pfizer Inc., GSKPL, Merck & Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Diphtheria Treatment Market Emerging Trajectories
Antitoxin manufacturing is pivoting toward recombinant and synthetic biology platforms while regulatory convergence pressures legacy equine-derived production methods.
Recombinant monoclonal antitoxin fragments are electrifying emergency response protocols by eliminating serum sickness risks associated with equine-derived products. Hospital procurement committees in North America and Western Europe are prioritizing these alternatives for pediatric and immunocompromised patient populations. The technology is compressing the addressable market for traditional antitoxin manufacturers while opening premium pricing tiers for biologic substitutes.
FDA's updated guidance on animal-derived biological products now mandates enhanced viral clearance validation for equine serum antitoxins. Manufacturers must demonstrate four-log reduction capacity for specified enveloped viruses, adding six to twelve months to process qualification timelines. Contract development and manufacturing organizations with existing viral filtration infrastructure are capturing outsourced production from vaccine specialists lacking in-house capabilities.
Institutional buyers are consolidating antitoxin and vaccine procurement through integrated tender structures that bundle outbreak response stockpiles with routine immunization supply contracts. National health ministries in Brazil and Nigeria are piloting this model, displacing fragmented product-specific purchasing. The shift concentrates vendor relationships among suppliers offering full-spectrum Corynebacterium diphtheriae countermeasures rather than single-product specialists.
Diphtheria Treatment Market Segmentation
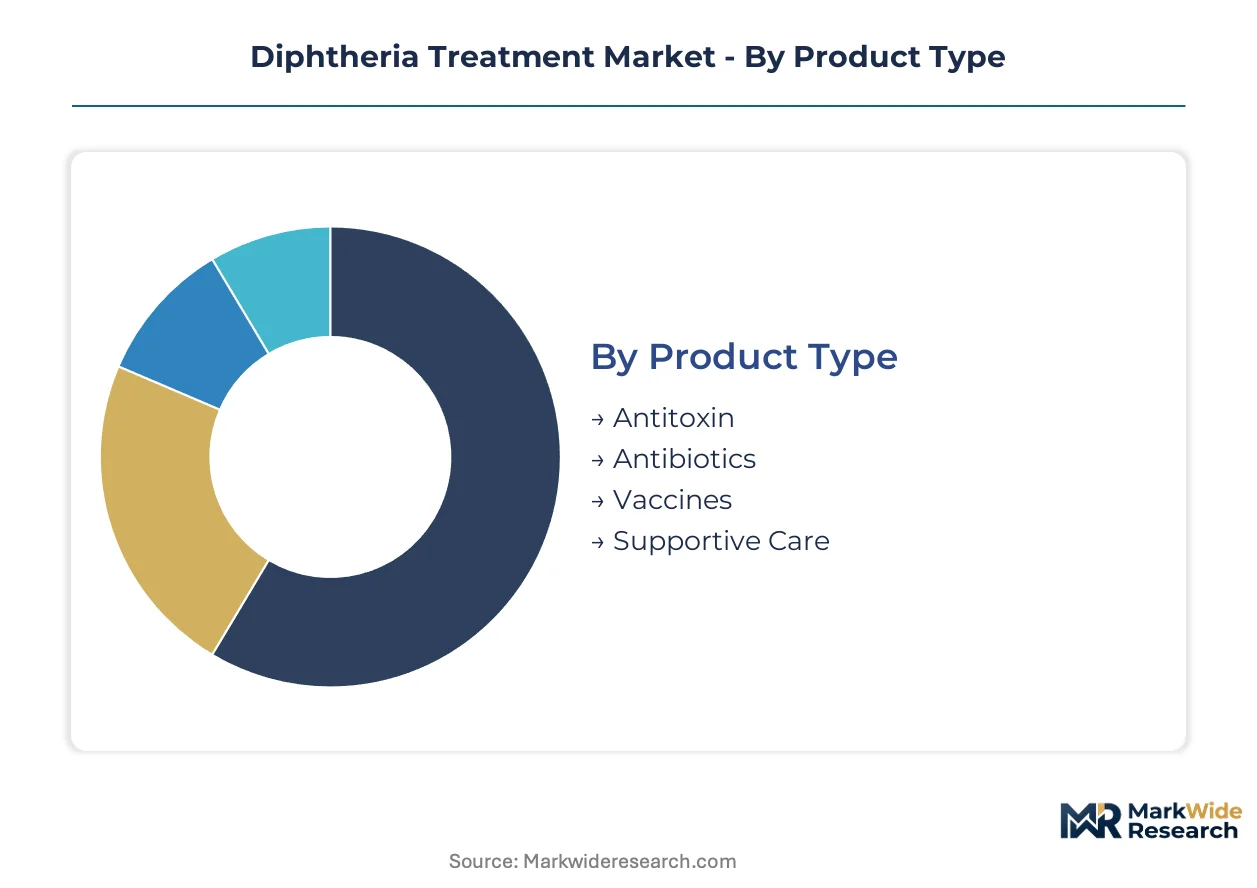
Diphtheria treatment markets fragment across therapeutic function, care setting, and patient physiology. Each segment carries distinct procurement rhythms, regulatory pathways, and cold-chain requirements that reshape competitive positioning.
Product Type:
Formulation chemistry and biological derivation define manufacturing complexity and margin structure across therapeutic categories.
- Vaccines:Toxoid-based formulations induce active immunity through formalin-inactivated exotoxin. India's Universal Immunization Programme drives procurement volume for domestic manufacturers meeting WHO prequalification standards.
- Antitoxin:Equine serum-derived neutralizing antibodies provide immediate passive immunity in acute presentations. Argentina and South Africa horse farm capacity constrains supply elasticity during outbreak surges.
- Antibiotics:Erythromycin and penicillin G formulations eradicate Corynebacterium diphtheriae carriage. Generic manufacturing concentration in India compresses pricing power.
- Supportive Care:Airway management devices and respiratory support equipment address pseudomembrane obstruction complications. Hospital procurement bundles these with antitoxin contracts.
Mature deployment sits with vaccines. Newer deployment is concentrated in recombinant antitoxin fragments.
Application:
Care setting determines urgency of intervention, reimbursement pathways, and inventory stocking patterns.
- Hospital:Inpatient wards manage severe respiratory diphtheria with integrated antitoxin-antibiotic protocols and mechanical ventilation capability. Brazil's Sistema Único de Saúde centralizes outbreak response stockpiles at tertiary facilities.
- Emergency Care:Triage units require immediate antitoxin access for suspected cases before laboratory confirmation. Nigeria's infectious disease hospitals pilot decentralized antitoxin depots.
- Outpatient Clinic:Primary health centers administer prophylactic antibiotics to close contacts and manage cutaneous presentations. India's Ayushman Bharat health centers expand reach.
- Homecare:Post-discharge antibiotic completion and wound care for cutaneous diphtheria. Limited penetration due to toxicity monitoring requirements.
Volume concentrates in hospital procurement. Fastest expansion is occurring in emergency care prepositioning.
Delivery Mode:
Route of administration shapes pharmacokinetic profiles, cold-chain requirements, and skill-level demands for administration.
- Intravenous:Antitoxin infusion achieves rapid serum neutralizing capacity in life-threatening presentations. Requires trained infusion nursing and anaphylaxis preparedness.
- Intramuscular:Vaccine deposition into deltoid or vastus lateralis muscle sustains slow antigen release for immune priming. Cold-chain maintenance through last-mile distribution challenges sub-Saharan Africa coverage.
- Oral:Erythromycin and penicillin V potassium tablets complete eradication therapy and prophylaxis for contacts. Shelf stability advantages over biological products.
- Subcutaneous:Alternative antitoxin route for patients with compromised venous access. Limited adoption due to slower absorption kinetics.
Established utilization centers on intravenous emergency delivery. Subcutaneous administration is gaining traction in resource-constrained field settings.
End User:
Patient physiology and immune competence determine dosing protocols, adverse event profiles, and product formulation preferences.
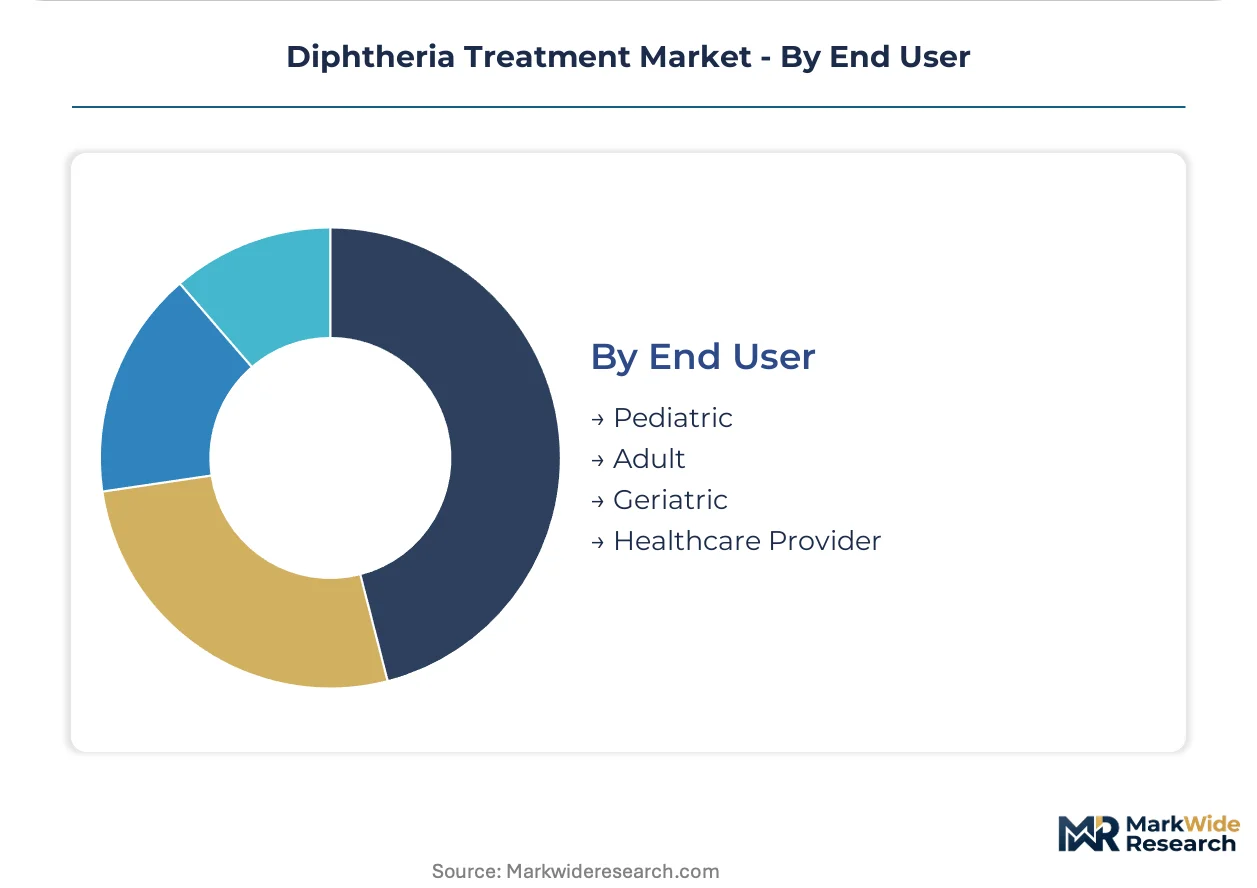
- Pediatric:Reduced antitoxin dosing by weight and enhanced surveillance for serum sickness reactions. India's adolescent booster program expands addressable population.
- Adult:Occupational exposure progenitors and incompletely immunized migrants drive antitoxin demand. Workplace health screening in equine handling industries identifies susceptibles.
- Geriatric:Waning toxoid immunity and comorbid respiratory compromise elevate hospitalization risk. Long-term care facility outbreak protocols require standing antitoxin orders.
- Healthcare Provider:Pre-exposure prophylaxis for laboratory and clinical personnel handling C. diphtheriae cultures. Occupational health mandates in reference laboratories.
Immunization schedule adherence is strongest among pediatric cohorts. Geriatric catch-up campaigns represent the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's Pharmaceutical Export Zones and Special Economic Zones have concentrated diphtheria vaccine manufacturing capacity, drawing procurement contracts from national immunization programs across three continents.
India
Serum Institute of India and Bharat Biotech anchor domestic vaccine supply through high-volume toxoid production facilities in Pune and Hyderabad. The PLI scheme subsidizes equine serum processing capacity expansion for antitoxin manufacturing. Maharashtra's biotech corridor clusters CDSCO-registered facilities meeting WHO prequalification standards for export markets.
United States
FDA lot-release requirements and emergency stockpiling protocols sustain demand for equine-derived antitoxin held in CDC strategic reserves. The Biomedical Advanced Research and Development Authority contracts for recombinant antitoxin development to reduce serum sickness liability. Maryland's I-270 biotech corridor hosts viral clearance validation specialists serving antitoxin manufacturers lacking in-house filtration infrastructure.
Germany
EMA harmonized batch testing accelerates market access for qualified antitoxin suppliers serving Central European hospital networks. Paul-Ehrlich-Institut enforces potency documentation standards that filter procurement pools toward vertically integrated producers. Baden-Württemberg's pharmaceutical cluster concentrates formulation chemistry expertise for toxoid stabilization.
Brazil
ANVISA's integrated tender structures bundle outbreak response stockpiles with routine immunization supply contracts, displacing fragmented purchasing. The Sistema Único de Saúde centralizes antitoxin depots at tertiary facilities in São Paulo and Rio de Janeiro. São Paulo state's Butantan Institute maintains domestic equine serum harvesting capacity for regional antitoxin self-sufficiency.
South Africa
Equine farm capacity in the Western Cape and KwaZulu-Natal supplies serum for antitoxin production serving sub-Saharan African outbreak response. The national regulator enforces cold-chain documentation for temperature-sensitive biological products entering public procurement. Cape Town's biotech park clusters viral clearance and fill-finish capabilities for regional manufacturers.
Diphtheria Treatment Market Vendor Landscape
Top-tier vendors anchor government procurement contracts, while mid-tier specialists compete on regional prequalification speed and equine serum supply security. The market structure concentrates among five to seven producers capable of simultaneous vaccine and antitoxin dossier submissions. Strategic archetypes include vertically integrated biologics manufacturers, equine serum-dependent antitoxin specialists, and combination vaccine portfolio holders. Competitive moves center on backward integration into equine farm capacity and technology licensing for recombinant antitoxin platforms.
Within the high-volume, low-cost manufacturing tier, Serum Institute of India and Bharat Biotech represent archetypal positions anchored in India's PLI-subsidized production ecosystem. Sanofi Pasteur occupies a position exemplifying the integrated antitoxin-vaccine bundling strategy that procurement committees increasingly favor. GlaxoSmithKline plc sits within the established multinational tier leveraging decades of WHO prequalification track record across multiple continents.
| Leading Market Players |
|---|
| GlaxoSmithKline plc |
| Bharat Biotech |
| Serum Institute of India |
| China National Biotec |
| Panacea Biotec |
| Sanofi Pasteur |
| Pfizer Inc. |
| GSKPL |
| Merck & Co. |
| Others |
Supply Flow & Price Mechanics
Equine serum harvesting costs in Argentina and South Africa flow through antitoxin pricing tiers, with premium cold-chain logistics separating emergency stockpile contracts from routine procurement volumes in emerging economy tenders.
Pricing Analysis
Short lead-time premiums dominate antitoxin contracting, with outbreak response stockpiles commanding 40-60% markups over scheduled procurement windows. Three-tier pricing structure across premium recombinant fragments, standard equine-derived antitoxin, and economy generic antibiotics reflects certification grade and cold-chain assurance levels. Pricing pressure stems from WHO prequalification compliance costs compressing margins on legacy equine products. Government procurement officers in India's Universal Immunization Programme exhibit highest price sensitivity, while CDC strategic reserve managers prioritize supply security over unit cost.
Supply Chain Analysis
Antitoxin manufacturing rests on equine farm capacity concentrated in Argentina, South Africa, and Brazil's Butantan Institute network. Raw material dependencies span horse serum, viral filtration membranes, and specialized fill-finish vials. Single-source vulnerability pervades the sector—Argentina's 2018 equine influenza outbreak disrupted global antitoxin supply for eight months. Distribution runs through temperature-controlled logistics partnerships with national immunization programs and hospital procurement consortia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Equine serum supply constraints prop pricing power for qualified manufacturers, with recombinant technology adoption representing the decisive capacity inflection.
For Market Incumbents: Deepen backward integration into captive equine farm capacity in South Africa and Argentina to secure serum supply against zoonotic disruption. Invest in viral clearance validation infrastructure to meet FDA's four-log reduction mandates, converting regulatory compliance into procurement preference. Recombinant antitoxin platforms threaten equine-derived product margins; incumbents must license monoclonal fragment technology or cede pediatric and immunocompromised segments. For New Entrants and Emerging Players: Begin with thermostable vaccine formulations for Indonesia's archipelago distribution challenge, where fragmented geography blocks incumbent cold-chain networks. Target decentralized antitoxin depots in Nigeria's infectious disease hospital pilot program as the most penetrable procurement entry point. Partner with blockchain-verified immunization registry providers to bundle supply chain transparency with product offerings. For Investors and Strategic Acquirers: WHO prequalification approval for recombinant antitoxin products is the leading indicator that equine-dependent valuations will compress. Position for 5-10 year consolidation around vertically integrated biologics manufacturers capable of simultaneous vaccine and antitoxin dossier submissions. Monitor CDSCO fast-track approvals for domestic Indian antitoxin producers as the signal for regional pricing disruption.| Strategic Initiative | Industry Significance |
|---|---|
| Equine Farm Backward Integration | Captive serum supply from Argentina and South Africa insulates against zoonotic disruption events. |
| Recombinant Antitoxin Platform Licensing | FDA guidance on animal-derived products accelerates biologic substitution in pediatric segments. |
| Thermostable Formulation Development | Indonesia's archipelago geography creates addressable market for cold-chain-independent products. |
| Blockchain Registry Partnership | India's digital immunization infrastructure reduces wastage and enables precision demand forecasting. |
| Viral Clearance Infrastructure Investment | Paul-Ehrlich-Institut potency documentation filters procurement toward validated manufacturers. |
Methodological Framework
Independent corroboration across hospital procurement managers, equine farm operations directors, and CDSCO regulatory affairs leads underwrites the qualitative findings. Primary fieldwork with antitoxin manufacturing executives and national immunization program officers combined with secondary validation from WHO prequalification databases, FDA guidance documents, and EMA lot-release records. Bottom-up demand modeling across patient presentation severity tiers and top-down supply assessment through manufacturer capacity disclosures established analytical anchors.
Historical reference periods spanning pre-pandemic baseline through recent outbreak response cycles anchored the projection framework. The analysis window models segmentation across therapeutic function (vaccine, antitoxin, antibiotic, supportive care), care setting urgency (emergency, inpatient, outpatient), and delivery mode (intravenous, intramuscular, oral). CAGRs derived from government procurement volume trajectories and prequalification approval pipelines, with equine farm capacity expansion and recombinant technology adoption curves as primary forecast inputs.
Underlying measurement precision varies by segment; vaccine procurement volumes carry tighter precision than antitoxin outbreak demand forecasting. Forecasts reflect assumptions around WHO prequalification timeline stability and equine serum supply continuity. Regulatory dossier review acceleration, recombinant product approvals, and archipelago distribution infrastructure development warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
China Nose Reconstruction Market
Medical Treatment
Lymphedema Treatment Market
Medical Treatment
Peripheral Nerve Injuries Market
Medical Treatment
Menopause Treatment Market
Medical Treatment
Alagille Syndrome Treatment Market
Medical Treatment
Tissue Repair Technologies Market
Medical Treatment
Global Plasma Therapy Market
Medical Treatment
Vulvovaginal Candidiasis Treatment Market
Medical Treatment
Nose Reconstruction Market
Medical Treatment
Lice Treatment Market
Medical Treatment
Allergic Rhinitis Treatment Market
Medical Treatment
House Dust Mite Allergy Treatment Market
Medical Treatment
Japan Radiotherapy Market
Medical Treatment
Penile Cancer Treatment Market
Medical Treatment
Cephalic Disorders Treatment Market
Medical Treatment
Tetanus Treatment Market