
 Disseminated Intravascular Coagulation (DIC) Treatment Market | 2026-2036
Disseminated Intravascular Coagulation (DIC) Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Disseminated Intravascular Coagulation (DIC) Treatment Market Outlook
Critical care applications are recalibrating the demand profile for DIC therapeutics as sepsis and trauma protocols expand in tertiary hospitals. Pfizer Inc. leverages its anticoagulant manufacturing scale to sustain supply security across North American hospital networks. Bayer AG anchors its position through R&D intensity in hemostasis research, while Novartis AG competes via specialized blood product portfolios in European clinical settings.
Disseminated Intravascular Coagulation treatment encompasses pharmacological and blood-based interventions designed to restore coagulation homeostasis through anticoagulant administration, plasma replacement, and platelet support, with therapeutic efficacy measured by fibrinogen recovery rates and bleeding time reduction. Blood products occupy the largest margin pool due to plasma fractionation complexity and cold-chain logistics barriers, while anticoagulants represent the fastest-expanding category as direct oral anticoagulant protocols penetrate emergency care workflows. Intravenous delivery dominates clinical practice owing to rapid onset requirements in acute hemorrhagic presentations, though subcutaneous formulations are gaining traction in step-down units seeking reduced nursing burden.
The FDA enforces stringent hemostatic agent approval pathways that elevate clinical trial costs and extend time-to-market for novel coagulation modulators, while the EMA's MDR framework imposes post-market surveillance obligations on blood product manufacturers that reshape quality management investments. WHO guidelines on blood safety standards further constrain sourcing flexibility for plasma-derived therapies, compelling manufacturers to diversify collection networks across multiple jurisdictions. Stakeholders must monitor evolving pharmacovigilance requirements and plasma supply security as regulatory stringency intensifies alongside patient volume expansion.
Market Dynamics
The FDA's evolving guidance on hemostatic agent approvals is compressing development timelines while elevating clinical evidence requirements, forcing manufacturers to restructure trial designs and plasma sourcing strategies before product submission.
Growth Catalysts
- Sepsis protocol expansion:Tertiary hospitals in the United States are embedding DIC management into standardized sepsis bundles, creating protocol-driven demand for coagulation therapies.
- EMA MDR framework:Post-market surveillance obligations on blood product manufacturers are accelerating quality investments that improve product reliability and clinical confidence.
- Point-of-care testing integration:Rapid fibrinogen assays are enabling faster therapeutic decision-making in emergency departments, shortening time-to-treatment windows.
Market Restraints
- Plasma supply concentration:Dependence on United States-based collection networks exposes manufacturers to geographic sourcing disruptions and donor pool volatility.
- Cold-chain logistics cost:Temperature-controlled distribution requirements for blood products impose infrastructure investments that limit regional market entry.
- Substitution pressure from direct oral anticoagulants:DOAC protocols in trauma settings are displacing traditional heparin-based DIC interventions in specific patient populations.
Strategic Opportunities
- Subcutaneous formulation development:Step-down unit adoption of non-intravenous delivery routes is opening revenue streams beyond acute care settings.
- Indian tertiary hospital expansion:CDSCO regulatory pathways for plasma-derived therapies are attracting manufacturers to establish local fractionation partnerships.
- Dual anticoagulant-hemostat platforms:Convergence of thrombin modulation with platelet enhancement technologies is creating next-generation product categories.
Industry Challenges
- Specialized hematology expertise scarcity:Coagulation laboratory staffing gaps in community hospitals delay protocol implementation and product utilization.
- ISO 13485 certification complexity:Blood product manufacturers face extended audit timelines when integrating new hemostatic agents into existing quality management systems.
- Legacy electronic health record integration:DIC scoring algorithm deployment requires costly interoperability upgrades across hospital IT infrastructures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Disseminated Intravascular Coagulation (DIC) Treatment Market |
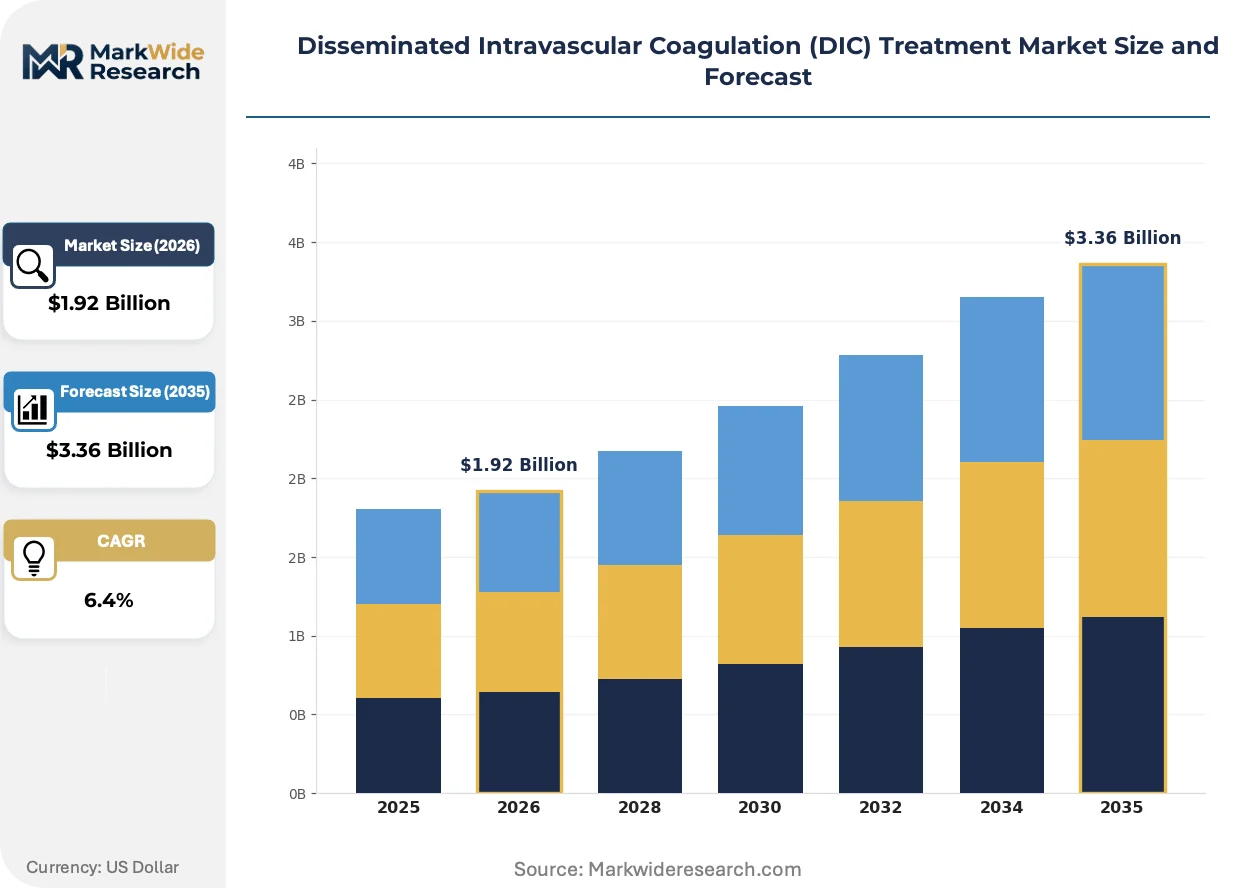
| Market Size in 2026 | $1.92 Billion |
| Market Size in 2035 | $3.36 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Anticoagulants, Blood Products, Antifibrinolytics, Platelet Aggregation Inhibitors Application: Emergency Care, Surgical Procedures, Critical Care, Standard Recovery End User: Hospitals, Clinics, Blood Banks, Rehabilitation Centers Delivery Mode: Intravenous, Subcutaneous, Oral, Topical |
| Companies Covered | Pfizer Inc., Bayer AG, Novartis AG, Sanofi S.A., Johnson & Johnson, F. Hoffmann-La Roche Ltd., Siemens Healthineers, Abbott Laboratories, Sysmex Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Disseminated Intravascular Coagulation (DIC) Treatment Market Strategic Shifts
Targeted coagulation therapies are fragmenting the traditional blood product dependency model as precision medicine approaches penetrate emergency care workflows and reshape therapeutic hierarchies.
Cartridge-based viscoelastic testing is decentralizing coagulation monitoring from centralized laboratories to bedside decision-making. Critical care units in academic medical centers are deploying these devices at scale to enable real-time transfusion guidance. This technology is decentralizing diagnostic authority and compressing the window between hemorrhage onset and therapeutic intervention.
REACH registration requirements for hemostatic raw materials are elevating documentation burdens on European plasma fractionators. Manufacturers must now trace protein sourcing through multi-tier supplier networks to demonstrate compliance. Blood product portfolios face reformulation pressures as ECHA substance evaluations tighten purity thresholds for imported plasma derivatives.
Hospital purchasing consortiums are consolidating anticoagulant procurement decisions under centralized pharmacy committees, displacing individual physician preference protocols. Group purchasing organizations are extracting volume-based pricing concessions that compress manufacturer margins. This concentration is most visible in United States integrated delivery networks where formulary standardization spans dozens of affiliated facilities.
Disseminated Intravascular Coagulation (DIC) Treatment Market Segmentation
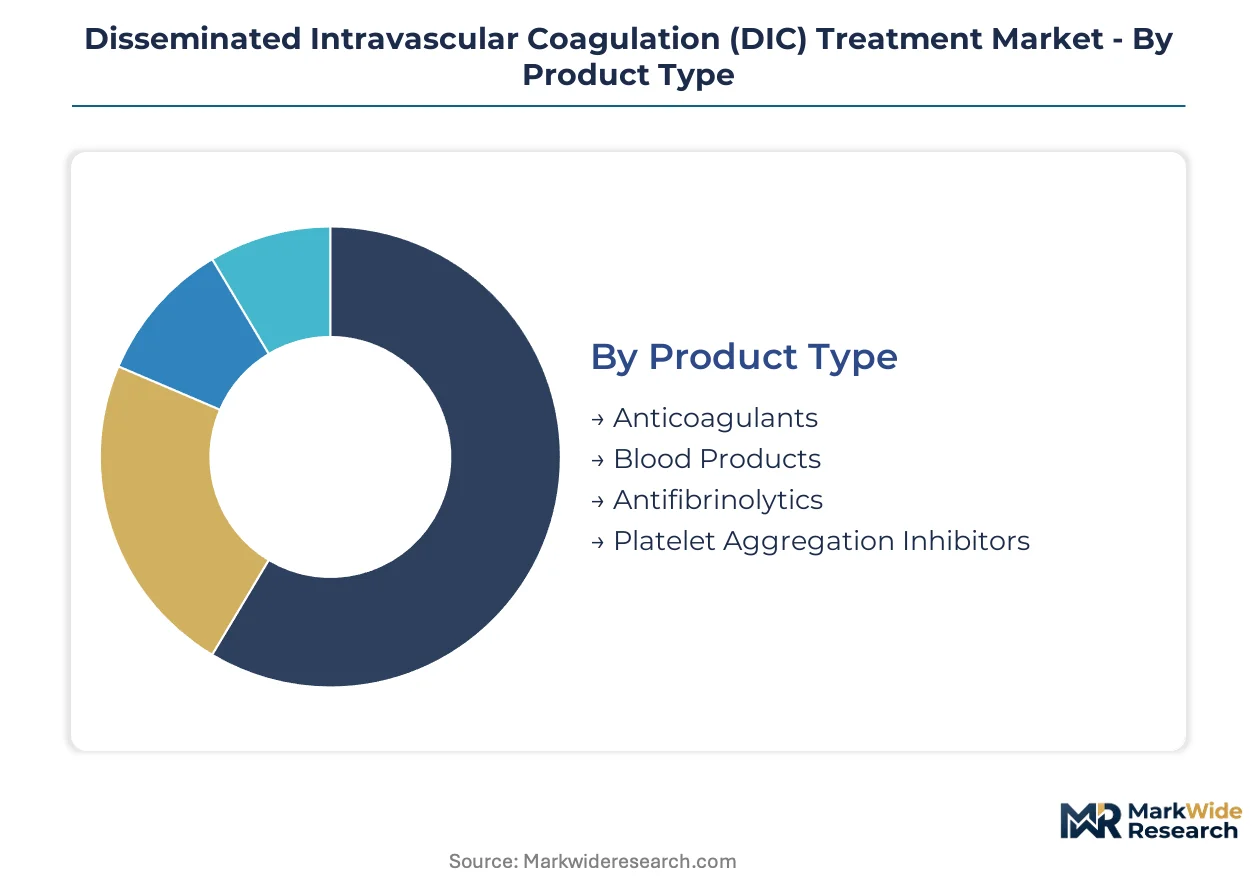
Therapeutic modality and care setting fragmentation creates distinct competitive arenas within DIC management. Product chemistry, urgency of intervention, and institutional capability requirements determine pricing power and sourcing relationships across segments.
Product Type:
Plasma fractionation complexity and synthesis pathways differentiate manufacturing economics across therapeutic categories.
- Blood Products:Plasma-derived concentrates including cryoprecipitate and fresh frozen plasma require cold-chain infrastructure and multi-step fractionation. Tertiary hospitals in the United States absorb the highest volumes due to sepsis protocol standardization and trauma center designation requirements.
- Anticoagulants:Heparin derivatives and direct thrombin inhibitors enable rapid coagulation modulation through enzymatic pathway interruption. Emergency departments in academic medical centers are expanding utilization as point-of-care testing accelerates therapeutic decision velocity.
- Antifibrinolytics:Tranexamic acid and epsilon-aminocaproic acid formulations stabilize fibrin clots through plasmin inhibition. Surgical suites deploy these agents in hemorrhage control protocols.
- Platelet Aggregation Inhibitors:Glycoprotein IIb/IIIa antagonists and P2Y12 inhibitors prevent microthrombus propagation in consumptive coagulopathy. Cardiac catheterization laboratories represent concentrated demand nodes.
Blood Products lead on scale; Anticoagulants lead on momentum.
Application:
Clinical urgency tiers stratify product specifications and dosing protocols.
- Emergency Care:Trauma bays and emergency departments require immediate-acting formulations with minimal preparation time. Rapid fibrinogen assays are compressing time-to-treatment windows in United States Level I trauma centers.
- Critical Care:Intensive care units manage DIC as a sepsis complication through protocol-driven anticoagulation bundles. Tertiary hospitals embed these interventions into standardized order sets.
- Surgical Procedures:Operating rooms deploy hemostatic agents prophylactically in high-bleeding-risk procedures. Cardiovascular and hepatic surgeries generate concentrated demand.
- Standard Recovery:Step-down units and general wards manage stabilized patients through oral or subcutaneous maintenance regimens. Rehabilitation timelines extend therapeutic exposure.
Emergency Care commands premium positioning; Critical Care drives volume expansion.
End User:
Institutional capability and patient acuity determine procurement patterns and formulary composition.
- Hospitals:Acute care facilities with hematology laboratory infrastructure manage complex DIC presentations through multidisciplinary protocols. Academic medical centers in the United States anchor demand concentration.
- Blood Banks:Transfusion services and plasma fractionation facilities supply processed blood components to clinical settings. Cold-chain logistics capabilities constrain geographic reach.
- Clinics:Outpatient hematology practices manage anticoagulation monitoring and stable patient follow-up. Anticoagulant prescribing concentrates in specialized coagulation clinics.
- Rehabilitation Centers:Post-acute facilities manage extended recovery phases through oral maintenance therapies. Step-down protocols are expanding subcutaneous formulation adoption.
Hospitals dominate absolute consumption; Blood Banks control upstream access.
Delivery Mode:
Pharmacokinetic requirements and nursing burden trade-offs shape formulation development priorities.
- Intravenous:Direct vascular administration achieves therapeutic plasma concentrations within minutes. Emergency departments and operating rooms require this route for acute hemorrhagic presentations.
- Subcutaneous:Depot formulations enable sustained release with reduced monitoring requirements. Step-down units seeking nursing efficiency gains are expanding adoption.
- Oral:Enteric formulations support maintenance therapy in stabilized outpatients. Direct oral anticoagulant protocols are penetrating post-discharge regimens.
- Topical:Localized hemostatic agents including fibrin sealants and thrombin sprays control surgical site bleeding. Operating room utilization concentrates in cardiovascular and orthopedic procedures.
Intravenous formulations anchor clinical practice; Subcutaneous routes are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Academic medical centers in the United States concentrate sepsis-associated DIC protocol development, driving therapeutic standardization that diffuses through international clinical networks. Regulatory divergence across major markets shapes product registration strategies and plasma sourcing requirements.
United States
FDA hemostatic agent guidance elevates clinical evidence thresholds for novel coagulation modulators entering emergency care workflows. The agency's evolving approval pathways compress development timelines while extending pre-submission consultation requirements. Major academic medical centers in Boston and Baltimore anchor protocol standardization that cascades through integrated delivery networks.
Germany
EMA MDR post-market surveillance obligations accelerate quality management investments among blood product manufacturers serving tertiary hospitals. REACH registration requirements for hemostatic raw materials impose documentation burdens on plasma fractionators sourcing protein derivatives. The Rhine-Ruhr industrial corridor hosts specialized cold-chain logistics providers supporting distribution across Central European clinical networks.
Japan
PMDA regulatory harmonization initiatives align hemostatic agent approval standards with international reference frameworks, reducing duplicate clinical study requirements. METI industrial policy supports domestic plasma fractionation capacity expansion to reduce import dependency. The Kanto region surrounding Tokyo concentrates hematology research institutes driving diagnostic protocol innovation.
India
CDSCO regulatory pathways for plasma-derived therapies attract multinational manufacturers establishing local fractionation partnerships with tertiary hospital networks. Central government health infrastructure schemes expand critical care capacity in state capitals, creating protocol-driven demand for coagulation therapies. Maharashtra's Mumbai-Pune corridor anchors private hospital chains deploying standardized sepsis bundles.
United Kingdom
NHS England specialized commissioning frameworks concentrate DIC management expertise in designated major trauma centers, concentrating product utilization in urban academic hospitals. MHRA post-Brexit regulatory autonomy enables accelerated approval pathways for innovative hemostatic agents meeting unmet clinical needs. The Oxford-Cambridge-London golden triangle anchors translational hematology research bridging diagnostic and therapeutic development.
Disseminated Intravascular Coagulation (DIC) Treatment Market Competitive Environment
Portfolio diversification dominates the current landscape as manufacturers extend from anticoagulant cores into adjacent hemostasis and diagnostic categories. The vendor base stratifies across three tiers: integrated pharmaceutical conglomerates with anticoagulant manufacturing scale, specialized blood product fractionators with plasma sourcing networks, and diagnostic equipment manufacturers with coagulation testing platforms. Two competitive vectors shape positioning: therapeutic modality convergence combining anticoagulant and hemostat functions, and vertical control over plasma collection networks securing raw material supply.
Within the integrated pharmaceutical tier, Pfizer Inc. and Bayer AG exemplify scale-driven positioning anchored in anticoagulant manufacturing infrastructure. Novartis AG occupies a specialized position through blood product portfolio concentration. These three entities represent distinct strategic archetypes: manufacturing scale leverage, R&D intensity in hemostasis research, and specialized clinical positioning in European hospital networks.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Bayer AG |
| Novartis AG |
| Sanofi S.A. |
| Johnson & Johnson |
| F. Hoffmann-La Roche Ltd. |
| Siemens Healthineers |
| Abbott Laboratories |
| Sysmex Corporation |
| Others |
Value Chain & Pricing Dynamics
Plasma fractionation costs cascade through three distinct pricing tiers as raw material scarcity at United States collection centers concentrates margin capture upstream. Cold-chain logistics expenditure and FDA compliance investments compound at each downstream handoff, embedding geographic proximity premiums into hospital procurement contracts.
Pricing Analysis
Direct-to-hospital contracts with integrated delivery networks command volume-based discounts that compress manufacturer margins at scale. Three-tier pricing structure across premium, standard, and economy levels separates plasma-derived concentrates from synthetic anticoagulants from generic antifibrinolytics, with certification grade and cold-chain reliability as primary differentiation drivers. Price erosion runs through the antifibrinolytic tier as tranexamic acid commoditization accelerates. Academic medical centers exhibit lowest price sensitivity due to protocol standardization requirements, while community hospitals face acute budget constraints.
Supply Chain Analysis
Direct-to-hospital channels handle hyperscale demand from United States integrated delivery networks, with blood banks serving as intermediate nodes for smaller facilities. Supply concentrates in the United States, Germany, and Japan due to plasma collection infrastructure and fractionation capacity. Raw material dependencies center on source plasma, cryoprecipitate feedstock, and heparin API. Single-source vulnerability from United States-based collection networks exposes manufacturers to donor pool volatility and geographic disruption. Distribution runs through temperature-controlled logistics providers with validated cold-chain documentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The DIC treatment market compounds steadily as sepsis protocol expansion in tertiary hospitals generates protocol-locked demand with limited substitution risk.
For Market Incumbents: Anchor manufacturing scale through backward integration into plasma collection networks, securing donor pool access against geographic concentration risk. Expand cryoprecipitate and fresh frozen plasma capacity in United States academic medical center corridors to capture protocol standardization benefits. Counter direct oral anticoagulant displacement threat by embedding heparin derivatives into sepsis bundle order sets. For New Entrants and Emerging Players: Cartridge-based viscoelastic testing platforms offer technology-first entry into emergency department point-of-care markets underserved by centralized laboratory incumbents. Target Indian tertiary hospital expansion through CDSCO partnership pathways, leveraging local fractionation joint ventures to bypass cold-chain infrastructure gaps. Pursue subcutaneous formulation development for step-down unit revenue streams beyond acute care saturation. For Investors and Strategic Acquirers: Consolidation pressure builds where plasma sourcing networks face geographic concentration and regulatory compliance burdens favor scaled operators. The market supports long-term viability through recurring demand from chronic sepsis and trauma presentations. Acquisition targets should demonstrate captive plasma collection relationships or specialized hemostasis R&D pipelines. Monitor FDA guidance evolution on hemostatic agent approvals as inflection signal for development timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| Plasma Collection Network Expansion | Captive sourcing from United States donor centers insulates against supply disruption and price volatility. |
| Subcutaneous Formulation Development | Step-down unit adoption in rehabilitation settings extends therapeutic exposure beyond acute care windows. |
| Point-of-Care Testing Integration | Cartridge-based viscoelastic devices compress emergency department time-to-treatment metrics. |
| CDSCO Regulatory Partnership | Indian fractionation joint ventures unlock access to expanding tertiary hospital infrastructure. |
| Sepsis Bundle Protocol Embedding | Academic medical center standardization creates formulary lock-in against anticoagulant substitution. |
Study Parameters
Direct dialogue with hematology laboratory directors, hospital pharmacy procurement managers, plasma fractionation executives, and regulatory affairs specialists grounded the qualitative foundation. Secondary validation drew from FDA hemostatic agent guidance documents, EMA MDR submission databases, WHO blood safety standards, and hospital formulary records. Bottom-up demand modeling across therapeutic modality and care setting segments triangulated against top-down market sizing from plasma collection volume and anticoagulant prescription data.
Segment-level revenue trajectories across the projection horizon reflect patient volume expansion, protocol penetration rates, and pricing tier evolution. The analytical framework modeled therapeutic modality, application urgency tier, end-user institutional type, and delivery route as core segmentation dimensions. CAGRs were derived from historic plasma product utilization trends and anticoagulant protocol adoption curves, with sepsis incidence projections and trauma center designation expansion as key forecast inputs.
The model holds under stable sepsis protocol standardization and intact plasma supply chains; deviation in FDA approval timelines or United States donor pool contraction would shift volume and value outputs. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Peanut Allergy Treatment Market
Medical Treatment
North America Breast Reconstruction Market
Medical Treatment
Otoplasty Market
Medical Treatment
Histiocytosis Treatment Market
Medical Treatment
Stereotactic Body Radiation Therapy Market
Medical Treatment
Adenomyosis Treatment Market
Medical Treatment
Liver Fluke Treatment Market
Medical Treatment
Global Nano Therapy Market
Medical Treatment
Europe Lysosomal Disease Treatment Market
Medical Treatment
Yellow Fever Treatment Market
Medical Treatment
Single-Dose Therapy Market
Medical Treatment
Gaucher Disease Treatment Market
Medical Treatment
Tauopathies Treatment Market
Medical Treatment
Global Sciatica Market
Medical Treatment
Hypercoagulability Treatment Market
Medical Treatment
Scabies Treatment Market