
 Factor XIII Deficiency Treatment Market | 2026-2036
Factor XIII Deficiency Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Factor XIII Deficiency Treatment Market Analytics
Plasma-derived factor XIII concentrate specifications are collapsing toward higher purity tiers and viral inactivation standards. CSL Behring leverages its vertically integrated plasma collection network across North America and Europe to sustain consistent output of pathogen-reduced concentrates. Grifols anchors its position through dedicated rare disease manufacturing infrastructure in Barcelona and Los Angeles. Octapharma competes on fractionation scale, operating one of the world's largest plasma processing facilities to secure economies in specialty coagulation products.
Factor XIII deficiency treatment encompasses therapeutic interventions for congenital or acquired deficiencies of fibrin-stabilizing factor, a transglutaminase that cross-links fibrin monomers to form stable clots; plasma-derived concentrates typically contain 250-1600 IU per vial with specific activity exceeding 10 IU per milligram of protein, while recombinant formulations eliminate human plasma sourcing risks entirely. Replacement therapy dominates clinical practice due to established hemostatic efficacy in surgical prophylaxis and bleeding episodes, whereas gene therapy represents the fastest-growing segment as adeno-associated viral vector platforms advance toward regulatory submission. Intravenous delivery maintains structural primacy in hospital settings, though subcutaneous formulations are gaining traction in homecare environments where patient self-administration reduces treatment burden.
FDA orphan drug exclusivity provisions and EMA's Committee for Orphan Medicinal Products shape development incentives, with both agencies mandating viral safety validation and potency consistency across manufacturing lots. The EU's Medical Device Regulation and ISO 13485 quality management standards govern ancillary delivery systems including reconstitution devices and infusion pumps. Stakeholders must monitor evolving gene therapy regulatory pathways and plasma supply chain resilience as manufacturing geography diversifies beyond traditional collection regions.
Market Dynamics
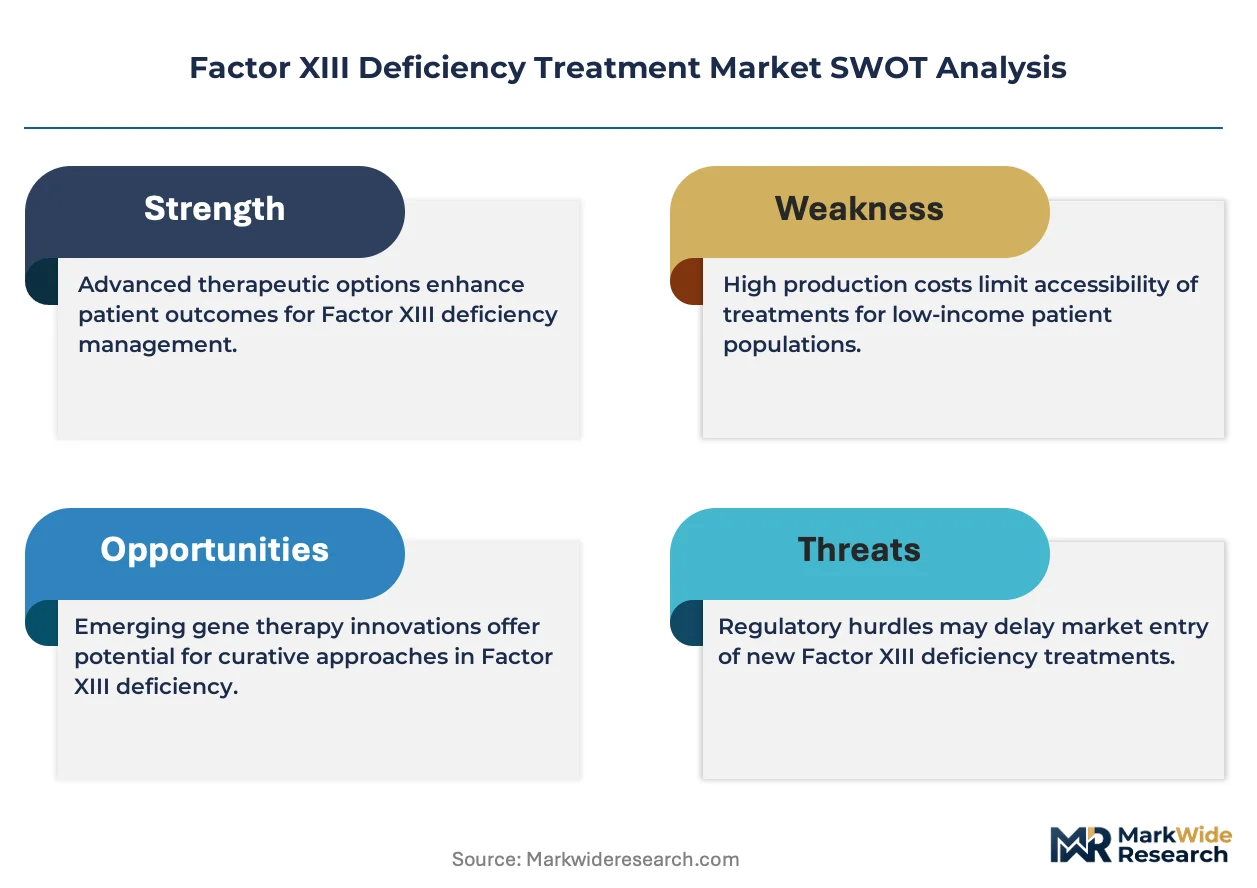
Plasma supply concentration across North American and European collection networks is compressing manufacturing flexibility for specialty coagulation concentrates, forcing fractionators to secure long-term donor contracts and diversify collection geographies.
Growth Catalysts
- EMA Orphan Drug Incentives:Fee waivers and protocol assistance accelerate development timelines for recombinant Factor XIII candidates, reducing regulatory burden for sponsors targeting rare bleeding disorders.
- Hematology Center Consolidation:Specialized treatment networks in the United States, Germany, and Japan centralize patient volumes, creating predictable demand anchors for prophylactic replacement therapy.
- Subcutaneous Delivery Platforms:Reconstitution device innovations enable home administration, reducing hospital dependency and expanding addressable patient populations beyond institutional settings.
Market Restraints
- Plasma Collection Concentration:Dependence on North American and European donor pools limits geographic redundancy, exposing supply chains to collection disruptions and viral screening protocol changes.
- Viral Inactivation Cost Burden:Nanofiltration and solvent-detergent treatment steps add substantial manufacturing overhead, compressing margins on low-volume specialty products.
- Gene Therapy Substitution Threat:Adeno-associated viral vector candidates in clinical development promise functional cures, potentially obsoleting lifelong replacement therapy for congenital deficiency patients.
Strategic Opportunities
- Japanese Rare Disease Infrastructure:PMDA's Sakigake designation pathway and centralized hemophilia treatment centers create favorable conditions for novel recombinant product launches.
- Acquired Deficiency Indications:Surgical prophylaxis in cardiac and trauma settings represents an expansion vector beyond congenital patient populations, leveraging existing hospital formulary relationships.
- ISO 13485-Certified Delivery Systems:Integrated reconstitution and infusion devices command premium positioning through reduced preparation error rates and improved patient compliance metrics.
Industry Challenges
- Transglutaminase Biochemistry Expertise Gap:Limited pool of specialists capable of Factor XIII potency assay development and validation constrains manufacturing scale-up and quality control staffing.
- Plasma Supply Chain Reconfiguration:Relocation of fractionation capacity to emerging collection regions requires extensive regulatory requalification and viral safety validation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Factor XIII Deficiency Treatment Market |
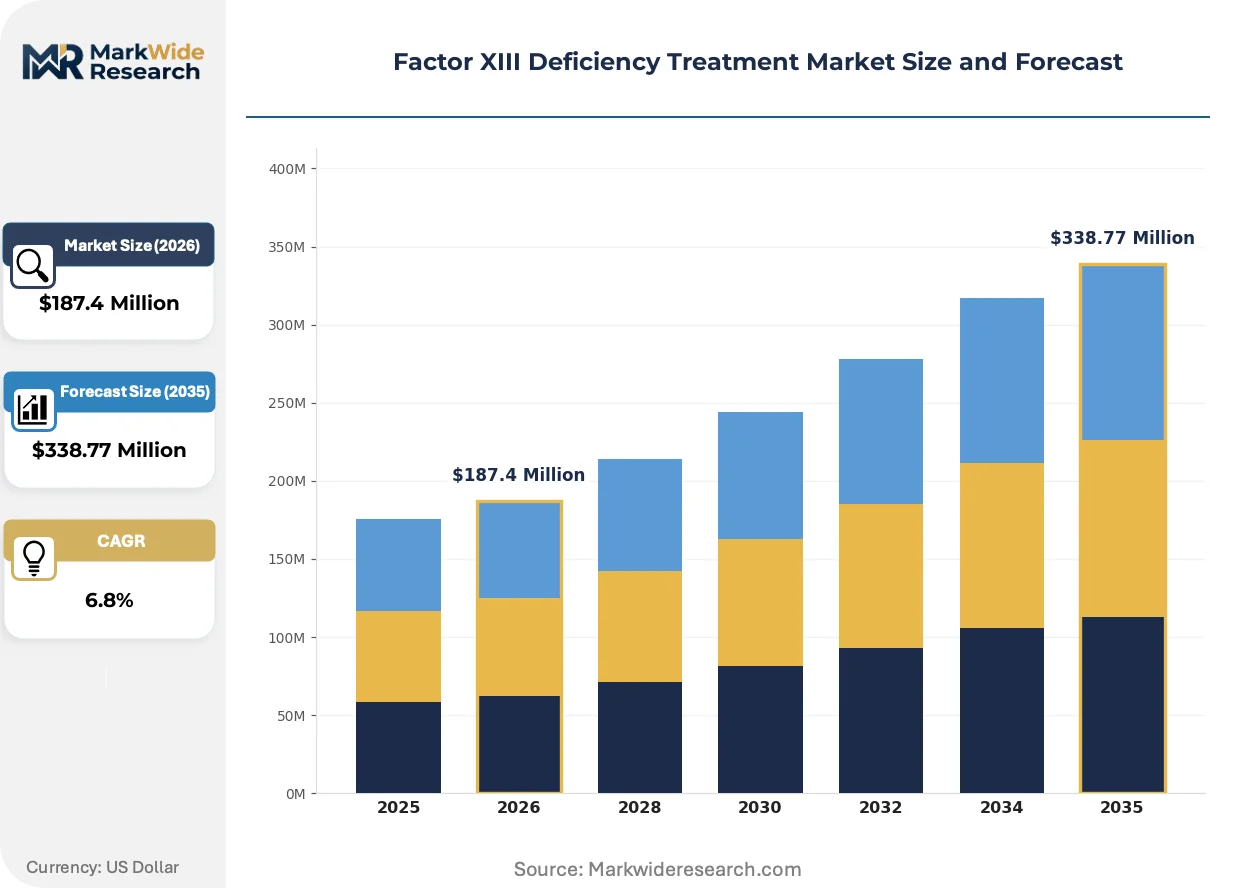
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Therapy Type: Replacement Therapy, Supportive Care, Gene Therapy, Plasma-derived Products Delivery Mode: Intravenous, Subcutaneous, Intramuscular, Oral End User: Hospitals, Specialty Clinics, Homecare, Research Laboratories Formulation: Liquid, Powder, Suspension, Lyophilized |
| Companies Covered | CSL Behring, Grifols, Octapharma, LFB Group, Novo Nordisk, Takeda Pharmaceutical Company, Merck KGaA, Bio Products Laboratory, Sobi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Factor XIII Deficiency Treatment Market Evolving Landscape
Technology trajectories in this market center on eliminating plasma dependency, compressing treatment burden, and migrating care from institutional to ambulatory settings. Three developments dominate strategic planning.
Recombinant Factor XIII production is fragmenting the historical dominance of plasma-derived concentrates. Biotechnology platforms utilizing yeast or mammalian cell expression systems eliminate human-sourced material risks entirely. Hematology centers in Germany and Japan are piloting recombinant transitions for prophylactic regimens, compressing the addressable market for traditional fractionators.
FDA's evolving gene therapy guidance for hemophilia and related bleeding disorders is reshaping clinical trial design requirements. The agency's emphasis on long-term follow-up protocols and durable expression endpoints extends development timelines. Sponsors targeting congenital Factor XIII deficiency must now integrate fifteen-year safety monitoring commitments into commercialization strategies.
Homecare infusion protocols are displacing hospital-based replacement therapy for stable prophylactic patients. Self-administration training programs and telemedicine monitoring reduce treatment center utilization. This pattern is most visible in United States hemophilia treatment centers, where reimbursement incentives favor reduced institutional encounters.
Factor XIII Deficiency Treatment Market Segmentation
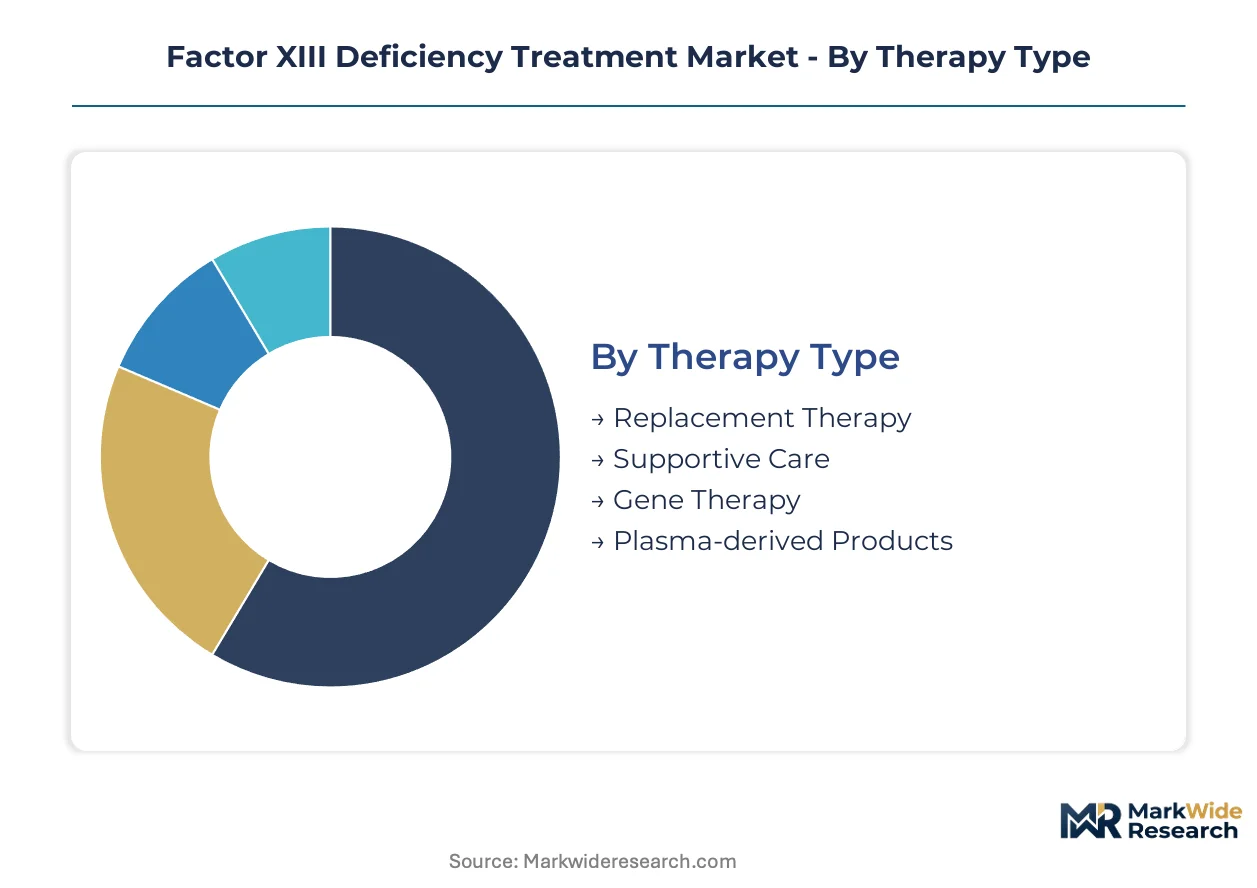
Factor XIII deficiency treatment segments fracture along therapy longevity, administration setting, and production chemistry. Substitution pressures vary dramatically across these dimensions, with some categories facing imminent technological obsolescence while others deepen institutional lock-in.
Therapy Type:
Gene therapy candidates threaten replacement therapy incumbency most acutely in congenital deficiency populations, while supportive care and plasma-derived products occupy defensive positions against substitution.
- Replacement Therapy:Plasma-derived or recombinant Factor XIII concentrates administered prophylactically or episodically to restore hemostatic function. Hematology centers in Germany and Japan anchor demand for prophylactic regimens, though fifteen-year follow-up requirements for gene therapy competitors compress long-term revenue visibility for concentrate manufacturers.
- Gene Therapy:Adeno-associated viral vector platforms delivering functional F13A1 or F13B gene constructs to hepatocytes for durable expression. PMDA's Sakigake designation pathway and FDA's hemophilia gene therapy guidance framework accelerate Japanese and United States clinical programs, threatening lifelong replacement therapy economics for congenital patients.
- Supportive Care:Adjunctive interventions including antifibrinolytic agents and local hemostatic measures for mild bleeding episodes. Acquired deficiency indications in cardiac surgery settings sustain demand where replacement therapy is contraindicated.
- Plasma-derived Products:Fractionated concentrates from pooled human plasma with viral inactivation processing. Viral safety validation costs and collection geography concentration constrain margin expansion despite established hemostatic efficacy.
Replacement therapy retains volume leadership; gene therapy holds the steepest expansion curve.
Delivery Mode:
Cost tier stratification separates hospital-intensive intravenous administration from emerging homecare-compatible alternatives, with reimbursement incentives driving migration toward lower-acuity settings.
- Intravenous:Direct venous infusion of reconstituted concentrate in institutional settings requiring nursing supervision. United States hemophilia treatment centers maintain formulary dominance for surgical prophylaxis and acute bleeding episodes.
- Subcutaneous:Depot formulations enabling patient self-administration outside hospital environments. Reconstitution device innovations reduce preparation error rates and expand addressable populations to stable prophylactic patients.
- Intramuscular:Limited application for localized hemostatic support in trauma settings where venous access is compromised.
- Oral:Experimental formulations targeting acquired deficiency populations with compliance barriers to parenteral therapy.
Intravenous administration commands premium pricing; subcutaneous delivery is climbing the fastest.
End User:
Customer type concentration determines procurement sophistication, with consolidated hospital networks exercising formulary control over fragmented homecare channels.
- Hospitals:Academic medical centers and surgical suites managing acute bleeding episodes and perioperative prophylaxis. Centralized pharmacy committees negotiate multi-year supply contracts with fractionators.
- Specialty Clinics:Dedicated bleeding disorder treatment centers in the United States, Germany, and Japan coordinating multidisciplinary care and patient registry enrollment.
- Homecare:Self-administration programs for stable prophylactic patients with telemedicine monitoring support. Reimbursement incentives in United States commercial and Medicare Advantage plans favor reduced institutional encounters.
- Research Laboratories:Academic and contract research organizations conducting potency assay development and gene therapy preclinical studies.
Hospitals retain volume leadership; homecare holds the steepest expansion curve.
Formulation:
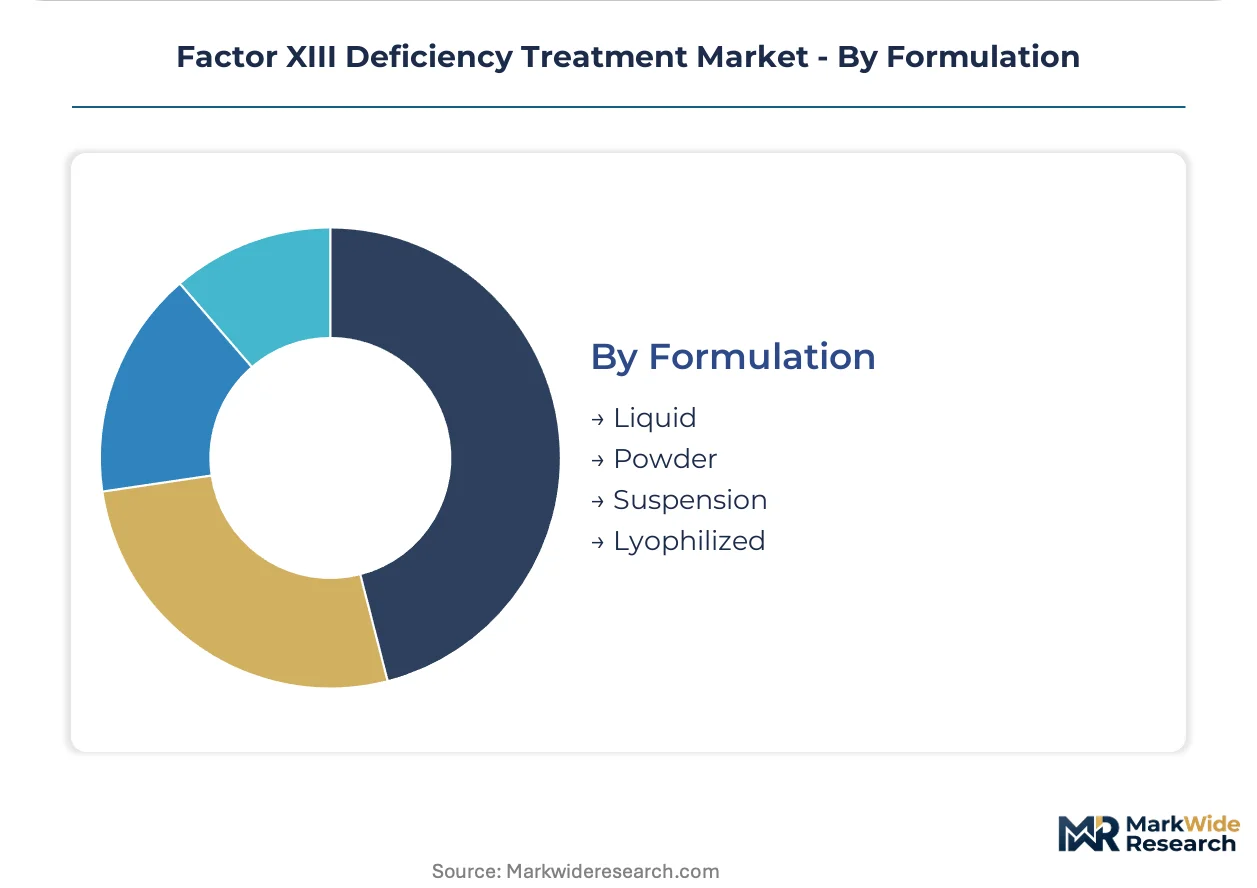
Supply concentration in fractionation infrastructure favors lyophilized and liquid formats with established cold chain distribution, while powder and suspension alternatives remain developmental.
- Liquid:Ready-to-use concentrates eliminating reconstitution steps and reducing preparation time in emergency settings. CSL Behring and Grifols dominate commercial supply with pathogen-reduced liquid formulations.
- Lyophilized:Freeze-dried concentrates with extended shelf stability and reduced cold chain burden for international distribution. Octapharma leverages fractionation scale to secure economies in specialty lyophilized coagulation products.
- Powder:Bulk intermediate for contract manufacturing and compounding pharmacy applications.
- Suspension:Experimental depot formulations targeting prolonged subcutaneous release kinetics.
Lyophilized formulations retain volume leadership; liquid concentrates are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export flows of plasma-derived concentrates originate from fractionation hubs in the United States and Germany, while Japan maintains import dependency for specialty coagulation products. Trade balances favor established collection networks with viral inactivation capabilities. Regulatory divergence across FDA, EMA, and PMDA jurisdictions shapes market access timelines.
United States
Academic medical centers in Boston and New York anchor surgical prophylaxis demand for congenital deficiency patients. FDA orphan drug exclusivity provisions accelerate approval pathways for recombinant candidates, compressing development timelines relative to standard biologics. The Research Triangle Park cluster in North Carolina concentrates contract manufacturing organizations supporting viral safety validation studies.
Germany
Specialized hemophilia treatment centers in Munich and Hamburg centralize patient registries and drive prophylactic replacement therapy volumes. EMA's Committee for Orphan Medicinal Products mandates centralized marketing authorization procedures, harmonizing access across member states. The Frankfurt-Rhine-Main biotech corridor hosts fractionation facilities with integrated pathogen reduction capabilities.
Japan
PMDA's Sakigake designation pathway attracts gene therapy sponsors targeting congenital bleeding disorders with expedited review timelines. The Tokyo-Osaka corridor concentrates hematology specialists and bleeding disorder treatment networks with established patient identification protocols. Domestic plasma collection remains insufficient, necessitating reliance on imported concentrates with extended cold chain distribution.
Switzerland
Swissmedic's alignment with EMA standards facilitates parallel regulatory submissions for recombinant products while maintaining independent pharmacovigilance requirements. The Basel biopharma cluster anchors European headquarters for multinational plasma fractionators with regional distribution networks. Zürich's university hospitals pilot subcutaneous administration protocols for stable prophylactic patients.
United Kingdom
NHS England's specialized commissioning framework consolidates procurement for rare bleeding disorder treatments across designated hemophilia centers. The MHRA's post-Brexit regulatory autonomy enables accelerated assessment pathways for novel recombinant formulations. London's academic medical centers maintain active gene therapy trial enrollment for congenital deficiency populations.
Factor XIII Deficiency Treatment Market Competitive Landscape
Listed leaders compete with private specialists across plasma supply security and manufacturing scale dimensions. The vendor base stratifies between vertically integrated plasma collectors with captive fractionation capacity and recombinant biotechnology platforms eliminating human-sourced material dependencies. Three archetypes dominate: plasma-dependent fractionators securing long-term donor contracts, recombinant protein specialists leveraging mammalian cell expression systems, and gene therapy platforms targeting functional cures. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with fractionators diversifying collection geographies and biotechnology firms securing contract manufacturing agreements.
Within the plasma-derived tier, CSL Behring, Grifols, and Octapharma exemplify scale-dependent positioning. CSL Behring represents Australian-listed vertical integration into North American and European donor networks. Grifols occupies a position within Spanish-headquartered private specialists with dedicated rare disease manufacturing infrastructure. Octapharma anchors the European private specialist archetype with large-scale fractionation capacity serving specialty coagulation markets.
| Leading Market Players |
|---|
| CSL Behring |
| Grifols |
| Octapharma |
| LFB Group |
| Novo Nordisk |
| Takeda Pharmaceutical Company |
| Merck KGaA |
| Bio Products Laboratory |
| Sobi |
| Others |
Value Network & Pricing Analysis
Recombinant Factor XIII production platforms are displacing plasma-derived concentrates as the dominant supply source, simultaneously shifting manufacturing geography toward biotechnology clusters in the United States and Germany while compressing pricing premiums previously commanded by fractionators with captive donor networks. This substitution dynamic forces plasma-dependent incumbents to absorb viral inactivation cost burdens without commensurate price recovery, eroding margins on specialty coagulation products.
Pricing Analysis
Hospital pharmacy committees and hematology center procurement directors anchor a contract-based long-term offtake structure with multi-year supply agreements. Pricing stratifies across pathogen-reduced premium tiers, recombinant standard formulations, and economy-positioned non-virally inactivated alternatives, with differentiation driven by FDA orphan drug exclusivity status and ISO 13485 certification of delivery systems. Cost compression in the plasma-derived tier is intensifying because viral validation overhead expands without volume scale benefits. Academic medical centers exhibit highest price sensitivity due to formulary budget constraints, while specialty clinics with dedicated rare disease funding demonstrate lowest sensitivity.
Supply Chain Analysis
Strategic stockpiling of lyophilized concentrates dominates inventory strategy among hematology centers managing congenital deficiency populations, contrasting with just-in-time replenishment patterns for liquid formulations in surgical settings. Geographic supply concentration centers on the United States, Germany, and Japan, with raw material dependencies spanning North American donor plasma pools, recombinant yeast expression systems, and single-source AAV vector production. Single-source vulnerability in plasma collection networks poses structural risk amid geographic concentration of fractionation capacity. Distribution runs through cold chain logistics providers with validated temperature monitoring for international concentrate shipments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat environment where regulatory entrenchment through FDA orphan drug exclusivity and EMA protocol assistance creates substantial switching costs for treatment centers with established patient registries and trained nursing protocols.
For Market Incumbents: Fortify plasma supply security through long-term donor contracts in North America and backward integration into collection center operations. Expand Barcelona and Los Angeles manufacturing infrastructure to absorb viral inactivation capacity constraints. Gene therapy substitution threats demand accelerated recombinant platform investment to retain congenital patient volumes. For New Entrants and Emerging Players: Differentiate on subcutaneous delivery innovation and homecare-compatible formulations to bypass hospital formulary lock-in. Target Japanese rare disease infrastructure through PMDA Sakigake pathway submissions. Acquired deficiency indications in cardiac surgery settings offer the most penetrable expansion vector with existing reimbursement codes. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed plasma fractionators possessing European collection networks but limited recombinant capabilities. Five-to-ten year viability hinges on successful gene therapy transition or niche consolidation in acquired deficiency segments. Watch FDA gene therapy approval timelines as inflection indicator for replacement therapy revenue erosion.| Strategic Initiative | Industry Significance |
|---|---|
| Recombinant Manufacturing Scale-Up | Eliminates plasma sourcing risks while securing EMA orphan drug fee waivers for sponsors. |
| Subcutaneous Delivery Development | Enables patient self-administration outside hospital settings, expanding addressable populations. |
| Gene Therapy Clinical Advancement | Positions sponsors for fifteen-year safety monitoring commitments under FDA hemophilia guidance. |
| Japanese Regulatory Pathway Entry | Leverages PMDA Sakigake designation for expedited review in concentrated treatment networks. |
| Plasma Collection Geographic Diversification | Reduces single-source vulnerability in North American and European donor pool dependencies. |
Research Methodology
Operator-level perspectives from drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists anchored the qualitative base. Primary interviews combined with secondary validation from FDA filings, EMA submissions, ClinicalTrials.gov records, and hospital formulary databases. Bottom-up patient population estimates and top-down fractionator revenue triangulation cross-verified market sizing across therapy type, delivery mode, and end user segments.
Sensitivity analysis tested forecast robustness across plasma supply disruption scenarios and gene therapy approval timelines over the projection horizon. The analytical framework modeled treatment line, dosage form, administration route, and regional regulatory cluster dimensions. CAGRs derived from historical concentrate pricing trends and projected patient identification rates in specialized hematology centers. Forecast inputs incorporated EMA orphan drug incentive utilization and PMDA Sakigake pathway adoption patterns.
The analysis sits within stated boundaries; outcomes outside sustained plasma collection volumes or accelerated gene therapy clinical success would require recalibration. Forecasts reflect documented assumptions regarding regulatory pathway timelines and patient registry enrollment trajectories. Revision becomes warranted when gene therapy durability data crosses efficacy thresholds or plasma supply geography shifts substantially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Stereotactic Body Radiation Therapy Market
Medical Treatment
Otoplasty Market
Medical Treatment
Neglected Tropical Disease Treatment Market
Medical Treatment
Molluscum Contagiosum (MC) Treatment Market
Medical Treatment
Yellow Fever Treatment Market
Medical Treatment
Mexico Hair Transplant Market
Medical Treatment
Anorectal Malformation Treatment Market
Medical Treatment
Vulvodynia Treatment Market
Medical Treatment
Lymphedema Treatment Market
Medical Treatment
Hemorrhoids Treatment Market
Medical Treatment
Chagas Disease Treatment Market
Medical Treatment
Europe Lysosomal Disease Treatment Market
Medical Treatment
Hereditary Amyloidosis Treatment Market
Medical Treatment
Brazilian Hemorrhagic Fever (Bzhf) Treatment Market
Medical Treatment
Ringworm Treatment Market
Medical Treatment
Anti-Rickettsial Treatment Market