
 Mercury Poisoning Treatment Market | 2026-2036
Mercury Poisoning Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Mercury Poisoning Treatment Market Foresight
Asset-light licensing arrangements for chelation drug manufacturing is fragmenting competitive access across emerging producers. Sanofi leverages its established hospital formulary relationships to sustain channel dominance in acute care settings. Teva Pharmaceutical Industries anchors its position through generic DMSA production at scale, while EmeraMed Limited differentiates through specialty DMPS formulations for chronic exposure protocols.
Mercury poisoning treatment encompasses pharmaceutical interventions designed to bind and eliminate elemental, inorganic, and organic mercury compounds from human tissue, primarily through sulfhydryl-group chelation that forms stable, excretable complexes. These therapies serve the critical clinical purpose of preventing neurological, renal, and gastrointestinal damage in exposed patients. Chelation therapy products command the largest current revenue share due to established reimbursement pathways, while DMSA oral formulations represent the fastest-expanding segment driven by outpatient chronic exposure management. The pediatric treatment application carries concentrated margin pools owing to specialized dosing requirements and limited approved alternatives.
The FDA governs new drug approvals and manufacturing standards for chelation agents under its orphan drug and emergency use frameworks, while EPA mercury emission regulations indirectly shape occupational exposure volumes and consequent treatment demand. OSHA workplace exposure limits for mercury vapor drive mandatory medical surveillance programs that generate recurring screening and intervention needs. Stakeholders must monitor evolving chelation protocol guidelines from WHO and national poison control networks to anticipate shifts in first-line therapy designations and procurement specifications.
Market Dynamics
Hospital procurement of mercury poisoning treatments is consolidating around standardized chelation protocols as EPA and OSHA tighten industrial exposure mandates, compressing vendor selection criteria toward formulary-preferred suppliers with proven acute-care logistics.
Growth Catalysts
- EPA Mercury Air Toxics Standards:Stricter emission controls at coal-fired power plants and cement kilns expand mandatory medical surveillance programs for exposed workers.
- Artisanal Mining:Informal gold extraction in the Amazon basin and Sub-Saharan Africa generates sustained demand for field-deployable chelation kits.
- Dimercaptosuccinic Acid (DMSA) Formulation Advances:Improved oral bioavailability enables outpatient chronic exposure management, extending treatment access beyond hospital settings.
Market Restraints
- API Supply Concentration:Active pharmaceutical ingredient production for British anti-Lewisite (dimercaprol) concentrates in a limited number of specialized chemical manufacturers.
- Dimercaprol Stability Requirements:The oil-based formulation demands cold-chain logistics that complicate distribution to remote industrial sites.
- Chelation Therapy Cost Structure:Intravenous administration requires specialized nursing staff and continuous cardiac monitoring, elevating per-patient treatment expenses.
Strategic Opportunities
- Southeast Asia Industrial Expansion:Vietnam and Indonesia electronics manufacturing growth creates new occupational exposure surveillance markets without established chelation vendor relationships.
- Pediatric Chronic Exposure Protocols:Thimerosal-containing vaccine manufacturing waste incidents drive demand for weight-adjusted DMSA dosing regimens.
- Telemedicine-Enabled Triage:Remote consultation platforms connect rural clinicians with poison control centers, accelerating chelation initiation decisions.
Industry Challenges
- Toxicology Specialist Shortage:Fellowship-trained medical toxicologists remain concentrated at academic medical centers, limiting 24/7 chelation expertise at community hospitals.
- DMPS Regulatory Pathway Complexity:The unapproved status of 2,3-dimercapto-1-propanesulfonic acid in the United States forces reliance on compounded formulations with variable quality.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mercury Poisoning Treatment Market |
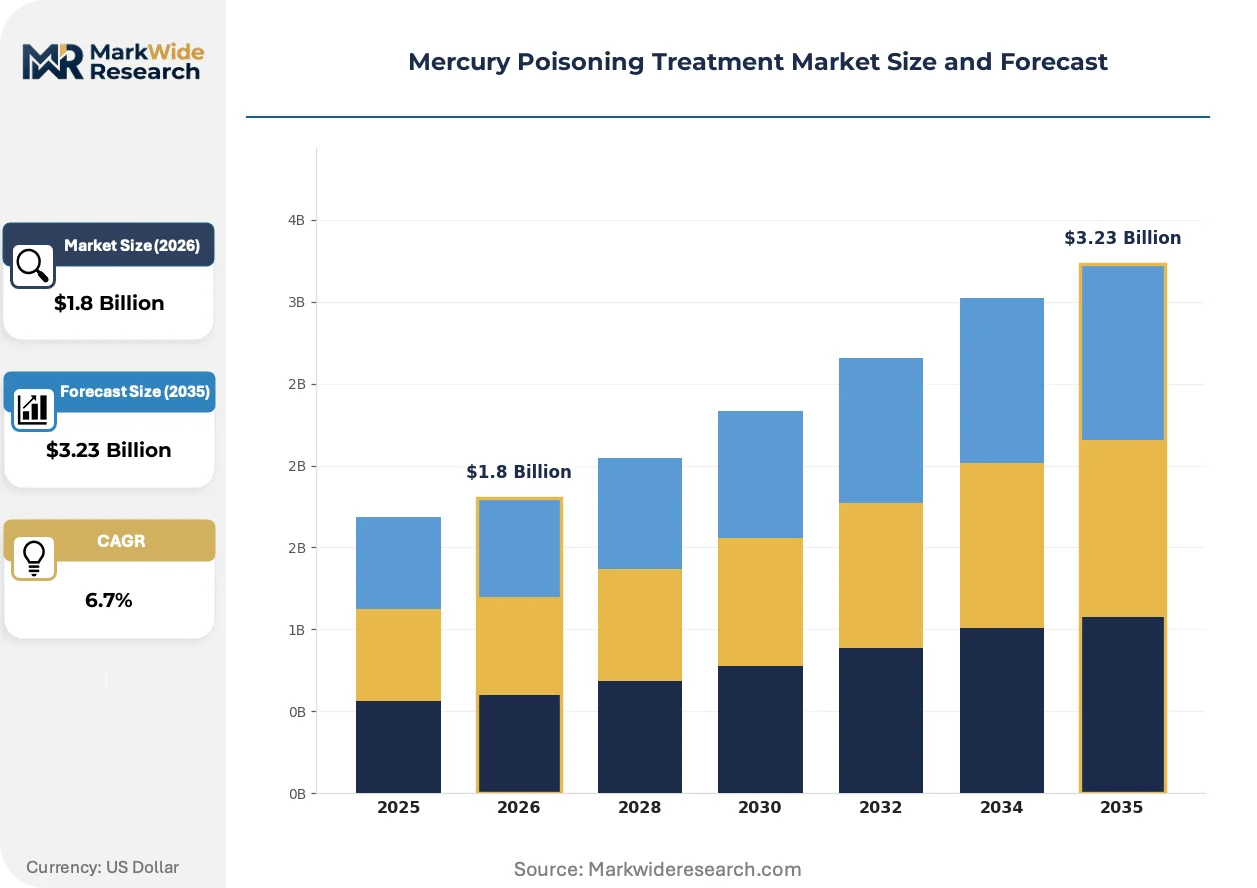
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dimercaprol, DMSA, DMPS, Chelation Therapy Application: Acute Poisoning, Chronic Exposure, Pediatric Treatment, Occupational Hazards Delivery Mode: Oral, Intravenous, Intramuscular, Topical End User: Hospitals, Clinics, Poison Control Centers, Home Care |
| Companies Covered | Mylan N.V., Sanofi, Bausch Health Companies, Recordati S.p.A., EmeraMed Limited, Akorn, Incorporated, Teva Pharmaceutical Industries, Heyl Chemisch-pharmazeutische Fabrik GmbH, Genex Pharma, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mercury Poisoning Treatment Market Shifts & Advancements
Chelation therapy delivery is fragmenting across point-of-care diagnostics, remote monitoring platforms, and algorithm-driven dosing protocols that compress the time from exposure confirmation to treatment initiation.
Point-of-care mercury biomarker testing is virtualizing exposure assessment workflows. Portable atomic absorption spectrometry devices enable immediate blood and urine mercury quantification at industrial clinics. Mining operators in Peru and Ghana deploy these units to bypass centralized laboratory delays. This capability is virtualizing the traditional referral pathway between occupational health stations and tertiary care centers.
REACH authorization requirements for mercury compounds are tightening industrial handling permits across European manufacturing facilities. The European Chemicals Agency now mandates substitution plans for mercury-containing catalysts in chlor-alkali plants. German and Polish industrial operators accelerate medical surveillance program investments to maintain operating licenses under the revised framework.
Hospital procurement committees now unbundle chelation drug purchasing from bundled poison response service contracts. Acute care facilities in Texas and California negotiate direct manufacturer agreements for dimercaprol and DMSA while sourcing clinical toxicology consultation separately. This disintermediation pressures traditional distributor margins and rewards suppliers with transparent unit pricing and verified cold-chain documentation.
Mercury Poisoning Treatment Market Segmentation
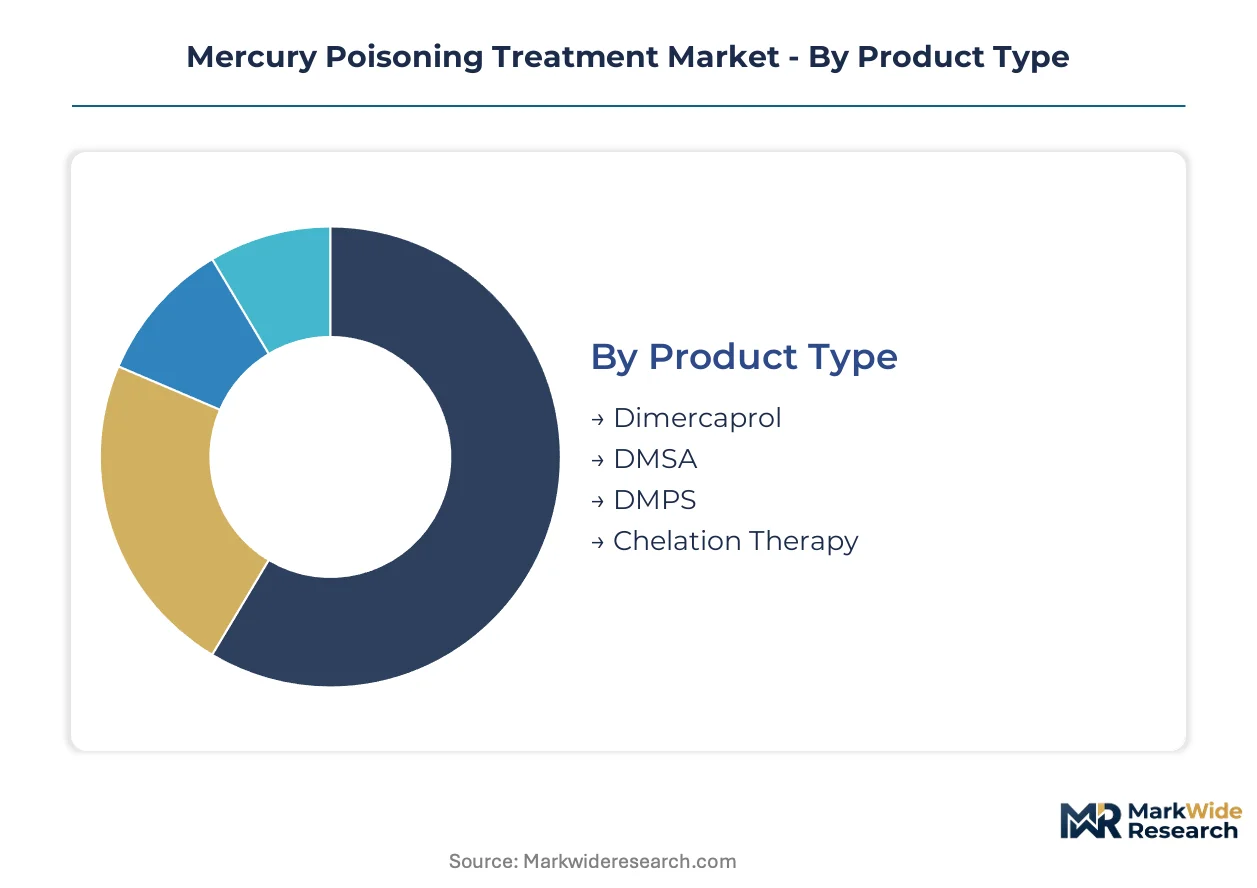
Mercury poisoning treatment selection hinges on exposure severity, patient physiology, and care setting logistics. Each segmentation dimension constrains formulation choice, dosing protocol, and procurement channel differently.
Product Type:
Use-case spectrum spans emergency neurological rescue through outpatient renal protection, with each agent occupying distinct clinical niches based on mercury speciation and tissue distribution kinetics.
- Chelation Therapy:The foundational therapeutic category employs sulfhydryl-binding agents to form stable, excretable mercury complexes. Hospital procurement committees prioritize formulary-preferred suppliers with verified cold-chain documentation for oil-based dimercaprol formulations.
- DMSA:Dimercaptosuccinic acid offers superior oral bioavailability for chronic inorganic mercury exposure, enabling outpatient management that extends treatment access beyond acute care facilities. Weight-adjusted pediatric dosing regimens command concentrated margin pools due to specialized formulation requirements.
- Dimercaprol:British anti-Lewisite remains the intravenous standard for severe acute organic mercury poisoning with neurological involvement. API production concentrates in specialized chemical manufacturers, creating supply vulnerability for emergency stockpiles.
- DMPS:2,3-dimercapto-1-propanesulfonic acid serves chronic exposure protocols in European and Asian markets where regulatory approval exists; unapproved status in the United States forces reliance on compounded formulations with variable quality.
Established volume favors chelation therapy; emerging adoption favors DMSA.
Application:
Cost tier stratification separates resource-intensive acute interventions from surveillance-driven chronic management programs.
- Acute Poisoning:Rapid-onset neurological and renal crises demand immediate intravenous dimercaprol administration with continuous cardiac monitoring. EPA and OSHA industrial exposure mandates tighten mandatory medical surveillance protocols that trigger emergency department referrals.
- Chronic Exposure:Subclinical mercury accumulation from dietary fish consumption or occupational vapor exposure requires extended oral DMSA courses with biomarker-guided dosing adjustments. REACH authorization requirements across European manufacturing facilities accelerate medical surveillance investments.
- Pediatric Treatment:Thimerosal-containing vaccine manufacturing waste incidents and congenital exposure scenarios drive demand for weight-calculated dosing regimens with limited approved alternatives.
- Occupational Hazards:Artisanal gold mining operations in the Amazon basin and Sub-Saharan Africa generate sustained demand for field-deployable chelation kits with simplified administration protocols.
Acute poisoning dominates current expenditure; chronic exposure protocols are climbing the fastest.
Delivery Mode:
Volume concentration reflects the tension between bioavailability optimization and care setting infrastructure constraints.
- Intravenous:Direct vascular administration achieves rapid systemic distribution for critical neurological presentations. Specialized nursing requirements and continuous monitoring elevate per-patient treatment expenses at tertiary care centers.
- Oral:DMSA tablets and capsules enable outpatient chronic exposure management without hospital admission. Formulation advances improving gastrointestinal absorption are displacing parenteral protocols for moderate severity cases.
- Intramuscular:Dimercaprol oil-based injections serve settings lacking intravenous capability, though pain at injection site limits patient acceptance. Cold-chain logistics complicate distribution to remote industrial sites.
- Topical:Limited application for dermal mercury absorption incidents with minimal systemic penetration; primarily adjunctive to oral or parenteral regimens.
Intravenous administration anchors hospital revenue; oral delivery is gaining share fastest.
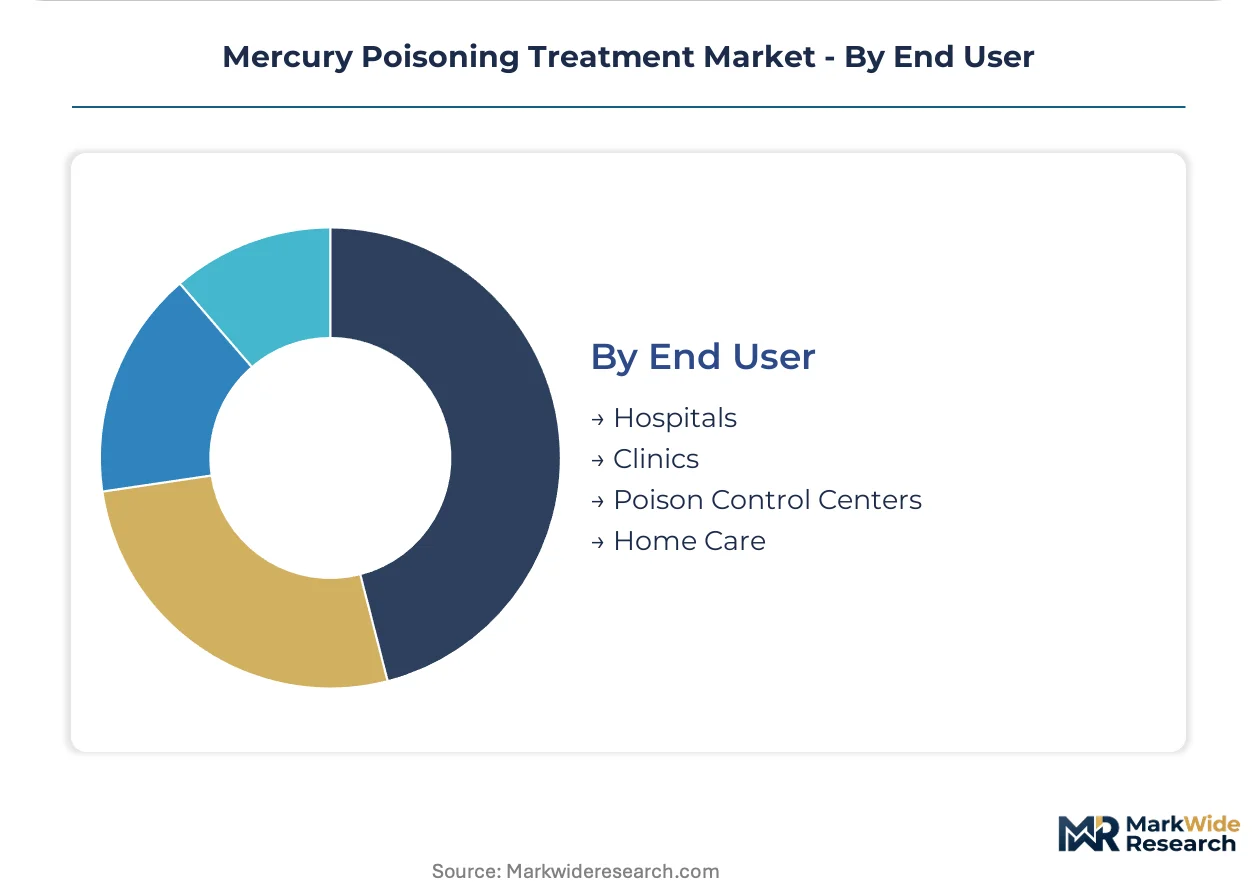
End User:
Customer type fragmentation separates centralized acute care capacity from distributed surveillance and home-based maintenance programs.
- Hospitals:Academic medical centers and community emergency departments maintain chelation stockpiles under poison control center protocols. Procurement committees unbundle drug purchasing from bundled poison response service contracts.
- Poison Control Centers:24/7 toxicology consultation hubs coordinate chelation initiation decisions for referring facilities. Telemedicine-enabled triage platforms connect rural clinicians with specialist expertise.
- Clinics:Occupational health stations at industrial facilities deploy portable biomarker testing to bypass centralized laboratory delays. Vietnamese and Indonesian electronics manufacturing growth creates new surveillance markets.
- Home Care:Oral DMSA maintenance regimens for stabilized chronic exposure patients reduce hospital readmission burden. Caregiver training requirements and dosing adherence monitoring limit expansion.
Hospitals retain the highest per-case value; clinics represent the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement power in Germany commands 15-20% price premiums over Brazilian public tenders for equivalent chelation formulations. This asymmetry reflects divergent reimbursement frameworks and cold-chain infrastructure maturity.
United States
EPA Mercury Air Toxics Standards and OSHA workplace exposure mandates drive mandatory medical surveillance at coal-fired power plants and cement kilns. The FDA governs chelation agent approvals under orphan drug frameworks. Texas and California acute care facilities unbundle drug purchasing from poison response contracts, negotiating direct manufacturer agreements for dimercaprol.
Germany
REACH authorization requirements tighten industrial handling permits for mercury-containing catalysts in chlor-alkali plants. The European Chemicals Agency mandates substitution plans that accelerate medical surveillance investments. Industrial operators in North Rhine-Westphalia and Bavaria deploy portable biomarker testing to maintain operating licenses.
Brazil
Artisanal gold mining in the Amazon basin generates sustained demand for field-deployable chelation kits with simplified administration protocols. ANVISA regulates pharmaceutical imports while public health programs struggle with cold-chain distribution to remote extraction sites. Mining cooperatives in Pará and Mato Grosso states coordinate with regional hospitals for emergency referral pathways.
China
Electronics manufacturing growth in the Yangtze River Delta and Pearl River Delta creates occupational exposure surveillance demand without established chelation vendor relationships. The National Medical Products Administration oversees drug approvals while provincial environmental bureaus tighten industrial emission enforcement. Shenzhen and Shanghai clinics pilot telemedicine-enabled triage connecting rural clinicians with toxicology expertise.
India
Thimerosal-containing vaccine manufacturing waste incidents drive demand for weight-adjusted DMSA dosing regimens in pediatric populations. The Central Drugs Standard Control Organization regulates chelation agent quality while state pollution control boards expand industrial mercury monitoring. Pharmaceutical clusters in Maharashtra and Gujarat scale generic DMSA production for domestic and export markets.
Mercury Poisoning Treatment Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream. The mercury poisoning treatment market consolidates around formulary-preferred suppliers with proven acute-care logistics and verified cold-chain documentation. Three archetypes dominate: multinational pharmaceutical conglomerates with hospital procurement relationships, generic manufacturers scaling oral DMSA production, and specialty firms developing chronic exposure formulations. Competitive moves center on unbundling service contracts from drug purchasing and expanding licensing arrangements for emerging market manufacturing.
Among European-based specialists, EmeraMed Limited and Heyl Chemisch-pharmazeutische Fabrik GmbH occupy positions within the chronic exposure formulation tier. Sanofi anchors the multinational platform segment through established hospital formulary channels. These three exemplify divergent strategic postures: specialty DMPS development, regional chemical manufacturing, and global acute-care distribution respectively.
| Leading Market Players |
|---|
| Mylan N.V. |
| Sanofi |
| Bausch Health Companies |
| Recordati S.p.A. |
| EmeraMed Limited |
| Akorn, Incorporated |
| Teva Pharmaceutical Industries |
| Heyl Chemisch-pharmazeutische Fabrik GmbH |
| Genex Pharma |
| Others |
Supply & Pricing Matrix
Cold-chain undercapacity in Brazilian Amazon extraction sites compresses supplier margins while elevating delivery premiums for oil-based dimercaprol formulations. Hospital procurement committees exploit this logistics asymmetry to extract favorable unit pricing from vendors with verified temperature-controlled documentation.
Pricing Analysis
Configured-to-order pricing for weight-adjusted pediatric DMSA regimens commands substantial premiums over standard adult oral formulations. Contract-based long-term offtake agreements dominate hospital procurement, with price differentiation driven by FDA orphan drug certification tier and cold-chain service bundling. Cost compression in generic DMSA intensifies as Indian and Chinese manufacturers scale API production. Community hospitals exhibit highest price sensitivity due to limited chelation stockpile budgets; academic medical centers prioritize formulary security over unit cost.
Supply Chain Analysis
Tariff exposure between China and the United States disrupts DMSA API flows that pharmaceutical manufacturers draw from specialized chemical producers in Jiangsu and Zhejiang provinces. British anti-Lewisite production concentrates in Germany and the United Kingdom, creating single-source vulnerability for emergency dimercaprol stockpiles. Distribution runs through hospital procurement committees that unbundle drug purchasing from clinical toxicology services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mercury poisoning treatment functions as a service-attach opportunity where biomarker monitoring and telemedicine triage subscriptions expand faster than chelation drug volumes. Recurring revenue from surveillance program management now exceeds hardware margins in chronic exposure protocols.
For Market Incumbents: Harden formulary-preferred status through captive cold-chain infrastructure investments that emerging producers cannot replicate. Secure backward integration into DMSA API production to insulate margin compression from Indian and Chinese generic entrants. Anchor hospital procurement relationships with bundled poison response service contracts that resist unbundling pressures. For New Entrants and Emerging Players: Establish a beachhead in Vietnamese and Indonesian electronics manufacturing surveillance markets lacking established chelation vendor relationships. Target occupational health clinics with portable biomarker testing platforms that bypass centralized laboratory delays. Pursue licensing arrangements for DMPS formulations in European and Asian regulatory jurisdictions where approval pathways exist. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across oral DMSA manufacturing as continuous processing displaces batch synthesis. Specialty firms with chronic exposure formulation expertise and existing regulatory approvals represent priority acquisition targets. Monitor EPA enforcement activity at coal-fired power plants as a demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | DMPS regulatory approval pathway in the United States would unlock compounded formulation substitution. |
| Manufacturing Scale-Up | Generic DMSA production expansion in Maharashtra and Gujarat feeds domestic and export hospital procurement. |
| Strategic Partnership | Telemedicine platform integration with poison control centers accelerates rural chelation initiation decisions. |
| Geographic Expansion | Field-deployable chelation kit distribution to Amazon basin mining cooperatives addresses surveillance gaps. |
| Reimbursement Strategy | Outpatient chronic exposure protocol coverage expansion extends DMSA access beyond acute care settings. |
Research Methodology
Initial hypotheses were tested against primary input from hospital procurement managers, poison control center toxicologists, pharmaceutical regulatory affairs leads, and occupational health clinic directors and refined through secondary validation. FDA orphan drug filings, EPA enforcement databases, OSHA workplace exposure records, and hospital formulary databases anchored the quantitative foundation. Bottom-up patient volume estimates and top-down pharmaceutical revenue triangulation converged on segment-level projections.
Demand-supply-balance framing structured the analytical approach across the analysis window, with segmentation modeling across treatment severity tier, delivery mode, patient population, and regional regulatory cluster. CAGRs were derived from fitted growth curves applied to exposure incident trajectories and procurement volume trends. Biomarker testing adoption curves and telemedicine platform penetration rates informed chronic exposure protocol expansion assumptions.
Macroeconomic conditions sit as an overlay; deviation in industrial manufacturing output or environmental enforcement budgets would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory mandate continuity and API supply stability. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Sepsis Treatment Market
Medical Treatment
Congenital Hyperinsulinism Treatment Market
Medical Treatment
Menopause Treatment Market
Medical Treatment
Hypogonadism Treatment Market
Medical Treatment
Lysosomal Storage Disease Treatment Market
Medical Treatment
Influenza Treatment Market
Medical Treatment
Single Dose Radiotherapy Services Market
Medical Treatment
Hypothermia Management Market
Medical Treatment
Hepatocellular Carcinoma (HCC) Treatment Market
Medical Treatment
Global Hyperhidrosis Treatment Market
Medical Treatment
Hemorrhagic Shock Treatment Market
Medical Treatment
Acupuncture Treatment Market
Medical Treatment
Transarterial Chemoembolization (TACE) Market
Medical Treatment
Mesotherapy Market
Medical Treatment
Vaginitis Treatment Drugs Market
Medical Treatment
Cervical Cancer Treatment Market