
 Antibody-Mediated Rejection Prevention Market | 2026-2036
Antibody-Mediated Rejection Prevention Market Size, Share, and Industry Trends Forecast 2026-2036
Antibody-Mediated Rejection Prevention Market Outlook
Specialized immunology talent is unwinding bottlenecks in monoclonal antibody development for transplant indications. Roche Holding AG leverages its diagnostics-therapeutics integration to anchor clinical decision-making in rejection risk stratification. CSL Behring sustains plasma-derived immunoglobulin supply chains that dominate prophylactic protocols across major transplant programs. Hansa Biopharma competes through enzyme-based antibody clearance technology that differentiates its approach from conventional immunosuppression.
Antibody-mediated rejection prevention encompasses biologic and small-molecule interventions designed to neutralize donor-specific antibodies, deplete B-cell populations, or interrupt complement activation cascades prior to or following solid organ transplantation. These therapies typically target CD20, plasma cell proteasome pathways, or terminal complement components to preserve graft perfusion and function. Monoclonal antibodies command the largest revenue share due to established rituximab and basiliximab protocols, while intravenous immunoglobulin retains strong positioning in desensitization regimens for sensitized candidates. Hospital administration settings concentrate the highest procedure volumes, though outpatient clinics are capturing growing share as infusion protocols shorten and remote monitoring capabilities expand.
FDA guidance on immunosuppressive biologics shapes trial design and labeling requirements for new entrants, while EMA's MDR framework imposes post-market surveillance obligations that extend development timelines. The EU Green Deal's pharmaceutical manufacturing sustainability standards are pressuring plasma fractionation and biologic production facilities to retool energy and waste profiles. Stakeholders must monitor how evolving complement-targeting approvals in renal transplantation reshape competitive dynamics and payer positioning across major transplant markets.
Market Dynamics
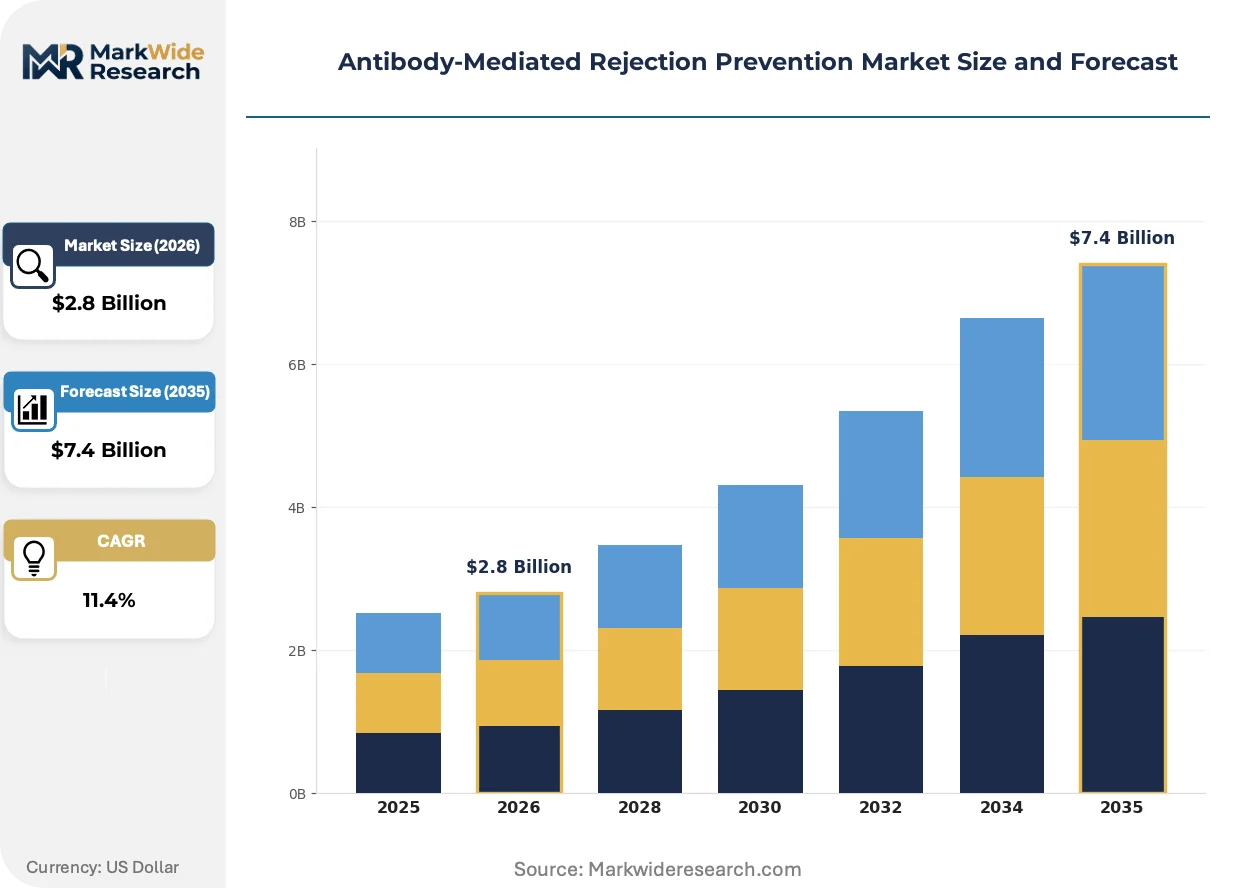
FDA's evolving guidance on immunosuppressive biologics is compressing development timelines for new entrants while transplant centers in Germany and the United States expand prophylactic protocols for high-risk graft recipients, reshaping competitive positioning across antibody-mediated rejection prevention.
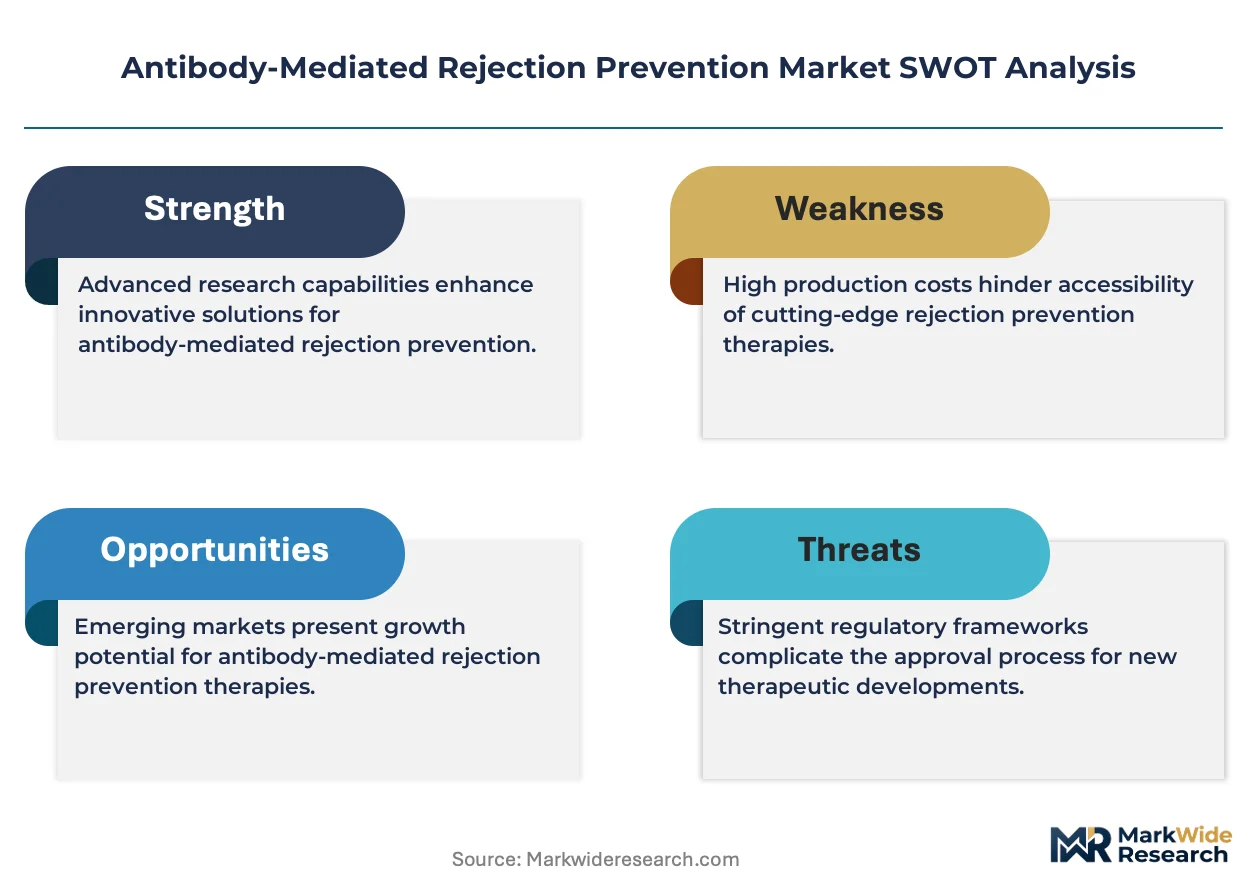
Growth Catalysts
- Specialized transplant networks:Germany's reimbursement clarity and integrated care models support earlier intervention protocols, accelerating adoption of biologic prophylaxis.
- Complement-targeting approvals:FDA pathways for terminal complement inhibitors in renal transplantation create regulatory momentum for pipeline assets.
- Enzyme-based antibody clearance:Novel immunoglobulin-degrading enzyme platforms differentiate therapeutic approaches from conventional B-cell depletion.
Market Restraints
- Plasma supply concentration:CSL Behring and limited fractionators control immunoglobulin raw material, creating vulnerability in desensitization regimen supply.
- EMA post-market surveillance:MDR framework obligations extend development timelines and raise compliance costs for biologic manufacturers.
- Rituximab biosimilar erosion:Patent expiry and biosimilar entry compress pricing power for established CD20 monoclonal antibody protocols.
Strategic Opportunities
- Outpatient infusion expansion:Shortened infusion protocols and remote monitoring capabilities shift administration from hospital to clinic settings.
- Heart transplant penetration:Underutilized prophylactic protocols in cardiac graft recipients represent expansion potential beyond dominant renal applications.
- EU Green Deal manufacturing incentives:Sustainability retooling requirements for plasma fractionation facilities favor capital-rich players with energy-efficient infrastructure.
Industry Challenges
- Monoclonal antibody development expertise:Scarce specialized immunology talent constrains pipeline advancement for transplant-specific indications.
- Diagnostics-therapeutics integration complexity:Rejection risk stratification platforms require harmonization with clinical decision workflows across heterogeneous transplant center IT systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Antibody-Mediated Rejection Prevention Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoclonal Antibodies, Intravenous Immunoglobulin, Proteasome Inhibitors, Other Immunosuppressants Delivery Mode: Subcutaneous, Intravenous, Oral, Transdermal Patient Demographics: Pediatric, Adult, Elderly, Transplant Recipients Administration Setting: Hospitals, Outpatient Clinics, Home Care, Long-term Care Facilities |
| Companies Covered | Roche Holding AG, Novartis AG, CSL Behring, Bristol-Myers Squibb, Sanofi, Hansa Biopharma, Pfizer, Alexion Pharmaceuticals, Talaris Therapeutics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Antibody-Mediated Rejection Prevention Market Strategic Shifts
Biologics development is fragmenting across multiple mechanistic pathways as complement inhibition, plasma cell proteasome targeting, and antibody clearance enzymes compete for protocol positioning. Three forces are reshaping how therapies reach transplant recipients.
Enzyme-based antibody clearance technology is fragmenting the traditional immunosuppression landscape by offering selective immunoglobulin depletion without broad B-cell suppression. High-sensitization transplant centers in Germany and the United States are piloting these protocols for incompatible graft candidates. The approach is compressing market share concentration among rituximab-dependent regimens by enabling shorter treatment courses.
EMA's MDR framework is tightening post-market surveillance obligations for immunosuppressive biologics, forcing manufacturers to expand pharmacovigilance infrastructure. Clinical trial designs now incorporate extended follow-up periods to satisfy safety monitoring requirements. Renal transplantation programs across Europe are experiencing delayed access to novel complement inhibitors as sponsors navigate expanded documentation.
Buyer concentration among integrated transplant networks is consolidating procurement decisions for biologic protocols. Large academic medical centers in the United States are negotiating multi-year supply agreements that bundle diagnostics with therapeutic products. This concentration is visible most acutely in high-volume kidney transplant programs where standardized protocols reduce formulary flexibility.
Antibody-Mediated Rejection Prevention Market Segmentation
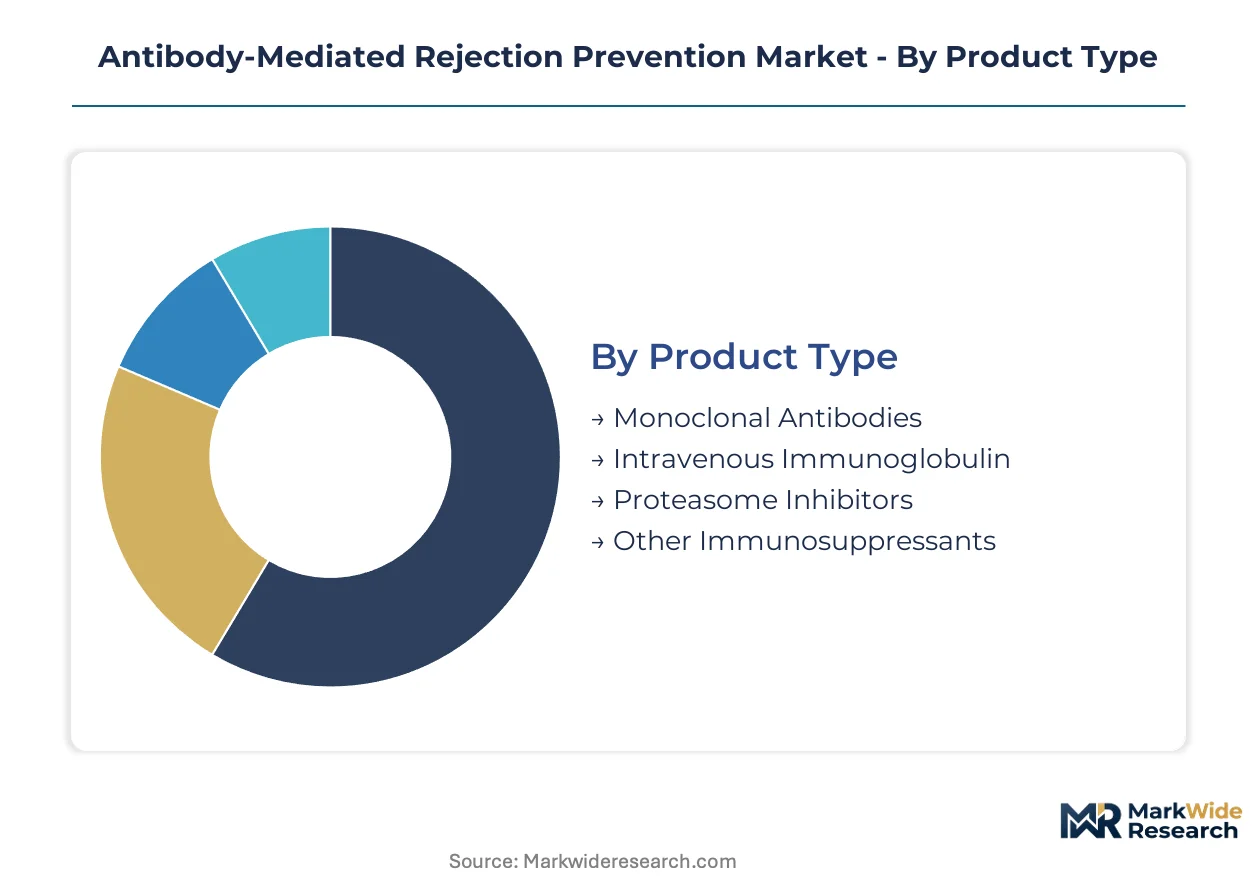
Antibody-mediated rejection prevention therapies fragment across mechanistic classes, delivery technologies, and care settings. Each segmentation axis reveals distinct procurement patterns, reimbursement pathways, and competitive dynamics that shape commercial strategy.
Product Type:
Monoclonal antibodies dominate domestic hospital procurement in the United States and Germany, while intravenous immunoglobulin supply chains stretch across international plasma collection networks.
- Monoclonal Antibodies:Engineered immunoglobulins targeting CD20, IL-2 receptor alpha, or terminal complement components enable precise B-cell depletion or complement inhibition. Demand clusters in high-volume kidney transplant centers at Cleveland Clinic and Charité Berlin, where standardized rituximab and basiliximab protocols anchor desensitization regimens. Pricing pressure from biosimilar entry is compressing margins for originator products.
- Intravenous Immunoglobulin:Polyclonal antibody pools derived from plasma fractionation provide broad immunomodulation for sensitized transplant candidates. Supply concentrates in CSL Behring's Australian and US collection infrastructure, creating geographic vulnerability for European transplant programs dependent on imported finished product. FDA lot-release requirements extend lead times for prophylactic protocol stocking.
- Proteasome Inhibitors:Small-molecule agents disrupting plasma cell antibody production through 26S proteasome inhibition.
- Other Immunosuppressants:Enzymatic immunoglobulin-degrading platforms and emerging complement-targeting biologics outside established categories.
Monoclonal antibodies hold the largest share; momentum sits with proteasome inhibitors as cardiac transplant penetration expands.
Delivery Mode:
Cost tiering separates hospital-based infusion therapies from emerging self-administration formats that shift economic burden to outpatient benefit design.
- Intravenous:Hospital-administered infusion requiring specialized nursing and adverse event monitoring. Centers at Massachusetts General and Heidelberg University Hospital capture economies through high-throughput infusion suites. EMA's MDR framework imposes device-therapy combination requirements that extend validation timelines for novel delivery systems.
- Subcutaneous:Self-administered or clinic-based injection reducing facility overhead and enabling remote patient management. Adoption accelerates in German integrated care networks where reimbursement bundles favor reduced hospital day utilization. Formulation stability challenges limit biologic applicability.
- Oral:Small-molecule immunosuppressants enabling patient-controlled dosing.
- Transdermal:Emerging patch-based delivery for continuous low-dose immunomodulation.
Intravenous administration retains volume leadership; subcutaneous formats are climbing the fastest as outpatient protocols mature.
Patient Demographics:
Application intensity varies sharply across age brackets, with pediatric protocols commanding premium pricing and elderly populations driving volume through expanded transplant eligibility.
- Adult:Prime-age transplant recipients aged 18-64 constitute the procedural volume base. US centers at Emory and Stanford standardize complement inhibitor protocols for this cohort, while German AOK and Barmer reimbursement frameworks cover biologic prophylaxis without prior authorization for sensitized candidates.
- Pediatric:Specialized dosing requirements and extended follow-up obligations concentrate demand in designated children's hospitals. Boston Children's and Cincinnati Children's maintain dedicated transplant immunology teams with protocol autonomy unavailable in general adult programs.
- Elderly:Expanding transplant eligibility above age 65.
- Transplant Recipients:Catch-all category capturing multi-organ and re-transplant populations.
Adult patients represent the largest addressable population; pediatric segments show the steepest expansion trajectory as infant heart transplant volumes rise.
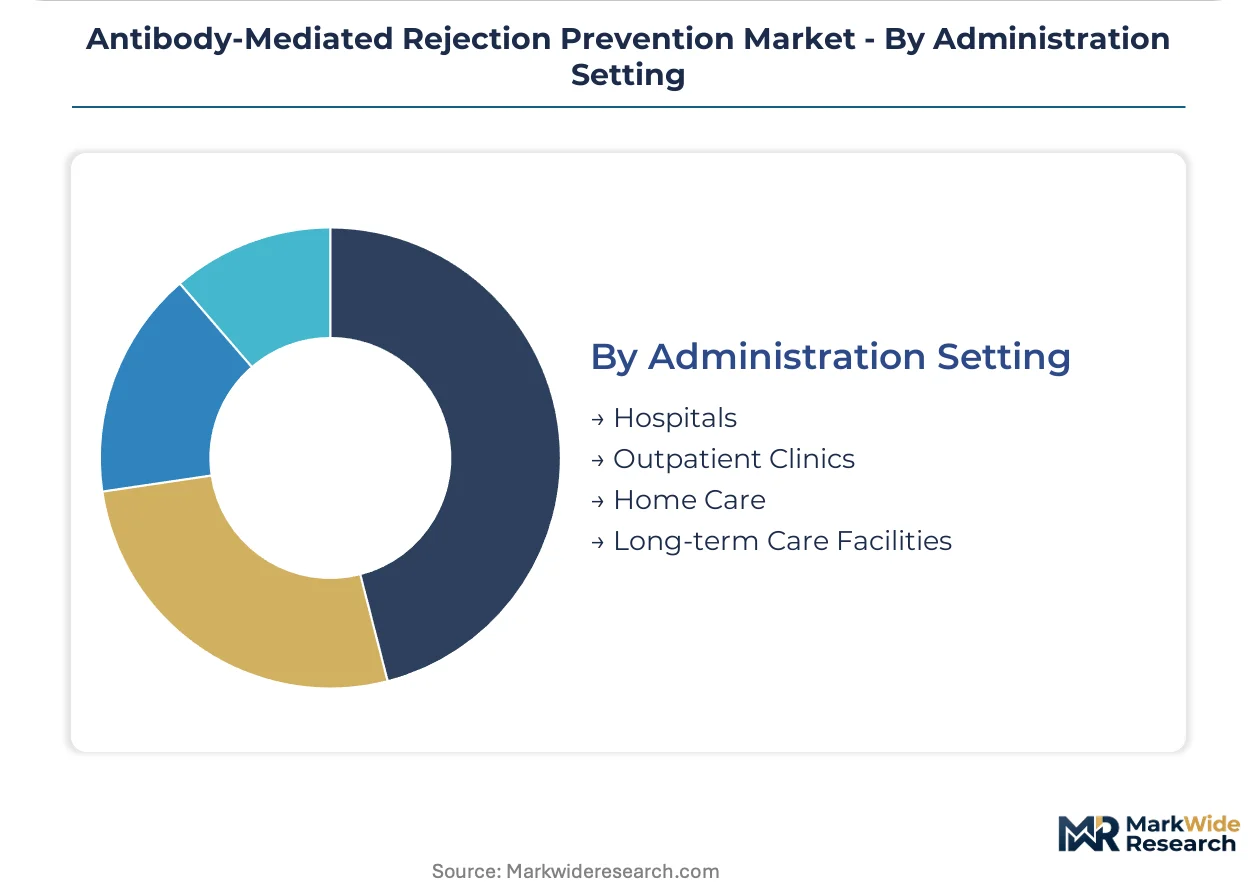
Administration Setting:
Customer type fragmentation pits hospital purchasing committees against outpatient clinic operators and home infusion vendors competing on total cost of care.
- Hospitals:Academic medical centers and transplant-focused community hospitals retain high-complexity induction therapy and acute rejection rescue. US News-ranked programs at Northwestern Memorial and Houston Methodist leverage case volume for formulary inclusion of novel complement inhibitors. Joint Commission transplant certification requirements mandate on-site pharmacy and infusion capabilities.
- Outpatient Clinics:Freestanding infusion centers and transplant clinic satellites capturing stable maintenance therapy. German ambulare Behandlungszentren exploit DRG-exempt status for biologic administration, while US Medicare Advantage plans drive site-of-care differentials favoring lower-cost clinic settings.
- Home Care:Nurse-supported residential infusion for selected low-risk regimens.
- Long-term Care Facilities:Skilled nursing settings for post-acute transplant recovery.
Hospitals retain the dominant share; outpatient clinics are gaining share fastest as infusion protocols shorten and remote monitoring capabilities mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Antibody-mediated rejection prevention therapies see divergent consumption patterns across major transplant markets. The United States concentrates prophylactic biologic use in high-volume academic centers, while Germany favors earlier intervention through integrated care reimbursement. Emerging markets in Asia-Pacific prioritize cost-containment over novel complement inhibitor adoption.
United States
FDA pathways for terminal complement inhibitors and rituximab biosimilar competition drive protocol evolution at Cleveland Clinic, Stanford, and Emory transplant centers. The agency's evolving guidance on immunosuppressive biologics compresses development timelines for new entrants. Massachusetts General and Houston Methodist anchor high-throughput infusion networks that standardize desensitization regimens.
Germany
Specialized transplant networks at Charité Berlin and Heidelberg University Hospital exploit reimbursement clarity from AOK and Barmer to deploy earlier biologic intervention. EMA's MDR framework imposes extended post-market surveillance obligations that delay novel therapy access. The country's DRG-exempt ambulare Behandlungszentren shift stable maintenance therapy from hospital to outpatient settings.
Japan
PMDA regulatory frameworks and aging transplant candidate demographics expand eligibility for sensitized recipient protocols. METI industrial policy supports domestic plasma fractionation capacity to reduce import dependency. Tokyo and Osaka academic medical centers pilot enzyme-based antibody clearance technologies for incompatible graft candidates.
United Kingdom
NICE technology appraisals and NHS England specialized commissioning constrain complement inhibitor adoption to designated high-risk cohorts. The MHRA post-Brexit regulatory autonomy enables accelerated access pathways for transplant immunology innovations. London transplant clusters at Guy's and St Thomas' NHS Foundation Trust concentrate pediatric heart transplant volumes requiring dedicated immunology teams.
Australia
TGA approval pathways and PBAC reimbursement assessments create lag times for novel biologic prophylaxis compared to US and EU access. The country's national transplant registry generates long-term outcome data that shapes protocol standardization. Sydney and Melbourne transplant programs maintain captive plasma-derived immunoglobulin reserves to buffer supply chain disruptions.
Antibody-Mediated Rejection Prevention Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in antibody-mediated rejection prevention. Large-cap pharmaceutical and biotechnology corporations with diagnostics-therapeutics integration or plasma fractionation infrastructure command procurement relationships with major transplant networks. Mid-tier specialists compete through enzyme-based antibody clearance platforms or complement-targeting biologics. Dominant competitive moves include strategic partnerships to bundle diagnostics with therapeutic products and geographic expansion into German integrated care networks.
Among integrated biopharmaceutical conglomerates, Roche Holding AG and Novartis AG occupy positions defined by diagnostics-therapeutics integration and established immunology portfolios. CSL Behring represents the plasma-derived supply chain archetype with fractionation infrastructure anchoring immunoglobulin availability. Hansa Biopharma sits within the specialist tier, exemplifying enzyme-based technology differentiation from conventional B-cell depletion approaches.
| Leading Market Players |
|---|
| Roche Holding AG |
| Novartis AG |
| CSL Behring |
| Bristol-Myers Squibb |
| Sanofi |
| Hansa Biopharma |
| Pfizer |
| Alexion Pharmaceuticals |
| Talaris Therapeutics |
| Others |
Value Chain & Pricing Dynamics
Plasma fractionation scale economies at CSL Behring's Australian and US facilities anchor global immunoglobulin supply, creating concentrated pricing power that propagates through desensitization regimens and compresses margins for smaller biologic manufacturers unable to secure captive raw material access.
Pricing Analysis
Long-term offtake contracts dominate procurement between major transplant centers and plasma fractionators, while spot purchasing for acute rejection rescue therapies introduces volatility into hospital pharmacy budgets. Price differentiation stems from FDA lot-release certification tiers and volume scale commitments negotiated by high-throughput programs at Cleveland Clinic and Charité Berlin. Cost compression in rituximab-originator products is intensifying because biosimilar entry erodes brand premiums. Pediatric transplant centers show least price sensitivity due to protocol rigidity, whereas German ambulare Behandlungszentren exploit DRG-exempt status to drive hardest bargain on maintenance therapy.
Supply Chain Analysis
Australia and the United States anchor plasma collection infrastructure, while Germany and Japan depend on imported finished immunoglobulin for desensitization protocols. Raw material dependencies center on source plasma volumes, fractionation capacity utilization, and cold-chain logistics networks. Single-source vulnerability concentrates in CSL Behring's collection infrastructure, exposing European programs to geographic disruption. Distribution runs through hospital-based pharmacy consignment for induction therapies, with outpatient clinic direct delivery expanding for stable maintenance regimens.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Antibody-mediated rejection prevention sits in early-cycle expansion as enzyme-based antibody clearance technologies displace conventional B-cell depletion protocols and transplant centers in Germany and the United States widen prophylactic eligibility criteria.
For Market Incumbents: Fortify plasma supply chain control through backward integration into collection infrastructure or long-term offtake agreements with fractionators, defending against enzyme-based platform substitution that threatens rituximab-dependent revenue streams. Deepen diagnostics-therapeutics bundling with transplant center IT systems to lock in formulary positioning ahead of complement inhibitor pipeline maturation. For New Entrants and Emerging Players: Differentiate on mechanistic novelty—complement inhibition or selective immunoglobulin degradation—rather than me-too CD20 targeting. White-space opportunity concentrates in cardiac transplant prophylaxis, where standardized protocols lag renal applications. Go-to-market angle should prioritize German integrated care networks with reimbursement clarity for earlier intervention. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors platform companies with diagnostics-therapeutics integration or enzyme-based clearance intellectual property over single-asset biologics developers. Long-term viability hinges on FDA guidance evolution for immunosuppressive biologics and EMA MDR compliance infrastructure. Signal to watch: complement inhibitor approval velocity in renal transplantation reshaping competitive dynamics.| Strategic Initiative | Industry Significance |
|---|---|
| Plasma Collection Infrastructure Expansion | Captive source plasma access insulates CSL Behring from supply disruption affecting European transplant programs. |
| Complement Inhibitor Clinical Advancement | FDA pathway momentum for terminal complement blockade reshapes protocol standardization at high-volume US centers. |
| Enzyme Platform Regulatory Submission | Hansa Biopharma's immunoglobulin-degrading enzyme differentiation from rituximab creates new therapeutic category. |
| Diagnostics-Therapeutics Integration | Roche's rejection risk stratification platforms embed therapeutic decision-making in transplant center workflows. |
| Outpatient Infusion Network Buildout | German ambulare Behandlungszentren exploit DRG-exempt status to shift administration from hospital settings. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases to construct bottom-up demand estimates and top-down market sizing for antibody-mediated rejection prevention therapies. Primary interviews engaged transplant immunologists, hospital pharmacy directors, payer access specialists, and plasma fractionation executives across the United States, Germany, and Japan. Secondary validation incorporated hospital procurement database analysis, GPO contract terms, and CMS Medicare reimbursement schedules.
Segmentation dimensions modeled span product type, delivery mode, patient demographics, and administration setting, with mechanistic class and regional regulatory cluster as industry-specific stratifiers. CAGRs derive from procedure volume projections, protocol penetration assumptions, and pricing trajectory analysis across the projection horizon. Forecast inputs incorporate transplant center expansion plans, biosimilar entry timelines, and evolving FDA guidance on immunosuppressive biologics.
Material uncertainties—regulatory approval delays, plasma supply disruptions, and complement inhibitor safety signals—sit outside the modeled envelope. Forecasts reflect assumptions about protocol standardization velocity and reimbursement stability in German integrated care networks. Recalibration cycles align with material shifts in FDA guidance releases and EMA MDR enforcement patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Research
Health Economics and Outcomes Research (HEOR) Services Market
Medical Research
Europe Induced Pluripotent Stem Cells (Ipscs) Market
Medical Research
Organoids and Spheroids Market
Medical Research
Epigenomics Market
Medical Research
Malaria Vaccine Market
Medical Research
Placenta Market
Medical Research
Global Patient Derived Xenograft Models Market
Medical Research
AAV Contract Development and Manufacturing Organizations Market
Medical Research
Clinical Genomics Market
Medical Research
Global Mice Model Market
Medical Research
Lab Automation in Drug Discovery Market
Medical Research
Mice Model Technologies Market
Medical Research
US Academic Medical Centers Market
Medical Research
Metabolomics Market
Medical Research
Medical Device Contract Research Organization Market
Medical Research
Global in Vitro Lung Model Market