
 Histiocytosis Treatment Market | 2026-2036
Histiocytosis Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Histiocytosis Treatment Market Foresight
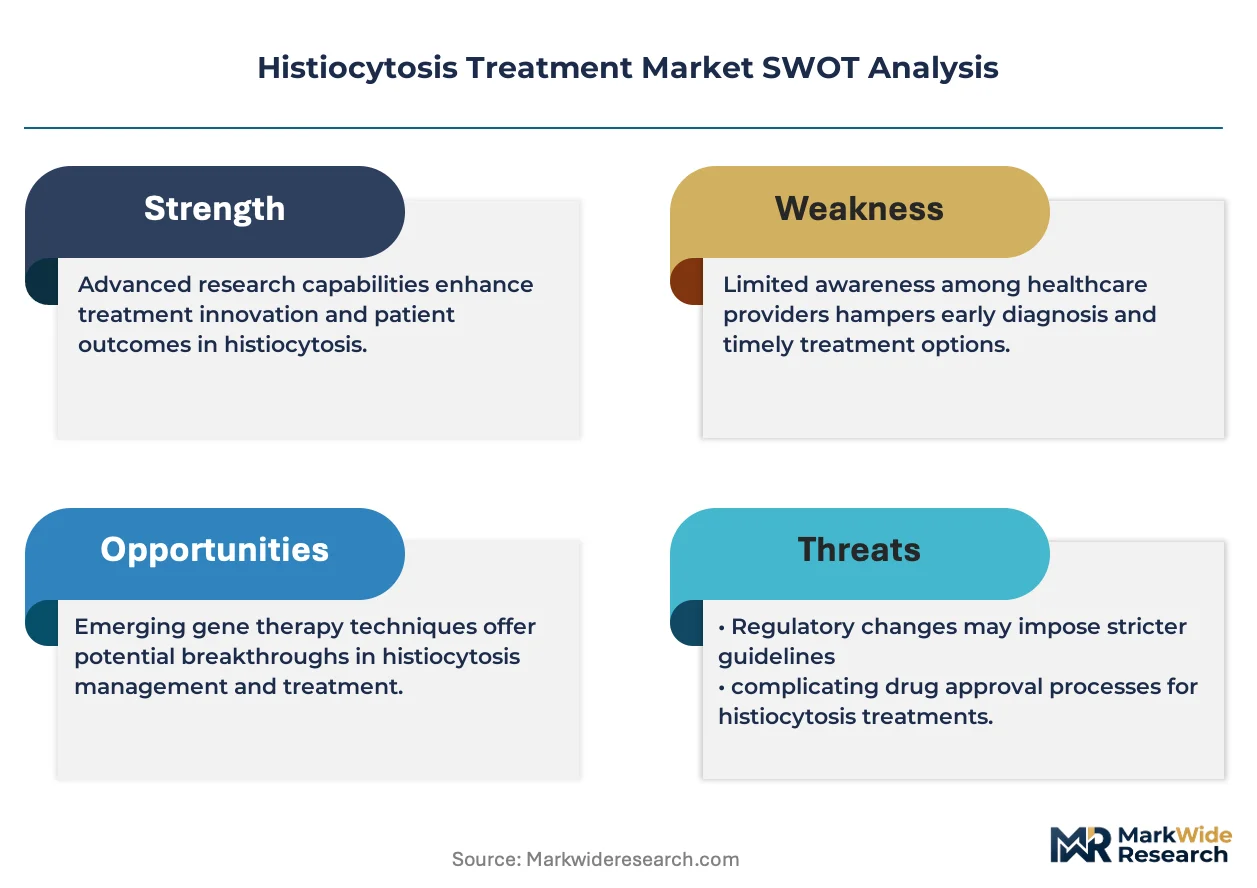
Orphan drug designation is broadening the cost-of-entry calculus for developers targeting rare histiocytosis subtypes. Pfizer Inc. leverages its global manufacturing scale to sustain supply continuity across pediatric and adult indications. Novartis AG differentiates through targeted therapy specialization in hematologic malignancies with overlapping pathways. Roche Holding AG anchors its position via diagnostic-therapeutic integration in histiocytic disorder management.
Histiocytosis treatment encompasses pharmacologic interventions targeting clonal proliferation of dendritic cell or macrophage lineages, including cladribine, vemurafenib for BRAF-mutant disease, and emapalumab for interferon-gamma neutralization in hemophagocytic lymphohistiocytosis. These therapies modulate cytokine signaling, immune checkpoint activity, or oncogenic kinase drivers to control tissue infiltration and systemic inflammation. Monoclonal antibodies command premium positioning due to targeted mechanism and orphan pricing dynamics, while chemotherapy agents retain volume share in first-line Langerhans cell protocols. Intravenous administration dominates hospital-based delivery, though subcutaneous formulations are gaining traction in home healthcare settings as infusion infrastructure expands.
FDA orphan drug incentives, EMA's PRIME designation pathway, and Japan's SAKIGAKE system collectively shape clinical development priorities and reimbursement negotiations for histiocytosis therapies. Regulatory frameworks mandate pediatric investigation plans and real-world evidence collection, extending trial timelines but securing market exclusivity buffers. Stakeholders must monitor biomarker-defined subset approvals and companion diagnostic co-development requirements as precision indications fragment addressable populations.
Market Dynamics
Orphan drug economics are compressing development timelines for histiocytosis therapies while fragmenting addressable patient populations into biomarker-defined subsets. The FDA's seven-year market exclusivity provision is accelerating sponsor investment in rare disease indications despite enrollment constraints.
Growth Catalysts
- EMA PRIME Designation:European regulators fast-track histiocytosis therapies through accelerated assessment, shortening time-to-reimbursement negotiations in Germany and France.
- Companion Diagnostic Co-Development:BRAF mutation testing platforms are expanding addressable populations for targeted kinase inhibitors across pediatric oncology centers.
- Japan SAKIGAKE System:PMDA priority review incentives are drawing multinational sponsors into early Japanese market entry for hemophagocytic lymphohistiocytosis therapies.
Market Restraints
- Plasma-Derived Input Volatility:Immunoglobulin supply constraints are elevating production costs for antibody-based histiocytosis interventions.
- Single-Site Manufacturing Concentration:Biologic fill-finish capacity in Switzerland and Ireland creates geographic vulnerability for monoclonal antibody supply continuity.
- Small Cohort Trial Design:FDA-mandated pediatric investigation plans extend clinical development timelines beyond standard oncology paradigms.
Strategic Opportunities
- Subcutaneous Formulation Expansion:Home healthcare infusion infrastructure in the United States is enabling outpatient administration of previously hospital-bound biologics.
- Real-World Evidence Pathways:FDA's expanded access programs are creating post-approval data collection frameworks that support label expansion into adult indications.
- Diagnostic-Therapeutic Bundling:Integrated BRAF testing and vemurafenib prescribing protocols are capturing margin across the care continuum in specialized histiocytosis centers.
Industry Challenges
- Pediatric Trial Recruitment:Ultra-rare disease prevalence is stretching site activation timelines across North American and European academic medical centers.
- Multi-Region Regulatory Synchronization:Divergent FDA and EMA requirements for biomarker validation are duplicating analytical development expenditures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Histiocytosis Treatment Market |
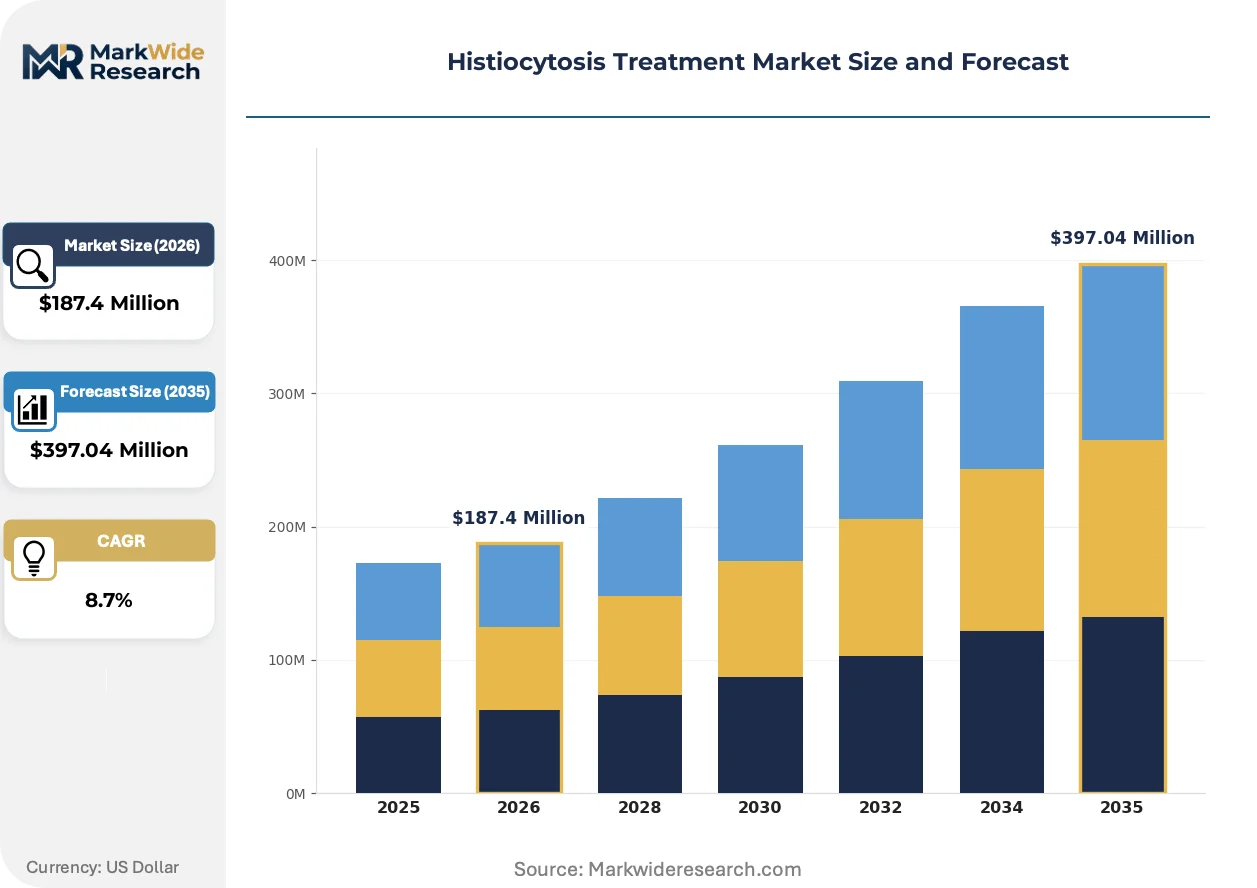
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoclonal Antibodies, Chemotherapy Agents, Targeted Therapies, Immunomodulators Administration Route: Intravenous, Subcutaneous, Oral, Intramuscular End User: Hospitals, Specialty Clinics, Home Healthcare, Research Institutions Disease Indication: Langerhans Cell Histiocytosis, Hemophagocytic Lymphohistiocytosis, Erdheim-Chester Disease, Others |
| Companies Covered | SOBI, Sanofi, Pfizer Inc., Novartis AG, Amgen Inc., Merck & Co., Inc., Roche Holding AG, Johnson & Johnson, Eli Lilly and Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Histiocytosis Treatment Market Shifts & Advancements
Precision medicine architectures are fragmenting histiocytosis treatment protocols into lineage-specific pathways. Biomarker stratification is displacing empirical chemotherapy selection across referral networks.
Next-generation sequencing panels are integrating BRAF, MAP2K1, and ARAF mutation detection into standard diagnostic workups for Langerhans cell histiocytosis. Pediatric hematology-oncology departments at Memorial Sloan Kettering and St. Jude Children's Research Hospital are deploying these platforms within 48-hour turnaround windows. The technology is integrating molecular stratification into first-line treatment decisions, compressing time-to-targeted therapy initiation.
REACH authorization requirements in the European Union are mandating enhanced pharmacovigilance for cladribine and other cytotoxic agents used in histiocytosis protocols. EMA's extended safety reporting obligations are elevating post-market surveillance costs for sponsors operating across Germany, France, and Italy. Adult Erdheim-Chester disease populations are experiencing delayed access as manufacturers prioritize pediatric indication submissions to satisfy regulatory incentives.
Consolidated procurement by integrated delivery networks is replacing individual hospital purchasing for high-cost biologics. Texas Children's Hospital and Boston Children's Hospital are negotiating multi-year emapalumab supply agreements with outcomes-linked pricing provisions. This concentration is most visible in the United States, where three national pediatric oncology consortia now control majority volume for orphan-designated histiocytosis therapies.
Histiocytosis Treatment Market Segmentation
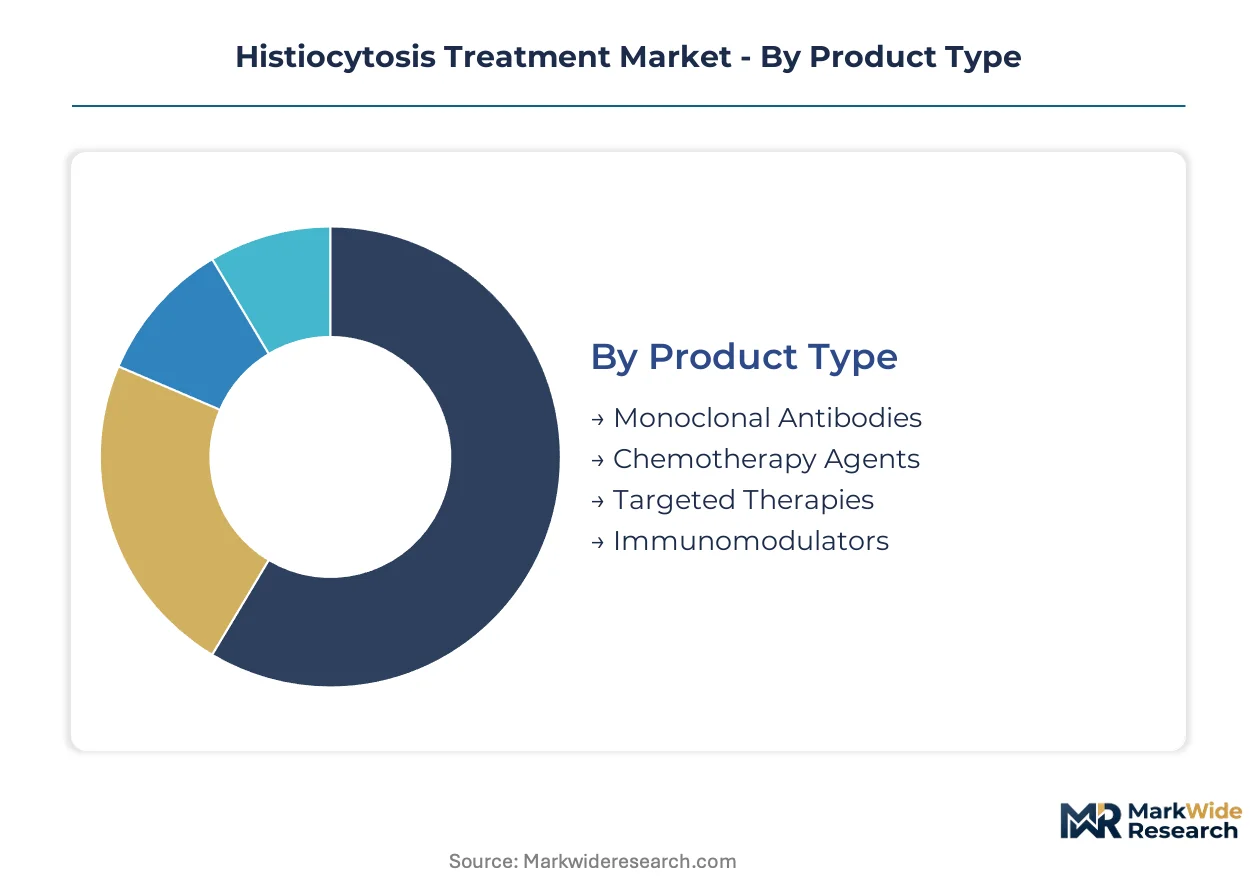
Histiocytosis treatment segmentation reflects divergent clinical priorities across pediatric and adult populations, with therapy selection driven by lineage specificity, biomarker status, and site-of-care capabilities. Understanding these partitions reveals where pricing power concentrates and which administration innovations are reshaping competitive positioning.
Product Type:
Cost tier separates institutional buyers, with premium biologics commanding dedicated procurement committees while commoditized agents flow through standard pharmacy formularies.
- Monoclonal Antibodies:Emapalumab and analogous interferon-gamma neutralizing biologics require cold-chain distribution and specialized infusion nursing. Memorial Sloan Kettering and Texas Children's Hospital anchor demand through dedicated histiocytosis protocols, though plasma-derived input volatility is elevating manufacturing costs.
- Chemotherapy Agents:Cladribine and cytarabine retain volume share in first-line Langerhans cell protocols despite biomarker-driven displacement. REACH authorization mandates in the European Union are elevating pharmacovigilance expenditures for cytotoxic sponsors.
- Targeted Therapies:Vemurafenib for BRAF-mutant disease requires companion diagnostic co-development.
- Immunomodulators:Cytokine modulation agents address hemophagocytic lymphohistiocytosis inflammation cascades.
Monoclonal antibodies lead volumes today; targeted therapies are gaining share fastest.
Administration Route:
Application context determines route selection, with hospital capacity constraints pushing subcutaneous adoption and patient mobility preferences driving oral formulation development.
- Intravenous:Hospital-based delivery dominates biologic administration, requiring infusion center staffing and adverse event monitoring infrastructure. Boston Children's Hospital and St. Jude Children's Research Hospital maintain dedicated pediatric oncology infusion suites.
- Subcutaneous:Home healthcare infrastructure expansion in the United States is enabling outpatient administration of previously hospital-bound therapies. Texas Children's Hospital negotiates multi-year supply agreements with outcomes-linked pricing for take-home biologics.
- Oral:Vemurafenib and small-molecule kinase inhibitors offer ambulatory convenience.
- Intramuscular:Limited application for depot immunomodulator formulations.
Intravenous administration anchors current revenue; subcutaneous delivery is climbing the fastest.
End User:
Customer type stratifies purchasing sophistication, with integrated delivery networks consolidating procurement for high-cost biologics while research institutions drive early adoption of experimental protocols.
- Hospitals:Academic medical centers anchor histiocytosis care through multidisciplinary tumor boards and molecular stratification capabilities. Three national pediatric oncology consortia in the United States now control majority volume for orphan-designated therapies.
- Specialty Clinics:Referral networks in Germany and Japan are consolidating around specialized histiocytosis centers with diagnostic-therapeutic integration.
- Home Healthcare:Infusion nursing services expand access to subcutaneous biologics.
- Research Institutions:Early-phase trial sites drive protocol development and biomarker validation.
Hospitals capture the dominant revenue share; home healthcare is expanding most quickly.
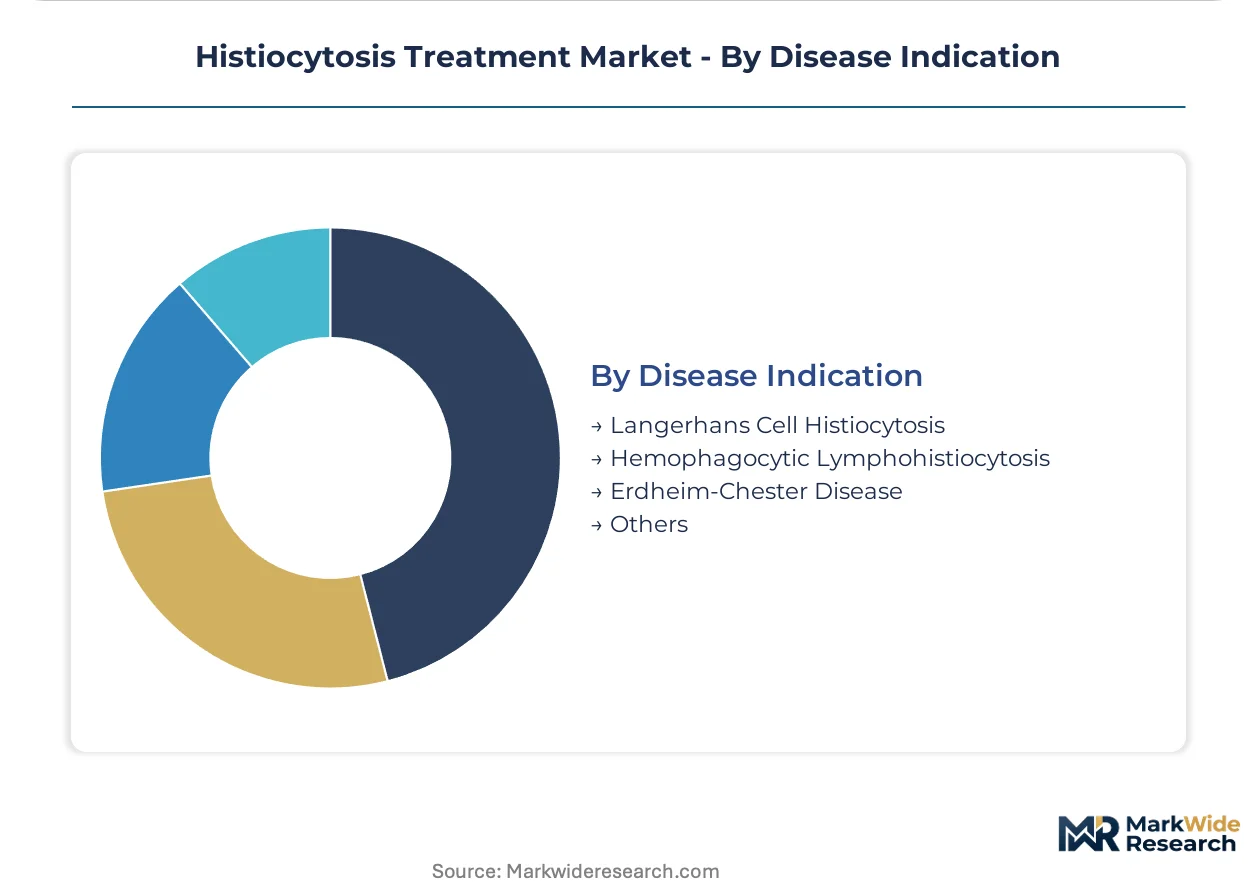
Disease Indication:
Maturity gradient separates established protocols from emerging indications, with Langerhans cell histiocytosis offering defined treatment pathways while Erdheim-Chester disease experiences delayed access due to pediatric prioritization.
- Langerhans Cell Histiocytosis:Next-generation sequencing panels integrating BRAF, MAP2K1, and ARAF detection are standardizing diagnostic workups. Pediatric hematology-oncology departments deploy 48-hour turnaround molecular stratification.
- Hemophagocytic Lymphohistiocytosis:Emapalumab approval has established interferon-gamma neutralization as standard-of-care, with Japan's SAKIGAKE system drawing multinational sponsors into early market entry.
- Erdheim-Chester Disease:Adult populations face access delays as manufacturers prioritize pediatric submissions for regulatory incentives.
- Others:Rare histiocytic disorders including juvenile xanthogranuloma and Rosai-Dorfman disease lack standardized protocols.
Langerhans cell histiocytosis leads treatment volumes today; hemophagocytic lymphohistiocytosis is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pediatric oncology specialists cluster in academic medical centers across the United States, Germany, and Japan, anchoring demand for orphan-designated histiocytosis therapies.
United States
Memorial Sloan Kettering, Texas Children's Hospital, and Boston Children's Hospital anchor North American demand through dedicated histiocytosis protocols. FDA orphan drug designation provides seven-year market exclusivity and tax credits for clinical trial expenditures. Three national pediatric oncology consortia now control majority procurement volume for biologic therapies.
Germany
Referral networks consolidate around specialized histiocytosis centers in Berlin, Munich, and Hamburg with diagnostic-therapeutic integration. EMA PRIME designation accelerates assessment timelines and shortens reimbursement negotiations with statutory health insurers. The country's hematology-oncology departments deploy next-generation sequencing panels within 48-hour turnaround windows.
Japan
PMDA's SAKIGAKE priority review system draws multinational sponsors into early market entry for hemophagocytic lymphohistiocytosis therapies. Tokyo and Osaka academic medical centers anchor Asia-Pacific demand through pediatric hematology specialization. Domestic regulatory incentives compress development timelines relative to standard oncology paradigms.
United Kingdom
London's Great Ormond Street Hospital and Manchester University NHS Foundation Trust anchor national referral networks for rare histiocytic disorders. MHRA recognition of EMA marketing authorizations streamlines access pathways for BRAF-targeted therapies. Integrated care systems in England consolidate procurement for high-cost biologics through specialized commissioning arrangements.
Switzerland
Swissmedic's accelerated access pathway supports early availability for therapies targeting ultra-rare histiocytosis subtypes. Basel and Zurich pharmaceutical clusters concentrate biologic fill-finish capacity for monoclonal antibody supply. The country's pediatric oncology centers participate in multinational trials through the Swiss Pediatric Oncology Group network.
Histiocytosis Treatment Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the histiocytosis treatment landscape. The vendor base spans multinational pharmaceutical corporations with hematology-oncology portfolios and biotechnology firms concentrated on rare disease indications. Three strategic archetypes dominate: large-cap diversifieds leveraging global manufacturing scale, mid-cap targeted therapy specialists, and emerging biotechs pursuing biomarker-defined subsets. Competitive moves center on companion diagnostic co-development partnerships and subcutaneous formulation expansion into home healthcare channels.
Among large-cap diversifieds, Pfizer Inc. and Novartis AG occupy positions reflecting global manufacturing infrastructure and targeted therapy specialization respectively. Roche Holding AG anchors the diagnostic-therapeutic integration archetype through molecular testing platform development. These three entities exemplify how scale, specialization, and vertical integration into companion diagnostics define competitive positioning in orphan-designated histiocytosis indications.
| Leading Market Players |
|---|
| SOBI |
| Sanofi |
| Pfizer Inc. |
| Novartis AG |
| Amgen Inc. |
| Merck & Co., Inc. |
| Roche Holding AG |
| Johnson & Johnson |
| Eli Lilly and Company |
| Others |
Supply & Pricing Matrix
Plasma protein pricing volatility cascades through monoclonal antibody production into three-tier cost structures across hospital procurement tiers. Cold-chain distribution requirements and fill-finish capacity constraints in Switzerland and Ireland amplify price stratification between academic medical centers and community hospitals.
Pricing Analysis
Bundled diagnostic-therapeutic protocols command premium positioning against unbundled chemotherapy regimens in Langerhans cell histiocytosis care. Three-tier pricing structure across premium biologics, standard targeted therapies, and economy chemotherapy agents reflects orphan drug exclusivity windows and manufacturing scale constraints. Pricing pressure stems from plasma-derived input scarcity elevating immunoglobulin-based therapy costs. Pediatric oncology consortia exhibit lowest price sensitivity due to outcomes-linked contracting, while independent community hospitals face acute budget compression.
Supply Chain Analysis
Regional distribution centers in Basel, Dublin, and Singapore anchor hub-and-spoke cold-chain networks for biologic therapies. Manufacturing concentration in Switzerland and Ireland draws from US and Australian plasma collection networks and German chemical synthesis clusters. Single-site fill-finish vulnerability creates geographic risk exposure for monoclonal antibody continuity. Distribution runs through specialized hospital pharmacy channels with direct-to-site cold-chain logistics bypassing wholesale intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Histiocytosis treatment functions as a regulatory compounder where FDA orphan drug designation and EMA PRIME pathways compound pricing power and exclusivity buffers for developers.
For Market Incumbents: Anticipate biomarker-defined subset fragmentation eroding empirical chemotherapy volumes by deepening companion diagnostic partnerships and securing exclusive BRAF testing platform alliances. Lock in multi-year supply agreements with Texas Children's Hospital and Memorial Sloan Kettering before pediatric oncology consortia consolidate procurement further. Counter plasma input volatility through backward integration into plasma collection networks or long-term fractionation contracts.
For New Entrants and Emerging Players: The premium-economy price gap in subcutaneous biologics creates white-space opportunity for home healthcare infusion services and outpatient administration platforms. Target Erdheim-Chester disease adult populations facing access delays from pediatric-prioritized sponsors. Penetrate through real-world evidence generation partnerships with St. Jude Children's Research Hospital and Swiss Pediatric Oncology Group trial networks.
For Investors and Strategic Acquirers: Consolidation pressure builds where biotechs with validated biomarker platforms lack commercial infrastructure to capture orphan pricing premiums. Frame five-to-ten-year viability around regulatory exclusivity runway and companion diagnostic co-development depth. Target acquisition candidates with SAKIGAKE or PRIME designations pending. Monitor FDA pediatric investigation plan completion rates as inflection signal for label expansion timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Co-Development | BRAF testing integration with vemurafenib prescribing captures margin across Memorial Sloan Kettering care pathways. |
| Subcutaneous Formulation Expansion | Home healthcare infrastructure enables Texas Children's Hospital outpatient administration of previously hospital-bound biologics. |
| Real-World Evidence Pathway Investment | FDA expanded access programs support label expansion into adult Erdheim-Chester disease indications. |
| Plasma Supply Security Agreement | Long-term fractionation contracts with CSL Behring or Takeda buffer immunoglobulin-based therapy cost volatility. |
| Pediatric Oncology Consortium Partnership | Three national US consortia now control majority volume for orphan-designated histiocytosis therapies. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Bottom-up patient flow modeling and top-down revenue triangulation anchored market size estimation.
Segment-weighting approaches applied treatment line, administration route, disease indication, and regional regulatory cluster dimensions across the projection horizon. CAGRs derived from epidemiological prevalence projections, therapy penetration curves, and pricing trajectory assumptions. Forecast inputs incorporated orphan drug exclusivity timelines, biomarker testing adoption rates, and plasma supply elasticity parameters.
Caveats apply where regulatory approval delays, biomarker platform validation failures, or plasma supply disruptions could materially shift the outlook. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Europe Nerve Repair and Regeneration Market
Medical Treatment
Radiation Therapy Market
Medical Treatment
Gunshot Injuries Treatment Market
Medical Treatment
Asthma Treatment Market
Medical Treatment
Hereditary Amyloidosis Treatment Market
Medical Treatment
Filariasis Treatment Market
Medical Treatment
Vulvodynia Treatment Market
Medical Treatment
Ascites Market
Medical Treatment
Corneal Transplant Market
Medical Treatment
Allergic Rhinitis Treatment Market
Medical Treatment
Tinea Pedis Treatment Market
Medical Treatment
Encephalitis Treatment Market
Medical Treatment
Nasal Allergy Treatment Market
Medical Treatment
Hypercoagulability Treatment Market
Medical Treatment
Leprosy Treatment Market
Medical Treatment
Histoplasmosis Treatment Market