
 Seropositive Rheumatoid Arthritis Treatment Market | 2026-2036
Seropositive Rheumatoid Arthritis Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Seropositive Rheumatoid Arthritis Treatment Market Analytics
Hospital infusion centers is rebalancing toward home care and specialty pharmacy channels as self-injectable biologics reduce site-of-care requirements. AbbVie Inc. dominates the adalimumab biosimilar defense with formulation patents and citrate-free delivery improvements. Pfizer, Inc. leverages its tofacitinib portfolio across oral JAK inhibition while competing in IL-6 receptor antagonism with biosimilar readiness. Eli Lilly and Company anchors its position through baricitinib expansion into earlier lines of therapy and comorbidity indications.
Seropositive rheumatoid arthritis treatment encompasses pharmaceutical interventions directed at patients with rheumatoid factor or anti-citrullinated protein antibody positivity, characterized by more aggressive joint erosion and systemic inflammation than seronegative subsets, with biologics and targeted synthetic DMARDs designed to interrupt cytokine signaling or immune cell activation. Biologics command the deepest margin pools due to manufacturing complexity and patent-protein structures, while DMARDs sustain volume leadership as first-line anchors. Injection delivery modes are capturing the fastest growth as subcutaneous formulations displace intravenous infusion for TNF-alpha and IL-6 inhibitors. Oral JAK inhibitors occupy a structural middle ground, bridging convenience gaps between conventional DMARDs and biologic injections.
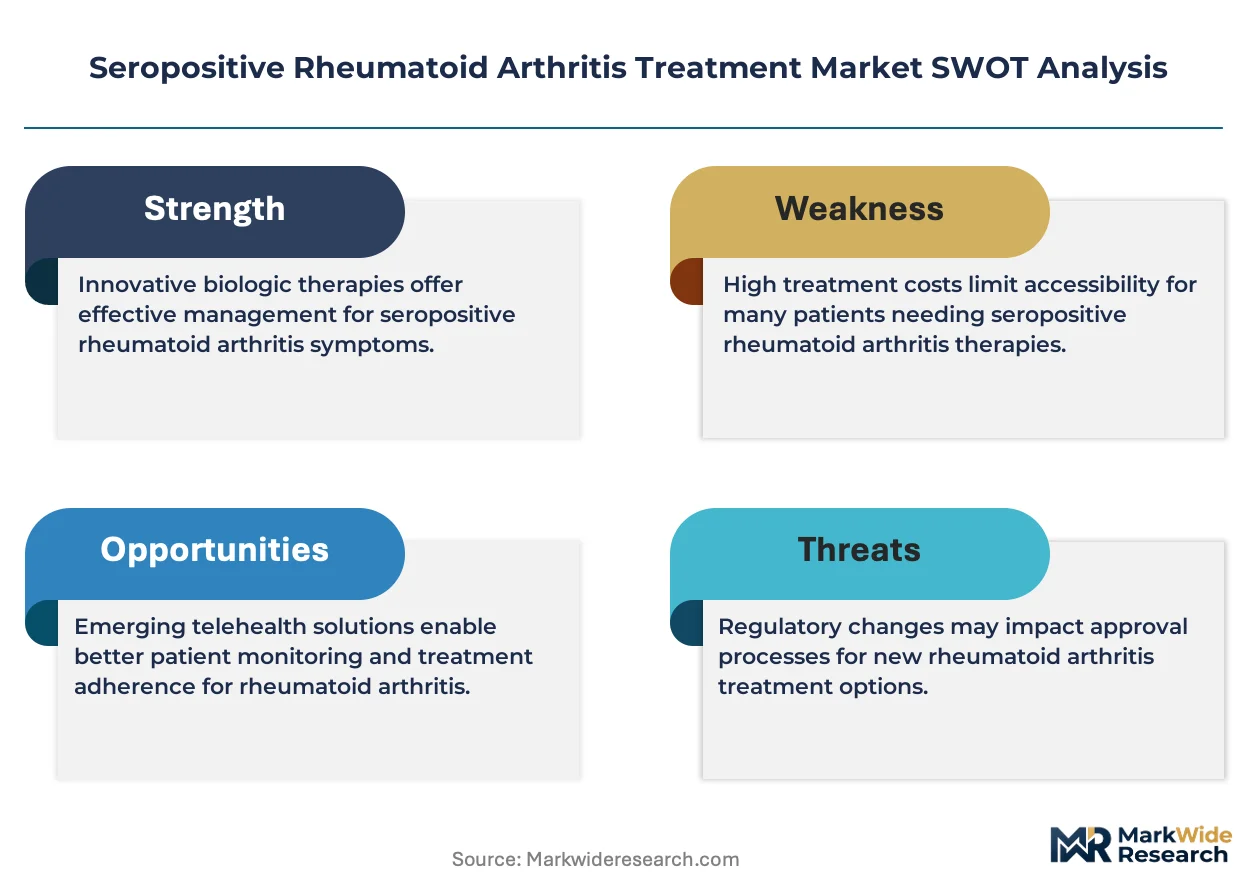
FDA biosimilar review standards, EMA immunogenicity guidance, and WHO prequalification pathways collectively shape product development timelines and interchangeability acceptance across major markets. The FDA's IRA Medicare price negotiation provisions for selected biologics will compress realized pricing for originator molecules reaching negotiation eligibility. Stakeholders must monitor pipeline positioning against biosimilar entry waves and regulatory divergence on JAK inhibitor cardiovascular warnings to calibrate portfolio and geographic prioritization.
Market Dynamics
The migration from hospital-based infusion to self-administered subcutaneous biologics is compressing site-of-care economics and redistributing margin capture toward specialty pharmacy networks and home health infrastructure.
Growth Catalysts
- FDA Biosimilar Pathway:Accelerated approval frameworks for interchangeable biologics are expanding physician prescribing comfort and payer formulary flexibility across United States commercial and Medicare channels.
- IL-6 Inhibitor Expansion:Extended indications for tocilizumab-class therapies into cardiovascular comorbidity management are opening parallel revenue streams beyond joint protection endpoints.
- Japan's Aging Rheumatology Population:Concentrated seropositive prevalence among patients over 65 is driving demand for oral JAK alternatives to injection-based regimens in Tokyo and Osaka metropolitan clusters.
Market Restraints
- Biologic Manufacturing Concentration:Single-source dependence on Chinese contract manufacturing organizations for active pharmaceutical ingredients creates supply vulnerability during geopolitical trade friction.
- JAK Inhibitor Cardiovascular Black Box:FDA-mandated warnings for thromboembolic events are constraining first-line prescribing enthusiasm and triggering prior authorization complexity.
- Reference Pricing Compression:European Union cross-border therapeutic reference frameworks are capping reimbursement ceilings for originator TNF-alpha inhibitors in Germany and France.
Strategic Opportunities
- India's Biosimilar Export Capacity:CDSCO-aligned manufacturing facilities in Hyderabad and Bangalore are positioning for WHO prequalification to supply emerging markets with adalimumab and rituximab alternatives.
- Digital Therapeutic Adjuvants:Convergence of remote patient monitoring platforms with subcutaneous injection devices is enabling adherence tracking and dosing optimization.
- Early-Line Therapy Expansion:EMA guidance supporting JAK inhibitor use before methotrexate failure is creating regulatory tailwind for oral therapy penetration in Nordic and Benelux markets.
Industry Challenges
- Immunogenicity Surveillance Infrastructure:Post-market anti-drug antibody monitoring requires specialized laboratory capacity that remains concentrated in academic medical centers.
- Cold Chain Integrity at Last Mile:Temperature excursion risk during specialty pharmacy delivery to patient homes demands redundant packaging investment and real-time tracking systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Seropositive Rheumatoid Arthritis Treatment Market |
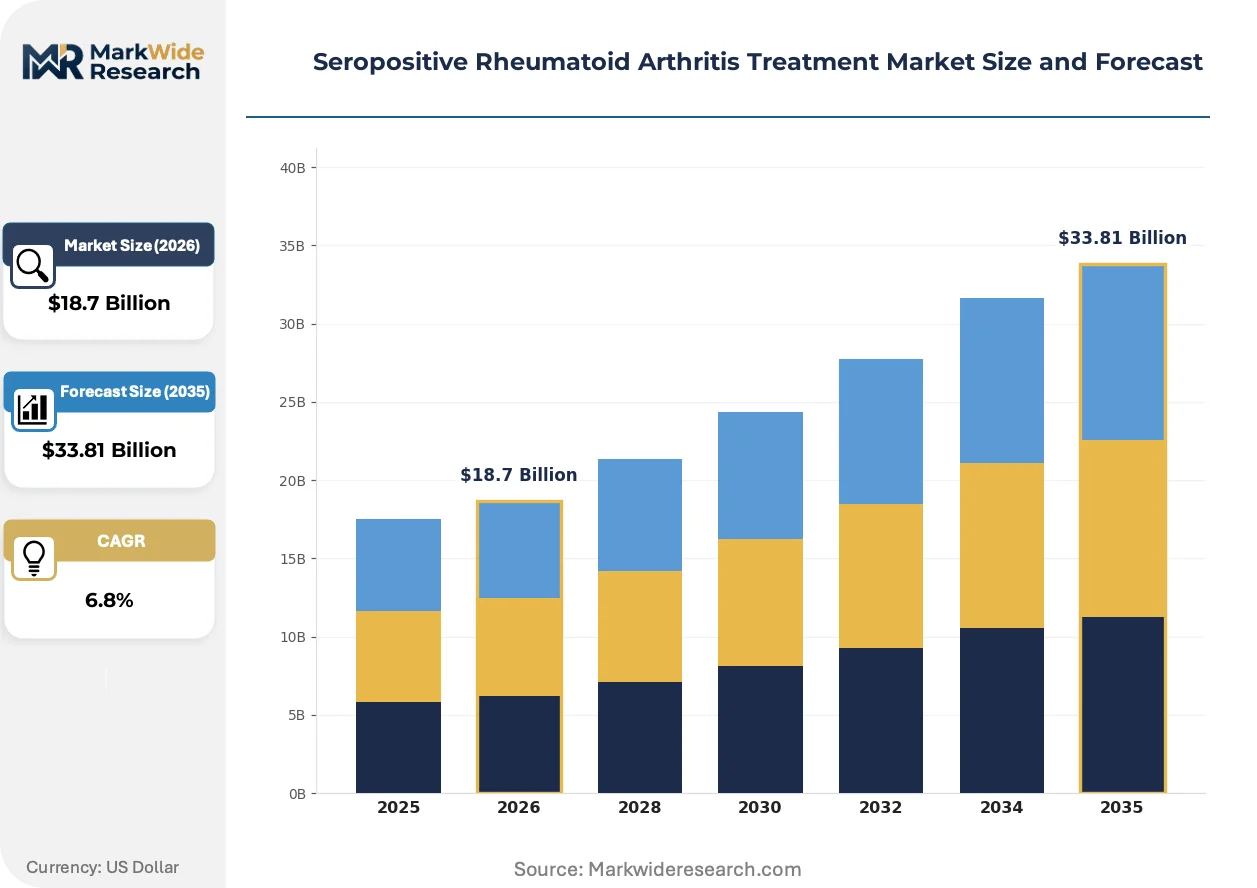
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biologics, DMARDs, NSAIDs, Corticosteroids Therapy Area: Immunosuppressants, Targeted Therapies, Pain Management, Disease Modifying Agents Delivery Mode: Oral, Injection, Infusion, Topical End User: Hospitals, Clinics, Home Care, Specialty Pharmacies |
| Companies Covered | Abbott Laboratories, Johnson & Johnson Limited, Novartis AG, Pfizer, Inc., Eli Lilly and Company, AbbVie Inc., Bristol-Myers Squibb Company, F. Hoffmann-La Roche Ltd., Amgen, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Seropositive Rheumatoid Arthritis Treatment Market Evolving Landscape
Biologic delivery systems are fragmenting the traditional infusion center model while regulatory convergence on biosimilar interchangeability accelerates competitive substitution dynamics across developed markets.
Subcutaneous auto-injector platforms are modularizing the administration experience for TNF-alpha and IL-6 inhibitors. Rheumatology practices in the United States and Germany are adopting these devices at pace exceeding intravenous protocol decline. This technology is modularizing patient visit schedules and compressing site-of-care revenue per patient episode.
EMA immunogenicity guidance updates are harmonizing post-approval safety surveillance requirements across European Union member states. Manufacturers must now standardize anti-drug antibody testing protocols for biosimilar comparability studies. Biologics seeking interchangeability designation in France and Italy face the steepest compliance adaptation timelines.
Specialty pharmacy direct-to-patient distribution is displacing wholesale-to-hospital procurement for self-injectable biologics. United States payers are mandating exclusive specialty pharmacy networks that bypass traditional hospital outpatient pharmacies. This channel migration concentrates fulfillment volume with CVS Caremark, Express Scripts, and OptumRx in metropolitan corridors.
Seropositive Rheumatoid Arthritis Treatment Market Segmentation
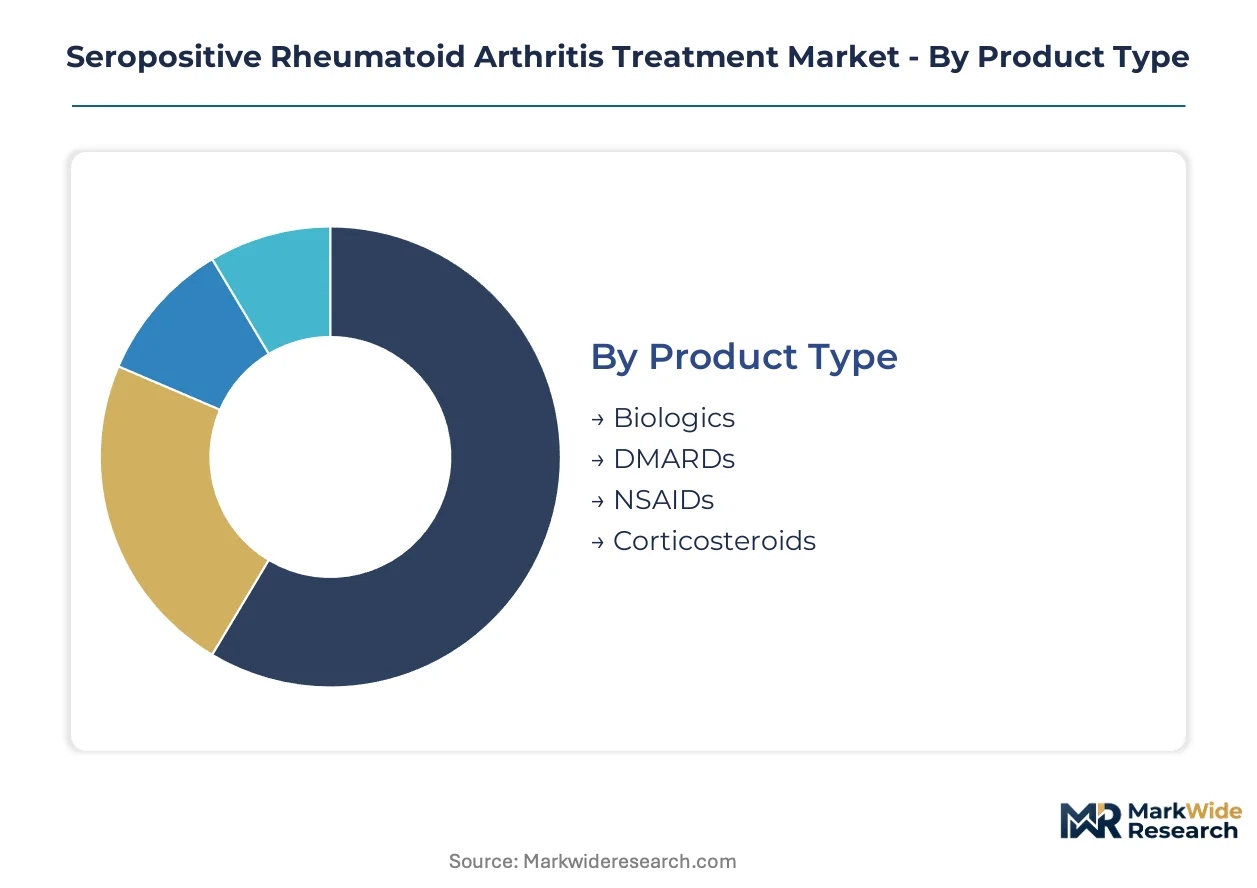
Segmentation in seropositive rheumatoid arthritis treatment reveals how regulatory pathways, site-of-care economics, and patient self-administration preferences partition commercial opportunity. Each dimension carries distinct certification burdens and margin structures that shape manufacturer portfolio prioritization.
Product Type:
FDA BLA approvals and EMA centralized marketing authorizations create tiered regulatory entry costs across molecular categories, with biologics facing the steepest immunogenicity surveillance requirements.
- Biologics:Monoclonal antibodies and fusion proteins targeting TNF-alpha, IL-6, and B-cell pathways require FDA biosimilar comparability studies or originator BLA pathways. Demand concentrates in the United States and Germany where rheumatologist density supports complex therapy initiation, though cold chain distribution constraints limit penetration in secondary Indian and Brazilian cities.
- DMARDs:Conventional synthetic disease-modifying antirheumatic drugs including methotrexate, sulfasalazine, and hydroxychloroquine operate under abbreviated FDA NDA or ANDA pathways. Volume leadership persists in Japan's aging metropolitan clusters and Medicare Part D formularies, where first-line protocol adherence and generic substitution economics sustain prescriber familiarity.
- NSAIDs:Non-steroidal anti-inflammatory drugs for symptom management carry OTC and prescription-tier FDA labeling distinctions.
- Corticosteroids:Oral and intra-articular glucocorticoid formulations bridge to biologic therapy with established pharmacovigilance profiles.
Leading the category by volume: DMARDs. Growing fastest: Biologics.
Therapy Area:
Mechanism-of-action clustering determines prescriber training intensity and payer prior authorization complexity, with targeted therapies demanding specialized rheumatology expertise.
- Targeted Therapies:JAK inhibitors and biologic DMARDs interrupt specific cytokine signaling or immune cell activation pathways. Demand concentrates in United States commercial payers and Germany's statutory health insurance system, where step-therapy protocols and cardiovascular risk stratification for tofacitinib-class molecules shape prescribing sequences.
- Immunosuppressants:Calcineurin inhibitors and antimetabolites broadly suppress immune response without molecular specificity. Volume persists in India's tier-2 hospital clusters and Latin American public procurement systems where cost containment overrides precision targeting.
- Pain Management:Analgesic and anti-inflammatory adjuncts address symptomatic relief without disease modification.
- Disease Modifying Agents:Encompasses both conventional and targeted therapies with structural joint protection endpoints.
Category leadership by revenue: Targeted Therapies. Steepest expansion trajectory: Targeted Therapies.
Delivery Mode:
Administration route selection directly determines site-of-care economics, patient adherence infrastructure, and specialty pharmacy channel capture.
- Injection:Subcutaneous auto-injector and pre-filled syringe formulations for TNF-alpha and IL-6 inhibitors enable home administration. Demand concentrates in United States specialty pharmacy networks and German home health programs, where patient training and remote monitoring platforms reduce infusion center dependency.
- Oral:Small-molecule JAK inhibitors and conventional DMARDs eliminate cold chain requirements and enable retail pharmacy dispensing. Volume leadership holds in Japan's elderly patient population and Medicare Part D enrollment, where needle avoidance and dosing convenience drive preference.
- Infusion:Intravenous biologic administration in controlled clinical settings.
- Topical:Localized NSAID and corticosteroid delivery for limited joint involvement.
Highest volume: Oral. Climbing the fastest: Injection.
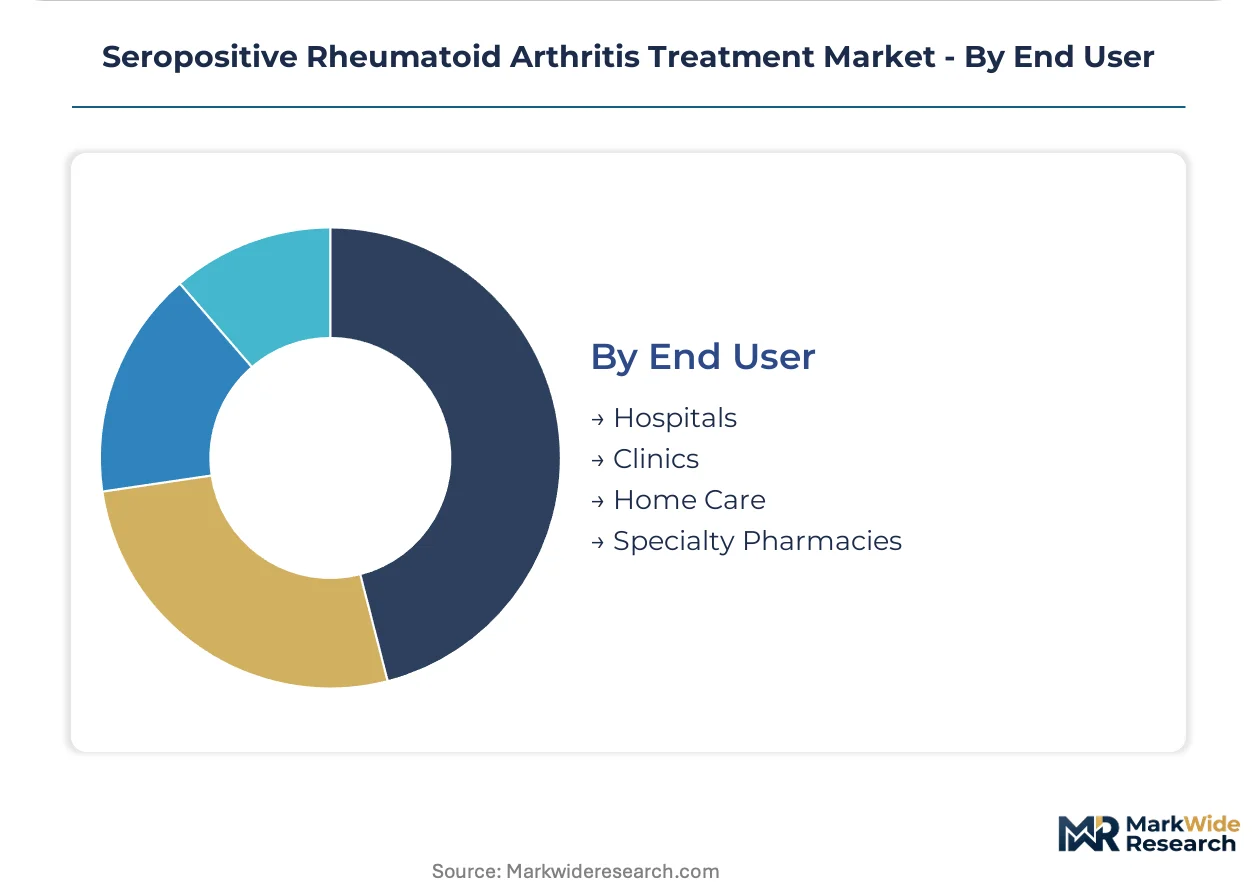
End User:
Channel configuration dictates procurement contracting structures, with site-of-care migration reshaping margin distribution between institutional and ambulatory settings.
- Specialty Pharmacies:CVS Caremark, Express Scripts, and OptumRx networks manage biologic dispensing, patient education, and adherence monitoring for self-injectable therapies. Demand concentrates in United States metropolitan corridors where payer-mandated exclusive networks bypass hospital outpatient pharmacies.
- Hospitals:Academic medical centers and community hospital infusion centers retain intravenous biologic administration and complex case management. Volume persists in Germany's integrated care contracts and Japan's rheumatology referral hierarchies, where comorbidity complexity requires multidisciplinary coordination.
- Home Care:Nursing-supported administration and patient self-management programs.
- Clinics:Private rheumatology practices and ambulatory care centers.
Dominant by patient volume: Hospitals. Gaining share fastest: Specialty Pharmacies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity for biologic active pharmaceutical ingredients concentrates in Chinese and Indian contract organizations, while consumption clusters in high-reimbursement markets with dense rheumatologist networks. This geographic split shapes regulatory compliance burdens and cold chain logistics investment across supply chains.
United States
Commercial payer density and Medicare Part D biologic coverage sustain the deepest market for TNF-alpha and IL-6 inhibitors. FDA biosimilar interchangeability guidance and IRA price negotiation provisions are compressing originator pricing timelines. The Boston-Cambridge corridor anchors biologic manufacturing R&D, while specialty pharmacy networks in New York and Los Angeles metropolitan areas capture dispensing volume from hospital outpatient migration.
Germany
Statutory health insurance reimbursement density and integrated care contracts for rheumatology sustain demand for JAK inhibitors and subcutaneous biologics. EMA centralized marketing authorizations and cross-border reference pricing frameworks cap originator TNF-alpha inhibitor ceilings. The Rhine-Ruhr and Munich clusters concentrate rheumatology academic centers and biosimilar prescribing adoption.
Japan
Aging demographics and concentrated seropositive prevalence among patients over 65 drive preference for oral JAK alternatives to injection regimens. PMDA regulatory pathways and post-market surveillance requirements shape biosimilar entry timelines. Tokyo and Osaka metropolitan areas anchor rheumatology referral hierarchies and home health infrastructure for self-administered therapies.
India
CDSCO-aligned manufacturing facilities in Hyderabad and Bangalore position for WHO prequalification to supply emerging markets with adalimumab and rituximab biosimilars. Domestic demand concentrates in tier-2 hospital clusters where cost containment overrides precision targeting. The country's national pharmaceutical regulator is streamlining abbreviated approval pathways for complex biologics.
United Kingdom
NICE technology appraisals and NHS England commissioning frameworks determine formulary access for biologic and targeted synthetic DMARDs. Post-Brexit divergence from EMA guidance is creating parallel regulatory compliance tracks for manufacturers. The London-Southeast corridor concentrates rheumatology academic centers and early-access programs for novel mechanisms.
Seropositive Rheumatoid Arthritis Treatment Market Competitive Landscape
Top-tier vendors anchor originator biologic development and defense, while mid-tier specialists and emerging biosimilar manufacturers capture share through manufacturing scale and regulatory agility. The structure consolidates around molecular platform ownership and formulation patent estates. Three archetypes dominate: integrated pharmaceutical conglomerates with rheumatology franchises, pure-play biologics specialists, and contract development organizations pivoting to branded biosimilars. Competitive moves concentrate on biosimilar litigation defense, subcutaneous delivery formulation improvements, and specialty pharmacy network exclusivity contracting.
Among integrated pharmaceutical conglomerates, AbbVie Inc., Pfizer, Inc., and Eli Lilly and Company occupy positions that exemplify divergent strategic postures. AbbVie anchors the adalimumab defense through formulation layering and citrate-free delivery improvements. Pfizer exemplifies dual-platform exposure across oral JAK inhibition and IL-6 biosimilar readiness. Eli Lilly represents baricitinib-lineage expansion into earlier therapy lines and comorbidity indications. These three structures illustrate how originator incumbents are calibrating between patent estate longevity, biosimilar competition timing, and oral-versus-injection portfolio balance.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Johnson & Johnson Limited |
| Novartis AG |
| Pfizer, Inc. |
| Eli Lilly and Company |
| AbbVie Inc. |
| Bristol-Myers Squibb Company |
| F. Hoffmann-La Roche Ltd. |
| Amgen |
| Others |
Value Network & Pricing Analysis
Private-equity-rolled-up specialty pharmacy networks have consolidated dispensing volume across United States metropolitan corridors, compressing procurement leverage for originator biologics while amplifying rebate extraction power that feeds back into manufacturer margin compression decisions.
Pricing Analysis
Margin tightening in originator TNF-alpha inhibitors reflects IRA Medicare price negotiation eligibility timelines and biosimilar entry waves. Pricing stratifies across originator biologics, interchangeable biosimilars, and non-interchangeable alternatives based on FDA designation tier and rheumatologist prescribing confidence. Cost-down pressure on hospital infusion centers accelerates as specialty pharmacy networks capture self-injectable volume. Medicare Part D enrollees exhibit highest price sensitivity; commercial payer populations with step-therapy exemptions show lowest.
Supply Chain Analysis
Regional distribution centers in Indianapolis, Memphis, and Louisville anchor cold chain logistics for temperature-sensitive biologics. Active pharmaceutical ingredient manufacturing concentrates in China, India, and South Korea. Cell culture media, single-use bioreactor bags, and purification resins constitute critical input dependencies. Single-source vulnerability for Chinese contract manufacturing organizations creates geopolitical exposure. Distribution runs through payer-mandated specialty pharmacy networks bypassing wholesale-to-hospital channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Subcutaneous auto-injector platforms are displacing intravenous infusion protocols, rendering legacy hospital-based site-of-care economics obsolete for TNF-alpha and IL-6 inhibitor administration.
For Market Incumbents: Lock in specialty pharmacy network exclusivity contracts before biosimilar interchangeability designations proliferate. Secure citrate-free formulation patents to defend adalimumab-class positioning against pending FDA biosimilar approvals. Backward integration into fill-finish capacity buffers Chinese API supply concentration risk. For New Entrants and Emerging Players: Launch via direct-to-patient specialty pharmacy partnerships targeting Japan's oral JAK inhibitor preference among elderly seropositive populations. India's CDSCO-aligned manufacturing clusters offer lowest regulatory entry cost for WHO-prequalified biosimilar exports. White-space penetration concentrates on Nordic markets where EMA guidance supports JAK inhibitor use before methotrexate failure. For Investors and Strategic Acquirers: Distressed-cycle entries favor contract development organizations with EMA immunogenicity surveillance capabilities in Germany's Rhine-Ruhr corridor. Long-term viability hinges on regulatory agility across divergent FDA and EMA interchangeability standards. Monitor PMDA biosimilar approval velocity as inflection signal for Asian market entry timing.| Strategic Initiative | Industry Significance |
|---|---|
| Specialty Pharmacy Network Exclusivity | Payer-mandated CVS Caremark and Express Scripts contracts concentrate dispensing volume away from hospital outpatient pharmacies. |
| Citrate-Free Formulation Patent Layering | AbbVie's delivery improvements extend adalimumab protection against FDA biosimilar pathway competitors. |
| EMA Immunogenicity Surveillance Compliance | Standardized anti-drug antibody protocols enable interchangeability designation in France and Italy markets. |
| Subcutaneous Auto-Injector Platform Development | Device modularization reduces rheumatology practice visit frequency and compresses site-of-care revenue per episode. |
| CDSCO-Aligned Manufacturing Scale-Up | Hyderabad and Bangalore facilities position for WHO prequalification to supply emerging markets with rituximab alternatives. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with rheumatology practice administrators, specialty pharmacy operations directors, payer formulary managers, and biologic manufacturing quality heads combined with FDA BLA submissions, EMA centralized marketing authorization documents, ClinicalTrials.gov entries, and Medicare Part D claims databases. Bottom-up patient population estimates and top-down reimbursement expenditure flows underwent triangulation validation.
Data-stream reconciliation across prescription audit channels, hospital procurement systems, and direct manufacturer reporting informed the analytical framework. Segmentation dimensions modeled include product molecular class, therapy mechanism of action, administration route, site-of-care channel, and regional regulatory cluster across the analysis window. CAGRs derived from patient prevalence projections, treatment penetration curves, and pricing trajectory assumptions. Forecast inputs incorporated rheumatologist density maps and biosimilar approval pipeline status.
Regulatory divergence on JAK inhibitor cardiovascular warnings, biosimilar interchangeability designation delays, and geopolitical trade friction affecting Chinese API supply are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions regarding physician prescribing behavior evolution and payer step-therapy protocol adoption. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Stereotactic Radiation Therapy Market
Medical Treatment
Amyloidosis Treatment Market
Medical Treatment
Neglected Tropical Disease Treatment Market
Medical Treatment
Penile Cancer Treatment Market
Medical Treatment
Nasal Allergy Treatment Market
Medical Treatment
Leprosy Treatment Market
Medical Treatment
Tauopathies Treatment Market
Medical Treatment
Peri-Implantitis Treatment Market
Medical Treatment
Familial Hypercholesterolemia Treatment Market
Medical Treatment
Nose Reconstruction Market
Medical Treatment
Peanut Allergy Treatment Market
Medical Treatment
Anti-Fungal Treatment Market
Medical Treatment
Radioimmunotherapy Treatment Market
Medical Treatment
Vulvovaginal Candidiasis Treatment Market
Medical Treatment
Global Leishmaniasis Treatment Market
Medical Treatment
Radiation Proctitis Treatment Market