
 Ligament Repair and Reconstruction Market | 2026-2036
Ligament Repair and Reconstruction Market Size, Share, and Industry Trends Forecast 2026-2036
Ligament Repair and Reconstruction Market Intelligence
Switzerland is narrowing its position as a precision manufacturing hub for synthetic ligament fibers. Arthrex, Inc. leverages vertically integrated arthroscopy instrument production to control surgical system bundling. Zimmer Biomet Holdings, Inc. anchors its European distribution through Basel-area logistics infrastructure. Smith+Nephew plc differentiates its portfolio with concentrated R&D spending on biodegradable scaffold architectures.
Ligament repair and reconstruction encompasses surgical restoration of torn or degenerated connective tissue using autografts, allografts, or synthetic substitutes engineered to withstand tensile loads exceeding 2,000 Newtons for anterior cruciate ligament applications. The primary purpose is restoring joint kinematic stability to prevent secondary osteoarthritis progression in active patient populations. Tendon allografts lead product type revenue due to established tissue banking networks and surgeon familiarity, while robot-assisted delivery mode segments capture expanding margin pools through capital equipment leasing models. Synthetic ligaments remain commercially immature outside sports medicine niches, though polymer science advances in polyethylene terephthalate braiding are narrowing performance gaps with biologic alternatives.
FDA 510(k) clearance requirements govern biologic implant commercialization in the United States, while EMA medical device regulation and MDR conformity assessment shape European market access timelines for suture anchor systems. ISO 13485 quality management certification functions as a baseline predicate for supplier qualification across OECD hospital procurement frameworks. Stakeholders must monitor evolving reimbursement coding for arthroscopic allograft procedures as payer evidence requirements tighten.
Market Dynamics
Synthetic ligament fiber manufacturing is concentrating in Switzerland and Germany as precision polymer braiding displaces traditional tendon harvesting, while FDA 510(k) clearance pathways compress product commercialization timelines for biologic implants.
Growth Catalysts
- Allograft utilization expansion:University hospital sports medicine programs are scaling tendon allograft volumes for ACL reconstruction, driven by established tissue banking networks and surgeon training standardization.
- FDA 510(k) streamlining:Biologic implant manufacturers benefit from abbreviated review pathways that reduce time-to-market for suture anchor systems and scaffold products in the United States.
- Polyethylene terephthalate braiding advances:Polymer science improvements in tensile load tolerance are narrowing performance gaps between synthetic ligaments and biologic alternatives for anterior cruciate ligament applications.
Market Restraints
- Allograft supply concentration:Tendon allograft volumes depend on specialized tissue banking networks concentrated in Germany and Switzerland, creating geographic vulnerability to supply disruptions.
- Synthetic ligament commercial immaturity:Polymer-based substitutes remain confined to sports medicine niches due to long-term biocompatibility data gaps and surgeon preference for autograft familiarity.
- EMA MDR conformity timelines:European suture anchor system approvals face extended assessment periods under Medical Device Regulation requirements, delaying market entry relative to FDA pathways.
Strategic Opportunities
- Robot-assisted delivery mode expansion:Capital equipment leasing models for surgical navigation systems capture margin pools beyond implant sales, particularly in high-volume orthopedic centers.
- Biodegradable scaffold R&D concentration:Concentrated research investment in absorbable polymer architectures offers differentiation for manufacturers seeking to displace permanent synthetic implants.
- Specialized orthopedic center penetration:Dedicated sports medicine facilities in Germany drive tendon allograft demand and create reference sites for technique adoption across Europe.
Industry Challenges
- ISO 13485 certification complexity:Quality management system implementation for supplier qualification across OECD hospital procurement frameworks demands sustained compliance investment.
- Reimbursement coding volatility:Payer evidence requirements for arthroscopic allograft procedures are tightening, requiring manufacturers to maintain clinical data generation capabilities.
- Surgeon training standardization gaps:Technique variation between autograft, allograft, and synthetic ligament implantation methods complicates product adoption curves and outcomes documentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ligament Repair and Reconstruction Market |
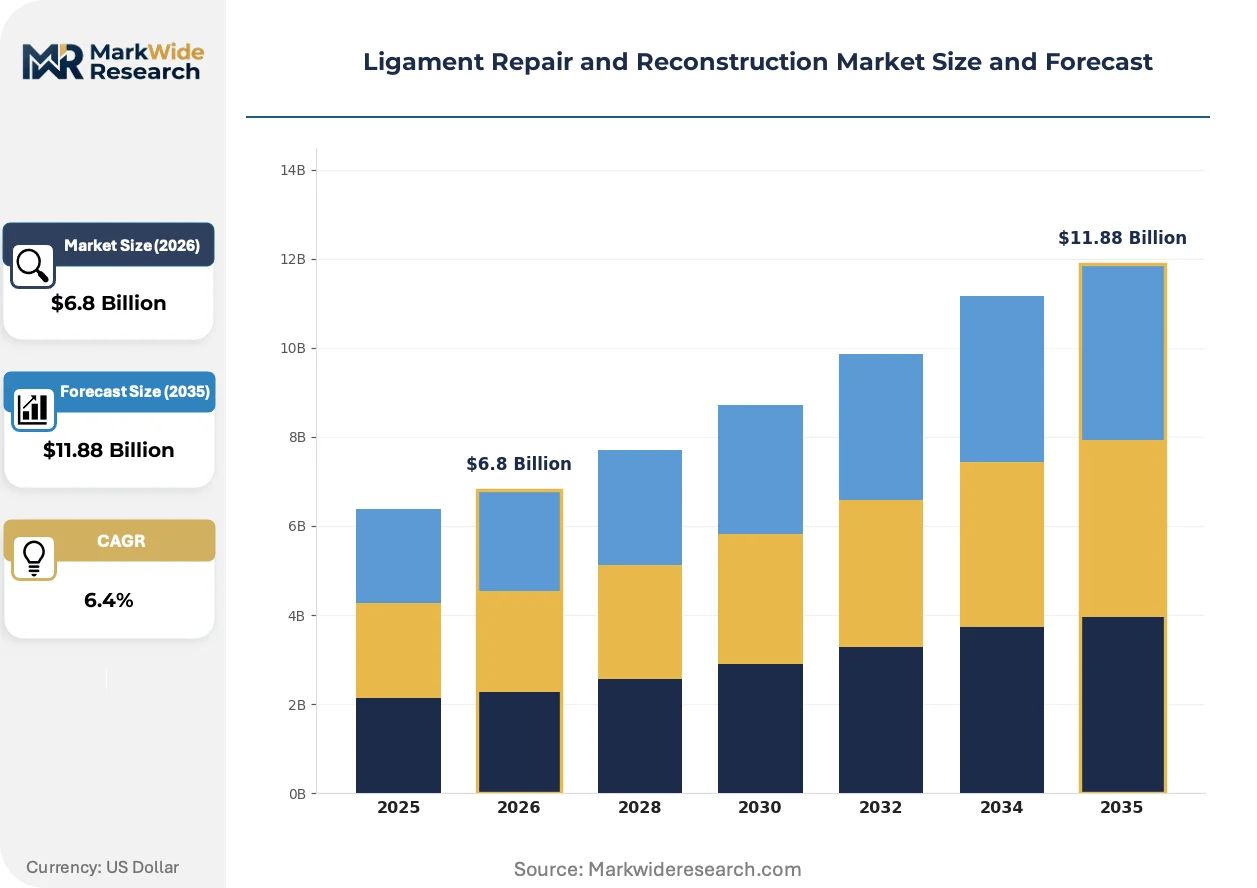
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.88 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bone Grafts, Tendon Allografts, Synthetic Ligaments, Scaffolds Application: Surgical Repair, Orthopedic, Sports Medicine, Trauma Delivery Mode: Open Surgery, Arthroscopy, Minimally Invasive, Robot-Assisted End User: Hospitals, Orthopedic Clinics, Sports Facilities, Rehabilitation Centers |
| Companies Covered | Johnson & Johnson (DePuy Synthes), CONMED Corporation, Arthrex, Inc., LifeNet Health, Medtronic plc, Stryker Corporation, Zimmer Biomet Holdings, Inc., RTI Surgical, Smith+Nephew plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ligament Repair and Reconstruction Market Strategic Shifts & Innovations
Preoperative surgical planning and intraoperative navigation systems are virtualizing traditional arthroscopic technique training, while regulatory frameworks on both sides of the Atlantic accelerate product lifecycle compression.
Computer-assisted surgical planning software is virtualizing conventional arthroscopy training methods by enabling three-dimensional joint modeling and implant trajectory simulation. Academic medical centers in Germany and Switzerland are deploying these systems for resident education and complex revision cases. This virtualization is compressing the learning curve for robot-assisted ligament reconstruction and reducing operative time variability among early-career surgeons.
EMA Medical Device Regulation conformity assessment procedures are extending review timelines for suture anchor systems and biologic scaffolds entering European markets. Manufacturers are responding by front-loading clinical evidence packages and establishing notified body relationships earlier in development cycles. The MDR transition most affects small-to-mid implant developers lacking legacy device grandfathering advantages.
Hospital procurement departments are consolidating orthopedic implant purchasing through specialty distributor networks rather than direct manufacturer contracts. German hospital systems and Swiss university hospitals are piloting consignment inventory models for high-cost tendon allografts and synthetic ligaments. This channel restructuring is most visible in centralized European procurement frameworks where volume aggregation offsets per-unit margin compression.
Ligament Repair and Reconstruction Market Segmentation
Segmentation in ligament repair and reconstruction reveals how tissue engineering maturity, surgical technique evolution, and care setting economics partition commercial opportunity. Understanding these divides helps manufacturers align R&D investment with reimbursement pathways and surgeon training requirements.
Product Type:
Mature tissue banking infrastructure contrasts with emerging polymer science platforms across this category.
- Tendon Allografts:Cadaver-derived connective tissue preserved through cryopreservation or freeze-drying protocols. German specialized orthopedic centers and university hospital sports medicine programs in Switzerland drive procurement volumes due to established tissue banking networks and surgeon familiarity with fixation techniques.
- Synthetic Ligaments:Braided polyethylene terephthalate constructs engineered to exceed 2,000 Newtons tensile load tolerance for anterior cruciate ligament applications. Sports medicine niches in Basel-area research clusters represent the primary adoption frontier as long-term biocompatibility datasets mature.
- Bone Grafts:Osteoconductive matrices harvested from autologous, allogeneic, or xenogeneic sources for tunnel fixation augmentation.
- Scaffolds:Biodegradable polymer architectures designed for cell infiltration and gradual mechanical load transfer.
Tendon allografts handle the majority of throughput; synthetic ligaments are expanding most quickly on share.
Application:
Volume concentration follows trauma incidence patterns while margin pools concentrate in elective procedure categories.
- Sports Medicine:Elective anterior cruciate ligament reconstruction in active patient populations seeking return-to-play outcomes. University hospital systems and dedicated sports facilities generate procedure volumes where robot-assisted navigation commands premium reimbursement.
- Orthopedic:Degenerative joint stabilization and revision reconstruction addressing secondary osteoarthritis progression. German hospital procurement frameworks and Swiss university hospitals aggregate demand through specialty distributor consignment models.
- Surgical Repair:Acute traumatic ligament disruption requiring immediate operative intervention.
- Trauma:Emergency department-initiated stabilization following high-energy injury mechanisms.
Sports medicine captures the steepest margin expansion; orthopedic applications provide the volume base.
Delivery Mode:
Capital intensity separates established technique categories from emerging platform investments.
- Arthroscopy:Endoscopic joint access through small-diameter portals enabling visualization-guided graft placement. High-volume orthopedic centers in Germany deploy these systems for resident training standardization and operative time compression.
- Robot-Assisted:Computer-navigated surgical navigation systems with haptic feedback and trajectory planning software. Capital equipment leasing models in Swiss university hospitals and German specialty centers capture margin pools beyond implant sales.
- Open Surgery:Traditional arthrotomy approaches for complex revision cases or multiligament reconstruction.
- Minimally Invasive:Percutaneous techniques reducing soft tissue disruption through specialized instrumentation.
Arthroscopy maintains procedure volume dominance; robot-assisted modalities are gaining share fastest through leasing penetration.
End User:
Procurement authority and reimbursement coding complexity stratify this category by care setting economics.
- Hospitals:Acute care facilities with centralized purchasing departments negotiating implant contracts through specialty distributor networks. German hospital systems pilot consignment inventory models for high-cost tendon allografts and synthetic ligaments.
- Orthopedic Clinics:Ambulatory surgery centers specializing in elective ligament reconstruction with streamlined FDA 510(k) cleared device utilization.
- Sports Facilities:On-site medical centers at professional and collegiate athletic programs with direct surgeon relationships.
- Rehabilitation Centers:Postoperative physical therapy providers influencing graft selection through outcomes data feedback.
Hospitals concentrate procurement volume; orthopedic clinics are climbing the fastest on procedure migration to outpatient settings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tissue banking infrastructure clusters in Central Europe while polymer science development concentrates in Swiss precision manufacturing corridors. FDA 510(k) pathways in the United States compress commercialization timelines relative to European Medical Device Regulation assessments.
United States
University hospital sports medicine programs drive tendon allograft procurement volumes through established tissue banking networks. FDA 510(k) clearance pathways streamline biologic implant commercialization for suture anchor systems and scaffold products. The Boston-Cambridge corridor anchors specialized orthopedic research centers developing computer-assisted surgical navigation.
Germany
Specialized orthopedic centers in Bavaria and North Rhine-Westphalia generate concentrated demand for tendon allograft volumes in ACL reconstruction procedures. EMA Medical Device Regulation conformity assessments govern suture anchor system approvals with extended review timelines. The Basel-area logistics infrastructure supports Zimmer Biomet's European distribution hub for implant consignment models.
Switzerland
Precision polymer braiding capabilities for synthetic ligament fibers concentrate around Basel and Zurich research clusters. Swissmedic regulates biologic implant commercialization with quality management requirements aligned to ISO 13485 certification baselines. Swiss university hospitals pilot capital equipment leasing models for robot-assisted surgical navigation systems.
United Kingdom
NHS procurement frameworks aggregate orthopedic implant purchasing through specialty distributor networks rather than direct manufacturer contracts. MHRA oversees medical device regulation with post-Brexit divergence from EMA MDR timelines creating approval complexity. London teaching hospitals drive resident training standardization for arthroscopic technique virtualization.
Japan
PMDA regulates biologic scaffold and synthetic ligament commercialization with clinical evidence requirements exceeding FDA pathways. The Kanto region around Tokyo concentrates sports medicine facilities serving aging active populations seeking joint stabilization. METI industrial policy supports domestic polymer science research for orthopedic applications.
Ligament Repair and Reconstruction Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in the value chain. The vendor base stratifies across diversified orthopedic conglomerates, specialized arthroscopy instrument manufacturers, and tissue banking service providers. Three archetypes dominate: vertically integrated surgical system bundlers, precision polymer science developers, and tissue banking network operators. Competitive moves concentrate on strategic partnerships for distribution access and portfolio diversification into biodegradable scaffold architectures.
Within the diversified orthopedic tier, Johnson & Johnson (DePuy Synthes), Stryker Corporation, and Zimmer Biomet Holdings, Inc. represent integrated platform players with captive distribution infrastructure. Arthrex, Inc. and Smith+Nephew plc exemplify specialized arthroscopy-focused competitors. CONMED Corporation, Medtronic plc, LifeNet Health, and RTI Surgical occupy positions across the tissue banking and biologic implant segments.
| Leading Market Players |
|---|
| Johnson & Johnson (DePuy Synthes) |
| CONMED Corporation |
| Arthrex, Inc. |
| LifeNet Health |
| Medtronic plc |
| Stryker Corporation |
| Zimmer Biomet Holdings, Inc. |
| RTI Surgical |
| Smith+Nephew plc |
| Others |
Cost & Logistics Intelligence
Basel-area logistics corridors govern freight cost dynamics for tendon allograft shipments moving between Swiss tissue banking facilities and German orthopedic centers, compressing margin pools for distributors while creating geographic price differentiation between Central European procurement clusters and peripheral hospital systems.
Pricing Analysis
FDA 510(k) clearance tiers dictate the pricing structure for biologic implants entering US markets, separating premium scaffold architectures with extensive clinical evidence packages from standard suture anchor systems with abbreviated review pathways. Price differentiation hinges on ISO 13485 certification grade and surgeon training bundling, with university hospital sports medicine programs showing lowest price sensitivity due to bundled capital equipment leases. Cost compression in standard allograft segments is intensifying as German hospital procurement frameworks consolidate purchasing through specialty distributor networks.
Supply Chain Analysis
Extended payment terms from Swiss and German tissue banking networks are financing inventory holding costs for tendon allograft distributors serving high-volume orthopedic centers. Raw material sourcing draws from cryopreserved cadaveric tissue deposits in Bavaria, polymer fiber braiding facilities in Zurich, and polyethylene terephthalate resin suppliers in Basel. Single-source vulnerability concentrates in specialized cryopreservation protocols, while distribution runs through consignment inventory models piloted by German hospital systems and Swiss university hospitals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ligament repair and reconstruction market is recovering from cyclical compression in elective procedure volumes, with sports medicine program expansion at university hospital systems serving as the primary demand restoration mechanism.
For Market Incumbents: Pre-empt synthetic ligament encroachment by locking in exclusive tendon allograft supply contracts with German tissue banking networks before polymer science advances mature. Deepen backward integration into cryopreservation infrastructure to defend margin position against distributor consolidation. Prioritize ISO 13485 certification maintenance across OECD procurement frameworks to sustain hospital qualification status.
For New Entrants and Emerging Players: Establish a beachhead in biodegradable scaffold architectures where concentrated R&D spending offers differentiation against permanent synthetic implants. Target Swiss university hospital pilot programs for robot-assisted surgical navigation systems, where capital equipment leasing models capture margin pools beyond implant sales. Deploy direct clinical specialist teams to bypass entrenched distributor relationships in German specialized orthopedic centers.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified orthopedic conglomerates seeking to divest non-core arthroscopy instrument portfolios. Long-term viability centers on platform integrators with captive distribution infrastructure and biodegradable scaffold pipelines. Monitor EMA MDR conformity assessment timeline extensions as the signal indicating regulatory barrier elevation favoring incumbent scale advantages.
| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Exclusive allograft supply contracts with German university hospitals lock in volume commitments. |
| CE Marking Pathway | Early notified body engagement compresses European market entry timelines under MDR requirements. |
| Biodegradable Scaffold R&D | Absorbable polymer architectures differentiate against permanent synthetic ligament substitutes. |
| Software Companion Development | Computer-assisted surgical planning tools virtualize resident training for robot-assisted delivery. |
| Reimbursement Strategy | Clinical data generation for arthroscopic allograft coding secures payer coverage stability. |
Research Approach
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, EMA MDR submission databases, hospital procurement records, and tissue banking network disclosures. Orthopedic surgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers provided structured input across German, Swiss, and US markets. Bottom-up segmentation modeling triangulates against top-down macroeconomic indicators to validate volume and value estimates.
Forecast inputs include procedure volume trajectories by delivery mode, allograft versus synthetic ligament substitution elasticities, and capital equipment leasing penetration rates across the projection horizon. Segmentation dimensions span product type, application, delivery mode, and end user, with CAGRs derived from regression analysis against historical reimbursement coding changes and regulatory approval velocity. Robot-assisted navigation adoption curves and biodegradable scaffold clinical trial readouts inform scenario-weighted projections.
Stress conditions across EMA MDR timeline extensions, tendon allograft supply disruptions, and synthetic ligament biocompatibility data releases were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding sports medicine program expansion and FDA 510(k) pathway stability. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
North America Chronic Disease Management Market
Medical Treatment
Tetanus Treatment Market
Medical Treatment
Non-Infectious Diarrhea Treatment Market
Medical Treatment
Histiocytosis Treatment Market
Medical Treatment
CINV Treatment Market
Medical Treatment
Inguinal Hernia Market
Medical Treatment
Hypercoagulability Treatment Market
Medical Treatment
Trauma and Extremities Market
Medical Treatment
US Hyperbaric Oxygen Therapy (HBOT) Market
Medical Treatment
Avian Flu Treatment Market
Medical Treatment
Systemic Sclerosis Treatment Market
Medical Treatment
Mesenteric Penniculitis Treatment Market
Medical Treatment
Global Thyroid Disorder Treatment Market
Medical Treatment
Paresthesia Treatment Market
Medical Treatment
Global Plasma Therapy Market
Medical Treatment
Adenomyosis Treatment Market