
 Europe Platelet Rich Plasma (PRP) Market | 2026-2036
Europe Platelet Rich Plasma (PRP) Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Platelet Rich Plasma (PRP) Market Foresight
The shift from hospital-based blood-bank sourcing to point-of-care centrifuge systems is broadening procurement options for orthopedic and aesthetic practices. Grifols, S.A. leverages its transfusion medicine heritage to sustain plasma fractionation expertise that anchors European supply security. Zimmer Biomet competes through specialized biologics portfolios that dominate sports medicine channels across the continent. Regen Lab SA differentiates via automated closed-system devices that control preparation consistency in clinic settings.
Platelet Rich Plasma comprises autologous blood plasma with concentrated platelets, typically achieving three-to-five-fold platelet enrichment through density gradient centrifugation, deployed to accelerate tissue regeneration and modulate inflammatory healing cascades. Pure PRP leads volume consumption in orthopedic injection protocols, while leukocyte-rich formulations capture expanding share in dental socket preservation and maxillofacial regeneration where white cell content enhances antimicrobial defense. Aesthetic medicine applications concentrate margin pools in private clinic networks, contrasting with hospital tenders that standardize pricing across concentrated platelet solutions.
EMA oversight through the ATMP framework and EU MDR classification rules shape product registration pathways, with notified bodies in Germany, France, and Italy enforcing divergent interpretation of PRP device-versus-drug boundaries. The EMA and national competent authorities are clarifying borderline determinations that decide whether platelet concentrate systems qualify as medical devices or advanced therapy medicinal products. Stakeholders must monitor evolving MDR guidance documents and national reimbursement rulings that will determine which preparation technologies achieve sustainable clinical adoption across European healthcare systems.
Market Dynamics
Point-of-care centrifuge systems are displacing hospital blood-bank sourcing across European orthopedic and aesthetic practices, redistributing procurement power toward clinic-level decision-makers and fragmenting traditional supply hierarchies.
Growth Catalysts
- EU MDR compliance timelines:The Medical Device Regulation's phased enforcement is accelerating facility upgrades to closed-system preparation devices, creating replacement demand across German and French clinic networks.
- Sports medicine corridor expansion:Orthopedic clinics in Munich, Berlin, and Hamburg are standardizing autologous tendon repair protocols, pulling concentrated platelet solutions into outpatient settings.
- Density gradient centrifugation automation:Next-generation preparation systems reduce technician variability, enabling protocol replication across multi-site clinic chains.
Market Restraints
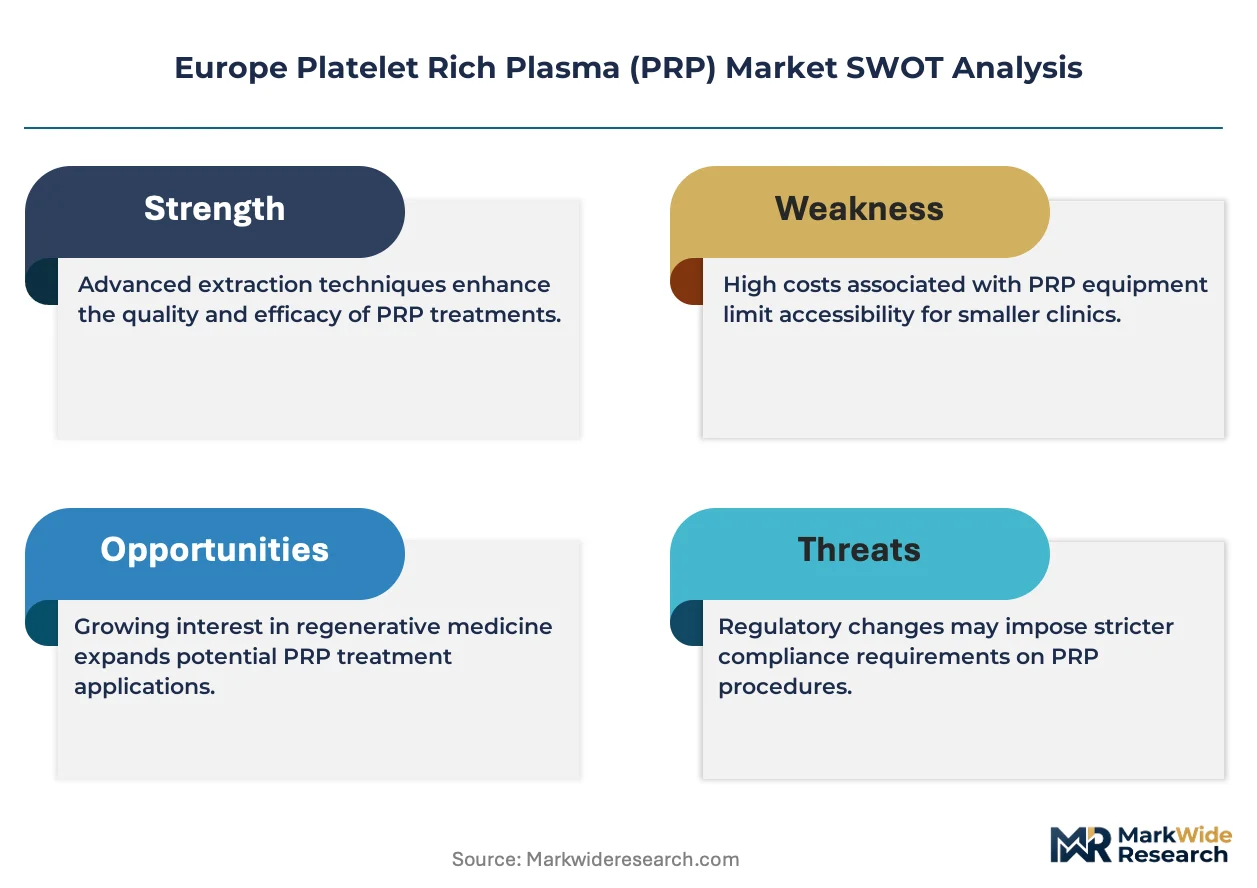
- EMA ATMP borderline uncertainty:Divergent national interpretations of whether PRP systems qualify as medical devices or advanced therapy medicinal products create registration friction and delay market entry.
- Leukocyte-rich formulation supply concentration:Production of antimicrobial-enhanced variants for dental applications depends on a narrow base of specialized reagent suppliers.
- Autologous blood collection infrastructure:Clinic-level preparation requires capital investment in sterile processing environments that smaller aesthetic practices cannot absorb.
Strategic Opportunities
- Italian reimbursement expansion:Pending national health service rulings on maxillofacial regeneration indications could unlock public funding for leukocyte-rich protocols.
- Digital workflow integration:Convergence of automated centrifuge systems with electronic health record platforms enables procedure tracking and outcome documentation for payor negotiations.
- Direct-to-clinic distribution:Bypassing traditional hospital procurement through specialized biologics distributors reduces tender friction and accelerates product access.
Industry Challenges
- Technician certification standardization:No harmonized training framework exists across Germany, France, and Italy for blood handling and sterile preparation, creating quality variability risks.
- Legacy hospital contract structures:Long-term blood-bank supply agreements lock orthopedic departments into centralized sourcing models that resist point-of-care adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Platelet Rich Plasma (PRP) Market |
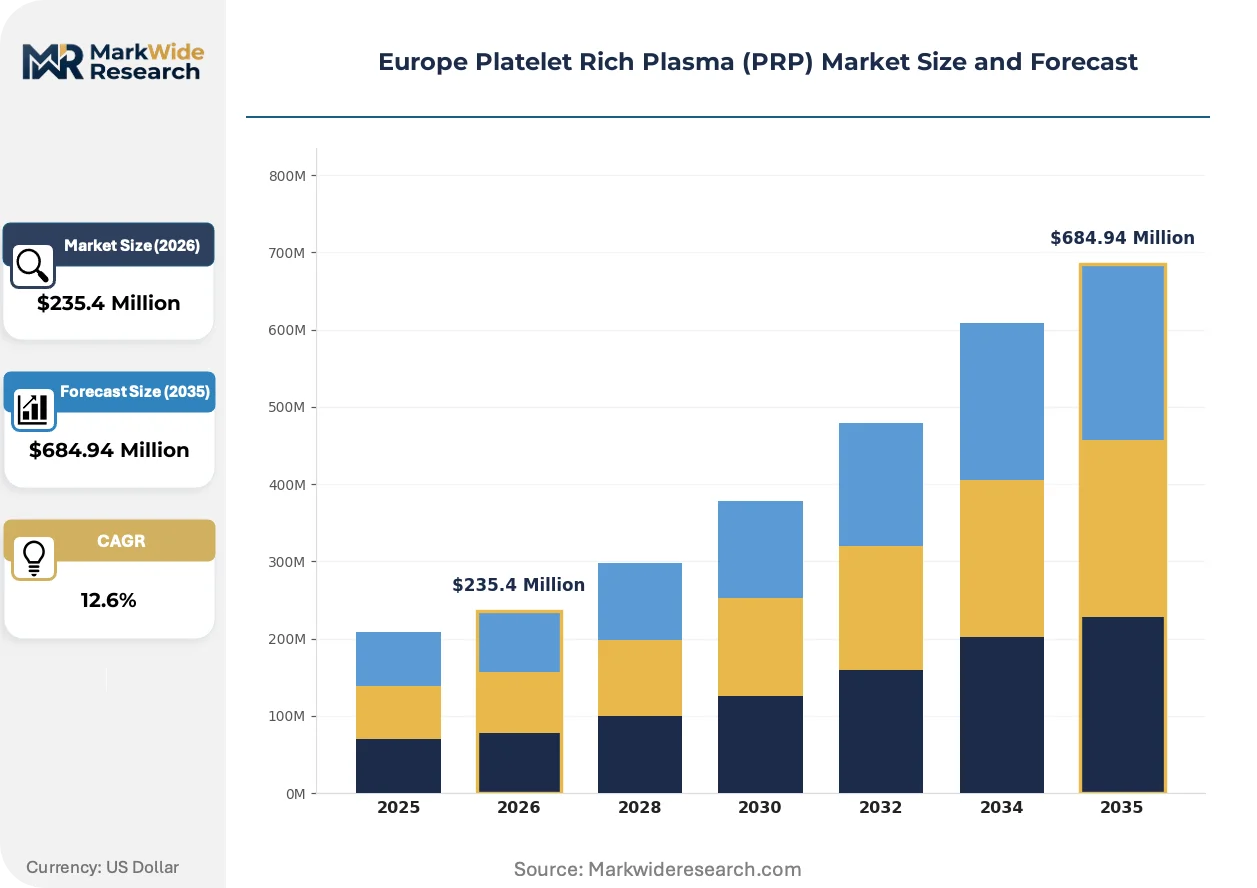
| Market Size in 2026 | $235.4 Million |
| Market Size in 2035 | $684.94 Million |
| CAGR (2026 – 2036) | 12.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pure PRP, Leukocyte-Rich PRP, PRP Gel, Concentrated Platelet Solution Application: Orthopedics, Aesthetic Medicine, Dentistry, Sports Medicine End User: Hospitals, Clinics, Research Institutions, Ambulatory Surgical Centers Delivery Mode: Injection, Topical Application, Surgical Procedure, Others |
| Companies Covered | Arthrex GmbH, Grifols, S.A., Zimmer Biomet, Stryker, Regen Lab SA, Johnson & Johnson, Terumo Corporation, EmCyte Corporation, Vivostat A/S, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Platelet Rich Plasma (PRP) Market Shifts & Advancements
Preparation technology automation and regulatory clarity efforts are compressing the gap between research-grade platelet concentration and reproducible clinical deployment, reshaping competitive differentiation around consistency rather than theoretical potency.
Closed-system automated centrifuge technology is converging with real-time optical density monitoring to eliminate batch-to-batch variability in platelet yield. Sports medicine clinics in Germany's Rhine-Ruhr metropolitan region are piloting these integrated platforms to standardize tendon injection outcomes. The technology is converging with outcome-tracking databases, enabling clinics to correlate preparation parameters with healing trajectories and justify premium positioning to private payors.
EMA guidance documents on blood-derived product classification are forcing manufacturers to restructure technical documentation for notified body review. The industrial consequence is a bifurcation between device-registered preparation systems and those pursuing the more stringent ATMP pathway. German notified bodies are interpreting MDR Annex VIII criteria most strictly, pushing leukocyte-rich formulations toward medicinal product registration and compressing margins through clinical trial requirements.
Clinic procurement committees are consolidating vendor relationships around single-source preparation platforms that bundle device, consumable, and training contracts. Hospital-based orthopedic departments in France are yielding purchasing authority to ambulatory surgery centers that prioritize turnkey solutions over component sourcing. This concentration is most visible in the Ile-de-France region, where private clinic networks negotiate enterprise pricing for standardized PRP protocols across multiple sites.
Europe Platelet Rich Plasma (PRP) Market Segmentation
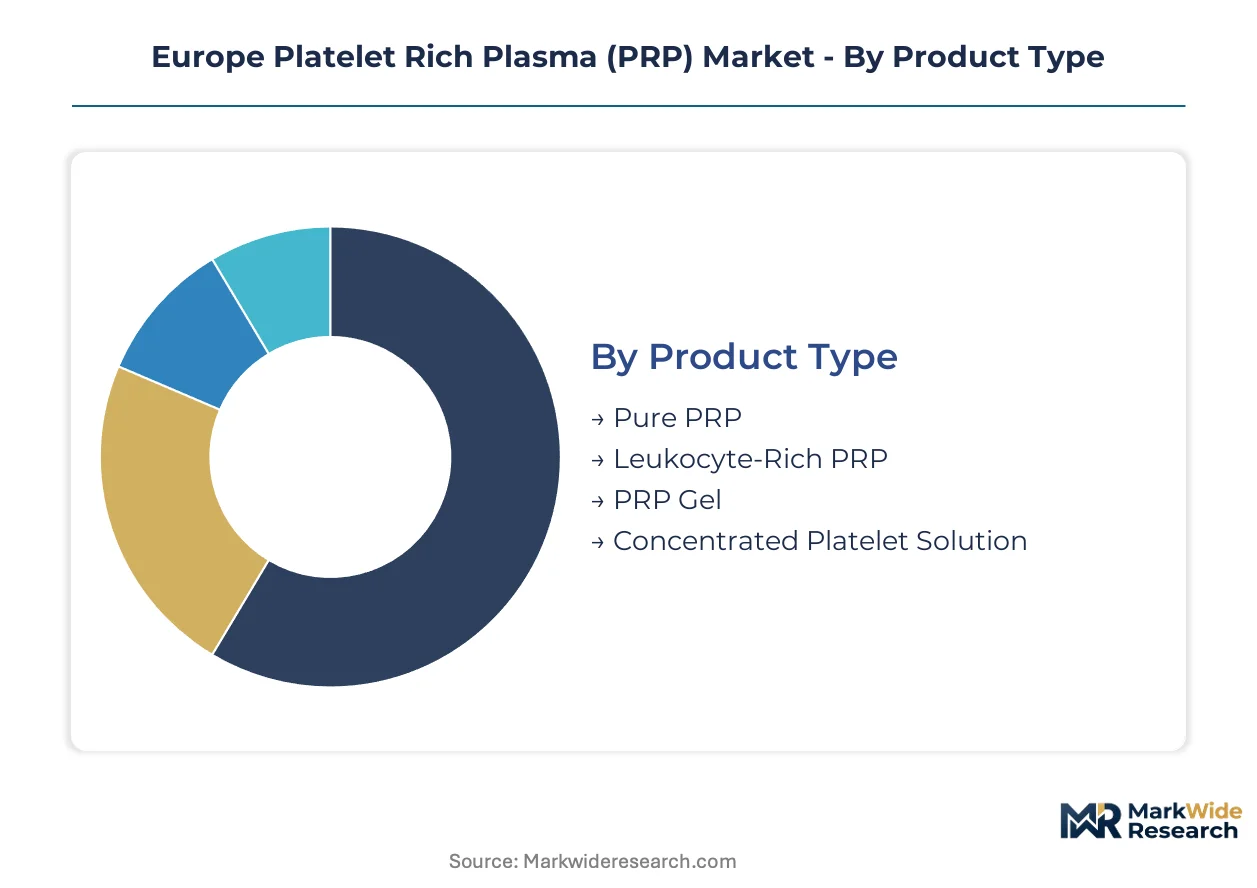
PRP preparation protocols diverge sharply across European clinical settings, with formulation choices determining reimbursement pathways and regulatory classification under EMA oversight. Device manufacturers align product portfolios to these segment boundaries, as preparation automation requirements vary substantially between orthopedic injection and aesthetic topical deployment.
Product Type:
Standardization pressures from EU MDR compliance are compressing the customization spectrum, pushing clinic networks toward validated preparation systems over artisanal blood-handling protocols.
- Pure PRP:Achieves three-to-five-fold platelet enrichment through density gradient centrifugation without leukocyte retention. German orthopedic clinics in Munich and Berlin concentrate demand here for tendon and ligament repair protocols where inflammatory modulation must be minimized.
- Leukocyte-Rich PRP:Incorporates white blood cells to enhance antimicrobial defense and inflammatory signaling. French dental practices in the Ile-de-France region are expanding adoption for socket preservation and maxillofacial regeneration where infection control dominates outcomes.
- PRP Gel:Viscous formulation enabling sustained release at wound sites. Italian aesthetic clinics deploy for facial rejuvenation protocols.
- Concentrated Platelet Solution:Liquid preparation optimized for injection delivery. Spanish sports medicine facilities favor for acute injury management.
Most installed capacity flows through Pure PRP. Expansion is steepest in Leukocyte-Rich PRP.
Application:
Margin structures invert across this category, with hospital tenders compressing orthopedic pricing while private aesthetic channels sustain premium positioning.
- Orthopedics:Tendon repair, ligament reconstruction, and joint regeneration protocols dominate hospital procurement in Germany's Rhine-Ruhr corridor. EMA ATMP borderline determinations are forcing preparation system upgrades to satisfy notified body scrutiny.
- Aesthetic Medicine:Facial rejuvenation and hair restoration applications concentrate in French and Italian private clinic networks where direct-to-consumer marketing sustains pricing power absent tender constraints.
- Dentistry:Socket preservation and implant osseointegration drive leukocyte-rich formulation demand across Iberian Peninsula practices.
- Sports Medicine:Acute injury management and accelerated return-to-play protocols pull point-of-care centrifuge adoption into German ambulatory settings.
Orthopedics retains the largest procedure volume base. Aesthetic Medicine is climbing the fastest as clinic networks expand across Southern Europe.
End User:
Procurement authority migration from centralized hospital blood banks to distributed clinic decision-makers is fragmenting traditional supply hierarchies across this category.
- Hospitals:Centralized blood bank sourcing persists in legacy orthopedic departments bound by long-term supply agreements, particularly in France's public hospital networks where tender standardization limits preparation system flexibility.
- Clinics:Private aesthetic and sports medicine practices in Germany's urban corridors are consolidating vendor relationships around single-source preparation platforms bundling device, consumable, and training contracts.
- Research Institutions:Academic medical centers in Italy and Spain pilot next-generation optical density monitoring systems for outcome correlation studies.
- Ambulatory Surgical Centers:Same-day procedure facilities in the Netherlands are capturing orthopedic volume through streamlined autologous preparation protocols.
Clinics are gaining share fastest as point-of-care centrifuge deployment accelerates. Hospitals retain the deepest procedure volume.
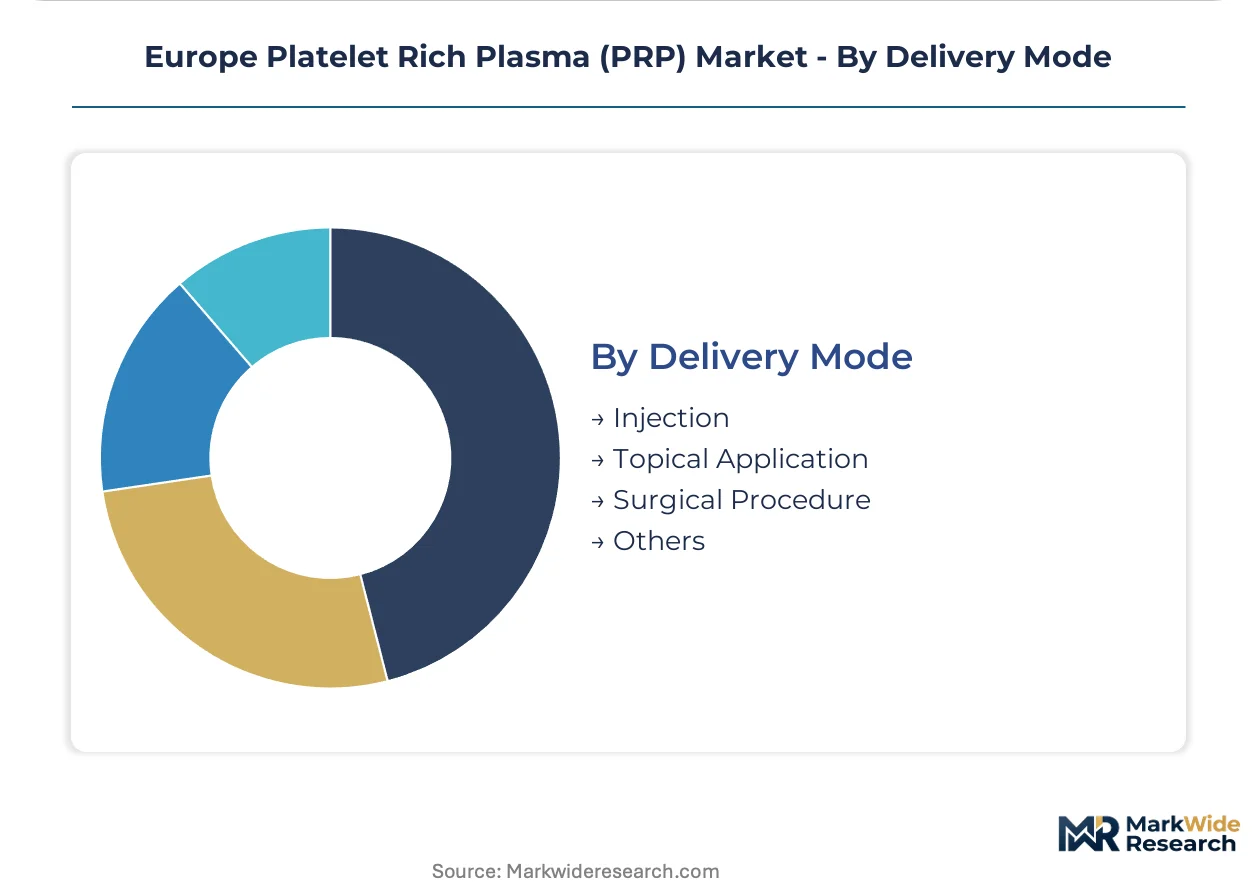
Delivery Mode:
Technician certification requirements and sterile processing infrastructure investments stratify adoption feasibility across this category.
- Injection:Ultrasound-guided delivery into tendon sheaths and joint spaces demands specialized training frameworks that German orthopedic societies are beginning to standardize. Munich-based sports medicine corridors are piloting digital workflow integration for procedure tracking.
- Topical Application:Post-procedural wound dressing and aesthetic facial protocols require minimal capital investment, enabling smaller Italian aesthetic practices to enter PRP services without centrifuge acquisition.
- Surgical Procedure:Intraoperative deployment during open orthopedic or maxillofacial procedures integrates with existing sterile fields in French hospital operating theaters.
- Others:Emerging delivery mechanisms including microneedling and laser-assisted penetration remain experimental across European regulatory jurisdictions.
Injection commands the largest installed base. Topical Application is expanding most quickly as aesthetic clinic networks proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are pulling PRP device manufacturing toward jurisdictions with streamlined MDR compliance pathways, while clinical demand concentrates in high-procedure-volume corridors where sports medicine infrastructure already exists.
Germany
Bavarian orthopedic networks in Munich and Berlin are standardizing autologous tendon repair protocols, creating concentrated demand for point-of-care centrifuge systems. The Federal Institute for Drugs and Medical Devices enforces strict MDR Annex VIII interpretations that push leukocyte-rich formulations toward medicinal product registration. The Rhine-Ruhr metropolitan region hosts pilot programs integrating optical density monitoring with outcome-tracking databases.
France
Île-de-France dental practices are expanding leukocyte-rich PRP adoption for socket preservation and maxillofacial regeneration. ANSM oversight of blood-derived therapeutic products creates registration friction that favors established device manufacturers with existing notified body relationships. Paris-based private clinic networks are consolidating vendor relationships around single-source preparation platforms bundling device and training contracts.
Italy
Lombardy and Emilia-Romagna aesthetic clinics are driving PRP gel consumption for facial rejuvenation protocols. Pending national health service rulings on maxillofacial regeneration indications could unlock public funding for leukocyte-rich preparations. Academic medical centers in Milan pilot next-generation optical density monitoring systems for outcome correlation studies.
Spain
Catalonia and Madrid sports medicine facilities favor concentrated platelet solutions for acute injury management. The Spanish Agency for Medicines and Health Products is clarifying borderline determinations between device and ATMP classifications. Barcelona-based ambulatory surgery centers are capturing orthopedic volume through streamlined autologous preparation protocols.
United Kingdom
London and Southeast England private aesthetic networks sustain premium pricing power absent tender constraints. The Medicines and Healthcare products Regulatory Agency is aligning post-Brexit device regulations with EU MDR standards to maintain market access. The Greater London clinic corridor is expanding direct-to-consumer marketing for hair restoration applications.
Europe Platelet Rich Plasma (PRP) Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue automated closed-system specialization. The vendor base stratifies around transfusion medicine heritage, sports medicine channel dominance, and preparation consistency automation. Three archetypes anchor competitive positioning: plasma fractionation specialists leveraging blood-bank expertise, orthopedic biologics portfolios dominating procedural channels, and device manufacturers controlling sterile processing workflows. M&A activity targets point-of-care technology assets, while capacity expansion concentrates in MDR-notified body clusters.
Within the heritage-tier, Grifols, S.A. and Zimmer Biomet exemplify divergent strategic foundations. Grifols, S.A. occupies a position anchored in transfusion medicine infrastructure that sustains European supply security for plasma-derived therapeutic segments. Zimmer Biomet sits within the orthopedic biologics archetype, with channel relationships across continental sports medicine corridors. Regen Lab SA represents the automation-focused tier, exemplifying closed-system device positioning that addresses preparation consistency demands in distributed clinic settings.
| Leading Market Players |
|---|
| Arthrex GmbH |
| Grifols, S.A. |
| Zimmer Biomet |
| Stryker |
| Regen Lab SA |
| Johnson & Johnson |
| Terumo Corporation |
| EmCyte Corporation |
| Vivostat A/S |
| Others |
Supply & Pricing Matrix
Centrifuge consumable costs flow from German and Italian precision manufacturing clusters through three-tier pricing structures separating premium closed-system devices from standard benchtop units and economy-grade open-bowl alternatives, with MDR compliance investments compressing margins at the standard tier while aesthetic clinic networks absorb premium markups for bundled training contracts.
Pricing Analysis
Input-cost pass-through from density-gradient reagent suppliers and single-use sterile kits shapes transactional per-procedure pricing across European clinic networks. Price differentiation hinges on CE-MDR certification tier and automation level, with German notified body scrutiny adding compliance premiums to device-registered systems. Pricing pressure stems from Italian reimbursement uncertainty for leukocyte-rich protocols, squeezing preparation system vendors into service-bundling concessions. Hospital procurement committees exhibit highest price sensitivity through tender standardization, while Paris-based private aesthetic clinics sustain lowest sensitivity via direct-to-consumer margin capture.
Supply Chain Analysis
Optical density sensor components rest on Swiss and Japanese precision electronics producers, while sterile single-use consumables draw from German medical-grade polymer specialists and Italian packaging converters. Blood collection tube supply centers on French and Spanish glass-forming facilities with limited secondary sourcing. Single-source vulnerability concentrates in specialized leukocyte-separation reagents where patent-protected formulations lock clinics into sole-supplier relationships. Distribution runs through specialized biologics distributors bypassing traditional hospital procurement hierarchies, with direct-to-clinic logistics networks expanding across German urban corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic-arbitrage opportunities concentrate where German MDR compliance investments exceed French and Spanish regulatory burdens, enabling margin capture through notified body shopping and clinic network expansion across lower-compliance jurisdictions.
For Market Incumbents: Anticipate EMA ATMP reclassification risk for leukocyte-rich formulations by accelerating device-registered pure PRP portfolio expansion and securing backward integration into sterile consumable production. Channel control through exclusive clinic training partnerships defends against emerging automated device entrants. CE-MDR certification depth serves as the priority differentiation lever as notified body capacity constraints lengthen competitor approval timelines. For New Entrants and Emerging Players: Begin with Spanish and Italian aesthetic clinic networks where capital-light topical application protocols minimize centrifuge infrastructure requirements and accelerate revenue generation. The most penetrable white space sits in Dutch and Belgian ambulatory surgical centers lacking established blood-bank relationships. A direct-to-clinic distribution model with outcome-tracking software bundling bypasses entrenched hospital procurement friction. For Investors and Strategic Acquirers: Consolidation pressure builds where MDR compliance costs exceed €500K per device variant and eliminate sub-scale device manufacturers. Long-term viability favors automated closed-system specialists with existing notified body relationships and multi-site clinic chain contracts. The signal to watch is Italian national health service reimbursement rulings on maxillofacial regeneration, which would validate leukocyte-rich protocol economics and trigger acquisition premiums for specialized reagent suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| CE-MDR Certification Pathway | Notified body selection in Germany or France determines approval timeline and market access speed. |
| Automated Preparation System Launch | Optical density monitoring integration addresses technician variability concerns in multi-site clinic chains. |
| Direct-to-Clinic Distribution Partnership | Bypassing hospital procurement tenders accelerates product access in German sports medicine corridors. |
| Reimbursement Strategy Development | Italian NHS maxillofacial rulings would unlock public funding for antimicrobial-enhanced formulations. |
| Training and Certification Program | Standardized blood-handling protocols reduce quality variability risks across fragmented technician base. |
Research Methodology
Direct dialogue with orthopedic clinic directors, aesthetic practice owners, biomedical engineers at notified bodies, and GPO contracts managers combined with secondary validation against EMA guidance documents, EU MDR implementation databases, hospital procurement registries, and national reimbursement rulings. Bottom-up procedure volume estimates triangulate with top-down device shipment data across the analysis window.
Segment-level value outputs reflect modeled projections across product type, application, end user, and delivery mode dimensions, with CAGRs derived from regression analysis of historical adoption curves and procedure volume trajectories. Forecast inputs incorporate MDR compliance timeline assumptions, clinic network expansion patterns, and reimbursement policy evolution across German, French, and Italian jurisdictions.
Several conditions sit outside the modeled scope, including Brexit regulatory divergence effects, raw material supply disruptions from geopolitical conflict, and breakthrough synthetic platelet substitute approvals. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Systemic Sclerosis Treatment Market
Medical Treatment
Behcet's Disease Treatment Market
Medical Treatment
Anti-Fungal Treatment Market
Medical Treatment
Global Sex Reassignment Surgery Market
Medical Treatment
Adenomyosis Treatment Market
Medical Treatment
Onchocerciasis Treatment Market
Medical Treatment
Lung Cancer Surgery Market
Medical Treatment
Hyperkalemia Treatment Market
Medical Treatment
Post-Operative Nausea and Vomiting (PONV) Market
Medical Treatment
Cervical Cancer Treatment Market
Medical Treatment
Achalasia Treatment Market
Medical Treatment
Corneal Transplant Market
Medical Treatment
Alagille Syndrome Treatment Market
Medical Treatment
Mesotherapy Market
Medical Treatment
Infertility Treatment Market
Medical Treatment
Single Dose Radiotherapy Services Market