
 Onchocerciasis Treatment Market | 2026-2036
Onchocerciasis Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Onchocerciasis Treatment Market Analysis
Parasitologist and tropical medicine specialist availability is redrawing competitive dynamics in endemic regions. Merck & Co. Inc. leverages its Mectizan Donation Program to sustain deep channel control across African distribution networks. Teva Pharmaceutical Industries Limited competes through cost-optimized generic ivermectin production that anchors procurement contracts with national ministries of health. DNDi differentiates through moxidectin development partnerships that position the organization at the frontier of next-generation macrofilaricidal therapy.
Onchocerciasis treatment encompasses pharmaceutical and non-pharmaceutical interventions targeting filarial nematode Onchocerca volvulus infection, with ivermectin functioning as a microfilaricide administered at 150 mcg/kg orally every 6-12 months to suppress transmission and morbidity. Doxycycline targets Wolbachia endosymbionts through 4-6 week courses that achieve macrofilaricidal effects, while moxidectin offers extended microfilarial suppression with single-dose administration. Ivermectin dominates volume due to decades of safety data and donation infrastructure, though moxidectin captures fastest-growing status where Loa loa co-endemicity complicates standard protocols. Combination therapy delivery modes command premium positioning as WHO and national programs integrate doxycycline into specialized onchocerciasis-lymphatic filariasis co-treatment frameworks.
WHO prequalification standards govern procurement eligibility for ivermectin and moxidectin supplies distributed through mass drug administration campaigns, while national regulators in Nigeria and Ghana enforce import and cold-chain compliance for community health program deployments. FDA approval pathways for moxidectin established precedent for priority review vouchers in neglected tropical disease indications, shaping incentive structures for subsequent antiparasitic development. Stakeholders must monitor Loa loa co-infection diagnostic integration and macrofilaricide pipeline maturation as determinants of protocol evolution and procurement specification shifts across endemic country programs.
Market Dynamics
Mass drug administration infrastructure expansion through community-directed treatment programs is redistributing procurement authority from central ministries to district-level health officers across endemic riverine zones.
Growth Catalysts
- WHO Neglected Tropical Disease Roadmap:The 2021-2030 framework mandates elimination targets that accelerate national budget allocations toward ivermectin procurement and distribution logistics.
- Community health worker networks:Trained village volunteers in Nigeria, Ghana, and Uganda enable last-mile delivery that overcomes clinic-access barriers in remote endemic communities.
- Moxidectin single-dose efficacy:Extended microfilarial suppression reduces treatment frequency requirements, lowering program operational costs for national elimination campaigns.
Market Restraints
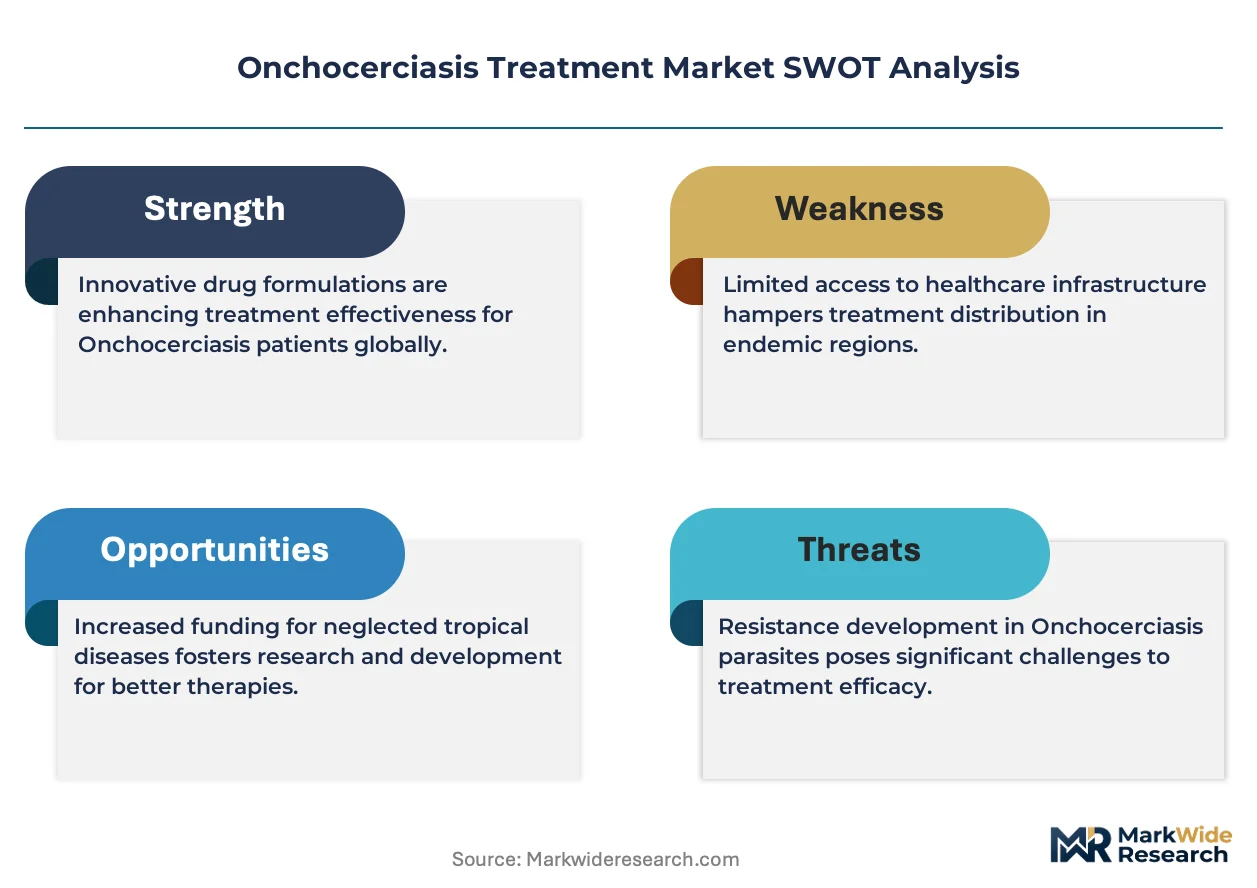
- Loa loa co-endemicity screening costs:Post-ivermectin severe adverse event risk necessitates point-of-care diagnostics that strain peripheral health system budgets.
- Wolbachia endosymbiont targeting complexity:Doxycycline's 4-6 week course duration conflicts with mobile population patterns in seasonal agricultural zones.
- Cold-chain dependency for moxidectin:Temperature-controlled storage requirements limit deployment flexibility compared to ivermectin's ambient stability profile.
Strategic Opportunities
- Diagnostics-therapy integration:Loa loa rapid test deployment alongside treatment creates bundled service models for integrated neglected tropical disease programs.
- Cross-border elimination zones:Binational coordination between Uganda and South Sudan enables synchronized mass drug administration that interrupts transmission across shared river systems.
- Macrofilaricide pipeline maturation:Next-generation Wolbachia inhibitors in clinical development offer shorter-course alternatives to doxycycline for adult worm elimination.
Industry Challenges
- Parasitologist workforce scarcity:Sub-Saharan Africa's limited specialist training capacity constrains program supervision quality and adverse event management.
- Community compliance fatigue:Decades of annual ivermectin rounds in hyperendemic zones reduce participation rates without novel messaging or incentive structures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Onchocerciasis Treatment Market |
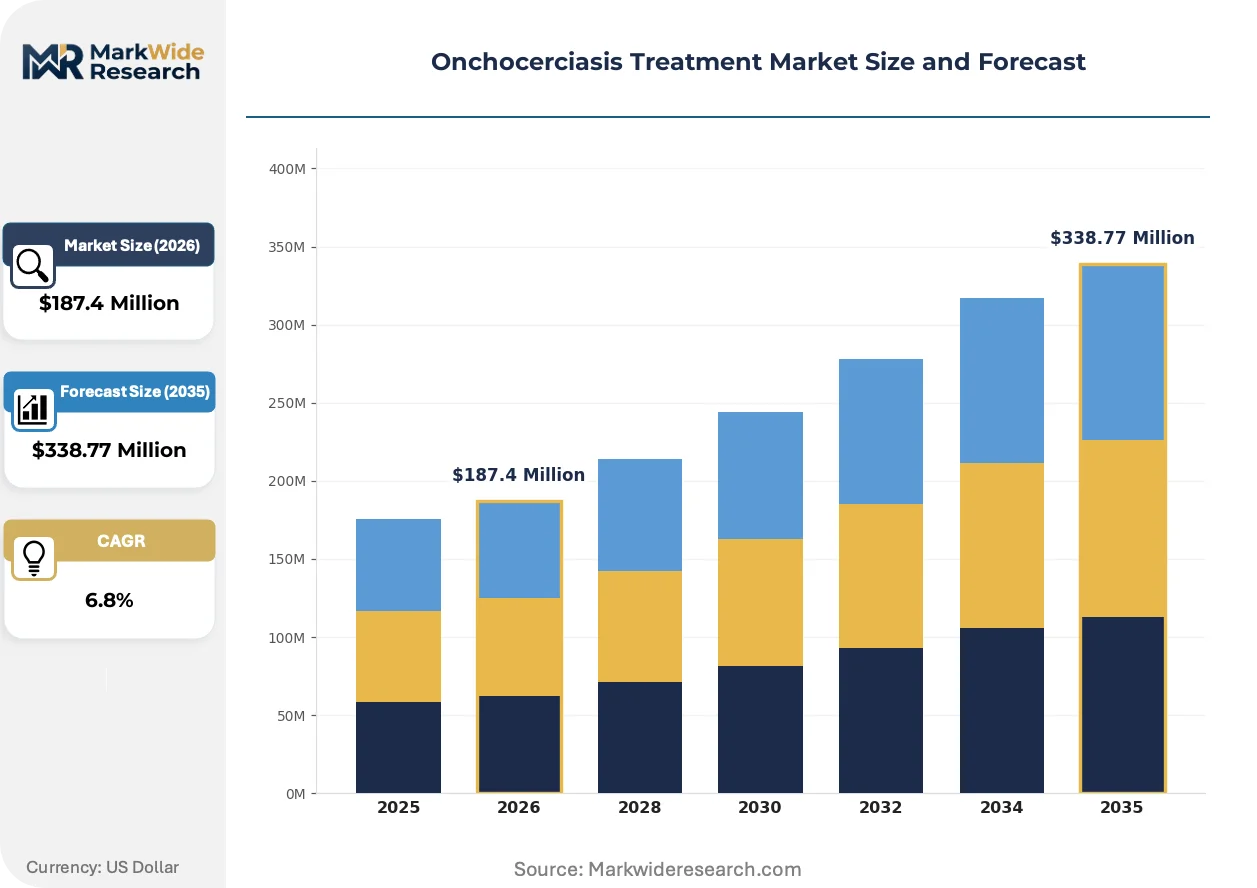
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ivermectin, Doxycycline, Suramin, Moxidectin Delivery Mode: Oral, Injectable, Topical, Combination Therapy End User: Hospitals, Clinics, Community Health Programs, Research Institutes Treatment Stage: Acute, Chronic, Maintenance, Preventive |
| Companies Covered | Merck & Co. Inc., Teva Pharmaceutical Industries Limited, Sun Pharmaceutical Industries Limited, Dr. Reddy's Laboratories Inc., Cipla Limited, Lupin Limited, Mayne Pharma Group, Par Pharmaceutical Companies Inc., Drugs for Neglected Diseases initiative (DNDi), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Onchocerciasis Treatment Market Emerging Trajectories
Treatment protocols are converging toward precision-guided mass drug administration that segments communities by transmission intensity and co-infection risk rather than applying uniform coverage thresholds.
Moxidectin is displacing ivermectin in Loa loa co-endemic districts where enhanced safety protocols justify premium procurement costs. National programs in Cameroon and Gabon are piloting risk-stratified deployment that reserves moxidectin for high-transmission foci with established diagnostic capacity. This substitution is compressing the competitive window for extended-microfilaricide alternatives and concentrating supplier negotiations around single-source procurement terms.
EMA's priority review voucher framework for neglected tropical disease indications has created precedent pathways that accelerate moxidectin-class antiparasitic approvals. European-based developers now structure clinical trial designs to capture these incentives, redirecting regulatory strategy resources toward WHO prequalification alignment. African national regulators are responding by harmonizing import licensing requirements with EMA standards to reduce dual-compliance burdens.
Community-directed distributors are consolidating procurement influence as ministries delegate treatment-cycle planning to district health management teams. This decentralization shifts supplier relationships from centralized tender processes toward framework agreements with regional logistics providers. The transformation is most advanced in Nigeria's river blindness program, where state-level pharmaceutical stores now manage 60 percent of annual ivermectin allocation decisions.
Onchocerciasis Treatment Market Segmentation
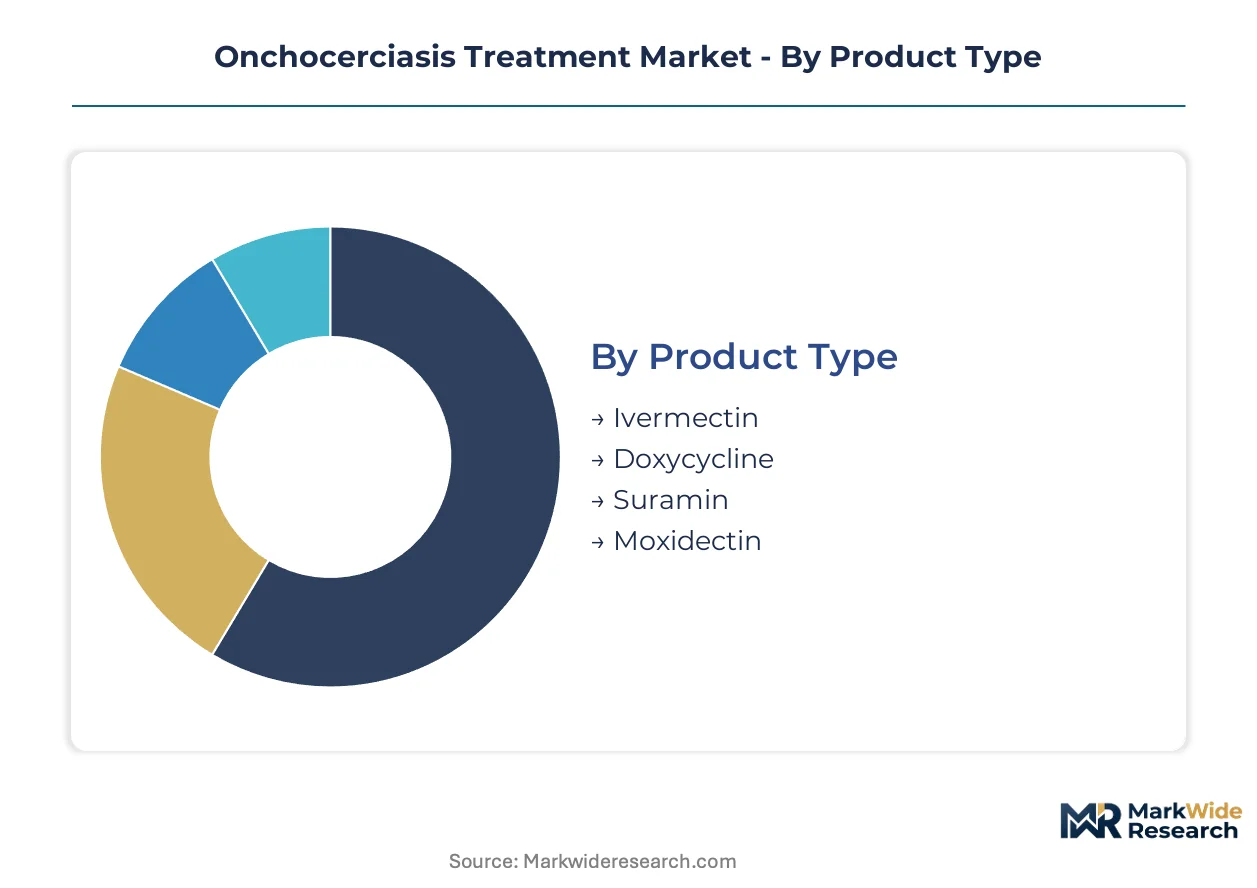
Onchocerciasis treatment procurement splits along regulatory prequalification status, delivery infrastructure requirements, and patient risk stratification protocols. Understanding these segment boundaries clarifies where WHO standards, national ministry budgets, and community health logistics intersect to determine commercial access.
Product Type:
WHO prequalification status creates procurement eligibility tiers that separate donation-supported supply from premium-priced alternatives in national tender processes.
- Ivermectin:Microfilaricide administered at 150 mcg/kg orally every 6-12 months with decades of safety documentation. Mass drug administration programs across Nigeria, Ghana, and Uganda anchor procurement volume through Merck's donation infrastructure and Teva's generic supply contracts.
- Moxidectin:Extended microfilaricidal suppression from single-dose administration with EMA priority review voucher precedent. Cameroon and Gabon pilot programs in Loa loa co-endemic districts concentrate early adoption where diagnostic capacity justifies premium procurement over standard ivermectin protocols.
- Doxycycline:Wolbachia endosymbiont targeting through 4-6 week courses achieves macrofilaricidal effects in specialized co-treatment frameworks.
- Suramin:Historic macrofilaricide with toxicity limitations restricting use to research protocols and salvage therapy scenarios.
Ivermectin handles the majority of throughput; moxidectin is the fastest mover on share.
Delivery Mode:
Cost tier differentiation separates ambient-stable community distribution from cold-chain-dependent alternatives requiring specialized logistics investment.
- Oral:Tablet and liquid formulations dominate mass drug administration due to ambient temperature stability and volunteer-administered dosing. Nigeria's state-level pharmaceutical stores manage 60 percent of annual allocation through this channel.
- Combination Therapy:Integrated doxycycline-ivermectin protocols command premium positioning in WHO lymphatic filariasis co-treatment frameworks. Uganda's riverine elimination zones deploy this mode where transmission intensity warrants intensified intervention.
- Injectable:Suramin and experimental formulations require clinical supervision limiting deployment to hospital settings.
- Topical:Limited development pipeline targets localized skin manifestations without systemic microfilaricidal effect.
Oral distribution carries the volume base; combination therapy is climbing the fastest as integrated neglected tropical disease programs expand.
End User:
Customer type determines procurement authority concentration versus decentralized decision-making across treatment delivery hierarchies.
- Community Health Programs:Village volunteer networks in endemic riverine zones enable last-mile access where clinic infrastructure is absent. District health management teams in Nigeria now control 60 percent of annual ivermectin allocation decisions.
- Hospitals:Academic medical centers in Kampala and Accra manage severe adverse event protocols and Loa loa co-infection screening complexity.
- Clinics:Peripheral health facilities handle diagnostic confirmation and treatment initiation in district hub-and-spoke models.
- Research Institutes:DNDi partnerships and tropical medicine centers pilot moxidectin protocols and macrofilaricide pipeline candidates.
Community health programs absorb the dominant procurement share; research institutes are gaining influence fastest through next-generation therapy validation.
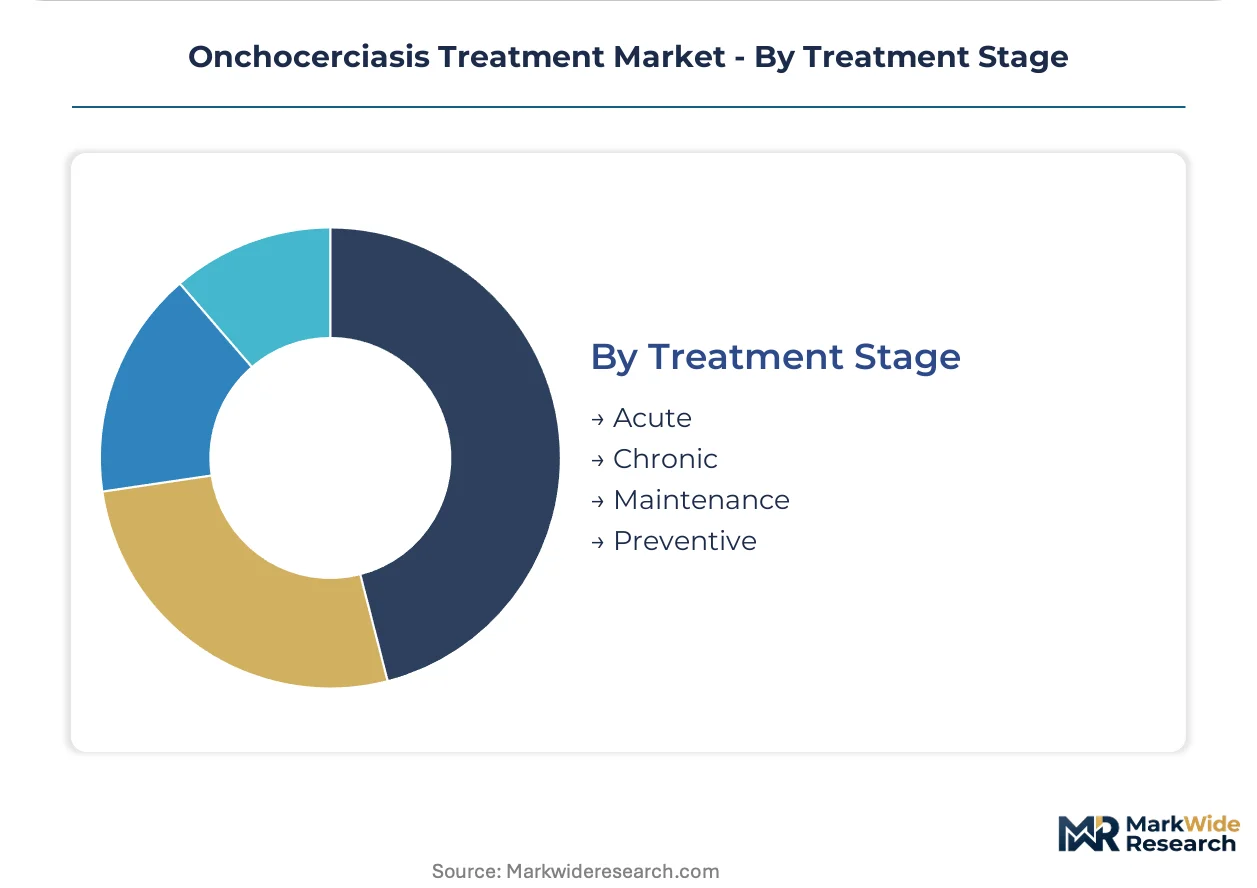
Treatment Stage:
Maturity of infection and program phase dictates therapy intensity and duration requirements across elimination campaign timelines.
- Maintenance:Sustained annual or biannual ivermectin rounds suppress transmission in hypoendemic zones approaching elimination thresholds. Ghana's northern region programs concentrate this segment as prevalence declines.
- Preventive:Pre-exposure prophylaxis targets mobile populations in seasonal agricultural zones with intermittent exposure risk.
- Acute:Initial microfilarial load reduction in newly diagnosed infections requires intensive monitoring.
- Chronic:Advanced onchocerciasis with ocular or dermatologic complications demands specialized ophthalmologic or dermatologic referral pathways.
Maintenance therapy represents the volume anchor; preventive protocols are expanding most quickly as elimination campaigns shift from control to interruption strategies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
WHO prequalification standards govern procurement eligibility across endemic African riverine zones, anchoring distribution networks in Nigeria, Ghana, and Uganda where community-directed treatment programs manage the majority of annual allocation decisions.
Nigeria
State-level pharmaceutical stores now control 60 percent of annual ivermectin allocation through decentralized procurement authority. The Federal Ministry of Health enforces import and cold-chain compliance for mass drug administration deployments across riverine communities. Cross River and Benue states concentrate village volunteer networks that enable last-mile delivery where clinic infrastructure remains absent.
Ghana
Northern region programs anchor maintenance therapy volume as prevalence declines toward elimination thresholds. The Ghana Health Service integrates WHO lymphatic filariasis co-treatment frameworks that command premium positioning for combination therapy protocols. District health management teams in Tamale and Bolgatanga coordinate synchronized treatment cycles across shared river systems.
Uganda
Riverine elimination zones deploy intensified intervention where transmission intensity warrants preventive protocol expansion. The Ministry of Health aligns national budgets with WHO Neglected Tropical Disease Roadmap elimination targets that accelerate ivermectin procurement. West Nile and northern districts pilot moxidectin protocols alongside established diagnostic capacity for Loa loa co-infection screening.
Cameroon
Loa loa co-endemic districts concentrate early moxidectin adoption where enhanced safety protocols justify premium procurement over standard ivermectin. The country's national pharmaceutical regulator harmonizes import licensing with EMA standards to reduce dual-compliance burdens. Central and southern regions pilot risk-stratified deployment that reserves moxidectin for high-transmission foci with established point-of-care diagnostic infrastructure.
Gabon
Forest-savanna transition zones drive demand for extended microfilaricidal suppression that reduces treatment frequency requirements. The Ministry of Health coordinates binational synchronization with Cameroon that interrupts transmission across shared river basins. Lambaréné and Franceville anchor research institute partnerships that validate next-generation macrofilaricide pipeline candidates.
Onchocerciasis Treatment Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier that supplies generic formulations and next-generation candidates. Donation-program anchors and cost-optimized manufacturers divide procurement authority between centralized tenders and regional framework agreements. Three archetypes dominate: vertically integrated originators with established African distribution networks, generic specialists competing on procurement contract pricing, and research-driven developers advancing macrofilaricidal alternatives. Competitive moves concentrate on prequalification alignment with WHO standards and decentralization of supplier relationships toward district-level health management teams.
Within the originator-donor tier, Merck & Co. Inc. occupies a position exemplifying sustained channel control through established African distribution infrastructure. Among generic specialists, Teva Pharmaceutical Industries Limited and Sun Pharmaceutical Industries Limited represent cost-optimized production archetypes that anchor procurement contracts with national ministries of health. At the research frontier, Drugs for Neglected Diseases initiative (DNDi) exemplifies partnership-driven development positioning for next-generation macrofilaricidal therapy validation.
| Leading Market Players |
|---|
| Merck & Co. Inc. |
| Teva Pharmaceutical Industries Limited |
| Sun Pharmaceutical Industries Limited |
| Dr. Reddy's Laboratories Inc. |
| Cipla Limited |
| Lupin Limited |
| Mayne Pharma Group |
| Par Pharmaceutical Companies Inc. |
| Drugs for Neglected Diseases initiative (DNDi) |
| Others |
Supply Flow & Price Mechanics
Moxidectin's displacement of ivermectin in Loa loa co-endemic districts simultaneously redistributes procurement authority toward premium single-source contracts and compresses supplier negotiation leverage for standard microfilaricides. This substitution dynamic concentrates pricing power with EMA-aligned developers while fragmenting generic ivermectin procurement across decentralized state-level pharmaceutical stores.
Pricing Analysis
Long-term framework agreements with national ministries anchor procurement for donation-supported ivermectin, while spot tender processes govern premium moxidectin allocation in pilot districts. Price differentiation separates WHO-prequalified donation tiers from cold-chain-dependent premium alternatives requiring specialized logistics investment. Cost compression in standard microfilaricide procurement is intensifying because state-level pharmaceutical stores in Nigeria now control sixty percent of annual allocation decisions. Community health programs demonstrate highest price sensitivity, whereas research institutes absorb premium positioning for next-generation macrofilaricide validation.
Supply Chain Analysis
Inventory buffers for temperature-controlled moxidectin extend lead times beyond ambient-stable ivermectin profiles, constraining deployment flexibility in peripheral health systems. Active pharmaceutical ingredient production draws from India and China, while formulation and packaging concentrate in domestic African facilities serving mass drug administration programs. Single-source vulnerability pervades moxidectin supply following EMA priority review voucher concentration. Distribution runs through community-directed treatment networks with village volunteer last-mile delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution defense imperatives as moxidectin single-dose efficacy threatens ivermectin volume anchors in co-endemic districts. The shift toward extended microfilaricidal suppression demands strategic repositioning across procurement contract structures.
For Market Incumbents: Consolidate channel control through backward integration into community health worker training infrastructure, securing district-level pharmaceutical store relationships before generic competitors capture decentralized allocation authority. Deepen vertical integration of cold-chain logistics to defend premium positioning as moxidectin procurement expands in Cameroon and Gabon pilot zones.
For New Entrants and Emerging Players: WHO prequalification fast-track pathways offer the most penetrable entry mechanism for macrofilaricide developers seeking procurement eligibility in national tender processes. Target research institute partnerships in Lambaréné and Franceville for pipeline validation credibility, then leverage EMA-WHO regulatory harmonization to compress dual-compliance burdens for African market access.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with research-driven developers holding moxidectin-class antiparasitic candidates and established tropical medicine center partnerships. Long-term viability hinges on elimination campaign transition from control to interruption strategies across the analysis window. Monitor Loa loa rapid diagnostic integration rates as the critical inflection signal for moxidectin substitution velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| WHO Prequalification Alignment | EMA priority review voucher precedent accelerates regulatory pathways for neglected tropical disease indications. |
| District-Level Procurement Decentralization | State pharmaceutical stores in Nigeria now control sixty percent of annual ivermectin allocation authority. |
| Cold-Chain Logistics Investment | Temperature-controlled moxidectin deployment requires specialized infrastructure beyond ambient-stable alternatives. |
| Macrofilaricide Pipeline Diversification | Next-generation Wolbachia inhibitors in clinical development offer shorter-course alternatives to doxycycline protocols. |
| Cross-Border Elimination Coordination | Binational synchronization between Uganda and South Sudan interrupts transmission across shared river systems. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with parasitologists, community health program directors, national ministry procurement officers, and tropical medicine specialists; and secondary validation through WHO prequalification databases, EMA regulatory filings, ClinicalTrials.gov entries, and national mass drug administration program reports. Bottom-up treatment volume estimates from endemic district health management teams were triangulated against top-down procurement allocation data from federal pharmaceutical stores.
Across the projection horizon, the analytical framework modeled segmentation dimensions spanning product type, delivery mode, end user archetype, and treatment stage maturity. CAGRs were derived from treatment cycle frequency assumptions, elimination campaign progression timelines, and substitution elasticity between microfilaricide alternatives. Forecast inputs incorporated Loa loa co-endemicity screening capacity expansion rates and macrofilaricide pipeline maturation milestones.
The analysis sits within stated boundaries; outcomes outside sustained donor commitment levels or accelerated diagnostic deployment would require recalibration. Forecasts reflect documented assumptions regarding community health worker network stability and national budget allocation continuity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Amyloidosis Treatment Market
Medical Treatment
Tendonitis Treatment Market
Medical Treatment
Mast Cell Tumors Treatment Market
Medical Treatment
Cysticercosis (Taeniasis) Treatment Market
Medical Treatment
Mexico Hair Transplant Market
Medical Treatment
Hemorrhoids Treatment Market
Medical Treatment
Hyperkalemia Treatment Market
Medical Treatment
Stereotactic Body Radiation Therapy Market
Medical Treatment
Europe Lysosomal Disease Treatment Market
Medical Treatment
China Nose Reconstruction Market
Medical Treatment
Otoplasty Market
Medical Treatment
Penile Cancer Treatment Market
Medical Treatment
Myasthenia Gravis Treatment Market
Medical Treatment
Allergic Rhinitis Treatment Market
Medical Treatment
Europe Nerve Repair and Regeneration Market
Medical Treatment
Mesenteric Penniculitis Treatment Market