
 Liver Transplantation Market | 2026-2036
Liver Transplantation Market Size, Share, and Industry Trends Forecast 2026-2036
Liver Transplantation Market Foresight
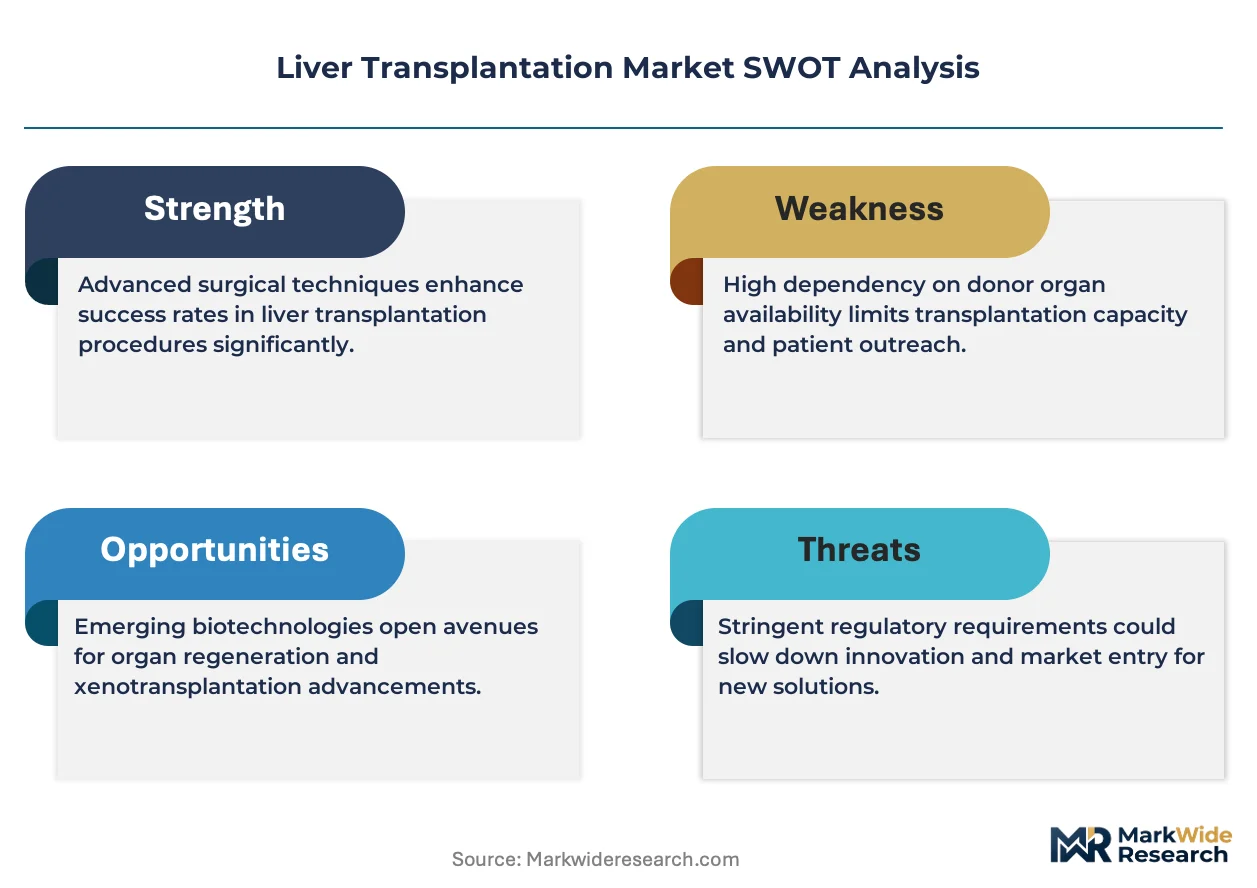
The EU Organ Donation Directive is rebalancing cost-of-entry calculus for European transplant programs by mandating standardized quality management systems and traceability infrastructure. AbbVie Inc. leverages its immunosuppression portfolio to sustain recurring revenue in post-transplant maintenance protocols. Novartis AG competes through differentiated mTOR inhibitor positioning in high-risk recipient populations. Medtronic anchors the surgical instrumentation layer with specialized vascular sealing and liver retraction systems.
Liver transplantation denotes the surgical replacement of a diseased liver with a functional allograft from either a living or deceased donor, requiring cold ischemia times under twelve hours and ABO-compatible matching to ensure graft survival. The procedure restores metabolic, synthetic, and detoxification functions in patients with end-stage organ failure. Deceased donor procedures still dominate procedure volumes, yet split liver transplantation represents the fastest-growing technical segment as surgeons maximize graft utility from pediatric and adult recipient pools. Cirrhosis indications command the largest share of transplant listings, while hepatocellular carcinoma segments attract concentrated R&D investment due to Milan criteria expansion debates and immunotherapy adjuvant protocols.
FDA oversight of organ procurement organizations through CMS conditions of participation shapes operational compliance costs, while EMA's advanced therapy medicinal products framework influences ex-vivo organ perfusion device classifications. Eurotransplant allocation algorithms directly determine center-level case volumes and waiting-list mortality outcomes. Stakeholders must monitor living donor reimbursement policy shifts and machine perfusion outcome data to decide between capital-intensive technology adoption and conventional cold storage protocols.
Market Dynamics
Machine perfusion technology is compressing cold ischemia constraints and expanding the pool of transplantable marginal grafts, forcing procurement organizations to reassess capital allocation between conventional preservation and advanced perfusion platforms.
Growth Catalysts
- CMS Reimbursement Revisions:The Centers for Medicare and Medicaid Services expanded living donor reimbursement coverage, incentivizing transplant centers to develop living donor programs and reduce waiting-list mortality.
- Normothermic Machine Perfusion:Ex-vivo organ perfusion systems extend viable preservation windows from six hours to twenty-four hours, enabling inter-regional organ sharing and reducing discard rates for steatotic livers.
- Eurotransplant Allocation Harmonization:Standardized organ allocation algorithms across Germany, Netherlands, and Austria optimize graft-recipient matching and reduce geographic disparities in access.
Market Restraints
- Perfusion Device Capital Intensity:Single-use disposable costs for normothermic perfusion circuits exceed cold storage expenses by an order of magnitude, constraining adoption at mid-volume transplant centers.
- Donor Organ Supply Concentration:Deceased donor availability clusters in specific metropolitan statistical areas, creating persistent supply-demand mismatches in rural and non-academic medical centers.
- ABO-Incompatible Technical Barriers:Desensitization protocols for incompatible transplants require specialized immunology infrastructure unavailable at smaller programs, limiting procedure expansion.
Strategic Opportunities
- Split Liver Transplantation:Technical advances in parenchymal division enable single deceased donor grafts to serve pediatric and adult recipients simultaneously, maximizing organ utility.
- Immunotherapy Adjuvant Protocols:Checkpoint inhibitor integration into hepatocellular carcinoma transplant pathways creates new post-operative care revenue streams and expands Milan criteria eligibility.
- Telemedicine-Based Living Donor Evaluation:Remote assessment protocols reduce geographic barriers for potential living donors, expanding the donor pool in underserved catchment areas.
Industry Challenges
- Hepatobiliary Surgeon Workforce Scarcity:Fellowship training positions in transplant surgery fail to match procedure volume growth, creating bottlenecks at high-volume centers.
- Perfusion Outcome Data Fragmentation:Inconsistent endpoints across machine perfusion clinical trials complicate payer coverage decisions and technology adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Liver Transplantation Market |
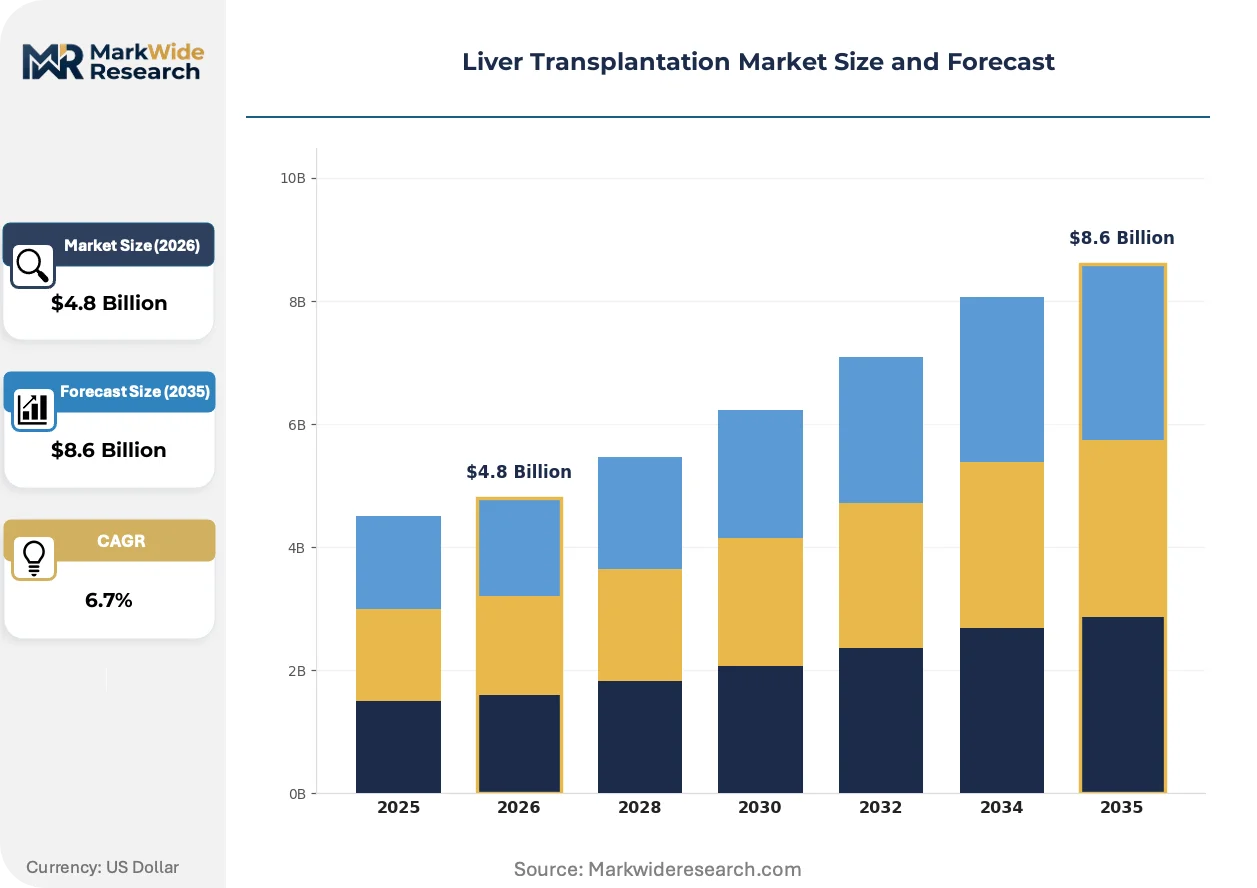
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Living Donor, Deceased Donor, Split Liver, Auxiliary Transplant Indication: Cirrhosis, Hepatocellular Carcinoma, Acute Liver Failure, Cholestatic Disease Care Setting: Transplant Centers, Hospitals, Specialty Clinics, Home Care Age Group: Pediatric, Adult, Geriatric, Others |
| Companies Covered | AlloSource, Dompé farmaceutici S.p.A., Thompson Surgical, Integra LifeSciences, AbbVie Inc., Novartis AG, Medtronic, RedHill Biopharma Ltd., Baxter International Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Liver Transplantation Market Shifts & Advancements
Organ preservation technology and allocation policy are converging to reshape graft logistics, with implications for center competitiveness and patient access patterns.
Normothermic machine perfusion is consolidating the organ procurement landscape by enabling extended-criteria donor acceptance previously excluded from transplantation. High-volume academic medical centers are adopting TransMedics Organ Care Systems at accelerating rates, compressing the viability gap between ideal and marginal grafts. This technology is consolidating procurement geography as extended preservation windows permit coast-to-coast organ transport without cold ischemia penalties.
EMA's advanced therapy medicinal products framework is reclassifying ex-vivo perfusion devices as combination products, triggering additional clinical evidence requirements. Device manufacturers face expanded post-market surveillance obligations and quality system audits under the MDR. Transplant programs in Germany and Austria are responding by centralizing perfusion services at designated high-volume hubs to amortize compliance costs.
Living donor advocacy organizations are demanding direct reimbursement for lost wages and travel expenses, shifting financial burden from donors to payers. This behavioral change disrupts traditional cost-shifting models where donors absorbed uncompensated economic losses. The United States exhibits the most visible policy experimentation, with several states implementing paid leave mandates for living organ donors.
Liver Transplantation Market Segmentation
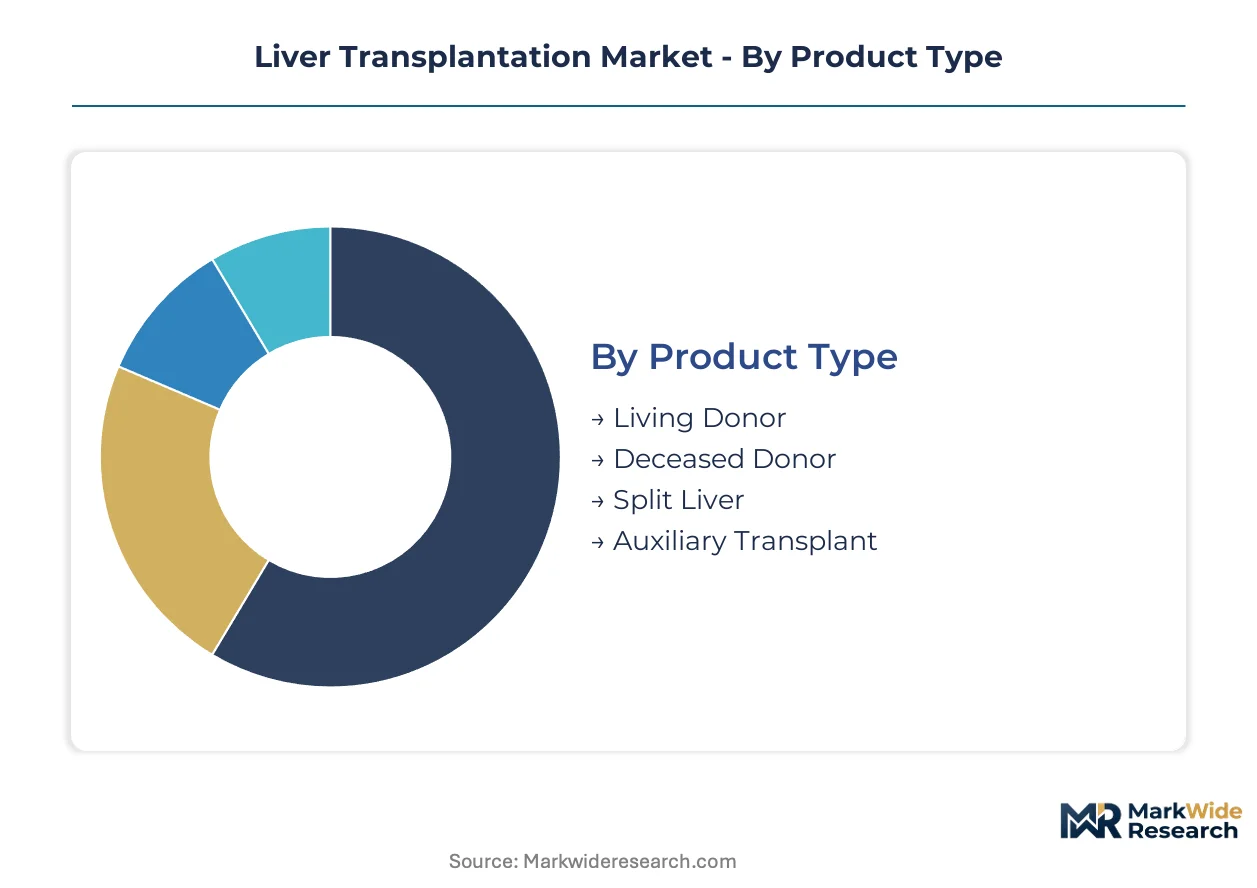
Surgical approach and donor source configuration determines reimbursement pathways, capital equipment requirements, and patient selection protocols across transplant programs. Indication-specific allocation algorithms and recipient risk stratification further fragment commercial opportunity by conditioning immunosuppression intensity and post-transplant monitoring frequency.
Product Type:
Technical complexity and graft procurement logistics differentiate procedure economics and center competency requirements.
- Living Donor:Hepatectomy of 40-60% of healthy liver parenchyma from voluntary donors with independent vascular and biliary supply. CMS reimbursement expansions in the United States now cover lost wages and travel, reducing financial barriers at high-volume academic centers.
- Deceased Donor:Whole-organ retrieval from brain-dead or circulatory-death donors with cold ischemia constraints under twelve hours. Germany dominates European procedure volumes through Eurotransplant allocation priority and elevated cirrhosis prevalence in industrial catchment zones.
- Split Liver:Parenchymal division enabling simultaneous pediatric and adult transplantation from single deceased donors. Technical advances in segmental anatomy mapping accelerate adoption at specialized hepatobiliary units.
- Auxiliary Transplant:Partial graft placement alongside native liver to provide temporary metabolic support with potential for regeneration and immunosuppression withdrawal. Niche application in acute liver failure and metabolic disorders.
Deceased donor procedures lead on scale; split liver transplantation leads on momentum.
Indication:
Disease etiology shapes waiting-list priority, graft survival expectations, and adjuvant therapy integration.
- Cirrhosis:End-stage fibrosis from alcohol, viral hepatitis, or non-alcoholic steatohepatitis with portal hypertension complications. MELD score-based allocation systems concentrate demand in high-urgency recipient pools across Germany, the Netherlands, and Austria.
- Hepatocellular Carcinoma:Primary liver malignancy constrained by Milan criteria for transplant eligibility. Checkpoint inhibitor adjuvant protocols and expanded radiographic criteria attract concentrated R&D investment from immunotherapy developers.
- Acute Liver Failure:Rapid hepatic necrosis from drug toxicity, viral infection, or autoimmune attack with encephalopathy progression. King College criteria determine super-urgent listing status with graft survival penalties from donor quality trade-offs.
- Cholestatic Disease:Progressive bile duct destruction in primary sclerosing cholangitis and biliary atresia with pruritus and fat-soluble vitamin deficiency. Pediatric dominance in biliary atresia segments drives specialized surgical volume at designated children's hospitals.
Cirrhosis leads on scale; hepatocellular carcinoma leads on momentum.
Care Setting:
Regulatory designation and reimbursement tier differentiate site-of-service economics and technology deployment.
- Transplant Centers:CMS-certified programs with mandated surgical volume thresholds, multidisciplinary committees, and organ procurement organization contracts. United States concentration in metropolitan statistical areas with academic medical center anchors.
- Hospitals:General acute care facilities providing pre-transplant evaluation and post-operative stabilization without independent organ procurement capacity. Rural access limitations concentrate evaluation travel burdens on donor candidates.
- Specialty Clinics:Outpatient hepatology and transplant infectious disease units managing immunosuppression titration and rejection surveillance. Telemedicine expansion reduces geographic barriers in underserved catchment areas.
- Home Care:Post-discharge monitoring for stable recipients with remote laboratory tracking and mobile health applications. Emerging segment with reimbursement uncertainty for non-physician services.
Transplant centers lead on scale; specialty clinics lead on momentum.
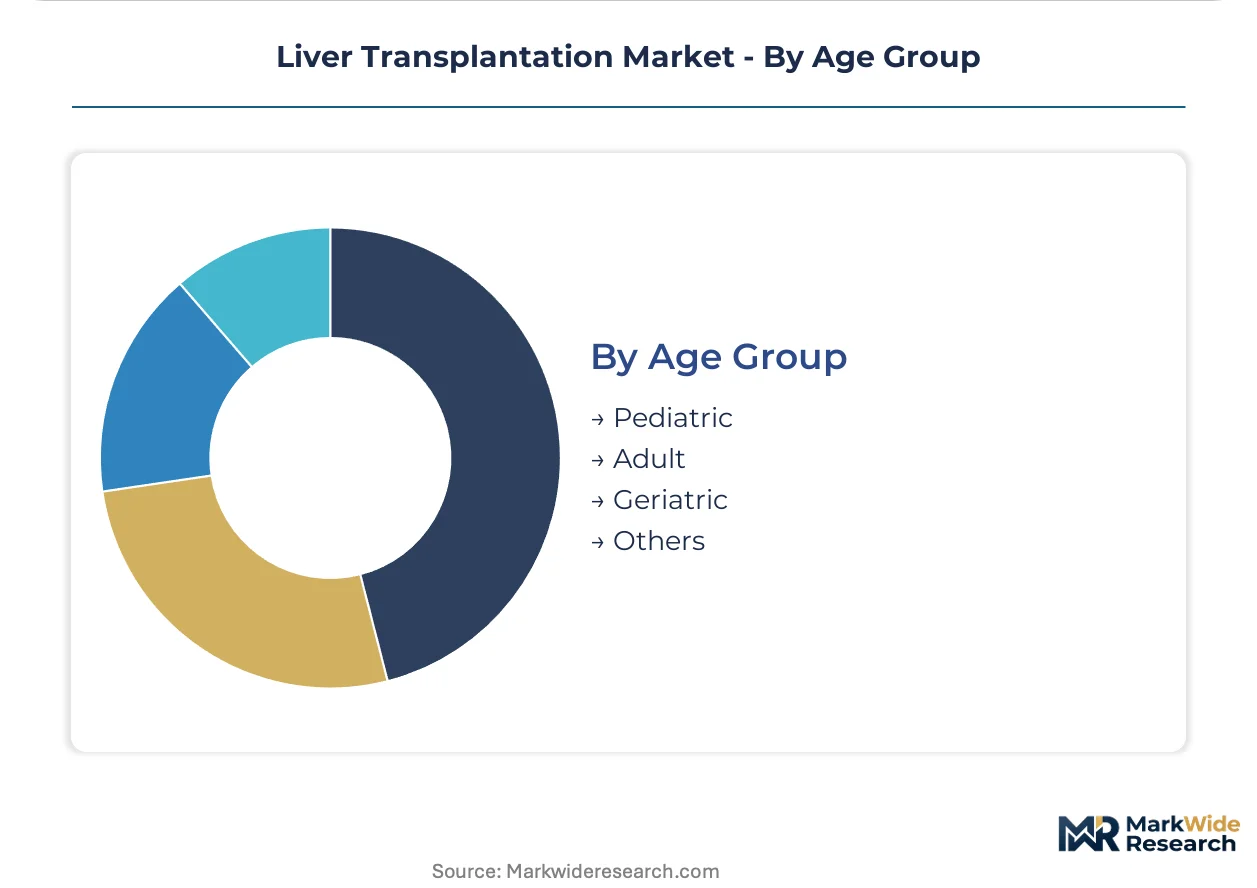
Age Group:
Recipient physiology determines graft size matching, immunosuppression protocols, and long-term survival modeling.
- Pediatric:Biliary atresia and metabolic disorders dominate indications with split liver and living donor preference for size-appropriate grafts. Technical specialization concentrates at designated children's transplant centers with dedicated anesthesia and critical care infrastructure.
- Adult:Cirrhosis and hepatocellular carcinoma peak incidence with full-size deceased donor grafts and machine perfusion technology adoption. Eurotransplant allocation algorithms prioritize urgency-adjusted medical benefit scores.
- Geriatric:Expanding recipient pool with modified immunosuppression intensity and cardiovascular comorbidity screening. Center-specific age cutoffs vary with recipient performance status and tumor biology.
- Others:Adolescent transition programs and rare disease categories with individualized protocol development.
Adult recipients lead on scale; geriatric recipients lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hepatobiliary surgeon density concentrates transplant capacity in metropolitan academic clusters, with Eurotransplant allocation algorithms and CMS reimbursement frameworks shaping regional access patterns across high-volume nations.
United States
Living donor program expansion accelerates at high-volume academic medical centers following CMS reimbursement revisions covering lost wages and travel expenses. FDA oversight through CMS conditions of participation mandates surgical volume thresholds and multidisciplinary committee structures. Transplant capacity clusters in metropolitan statistical areas anchored by academic medical centers in Houston, Pittsburgh, and Los Angeles, with machine perfusion adoption compressing geographic procurement constraints.
Germany
Elevated cirrhosis prevalence in industrial catchment zones sustains the highest European procedure volumes through Eurotransplant allocation priority. The EU Organ Donation Directive mandates standardized quality management systems and traceability infrastructure across transplant programs. Designated high-volume hubs in Berlin, Munich, and Hamburg centralize normothermic perfusion services to amortize MDR compliance costs and quality system audit obligations.
United Kingdom
NHS Blood and Transplant allocation frameworks prioritize super-urgent listings for acute liver failure while managing waiting-list mortality through optimized graft-recipient matching. The country's national pharmaceutical regulator enforces advanced therapy medicinal products classification for ex-vivo perfusion devices. Transplant programs concentrate at specialized hepatobiliary units in London, Birmingham, and Edinburgh with dedicated pediatric infrastructure for biliary atresia segments.
France
Agence de la biomédecine coordinates national allocation algorithms while ANSM oversees immunosuppression safety surveillance and post-market pharmacovigilance. Living donor advocacy organizations press for direct wage reimbursement, shifting financial burden from donors to statutory health insurance. Surgical expertise clusters at AP-HP institutions in Paris and regional university hospitals in Lyon and Marseille with established split liver transplantation protocols.
Japan
PMDA regulates organ perfusion device classifications under pharmaceutical and medical device frameworks, influencing technology adoption timelines at transplant centers. METI initiatives support domestic development of preservation technologies to reduce import dependence. Procedure volume concentrates at designated transplant hospitals in Tokyo, Osaka, and Nagoya with strict ABO-compatible matching protocols limiting expansion into incompatible transplantation.
Liver Transplantation Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across immunosuppression, surgical instrumentation, and organ preservation technology layers. The market structure exhibits tiered consolidation with pharmaceutical incumbents anchoring post-transplant maintenance revenue and medical technology firms capturing procedural instrumentation spend. Three archetypes dominate: diversified healthcare conglomerates with transplant-adjacent portfolios, specialized immunosuppression developers with recurring revenue protocols, and surgical instrumentation providers with procedure-specific device ecosystems. Competitive moves center on portfolio diversification into adjacent transplant technologies and strategic partnerships to secure procurement organization contracts.
Among diversified healthcare conglomerates, AbbVie Inc. and Novartis AG exemplify pharmaceutical archetypes with immunosuppression positioning in post-transplant maintenance protocols, while Medtronic occupies a position in surgical instrumentation with specialized vascular sealing and retraction systems. Baxter International Inc. represents the medical technology tier with perfusion and preservation adjacencies. These anchors demonstrate how incumbent players leverage existing hospital relationships and reimbursement pathways to defend position across transplant center procurement decisions.
| Leading Market Players |
|---|
| AlloSource |
| Dompé farmaceutici S.p.A. |
| Thompson Surgical |
| Integra LifeSciences |
| AbbVie Inc. |
| Novartis AG |
| Medtronic |
| RedHill Biopharma Ltd. |
| Baxter International Inc. |
| Others |
Supply & Pricing Matrix
Organ procurement organization reimbursement benchmarks cascade through transplant center procurement decisions into tiered service pricing across living donor, deceased donor, and machine perfusion protocols. CMS conditions of participation and Eurotransplant allocation algorithms compress margin flexibility at mid-volume centers while high-volume academic hubs amortize fixed costs across expanded procedure volumes.
Pricing Analysis
Bundled episode-of-care contracts dominate deceased donor procedures while unbundled itemized billing persists for living donor evaluation and machine perfusion add-ons. Three-tier pricing structure across premium, standard, and economy levels reflects center certification tier, surgical volume thresholds, and after-transplant care bundling. Cost compression in perfusion disposables is intensifying because single-use circuit expenses exceed cold storage by an order of magnitude. Safety-net hospitals and rural transplant programs exhibit the highest price sensitivity, while academic medical centers with research funding demonstrate the lowest.
Supply Chain Analysis
Hepatobiliary surgeon workforce scarcity in the United States, Germany, and United Kingdom constrains procurement organization graft retrieval capacity and extends cold ischemia windows. Supply chains draw from specialized immunosuppression manufacturing in Switzerland and Ireland, surgical instrumentation production in Germany and Japan, and perfusion device assembly in the United States and Netherlands. Single-source vulnerability in normothermic machine perfusion circuits creates bottleneck risk at centers dependent on TransMedics Organ Care Systems. Distribution runs through CMS-certified transplant centers with organ procurement organization contracts, bypassing general hospital procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds regulatory tailwinds into sustained procedure volume expansion, with CMS reimbursement revisions for living donor programs representing the most visible demand catalyst across the analysis window.
For Market Incumbents: Anchor post-transplant maintenance revenue through immunosuppression portfolio breadth against biosimilar erosion threats. Pursue backward integration into organ perfusion services to capture procurement organization technology budgets. Deepen hospital system partnerships with GPO contracts managers to secure formulary positioning for maintenance protocols. For New Entrants and Emerging Players: Telemedicine-based living donor evaluation platforms offer the most penetrable white-space target, particularly in underserved rural catchment areas with geographic barriers to donor recruitment. Split liver transplantation technical services represent a secondary entry vector for specialized hepatobiliary surgical consultancies. Pursue direct-to-transplant-center software licensing to bypass incumbent device distribution channels. For Investors and Strategic Acquirers: Asymmetric upside sits with machine perfusion technology developers with FDA breakthrough device designation and emerging reimbursement codes. Long-term viability hinges on outcome data maturation sufficient for payer coverage expansion. Watch for harmonized machine perfusion clinical trial endpoints as the inflection signal for technology consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Living Donor Program Expansion | CMS reimbursement revisions enable lost-wage coverage, reducing financial barriers for donor recruitment. |
| Normothermic Perfusion Adoption | FDA breakthrough designation accelerates coverage pathways for marginal graft acceptance protocols. |
| Immunosuppression Portfolio Diversification | mTOR inhibitor positioning in high-risk recipients defends against generic tacrolimus erosion. |
| Telemedicine Donor Evaluation | Remote assessment protocols expand donor pools in rural catchment areas with surgeon workforce gaps. |
| Split Liver Technical Training | Segmental anatomy mapping capabilities maximize single-deceased-donor utility across pediatric-adult recipient pools. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining hepatobiliary surgeon interviews, transplant center administrator discussions, organ procurement organization executive consultations, and payer formulary director assessments with secondary validation. FDA 510(k) filings, CMS Medicare cost report data, Eurotransplant annual statistics, and EMA advanced therapy medicinal products registrations anchored supply-side modeling. Bottom-up procedure volume estimates triangulated against top-down immunosuppression revenue segmentation.
Comparable-period anchoring linked historical transplant registry data to forward projection assumptions across the modeling period. Segmentation dimensions included donor source configuration, indication-specific allocation algorithms, care setting regulatory tier, and recipient age physiology. CAGRs derived from logistic diffusion modeling of machine perfusion adoption curves, conditioned on reimbursement policy scenarios and surgeon workforce growth constraints.
The model assumes a particular technology adoption path; alternative pathways for normothermic machine perfusion would alter the outlook if cold storage protocol improvements match graft survival outcomes. Forecasts reflect assumptions about CMS living donor reimbursement expansion continuity and Eurotransplant allocation algorithm stability. Material deviation in FDA perfusion device classification decisions or hepatobiliary fellowship training position growth warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Rett Syndrome Treatment Market
Medical Treatment
Hyponatremia Treatment Market
Medical Treatment
Parathyroid Disease Treatment Market
Medical Treatment
Radioactive Iodine Ablation Therapy Market
Medical Treatment
Adenomyosis Treatment Market
Medical Treatment
Cephalic Disorders Treatment Market
Medical Treatment
Gunshot Injuries Treatment Market
Medical Treatment
Mexico Hair Transplant Market
Medical Treatment
North America Nerve Repair and Regeneration Market
Medical Treatment
Scalp Care Treatment Market
Medical Treatment
Myotonic Dystrophy Treatment Market
Medical Treatment
Surgical Procedures Volume Market
Medical Treatment
House Dust Mite Allergy Treatment Market
Medical Treatment
Global Sciatica Market
Medical Treatment
Global Systemic Lupus Erythematosus Treatment Market
Medical Treatment
Thymus Cancer Treatment Market