
 Pompe Disease Treatment Market | 2026-2036
Pompe Disease Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Pompe Disease Treatment Market Analysis
High-purity recombinant enzyme formulations is rotating toward center stage as clinicians and payers prioritize sustained efficacy profiles over cost-minimization strategies. Sanofi leverages its manufacturing scale to anchor supply security for intravenous alglucosidase alfa across major treatment centers. Amicus Therapeutics competes through differentiated oral small-molecule adjunct therapy that addresses limitations of ERT monotherapy. Genzyme Corporation sustains its historical presence in lysosomal storage disorder care through deep clinical trial infrastructure and established prescriber relationships.
Pompe disease treatment encompasses therapeutic interventions targeting acid alpha-glucosidase deficiency, a progressive glycogen storage disorder characterized by lysosomal glycogen accumulation in cardiac, skeletal, and smooth muscle tissues. Recombinant human GAA enzyme manufactured in CHO cell bioreactors requires specific glycosylation patterns to enable mannose-6-phosphate receptor-mediated cellular uptake, with dosing typically calibrated by patient weight and disease phenotype severity. Enzyme Replacement Therapy occupies the dominant revenue position due to established reimbursement pathways and decades of clinical validation, while Gene Therapy represents the fastest-expanding development category as AAV vector manufacturing matures and durability questions advance through late-stage trials. Intravenous Infusion remains the standard delivery mode for approved biologics, though Subcutaneous Injection formats under investigation promise to shift site-of-care economics toward home administration.
FDA orphan drug exclusivity provisions and EMA's pediatric investigation plan requirements shape development timelines and commercial exclusivity structures for manufacturers seeking market access. Japan's PMDA Sakigake designation accelerates review for innovative modalities, creating competitive pressure on Western regulators to streamline pathways for next-generation approaches. Stakeholders must monitor how payer evidence requirements evolve for gene therapy candidates promising functional cure versus chronic ERT dependence.
Market Dynamics
Gene therapy vectors are compressing development timelines and forcing established enzyme replacement manufacturers to reposition clinical trial infrastructure around functional cure endpoints rather than chronic disease management.
Growth Catalysts
- Newborn screening mandates:State-level expansion of dried blood spot testing protocols in the United States accelerates infantile-onset diagnosis and treatment initiation before irreversible muscle damage accumulates.
- EMA orphan drug incentives:Pediatric investigation plan requirements and market exclusivity provisions sustain manufacturer commitment to rare disease pipelines despite limited addressable populations.
- Mannose-6-phosphate glycoengineering:Improved cellular uptake efficiency in next-generation recombinant enzyme formulations enhances tissue penetration in skeletal muscle, addressing a historical pharmacokinetic limitation of intravenous ERT.
Market Restraints
- Bioreactor capacity concentration:Mammalian cell culture manufacturing for clinical-grade GAA enzyme concentrates among a limited set of contract development organizations, creating single-source vulnerability for commercial supply security.
- Infusion center infrastructure gaps:Rural and secondary hospital networks lack dedicated spaces for multi-hour intravenous enzyme administration, restricting patient access outside major metropolitan treatment hubs.
- Immunogenicity management complexity:Neutralizing antibody formation against recombinant GAA protein necessitates immunomodulation protocols that complicate long-term therapeutic continuity and outcomes predictability.
Strategic Opportunities
- Subcutaneous delivery platforms:Recombinant enzyme formulations compatible with home injection devices promise to shift site-of-care economics away from hospital-based infusion centers toward outpatient and residential settings.
- Late-onset phenotype underdiagnosis:Adult patients presenting with progressive limb-girdle weakness represent a substantial untreated reservoir in Germany and Japan where neuromuscular referral pathways remain suboptimal.
- AAV vector manufacturing scale-up:Contract gene therapy producers in the United States and Switzerland are expanding GMP capacity to support pivotal trials for one-time functional cure candidates targeting liver-directed GAA expression.
Industry Challenges
- Gene therapy durability uncertainty:Long-term expression stability of transduced GAA transgenes in human hepatocytes remains unvalidated, complicating payer value assessments and reimbursement negotiations for curative modalities.
- Cross-functional talent scarcity:Clinical development teams require combined expertise in lysosomal storage disorder natural history, immunogenicity risk mitigation, and vector immunology that remains concentrated among a limited specialist workforce.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pompe Disease Treatment Market |
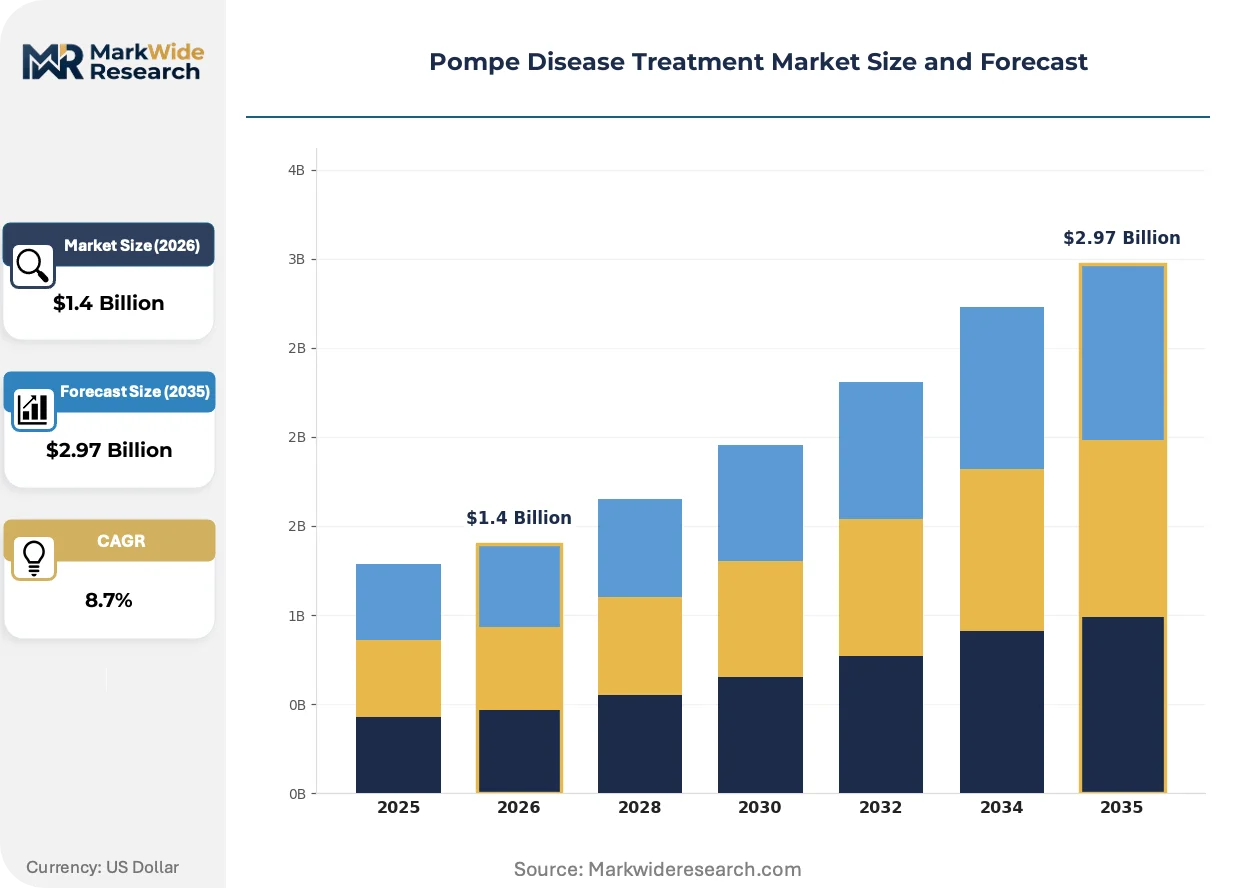
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.97 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Enzyme Replacement Therapy, Gene Therapy, Small Molecule, Others End User: Hospitals, Clinics, Home Care, Specialty Pharmacies Application: Infantile Form, Late-Onset Form, Asymptomatic Form, Carrier Screening Delivery Mode: Intravenous Infusion, Subcutaneous Injection, Oral, Intramuscular Injection |
| Companies Covered | Sanofi, Amicus Therapeutics, Genzyme Corporation, Novartis AG, Astellas Pharma, Valerion Therapeutics, Audentes Therapeutics, Roche, Fresenius Kabi AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pompe Disease Treatment Market Emerging Trajectories
Next-generation therapeutic modalities are fragmenting the historical ERT monopoly and forcing incumbent manufacturers to defend market position through combination therapy strategies rather than standalone enzyme products.
AAV9-based gene therapy constructs designed for systemic GAA expression are displacing chronic intravenous infusion paradigms in prescriber preference hierarchies. Pediatric metabolic specialists at quaternary referral centers are prioritizing clinical trial enrollment for one-time administration candidates. This technology is displacing the assumption of lifelong treatment dependence that has structured two decades of Pompe disease commercial strategy.
Japan's PMDA Sakigake designation pathway accelerates review timelines for innovative modalities and creates competitive pressure on FDA and EMA to streamline comparable access mechanisms. Western regulators are responding with adaptive trial design guidance that accommodates smaller patient populations and surrogate endpoint acceptance. Gene therapy developers targeting the United States market are structuring rolling submission strategies to match Japanese regulatory speed.
Hospital procurement committees are unbundling enzyme acquisition from infusion service contracts and negotiating direct purchasing arrangements with specialty distributors. This pattern compresses margins for integrated health system vendors while creating openings for independent specialty pharmacies with cold-chain logistics capabilities. The United States exhibits the most pronounced shift toward decentralized acquisition models as accountable care organizations seek to capture site-of-care differential economics.
Pompe Disease Treatment Market Segmentation
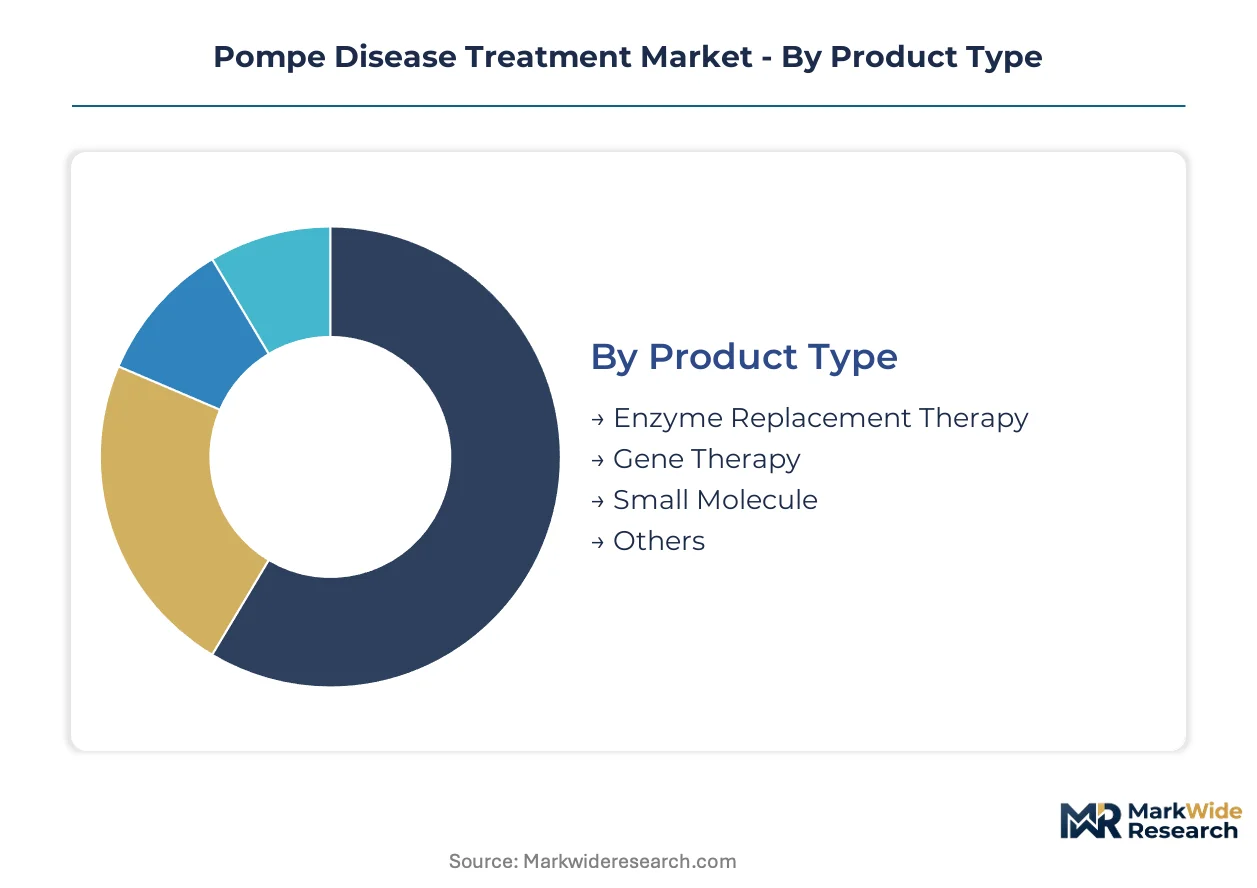
Segmentation in Pompe disease treatment reveals how therapeutic modality, care setting, and patient phenotype interact to determine access pathways and reimbursement structures. Manufacturers must align portfolio investments with the specific clinical and logistical requirements of each segment combination.
Product Type:
Gene therapy vectors pose the most acute substitution threat to established enzyme replacement platforms, compressing the window for manufacturers to capture lifetime value from chronic administration models.
- Enzyme Replacement Therapy:Recombinant human acid alpha-glucosidase manufactured in CHO cell bioreactors requires mannose-6-phosphate glycoengineering for lysosomal targeting. Demand concentrates in major metropolitan hospital systems across the United States, Germany, and Japan where infusion center infrastructure and specialist metabolic expertise coexist.
- Gene Therapy:AAV9-based vectors designed for systemic GAA expression promise functional cure through one-time administration. Clinical trial enrollment at quaternary referral centers in the United States and Switzerland is accelerating as manufacturing scale matures, though payer uncertainty around durability complicates commercial planning.
- Small Molecule:Pharmacological chaperones stabilize misfolded GAA enzyme to improve cellular trafficking.
- Others:Investigational modalities including substrate reduction therapy and mRNA-based approaches remain preclinical.
Enzyme Replacement Therapy anchors the volume base while Gene Therapy gains share at the steepest rate.
End User:
Cost tier differentiation separates high-complexity academic medical centers from decentralized outpatient channels seeking site-of-care arbitrage.
- Hospitals:Quaternary referral centers with dedicated metabolic disease units manage infantile-onset cases requiring intensive cardiac and respiratory monitoring. These institutions in the United States and Germany negotiate direct purchasing arrangements that bypass traditional specialty distributor markups.
- Clinics:Neuromuscular and genetic counseling practices identify late-onset phenotypes through progressive limb-girdle weakness presentations. Diagnostic yield in Japan and Germany remains constrained by fragmented referral pathways from primary care.
- Home Care:Subcutaneous delivery platforms under development would shift administration from infusion centers to residential settings.
- Specialty Pharmacies:Independent distributors with cold-chain logistics capabilities are capturing procurement committee contracts unbundled from hospital service agreements.
Hospitals retain the highest patient acuity mix while Specialty Pharmacies expand fastest through decentralized acquisition models.
Application:
Volume concentration in infantile diagnosis reflects newborn screening penetration, while adult phenotype recognition represents the largest addressable expansion opportunity.
- Infantile Form:Severe GAA deficiency presenting within months of birth with hypertrophic cardiomyopathy and hypotonia. State-level dried blood spot mandates in the United States and prefectural screening expansion in Japan compress time to treatment initiation.
- Late-Onset Form:Progressive skeletal myopathy without cardiac involvement, frequently misdiagnosed as limb-girdle muscular dystrophy. Underdiagnosis in Germany and Japan creates substantial untreated reservoir as neuromuscular referral pathways remain suboptimal.
- Asymptomatic Form:Identified through family cascade screening or incidental findings.
- Carrier Screening:Preconception and prenatal testing protocols for at-risk populations.
Infantile Form anchors the volume base while Late-Onset Form gains share at the steepest rate.
Delivery Mode:
Supply concentration in intravenous manufacturing creates vulnerability that subcutaneous and oral alternatives are engineered to resolve.
- Intravenous Infusion:Established administration route for approved biologics requiring multi-hour hospital-based sessions. Infusion center infrastructure gaps in rural United States networks restrict patient access outside major metropolitan hubs.
- Subcutaneous Injection:Recombinant enzyme formulations compatible with home injection devices promise to shift site-of-care economics. Development programs in the United States and Switzerland target reduced infusion burden and improved quality-of-life metrics.
- Oral:Small-molecule pharmacological chaperones enable patient-administered therapy without cold-chain requirements.
- Intramuscular Injection:Localized delivery approaches remain investigational for tissue-specific targeting.
Intravenous Infusion anchors the volume base while Subcutaneous Injection gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity for clinical-grade recombinant enzymes clusters among contract development organizations in the United States, Switzerland, and select Asian hubs. This geographic concentration creates supply security vulnerabilities that regional regulators are addressing through localized production incentives and accelerated approval pathways.
United States
Newborn screening mandates in over 40 states now include Pompe disease detection, compressing time-to-treatment for infantile-onset patients. FDA orphan drug exclusivity provisions sustain manufacturer commitment despite limited addressable populations. Boston and San Francisco anchor gene therapy development clusters where AAV vector manufacturing scale is maturing.
Germany
Quaternary referral centers in Munich and Heidelberg manage high-acuity infantile cases through established metabolic disease units. EMA pediatric investigation plan requirements shape development timelines for manufacturers seeking European market access. Late-onset phenotype underdiagnosis persists due to fragmented neuromuscular referral pathways from primary care.
Japan
Prefectural expansion of dried blood spot testing accelerates infantile diagnosis beyond Tokyo and Osaka metropolitan areas. PMDA Sakigake designation creates competitive pressure for streamlined regulatory pathways. Yokohama and Kobe host contract manufacturing facilities supporting clinical-grade enzyme supply for domestic and export markets.
Switzerland
Gene therapy vector production capacity in Basel and Zurich supports pivotal trials for liver-directed GAA expression candidates. Swissmedic aligns review timelines with EMA frameworks while maintaining independent assessment authority. Contract manufacturers are expanding GMP facilities to meet demand from Western pipeline sponsors.
United Kingdom
NHS specialized commissioning frameworks concentrate infantile-onset treatment at designated metabolic centers in London and Manchester. MHRA post-Brexit regulatory autonomy enables adaptive trial design guidance for rare disease modalities. Research partnerships between academic medical centers and gene therapy developers are intensifying.
Pompe Disease Treatment Market Vendor Landscape
Concentration sits with integrated biopharmaceutical conglomerates and specialized rare disease therapeutics developers. The market structure reflects consolidation around enzyme replacement platforms alongside fragmentation among gene therapy innovators. Three archetypes dominate: large-cap diversified manufacturers with manufacturing scale, mid-cap rare disease specialists with clinical trial infrastructure, and emerging gene therapy pure-plays with vector technology. Competitive moves center on subcutaneous delivery platform development and AAV manufacturing capacity expansion.
Within the integrated conglomerate tier, Sanofi anchors supply security through bioreactor scale, while Genzyme Corporation exemplifies historical lysosomal storage disorder presence. Among rare disease specialists, Amicus Therapeutics occupies a position differentiated by oral small-molecule adjunct therapy. These three represent the strategic positioning spectrum from manufacturing dominance through clinical infrastructure depth to modality innovation.
| Leading Market Players |
|---|
| Sanofi |
| Amicus Therapeutics |
| Genzyme Corporation |
| Novartis AG |
| Astellas Pharma |
| Valerion Therapeutics |
| Audentes Therapeutics |
| Roche |
| Fresenius Kabi AG |
| Others |
Supply Flow & Price Mechanics
FDA orphan drug exclusivity provisions gate both supply qualification and price differentiation simultaneously, requiring manufacturers to navigate pediatric investigation plans and market exclusivity structures before commanding premium positioning for novel enzyme formulations.
Pricing Analysis
FDA orphan drug exclusivity dictates the pricing tier structure across recombinant enzyme therapies, with mannose-6-phosphate glycoengineering quality separating premium formulations from standard ERT alternatives. Price differentiation centers on tissue penetration efficiency and immunogenicity profiles, with infantile-onset indications commanding the highest reimbursement rates. Cost compression in late-onset segments is intensifying as gene therapy candidates enter pivotal trials. Payers in the United States exhibit the greatest price sensitivity, while Japanese procurement committees prioritize supply security over cost minimization.
Supply Chain Analysis
The United States and Switzerland anchor clinical-grade recombinant enzyme manufacturing, with contract development organizations in Basel and Boston producing GMP-certified acid alpha-glucosidase for global distribution. Raw material dependencies center on CHO cell culture media, mannose-6-phosphate modification reagents, and cold-chain packaging systems. Single-source vulnerability concentrates among a limited set of mammalian cell bioreactor facilities. Distribution runs through hospital procurement committees unbundling acquisition from infusion services, with specialty pharmacies capturing decentralized contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Gene therapy pipeline maturation signals a cyclical recovery as AAV manufacturing scale validates durability hypotheses and compresses development timelines for functional cure candidates.
For Market Incumbents: Compound manufacturing scale advantages through backward integration into CHO cell bioreactor capacity in the United States and Switzerland, securing supply continuity against gene therapy substitution. Deepen prescriber relationships at quaternary referral centers to defend enrollment share against emerging AAV developers. Prioritize subcutaneous delivery platform investment to shift site-of-care economics before outpatient gene therapy administration normalizes.
For New Entrants and Emerging Players: Japan's PMDA Sakigake designation offers the fastest regulatory pathway for novel modalities, enabling accelerated market access ahead of FDA and EMA timelines. Target late-onset phenotype underdiagnosis in Germany and Japan where fragmented neuromuscular referral pathways leave substantial untreated reservoirs. Pursue home administration positioning through subcutaneous formulation partnerships with established metabolic disease networks.
For Investors and Strategic Acquirers: EMA pediatric investigation plan requirements reshape the acquisition landscape by extending exclusivity periods for compliant developers, creating differentiated holding value. Gene therapy pure-plays with validated AAV9 liver-directed constructs represent the highest-conviction target archetype over the medium-term horizon. Monitor payer coverage determinations for one-time administration candidates as the critical inflection signal for modality substitution velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| AAV Vector Manufacturing Scale-Up | Basel and Boston facilities expand GMP capacity to supply pivotal gene therapy trials. |
| Subcutaneous Delivery Platform Development | Home injection devices shift economics from hospital infusion centers toward residential settings. |
| Newborn Screening Mandate Expansion | State-level dried blood spot protocols in the United States compress time-to-treatment initiation. |
| Mannose-6-Phosphate Glycoengineering Investment | Enhanced cellular uptake efficiency addresses historical skeletal muscle penetration limitations. |
| PMDA Sakigake Designation Pursuit | Accelerated Japanese review creates competitive pressure on Western regulatory timelines. |
Methodological Framework
Cross-validation between primary interviews with metabolic disease specialists and secondary analysis of FDA orphan drug filings anchors the qualitative findings in this study. Conversations with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists informed competitive positioning assessments. Secondary sources included ClinicalTrials.gov enrollment data, EMA pediatric investigation plan submissions, formulary databases, and SEC 10-K disclosures from publicly traded manufacturers. Bottom-up patient population estimates triangulated against top-down revenue reconstructions across the analysis window.
Sensitivity analysis around newborn screening penetration rates and gene therapy durability assumptions shaped the analytical framework. Segmentation dimensions modeled encompassed therapeutic modality, patient phenotype, administration route, care setting, and regional regulatory cluster. CAGRs derived from fitted growth curves calibrated against historical ERT adoption patterns and emerging modality substitution elasticities. Forecast inputs incorporated immunogenicity incidence rates, bioreactor capacity expansion schedules, and payer coverage determination timelines.
Underlying assumptions cover sustained orphan drug exclusivity provisions, with deviation risk concentrated in gene therapy durability validation and subcutaneous formulation approval delays. Recalibration cycles align with material shifts in regulatory pathway streamlining, manufacturing scale milestones, and payer value assessment frameworks.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Scoliosis Management Market
Medical Treatment
Global Fabry Disease Treatment Market
Medical Treatment
Global Nano Therapy Market
Medical Treatment
Monkeypox Treatment Market
Medical Treatment
Transarterial Chemoembolization (TACE) Market
Medical Treatment
Spinal Cord Compression Market
Medical Treatment
Cysticercosis (Taeniasis) Treatment Market
Medical Treatment
Birch Allergy Treatment Market
Medical Treatment
House Dust Mite Allergy Treatment Market
Medical Treatment
Squamous Cell Carcinoma Treatment Market
Medical Treatment
Anorectal Malformation Treatment Market
Medical Treatment
Radioactive Iodine Ablation Therapy Market
Medical Treatment
Tauopathies Treatment Market
Medical Treatment
Hepatocellular Carcinoma (HCC) Treatment Market
Medical Treatment
Allergy Treatment Market
Medical Treatment
Non-Infectious Diarrhea Treatment Market