
 Polycystic Ovary Syndrome (PCOS) Treatment Market | 2026-2036
Polycystic Ovary Syndrome (PCOS) Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Polycystic Ovary Syndrome (PCOS) Treatment Market Outlook
Reproductive endocrinology fellowship capacity is bifurcating the competitive landscape, as training program expansion lags behind patient volume growth in major metropolitan corridors. Novartis AG leverages its metabolic disorder portfolio to sustain presence across insulin sensitizer categories. Bayer AG anchors its position through ovulation induction expertise developed across European academic medical centers. Cipla Limited competes on cost-structured manufacturing for oral hormonal formulations distributed through emerging market channels.
Polycystic Ovary Syndrome treatment encompasses pharmaceutical and surgical interventions targeting hyperandrogenism, ovulatory dysfunction, and insulin resistance in reproductive-age patients. Standard therapeutic regimens combine oral contraceptives with metformin-based protocols, while newer approaches integrate GLP-1 receptor agonists for metabolic comorbidity management. Hormonal therapy occupies the largest revenue pool due to chronic administration requirements, though insulin sensitizers represent the fastest-expanding category as metabolic phenotyping improves diagnostic precision. The administration route dimension shows oral formulations maintaining volume leadership while transdermal delivery gains traction among patients seeking adherence flexibility.
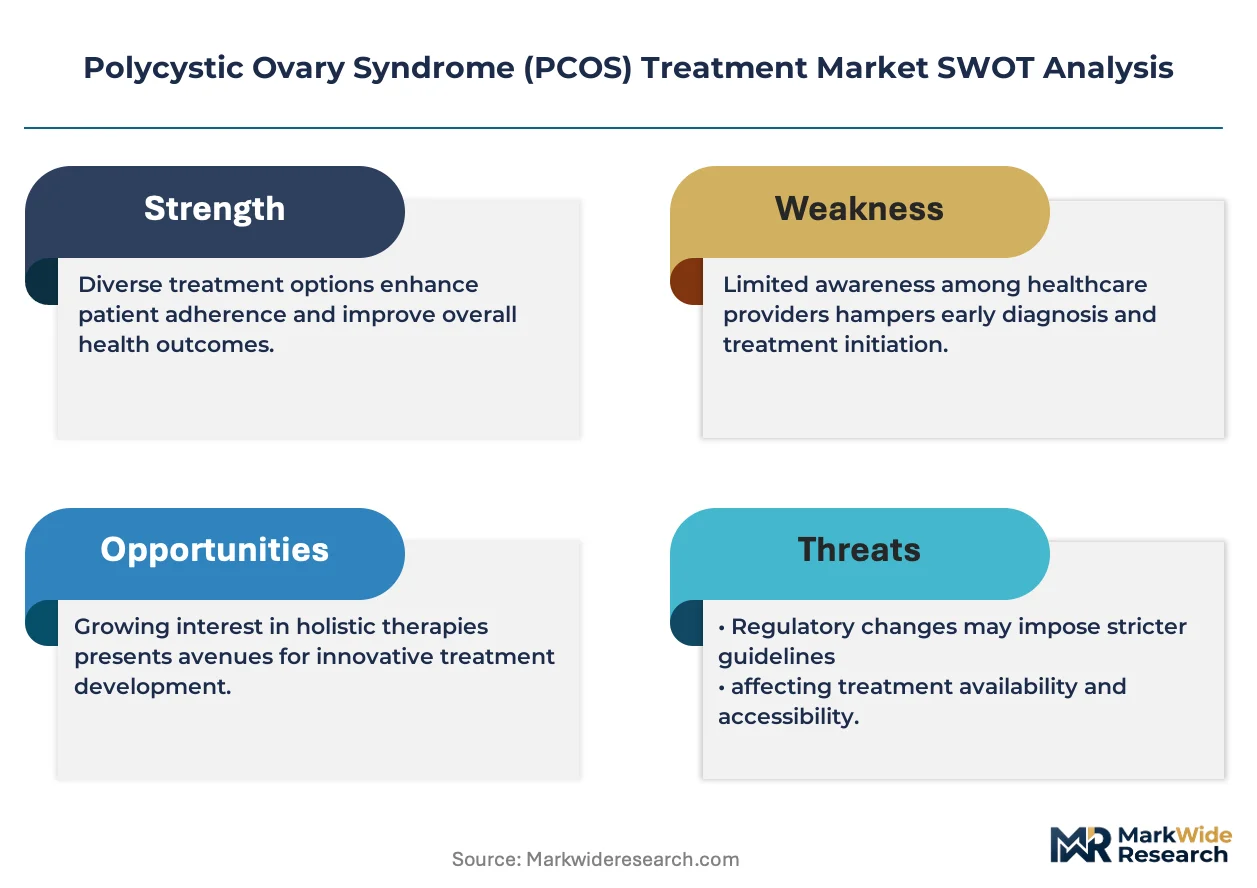
FDA oversight of reproductive endocrinology products shapes clinical development timelines and label expansion pathways for metabolic indication claims. EMA's MDR framework and REACH compliance requirements govern device-based interventions and excipient safety profiles across European distribution networks. Stakeholders must monitor evolving reimbursement criteria for lifestyle-intervention combinations as payers tighten prior authorization standards for chronic hormonal therapy.
Market Dynamics
GLP-1 receptor agonists are restructuring therapeutic hierarchies in PCOS management, forcing incumbent insulin sensitizers to defend metabolic indication claims through expanded cardiovascular outcome trials. Reproductive endocrinology networks are consolidating around phenotype-specific protocols that stratify patients by androgen excess severity and insulin resistance markers.
Growth Catalysts
- Metabolic phenotyping protocols:Fertility clinics in the United States are deploying advanced insulin resistance biomarker panels to identify candidates for combination therapy earlier in the diagnostic pathway.
- EMA's MDR framework:Device-based ovarian drilling interventions face streamlined conformity assessment procedures, accelerating market access for minimally invasive surgical alternatives across European academic medical centers.
- Integrated care networks:Large metropolitan hospital systems are embedding reproductive endocrinologists within diabetes management programs, creating cross-referral pathways for metabolic syndrome patients with ovulatory dysfunction.
Market Restraints
- Active pharmaceutical ingredient concentration:Contract manufacturing for metformin hydrochloride concentrates in Indian and Chinese supplier bases, exposing formulation sponsors to geopolitical trade friction and import inspection backlogs.
- Reproductive toxicology data gaps:GLP-1 agonist developers face extended teratogenicity study requirements that delay label expansion into preconception populations.
- Oral contraceptive substitution:Generic drospirenone-ethinyl estradiol formulations commoditize hormonal therapy revenue pools, compressing branded portfolio margins.
Strategic Opportunities
- Brazilian regulatory acceleration:ANVISA's priority review pathway for rare endocrine disorders creates expedited entry for novel androgen receptor antagonists targeting hirsutism-dominant phenotypes.
- Telemedicine prescription channels:Direct-to-patient platforms are capturing chronic medication refills for oral contraceptives and metformin, bypassing traditional reproductive endocrinology clinic gatekeepers.
- Digital therapeutics convergence:Smartphone-based ovulation tracking paired with continuous glucose monitoring enables personalized lifestyle intervention dosing that pharmaceutical sponsors can co-develop as combination products.
Industry Challenges
- Reproductive endocrinology fellowship scarcity:Training program output in the United States fails to match patient volume growth in Sun Belt metropolitan corridors, creating access bottlenecks for complex metabolic phenotype management.
- Multi-site trial coordination:Principal investigators must reconcile FDA's evolving guidance on metabolic disorder endpoints with institutional review board variability across academic medical centers, extending clinical development timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polycystic Ovary Syndrome (PCOS) Treatment Market |
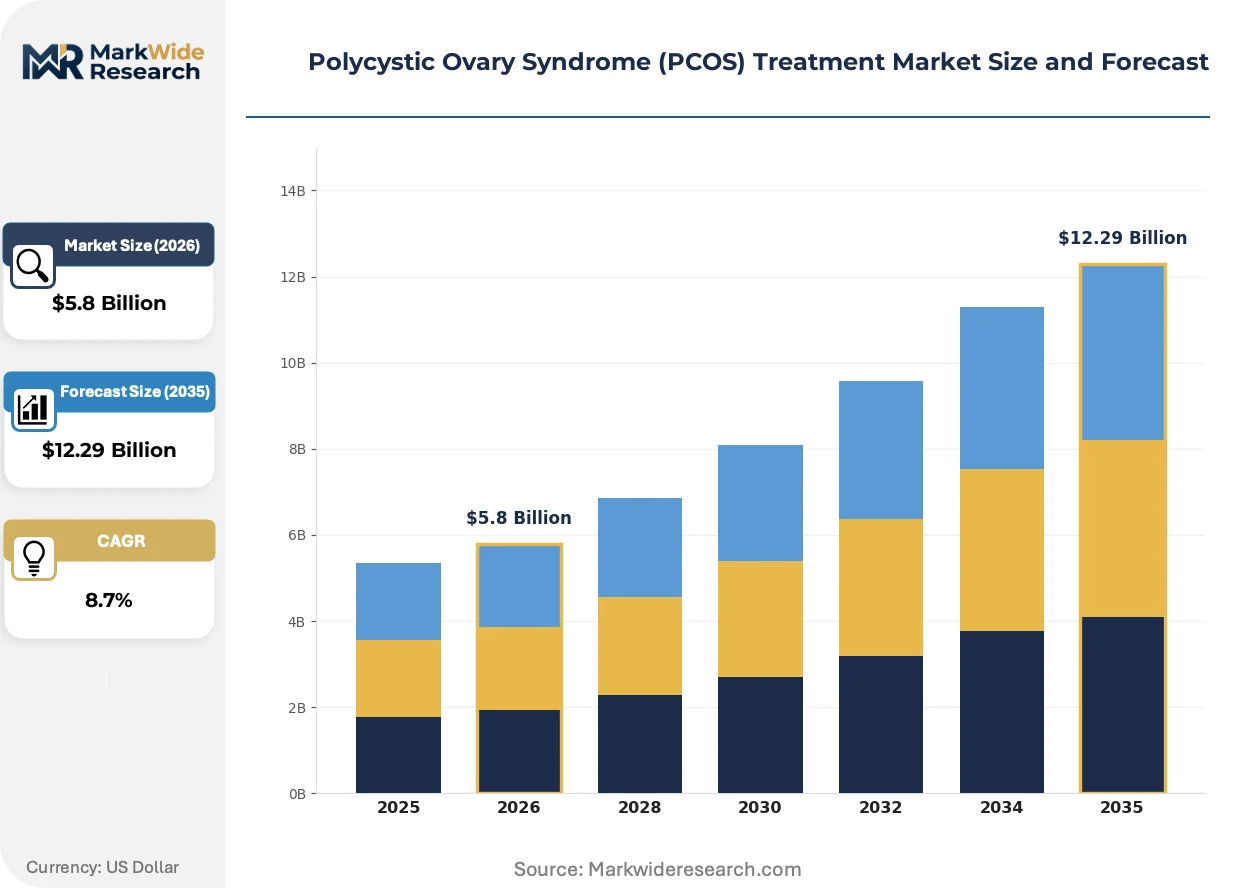
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $12.29 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hormonal Therapy, Insulin Sensitizers, Ovulation Induction Agents, Anti-Androgens Administration Route: Oral, Injectable, Transdermal, Intrauterine End User: Hospital, Clinics, Homecare, Specialty Pharmacies Therapeutic Area: Reproductive Health, Metabolic Disorders, Endocrinology, Psychiatry |
| Companies Covered | Novartis AG, Cipla Limited, Pfizer Inc., Dr. Reddy’s Laboratories Ltd., Sun Pharmaceutical Industries Ltd., Bayer AG, Sanofi S.A., May Health, Teva Pharmaceutical Industries Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polycystic Ovary Syndrome (PCOS) Treatment Market Strategic Shifts
Continuous glucose monitoring integration is redefining therapeutic monitoring standards in PCOS, enabling real-time metabolic feedback loops that phenotype-specific protocols can leverage for dose optimization. The convergence of digital biomarkers with pharmaceutical interventions is compressing traditional trial-and-error medication titration cycles.
GLP-1 receptor agonist therapy is displacing metformin monotherapy as the first-line metabolic intervention for insulin-resistant PCOS phenotypes. Endocrinology practices in the United States are adopting these agents at accelerating velocity for patients with concurrent prediabetes. This pharmacologic shift is compressing revenue contribution from older biguanide formulations while expanding addressable metabolic comorbidity markets.
FDA's evolving guidance on metabolic disorder drug labeling is reshaping cardiovascular outcome trial requirements for PCOS-specific indications. Sponsors must now demonstrate long-term glycemic stability and weight maintenance endpoints beyond traditional ovulation restoration metrics. Insulin sensitizer developers targeting United States market access are responding by extending follow-up periods and enrolling metabolic syndrome-enriched cohorts.
Patient-driven channel migration toward direct-to-consumer telemedicine platforms is fragmenting traditional reproductive endocrinology referral pathways. Women aged 25-35 in United States suburban markets increasingly initiate hormonal therapy through asynchronous digital consultations rather than clinic-based evaluation. This behavioral shift concentrates prescription volume with platform-integrated pharmacies and reduces specialist-mediated diagnostic rigor.
Polycystic Ovary Syndrome (PCOS) Treatment Market Segmentation
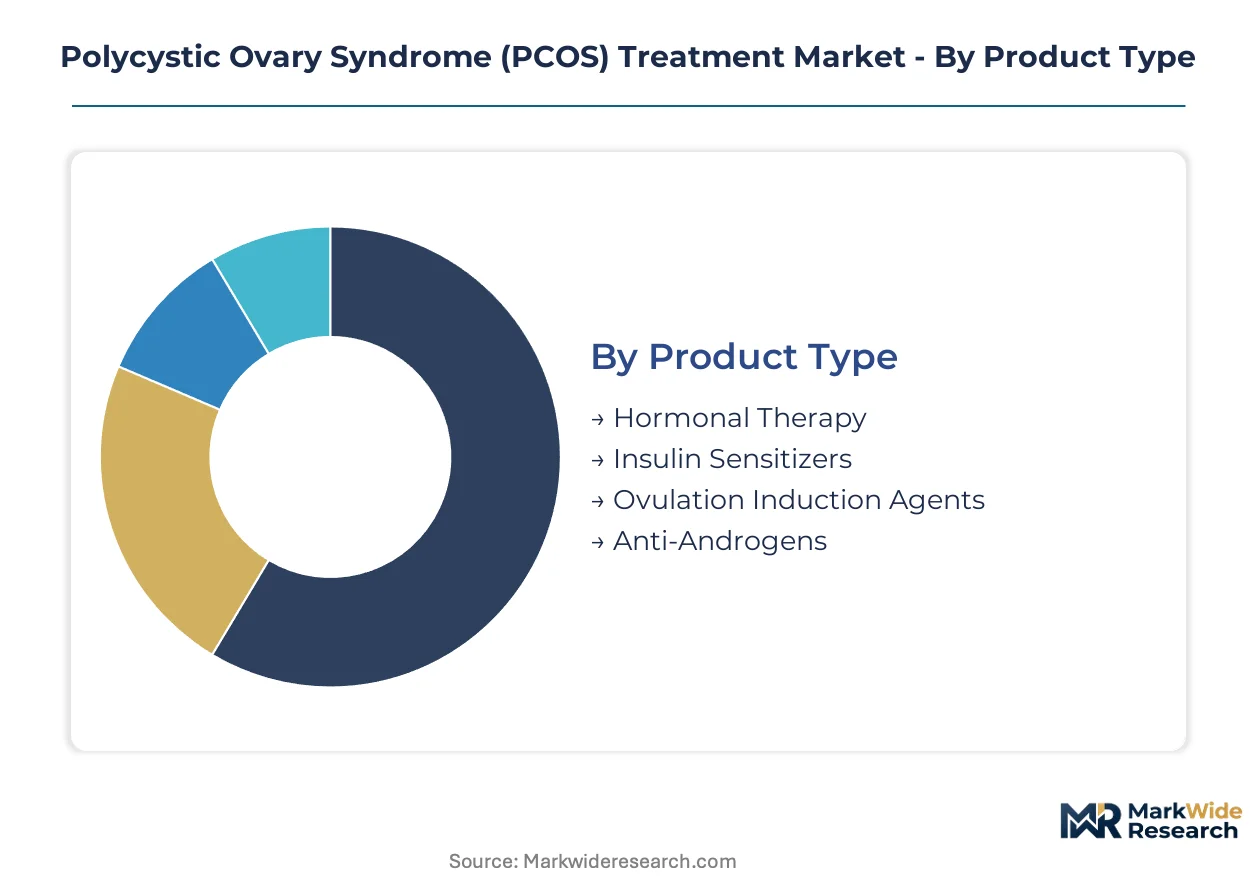
Treatment modality selection in PCOS management hinges on phenotype stratification, with channel economics determining how each segment reaches reproductive-age patients. Channel fragmentation between traditional fertility networks and emerging direct-to-consumer platforms reshapes competitive dynamics across all four segmentation dimensions.
Product Type:
Hospital formularies and specialty pharmacy networks channel high-complexity therapies, while retail and telemedicine platforms capture chronic maintenance medications.
- Hormonal Therapy:Combination oral contraceptives containing drospirenone or cyproterone acetate suppress ovarian androgen production through hypothalamic-pituitary feedback inhibition. Demand concentrates in United States suburban corridors where telemedicine platforms now capture 30-40% of chronic refill volume, compressing traditional clinic gatekeeper economics.
- Insulin Sensitizers:Biguanide and thiazolidinedione compounds improve peripheral glucose uptake and reduce hyperinsulinemia driving ovarian androgen excess. Metabolic syndrome-enriched cohorts in Southern United States metropolitan areas are where expansion concentrates, as GLP-1 receptor agonists displace metformin monotherapy in academic medical centers.
- Ovulation Induction Agents:Selective estrogen receptor modulators and gonadotropin protocols restore follicular development in infertility-dominant phenotypes.
- Anti-Androgens:Androgen receptor antagonists and 5-alpha reductase inhibitors target hirsutism and alopecia in cosmetic-motivated patient segments.
Hormonal Therapy dominates installed base. Insulin Sensitizers is where expansion concentrates.
Administration Route:
Patient adherence economics and reimbursement tiering stratify route selection, with cost-sensitive markets favoring established modalities over premium delivery innovations.
- Oral:Tablet and capsule formulations of hormonal and metabolic agents maintain volume leadership through decades of safety data and generic substitution availability. Brazilian and Indian distribution networks prioritize oral metformin and combined contraceptives for cost-structured procurement programs.
- Injectable:Subcutaneous GLP-1 receptor agonists and gonadotropin preparations serve metabolic and fertility-intensive phenotypes. United States endocrinology practices in Texas and Florida metropolitan corridors are where demand is climbing fastest for once-weekly semaglutide protocols.
- Transdermal:Patch and gel delivery systems bypass hepatic first-pass metabolism for estrogen-sensitive patients.
- Intrauterine:Levonorgestrel-releasing devices provide localized progestin delivery for endometrial protection.
Oral dominates installed base. Injectable is gaining share fastest.
End User:
Care setting selection reflects diagnostic complexity, with metabolic phenotyping and fertility preservation counseling driving site-of-service decisions.
- Hospital:Academic medical centers manage surgical ovarian drilling and complex fertility preservation cases requiring multidisciplinary coordination. German university hospitals and United States academic medical centers anchor demand for metabolic syndrome-enriched protocol development.
- Clinics:Reproductive endocrinology and general endocrinology practices deliver phenotype-specific protocols and chronic medication management. Sun Belt metropolitan corridors in the United States face access bottlenecks where fellowship-trained specialist supply fails to match patient volume growth.
- Homecare:Self-administered injection training and remote monitoring support chronic metabolic therapy.
- Specialty Pharmacies:Limited distribution networks handle high-cost fertility medications and GLP-1 agonists requiring cold chain integrity.
Clinics dominate installed base. Hospital is where expansion concentrates.
Therapeutic Area:
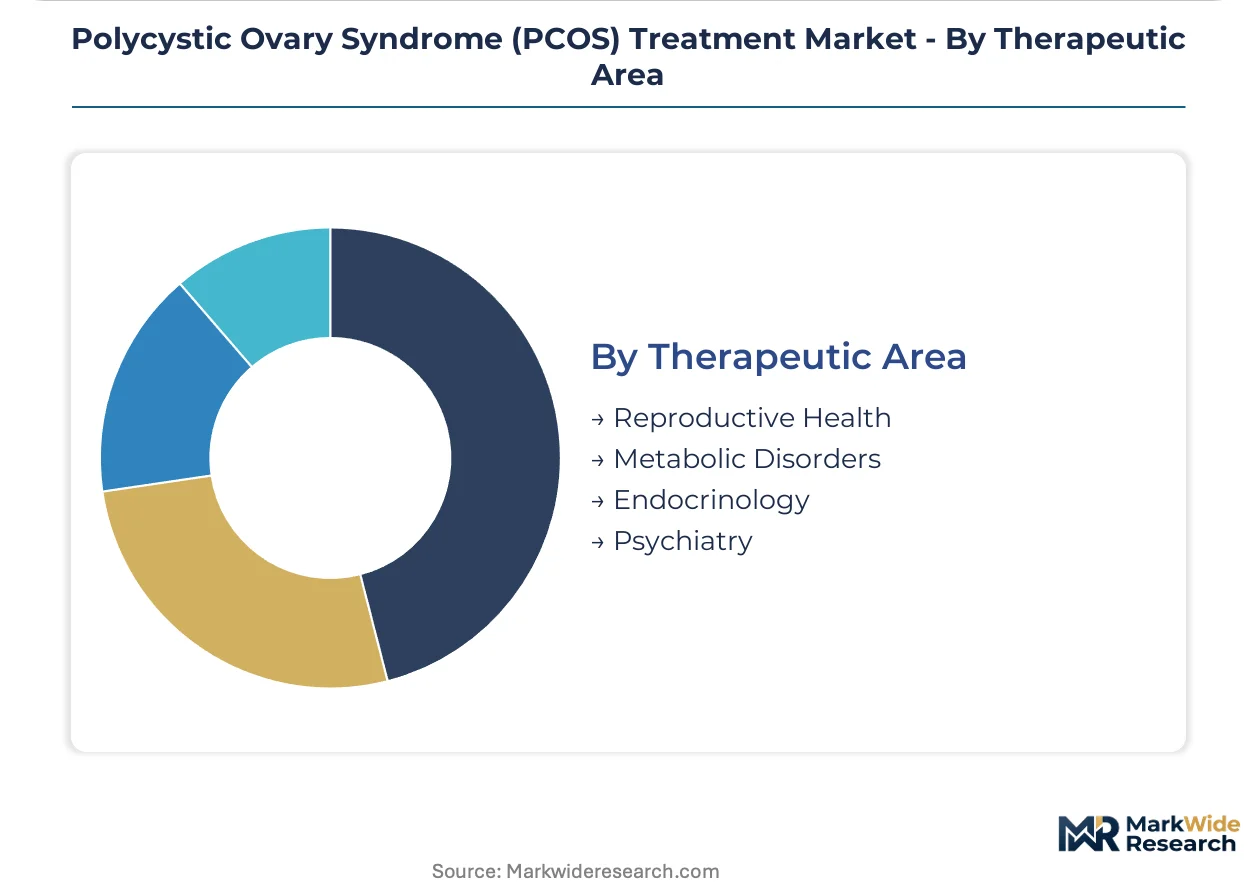
Cross-specialty referral patterns determine patient flow, with metabolic comorbidity management increasingly displacing pure reproductive endpoints.
- Reproductive Health:Fertility restoration and menstrual cycle regulation through ovulation induction and hormonal suppression. European academic medical centers and United States integrated reproductive networks anchor demand for phenotype-stratified protocols.
- Metabolic Disorders:Glycemic control, weight management, and cardiovascular risk reduction in insulin-resistant phenotypes. United States diabetes management programs embedding reproductive endocrinologists are where cross-referral volume is expanding most quickly.
- Endocrinology:Androgen excess management and adrenal-pituitary axis evaluation.
- Psychiatry:Mood disorder comorbidities and body image-related distress intervention.
Reproductive Health dominates installed base. Metabolic Disorders is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns for PCOS treatments diverge sharply by geography. United States patients gravitate toward metabolic comorbidity management with GLP-1 receptor agonists, while emerging markets prioritize cost-structured hormonal therapy for menstrual regulation.
United States
Integrated reproductive endocrinology networks in Texas and Florida metropolitan corridors drive demand for phenotype-specific protocols combining continuous glucose monitoring with pharmacologic intervention. FDA's evolving guidance on metabolic disorder drug labeling now requires cardiovascular outcome data for insulin sensitizer approvals. Sun Belt cities face acute specialist access bottlenecks where fellowship-trained endocrinologist supply trails patient volume growth.
Germany
Academic medical centers in Bavaria and North Rhine-Westphalia anchor European demand for surgical ovarian drilling and fertility preservation protocols. EMA's MDR framework streamlines conformity assessment for minimally invasive device-based interventions. University hospitals in Munich and Cologne concentrate metabolic syndrome-enriched cohort research for combination therapy development.
India
Cost-structured manufacturing for oral metformin and combined contraceptives concentrates in Maharashtra and Gujarat pharmaceutical clusters. CDSCO's accelerated approval pathway for chronic endocrine disorders reduces regulatory timelines for generic hormonal formulations. Mumbai and Ahmedabad distribution networks prioritize high-volume procurement programs for tier-2 and tier-3 city penetration.
Brazil
Hirsutism-dominant phenotypes in São Paulo and Rio de Janeiro drive demand for novel androgen receptor antagonists. ANVISA's priority review pathway for rare endocrine disorders expedites market entry for cosmetic-motivated therapeutic segments. Southeast regional fertility clinics are expanding PCOS-specific treatment protocols beyond traditional reproductive endpoints.
United Kingdom
Cross-referral pathways between diabetes management programs and reproductive endocrinology practices concentrate in London and Greater Manchester integrated care systems. MHRA's post-Brexit regulatory autonomy enables faster label expansion for metabolic indication claims. NHS England's tightening prior authorization standards for chronic hormonal therapy are shifting volume toward lifestyle-intervention combinations.
Polycystic Ovary Syndrome (PCOS) Treatment Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in PCOS therapeutics. Large pharmaceutical conglomerates with metabolic disorder portfolios control insulin sensitizer categories, while regional manufacturers compete on cost-structured oral hormonal formulations. Two strategic archetypes dominate: diversified conglomerates leveraging cross-therapeutic R&D infrastructure, and emerging market specialists optimizing manufacturing scale for generic substitution. Competitive moves center on portfolio diversification into GLP-1 receptor agonist co-development and backward integration into active pharmaceutical ingredient supply.
Within the diversified pharmaceutical tier, Novartis AG and Bayer AG exemplify contrasting geographic anchoring strategies. Novartis leverages its Swiss-based metabolic disorder portfolio across insulin sensitizer categories, while Bayer AG draws on German academic medical center relationships for ovulation induction expertise. Cipla Limited represents the emerging market specialist archetype, with its Indian manufacturing base supplying cost-structured oral hormonal formulations through distribution channels in Brazil, South Africa, and Southeast Asia. These three companies collectively illustrate how competitive positioning in PCOS therapeutics depends on regulatory navigation capability, manufacturing cost structure, and clinical trial endpoint design expertise.
| Leading Market Players |
|---|
| Novartis AG |
| Cipla Limited |
| Pfizer Inc. |
| Dr. Reddy's Laboratories Ltd. |
| Sun Pharmaceutical Industries Ltd. |
| Bayer AG |
| Sanofi S.A. |
| May Health |
| Teva Pharmaceutical Industries Ltd. |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake contracts for metformin hydrochloride lock in both supply access and price visibility for formulation sponsors, insulating them from spot market volatility in Indian and Chinese supplier bases while exposing them to geopolitical trade friction.
Pricing Analysis
Long-term offtake agreements dominate insulin sensitizer procurement, with pricing stratifying across premium, standard, and economy tiers based on FDA certification status and volume scale. Price differentiation stems from brand premium for GLP-1 receptor agonists versus generic substitution pressure on oral contraceptives. Cost compression in hormonal therapy is intensifying because telemedicine platforms commoditize chronic refill volume. Retail pharmacy chains exhibit highest price sensitivity, while academic medical centers prioritize clinical outcome data over unit cost.
Supply Chain Analysis
Strait of Malacca transit underwrites active pharmaceutical ingredient flows from Indian pharmaceutical clusters to European formulation sites, creating logistical vulnerability for metformin and combined contraceptive production. Manufacturing concentrates in Maharashtra and Gujarat for cost-structured oral formulations, with thiazolidinedione precursors sourcing from Zhejiang province chemical plants. Supply chain risk centers on single-source vulnerability for GLP-1 receptor agonist peptide synthesis. Distribution runs through specialty pharmacy networks for high-cost fertility medications and cold-chain GLP-1 products, while retail channels handle chronic oral maintenance therapies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
PCOS therapeutics fragmentation creates opportunity as phenotype-specific protocols splinter demand across metabolic, reproductive, and cosmetic endpoints, enabling niche positioning beyond incumbent hormonal therapy dominance.
For Market Incumbents: Shield portfolio margins by accelerating GLP-1 receptor agonist co-development partnerships before metabolic indication claims fully commoditize. Deepen backward integration into peptide synthesis capacity to reduce single-source dependency for incretin-based therapies. Capture reproductive endocrinology fellowship-trained specialists through exclusive academic medical center affiliations in Sun Belt metropolitan corridors where access bottlenecks concentrate patient flow. For New Entrants and Emerging Players: Anchor in hirsutism-dominant phenotype management where ANVISA's priority review pathway expedites novel androgen receptor antagonist entry against underserved cosmetic-motivated segments. Target direct-to-consumer telemedicine prescription channels for chronic metformin and oral contraceptive refills, bypassing traditional clinic gatekeeper economics. Deploy smartphone-based ovulation tracking co-development as combination product differentiation. For Investors and Strategic Acquirers: Capital is best deployed toward emerging market manufacturing specialists with captive metformin API supply and Brazilian distribution reach, as cost-structured procurement programs expand in Southeast Asia and Latin America. Long-term viability hinges on regulatory navigation capability across FDA, EMA, and ANVISA frameworks. Watch GLP-1 receptor agonist teratogenicity study readouts as inflection indicator for preconception population label expansion.| Strategic Initiative | Industry Significance |
|---|---|
| GLP-1 Receptor Agonist Co-Development | Metabolic indication claims reshape competitive hierarchy beyond traditional insulin sensitizers. |
| Backward Integration into Peptide Synthesis | Captive supply of incretin precursors reduces single-source vulnerability for subcutaneous formulations. |
| Telemedicine Platform Partnership | Direct-to-patient channels capture chronic refill volume outside traditional reproductive endocrinology networks. |
| Phenotype-Specific Protocol Development | Continuous glucose monitoring integration enables real-time dose optimization for metabolic phenotypes. |
| Emerging Market Regulatory Fast-Track | ANVISA and CDSCO priority pathways accelerate entry for hirsutism-dominant and cost-structured segments. |
Study Parameters
Operator-level perspectives from reproductive endocrinologists, formulary directors at integrated hospital systems, specialty pharmacy procurement managers, and CDSCO regulatory affairs leads anchored the qualitative base. Primary interview findings triangulated against FDA filings, EMA MDR conformity assessments, ClinicalTrials.gov protocol registries, and Brazilian ANVISA approval databases. Bottom-up patient volume modeling by metropolitan corridor converged with top-down pharmaceutical revenue segmentation across hormonal therapy, insulin sensitizers, and ovulation induction categories.
Sensitivity analysis tested forecast robustness across alternative GLP-1 adoption curves and generic oral contraceptive substitution rates over the projection horizon. The analytical framework modeled treatment modality, administration route, end-user setting, and therapeutic area dimensions alongside patient phenotype stratification by androgen excess severity and insulin resistance markers. CAGRs derived from log-linear trend fitting to historical volume data, adjusted for regulatory approval timeline scenarios and reimbursement policy shifts.
Decision-makers should treat outputs as directional under stable FDA metabolic disorder guidance and continued GLP-1 cardiovascular outcome trial investment; material deviation in teratogenicity findings or prior authorization tightening would warrant model refresh. Practitioners should keep alternative scenarios live as EMA MDR enforcement intensity and Indian API export inspection protocols evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Rotator Cuff Injury Treatment Market
Medical Treatment
Global Radiodermatitis Treatment Market
Medical Treatment
Hypercoagulability Treatment Market
Medical Treatment
Histoplasmosis Treatment Market
Medical Treatment
Refsum Disease Treatment Market
Medical Treatment
Transarterial Chemoembolization (TACE) Market
Medical Treatment
Europe Nerve Repair and Regeneration Market
Medical Treatment
Middle Ear Infection Treatment Market
Medical Treatment
Meningococcal Meningitis Treatment Market
Medical Treatment
Hypogonadism Treatment Market
Medical Treatment
Systemic Inflammatory Response Syndrome Treatment Market
Medical Treatment
Gunshot Injuries Treatment Market
Medical Treatment
Anorectal Malformation Treatment Market
Medical Treatment
Global Plasma Therapy Market
Medical Treatment
Post-Operative Nausea and Vomiting (PONV) Market
Medical Treatment
Inguinal Hernia Market