
 Cytokine Release Syndrome Management Market | 2026-2036
Cytokine Release Syndrome Management Market Size, Share, and Industry Trends Forecast 2026-2036
Cytokine Release Syndrome Management Market Outlook
ISO 14155 clinical investigation standards for biologics is collapsing the barrier between established pharmaceutical developers and emerging immuno-oncology entrants. Eli Lilly and Company leverages its end-to-end manufacturing infrastructure to control supply of CRS-targeted therapeutics. Novartis AG anchors its position through deep integration with CAR-T therapy platforms where CRS represents a critical adverse event. F. Hoffmann-La Roche AG differentiates via biomarker-guided patient stratification tools that precede intervention.
Cytokine release syndrome management encompasses the clinical and pharmacological protocols used to prevent, monitor, and treat systemic inflammatory cascades triggered by immunotherapies, characterized by elevated ferritin, hypotension, and multi-organ dysfunction requiring IL-6 pathway blockade or corticosteroid suppression. The primary purpose is preserving patient viability during CAR-T, bispecific antibody, and other T-cell engaging therapies where uncontrolled cytokine elevation drives mortality. Monoclonal antibodies and IL-6 inhibitors command the deepest margin pools due to patent-protected mechanisms and hospital formulary anchoring, while intravenous administration dominates treatment settings owing to the acute, monitored nature of CRS events. Outpatient clinic and home care channels remain structurally underdeveloped, constrained by the narrow therapeutic window and need for rapid intervention.
FDA biologics guidance, EMA's pharmacovigilance frameworks for advanced therapy medicinal products, and WHO prequalification pathways for cytokine storm diagnostics collectively elevate the compliance burden for market participants seeking multi-jurisdictional access. These regulators mandate real-world evidence collection and risk evaluation mitigation strategies that directly shape product development priorities and commercial launch sequencing. Stakeholders must monitor evolving FDA guidance on CAR-T long-term follow-up requirements to anticipate shifts in prophylactic versus reactive CRS treatment protocols.
Market Dynamics
The FDA's evolving guidance on biologics safety monitoring is compressing the timeline between CAR-T therapy administration and mandatory cytokine surveillance, forcing tertiary oncology centers to restructure their intensive care protocols and staffing models around real-time inflammatory biomarker tracking.
Growth Catalysts
- CAR-T therapy platform expansion:Academic medical centers in the United States are scaling T-cell engaging therapy programs, generating captive demand for IL-6 pathway blockade protocols and dedicated CRS response infrastructure.
- EMA pharmacovigilance frameworks:The European Medicines Agency's advanced therapy medicinal product surveillance mandates are standardizing post-market cytokine monitoring requirements across EU member states, harmonizing clinical trial endpoints for CRS therapeutics.
- Biomarker-guided stratification:Ferritin and IL-6 level thresholds are displacing symptom-based intervention triggers, enabling preemptive tocilizumab administration before hemodynamic collapse.
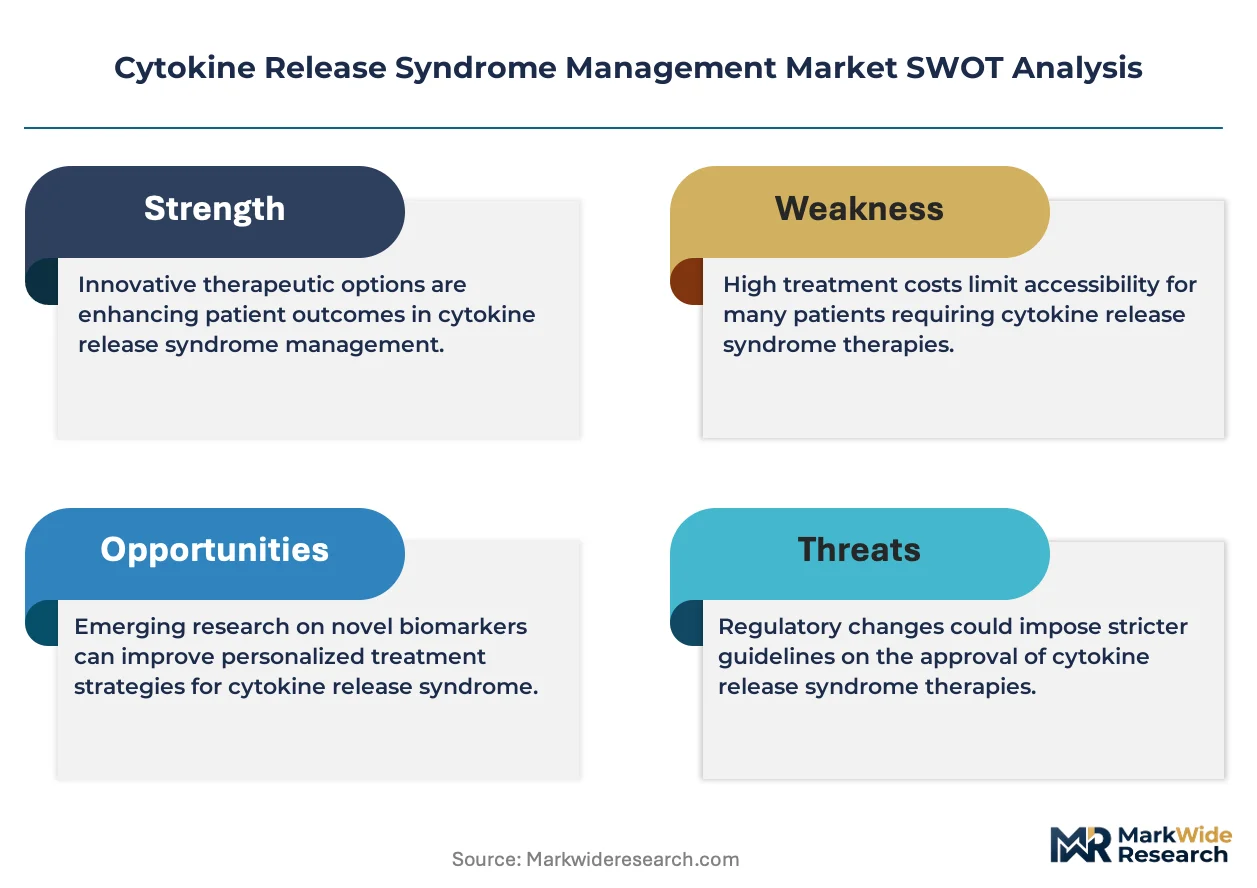
Market Restraints
- Plasma-derived protein supply volatility:Monoclonal antibody production depends on fractionation facility capacity concentrated in the United States and Germany, exposing formularies to batch release delays.
- ISO 14155 compliance burden:Clinical investigation standards for biologics impose documentation requirements that extend trial timelines for emerging immuno-oncology entrants lacking established quality management systems.
- Corticosteroid substitution threat:Generic methylprednisolone protocols retain formulary preference in cost-constrained hospital systems despite inferior cytokine specificity.
Strategic Opportunities
- Outpatient clinic channel development:Subcutaneous IL-6 inhibitor formulations could unlock home-based CRS prophylaxis for low-risk CAR-T patients, bypassing ICU bed constraints.
- WHO prequalification pathways:Cytokine storm diagnostic eligibility for WHO procurement lists would open institutional access across Southeast Asian and African tertiary referral networks.
- AI-integrated early warning systems:Machine learning algorithms processing continuous vital sign streams are converging with electronic health record architectures to flag CRS onset hours before clinical deterioration.
Industry Challenges
- Critical care nursing specialization gaps:Tertiary oncology centers face recruitment bottlenecks for nurses trained simultaneously in CAR-T cell therapy protocols and hemodynamic resuscitation.
- Multi-jurisdictional trial design complexity:Reconciling FDA risk evaluation mitigation strategies with EMA pharmacovigilance frameworks and WHO prequalification requirements fragments clinical development programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cytokine Release Syndrome Management Market |
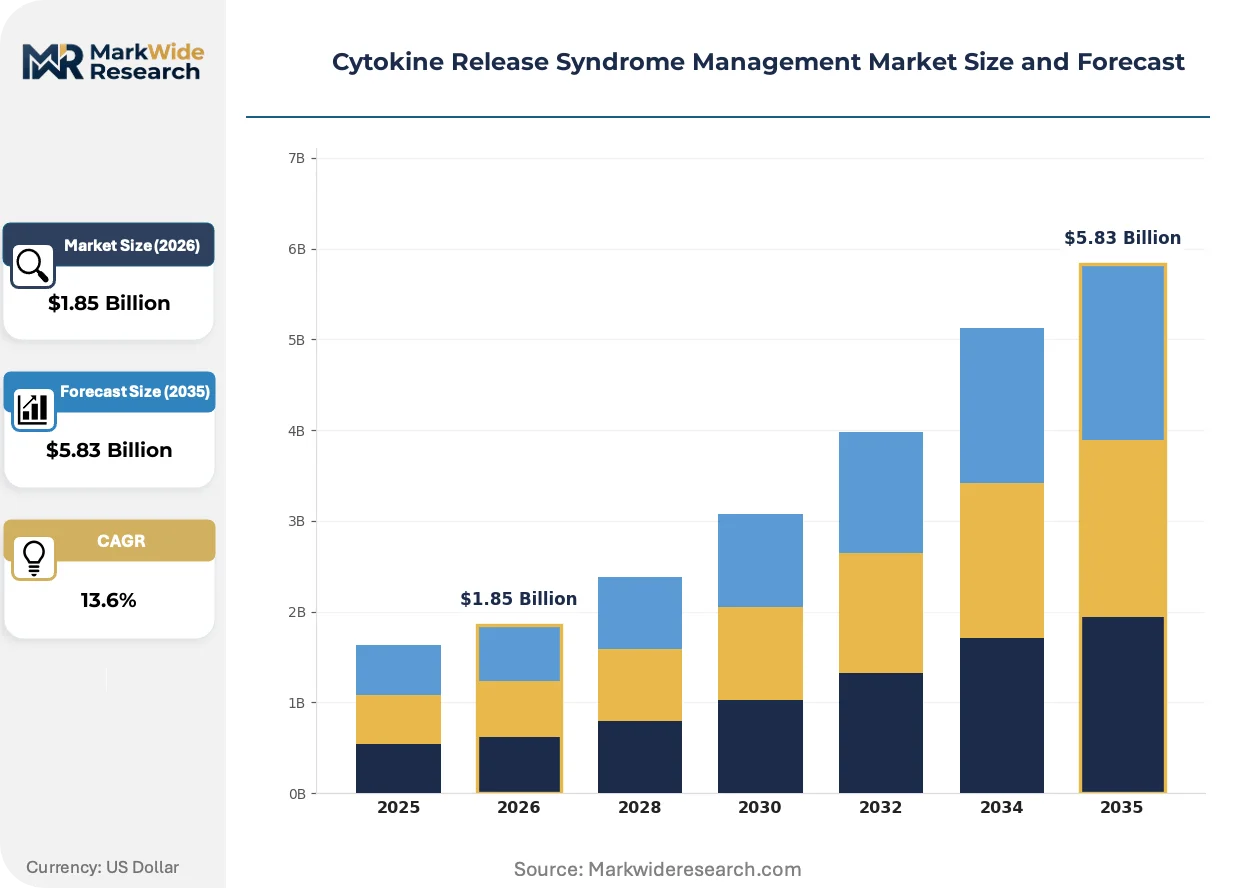
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $5.83 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoclonal Antibodies, Corticosteroids, IL-6 Inhibitors, Immunomodulators Treatment Setting: Hospital, Outpatient Clinic, Home Care, Research Facility Patient Type: Pediatric, Adult, Geriatric, Immunocompromised Administration Route: Intravenous, Subcutaneous, Oral, Intramuscular |
| Companies Covered | Eli Lilly and Company, Johnson & Johnson, Novartis AG, GlaxoSmithKline plc, AbbVie Inc., Genentech, Sanofi S.A., F. Hoffmann-La Roche AG, Pfizer Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cytokine Release Syndrome Management Market Strategic Shifts
Real-world evidence collection infrastructure is reshaping how CRS therapeutics demonstrate value, with regulators and hospital pharmacy committees demanding longitudinal outcome data that extends far beyond traditional randomized controlled trial endpoints.
Next-generation IL-1 receptor antagonists are displacing tocilizumab as the first-line intervention in steroid-refractory CRS cases. Pediatric oncology units at centers like Memorial Sloan Kettering and Texas Children's Hospital are piloting these agents in neuroblastoma CAR-T protocols. The shift is compressing market share for legacy IL-6 inhibitors while expanding the addressable patient population to those with concurrent macrophage activation syndrome.
EMA's advanced therapy medicinal product framework is mandating 15-year follow-up registries for all commercial CAR-T therapies, forcing manufacturers to underwrite post-authorization safety studies that capture late-onset CRS and neurotoxicity events. German and French national health technology assessment bodies are incorporating these longitudinal datasets into reimbursement decisions. Hospital pharmacists across Northern Europe are now prioritizing therapies with established real-world safety archives over newer entrants lacking extended track records.
Consolidated purchasing coalitions among US academic medical centers are unbundling CRS management protocols from CAR-T therapy list prices. The National Comprehensive Cancer Network's group purchasing organization is negotiating standalone tocilizumab and corticosteroid formularies separate from cellular therapy acquisition costs. This procurement restructuring is most visible in the Midwest, where Ohio State University and University of Michigan anchor multi-hospital buying consortia that extract volume-based discounts from cytokine inhibitor suppliers.
Cytokine Release Syndrome Management Market Segmentation
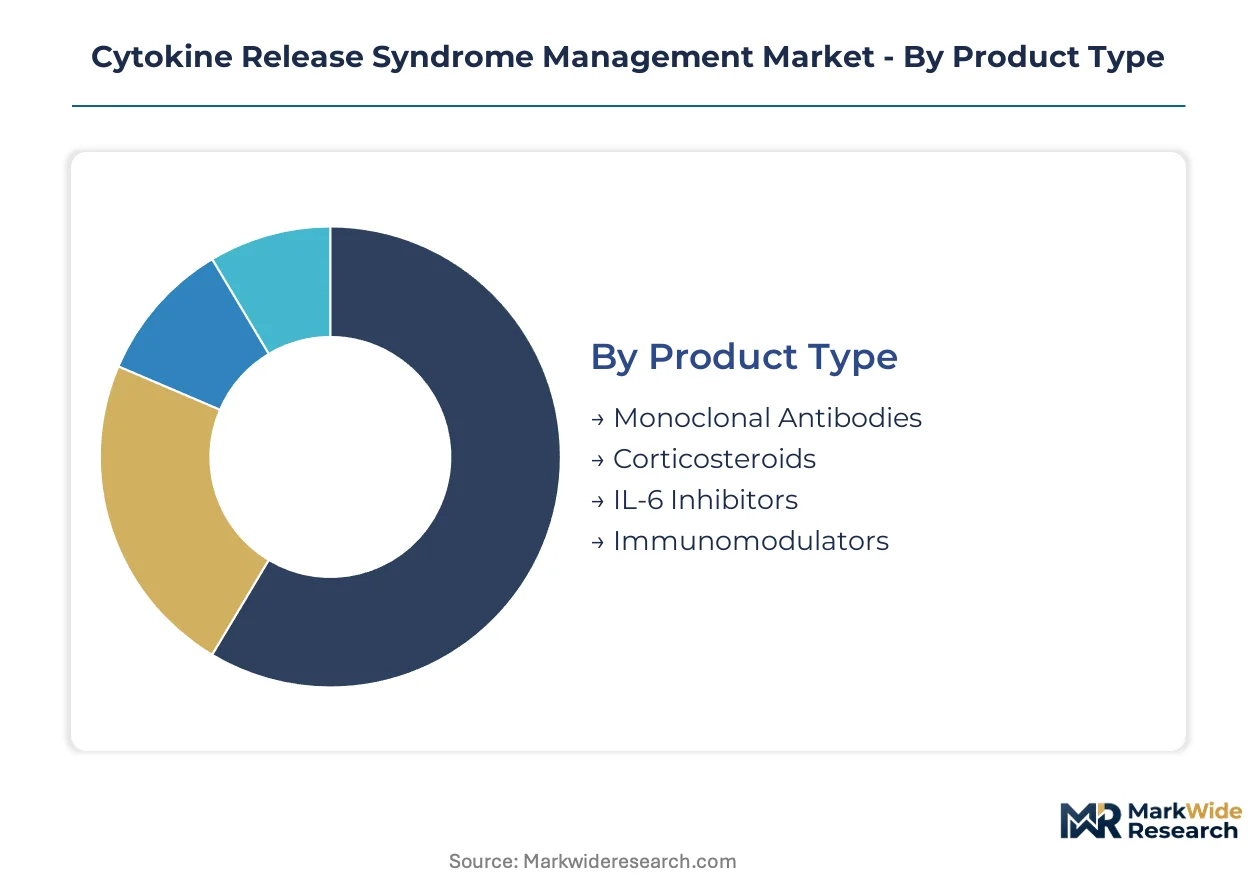
CRS therapeutics fragment across four distinct axes: mechanism of action, care setting acuity, patient vulnerability profile, and delivery modality. Each axis carries divergent regulatory pathways, reimbursement codes, and supply chain requirements that reshape commercial strategy.
Product Type:
FDA biologics licensing pathways create tiered approval timelines that stratify competitive entry: monoclonal antibodies and IL-6 inhibitors navigate accelerated oncology designations while corticosteroids remain grandfathered under generic frameworks.
- Monoclonal Antibodies:Engineered immunoglobulins targeting specific cytokine receptors or inflammatory mediators. Demand concentrates in tertiary oncology centers administering CAR-T therapies, constrained by cold-chain distribution requirements and batch release testing protocols.
- IL-6 Inhibitors:Recombinant proteins blocking interleukin-6 signaling, the primary pathway in CRS pathophysiology. Memorial Sloan Kettering and MD Anderson anchor volume for tocilizumab and siltuximab protocols, driven by EMA pharmacovigilance mandates for advanced therapy medicinal products.
- Corticosteroids:Synthetic glucocorticoids suppressing broad inflammatory cascades. Methylprednisolone retains formulary preference in cost-constrained hospital systems despite inferior cytokine specificity.
- Immunomodulators:Small molecules and biologics modulating T-cell activation thresholds. Emerging entrants target steroid-refractory cases with novel mechanisms.
IL-6 inhibitors handle the majority of throughput; immunomodulators are expanding most quickly on share.
Treatment Setting:
Reimbursement codes and ICU bed economics determine where CRS protocols deploy, with Medicare severity-adjusted diagnosis-related groups favoring inpatient administration for high-acuity events.
- Hospital:Inpatient intensive care units with continuous hemodynamic monitoring and rapid tocilizumab access. University of Pennsylvania and Stanford Health anchor captive demand through integrated CAR-T programs.
- Outpatient Clinic:Ambulatory infusion centers managing low-risk prophylaxis. Subcutaneous formulation development is unlocking this channel for select patient cohorts.
- Home Care:Residential administration remains structurally underdeveloped due to narrow therapeutic windows and rapid intervention requirements.
- Research Facility:Clinical trial sites conducting investigator-initiated studies under FDA risk evaluation mitigation strategies.
Hospital settings capture the dominant share of administered volume; outpatient clinics are climbing the fastest as prophylactic protocols expand.
Patient Type:
FDA pediatric investigational plans and geriatric exclusion criteria from pivotal trials create labeled indication gaps that off-label prescribing fills.
- Pediatric:Patients under 18 with distinct weight-based dosing requirements and higher macrophage activation syndrome comorbidity. Texas Children's Hospital and Boston Children's pilot next-generation IL-1 antagonists in neuroblastoma protocols.
- Adult:The core demographic for commercial CAR-T therapies, with established ferritin and IL-6 threshold protocols.
- Geriatric:Patients over 65 with elevated baseline inflammatory markers and competing mortality risks. Formularies favor corticosteroid-sparing approaches to preserve immune recovery.
- Immunocompromised:Recipients with prior autologous stem cell transplants or chronic immunosuppression requiring modified prophylaxis regimens.
Adult patients handle the majority of throughput; pediatric applications are gaining share fastest as childhood leukemia CAR-T approvals expand.
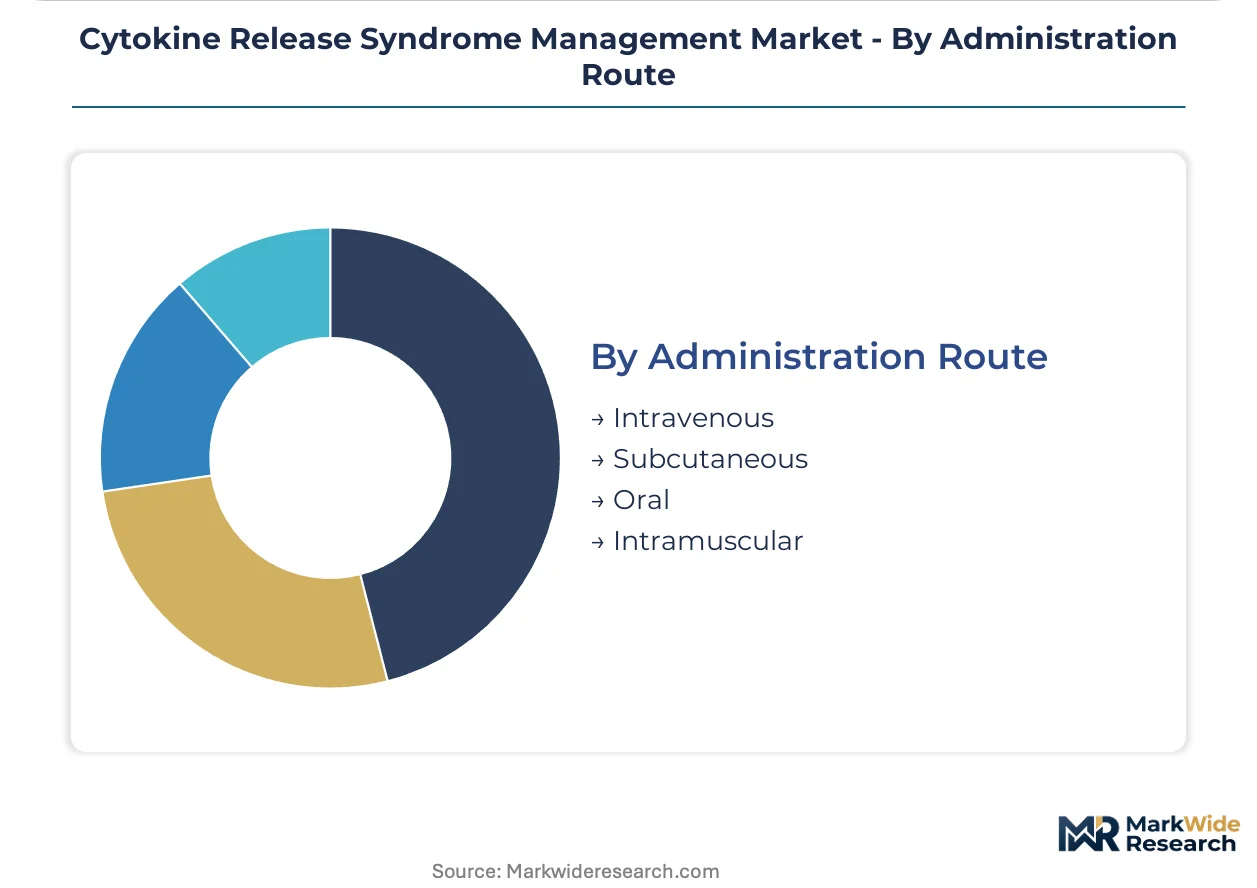
Administration Route:
Pharmacokinetic profiles and emergency intervention timelines dictate route selection, with intravenous formulations commanding premium positioning due to immediate bioavailability.
- Intravenous:Direct vascular delivery enabling rapid peak serum concentrations. Hospital formularies anchor procurement around IV tocilizumab and corticosteroid protocols.
- Subcutaneous:Depot absorption suitable for prophylactic administration in low-risk patients. Development pipelines target outpatient clinic channel expansion.
- Oral:Enteric corticosteroid formulations for maintenance or step-down therapy after acute CRS resolution.
- Intramuscular:Limited application for emergency corticosteroid rescue when vascular access is compromised.
Intravenous administration handles the majority of throughput; subcutaneous delivery is expanding most quickly as prophylactic use cases develop.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA biologics licensing pathways and EMA advanced therapy medicinal product frameworks are accelerating infrastructure buildout for cytokine release syndrome management across major oncology clusters. Reimbursement codes for IL-6 pathway blockade are concentrating demand in jurisdictions with integrated CAR-T therapy programs.
United States
Memorial Sloan Kettering and MD Anderson anchor tocilizumab procurement volume through dedicated CRS response infrastructure. FDA risk evaluation mitigation strategies mandate 15-year follow-up registries that reshape prophylactic prescribing patterns. The National Comprehensive Cancer Network's group purchasing organization extracts volume-based discounts across Midwest academic medical centers.
Germany
EMA pharmacovigilance frameworks standardize post-market cytokine monitoring requirements across EU member states. German national health technology assessment bodies incorporate longitudinal safety datasets into reimbursement decisions for CAR-T therapies. Heidelberg and Munich university hospitals pilot next-generation IL-1 receptor antagonists in steroid-refractory protocols.
United Kingdom
NHS England's specialized commissioning framework concentrates CRS management capacity in designated tertiary oncology centers. The Medicines and Healthcare products Regulatory Agency aligns with EMA advanced therapy medicinal product surveillance mandates. London's Royal Marsden and University College Hospital anchor integrated CAR-T and cytokine monitoring programs.
Japan
PMDA accelerated approval pathways for oncology biologics compress timelines between therapy authorization and CRS protocol establishment. Japanese academic medical centers in Tokyo and Osaka deploy ferritin-guided intervention thresholds ahead of hemodynamic collapse. METI funding for cellular therapy manufacturing infrastructure expands captive demand for cytokine surveillance systems.
China
NMPA biologics licensing reforms prioritize domestic CAR-T developers requiring CRS management protocol integration. Shanghai and Beijing tertiary oncology centers scale IL-6 inhibitor formularies alongside T-cell engaging therapy programs. The country's national pharmaceutical regulator mandates real-world evidence collection infrastructure that mirrors FDA frameworks.
Cytokine Release Syndrome Management Market Competitive Environment
Player mix skews toward integrated pharmaceutical conglomerates with end-to-end biologics manufacturing infrastructure. Market structure concentrates around entities controlling both CAR-T therapy platforms and cytokine inhibitor supply chains. Three archetypes dominate: legacy oncology biologics manufacturers with IL-6 pathway expertise, diversified pharmaceutical conglomerates leveraging hospital formulary relationships, and emerging immuno-oncology specialists targeting steroid-refractory segments. Competitive moves center on manufacturing capacity expansion for monoclonal antibody production and strategic partnerships with academic medical centers for real-world evidence generation.
Within the integrated pharmaceutical tier, Eli Lilly and Company and Novartis AG exemplify archetypes built on manufacturing control and therapy platform integration respectively. F. Hoffmann-La Roche AG occupies a position emphasizing biomarker-guided patient stratification tools. Johnson & Johnson represents the diversified conglomerate archetype leveraging hospital system relationships across multiple therapeutic areas. These entities anchor competitive dynamics through formulary positioning rather than direct product rivalry, with each representing distinct strategic pathways to CRS management market participation.
| Leading Market Players |
|---|
| Eli Lilly and Company |
| Johnson & Johnson |
| Novartis AG |
| GlaxoSmithKline plc |
| AbbVie Inc. |
| Genentech |
| Sanofi S.A. |
| F. Hoffmann-La Roche AG |
| Pfizer Inc. |
| Others |
Value Chain & Pricing Dynamics
Generic methylprednisolone substitution for tocilizumab in cost-constrained hospital systems is simultaneously redrawing manufacturing geography toward Indian and Chinese corticosteroid API producers while compressing margin pools for patent-protected IL-6 inhibitors in United States academic medical centers.
Pricing Analysis
Cost-plus contracts with plasma protein indexation anchor monoclonal antibody procurement between United States tertiary oncology centers and fractionation facilities in Germany. Three-tier pricing structure across premium tocilizumab, standard siltuximab, and economy corticosteroid levels reflects brand premium and FDA biologics licensing tier differentiation. Pricing pressure stems from consolidated purchasing coalitions extracting volume-based discounts across Midwest academic medical centers. Community hospital systems exhibit highest price sensitivity, while integrated cancer centers anchor premium positioning through captive CAR-T therapy demand.
Supply Chain Analysis
Cold-chain distribution chokepoints at United States and German fractionation facilities tether monoclonal antibody availability to batch release testing protocols and plasma collection center capacity. Manufacturing concentrates in United States, Germany, and Switzerland for IL-6 pathway inhibitors, with recombinant protein production drawing from Chinese hamster ovary cell line feedstocks and single-use bioreactor components. Single-source vulnerability at plasma-derived protein suppliers exposes formularies to supply interruption. Distribution runs through hospital specialty pharmacy channels and GPO-negotiated formularies with direct-to-site cold chain logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity is opening as outpatient clinic channels for subcutaneous prophylaxis outpace incumbent infrastructure, creating service-layer niches for agile entrants targeting low-risk CAR-T patient stratification.
For Market Incumbents: Consolidate manufacturing control through backward integration into plasma collection networks and captive recombinant protein capacity in Germany. Lock in formulary anchoring at Memorial Sloan Kettering and MD Anderson through 15-year follow-up registry commitments that satisfy FDA risk evaluation mitigation strategies. Vertical integration into diagnostic biomarker platforms defends against AI-integrated early warning system substitutes. For New Entrants and Emerging Players: Home-based CRS prophylaxis for low-risk pediatric neuroblastoma patients represents the most penetrable service-layer gap where incumbents under-serve. Target Texas Children's Hospital and Boston Children's pilot programs for next-generation IL-1 receptor antagonist positioning. Deploy subcutaneous formulation development partnerships as the primary go-to-market angle, bypassing ICU bed constraints that limit incumbent channel control. For Investors and Strategic Acquirers: The market sits at a platform-integration phase that favors biologics manufacturers with end-to-end cytokine inhibitor supply chains and CAR-T therapy co-development relationships. Long-term viability over the coming decade hinges on real-world evidence generation infrastructure and EMA pharmacovigilance framework compliance. Monitor FDA guidance evolution on CAR-T long-term follow-up requirements as the critical inflection signal for prophylactic versus reactive protocol shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Plasma fractionation capacity expansion in Germany secures tocilizumab supply for EMA-mandated post-market surveillance. |
| Regulatory Approval Pathway | WHO prequalification for cytokine storm diagnostics opens institutional access across Southeast Asian tertiary networks. |
| Strategic Partnership | AI-integrated early warning system alliances with Epic and Cerner embed CRS prediction into EHR architectures. |
| Pipeline Diversification | Next-generation IL-1 receptor antagonists target steroid-refractory cases with concurrent macrophage activation syndrome. |
| Reimbursement Strategy | Unbundled tocilizumab formularies separate from CAR-T list prices extract volume discounts through NCCN purchasing coalitions. |
Study Parameters
A spread of perspectives from CAR-T therapy program directors, hospital formulary pharmacists, cytokine inhibitor procurement managers, and regulatory affairs specialists converged on the working assumptions underlying this analysis. Primary interviews with these stakeholders combined with secondary validation against FDA biologics licensing filings, EMA advanced therapy medicinal product submissions, ClinicalTrials.gov investigator-initiated study records, and hospital GPO contract databases. Bottom-up patient volume modeling across United States, German, and Japanese academic medical centers triangulated with top-down cytokine inhibitor revenue estimates.
Segmentation dimensions modeled span mechanism of action, treatment setting acuity, patient vulnerability profile, and administration route across the analysis window. Product-type splits capture monoclonal antibody, IL-6 inhibitor, corticosteroid, and immunomodulator throughput shares. CAGRs derive from therapy adoption curves at named tertiary oncology centers and biomarker-guided intervention threshold penetration. Forecast inputs incorporate CAR-T therapy platform expansion rates and EMA pharmacovigilance framework compliance costs.
Underlying assumptions cover sustained FDA biologics safety monitoring evolution and plasma-derived protein supply stability, with deviation risk concentrated in corticosteroid substitution acceleration and subcutaneous formulation development timelines. Practitioners should keep alternative scenarios live as outpatient clinic channel economics and AI-integrated early warning system regulatory pathways evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
House Dust Mite Allergy Treatment Market
Medical Treatment
Mesotherapy Market
Medical Treatment
Radiation Therapy Market
Medical Treatment
Post-Operative Nausea and Vomiting (PONV) Market
Medical Treatment
Lysosomal Acid Lipase (LAL) Deficiency Treatment Market
Medical Treatment
Birch Allergy Treatment Market
Medical Treatment
Non-Infectious Diarrhea Treatment Market
Medical Treatment
China Nose Reconstruction Market
Medical Treatment
Peanut Allergy Treatment Market
Medical Treatment
Prion Disease Treatment Market
Medical Treatment
Hyperbaric Oxygen Therapy (HBOT) Market
Medical Treatment
Frozen Skin Graft Market
Medical Treatment
US and Japan Platelet Rich Plasma Market
Medical Treatment
Facial Spasm Treatment Market
Medical Treatment
Porphyria Treatment Market
Medical Treatment
Cysticercosis (Taeniasis) Treatment Market