
 Monkeypox Vaccine and Treatment Market | 2026-2036
Monkeypox Vaccine and Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Monkeypox Vaccine and Treatment Market Intelligence
Public health organizations is repositioning procurement priorities toward third-generation vaccines and novel antivirals after the 2022-2023 multi-country outbreak. Bavarian Nordic leverages its MVA-BN platform to dominate European and North American supply channels for replication-deficient vaccines. SIGA Technologies anchors the antiviral segment through TPOXX stockpiling contracts with national strategic reserves. Emergent BioSolutions sustains manufacturing scale across multiple biodefense product lines, while Chimerix competes in the antiviral niche with brincidofovir development.
Monkeypox vaccine and treatment encompasses prophylactic and therapeutic countermeasures targeting Orthopoxvirus infections, with third-generation vaccines employing modified vaccinia Ankara delivered via subcutaneous injection at dose volumes below 0.5 mL. The primary purpose centers on outbreak containment and strategic stockpile maintenance for both routine immunization and emergency response deployment. Live vaccines command the largest revenue share due to established regulatory pathways and proven efficacy profiles, while monoclonal antibodies represent the fastest-growing segment as developers pursue post-exposure prophylaxis indications. Antiviral drugs capture concentrated margin pools through government procurement contracts rather than commercial pharmacy channels.
FDA emergency use authorizations and EMA conditional marketing approvals shape product access timelines for novel vaccines and therapeutics, while WHO prequalification status determines procurement eligibility for low-income country buyers. The EU Green Deal and CSRD reporting requirements are forcing manufacturers to document supply chain emissions and cold-chain logistics footprints. Stakeholders must monitor regulatory divergence between FDA animal efficacy rule pathways and EMA human challenge trial demands for next-generation orthopoxvirus candidates.
Market Dynamics
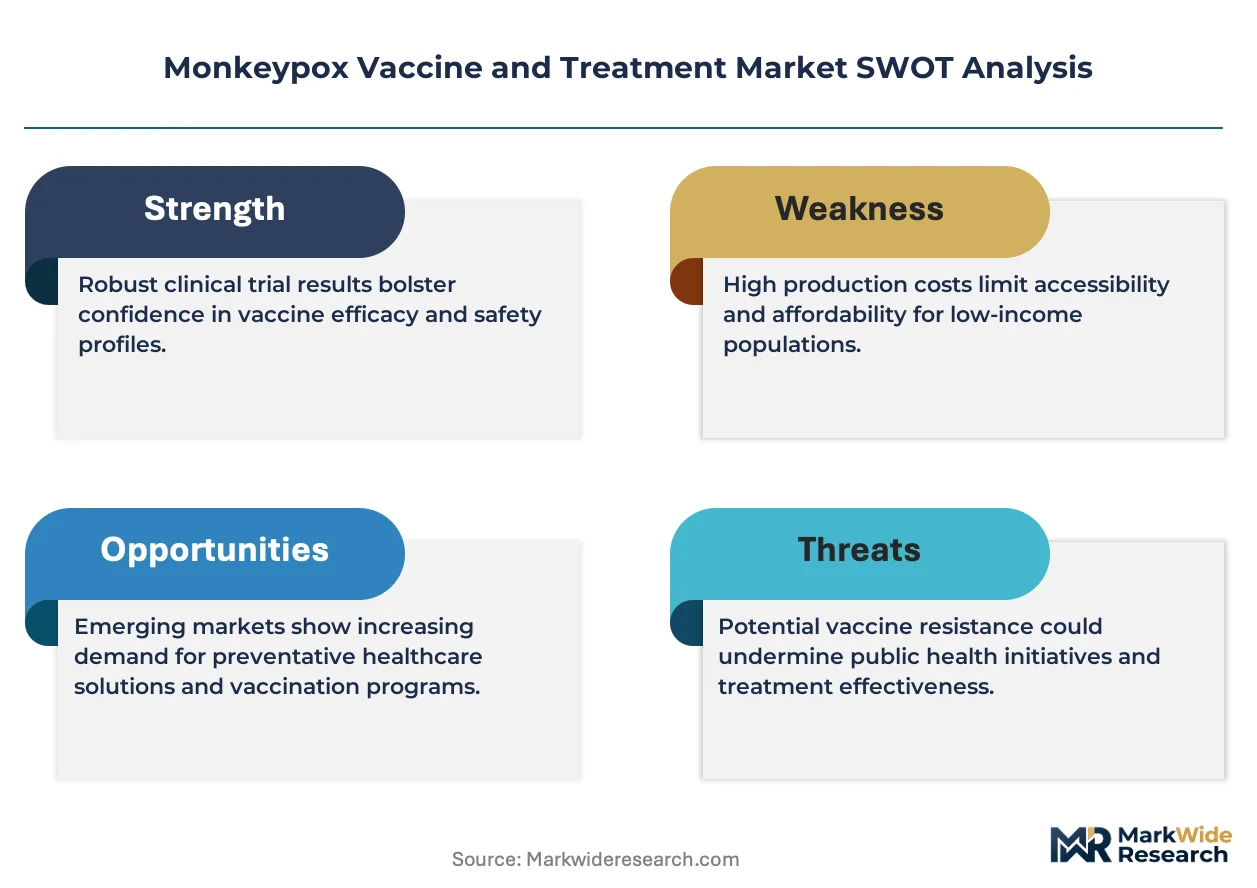
Third-generation vaccine platforms are consolidating procurement power around replication-deficient candidates, compressing development timelines for orthopoxvirus countermeasures while national strategic reserves rewrite inventory specifications.
Growth Catalysts
- WHO Emergency Use Pathway:The prequalification mechanism accelerates access for low-income country buyers, expanding addressable demand beyond traditional stockpile customers.
- Subcutaneous delivery innovation:Dose-sparing intradermal administration protocols stretch finite supply during outbreak response, amplifying effective coverage per manufactured lot.
- Biodefense procurement mandates:United States Strategic National Stockpile maintenance requirements sustain baseline demand regardless of epidemic cycles.
Market Restraints
- Fill-finish capacity concentration:European contract manufacturing organizations control sterile injectable finishing for MVA-BN derived products, creating single-source vulnerability.
- Animal efficacy rule dependency:FDA's requirement for well-characterized animal models when human challenge studies are unethical extends validation timelines for novel candidates.
- Live vaccine cold chain:Ultra-low temperature distribution infrastructure gaps in tropical outbreak zones degrade product potency before administration.
Strategic Opportunities
- Post-exposure prophylaxis indication:Monoclonal antibody developers pursuing shortened dosing windows after known exposure capture reimbursement premiums beyond pre-event vaccination.
- EU Green Deal alignment:CSRD emissions disclosure requirements favor manufacturers documenting carbon-negative cold chain logistics, creating procurement preference.
- Intradermal microarray patches:Solid-dose thermostable delivery formats eliminate refrigeration dependency for last-mile distribution in equatorial regions.
Industry Challenges
- High-containment manufacturing workforce:Biosafety level 3 production facilities face persistent vacancies for trained operators and quality assurance specialists.
- Cross-reactive serology assays:Distinguishing vaccine-induced immunity from natural orthopoxvirus exposure complicates efficacy endpoint measurement in clinical trials.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Monkeypox Vaccine and Treatment Market |
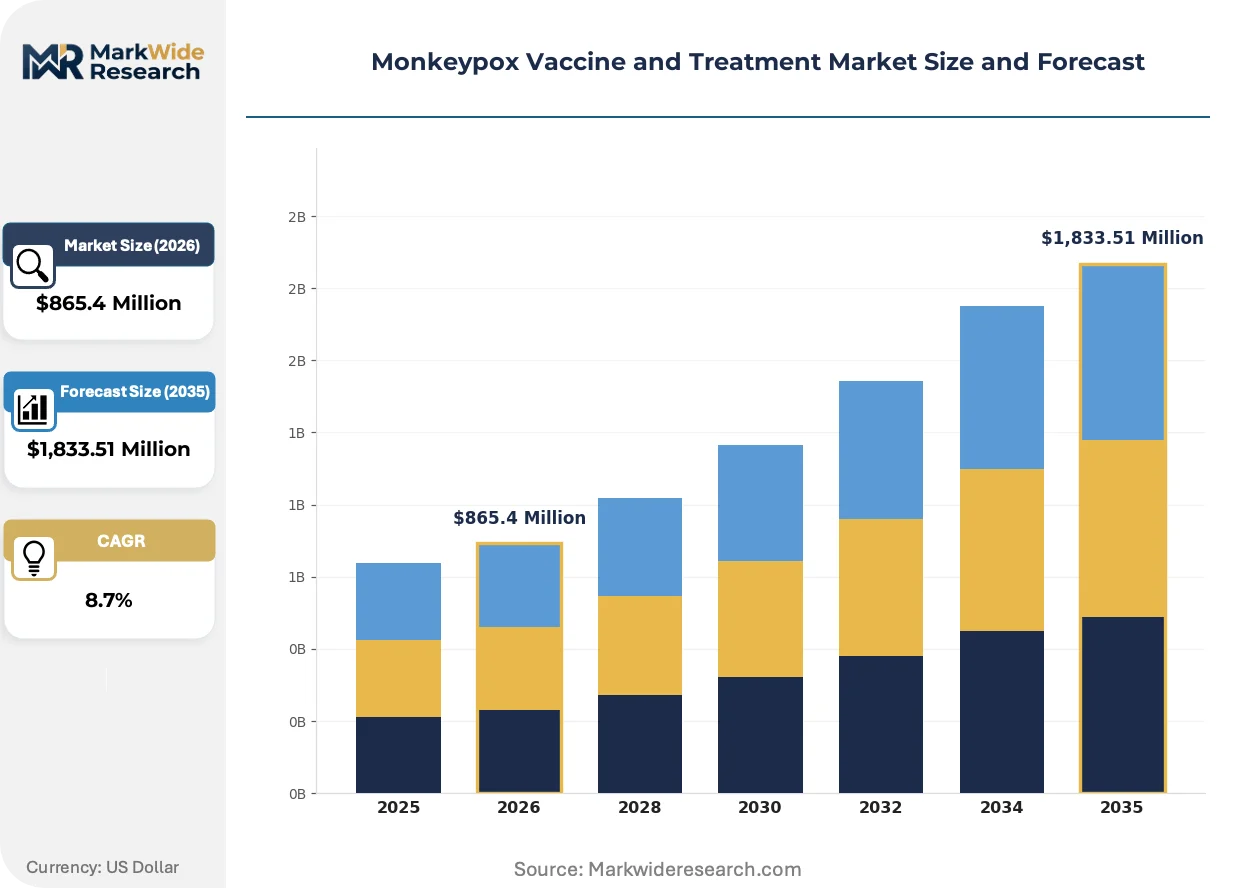
| Market Size in 2026 | $865.4 Million |
| Market Size in 2035 | $1,833.51 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Live Vaccines, Inactivated Vaccines, Antiviral Drugs, Monoclonal Antibodies Therapy Area: Infectious Diseases, Viral Infections, Epidemic Response, Immunization End User: Hospitals, Clinics, Research Institutions, Public Health Organizations Delivery Mode: Intravenous, Subcutaneous, Intramuscular, Oral |
| Companies Covered | SIGA Technologies, Bavarian Nordic, Chimerix, Emergent BioSolutions, Gilead Sciences, Sanofi, Moderna, Johnson & Johnson, Tonix Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Monkeypox Vaccine and Treatment Market Strategic Shifts & Innovations
Platform standardization around modified vaccinia Ankara derivatives is compressing competitive differentiation to manufacturing scale and regulatory access speed rather than fundamental immunological innovation.
Messenger RNA encoding orthopoxvirus antigens is rewriting the development economics for rapid-response vaccines, with synthetic manufacturing timelines collapsing from months to weeks. BARDA and CEPI funding recipients are advancing candidates through preclinical stages, positioning mRNA as the substrate for next-generation stockpile rotation. The structural consequence is a looming displacement of egg-based and cell-culture production for emergency-use indications.
EMA's conditional marketing authorization pathway for public health emergencies compresses review timelines for outbreak-countermeasure developers willing to accept post-authorization efficacy commitments. Manufacturers gain nine-to-twelve month accelerations versus standard centralized procedures, though pharmacovigilance obligations intensify. Small-cap developers lacking EU regulatory affairs infrastructure are partnering with established MVA-BN license holders to navigate rapporteur assignment.
National health security agencies are unbundling procurement from delivery, with CDC and ECDC establishing separate logistics contracts from product acquisition. This bifurcation favors specialized cold-chain operators over vertically integrated pharmaceutical companies. The United Kingdom's UKHSA pioneered this model during the 2022 outbreak, with NHS England now managing distribution independent of MHRA procurement decisions.
Monkeypox Vaccine and Treatment Market Segmentation
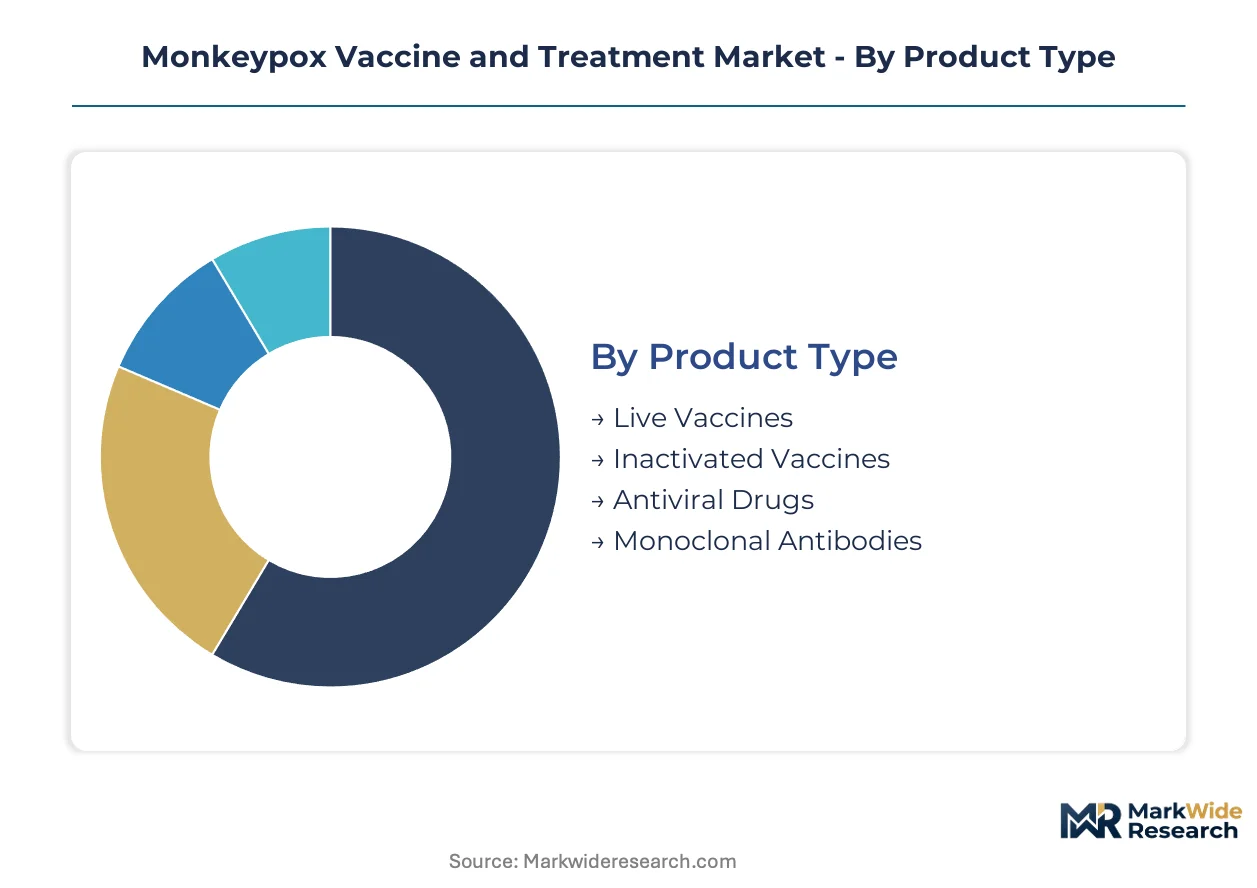
Orthopoxvirus countermeasures fragment across prophylactic and therapeutic modalities, with procurement patterns diverging between routine immunization programs and emergency stockpile deployment. Segmentation reveals how manufacturing scale, regulatory pathway, and cold-chain infrastructure shape competitive positioning across distinct product categories.
Product Type:
Live vaccines anchor standalone pre-exposure prophylaxis programs, while antiviral drugs and monoclonal antibodies embed within outbreak response protocols as reactive interventions.
- Live Vaccines:Modified vaccinia Ankara derivatives deliver replication-deficient immunization via subcutaneous or intradermal routes. Demand concentrates in the United States Strategic National Stockpile and European national reserves, driven by biodefense procurement mandates that sustain baseline orders independent of epidemic cycles.
- Antiviral Drugs:Small-molecule therapeutics targeting viral DNA replication provide post-exposure treatment for confirmed infections. Procurement flows through government stockpiling contracts rather than commercial pharmacy channels, with SIGA Technologies' TPOXX dominating supply commitments across North America and Europe.
- Inactivated Vaccines:Non-replicating candidates offer alternatives for immunocompromised populations excluded from live-virus products.
- Monoclonal Antibodies:Engineered immunoglobulins pursue post-exposure prophylaxis indications with shortened dosing windows after known exposure.
Volume placements concentrate in Live Vaccines; the faster expansion belongs to Monoclonal Antibodies.
Therapy Area:
Cost tiering separates mass vaccination campaigns from targeted epidemic containment, with infectious disease programs absorbing the largest procurement budgets.
- Infectious Diseases:Broad-spectrum orthopoxvirus countermeasures address both routine immunization and emergency deployment scenarios. Procurement scales through WHO prequalification pathways that accelerate access for low-income country buyers beyond traditional stockpile customers.
- Epidemic Response:Rapid-deployment stockpiles require thermostable formulations and dose-sparing administration protocols. Demand clusters in tropical outbreak zones where ultra-low temperature distribution infrastructure gaps degrade product potency before administration.
- Viral Infections:Narrower indications target specific orthopoxvirus species with differentiated clinical presentations.
- Immunization:Preventive programs integrate with existing smallpox eradication legacy infrastructure.
Procurement budgets concentrate in Infectious Diseases; the steepest expansion trajectory appears in Epidemic Response.
End User:
Customer type determines order scale and reimbursement pathway, with public health organizations commanding multi-year supply contracts unavailable to institutional buyers.
- Public Health Organizations:National health security agencies and international bodies coordinate multi-million dose procurements through centralized tender processes. The CDC and ECDC unbundle acquisition from delivery, establishing separate logistics contracts that favor specialized cold-chain operators.
- Hospitals:Acute care facilities manage outbreak containment within defined catchment areas, requiring rapid replenishment capabilities. Demand concentrates in metropolitan clusters with international travel connectivity that elevates importation risk.
- Clinics:Outpatient settings administer pre-exposure prophylaxis to occupational risk groups including laboratory personnel.
- Research Institutions:Academic and government laboratories conduct efficacy studies and variant surveillance.
Contract value concentrates in Public Health Organizations; the fastest volume growth emerges in Hospitals.
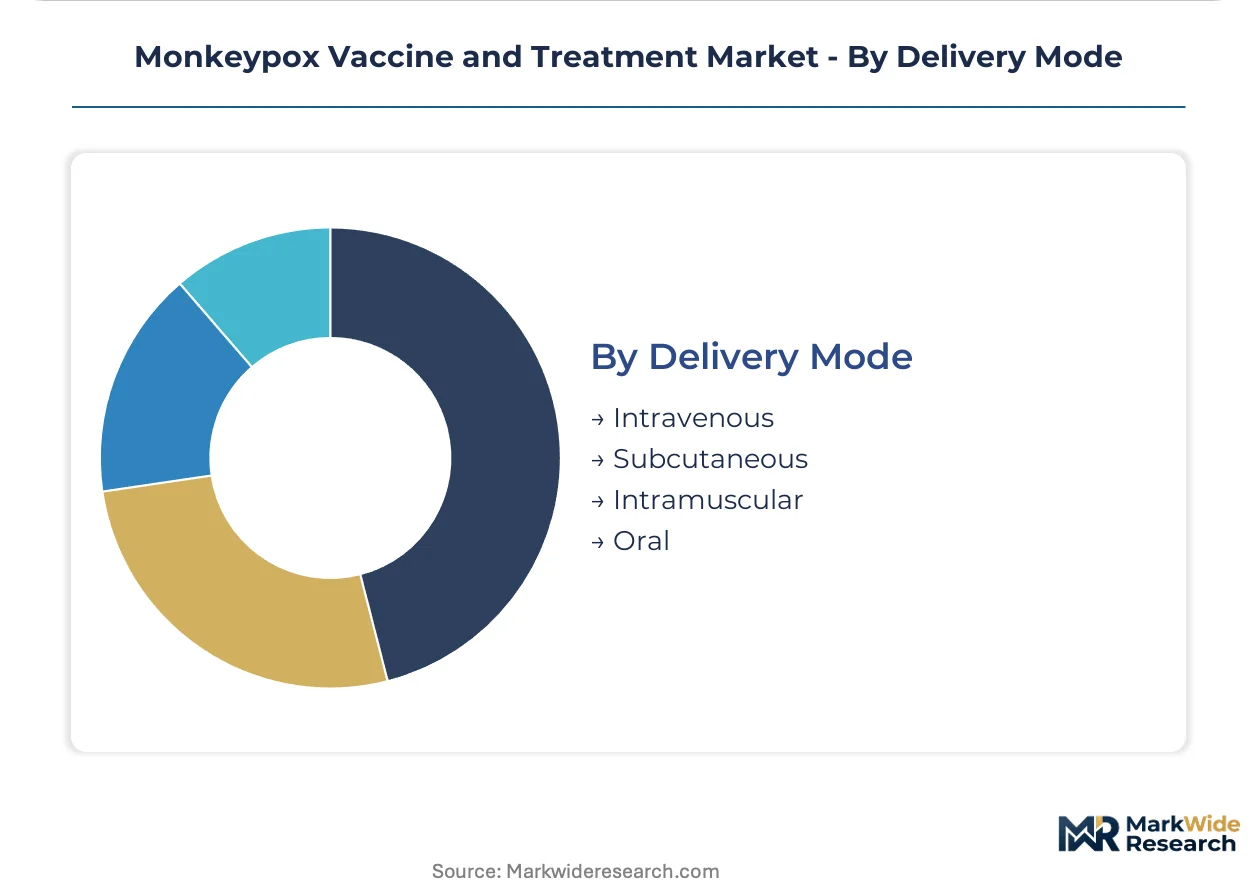
Delivery Mode:
Supply concentration in sterile injectable manufacturing shapes route availability, with subcutaneous administration dominating current dose-sparing protocols.
- Subcutaneous:Dose-sparing intradermal administration protocols stretch finite supply during outbreak response, amplifying effective coverage per manufactured lot. European contract manufacturing organizations control fill-finish capacity for MVA-BN derived products.
- Intravenous:Antiviral drugs requiring hospital infusion target severe disease presentations with therapeutic monitoring. Administration concentrates in tertiary care centers with biocontainment capabilities.
- Intramuscular:Conventional injection routes persist for legacy vaccine formulations.
- Oral:Solid-dose formats eliminate refrigeration dependency for last-mile distribution in equatorial regions.
Manufacturing scale concentrates in Subcutaneous; the most rapid technology transition targets Oral.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bioscience parks in Maryland and Massachusetts concentrate biodefense manufacturing capacity, attracting federal procurement contracts and specialized cold-chain logistics operators to the I-270 corridor.
United States
The Strategic National Stockpile sustains baseline demand through multi-year supply contracts with Bavarian Nordic and SIGA Technologies. FDA's animal efficacy rule shapes validation timelines for novel orthopoxvirus candidates. Maryland's I-270 biotechnology corridor hosts fill-finish facilities for MVA-BN derived products.
Germany
EMA conditional marketing authorizations accelerate review timelines for outbreak countermeasures. The EU Green Deal and CSRD reporting requirements force manufacturers to document cold-chain emissions. Bavaria's vaccine manufacturing cluster anchors European production of replication-deficient vaccines.
United Kingdom
UKHSA pioneered unbundled procurement models separating product acquisition from NHS England distribution. MHRA emergency use pathways enabled rapid deployment during the 2022 outbreak. London's national health security infrastructure coordinates multi-million dose tenders.
Denmark
Bavarian Nordic's headquarters anchors Nordic biodefense supply chains to North American and European reserves. The Danish Medicines Agency aligns with EMA centralized procedures for orthopoxvirus countermeasures. Copenhagen's pharmaceutical cluster specializes in high-containment viral vector manufacturing.
Canada
Health Canada leverages FDA emergency use authorizations through reliance pathways for rapid product access. The Public Health Agency of Canada maintains strategic reserves through Public Services and Procurement Canada. Ontario's Toronto-Waterloo bioscience corridor hosts contract manufacturing for sterile injectables.
Monkeypox Vaccine and Treatment Market Key Industry Players
Top-tier vendors anchor government stockpile contracts, while mid-cap developers pursue novel platform technologies through BARDA and CEPI funding mechanisms. The market structure consolidates around replication-deficient vaccine platforms and small-molecule antivirals. Two strategic archetypes dominate: vertically integrated biodefense contractors with established regulatory access, and platform-technology developers seeking emergency use pathways. Competitive moves center on manufacturing scale expansion and strategic licensing of MVA-BN derivatives.
Among established biodefense contractors, Bavarian Nordic and SIGA Technologies occupy positions as archetypal stockpile suppliers, with Emergent BioSolutions representing the diversified manufacturing tier. These entities exemplify contrasting strategic postures: the MVA-BN platform licensor versus the antiviral specialist, both sustained by government procurement rather than commercial pharmacy channels. Moderna and Chimerix sit within the development-stage tier, pursuing mRNA and novel antiviral platforms respectively.
| Leading Market Players |
|---|
| SIGA Technologies |
| Bavarian Nordic |
| Chimerix |
| Emergent BioSolutions |
| Gilead Sciences |
| Sanofi |
| Moderna |
| Johnson & Johnson |
| Tonix Pharmaceuticals |
| Others |
Cost & Logistics Intelligence
US Strategic National Stockpile multi-year procurement mandates compress supplier margins while demanding guaranteed surge capacity, forcing manufacturers to embed cold-chain redundancy costs into contract pricing and prioritize fill-finish scale over R&D investment.
Pricing Analysis
Short lead-time premiums dominate government procurement contracts, with emergency outbreak response orders commanding price multiples over scheduled stockpile replenishment. Three-tier pricing structure across emergency surge, scheduled rotation, and pre-positioned inventory levels separates biodefense readiness tiers. Cost compression in scheduled procurement is intensifying because BARDA and CEPI funding recipients are advancing mRNA alternatives that threaten MVA-BN platform incumbency. Public health organizations exhibit lowest price sensitivity due to statutory stockpile maintenance requirements, while research institutions face strict budget caps that amplify competitive bidding pressure.
Supply Chain Analysis
Direct-to-government channels handle strategic reserve procurement, bypassing wholesale distributors entirely. Fill-finish capacity concentrates in Denmark, Germany, and the United States, with Bavarian Nordic's Copenhagen facility anchoring European MVA-BN output. High-containment viral vector manufacturing draws from specialized BSL-3 infrastructure, fetal bovine serum, and single-use bioreactor consumables. Single-source vulnerability pervades sterile injectable finishing, where European contract manufacturing organizations control critical-path capacity for replication-deficient vaccines. Distribution runs through federally contracted cold-chain operators with validated ultra-low temperature custody documentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race. Manufacturers are pursuing upstream control over high-containment production infrastructure to secure regulatory priority and lock out platform competitors.
For Market Incumbents: Deploy MVA-BN platform licensing as a defensive perimeter against mRNA displacement threats. Secure exclusive fill-finish partnerships with European contract manufacturing organizations to constrain competitor capacity access. Accelerate post-exposure prophylaxis indication expansion for monoclonal antibodies to capture reimbursement premiums beyond pre-event vaccination tiers. For New Entrants and Emerging Players: Enter via thermostable solid-dose delivery formats that eliminate cold-chain dependency in tropical outbreak zones. Target epidemic response procurement channels where ultra-low temperature infrastructure gaps degrade incumbent product potency. Pursue WHO prequalification status as the primary go-to-market angle to unlock low-income country demand beyond traditional stockpile customers. For Investors and Strategic Acquirers: The window for entry favors platform-technology developers with emergency use pathway experience and BARDA funding relationships. Long-term viability hinges on regulatory access speed rather than manufacturing scale alone. Watch for EMA conditional marketing authorization accelerations as the inflection signal indicating which candidates will capture nine-to-twelve month review advantages.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | High-containment BSL-3 capacity expansion in Denmark and Maryland secures MVA-BN supply commitments. |
| Regulatory Approval Pathway | FDA animal efficacy rule navigation accelerates novel orthopoxvirus candidate validation timelines. |
| Licensing Agreement | MVA-BN derivative sublicensing to mid-cap developers spreads platform risk across multiple indications. |
| Clinical Trial Advancement | Post-exposure prophylaxis dosing window compression trials unlock monoclonal antibody reimbursement premiums. |
| Pipeline Diversification | mRNA orthopoxvirus antigen programs position developers for next-generation stockpile rotation displacement. |
Research Approach
FDA filings, EMA centralized procedure documentation, and WHO prequalification status records formed the secondary backbone, cross-referenced against ClinicalTrials.gov entries and national stockpile procurement disclosures. Primary interviews with biodefense procurement officers, regulatory affairs leads at vaccine developers, high-containment facility operations directors, and GPO contracts managers validated demand assumptions and manufacturing capacity constraints. Bottom-up and top-down triangulation reconciled dose-volume forecasts with government budget appropriation trajectories.
Bottom-up modeling anchored volume projections to disclosed Strategic National Stockpile maintenance requirements and ECDC unbundled procurement patterns, while top-down validation assessed macro-level biodefense spending envelopes. Segmentation across product type, therapy area, end user, and delivery mode informed granular demand disaggregation. CAGRs were derived from multi-year contract value analysis and dose-schedule evolution assumptions. Forecast inputs included cold-chain logistics cost trajectories and BSL-3 workforce availability indices.
Forecast precision tightens around the base case; tail outcomes carry wider variance under outbreak-driven emergency procurement surges or regulatory pathway delays for novel platforms. Periodic stress-testing of base assumptions is recommended, particularly regarding mRNA platform displacement timelines and EU Green Deal emissions disclosure enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
China Opioids Market
Pharmaceuticals
Antiplatelet Drugs Market
Pharmaceuticals
Omega 3 Prescription Drugs Market
Pharmaceuticals
Josamycin Market
Pharmaceuticals
Hydrocortisone Market
Pharmaceuticals
Digital Pharmaceutical Supply Chain Management Market
Pharmaceuticals
Global Compounding Pharmacy Market
Pharmaceuticals
Europe Parenteral Lipid Emulsion Market
Pharmaceuticals
Global Janus Kinase Inhibitor (JAK) Market
Pharmaceuticals
Mouth Ulcers Treatment Market
Pharmaceuticals
Global Muscle Relaxant Drugs Market
Pharmaceuticals
Cannabinoid Drugs Market
Pharmaceuticals
Asia Pacific Multiple Sclerosis Drugs Market
Pharmaceuticals
Ocular Excipients Market
Pharmaceuticals
Global Pharmaceutical Traceability Market
Pharmaceuticals
Ebola Drug and Vaccine Market