
 Mouth Ulcers Treatment Market | 2026-2036
Mouth Ulcers Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Mouth Ulcers Treatment Market Intelligence
The specialized knowledge of formulation chemists in developing bioadhesive polymers is redrawing the product landscape for pain relief. GlaxoSmithKline plc leverages its extensive R&D in consumer healthcare to maintain a strong portfolio. Colgate-Palmolive Company sustains its market presence through powerful brand recognition and vast distribution channels. Meanwhile, 3M Company differentiates with its material science expertise, particularly in oral care patches.
Mouth ulcer treatments encompass pharmaceutical formulations designed to alleviate pain and accelerate the healing of oral lesions. These products often contain active ingredients like local anesthetics or anti-inflammatory agents within a mucoadhesive base for prolonged contact. Topical gels and oral rinses constitute the largest product segments by volume, while patches are gaining traction as a high-margin option. Aphthous stomatitis remains the primary therapy area, driving the bulk of treatment applications.
Regulatory oversight from bodies like the US FDA, Europe's EMA, and China's NMPA governs product classification and market access. These agencies' rules for over-the-counter drugs and medical devices directly influence permissible active ingredients and marketing claims. Success for manufacturers will depend on their ability to navigate the varying classification of treatments as either a cosmetic, medical device, or pharmaceutical across key international markets.
Market Dynamics
The development of advanced bioadhesive polymers for prolonged, targeted drug delivery is the central force shaping the market, moving it beyond simple topical anesthetics and toward more efficacious, higher-margin treatment modalities like patches and advanced gels.
Growth Catalysts
- Bioadhesive Polymers:The formulation of new polymers enhances drug delivery for topical gels and patches, improving mucoadhesion for prolonged contact time and greater therapeutic effect on oral lesions.
- Aging Demographics:An increasing elderly population in developed nations like Japan, which often experiences higher rates of oral mucosal conditions, provides a consistent source of demand for effective ulcer treatments.
- OTC Accessibility:The reclassification of certain formulations to over-the-counter status by regulators in various markets expands consumer access, allowing purchase without a prescription and broadening the customer base.
Market Restraints
- Substitution Threat:Low-cost antiseptic mouthwashes and simple home remedies remain a significant alternative for price-sensitive consumers, limiting the pricing power for more advanced, specialized treatments.
- Regulatory Heterogeneity:Navigating disparate product classifications as a drug (US FDA), medical device (Europe's EMA), or cosmetic across key markets increases compliance costs and time-to-market.
- API Costs:The high cost of specific active pharmaceutical ingredients, such as potent corticosteroids or novel anesthetics, restricts their use in mass-market formulations and can make premium products prohibitively expensive.
Strategic Opportunities
- Emerging Markets:Untapped potential exists in Southeast Asian nations, where rising disposable incomes and improving oral health awareness are creating new demand for specialized ulcer treatments.
- Pediatric Formulations:Developing flavored, non-stinging products specifically for children addresses an underserved segment of the aphthous stomatitis patient population, offering a clear path for product differentiation.
- Combination Therapies:Formulations that merge a local anesthetic for immediate relief with an anti-inflammatory agent for accelerated healing represent a key innovation path for creating high-value products.
Industry Challenges
- Clinical Trial Burden:Proving the efficacy of high-margin patches to meet the stringent standards of regulators like Japan's PMDA or China's NMPA requires lengthy and expensive clinical studies.
- Consumer Education Gap:Differentiating advanced, higher-priced treatments from basic gels demands significant marketing investment to explain the benefits of new delivery mechanisms like bioadhesion or controlled release.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mouth Ulcers Treatment Market |
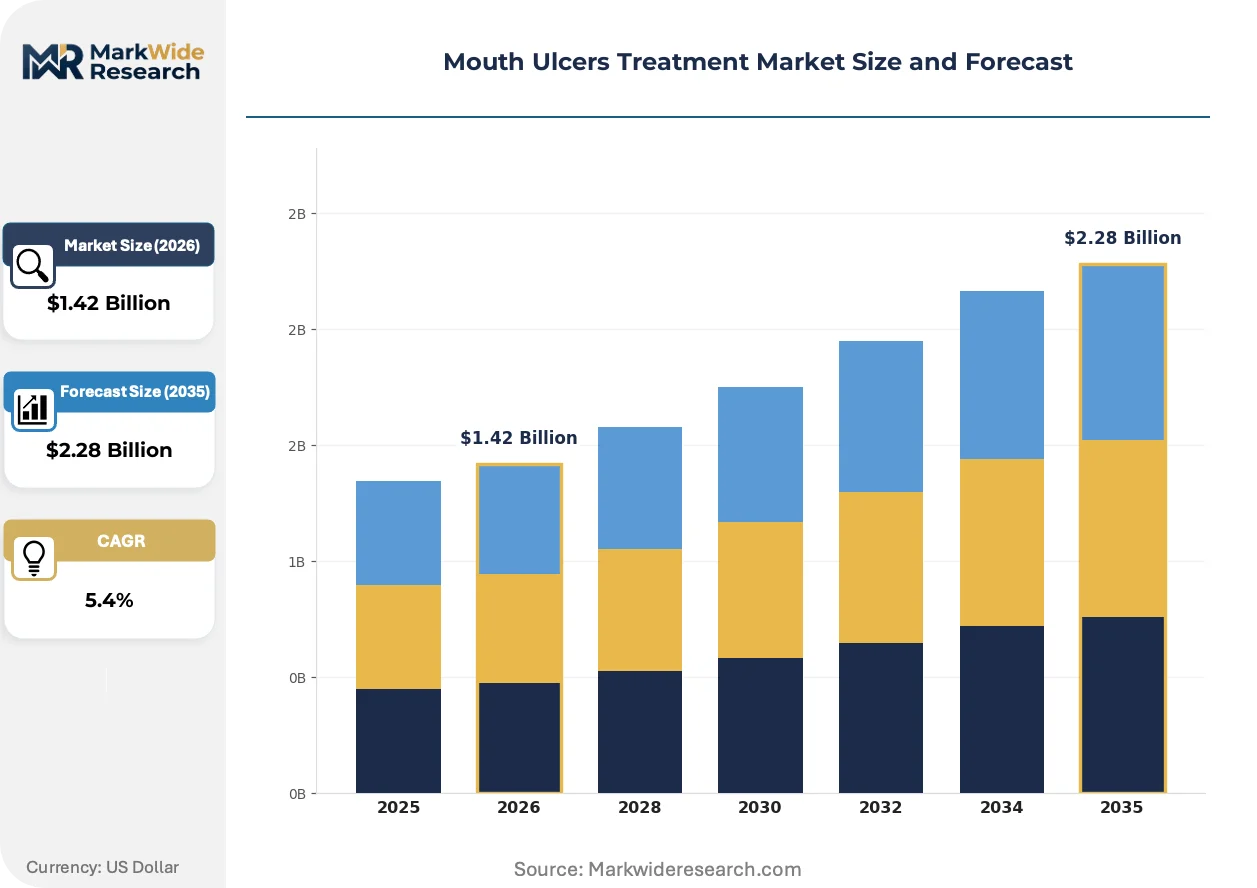
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.28 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Topical Gels, Oral Rinses, Pastes, Lozenges, Patches Therapy Area: Aphthous Stomatitis, Traumatic Ulcers, Viral Ulcers, Allergic Ulcers, Drug-Induced Ulcers Administration Route: Oral, Sublingual, Buccal, Topical, Spray End User: Dental Clinics, Oral Care Centers, Pharmacies, Hospitals |
| Companies Covered | GlaxoSmithKline plc, Colgate-Palmolive Company, Blistex Inc., 3M Company, Church & Dwight Co., Inc., Pfizer Inc., Bristol-Myers Squibb Company, ECR Pharmaceuticals, Taro Pharmaceutical Industries Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mouth Ulcers Treatment Market Strategic Shifts & Innovations
The market is shifting from generalized, one-size-fits-all treatments toward more personalized and targeted therapeutic approaches. This evolution prioritizes not just pain relief but also the mechanism and duration of active ingredient delivery, creating distinct value tiers.
Biodegradable mucoadhesive polymers function by delivering active ingredients directly to the ulcer site before safely dissolving. Dental clinics and informed consumers are adopting these advanced patches for their convenience and targeted action. This technology is decomposing the traditional boundary between a topical drug and a physical wound dressing, creating a new hybrid product category.
Europe's Medical Device Regulation (MDR) imposes stricter requirements for products classified as medical devices, including many advanced oral care patches. The regulation mandates more rigorous clinical evidence and post-market surveillance for market access. Consequently, manufacturers of high-margin patches face increased investment in clinical data generation to maintain their presence in the EU.
A clear consumer behavior shift involves purchasing specialized oral care products through e-commerce platforms and direct-to-consumer channels. This pattern disrupts the traditional dominance of physical pharmacies as the primary point of sale for such treatments. The direct-to-consumer movement is particularly prominent in North American and European markets, where digital-native brands are gaining traction.
Mouth Ulcers Treatment Market Segmentation
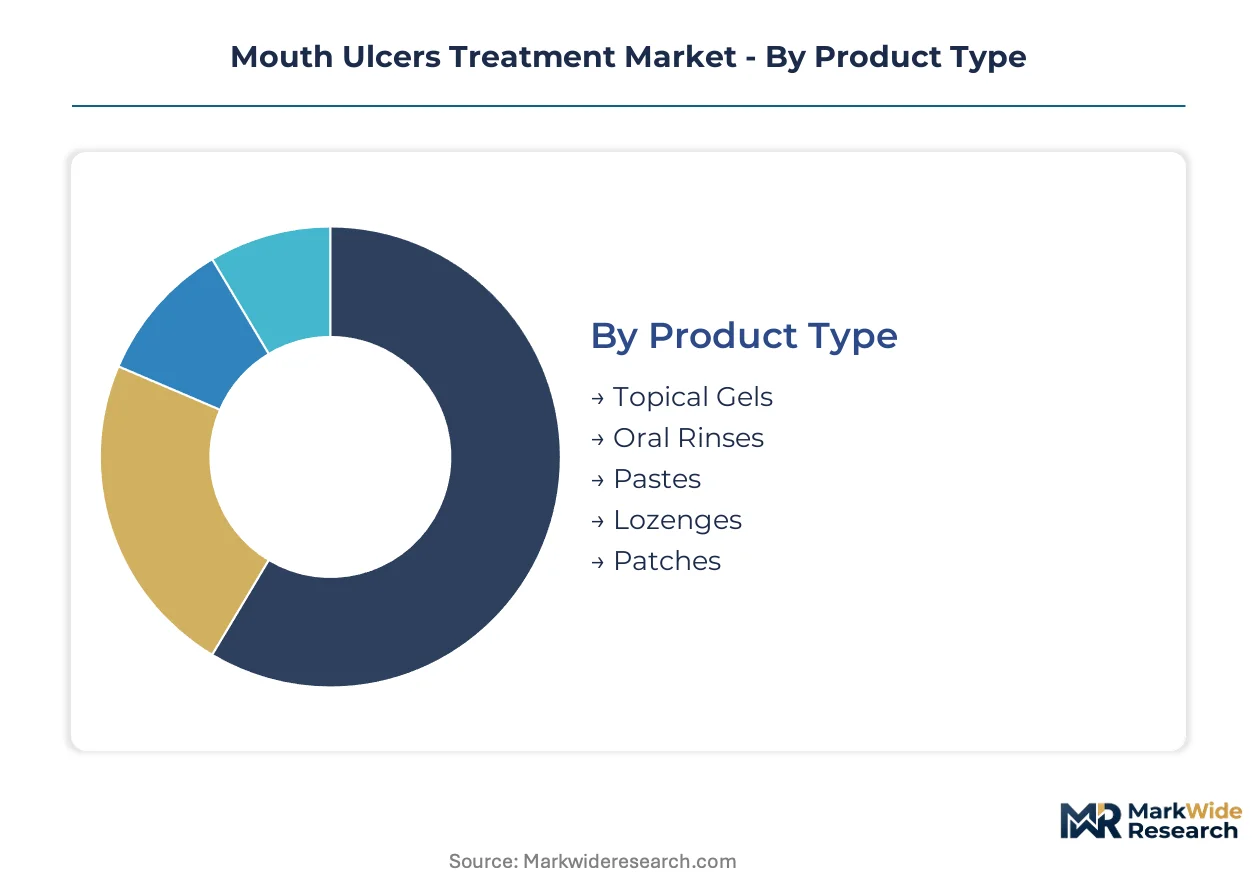
Market segmentation provides a structured view of the diverse product offerings and end-user demands shaping the mouth ulcers treatment landscape. Understanding these distinct categories allows manufacturers to tailor product development and marketing strategies for specific patient needs and commercial opportunities.
Product Type:
Margin pools for product types concentrate in advanced delivery systems offering enhanced efficacy and patient convenience.
- Patches:These products leverage biodegradable mucoadhesive polymers to deliver active ingredients directly to the ulcer site before safely dissolving. Demand concentrates in Japan, driven by an aging demographic and high oral hygiene standards seeking convenient, targeted solutions.
- Topical Gels:These formulations often contain active ingredients like local anesthetics or anti-inflammatory agents within a mucoadhesive base for prolonged contact. Demand is significant across Europe, where consumers seek immediate pain relief and accelerated healing for common oral lesions.
- Oral Rinses:Antiseptic or analgesic solutions provide broad coverage of the oral cavity for general oral hygiene and minor discomfort.
- Pastes:Thick, adhesive formulations offer localized application and a protective barrier over specific ulcerations.
- Lozenges:Solid dosage forms slowly dissolve in the mouth, releasing active ingredients for localized relief.
Topical Gels hold installed capacity. Patches are rotating up the share rankings.
Therapy Area:
Treatment application volume is highest for common oral conditions, driving product development and distribution efforts.
- Aphthous Stomatitis:These recurrent oral ulcers are characterized by painful, round lesions appearing inside the mouth. Demand for treatments is high globally, as aphthous stomatitis remains the primary therapy area driving the bulk of treatment applications.
- Traumatic Ulcers:Physical injury or irritation, often from dental appliances or accidental biting, causes these lesions. Demand is notable in dental clinics, where professionals often recommend specialized products for healing and pain management.
- Viral Ulcers:Caused by viral infections, these lesions frequently manifest as cold sores or fever blisters.
- Allergic Ulcers:Hypersensitivity reactions to certain foods, medications, or dental materials can trigger these specific ulcers.
- Drug-Induced Ulcers:Certain medications, such as chemotherapy drugs, can cause oral ulceration as an adverse side effect.
Aphthous Stomatitis treatments maintain the largest market volume. Traumatic Ulcers are expanding most quickly.
Administration Route:
Customer preference for ease of application and targeted delivery shapes the administration route landscape.
- Topical:Direct application to the ulcer site ensures localized drug delivery, minimizing systemic absorption and side effects. This route sees high demand in over-the-counter products across North America, favored for immediate relief and user-friendliness.
- Buccal:Products administered via the buccal mucosa allow for either systemic absorption or targeted local action within the mouth. Demand is growing in advanced markets like Germany, where patients value precise drug delivery and prolonged contact time.
- Oral:Systemic medications taken by mouth address underlying causes or provide general pain relief throughout the body.
- Sublingual:Rapid absorption of active ingredients occurs directly into the bloodstream through placement under the tongue.
- Spray:Convenient, non-contact application methods allow for broad coverage or access to hard-to-reach areas.
Topical administration holds the largest installed base. Buccal delivery is gaining share fastest.
End User:
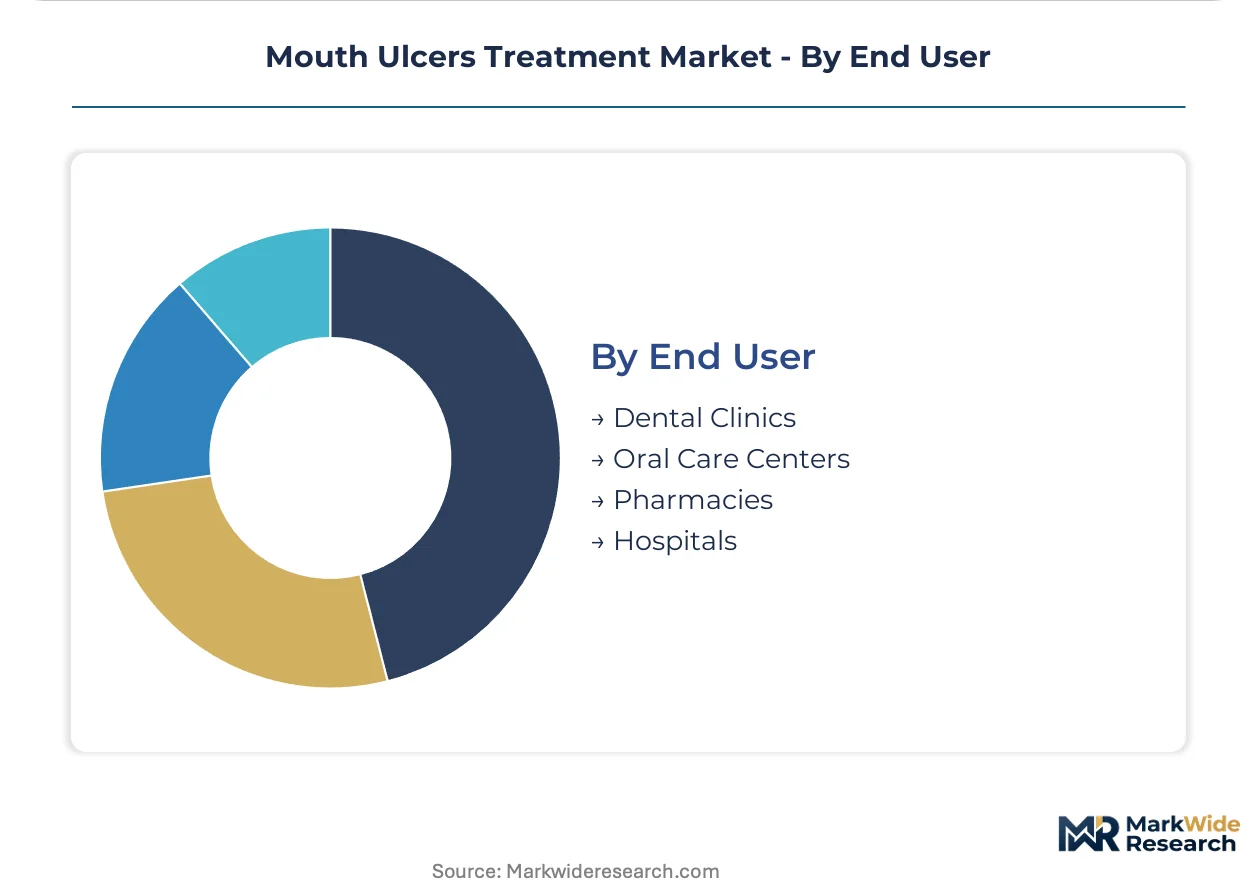
Cost efficiency and professional guidance influence end-user segment dynamics, dictating distribution channels and product access.
- Pharmacies:These retail outlets serve as primary points of sale for a wide range of over-the-counter mouth ulcer treatments. Demand is high in populous regions like China, where broad consumer accessibility drives product distribution.
- Dental Clinics:Healthcare facilities provide professional diagnosis and specialized treatment recommendations for oral lesions. These clinics in the US are seeking effective patient solutions, driving demand for advanced products.
- Oral Care Centers:Specialized facilities focus on comprehensive oral health, including advanced diagnostics and treatments for complex cases.
- Hospitals:Medical institutions provide care for severe or complex cases of oral ulceration, including post-surgical management and inpatient treatment.
Pharmacies command the largest distribution network. Dental Clinics show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's Pharmaceutical and Medical Devices Agency (PMDA) significantly influences global mouth ulcer treatment development, particularly for advanced patches. This regulatory body's stringent requirements for clinical evidence often set a benchmark for efficacy and safety. Demand for these specialized treatments is robust across several key international markets.
Japan
An aging demographic and high oral hygiene standards drive consistent demand for effective ulcer treatments in Japan. The PMDA's strict clinical trial standards apply to high-margin patches, necessitating significant investment from manufacturers. Tokyo's pharmaceutical research hubs are focusing on innovative bioadhesive polymer development for targeted drug delivery.
United States
OTC accessibility for many formulations and dental clinics seeking effective patient solutions bolster demand in the United States. The US FDA's classification of treatments as either drugs or medical devices directly influences permissible active ingredients and marketing claims. Biotech clusters in Boston and San Francisco are developing novel drug delivery systems for oral lesions.
Germany
Patients in Germany value precise drug delivery and prolonged contact time, especially for buccal administration routes. Europe's EMA and the Medical Device Regulation (MDR) influence product classification and market access for advanced oral care medical devices. Pharmaceutical centers in Frankfurt and Munich are advancing specialized topical gel formulations.
China
High demand in populous regions and broad consumer accessibility through pharmacies characterize the Chinese market. China's NMPA governs market access and clinical trial requirements for new oral care products, impacting time-to-market. Shanghai and Beijing are emerging as key hubs for both local and international manufacturers of oral health solutions.
India
Rising disposable incomes and improving oral health awareness in India create new demand for specialized ulcer treatments. The Central Drugs Standard Control Organization (CDSCO) regulates pharmaceutical products and medical devices, influencing market entry strategies. Major pharmaceutical manufacturing in Hyderabad and Mumbai is expanding production of affordable topical treatments.
Mouth Ulcers Treatment Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier within the mouth ulcers treatment market. This structure features consumer healthcare giants, material science innovators, and specialized pharmaceutical companies. Strategic archetypes include those leveraging extensive R&D, those focused on powerful brand recognition, and those with material science expertise. Competitive moves center on R&D into bioadhesive polymers, leveraging brand recognition, and expanding distribution networks.
Among the established players, GlaxoSmithKline plc exemplifies a global pharmaceutical presence, leveraging its extensive R&D in consumer healthcare. Colgate-Palmolive Company sustains its market presence through powerful brand recognition and vast distribution channels, particularly for general oral care. 3M Company, a Minnesota-based entity, differentiates with its material science expertise, particularly in oral care patches.
| Leading Market Players |
|---|
| GlaxoSmithKline plc |
| Colgate-Palmolive Company |
| Blistex Inc. |
| 3M Company |
| Church & Dwight Co., Inc. |
| Pfizer Inc. |
| Bristol-Myers Squibb Company |
| ECR Pharmaceuticals |
| Taro Pharmaceutical Industries Ltd. |
| Others |
Cost & Logistics Intelligence
Long-term supply agreements for specialized bioadhesive polymers lock in both supply access and price visibility for manufacturers of advanced mouth ulcer treatments. This structure enables consistent product development and market penetration.
Pricing Analysis
Price differentials across Japan and China reflect varying regulatory burdens and consumer willingness to pay for advanced treatments. The market operates on a value-based pricing model for high-margin patches, contrasting with per-unit transactional pricing for basic gels. Bioadhesive polymer quality and regulatory certification, such as PMDA approval, drive price differentiation. Pricing pressure stems from the substitution threat of low-cost antiseptic mouthwashes. Pharmacies and general consumers are price-sensitive for basic gels, while dental clinics prioritize efficacy and targeted relief.
Supply Chain Analysis
China and India anchor active pharmaceutical ingredient (API) production for many oral care formulations. The supply chain draws heavily from specialized manufacturers of bioadhesive polymers, often concentrated in Germany and the US. API cost volatility represents a significant structural risk for manufacturers. Distribution runs through multi-channel networks, encompassing pharmacies, dental clinics, and a rapidly expanding e-commerce presence.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The mouth ulcers treatment market is experiencing a buyer-power shift, with large pharmacy chains consolidating procurement and influencing product selection for over-the-counter solutions.
For Market Incumbents: Fortify existing product portfolios by investing in advanced bioadhesive polymer R&D and strengthening intellectual property around novel delivery systems. This defends against emerging direct-to-consumer brands and the substitution threat from generic alternatives. Incumbents should leverage channel control through dental clinics and invest in certification for complex medical devices under EU MDR to reinforce market position.
For New Entrants and Emerging Players: Under-served pediatric patient populations present a significant entry point for specialized formulations. Developing flavored, non-stinging products for children, particularly for aphthous stomatitis, targets a clear white-space opportunity. Focusing on e-commerce platforms in Southeast Asian markets offers a direct-to-consumer go-to-market angle, bypassing traditional pharmacy dominance.
For Investors and Strategic Acquirers: Specialized biotech firms with proprietary bioadhesive polymer technologies represent attractive acquisition targets for long-term market viability over the next decade. These firms often possess critical intellectual property for high-margin patches. Successful clinical trials for novel combination therapies will serve as a key inflection indicator for potential investment.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Accelerates market access for high-margin patches by meeting stringent PMDA and NMPA standards. |
| Regulatory Approval Pathway | Navigates diverse classifications (drug, device, cosmetic) across US FDA and Europe's EMA. |
| Manufacturing Scale-Up | Ensures cost-effective production of advanced bioadhesive polymers and specialized formulations. |
| Distribution Channel Expansion | Reaches new consumer segments through e-commerce platforms and dental clinic partnerships. |
| Product Launch | Introduces novel combination therapies blending anesthetics with anti-inflammatory agents for enhanced relief. |
Research Approach
The analysis maps product types, therapy areas, and end-user segments, each validated through extensive primary interviews. Stakeholders included formulation chemists, regulatory affairs specialists, dental practitioners, and pharmacy buyers. Secondary data sources such as FDA filings, EMA guidance documents, and NMPA reports provided further validation. This approach combined bottom-up market sizing with top-down industry trend analysis.
Forecast outputs underwent rigorous cross-validation against established market benchmarks and historical performance. The analytical framework modeled segmentation dimensions including product type, therapy area, administration route, end-user, and regional market dynamics across the analysis window. Compound annual growth rates were derived from historical trends and projected growth drivers. Key forecast inputs included demographic shifts, specifically aging populations, and regulatory reclassification trends.
Forecasts assume regulatory continuity in key regimes like the US FDA and Europe's EMA; material policy shifts would require re-modeling. Unforeseen API supply disruptions or significant changes in consumer purchasing behavior represent additional risk factors. Recalibration cycles align with material shifts in named drivers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Middle East and Africa Glucagon-Like Peptide-1 (GLP-1) Agonists Market
Pharmaceuticals
Dual Migraine Treatment Market
Pharmaceuticals
Nefopam Hydrochloride Injection Market
Pharmaceuticals
Sarcoidosis Drugs Market
Pharmaceuticals
Filgrastim Market
Pharmaceuticals
Anticancer Drugs Market
Pharmaceuticals
Global Immuno Oncology Drugs Market
Pharmaceuticals
Anti-Obesity Drugs Market
Pharmaceuticals
Italy Diabetes Drugs Market
Pharmaceuticals
Flumazenil Market
Pharmaceuticals
Non-Sterile Compounding Pharmacy Market
Pharmaceuticals
Compound Potassium Hydrogen Phosphate Injection Market
Pharmaceuticals
Oral Solid Dosage Contract Manufacturing Market
Pharmaceuticals
Sarcoma Drugs Market
Pharmaceuticals
Cortisone Market
Pharmaceuticals
Asia-Pacific Meglitinide Market