
 Ebola Drug and Vaccine Market | 2026-2036
Ebola Drug and Vaccine Market Size, Share, and Industry Trends Forecast 2026-2036
Ebola Drug and Vaccine Market Foresight
mRNA platform technology is reshaping how Ebola vaccines are developed and manufactured, compressing timelines from strain identification to clinical-ready candidates. Merck & Co., Inc. anchors the licensed vaccine landscape with its recombinant vesicular stomatitis virus-based product. Johnson & Johnson competes through a heterologous prime-boost regimen leveraging Ad26 and MVA vector platforms. Regeneron specializes in monoclonal antibody cocktails that target glycoprotein epitopes for post-exposure therapeutic intervention.
Ebola drugs and vaccines comprise biologics designed to prevent or treat infection by ebolaviruses, typically formulated as live-attenuated or viral-vectored immunogens and recombinant protein therapeutics requiring cold-chain distribution at minus sixty to minus eighty degrees Celsius. Their primary purpose is to interrupt transmission chains during outbreaks and protect frontline healthcare workers in endemic zones. Vaccines dominate procurement volumes through government stockpiling programs, while monoclonal antibodies capture premium pricing in therapeutic deployment. mRNA technology represents the fastest-expanding development pipeline as developers seek multivalent filovirus coverage.
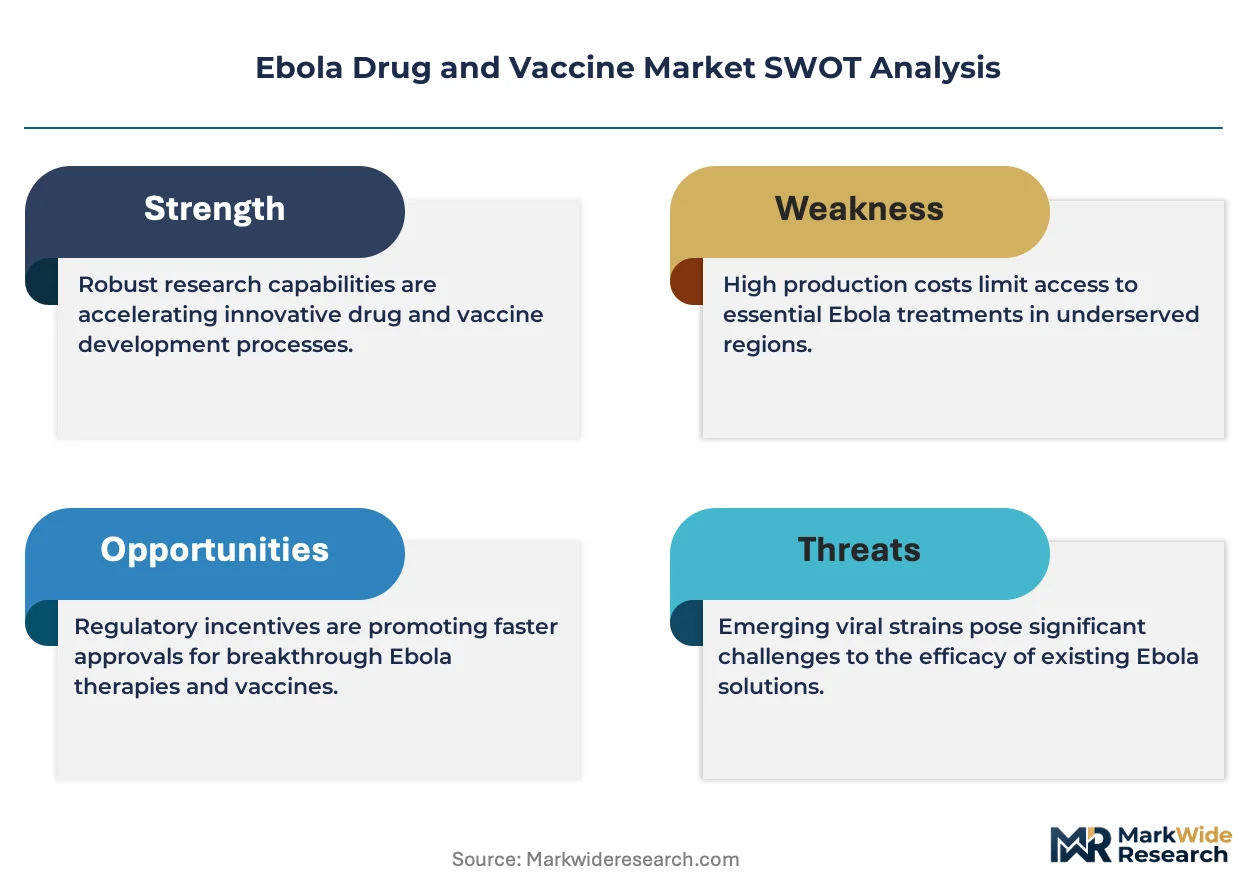
The FDA's Animal Rule governs approval pathways for Ebola therapeutics where human efficacy studies are unethical, while the EMA's PRIME designation accelerates access review for vaccines targeting unmet medical needs in tropical diseases. WHO prequalification status determines eligibility for Gavi and UNICEF procurement frameworks that channel products into outbreak response. Stakeholders must monitor viral emergence patterns in Central and West African reservoir species to align R&D portfolios with circulating strains and evolving glycoprotein divergence.
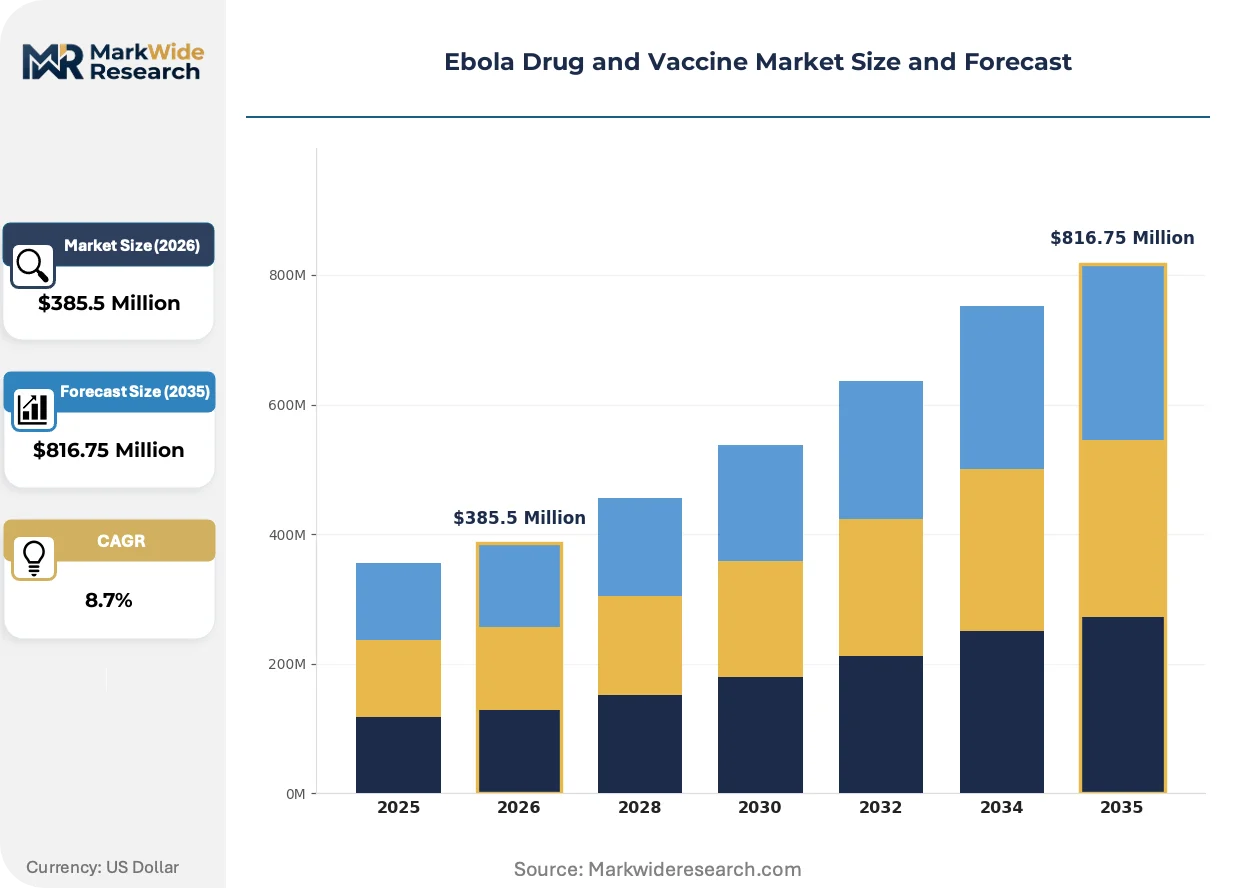
Market Dynamics
mRNA platform acceleration is compressing development timelines for filovirus countermeasures while the FDA's Animal Rule pathway removes traditional efficacy trial barriers for lethal-disease therapeutics.
Growth Catalysts
- WHO Prequalification Framework:Gavi and UNICEF procurement eligibility hinges on this designation, channeling vaccines into outbreak response stockpiles across endemic African nations.
- Democratic Republic of Congo:Persistent Zaire ebolavirus circulation in North Kivu and Ituri provinces sustains demand for rapid-deployment monoclonal antibody cocktails and vector-based vaccines.
- Cold-chain infrastructure expansion:Ultra-low temperature storage networks at minus sixty to minus eighty degrees Celsius are extending reach into previously inaccessible rural health facilities.
Market Restraints
- Ultra-cold distribution requirements:Stabilization chemistries for mRNA and viral-vectored products impose capital-intensive logistics that limit supplier participation to well-capitalized developers.
- Filovirus strain divergence:Glycoprotein evolution in reservoir bat populations reduces cross-protection efficacy of single-strain vaccines, forcing multivalent formulation complexity.
- EMA centralized authorization:Marketing authorization holder requirements create procedural friction for products developed under the FDA's Animal Rule without European clinical data.
Strategic Opportunities
- Sudan ebolavirus emergence:Uganda's 2022 outbreak revealed coverage gaps in existing countermeasure portfolios, opening development lanes for broad-spectrum filovirus vaccines.
- Ad26.MVA heterologous prime-boost:Johnson & Johnson's two-dose regimen offers durability advantages that could displace single-shot approaches in pre-exposure prophylaxis programs.
- Government stockpile tenders:BARDA and equivalent agencies in France, Germany, and Japan are issuing multi-year procurement contracts with guaranteed minimum volumes.
Industry Challenges
- Biosafety Level 4 manufacturing capacity:Live filovirus handling requirements restrict production to a handful of global facilities, creating single-point-of-failure risks during surge demand.
- Human challenge trial ethics:The inability to conduct traditional efficacy studies complicates health-economic modeling for payer reimbursement negotiations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ebola Drug and Vaccine Market |
| Market Size in 2026 | $385.5 Million |
| Market Size in 2035 | $816.75 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vaccines, Therapeutics, Monoclonal Antibodies, Antivirals End User: Hospitals, Research Institutes, Government Agencies, NGOs Technology: Live Attenuated, Viral Vector, Protein Subunit, mRNA Distribution Channel: Online Pharmacies, Direct Sales, Government Procurement, Wholesale |
| Companies Covered | Merck & Co., Inc., Johnson & Johnson, GSK plc, Mapp Biopharmaceutical, BioCryst Pharmaceuticals, NewLink Genetics, AIM ImmunoTech Inc., Regeneron, Gilead Sciences, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ebola Drug and Vaccine Market Shifts & Advancements
Platform technology maturation is bifurcating the competitive landscape between rapid-response mRNA developers and established viral vector incumbents with licensed products.
Lipid nanoparticle-encapsulated mRNA encoding ebolavirus glycoproteins is rendering obsolete the twelve-to-eighteen-month strain adaptation timelines required for recombinant vesicular stomatitis virus platforms. BARDA and the Coalition for Epidemic Preparedness Innovations are funding these programs for pandemic preparedness stockpiles. The structural consequence is a shift toward multivalent filovirus coverage that compresses outbreak response initiation from months to weeks.
The FDA's Animal Rule pathway for lethal-disease therapeutics permits licensure based on animal efficacy when human trials are unethical, fundamentally altering clinical development economics for Ebola countermeasures. Developers can now pursue approval without field efficacy studies during inter-epidemic periods. Post-exposure monoclonal antibody developers are responding by prioritizing non-human primate challenge data packages over traditional Phase III designs.
Stockpile contracting is consolidating procurement authority under national strategic reserves rather than fragmented hospital or ministry purchasing. The U.S. Strategic National Stockpile and equivalent French and German federal reserves now specify performance-based shelf-life requirements that favor thermostable formulations. This behavioral shift is most visible in African outbreak-prone regions where government-to-government bilateral agreements are displacing fragmented NGO procurement channels.
Ebola Drug and Vaccine Market Segmentation
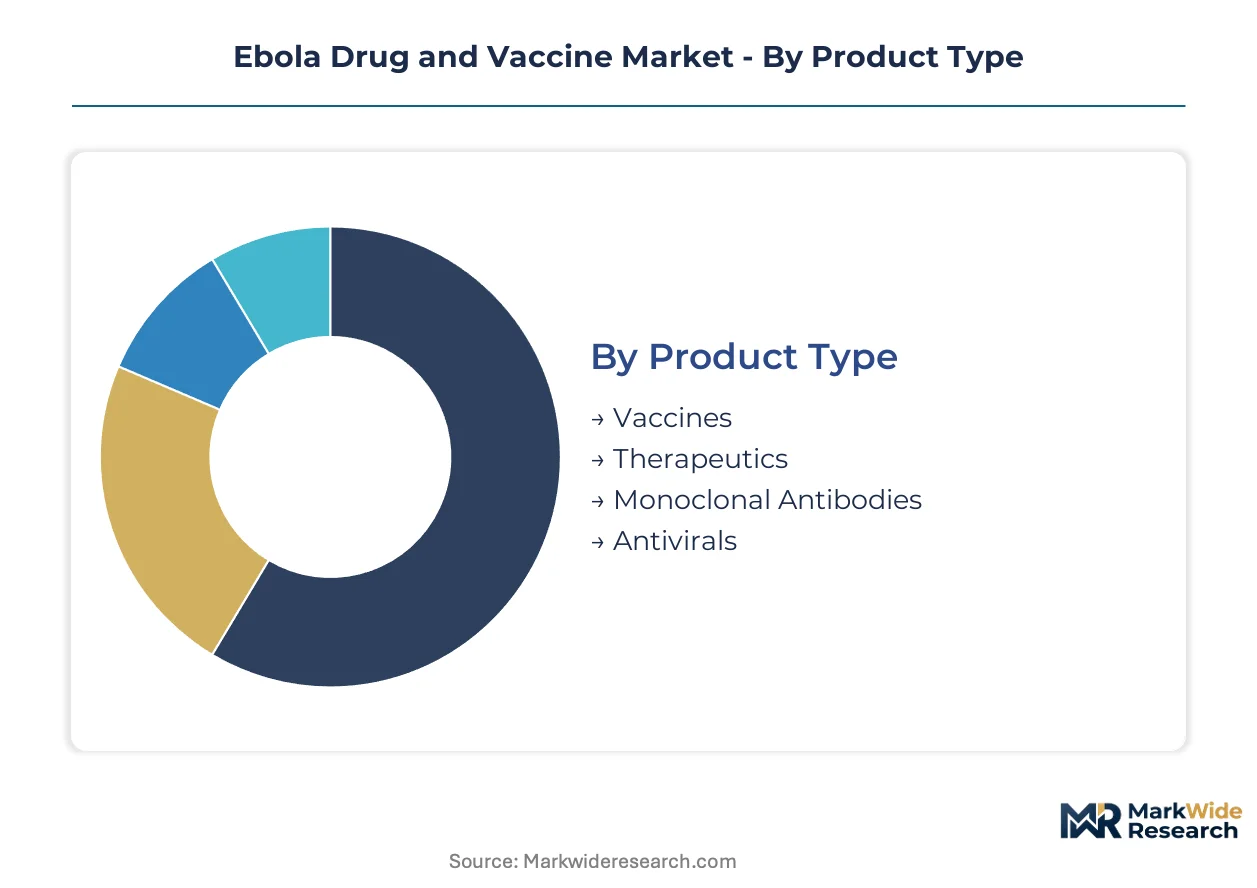
Ebola countermeasures fragment across four critical dimensions that determine procurement cycles, regulatory pathways, and cold-chain logistics. Product type and technology platform dictate development timelines spanning months to years, while end-user concentration shapes tender structures and distribution density.
Product Type:
Vaccines rotate through stockpile renewal cycles faster than therapeutics due to strain-matching pressures and shelf-life constraints, while monoclonal antibodies turn over most rapidly during active outbreak response.
- Vaccines:Recombinant viral-vectored and mRNA formulations dominate pre-exposure prophylaxis procurement by the U.S. Strategic National Stockpile and African national reserves. Demand concentrates in outbreak-prone provinces of the Democratic Republic of Congo where ring-vaccination protocols require rapid-deployment single-dose products.
- Monoclonal Antibodies:Regeneron's triple-antibody cocktail and similar glycoprotein-targeting biologics command premium pricing in post-exposure therapeutic settings. Procurement surges through emergency use authorizations during active epidemics in Uganda and the Democratic Republic of Congo.
- Therapeutics:Small-molecule antiviral candidates remain in development pipelines with limited licensed availability, constrained by the FDA's Animal Rule evidentiary requirements.
- Antivirals:Oral and intravenous small-molecule inhibitors target viral RNA polymerase function, though clinical validation lags behind antibody-based approaches.
Vaccines anchor the volume base while monoclonal antibodies gain share at the steepest rate during outbreak periods.
End User:
Cost tiers separate emergency-response procurement from research and development funding, with government stockpiles absorbing the highest unit volumes at contracted prices.
- Government Agencies:National strategic reserves in France, Germany, Japan, and the United States issue multi-year tenders with guaranteed minimum volumes and performance-based shelf-life specifications. BARDA and equivalent agencies channel funding through advanced purchase commitments.
- Hospitals:Ebola treatment units in the Democratic Republic of Congo and Uganda require immediate-access monoclonal antibody inventories with minus-eighty-degree Celsius storage infrastructure. Procurement flows through ministry of health centralized purchasing rather than institutional buying.
- Research Institutes:BSL-4 facilities in the United States, United Kingdom, and Germany consume reference materials and challenge stocks for non-human primate efficacy studies under the FDA's Animal Rule pathway.
- NGOs:Médecins Sans Frontières and similar organizations coordinate outbreak response logistics but increasingly defer procurement authority to bilateral government agreements.
Government agencies anchor the volume base while hospitals gain share at the steepest rate as treatment unit networks expand.
Technology:
Platform maturity stratifies manufacturing complexity and regulatory familiarity, with established viral vectors offering shortest approval paths and mRNA requiring novel cold-chain investments.
- Viral Vector:Recombinant vesicular stomatitis virus and adenovirus 26 platforms deliver licensed products with demonstrated efficacy in the Democratic Republic of Congo. Merck's Ervebo and Johnson & Johnson's Zabdeno/Mvabea regimen anchor this segment.
- mRNA:Lipid nanoparticle-encapsulated nucleoside-modified mRNA enables multivalent filovirus coverage with six-to-eight-week strain adaptation timelines. BARDA and CEPI funding accelerates candidates toward stockpile qualification.
- Live Attenuated:Traditional attenuation approaches face biosafety manufacturing constraints and limited pipeline activity due to BSL-4 production requirements.
- Protein Subunit:Recombinant glycoprotein formulations offer thermostability advantages but require adjuvant optimization and have not advanced to licensed status.
Viral vector platforms anchor the volume base while mRNA gains share at the steepest rate as developers pursue pandemic preparedness contracts.
Distribution Channel:
Customer type determines contract structure, with direct government tenders offering volume certainty and wholesale channels serving fragmented emergency response.
- Government Procurement:Federal strategic reserves specify ultra-cold chain compliance and extended shelf-life performance in multi-year supply agreements. The U.S. SNS and French national stockpile issue consolidated tenders displacing fragmented purchasing.
- Direct Sales:Manufacturers negotiate bilateral outbreak response contracts with ministries of health in the Democratic Republic of Congo, Rwanda, and Uganda, bypassing intermediary distributors for speed.
- Wholesale:Regional distributors serve African national immunization programs with established cold-chain infrastructure, though volumes remain secondary to direct government channels.
- Online Pharmacies:Negligible current penetration due to controlled-substance status, cold-chain requirements, and emergency-use authorization restrictions.
Government procurement anchors the volume base while direct sales gain share at the steepest rate as bilateral agreements proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Belgium exports Ebola vaccine stockpiles to the Democratic Republic of Congo through bilateral humanitarian agreements, establishing the primary trade corridor for outbreak response procurement in Central Africa.
United States
BARDA maintains the world's largest filovirus countermeasure reserve through multi-year procurement contracts with thermostable formulation requirements. The FDA's Animal Rule pathway accelerates licensure for products lacking human efficacy data. Maryland-based manufacturing clusters near Fort Detrick anchor BSL-4 production capacity for monoclonal antibody cocktails.
Germany
The Paul Ehrlich Institute coordinates EU-wide stockpile standardization for viral-vectored vaccines requiring minus-eighty-degree Celsius distribution chains. German federal reserves specify performance-based shelf-life extensions in tender documentation. Marburg and Hamburg harbor specialized cold-chain logistics providers serving African outbreak zones.
Democratic Republic of Congo
North Kivu and Ituri provinces sustain continuous demand for ring-vaccination deployment through WHO-coordinated emergency response frameworks. The national pharmaceutical regulator fast-tracks emergency use authorizations during active Zaire ebolavirus circulation. Kinshasa-based procurement authorities centralize purchasing authority previously fragmented across provincial health ministries.
Uganda
The 2022 Sudan ebolavirus outbreak exposed coverage gaps in existing vaccine portfolios, triggering accelerated development partnerships. The national drug authority streamlined import pathways for investigational monoclonal antibodies under compassionate use protocols. Kampala's infectious disease treatment units serve as regional referral hubs for neighboring Great Lakes nations.
United Kingdom
UK Research and Innovation channels pandemic preparedness funding toward mRNA platform developers pursuing multivalent filovirus coverage. The Medicines and Healthcare products Regulatory Agency aligns post-Brexit pathways with FDA Animal Rule standards for lethal-disease therapeutics. Oxfordshire research clusters concentrate non-human primate efficacy studies required for stockpile qualification.
Ebola Drug and Vaccine Market Competitive Landscape
Channel-controlling players compete with product-specialist players across differentiated regulatory pathways and cold-chain capabilities. The market structure consolidates around three tiers: established viral vector incumbents with licensed products, mRNA platform developers pursuing stockpile contracts, and monoclonal antibody specialists serving therapeutic deployment. Strategic archetypes include government-contracted stockpile suppliers, rapid-response platform innovators, and post-exposure therapeutic developers. Capacity expansion and strategic partnerships dominate competitive moves as developers secure BSL-4 manufacturing access.
Within the viral vector tier, Merck & Co., Inc. and Johnson & Johnson exemplify established incumbents with differentiated regimen approaches. Regeneron occupies a position among therapeutic specialists targeting glycoprotein epitopes for post-exposure intervention. These three anchors represent divergent competitive strategies: single-dose rapid deployment, heterologous prime-boost durability, and monoclonal antibody cocktail premium positioning.
| Leading Market Players |
|---|
| Merck & Co., Inc. |
| Johnson & Johnson |
| GSK plc |
| Mapp Biopharmaceutical |
| BioCryst Pharmaceuticals |
| NewLink Genetics |
| AIM ImmunoTech Inc. |
| Regeneron |
| Gilead Sciences |
| Others |
Supply & Pricing Matrix
BSL-4 manufacturing concentration in Maryland and Hamburg determines both the premium commanded by thermostable formulations and the three-tier supply chain structure separating government stockpiles from emergency response channels.
Pricing Analysis
Prior-generation viral-vectored vaccines trade at contracted government rates while next-generation mRNA platforms capture development premiums through BARDA pandemic preparedness awards. Pricing stratifies across premium monoclonal antibody cocktails, standard vector-based vaccines, and economy-tier research materials. Cost compression in standard vaccines intensifies as strain-matching pressures accelerate stockpile renewal cycles. Government procurement agencies exhibit lowest price sensitivity, while NGO emergency responders face acute budget constraints during outbreak surges.
Supply Chain Analysis
Lonza and Emergent BioSolutions hold captive BSL-4 manufacturing capacity for live filovirus handling, with fill-finish operations concentrated in Switzerland and the United States. Supply draws from German lipid nanoparticle producers, Belgian viral vector facilities, and American fill-finish networks. Single-source vulnerability pervades the minus-eighty-degree Celsius cold-chain segment where specialized logistics providers serve African outbreak zones. Distribution runs through government strategic reserves rather than wholesale pharmaceutical channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is consolidating under national strategic stockpiles, with fragmented hospital procurement giving way to centralized federal tenders specifying performance-based shelf-life requirements.
For Market Incumbents: Build regulatory moats through FDA Animal Rule master file accumulation and EMA centralized authorization alignment. Merck and Johnson & Johnson should deepen BSL-4 manufacturing partnerships to lock out mRNA entrants lacking biosafety infrastructure. Threat substitution from rapid-response nucleic acid platforms demands thermostable formulation investment as the defensive priority. For New Entrants and Emerging Players: Multivalent Sudan ebolavirus coverage represents the most penetrable entry point, with Uganda's 2022 outbreak exposing portfolio gaps in incumbent offerings. BARDA stockpile qualification pathways offer non-dilutive funding access for platform innovators. Go-to-market leverage rests on bilateral government agreements with Kinshasa and Kampala health authorities rather than multilateral NGO channels. For Investors and Strategic Acquirers: FDA breakthrough therapy designation for lethal-disease therapeutics reshapes the acquisition landscape toward animal-efficacy-stage assets. Five-to-ten-year viability favors developers with dual-use pandemic preparedness platforms spanning filovirus and coronavirus applications. Watch WHO prequalification timelines as the inflection signal determining Gavi and UNICEF eligibility.| Strategic Initiative | Industry Significance |
|---|---|
| BSL-4 Manufacturing Partnership | Captive biosafety capacity at Fort Detrick and Hamburg secures surge production rights for outbreak response. |
| Thermostable Formulation Development | Extended shelf-life specifications in French and German tenders favor lyophilized over frozen presentation. |
| Multivalent Filovirus Expansion | Sudan ebolavirus coverage opens procurement channels previously closed to Zaire-specific products. |
| WHO Prequalification Submission | Gavi and UNICEF eligibility hinges on this designation for African national immunization programs. |
| Direct Government Contracting | Bilateral agreements with DRC and Uganda ministries displace fragmented NGO procurement channels. |
Research Methodology
Cross-validation between regulatory filing analysis and procurement database triangulation anchors the qualitative findings. Primary interviews with vaccine development executives, regulatory affairs leads at the Paul Ehrlich Institute, hospital procurement managers in Kinshasa, and BARDA program officers combined with secondary validation against FDA Animal Rule guidance documents, EMA centralized authorization records, WHO prequalification listings, and Gavi tender archives. Bottom-up stockpile volume estimates and top-down epidemiological demand modeling were reconciled.
Calibration against historical procurement cycles across the analysis window employed treatment line stratification, technology platform segmentation, regional regulatory cluster differentiation, and cold-chain capability tiers. CAGRs were derived from epidemiological surveillance trends, government budget appropriation patterns, and platform substitution elasticity. Forecast inputs incorporated filovirus reservoir surveillance data and bilateral stockpile commitment announcements.
Macroeconomic conditions sit as an overlay; deviation in African national health budgets and pandemic preparedness appropriations would shift the trajectory. Forecasts reflect assumptions about strain circulation persistence and regulatory pathway stability. Quarterly review of WHO Disease Outbreak News and national strategic reserve tender releases is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Asia-Pacific Contraceptive Drugs and Devices Market
Pharmaceuticals
Peptide Therapeutics Market
Pharmaceuticals
Inhaled Nitric Oxide Market
Pharmaceuticals
Middle-East and Africa Alpha-Glucosidase Inhibitors Market
Pharmaceuticals
China Plasma Protein Therapeutics Market
Pharmaceuticals
Esophageal Achalasia Drug Market
Pharmaceuticals
Nicorandil Market
Pharmaceuticals
Sporanox Market
Pharmaceuticals
Leflunomide Market
Pharmaceuticals
Migraine Drugs Market
Pharmaceuticals
Global Chemotherapy-Induced Nausea and Vomiting (CINV) Market
Pharmaceuticals
Global Basal Insulin Market
Pharmaceuticals
Latin America Biguanide Market
Pharmaceuticals
Global Aromatase Inhibitors Drug Market
Pharmaceuticals
Xanthine Oxidase Inhibitors Market
Pharmaceuticals
Drug Delivery Market