
 Europe Parenteral Lipid Emulsion Market | 2026-2036
Europe Parenteral Lipid Emulsion Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Parenteral Lipid Emulsion Market Insights
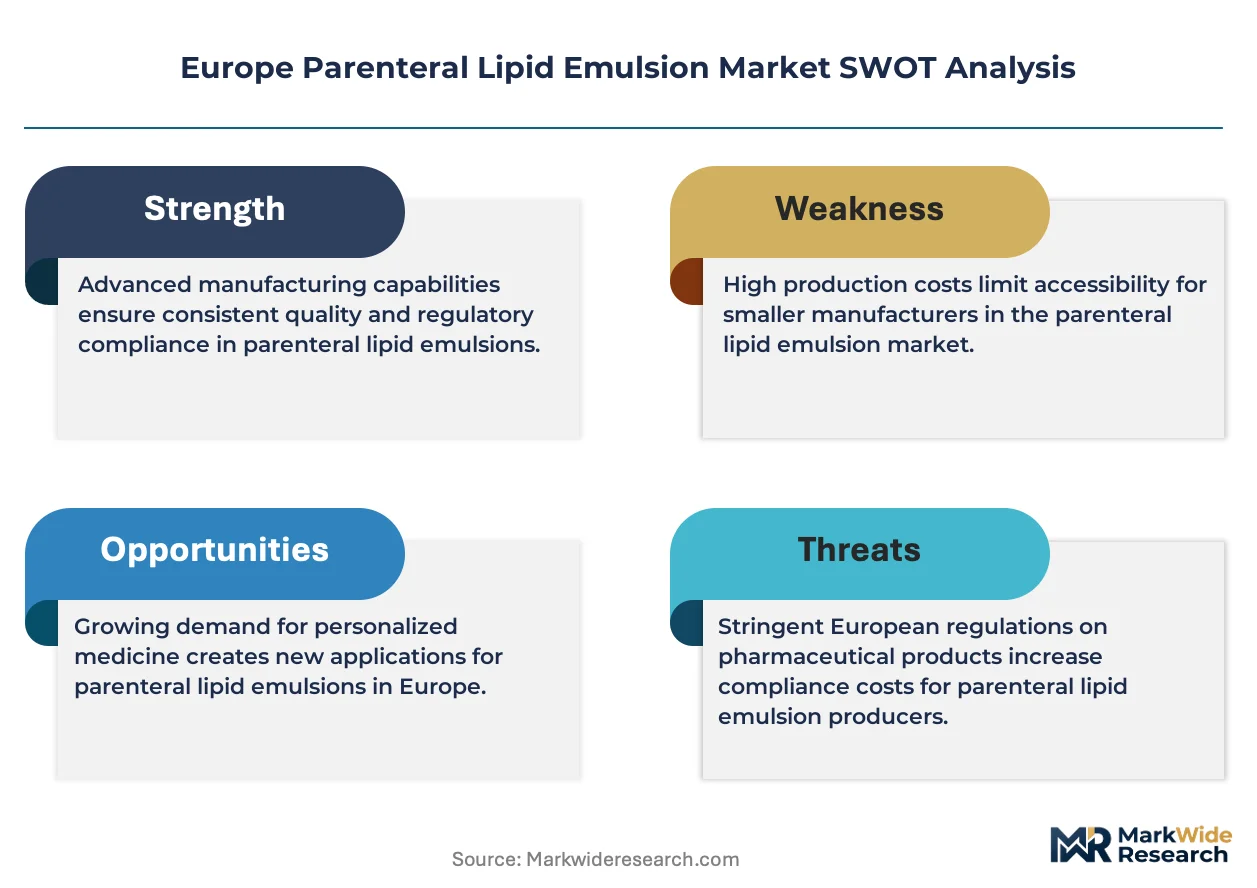
The gap between premium fish-oil formulations and commodity soybean-based emulsions is expanding as clinical evidence for omega-3 enriched therapies hardens purchasing criteria across European hospitals. Baxter leverages its integrated plasma and nutrition portfolio to sustain supply chain control from lipid sourcing to sterile filling. Fresenius Kabi AG competes through geographic dominance in German-speaking markets, where it anchors hospital formulary relationships. B Braun SE differentiates via technology leadership in dual-chamber delivery systems that reduce compounding error rates.
Europe parenteral lipid emulsions are sterile oil-in-water dispersions, typically 10-20% lipid concentration, manufactured by high-pressure homogenization under nitrogen to prevent peroxidation of polyunsaturated fatty acids; they deliver essential fatty acids and caloric density to patients unable to absorb enteral nutrition. Soybean oil emulsions occupy the mature volume base but face margin compression from olive oil and medium-chain triglyceride blends that command premium positioning in hepatic and pediatric populations. Intravenous delivery dominates the channel structure, though subcutaneous administration in homecare settings captures the fastest-growing application trajectory as reimbursement frameworks expand beyond acute settings.
EMA pharmacovigilance requirements and the EU MDR impose escalating documentation burdens on lipid emulsion manufacturers, particularly for novel formulations seeking centralized marketing authorization. The F-Gas Regulation indirectly shapes manufacturing economics by restricting fluorinated greenhouse gases used in certain sterilization and cold-chain processes. REACH compliance for residual solvents and emulsifier purity standards further narrows the supplier base for pharmaceutical-grade lipids. Stakeholders must monitor how the EU Green Deal's pharmaceutical sustainability criteria will reshape raw material sourcing and packaging specifications for parenteral nutrition products.
Market Dynamics
The EU Medical Device Regulation (MDR) and EMA pharmacovigilance mandates are compressing formulation approval timelines while elevating documentation burdens, forcing manufacturers to restructure quality management systems and sterilization validation protocols.
Growth Catalysts
- Homecare reimbursement expansion:Post-acute parenteral nutrition coverage frameworks in Germany and France now extend beyond hospital walls, enabling subcutaneous lipid emulsion administration in domestic settings.
- REACH emulsifier purity standards:Stricter residual solvent thresholds are filtering out commodity-grade suppliers, concentrating volume among pharmaceutical-certified lipid processors with validated supply chains.
- Fish-oil clinical evidence hardening:Omega-3 enriched formulations demonstrate superior inflammatory markers in hepatic and pediatric populations, reshaping hospital formulary purchasing criteria across Nordic and Benelux markets.
Market Restraints
- Pharmaceutical-grade lipid supply concentration:European sources for epoxidized soybean oil and refined fish oil derivatives cluster among Netherlands and German processors, creating input vulnerability during harvest volatility or marine ecosystem disruptions.
- F-Gas Regulation sterilization constraints:Restricted fluorinated greenhouse gas availability elevates cold-chain and terminal sterilization costs for emulsion manufacturers dependent on specific aseptic processing technologies.
- Enteral nutrition substitution:Improved nasogastric feeding protocols and intestinal rehabilitation programs reduce dependency on intravenous lipid delivery in certain gastrointestinal disorder populations.
Strategic Opportunities
- Poland and Romania hospital infrastructure:Underpenetrated clinical nutrition protocols in Eastern European tertiary centers present volume expansion potential as healthcare spending converges toward Western European benchmarks.
- Dual-chamber delivery convergence:Integration of lipid emulsion with amino acid and glucose compartments in single-container systems reduces compounding error rates and pharmacy labor intensity.
- EU Green Deal pharmaceutical sustainability criteria:Emerging packaging specifications and raw material traceability mandates favor early movers with bio-based emulsifier sourcing and recyclable container portfolios.
Industry Challenges
- High-pressure homogenization technician scarcity:Specialized expertise in nitrogen-inerted emulsion manufacturing and particle size distribution control remains concentrated among aging workforce cohorts in Northern Italy and Southern Germany.
- MDR technical documentation timelines:Centralized marketing authorization submissions for novel lipid blends require 18-24 month validation cycles, compressing product pipeline velocity against competitive pressure.
- Legacy ERP integration with Eudamed:Hospital and manufacturer traceability systems face interoperability friction with the EMA's device registration database, delaying adverse event reporting automation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Parenteral Lipid Emulsion Market |
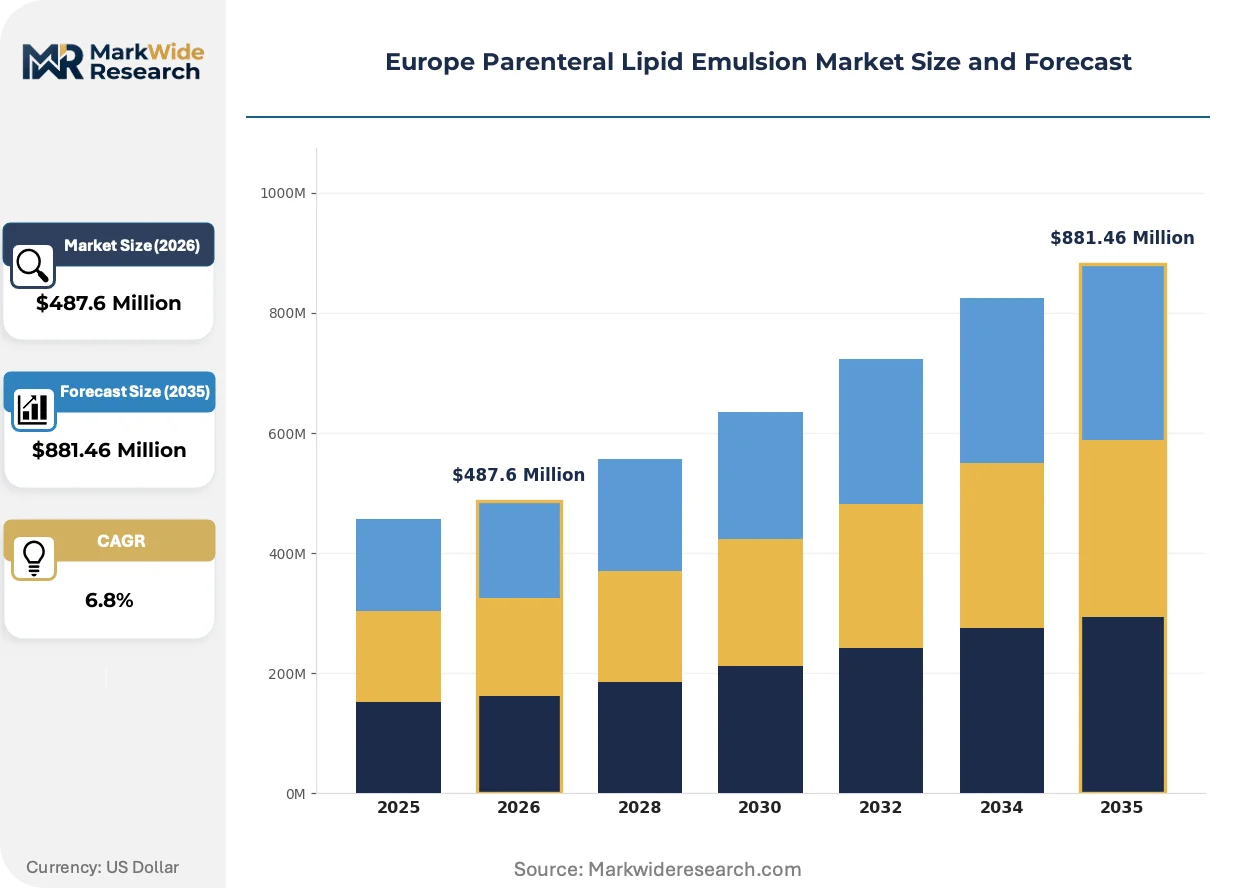
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Soybean Oil, Olive Oil, Medium-Chain Triglycerides, Fish Oil Application: Parenteral Nutrition, Cancer Therapy, Postoperative Care, Gastroenterology End User: Hospitals, Clinics, Homecare Settings, Specialty Pharmacies Delivery Mode: Intravenous, Subcutaneous, Intraosseous, Epidural |
| Companies Covered | Baxter, Braun Melsungen AG, Fresenius SE & Co. KGaA, Grifols S.A., Fresenius Kabi AG, B Braun SE, ICU Medical Inc, Otsuka Pharmaceuticals Co Ltd, Pfizer Inc, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Parenteral Lipid Emulsion Market Trends and Innovations
Formulation science and delivery technology are converging to reduce clinical risk while expanding administration settings beyond traditional inpatient boundaries. These developments reshape competitive positioning through technical differentiation rather than commodity volume.
Multi-compartment bag technology is consolidating parenteral nutrition preparation workflows by pre-mixing lipid, amino acid, and glucose phases in nitrogen-flushed dual or triple chambers. German university hospitals and French cancer centers adopt these systems fastest, reducing pharmacy compounding labor by half. The technology is consolidating market share among manufacturers with integrated blow-fill-seal capabilities and sterile welding expertise.
EMA's strengthened post-market surveillance requirements for parenteral nutrition products now mandate real-world evidence collection on long-chain fatty acid oxidation complications. Manufacturers must maintain pharmacovigilance databases tracking hepatic steatosis and essential fatty acid deficiency events across diverse patient populations. Novel formulation entrants face extended conditional approval pathways, advantaging incumbents with established safety dossiers in centralized European markets.
Hospital procurement committees increasingly unbundle parenteral nutrition contracts from broad-spectrum infusion device agreements, creating direct purchasing relationships with lipid emulsion specialists. French public hospital groups and British NHS trusts lead this fragmentation, negotiating formulation-specific tenders based on clinical outcome metrics rather than bundled supply discounts. The shift concentrates volume among suppliers with dedicated clinical nutrition sales forces and hospital pharmacist education programs.
Europe Parenteral Lipid Emulsion Market Segmentation
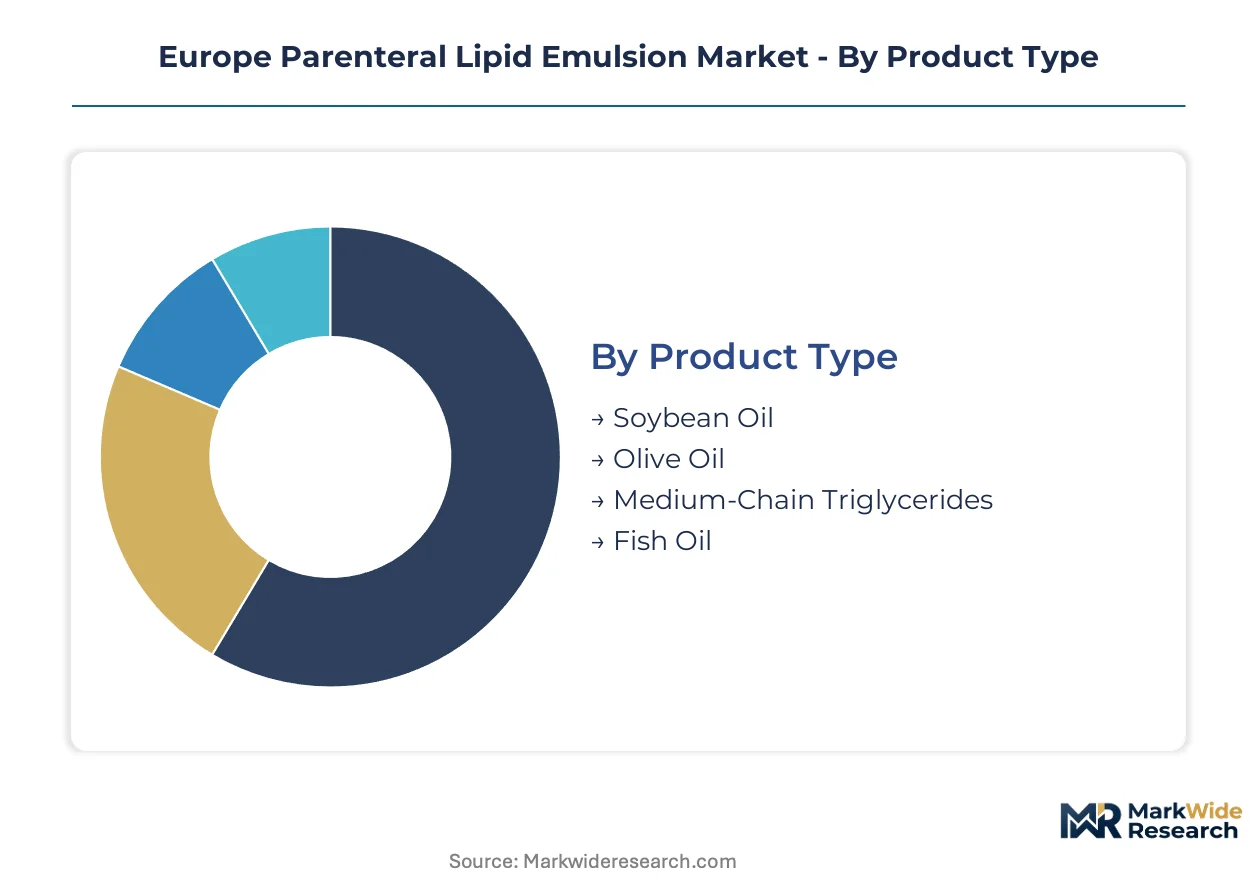
Segmentation in the Europe parenteral lipid emulsion market reveals how formulation chemistry, clinical application, and care setting intersect to determine procurement priorities. Manufacturers configure production assets and regulatory dossiers around these divisions, with capital allocation favoring segments that command premium positioning or volume concentration.
Product Type:
Capital intensity varies sharply across lipid sources, with omega-3 refining and nitrogen-inerted processing demanding specialized infrastructure that soybean oil emulsion lines cannot accommodate without substantial retrofit.
- Soybean Oil:Long-chain triglyceride emulsions with 50-60% linoleic acid content remain the volume foundation across European hospital formularies. German and French purchasing consortia negotiate these formulations most aggressively, squeezing margins as olive oil and fish oil alternatives capture premium indications.
- Fish Oil:Omega-3 enriched emulsions containing EPA and DHA require cold-chain marine lipid sourcing and peroxidation-resistant manufacturing protocols. Nordic hospital systems and Dutch pediatric centers drive adoption based on anti-inflammatory outcome data in hepatic and immunocompromised populations.
- Olive Oil:Monounsaturated fatty acid dominance reduces oxidative stress markers in long-term parenteral nutrition patients.
- Medium-Chain Triglycerides:Rapid hepatic oxidation without carnitine dependency suits cholestatic and critically ill patient cohorts.
Soybean oil absorbs the bulk of installed capacity; fish oil is expanding most quickly.
Application:
Clinical indication determines reimbursement tier and formulary access, with oncology and perioperative protocols commanding dedicated pharmacy budgets that gastroenterology services cannot match.
- Parenteral Nutrition:Complete intravenous feeding regimens for intestinal failure patients require lipid emulsion as the primary caloric substrate. British NHS trusts and French public hospital groups standardize these protocols through centralized nutrition support teams.
- Cancer Therapy:Chemotherapy-induced mucositis and cachexia management drives demand for anti-inflammatory lipid formulations. Belgian and Swiss oncology centers lead adoption of fish oil-enriched regimens based on neutropenia reduction studies.
- Postoperative Care:Short-term nutritional support following major abdominal surgery favors cost-efficient soybean oil emulsions.
- Gastroenterology:Inflammatory bowel disease and short bowel syndrome applications require individualized lipid tailoring.
Parenteral nutrition commands the largest share of clinical pharmacy spend; cancer therapy is climbing the fastest as immuno-oncology protocols expand.
End User:
Channel structure shapes packaging specifications and cold-chain requirements, with homecare reimbursement frameworks now permitting configurations that hospital-only regulations previously prohibited.
- Hospitals:Tertiary and university medical centers in Germany, France, and the United Kingdom dominate volume through centralized compounding pharmacies. These institutions negotiate multi-year supply agreements that lock in formulation standards across clinical departments.
- Homecare Settings:Subcutaneous administration of lipid emulsions in domestic environments requires simplified infusion pump compatibility and patient-training support. German statutory health insurance expansions and French post-acute care reforms accelerate this channel's development.
- Clinics:Outpatient infusion centers handle stabilized patients transitioning from acute care.
- Specialty Pharmacies:Centralized compounding for rare disease populations demands batch traceability exceeding standard hospital requirements.
Hospitals retain the dominant procurement position; homecare settings are gaining share fastest as reimbursement frameworks mature.
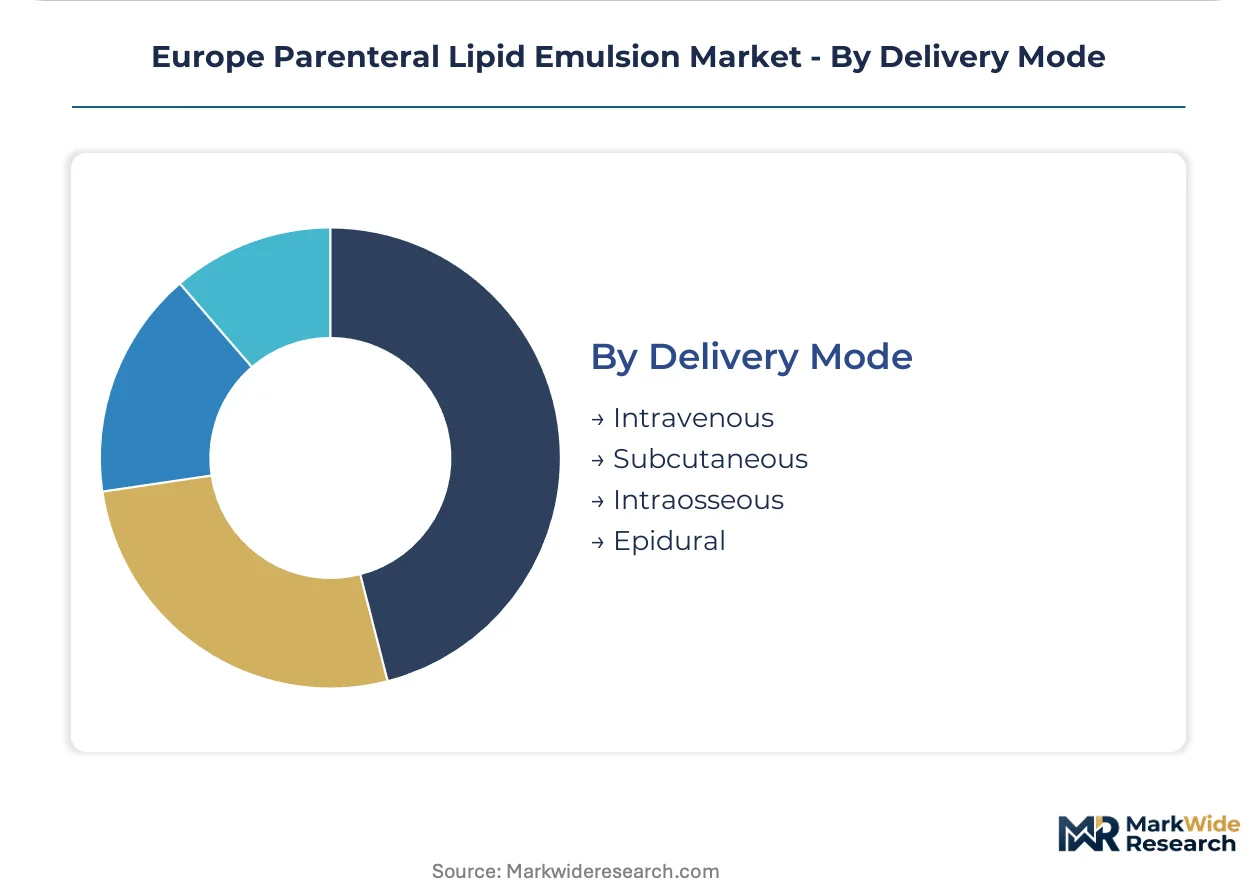
Delivery Mode:
Route of administration determines container design, particle size distribution tolerances, and compatibility with infusion pump technologies, with peripheral venous access limitations driving subcutaneous innovation.
- Intravenous:Central and peripheral venous delivery remains the standard for complete parenteral nutrition, requiring 0.22-micron filtration and emulsion stability across 24-hour infusion cycles. German university hospitals validate these protocols through pharmacy and therapeutics committees.
- Subcutaneous:Hypodermoclysis-compatible lipid emulsions enable home-based administration for stable patients with functional gastrointestinal tracts. French and Dutch reimbursement authorities now cover these alternatives for postoperative and palliative populations.
- Intraosseous:Emergency vascular access in pediatric and trauma settings demands immediate availability of pre-mixed emulsion formulations.
- Epidural:Regional anesthesia applications utilize lipid emulsion as a carrier for lipophilic analgesic agents.
Intravenous delivery maintains capacity dominance; subcutaneous administration shows the steepest expansion trajectory as homecare infrastructure develops.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Main industrial corridor anchors European parenteral lipid emulsion manufacturing, with Frankfurt's pharmaceutical logistics hub coordinating nitrogen-inerted emulsion distribution across the continent's hospital networks.
Germany
German university hospitals in Heidelberg and Munich drive fish oil formulation adoption through centralized nutrition support teams. The Federal Institute for Drugs and Medical Devices enforces MDR compliance timelines that compress novel product approvals. Baden-Württemberg's sterile manufacturing corridor hosts dual-chamber bag production facilities serving German-speaking markets.
France
French public hospital groups in Paris and Lyon unbundle parenteral nutrition contracts from infusion device agreements, creating direct lipid emulsion procurement channels. ANSM pharmacovigilance mandates require real-world evidence collection on hepatic steatosis complications. The Île-de-France region concentrates multi-compartment bag adoption among cancer centers seeking pharmacy labor reduction.
United Kingdom
British NHS trusts standardize parenteral nutrition protocols through centralized nutrition support teams in London and Manchester. The MHRA's post-Brexit regulatory divergence creates parallel submission requirements for novel formulations. The Oxford-Cambridge arc anchors clinical research on omega-3 enriched therapies in immunocompromised populations.
Netherlands
Dutch pediatric centers in Rotterdam and Utrecht lead fish oil emulsion adoption based on anti-inflammatory outcome data in hepatic populations. REACH emulsifier purity standards filter commodity-grade suppliers, concentrating volume among Rotterdam's pharmaceutical-certified lipid processors. The port's marine lipid refining infrastructure supports cold-chain omega-3 sourcing.
Italy
Northern Italian manufacturers in Milan and Bologna face technician scarcity in high-pressure homogenization expertise for nitrogen-inerted emulsion production. The Italian Medicines Agency's MDR technical documentation requirements extend validation cycles for novel lipid blends. Lombardy's sterile filling facilities supply Mediterranean hospital networks with soybean oil volume formulations.
Europe Parenteral Lipid Emulsion Market Competitive Landscape
Premium-margin players sit above commodity-margin players across formulation complexity, with fish oil and olive oil emulsions commanding pricing power that soybean oil volumes cannot match. The vendor base concentrates among integrated plasma processors and dedicated clinical nutrition specialists. Three archetypes dominate: diversified healthcare conglomerates with sterile filling capabilities, mid-cap nutrition pure-plays with formulary anchoring expertise, and device-integrated players with dual-chamber delivery technology. Competitive moves center on backward integration into pharmaceutical-grade lipid sourcing and geographic expansion into underpenetrated Eastern European hospital markets.
Among diversified healthcare conglomerates, Baxter and Fresenius Kabi AG exemplify archetypes built on plasma processing heritage and hospital supply chain integration. B Braun SE occupies a position within the device-integrated tier, representing manufacturers that combine emulsion formulation with infusion technology. These three entities anchor the competitive structure through distinct capability configurations rather than overlapping strategic positioning.
| Leading Market Players |
|---|
| Baxter |
| Braun Melsungen AG |
| Fresenius SE & Co. KGaA |
| Grifols S.A. |
| Fresenius Kabi AG |
| B Braun SE |
| ICU Medical Inc |
| Otsuka Pharmaceuticals Co Ltd |
| Pfizer Inc |
| Others |
Pricing and Supply Chain Analysis
High-pressure homogenization under nitrogen-inerted conditions simultaneously elevates manufacturing cost structures and concentrates production capacity among German and Northern Italian processors with validated sterile filling capabilities. This technical barrier creates pricing power asymmetry between pharmaceutical-certified lipid emulsion manufacturers and commodity-grade suppliers filtered out by REACH emulsifier purity standards.
Pricing Analysis
Value-based pricing anchored to clinical outcome metrics reshapes hospital procurement negotiations across German university hospitals and French public hospital groups. Three-tier pricing structure across premium fish-oil formulations, mid-tier olive oil blends, and economy soybean oil volumes reflects certification grade and anti-inflammatory efficacy data. Pricing pressure stems from German purchasing consortia aggressive negotiation of soybean oil contracts. Oncology and perioperative segments demonstrate lowest price sensitivity; postoperative care segments face highest cost compression.
Supply Chain Analysis
Pharmaceutical-grade lipid sourcing certification gates concentrate European supply among Netherlands marine oil refiners and German epoxidized soybean oil processors. Raw material dependencies center on refined fish oil derivatives, epoxidized soybean oil, and pharmaceutical-grade egg phospholipids. Single-source vulnerability in Rotterdam's omega-3 cold-chain infrastructure creates harvest volatility exposure. Distribution runs through Frankfurt's pharmaceutical logistics hub coordinating nitrogen-flushed emulsion delivery to hospital networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Multi-compartment bag technology is displacing traditional pharmacy compounding workflows, creating asymmetric opportunity for manufacturers with integrated blow-fill-seal capabilities against legacy single-chamber suppliers.
For Market Incumbents: Hedge against enteral nutrition substitution by deepening backward integration into pharmaceutical-grade lipid sourcing and accelerating dual-chamber bag capacity in Baden-Württemberg. Prioritize MDR technical documentation investment to compress novel formulation approval timelines against emerging competitors.
For New Entrants and Emerging Players: Begin with underpenetrated Eastern European tertiary centers in Poland and Romania where clinical nutrition protocols lag Western European benchmarks. Target homecare reimbursement expansion with simplified subcutaneous delivery configurations and patient-training support services.
For Investors and Strategic Acquirers: Exit pathways concentrate in device-integrated clinical nutrition specialists with dual-chamber technology and established hospital formulary relationships. Long-term viability favors manufacturers with captive marine lipid sourcing and Eudamed-integrated traceability systems. Watch for EU Green Deal pharmaceutical sustainability criteria implementation as inflection trigger for bio-based emulsifier sourcing mandates.
| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Chamber Bag Capacity Expansion | Reduces pharmacy compounding labor by half in German university hospitals and French cancer centers. |
| Backward Integration into Marine Lipid Sourcing | Captures Rotterdam cold-chain infrastructure and secures omega-3 supply against harvest volatility. |
| MDR Technical Documentation Investment | Accelerates centralized marketing authorization timelines for novel lipid blends across EMA jurisdictions. |
| Homecare Reimbursement Strategy | Aligns product configurations with German statutory health insurance and French post-acute care reforms. |
| EU Green Deal Compliance Program | Positions early movers for emerging pharmaceutical sustainability criteria on packaging and raw material traceability. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with hospital pharmacy directors, clinical nutrition specialists, GPO contracts managers, and sterile manufacturing engineers. EMA pharmacovigilance databases, EU MDR technical documentation, REACH compliance filings, and hospital procurement records provided quantitative validation. Bottom-up volume estimates triangulated against top-down spending data from national health accounts.
Segment-level modeling applied treatment line stratification, lipid source chemistry, administration route, and regional regulatory cluster dimensions across the projection horizon. CAGRs derived from weighted average of historical volume trajectories and policy-driven reimbursement expansion scenarios. Forecast inputs incorporated homecare infrastructure development timelines and MDR implementation compliance curves.
Underlying measurement precision varies by segment; fish oil formulation adoption rates carry tighter precision than soybean oil volume projections given consolidated prescribing data. Forecasts reflect assumptions on reimbursement framework stability and marine lipid supply continuity. A model refresh is warranted upon material change in EU Green Deal pharmaceutical sustainability criteria implementation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Istradefylline API Market
Pharmaceuticals
Global Recombinant Vaccines Market
Pharmaceuticals
Europe Generic Drug Market
Pharmaceuticals
Europe Pharmaceutical Contract Manufacturing Market
Pharmaceuticals
Anti-Radiation Drugs Market
Pharmaceuticals
Anti-Viral Therapeutics Market
Pharmaceuticals
United States Pharmaceutical Logistics Market
Pharmaceuticals
Direct Oral Anticoagulants Market
Pharmaceuticals
Middle East and Africa Gastrointestinal Drugs Market
Pharmaceuticals
Global Interstitial Cystitis Drugs Market
Pharmaceuticals
Europe Insulin Drugs and Glucagon-Like Peptide 1 (GLP-1) Receptor Agonist Market
Pharmaceuticals
Over-The-Counter (OTC) Analgesics Market
Pharmaceuticals
Specialty Active Pharmaceutical Ingredients Market
Pharmaceuticals
Hyoscine Market
Pharmaceuticals
Hydroxycarbamide Market
Pharmaceuticals
Canada Specialty Pharmacy Market