
 Gram Positive Bacterial Infections Market | 2026-2036
Gram Positive Bacterial Infections Market Size, Share, and Industry Trends Forecast 2026-2036
Gram Positive Bacterial Infections Market Intelligence
Demand from specialized clinics and outpatient settings is rotating away from an exclusive focus on large-scale hospital procurement for treating common gram-positive infections. Pfizer leverages its extensive portfolio of established and novel antibiotics to serve both hospital and community channels. Merck & Co. sustains its market presence through a focus on treatments for severe, hospital-acquired infections like MRSA. In parallel, Novartis AG differentiates its strategy by investing in next-generation therapies targeting drug-resistant bacterial strains.
Gram-positive bacterial infections are illnesses caused by bacteria possessing a thick peptidoglycan cell wall, which results in their retaining the crystal violet stain in Gram staining tests. These pathogens are responsible for a wide spectrum of diseases, from mild skin infections to life-threatening conditions like pneumonia and endocarditis. Antibiotics constitute the primary product type for treatment, with development focused on overcoming resistance. Within indications, pneumonia and skin infections command the highest treatment volumes, while managing meningitis presents significant clinical challenges.
The regulatory environment is defined by agencies like the United States FDA, the European Medicines Agency (EMA), and China's NMPA. These bodies provide fast-track approval pathways and market exclusivity incentives to stimulate the development of new antibiotics against priority pathogens. Successfully navigating the varied reimbursement policies for new, higher-priced antimicrobials across different healthcare systems remains a critical hurdle for drug developers to overcome.
Market Dynamics
The central dynamic shaping the market is the escalating crisis of antimicrobial resistance, which creates a paradoxical environment. This force simultaneously drives urgent demand for novel therapies while undermining the traditional volume-based commercial models for antibiotic development and sales.
Growth Catalysts
- Regulatory Incentives:Push-and-pull incentives, including the FDA's Qualified Infectious Disease Product (QIDP) designation and the EMA's PRIME scheme, accelerate development timelines and grant extended market exclusivity for novel antibiotics targeting priority pathogens.
- High Disease Burden:A high incidence of community- and hospital-acquired infections in populous countries, particularly India, creates sustained, high-volume demand for a wide range of gram-positive antibacterial agents.
- Hospital-Acquired Infections:The rising prevalence of complex, resistant infections within hospital settings necessitates the use of advanced, premium-priced antibiotics, driving value growth in this specific end-user segment.
Market Restraints
- Economic Viability:The "antibiotic paradox" restrains investment, as the most effective new drugs are used sparingly to preserve efficacy, leading to low sales volumes and a poor return on R&D investment for developers.
- Clinical Trial Hurdles:Demonstrating superiority over existing, often generic, antibiotics in clinical trials is a significant barrier, increasing the complexity, cost, and failure rate of late-stage drug development programs.
- Scientific Discovery Limits:The intrinsic scientific difficulty of discovering new classes of antibiotics that can effectively bypass existing bacterial resistance mechanisms remains a fundamental and persistent restraint on pipeline innovation.
Strategic Opportunities
- Alternative Therapeutics:Development of non-traditional treatments such as bacteriophage therapy, lysins, and monoclonal antibodies presents an opportunity to address infections caused by multi-drug resistant organisms where conventional antibiotics fail.
- Diagnostic-Therapeutic Pairing:Integrating novel antibiotics with rapid, point-of-care diagnostic tests offers a pathway to justify premium pricing and ensure appropriate use, aligning with antimicrobial stewardship goals.
- Targeted Access Programs:Creating specialized programs for low- and middle-income countries in regions like Southeast Asia can open new markets by addressing affordability and improving local treatment guidelines.
Industry Challenges
- Reimbursement Complexity:Navigating disparate and often restrictive reimbursement policies for new, higher-priced antimicrobials across national healthcare systems in Europe and private payers in the U.S. is a major operational hurdle.
- Manufacturing Scale-Up:The technical challenges associated with scaling up production for novel biologicals or complex synthetic molecules while ensuring consistent quality and cost-efficiency can delay market entry.
- Stewardship Implementation:Effectively implementing antimicrobial stewardship programs in hospitals requires significant investment in training, surveillance technology, and personnel, creating a barrier to the optimal use of new drugs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gram Positive Bacterial Infections Market |
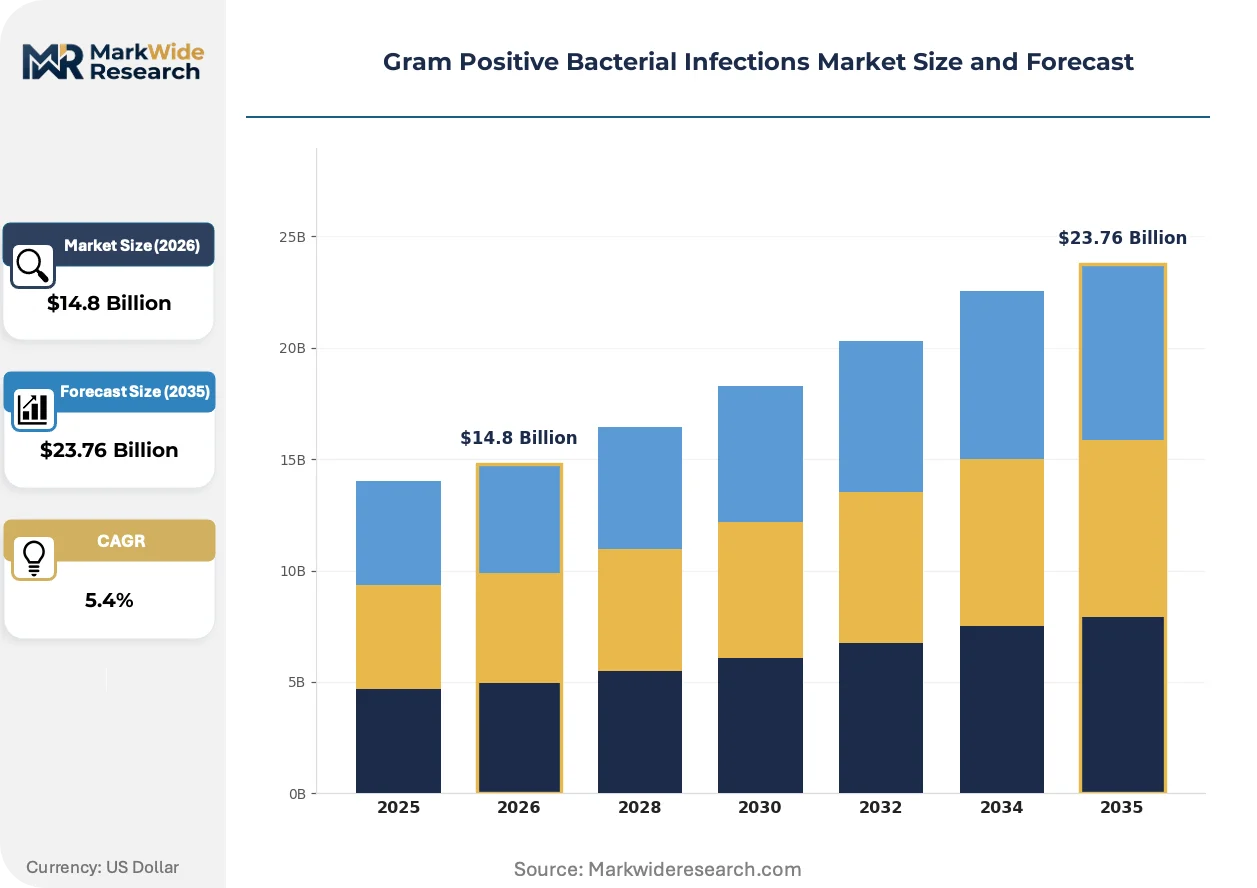
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $23.76 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antibiotics, Vaccines, Diagnostics, Antiseptics Indication: Pneumonia, Skin Infections, Endocarditis, Meningitis Delivery Mode: Oral, Intravenous, Inhalation, Topical End User: Hospitals, Clinics, Home Healthcare, Laboratories |
| Companies Covered | Pfizer, Merck & Co., GlaxoSmithKline, Novartis AG, Johnson & Johnson, Sanofi, Cipla, Sun Pharmaceutical, Bayer AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gram Positive Bacterial Infections Market Strategic Shifts & Innovations
Precision is becoming the guiding principle in treating gram-positive infections. The market is shifting from reliance on broad-spectrum empirical therapy toward a more targeted approach, driven by technological advancements in diagnostics and new economic models for drug reimbursement.
Point-of-care molecular diagnostics provide rapid bacterial identification and antimicrobial susceptibility results directly at the patient bedside. Hospital emergency departments and intensive care units are early adopters, seeking to reduce treatment delays. This technology is miniaturizing the diagnostic feedback loop, enabling clinicians to select the correct targeted antibiotic within hours instead of days.
New reimbursement frameworks are emerging to address the antibiotic market failure. The United Kingdom's subscription-style model, piloted by its National Health Service, delinks company revenue from the volume of antibiotics sold. This approach, which pays a fixed annual fee for access, encourages development against critical pathogens by ensuring a predictable return for drug innovators.
Hospital purchasing behavior is evolving from a focus on per-unit drug cost to a total-value assessment within stewardship programs. This change concentrates decision-making within pharmacy and therapeutics committees, which evaluate antibiotics based on their ability to improve patient outcomes and reduce overall hospital costs. This model is most prominent in large, integrated health networks across North America and Europe.
Gram Positive Bacterial Infections Market Segmentation
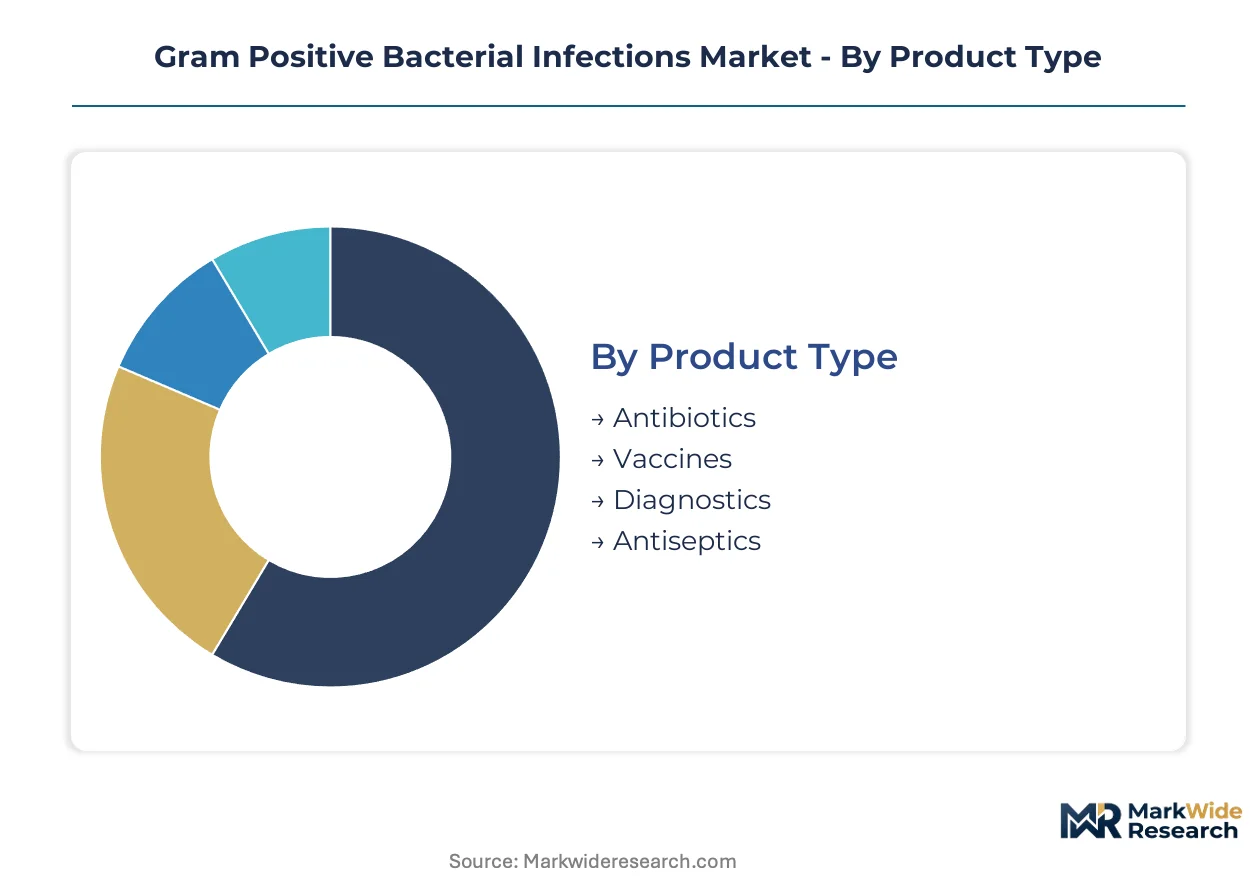
Understanding the segmentation of the gram-positive bacterial infections market is crucial for identifying key growth vectors and strategic investment areas. This detailed breakdown illuminates where product innovation and commercial efforts are most effectively deployed to combat evolving bacterial resistance and patient needs.
Product Type:
The distribution of gram-positive infection treatments across various product types reflects distinct commercial channels and patient care pathways.
- Antibiotics:These pharmaceutical agents remain the primary treatment modality, targeting bacterial cell structures or metabolic processes. Demand concentrates in hospital settings for severe, resistant infections, driving continuous R&D investment.
- Diagnostics:These tools identify specific pathogens and their antibiotic susceptibility, guiding targeted therapy selection. Hospital emergency departments and intensive care units are early adopters, seeking to reduce treatment delays.
- Vaccines:Prophylactic agents designed to prevent gram-positive bacterial infections. Development focuses on high-risk populations and emerging resistant strains.
- Antiseptics:Topical agents used for skin and wound disinfection to prevent bacterial colonization. These products see widespread use in both clinical and community settings.
By volume, Antibiotics lead treatment prescriptions. By growth pace, Diagnostics are ahead.
Indication:
The clinical prevalence and severity of gram-positive infections define treatment priorities and resource allocation across different indications.
- Pneumonia:This respiratory tract infection, often severe and hospital-acquired, drives significant demand for advanced gram-positive antibiotics. Treatment volumes are particularly high in older adult populations and immunocompromised patients.
- Skin Infections:Ranging from mild to severe, these infections represent a high-volume treatment area across outpatient clinics and emergency departments. Managing resistant strains like MRSA remains a significant challenge.
- Endocarditis:A serious infection of the heart's inner lining, requiring prolonged and often intravenous antibiotic therapy. Clinical management focuses on preventing severe cardiac complications.
- Meningitis:This life-threatening infection of the brain and spinal cord membranes necessitates rapid diagnosis and aggressive antimicrobial intervention. Treatment presents significant clinical challenges due to the blood-brain barrier.
Pneumonia treatments generate the largest revenue streams. Skin Infections demonstrate the steepest expansion trajectory.
Delivery Mode:
Patient convenience and the acuity of infection dictate the preferred delivery mode, influencing both product formulation and administration settings.
- Intravenous:This delivery method is crucial for severe, systemic infections requiring rapid and high concentrations of antibiotics. Hospital pharmacies manage the majority of intravenous antimicrobial procurement.
- Oral:These formulations offer convenience for outpatient treatment and step-down therapy following intravenous administration. Demand is expanding for oral options in community settings.
- Inhalation:Specialized delivery for respiratory infections, allowing direct targeting of the lungs. This mode is particularly relevant for chronic conditions like cystic fibrosis.
- Topical:Applied directly to the skin for localized infections, reducing systemic exposure. Over-the-counter and prescription topical products are widely available.
Intravenous administration accounts for the largest share of acute care spending. Oral delivery modes are gaining share fastest for post-discharge management.
End User:
Procurement patterns for gram-positive infection therapies vary significantly across end-user segments, reflecting differing patient populations and institutional capacities.
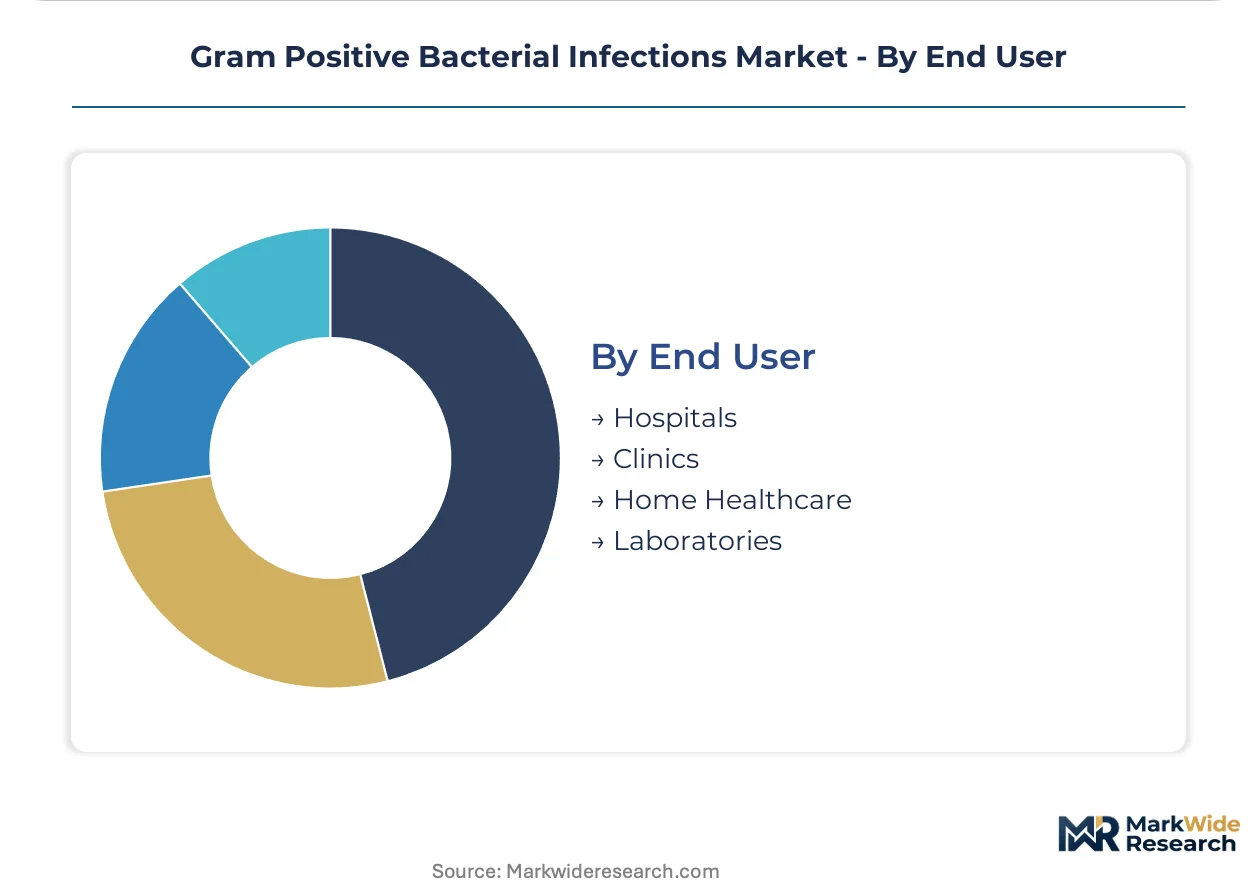
- Hospitals:These institutions are the primary consumers of high-value, broad-spectrum antibiotics for complex and resistant infections. Purchasing decisions are often concentrated within pharmacy and therapeutics committees.
- Clinics:Specialized clinics and outpatient settings manage a substantial volume of community-acquired gram-positive infections. Demand is rotating away from an exclusive focus on large-scale hospital procurement.
- Home Healthcare:Provides treatment for stable patients with less severe infections or those completing intravenous therapy outside a hospital. This segment is driven by cost containment and patient preference.
- Laboratories:These facilities utilize diagnostic products for pathogen identification and susceptibility testing. Investment in rapid molecular diagnostics is increasing.
Hospitals remain the primary purchasing entity for high-value antimicrobials. Clinics are expanding their role in managing community-acquired cases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global network of pharmaceutical supply chains, underpinned by robust air cargo hubs and specialized cold chain logistics, underwrites the Gram Positive Bacterial Infections Market's geographic distribution. This infrastructure ensures the timely delivery of critical antibiotics and diagnostic tools to regions with high disease burdens and advanced healthcare systems. Effective distribution channels are paramount for market penetration and patient access.
United States
Demand for novel antibiotics in the United States stems from a high prevalence of hospital-acquired infections and a strong focus on advanced treatments. The FDA's Qualified Infectious Disease Product (QIDP) designation accelerates drug development and market entry for new antimicrobials. Research hubs in Boston and San Francisco drive significant innovation in next-generation therapies.
Germany
Germany's advanced healthcare infrastructure and an aging population create sustained demand for effective gram-positive infection treatments. The European Medicines Agency (EMA) facilitates approval processes for innovative antibiotics across the European Union. Pharmaceutical clusters in Bavaria and North Rhine-Westphalia are key centers for antibiotic R&D and manufacturing.
India
A high incidence of community- and hospital-acquired bacterial diseases in India generates substantial demand for a wide range of gram-positive antibacterial agents. The country's national pharmaceutical regulator (CDSCO) aims to streamline approval for essential medicines to address public health needs. Manufacturing hubs in Hyderabad and Ahmedabad contribute significantly to global antibiotic production.
Japan
Japan's focus on geriatric care and a sophisticated healthcare system drive demand for high-quality gram-positive infection therapies. The Pharmaceuticals and Medical Devices Agency (PMDA) offers fast-track review pathways for drugs addressing unmet medical needs. Research institutions in Tokyo and Osaka lead efforts in developing novel antimicrobial compounds.
China
China's large population and expanding healthcare access contribute to the rising demand for gram-positive infection treatments. The National Medical Products Administration (NMPA) implements policies to encourage domestic innovation in antibiotic development. Pharmaceutical industrial parks in the Yangtze River Delta are expanding production capacities for essential medicines.
Gram Positive Bacterial Infections Market Key Industry Players
Listed leaders compete with private specialists across the Gram Positive Bacterial Infections Market, influencing innovation and access for novel therapies. The market exhibits a tiered structure, with established pharmaceutical giants alongside nimble biotech firms focusing on specific disease areas. Strategic archetypes include diversified portfolio holders, niche therapeutic developers targeting resistant strains, and diagnostic innovators integrating with treatment pathways. Dominant competitive moves involve strategic partnerships for R&D and targeted acquisitions of promising drug candidates to bolster pipelines.
Diversified pharmaceutical giants like Pfizer and Merck & Co. exemplify the established archetype, leveraging extensive research capabilities and global distribution networks. Pfizer, a US-based corporation, maintains a broad portfolio spanning both established and novel antibiotics. Merck & Co., also a US-based entity, sustains its market presence through a focus on treatments for severe, hospital-acquired infections. Novartis AG, a Swiss-based multinational, differentiates its strategy by investing in next-generation therapies targeting drug-resistant bacterial strains. These companies anchor the market through continuous investment in advanced antimicrobial solutions.
| Leading Market Players |
|---|
| Pfizer |
| Merck & Co. |
| GlaxoSmithKline |
| Novartis AG |
| Johnson & Johnson |
| Sanofi |
| Cipla |
| Sun Pharmaceutical |
| Bayer AG |
Cost & Logistics Intelligence
The FDA's Qualified Infectious Disease Product (QIDP) designation gates both novel antibiotic supply qualification and influences premium price differentiation for new antimicrobials. This regulatory framework incentivizes development while shaping how innovative treatments enter the market.
Pricing Analysis
Volume-based contracts and tiered pricing structures dominate gram-positive antibiotic procurement within hospital systems. Price differentiation stems from the level of innovation, the efficacy against resistant strains, and the specific FDA/EMA certification status. Pricing softness runs through generic antibiotic segments due to intense competition and high supply volumes. Hospital pharmacy and therapeutics committees, focused on patient outcomes, are less price-sensitive for novel, life-saving drugs compared to outpatient clinics managing common infections.
Supply Chain Analysis
India and China anchor the global production of active pharmaceutical ingredients (APIs) for gram-positive antibiotics, supplying a significant portion of the world's pharmaceutical raw materials. Key raw material dependencies include fermentation precursors and specialized chemical intermediates. A structural risk involves single-source vulnerability for specific complex molecules, exacerbated by geopolitical tensions or manufacturing disruptions. Distribution runs through a dual model, with direct pharmaceutical company sales to large hospital networks and wholesale distributors serving smaller clinics and retail pharmacies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Gram Positive Bacterial Infections Market represents an early-cycle expansion story, propelled by the urgent demand for novel therapies driven by antimicrobial resistance.
For Market Incumbents: Shield existing market share by investing in next-generation therapies targeting drug-resistant bacterial strains. Diversify R&D portfolios to include non-traditional treatments like bacteriophage therapy, mitigating the threat from emerging pathogens. Leverage established global distribution networks to ensure rapid market penetration for newly approved antimicrobials across diverse geographies.
For New Entrants and Emerging Players: Anchor in specialized diagnostic-therapeutic pairings to penetrate the market for multi-drug resistant organisms. Target niche indications with high unmet needs, such as rare hospital-acquired infections, where premium pricing is justifiable. Develop novel oral formulations for post-discharge management, addressing the expanding home healthcare segment with convenient options.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with mid-sized biotech firms specializing in bacteriophage therapy or novel antibiotic platforms. These companies offer long-term viability within the 5-10 year window, driven by persistent antimicrobial resistance challenges. The acquisition target archetype includes firms with late-stage clinical assets or unique technology platforms. A signal to watch is the successful completion of Phase 3 trials for a novel antibiotic with a new mechanism of action.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Accelerates market entry for novel antibiotics addressing critical unmet medical needs. |
| Regulatory Approval Pathway | Secures fast-track designations, reducing time-to-market for priority antimicrobial products. |
| Manufacturing Scale-Up | Ensures consistent supply for high-demand novel therapies, preventing shortages in critical care. |
| Diagnostic-Therapeutic Integration | Aligns treatment with rapid pathogen identification, optimizing patient outcomes and antibiotic stewardship. |
| Strategic Partnerships | Expands market reach and combines R&D expertise for complex drug development programs. |
Research Approach
A standing panel of drug development executives, hospital formulary directors, and regulatory affairs leads provided ongoing calibration for this study. This primary research was rigorously cross-referenced with secondary validation from sources including FDA filings, EMA submissions, and national health organization reports. The analysis incorporated both bottom-up market sizing and top-down revenue validation.
External benchmarks consistently validated volume and value outputs across the analysis window. The analytical framework modeled market dynamics across product type, indication, delivery mode, end user, and regional regulatory clusters. Compound annual growth rates were derived from historical trends and projected market drivers, with key inputs including new drug approvals and antimicrobial resistance prevalence data.
Underlying assumptions cover evolving regulatory incentives and antimicrobial stewardship policies, with deviation risk concentrated in the pace of new antibiotic discovery. Recalibration cycles align with material shifts in named drivers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infectious Disease
Pelvic Inflammatory Disease (PID) Treatment Market
Infectious Disease
Infectious Enteritis Treatment Market
Infectious Disease
Global Acute Bacterial Skin and Skin Structure Infection (ABSSSI) Market
Infectious Disease
Meningococcal Disease Treatment Market
Infectious Disease
Acute Vulvovaginal Candidiasis Treatment Market
Infectious Disease
Bacterial Conjunctivitis Market
Infectious Disease
Clostridium Difficile Infection Treatment Market
Infectious Disease
Bronchitis Market
Infectious Disease
Veterinary Infectious Disease Therapeutics Market
Infectious Disease
Periodic Fever Syndrome Market
Infectious Disease
Europe Hospital Acquired Disease Testing Market
Infectious Disease
Pork Tapeworm Infection Treatment Market
Infectious Disease
Global Leptospirosis Market
Infectious Disease
Efavirenz Market
Infectious Disease
Chikungunya Fever Market
Infectious Disease
Herpes Infection Treatment Market