
 Global Janus Kinase Inhibitor (JAK) Market | 2026-2036
Global Janus Kinase Inhibitor (JAK) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Janus Kinase Inhibitor (JAK) Market Foresight
The EU Green Deal's pharmaceutical sustainability criteria is repositioning manufacturing priorities across the JAK value chain. Pfizer Inc. leverages its established tofacitinib infrastructure to sustain volume leadership in oral JAK therapies. AbbVie Inc. anchors its position through Rupatadine-adjacent immunology expertise and selective JAK1 specialization. Bristol Myers Squibb Co. differentiates via deucravacitinib-adjacent signaling research that extends its immunology footprint beyond TYK2 into broader JAK modulation.
Janus Kinase Inhibitors are small-molecule compounds that selectively or non-selectively block JAK1, JAK2, JAK3, or TYK2 enzyme activity, thereby interrupting cytokine-driven JAK-STAT signaling cascades central to inflammatory pathophysiology; these agents typically achieve therapeutic effect at nanomolar concentrations through ATP-competitive binding at the kinase active site. The therapy area dimension shows rheumatoid arthritis and atopic dermatitis commanding the largest patient pools, while ulcerative colitis represents the fastest-expanding indication as gastroenterology practices integrate JAK inhibitors ahead of biologic step-down protocols. Among administration routes, oral formulations dominate prescription volumes due to patient preference and pharmacy benefit design, though intravenous delivery captures premium positioning in hospital-based induction regimens for severe inflammatory bowel disease.
The FDA maintains stringent cardiovascular surveillance requirements through REMS programs and post-marketing safety commitments, while the EMA's PRAC conducts periodic benefit-risk reassessments that directly influence prescriber confidence and formulary placement across European markets. Japan's PMDA imposes localized pharmacovigilance reporting standards that shape launch sequencing and label expansion strategies for multinational sponsors. Stakeholders must monitor evolving thromboembolic safety signals and corresponding regulatory label restrictions, as these dynamics will determine which JAK inhibitors retain broad autoimmune eligibility versus narrowing to second-line or refractory populations.
Market Dynamics
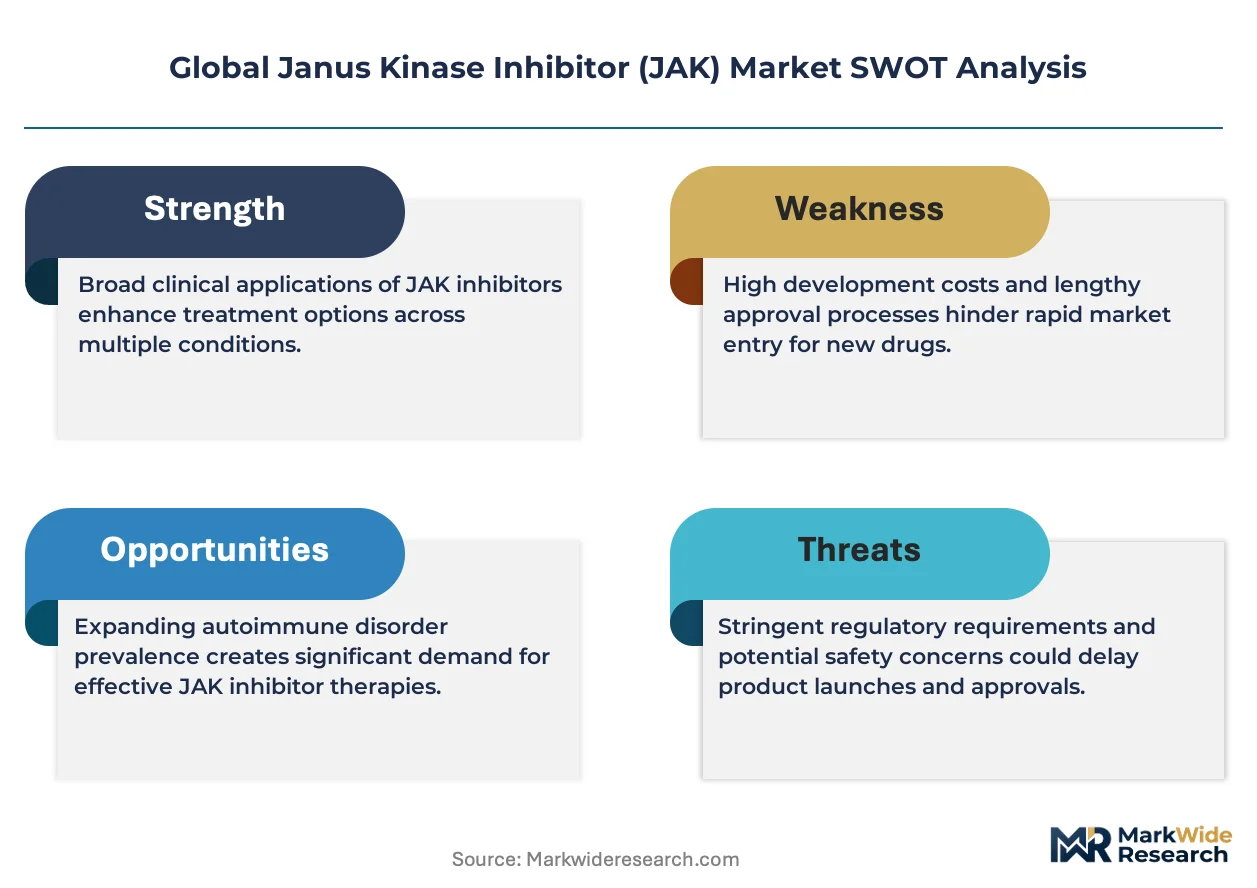
Cardiovascular safety surveillance requirements from the FDA, EMA, and PMDA are restructuring prescriber protocols and formulary placement across all major markets, forcing sponsors to differentiate through selective kinase inhibition profiles rather than broad immunosuppression.
Growth Catalysts
- Specialty clinic expansion:Gastroenterology and dermatology practices in the United States are integrating JAK inhibitors into step-down protocols ahead of biologic discontinuation, expanding addressable patient pools beyond rheumatology.
- EU Green Deal pharmaceutical criteria:Sustainability manufacturing standards are redirecting capital toward continuous processing and solvent reduction, rewarding early adopters with preferential tender positioning in Germany and France.
- Ulcerative colitis protocol adoption:Hospital-based induction regimens for severe inflammatory bowel disease are capturing intravenous delivery premiums, creating volume anchors for oral maintenance switches.
Market Restraints
- Thromboembolic boxed warnings:FDA REMS programs and EMA PRAC benefit-risk reassessments are narrowing eligible populations to second-line or refractory cases, compressing addressable market scope.
- Active-site ATP competition:First-generation non-selective JAK inhibition faces substitution pressure from biologic IL inhibitors and emerging TYK2-selective agents with cleaner safety profiles.
- API synthesis concentration:Key intermediate manufacturing clusters in India and China create single-source vulnerability for multinational sponsors scaling commercial supply.
Strategic Opportunities
- Japan's localized pharmacovigilance:PMDA post-market reporting standards favor sponsors with established safety databases, creating first-mover advantages for label expansion in atopic dermatitis.
- Oral formulation preference:Pharmacy benefit designs in the United States are accelerating patient-driven switches from subcutaneous biologics, rewarding sponsors with once-daily dosing profiles.
- TYK2-JAK1 combination modulation:Convergent signaling research is opening indications in psoriasis and hidradenitis suppurativa previously dominated by IL-17 and IL-23 inhibitors.
Industry Challenges
- Cross-functional safety expertise:Cardiovascular epidemiology and hematology specialist recruitment lags behind regulatory demands for thrombotic signal detection and REMS program management.
- Legacy biologic integration:Hospital formulary committees require complex switching protocols and real-world evidence generation before displacing entrenched anti-TNF and IL inhibitor contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Janus Kinase Inhibitor (JAK) Market |
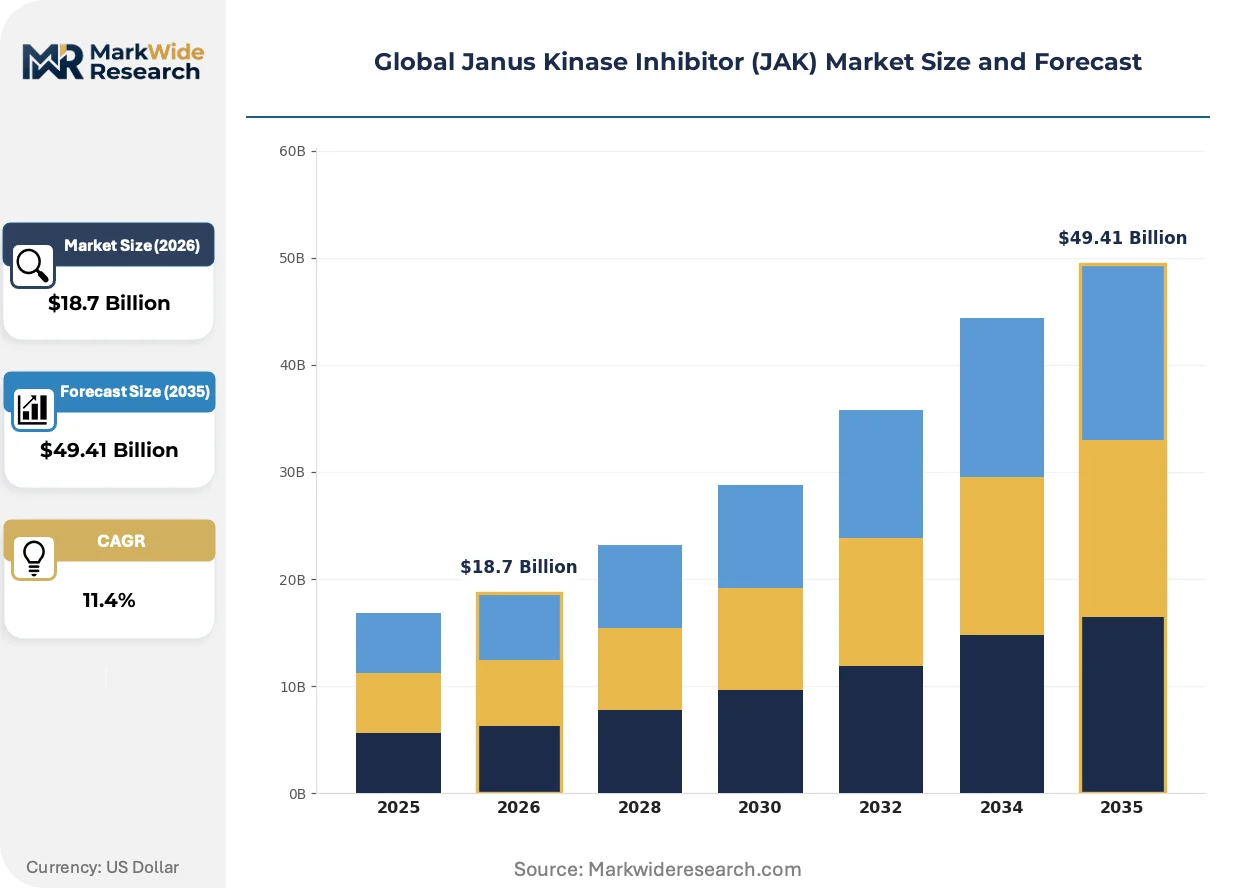
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tofacitinib, Baricitinib, Ruxolitinib, Upadacitinib, Filgotinib Therapy Area: Rheumatoid Arthritis, Psoriatic Arthritis, Atopic Dermatitis, Hair Loss Disorders, Ulcerative Colitis End User: Specialty Clinics, Dermatology Centers, Research Institutes, Hospitals Administration Route: Oral, Topical, Injectable, Intravenous |
| Companies Covered | AbbVie Inc., Astellas Pharma Inc., Pfizer Inc., Gilead Sciences Inc., Bristol Myers Squibb Co., Incyte Corp., Novartis AG, GlaxoSmithKline Plc, Eli Lilly and Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Janus Kinase Inhibitor (JAK) Market Shifts & Advancements
Modular kinase selectivity engineering is fragmenting the competitive landscape, as sponsors abandon pan-JAK inhibition for discrete target combinations that match specific cytokine signatures to disease pathophysiology.
Next-generation JAK1-selective and TYK2-selective small molecules are modularizing clinical trial design by enabling indication-specific biomarker stratification. Rheumatology and dermatology practices in Germany and the United States are adopting these agents at accelerating pace for patients with prior biologic failure. The technology is modularizing regulatory submission pathways, allowing sponsors to pursue parallel label expansions across autoimmune categories without cumulative safety baggage from non-selective predecessors.
REACH pharmaceutical sustainability criteria and the EU Green Deal's carbon border adjustments are mandating solvent recovery rates and green chemistry metrics in active pharmaceutical ingredient manufacturing. Contract manufacturers serving European markets are retrofitting batch processes to continuous flow chemistry to maintain access. Oral solid dose formulations for the German and French hospital sectors face the steepest compliance timelines, with tender eligibility contingent on validated environmental impact disclosures.
Step therapy unbundling is compressing prior authorization cycles as United States payers demand head-to-head non-inferiority data against biologics before granting preferred tier placement. Specialty pharmacies and integrated delivery networks are displacing traditional wholesale channels for JAK inhibitor dispensing, capturing patient adherence data as a reimbursement lever. This shift is most visible in Medicare Part D and commercial managed care plans covering rheumatoid arthritis populations in Florida and Texas.
Global Janus Kinase Inhibitor (JAK) Market Segmentation
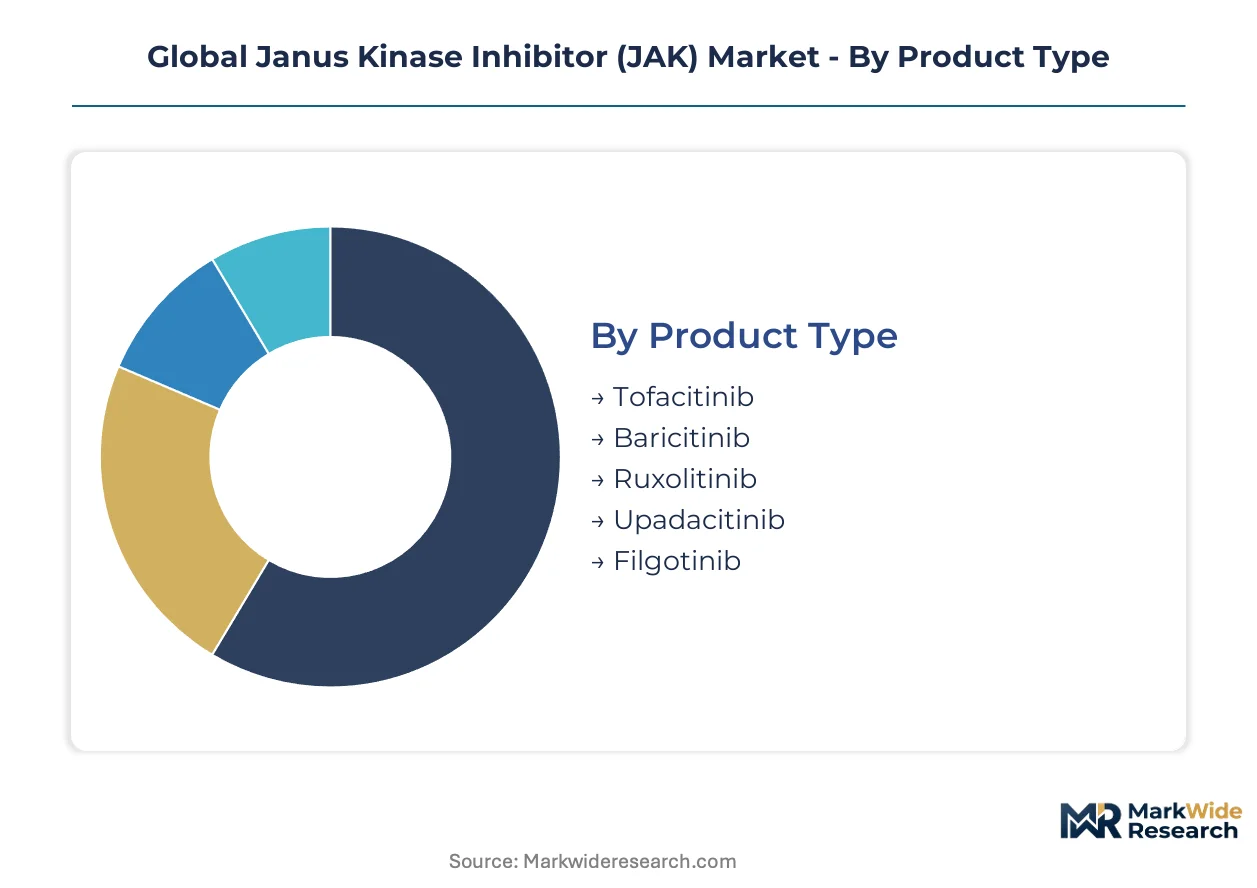
JAK inhibitor segmentation reveals how regulatory requirements, clinical protocols, and delivery preferences fragment commercial opportunity across distinct patient populations and care settings. Understanding these divides illuminates where sponsors must tailor evidence generation and access strategies.
Product Type:
FDA REMS classifications and EMA PRAC benefit-risk profiles vary substantially across this portfolio, determining which agents retain broad autoimmune eligibility versus restricted second-line positioning.
- Tofacitinib:The pioneering pan-JAK inhibitor carries the most extensive thromboembolic safety baggage, with FDA-mandated cardiovascular surveillance compressing its eligible population to refractory rheumatoid arthritis cases despite established efficacy. Demand concentrates in United States Medicare Part D plans where prior authorization protocols favor oral step-down therapy over biologic discontinuation.
- Upadacitinib:AbbVie's JAK1-selective agent achieves cleaner regulatory positioning through discrete kinase targeting, enabling broader atopic dermatitis and ulcerative colitis labeling with reduced REMS burden. German dermatology practices are adopting this agent fastest for biologic-experienced patients.
- Baricitinib:Eli Lilly's JAK1/JAK2 inhibitor balances selectivity with established rheumatology infrastructure.
- Ruxolitinib:Incyte's JAK1/JAK2 agent dominates myelofibrosis with limited autoimmune crossover.
- Filgotinib:Gilead's JAK1-selective molecule faces compressed European positioning following EMA reproductive toxicity signals.
Leading the category by volume: Tofacitinib. Growing fastest: Upadacitinib.
Therapy Area:
Cost tiers stratify sharply across these indications, with hospital-based induction regimens commanding intravenous premiums and outpatient maintenance capturing pharmacy benefit economics.
- Rheumatoid Arthritis:The foundational autoimmune indication for JAK therapy carries mature step-therapy protocols and entrenched anti-TNF contracts that new entrants must displace through real-world evidence. United States rheumatology practices in Florida and Texas are unbundling prior authorization cycles fastest for JAK1-selective switches.
- Ulcerative Colitis:Severe inflammatory bowel disease represents the steepest expansion trajectory as gastroenterology protocols integrate JAK inhibitors ahead of biologic step-down, with hospital-based induction capturing premium intravenous positioning. Japanese gastroenterology societies are updating clinical guidelines fastest to accommodate oral maintenance transitions.
- Psoriatic Arthritis:IL-17 and IL-23 inhibitors retain formulary preference in most United States commercial plans.
- Atopic Dermatitis:Pediatric labeling restrictions limit addressable scope despite strong efficacy signals.
- Hair Loss Disorders:Alopecia areata remains a niche indication with limited payer coverage.
Volume concentration: Rheumatoid Arthritis. Steepest expansion trajectory: Ulcerative Colitis.
End User:
Customer type determines procurement channel and adherence monitoring intensity, with integrated delivery networks capturing patient data as reimbursement leverage.
- Specialty Clinics:United States rheumatology and gastroenterology practices are consolidating JAK prescribing through specialty pharmacy partnerships that capture real-world outcomes data for payer contracting.
- Hospitals:Severe inflammatory bowel disease induction regimens anchor intravenous volume before oral maintenance handoff.
- Dermatology Centers:German and French hospital sectors face the steepest EU Green Deal compliance timelines for tender eligibility.
- Research Institutes:Academic medical centers drive biomarker-stratified trial enrollment for next-generation selective agents.
Dominant channel by prescription volume: Specialty Clinics. Fastest infrastructure investment: Hospitals.
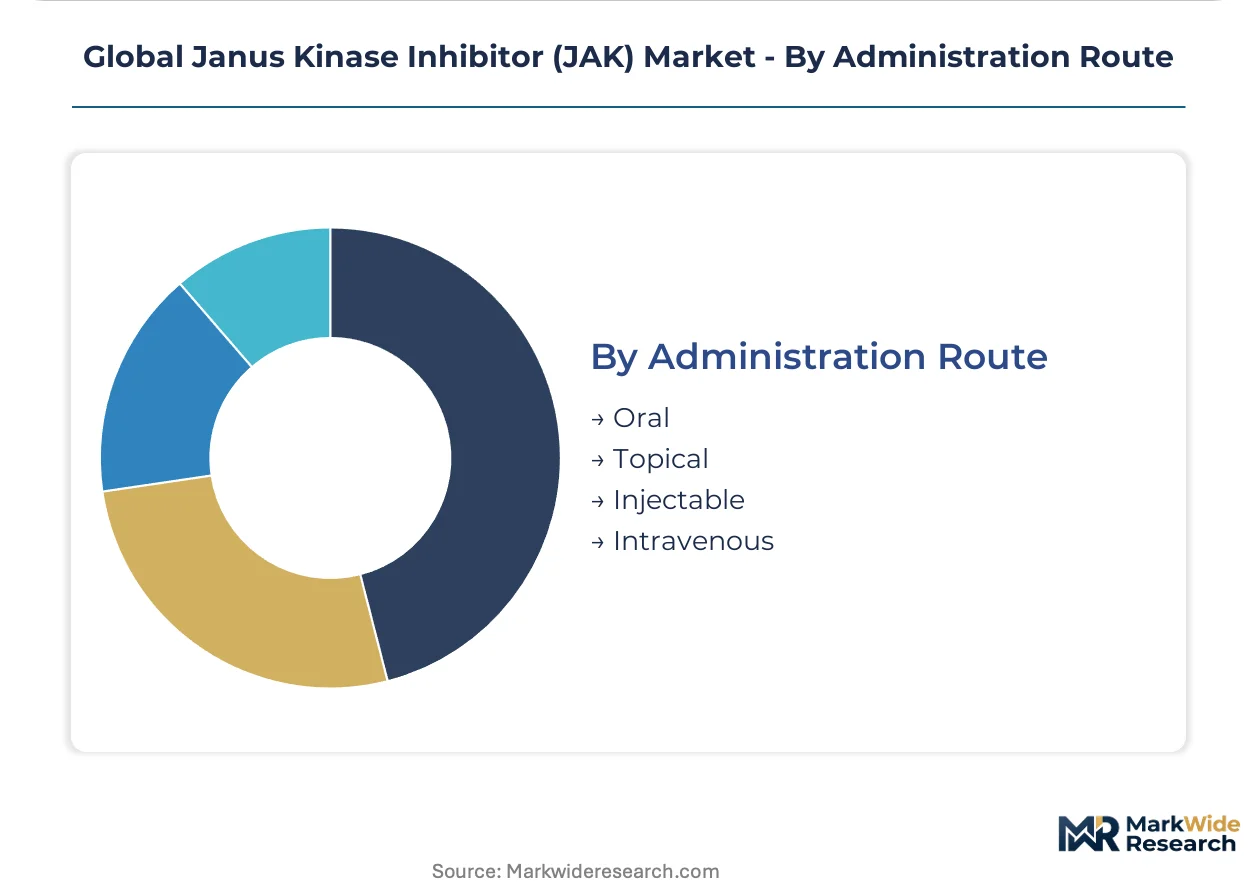
Administration Route:
Supply concentration in API manufacturing clusters shapes formulation availability, with oral solid dose facing the steepest sustainability retrofit requirements.
- Oral:Once-daily tablet formulations dominate patient preference and pharmacy benefit design, driving switches from subcutaneous biologics in United States commercial plans. Continuous processing retrofits for green chemistry compliance are concentrating investment among European contract manufacturers.
- Intravenous:Hospital-based induction for severe ulcerative colitis captures premium positioning before maintenance transition.
- Injectable:Subcutaneous delivery retains niche positioning for patients with absorption concerns.
- Topical:Limited to atopic dermatitis with formulation stability challenges constraining commercial scale.
Prescription volume leader: Oral. Premium positioning: Intravenous.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston's biotech corridor anchors JAK inhibitor clinical development density, with Massachusetts General Hospital and Brigham and Women's Hospital driving biomarker-stratified trial enrollment. Specialty pharmacy networks in the metropolitan area capture adherence data that shapes payer contracting nationwide.
United States
Florida and Texas rheumatology practices unbundle prior authorization cycles fastest for JAK1-selective switches, while Medicare Part D plans favor oral step-down therapy. FDA REMS programs mandate cardiovascular surveillance that compresses eligible populations for non-selective agents. The Research Triangle Park cluster in North Carolina concentrates pharmacovigilance operations for multinational sponsors.
Germany
Dermatology practices in Bavaria adopt JAK1-selective agents fastest for biologic-experienced patients, with hospital formulary committees demanding real-world evidence before displacing anti-TNF contracts. EMA PRAC benefit-risk reassessments directly influence prescriber confidence across German markets. The Frankfurt-Rhine-Main pharmaceutical manufacturing belt retrofits batch processes to continuous flow chemistry for EU Green Deal compliance.
Japan
Tokyo's gastroenterology societies update clinical guidelines fastest to accommodate oral maintenance transitions for ulcerative colitis patients. PMDA post-market reporting standards favor sponsors with established safety databases, creating first-mover advantages for atopic dermatitis label expansion. The Kansai region's Osaka-based contract research organizations specialize in localized pharmacovigilance studies.
United Kingdom
London's integrated care systems consolidate JAK prescribing through specialty pharmacy partnerships that capture real-world outcomes data. NICE technology appraisals weigh thromboembolic risk profiles heavily in formulary recommendations. The Cambridge-London life sciences corridor drives next-generation selective kinase engineering through academic-industry consortia.
France
Paris hospital sectors face steep EU Green Deal compliance timelines for tender eligibility, with oral solid dose formulations requiring validated environmental impact disclosures. ANSM safety signal monitoring influences prescriber behavior in Île-de-France dermatology centers. The Lyon biocluster specializes in green chemistry metrics for active pharmaceutical ingredient manufacturing.
Global Janus Kinase Inhibitor (JAK) Market Competitive Landscape
Premium-margin players sit above commodity-margin players across kinase selectivity engineering, with selective JAK1 and TYK2 modalities commanding favorable formulary placement over pan-JAK predecessors. The vendor base stratifies into three tiers: established immunology majors with rheumatology infrastructure, emerging biotechs with discrete target specialization, and contract manufacturers retrofitting for sustainability compliance. Dominant competitive moves include portfolio diversification toward indication-specific biomarker stratification and backward integration into continuous processing API supply.
Within the established infrastructure tier, Pfizer Inc. and AbbVie Inc. occupy positions shaped by divergent selectivity strategies, with the former anchored in broad-spectrum oral therapy platforms and the latter specialized in discrete JAK1 targeting. Bristol Myers Squibb Co. exemplifies the signaling research archetype through its immunology footprint extension. These three Inc.-structured entities represent distinct competitive responses to thromboembolic safety surveillance requirements.
| Leading Market Players |
|---|
| AbbVie Inc. |
| Astellas Pharma Inc. |
| Pfizer Inc. |
| Gilead Sciences Inc. |
| Bristol Myers Squibb Co. |
| Incyte Corp. |
| Novartis AG |
| GlaxoSmithKline Plc |
| Eli Lilly and Co. |
| Others |
Supply & Pricing Matrix
Captive API production through in-house synthesis of JAK inhibitor intermediates anchors both supply security and pricing power for sponsors navigating EU Green Deal solvent restrictions and FDA cardiovascular surveillance mandates. This backward integration shields against single-source vulnerability in Indian and Chinese manufacturing clusters while preserving margin flexibility against generic substitution pressure.
Pricing Analysis
Outcome-linked pricing for JAK inhibitors in ulcerative colitis and atopic dermatitis anchors reimbursement negotiations to clinical response rates rather than flat per-unit transactions. Pricing stratifies across premium, standard, and economy tiers based on kinase selectivity profiles and REMS burden intensity, with JAK1-selective agents commanding favorable formulary placement over pan-JAK predecessors. Cost compression in the non-selective tier intensifies because EMA PRAC benefit-risk reassessments narrow eligible populations to refractory cases. Medicare Part D plans exhibit highest price sensitivity for oral maintenance therapies, while hospital-based induction regimens show lowest sensitivity due to bundled payment structures.
Supply Chain Analysis
Refurbishment flows for clinical trial materials and returned commercial inventory create secondary supply streams that supplement primary API production. Active pharmaceutical ingredient manufacturing concentrates in India, China, and the United States, with key pyrrolopyrimidine and piperidine intermediates sourced from specialized chemical producers in Gujarat and Zhejiang. Raw material dependencies include palladium catalysts, chiral auxiliaries, and high-purity solvents subject to REACH carbon border adjustments. Single-source vulnerability for JAK2-selective scaffold intermediates poses structural risk. Distribution runs through specialty pharmacy networks that capture patient adherence data for payer contracting leverage.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The JAK inhibitor market is becoming a vertical-integration race as sponsors pursue captive API synthesis to secure supply continuity and negotiate sustainability-compliant tender positioning in Germany and France.
For Market Incumbents: Acquire continuous processing manufacturing assets in the Frankfurt-Rhine-Main belt to preempt EU Green Deal compliance deadlines and displace batch-dependent competitors. Consolidate pharmacovigilance databases to satisfy PMDA localized reporting standards for atopic dermatitis label expansion in Japan. TYK2-selective substitution pressure threatens pan-JAK volume leadership; defend through biomarker-stratified trial enrollment that segments refractory populations. For New Entrants and Emerging Players: Biologic-experienced ulcerative colitis patients in Japanese gastroenterology practices represent an underserved buyer archetype with fastest guideline update velocity and lowest prior authorization friction. Target this segment through oral maintenance transition protocols that bypass intravenous induction infrastructure requirements. Partner with Osaka-based contract research organizations to generate localized safety signals that satisfy PMDA post-market commitments. For Investors and Strategic Acquirers: Exit pathways concentrate in platform acquisitions by immunology majors seeking TYK2-JAK1 combination modulation capabilities. Long-term viability hinges on sponsors demonstrating cardiovascular safety differentiation through discrete kinase targeting rather than broad immunosuppression. Acquisition target archetype: mid-cap developers with biomarker-stratified Phase II assets in hidradenitis suppurativa or alopecia areata. Watch for EMA PRAC benefit-risk reassessment outcomes as inflection indicators for formulary access compression.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Biomarker-stratified enrollment in ulcerative colitis accelerates label expansion timelines for selective JAK1 agents. |
| Regulatory Approval Pathway | EMA PRAC pre-submission consultations reduce benefit-risk reassessment uncertainty for TYK2-selective filings. |
| Manufacturing Scale-Up | Continuous flow chemistry retrofitting in the Frankfurt-Rhine-Main belt secures EU Green Deal tender eligibility. |
| Pipeline Diversification | TYK2-JAK1 combination programs in psoriasis extend addressable indications beyond IL-17 and IL-23 inhibitor dominance. |
| Licensing Agreement | Japanese pharmacovigilance data partnerships with Osaka CROs satisfy PMDA post-market reporting mandates. |
Research Methodology
Independent corroboration across formulary database audits, FDA REMS program filings, and EMA PRAC assessment reports underwrites the qualitative findings in this analysis. Primary interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists combined with secondary validation from ClinicalTrials.gov entries, SEC 10-K pharmaceutical disclosures, and national pharmacovigilance registries. Bottom-up patient pool estimates and top-down prescription volume reconciliations triangulate market sizing across the analysis window.
Comparable-period anchoring to historical FDA approval dates and EMA centralized procedure timelines established the forecast window boundaries. The analytical framework models volume and value across therapy area, product selectivity profile, administration route, patient treatment line, and regional regulatory cluster dimensions. CAGRs derive from indication-specific adoption curves weighted by REMS burden intensity and step-therapy protocol penetration. Forecast inputs include gastroenterology society guideline update velocities and specialty pharmacy network expansion rates.
Revisions become necessary when thromboembolic safety signals trigger regulatory label restrictions, when API manufacturing clusters face environmental compliance shutdowns, or when biologic IL inhibitors demonstrate superior head-to-head non-inferiority in ulcerative colitis induction. Forecasts reflect documented assumptions about kinase selectivity preference evolution and sustainability tender weighting. Material deviation in cardiovascular surveillance mandates or EU Green Deal enforcement intensity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Telmisartan Market
Pharmaceuticals
Peptic Ulcer Drugs Market
Pharmaceuticals
Direct Oral Anticoagulants Market
Pharmaceuticals
Asia-Pacific Anesthesia Drugs Market
Pharmaceuticals
Cefazedone Sodium Market
Pharmaceuticals
Otic Drugs Market
Pharmaceuticals
Global Divalproex Sodium Market
Pharmaceuticals
Repurposed Human Immunosuppressants Market
Pharmaceuticals
Europe Contraceptives Market
Pharmaceuticals
Lamotrigine API Market
Pharmaceuticals
Europe Generic Drug Market
Pharmaceuticals
Tranquilizer Drugs Market
Pharmaceuticals
Germany Pharmaceutical Cold Chain Logistics Market
Pharmaceuticals
Intravenous Pegloticase Market
Pharmaceuticals
China Human Papillomavirus Vaccine Market
Pharmaceuticals
Sitagliptin Market