
 Canine Flu Therapeutics Market | 2026-2036
Canine Flu Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Canine Flu Therapeutics Market Outlook
North American veterinary biologics manufacturing is expanding its fill-finish capacity for multivalent canine influenza formulations. Zoetis Inc. leverages integrated vaccine development platforms spanning mammalian cell culture to sterile packaging. Merck Animal Health anchors its position through USDA-licensed production facilities in Iowa and Georgia. Boehringer Ingelheim differentiates via recombinant vector technologies that reduce cold-chain dependency.
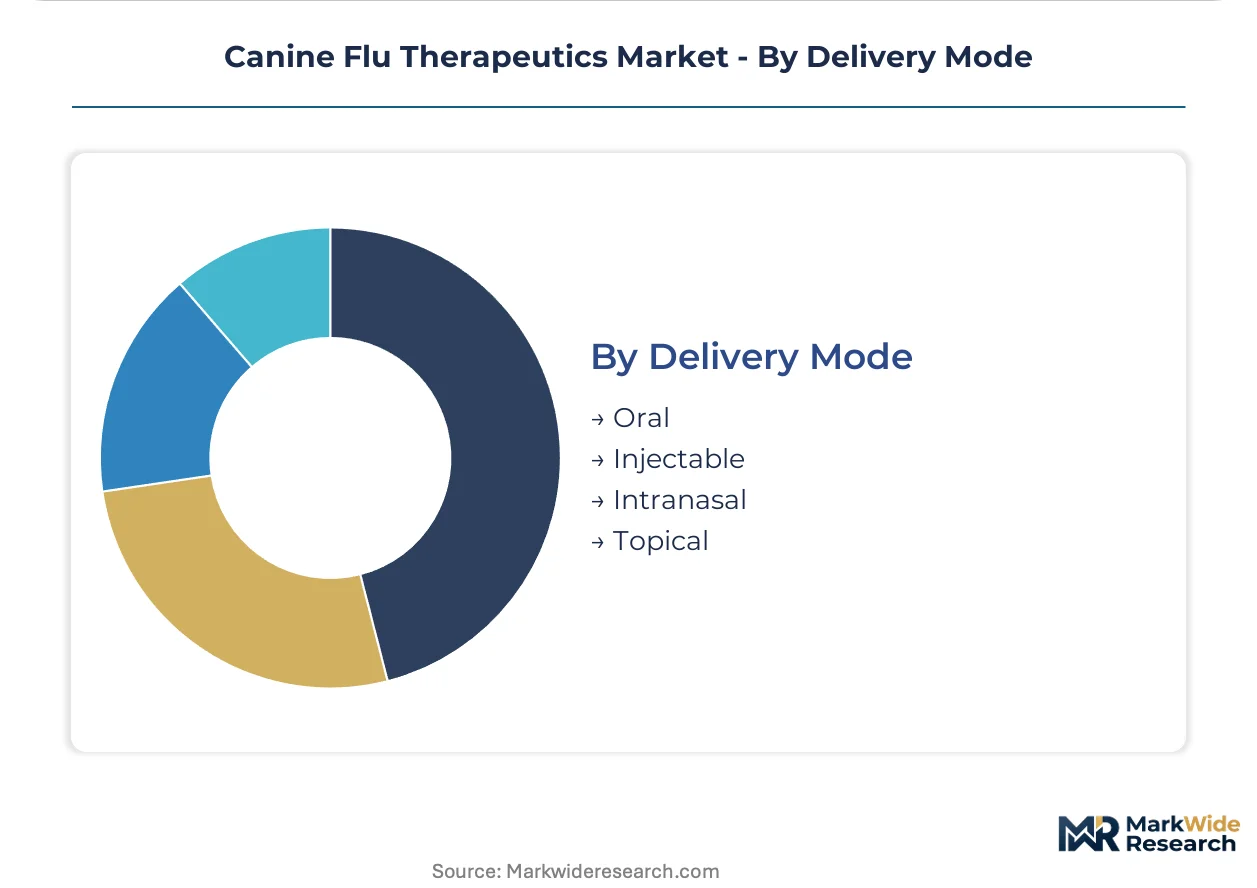
Canine flu therapeutics encompass prophylactic vaccines, antiviral agents, and adjunctive immune modulators formulated for H3N8 and H3N2 influenza A subtypes, typically administered as aqueous suspensions containing inactivated or attenuated viral particles with aluminum hydroxide adjuvants. These products serve to reduce clinical severity, viral shedding duration, and kennel outbreak incidence in high-density canine populations. The injectable delivery mode dominates commercial volumes due to established veterinary familiarity and reliable seroconversion rates, while intranasal platforms capture growing interest for mucosal immunity induction in shelter and boarding environments. Vaccines command the largest revenue pool among product types, though immune modulators represent the fastest-expanding category as practitioners seek reduced antibiotic co-dependence.
The USDA Center for Veterinary Biologics enforces batch-release potency testing and facility inspection schedules that determine market access timelines for new entrants. FDA's Center for Veterinary Medicine oversees antiviral drug approvals under the Animal Medicinal Drug Use Clarification Act, constraining extra-label prescribing patterns. State veterinary medical boards in California, Texas, and Florida implement continuing education mandates that influence prescriber familiarity with emerging influenza strains. Stakeholders must monitor antigenic drift surveillance data and regulatory harmonization discussions between USDA and OIE guidelines to anticipate reformulation cycles and licensure pathway adjustments.
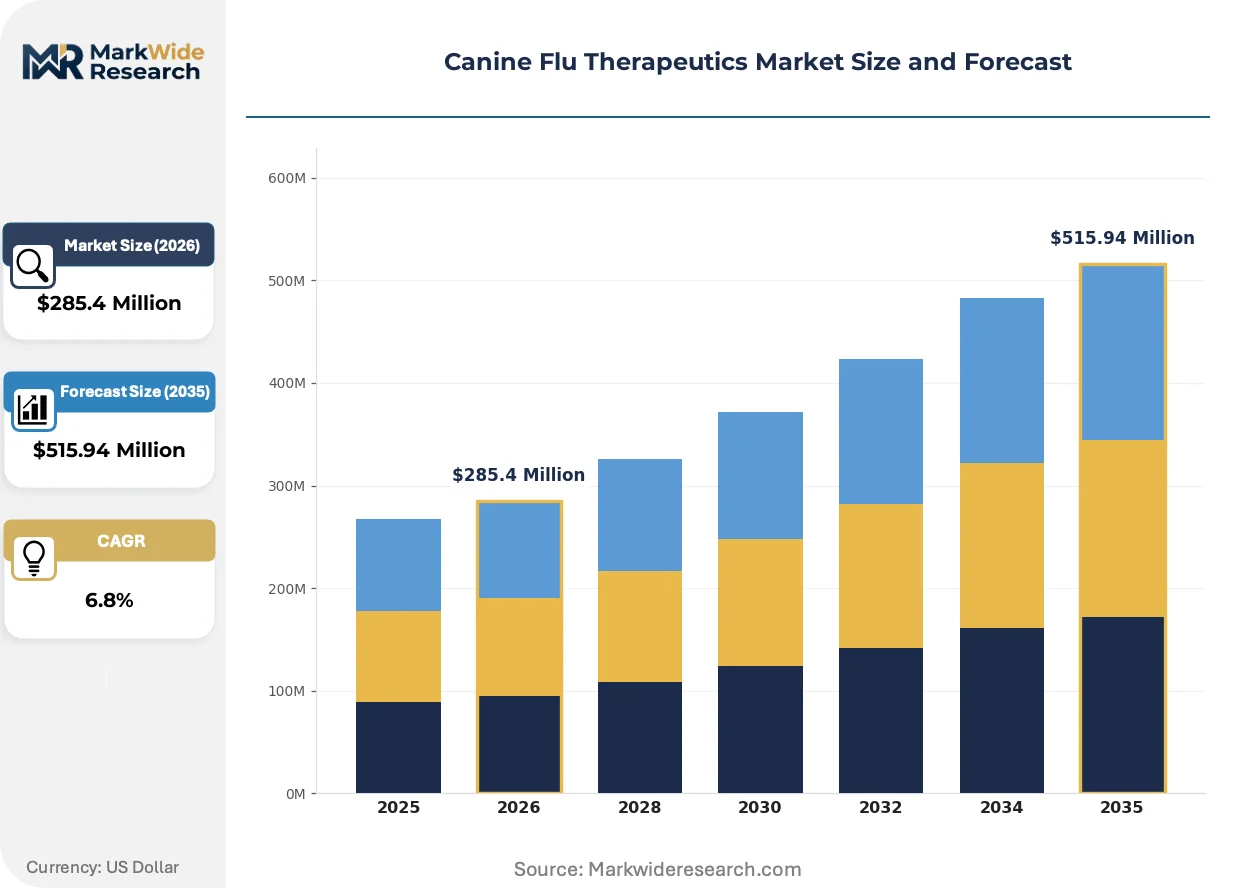
Market Dynamics
The canine flu therapeutics sector is restructuring around antigenic drift surveillance and multivalent reformulation cycles, as USDA batch-release protocols compress development timelines and veterinary clinics consolidate purchasing through distributor networks.
Growth Catalysts
- H3N2 Antigenic Surveillance:USDA's real-time strain monitoring accelerates vaccine reformulation approvals, reducing time-to-market for updated formulations targeting emerging clades.
- Boarding Facility Mandates:State-level kennel licensing requirements in high-density metropolitan corridors are institutionalizing annual revaccination protocols.
- Recombinant Vector Platforms:Reduced cold-chain dependency expands distribution reach to rural veterinary practices previously excluded from biologics access.
Market Restraints
- Egg-Based Production Bottlenecks:Influenza vaccine manufacturing remains tethered to embryonated chicken egg supply chains vulnerable to avian disease outbreaks.
- Adjuvant Input Concentration:Aluminum hydroxide sourcing concentrates among a limited supplier base in the US Gulf Coast chemical corridor.
- Veterinary Labor Scarcity:Companion animal practice capacity constraints limit appointment availability for preventive care administration.
Strategic Opportunities
- Shelter Medicine Expansion:Municipal animal control contracts in Texas and Florida represent underpenetrated volume pools for intranasal platform deployment.
- Telemedicine Prescription Pathways:State veterinary board telehealth rule relaxations enable remote consultation-driven vaccine scheduling.
- Human-Animal Interface Surveillance:CDC One Health initiative funding creates diagnostic co-development opportunities for zoonotic strain monitoring.
Industry Challenges
- USDA Facility Inspection Backlogs:Center for Veterinary Biologics site visit scheduling delays extend licensure timelines for novel platform submissions.
- Serological Correlates of Protection:Absence of standardized HAI titer thresholds complicates efficacy claim substantiation across H3N8 and H3N2 subtypes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canine Flu Therapeutics Market |
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $515.94 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vaccines, Antivirals, Immune Modulators, Supportive Care Therapy Area: Infectious Diseases, Respiratory Diseases, Preventive Care, Emergency Care End User: Veterinary Clinics, Animal Hospitals, Research Labs, Pet Owners Delivery Mode: Oral, Injectable, Intranasal, Topical |
| Companies Covered | Zoetis Inc., Merck Animal Health, Elanco Animal Health, Boehringer Ingelheim, Virbac, Ceva Santé Animale, Vetoquinol, Heska Corporation, Pfizer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canine Flu Therapeutics Market Strategic Shifts
Molecular diagnostic integration and point-of-care testing platforms are compressing the diagnostic-to-treatment interval in companion animal respiratory disease management. These capabilities reshape how practitioners sequence prophylaxis and therapeutic intervention.
CRISPR-guided attenuation is automating live-virus vaccine development by enabling precise genomic editing of influenza virulence factors. Zoetis and Merck Animal Health have accelerated internal platform adoption, reducing empirical passage attenuation cycles from months to weeks. This compression enables faster response to antigenic drift events.
USDA's revised veterinary biologics guidance on platform technology approvals is streamlining subsequent strain updates for licensed recombinant vectors. The policy shift reduces supplemental application requirements when master seed lots remain unchanged. Multivalent manufacturers in Iowa and Georgia are restructuring regulatory affairs teams to exploit this pathway.
Corporate veterinary group procurement consolidation is displacing independent practice purchasing autonomy. Mars Petcare and National Veterinary Associates aggregate vaccine volumes through centralized distributor negotiations, extracting tiered pricing concessions previously unavailable to standalone clinics. California and New York metropolitan markets exhibit the most pronounced buyer concentration.
Canine Flu Therapeutics Market Segmentation
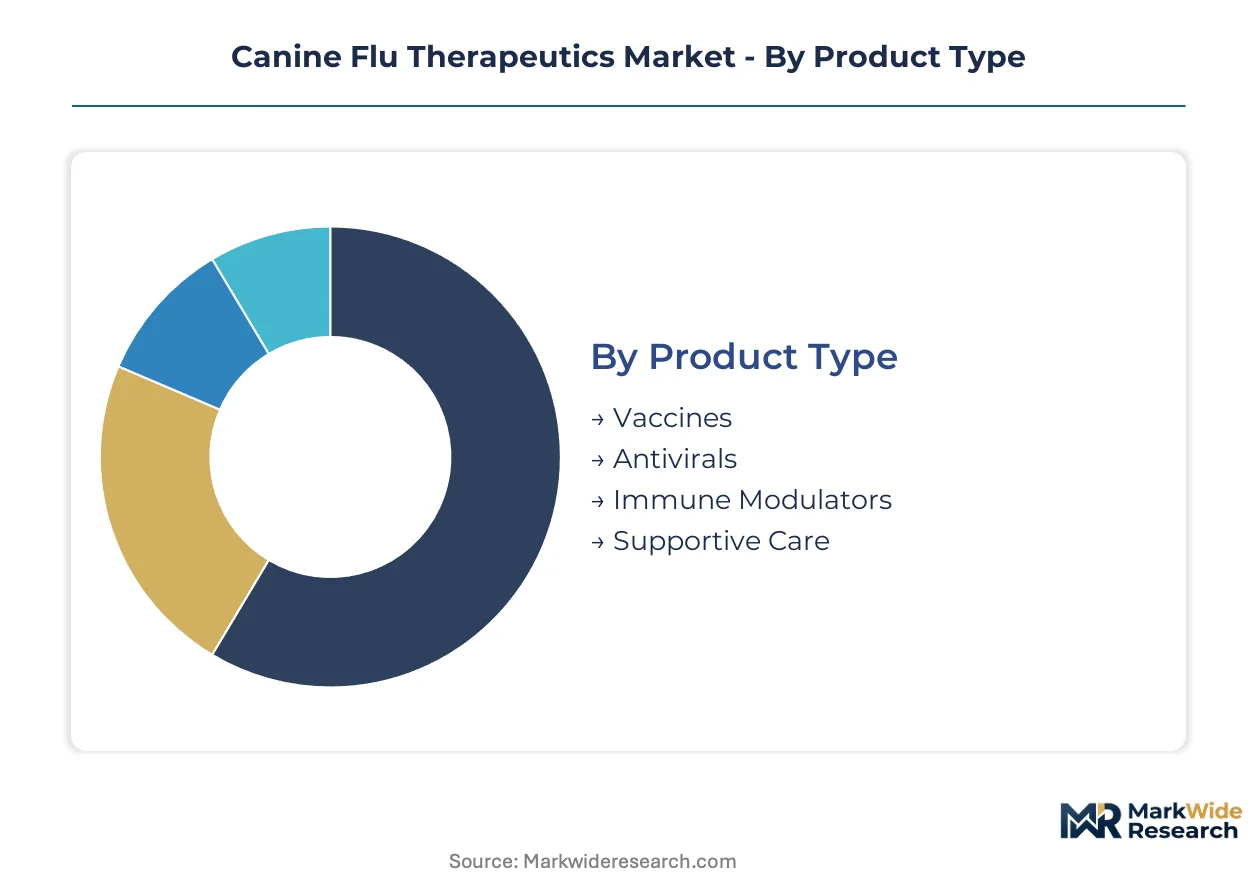
Canine flu therapeutics fragment across four distinct classification schemes that reshape procurement patterns and margin structures. Product type and delivery mode classifications dominate commercial decision-making, while therapy area and end-user dimensions govern regulatory pathway selection and reimbursement dynamics.
Product Type:
Cost tier separates institutional buyers from retail-oriented channels, with premium biologics commanding distinct purchasing workflows.
- Vaccines:Inactivated or attenuated viral suspensions containing H3N8 and H3N2 antigens with aluminum hydroxide adjuvants. Demand concentrates in North American companion animal practices where boarding facility mandates drive annual revaccination protocols.
- Immune Modulators:Adjunctive biological agents formulated to reduce antibiotic co-dependence in respiratory management. Shelter medicine programs in Texas and Florida represent the fastest-expanding uptake channel for these platforms.
- Antivirals:FDA Center for Veterinary Medicine-regulated therapeutics targeting neuraminidase inhibition.
- Supportive Care:Fluid therapy and nutritional supplementation products for acute respiratory distress management.
Volume sits with vaccines; growth tilts toward immune modulators.
Therapy Area:
Application context determines whether products route through emergency reimbursement codes or preventive care budgets.
- Preventive Care:Prophylactic protocols administered prior to kennel boarding or dog show participation. High-density metropolitan corridors in California institutionalize these programs through licensing requirements.
- Infectious Diseases:Targeted intervention against confirmed influenza A subtype infections with diagnostic confirmation. USDA antigenic drift surveillance directly shapes product relevance in this segment.
- Respiratory Diseases:Broad-spectrum management of upper and lower respiratory tract pathology.
- Emergency Care:Acute intervention for severe pneumonia or secondary bacterial complications.
Revenue concentrates in preventive care; steepest expansion trajectory emerges in infectious diseases as molecular diagnostic integration accelerates.
End User:
Customer type dictates packaging scale, cold-chain requirements, and technical support intensity.
- Veterinary Clinics:Primary care settings administering routine prophylaxis and outpatient respiratory management. Corporate group procurement through Mars Petcare and National Veterinary Associates is displacing independent purchasing autonomy in California and New York metropolitan markets.
- Animal Hospitals:Specialty and emergency facilities managing severe influenza complications requiring hospitalization.
- Research Labs:Academic and contract research organizations conducting efficacy studies and strain surveillance.
- Pet Owners:Direct-to-consumer channels for over-the-counter immune support and prescription fulfillment.
Procurement volume anchors in veterinary clinics; share gains accrue fastest to animal hospitals as case complexity escalates.
Delivery Mode:
Supply concentration and cold-chain infrastructure shape geographic accessibility across administration routes.
- Injectable:Subcutaneous or intramuscular aqueous suspensions with established seroconversion profiles. Rural veterinary practices in Iowa and Georgia rely on this mode due to familiar handling protocols and reliable USDA batch-release supply.
- Intranasal:Mucosal immunity-inducing platforms with reduced systemic reactogenicity. Shelter and boarding environments in Texas and Florida are capturing growing interest for outbreak containment applications.
- Oral:Palatable formulations for antiviral and immune modulator administration.
- Topical:Transdermal or ocular delivery systems for localized adjunctive therapy.
Commercial volumes cluster around injectable platforms; intranasal formats are climbing the fastest as mucosal immunity protocols penetrate high-density canine populations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Embryonated chicken egg supply chains in the US Midwest and aluminum hydroxide production along the Gulf Coast anchor canine flu therapeutics manufacturing geography. Veterinary biologics fill-finish capacity concentrates in Iowa and Georgia production corridors. Regulatory batch-release protocols at USDA facilities determine market access timelines across all production zones.
United States
USDA-licensed production facilities in Iowa and Georgia dominate multivalent vaccine output for H3N8 and H3N2 subtypes. The Center for Veterinary Biologics enforces batch-release potency testing that compresses reformulation cycles for emerging clades. Corporate veterinary group procurement through Mars Petcare and National Veterinary Associates is displacing independent clinic purchasing autonomy in California and New York metropolitan markets.
Germany
Boehringer Ingelheim's recombinant vector development programs reduce cold-chain dependency for rural veterinary access. The EMA's veterinary medicinal product framework coordinates with USDA guidelines on antigenic drift surveillance data sharing. Manufacturing clusters in the Rhine-Main region specialize in adjuvant formulation chemistry for aluminum hydroxide suspensions.
France
Ceva Santé Animale and Virbac anchor European companion animal vaccine development through platform technology investments. ANSM oversight of veterinary biologics imports aligns with OIE harmonization discussions on strain update protocols. The Lyon-Grenoble corridor concentrates molecular diagnostic integration for point-of-care respiratory testing.
United Kingdom
Specialty veterinary practices in Greater London drive demand for intranasal mucosal immunity platforms in high-density boarding environments. The Veterinary Medicines Directorate coordinates with USDA on master seed lot equivalency determinations for recombinant vector approvals. Research partnerships between Cambridge veterinary schools and commercial manufacturers accelerate CRISPR-guided attenuation cycles.
Japan
PMDA's animal drug approval pathways accommodate imported USDA-licensed vaccines through abbreviated review procedures for established platform technologies. METI funding for One Health surveillance creates diagnostic co-development opportunities with CDC-aligned programs. Osaka-based distributors manage cold-chain logistics for biologics reaching veterinary clinics across Honshu island.
Canine Flu Therapeutics Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue recombinant vector and mucosal delivery niches. The sector exhibits moderate consolidation around integrated vaccine development platforms spanning mammalian cell culture to sterile packaging. Three archetypes dominate: multivalent formulation specialists, recombinant technology innovators, and distributor-integrated service providers. Capacity expansion and strategic technology licensing represent the primary competitive moves as firms respond to antigenic drift surveillance demands.
Among US-based integrated animal health corporations, Zoetis Inc. and Merck Animal Health exemplify the multivalent formulation archetype through USDA-licensed production infrastructure. Boehringer Ingelheim occupies a position representing recombinant vector innovation with reduced cold-chain dependency. These three entities anchor the competitive structure by spanning development platforms from genomic editing to distributor network integration.
| Leading Market Players |
|---|
| Zoetis Inc. |
| Merck Animal Health |
| Elanco Animal Health |
| Boehringer Ingelheim |
| Virbac |
| Ceva Santé Animale |
| Vetoquinol |
| Heska Corporation |
| Pfizer |
| Others |
Value Chain & Pricing Dynamics
Veterinary biologics manufacturing specialists concentrated in Iowa and Georgia drive labor-cost differentials that widen pricing-tier spreads between premium USDA-licensed formulations and standard imported alternatives. These regional workforce pools command distinct compensation premiums that manufacturers pass through to institutional buyers versus retail-oriented channels.
Pricing Analysis
Warranty-backed potency guarantees and batch-release documentation separate premium biologics from unbundled economy alternatives. Pricing stratifies across premium USDA-licensed, standard CE-marked import, and economy non-adjuvanted tiers based on cold-chain certification grade and veterinary technical support intensity. Cost compression in the standard tier is intensifying because corporate group procurement aggregates volumes through centralized distributor negotiations. Independent companion animal practices exhibit highest price sensitivity; specialty emergency hospitals demonstrate lowest.
Supply Chain Analysis
Freight costs for temperature-controlled biologics distribution hinge on last-mile rural veterinary access, with logistics premiums reaching 15-40% above base product cost in non-metropolitan corridors. Manufacturing concentrates in the United States, Germany, and France. Embryonated chicken egg supply chains draw from Midwest poultry operations; aluminum hydroxide adjuvant sourcing rests on Gulf Coast chemical corridor production. Single-source vulnerability in egg supply creates structural risk. Distribution runs through veterinary distributor networks with cold-chain custody verification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is accelerating into a vertical-integration race as players pursue captive control over mammalian cell culture platforms to secure antigenic drift response speed.
For Market Incumbents: To counter recombinant vector platform entrants with reduced cold-chain dependency, incumbents should deepen backward integration into adjuvant formulation chemistry and expand fill-finish capacity in USDA-licensed Iowa and Georgia corridors. Regulatory affairs team restructuring to exploit streamlined platform technology approvals represents a critical certification investment lever. For New Entrants and Emerging Players: Telemedicine-enabled prescription pathways offer the most penetrable route for bypassing established distributor relationships. Municipal animal control contracts in Texas and Florida shelter medicine programs represent underpenetrated volume pools. A direct-to-clinic digital scheduling platform with remote consultation integration provides the strongest go-to-market angle. For Investors and Strategic Acquirers: Re-rating potential sits with recombinant vector technology specialists given USDA platform technology guidance streamlining subsequent strain updates. Long-term viability over a decade horizon favors entities with master seed lot libraries and regulatory pathway expertise. Watch for CDC One Health initiative funding inflections as diagnostic co-development demand signals.| Strategic Initiative | Industry Significance |
|---|---|
| USDA Platform Technology Licensing | Streamlined approvals for recombinant vector updates reduce reformulation cycles against H3N2 antigenic drift. |
| Cold-Chain Infrastructure Expansion | Rural veterinary access in Texas and Florida depends on reduced-temperature-dependency distribution networks. |
| Shelter Medicine Contract Aggregation | Municipal animal control procurement in high-density metropolitan corridors institutionalizes intranasal platform volumes. |
| CRISPR-Guided Attenuation Adoption | Genomic editing of influenza virulence factors compresses development timelines from months to weeks. |
| Corporate Group Procurement Integration | Mars Petcare and National Veterinary Associates centralized purchasing extracts tiered pricing concessions. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with veterinary biologics manufacturing executives, USDA Center for Veterinary Biologics regulatory affairs leads, corporate group procurement directors, and companion animal practice owners. Secondary sources encompassed FDA Center for Veterinary Medicine submissions, EMA veterinary medicinal product frameworks, OIE strain surveillance databases, and customs import records. Bottom-up volume estimates triangulated against top-down market sizing.
Reconciliation of production capacity disclosures, distributor shipment data, and veterinary clinic procurement surveys informed the analytical framework across the projection horizon. Segmentation dimensions modeled included product type, delivery mode, therapy area, and end-user category with regional regulatory cluster overlays. CAGRs derived from historical volume trajectories and anticipated reformulation cycle frequencies. Antigenic drift surveillance intensity and corporate group procurement consolidation served as industry-specific forecast inputs.
Inputs from USDA batch-release records and state veterinary medical board continuing education mandates were available through the study window; gaps in real-time shelter medicine procurement data introduce uncertainty bands around intranasal platform adoption trajectories. Forecasts reflect documented assumptions regarding regulatory harmonization timelines and cold-chain infrastructure investment. Antigenic shift events or avian disease outbreaks affecting embryonated egg supply could materially revise projections. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary
Milking Salve Market
Veterinary
Veterinary Antibiotics Market
Veterinary
Pet Cremation Market
Veterinary
Global Veterinary Rapid Test Market
Veterinary
Mexico Veterinary Healthcare Market
Veterinary
Veterinary Lasers Market
Veterinary
Global Animal Antimicrobials and Antibiotics Market
Veterinary
Otc Pet Medication Market
Veterinary
Canine Separation Anxiety Treatment Market
Veterinary
Asia-Pacific Veterinary Healthcare Market
Veterinary
Veterinary Parasiticides Market
Veterinary
Global Veterinary Drugs Market
Veterinary
Veterinary Consumables Market
Veterinary
Feline Atopic Dermatitis Treatment Market
Veterinary
Veterinary and Animal Healthcare Logistics Market
Veterinary
Bovine Respiratory Disease Treatment Market