
 Asia Pacific Multiple Sclerosis Drugs Market | 2026-2036
Asia Pacific Multiple Sclerosis Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Multiple Sclerosis Drugs Market Insights
Good Manufacturing Practice certification for biologics production is collapsing the supplier base eligible to serve Asia Pacific regulators. Novartis AG leverages its Basel-based manufacturing network to sustain supply continuity across Japanese and Australian distribution channels. F. Hoffmann-La Roche Ltd anchors its regional position through deep specialization in monoclonal antibody production for relapsing-remitting indications. Biogen competes aggressively on neurologist relationships and clinical trial infrastructure within South Korean and Taiwanese hospital systems.
Multiple sclerosis drugs comprise pharmaceutical formulations designed to modulate immune system activity, reduce inflammation, and slow neurodegeneration in the central nervous system; these agents typically require cold-chain distribution at 2-8°C and sterile manufacturing environments to maintain protein stability. The primary commercial purpose centers on disease modification and symptom management in autoimmune-mediated demyelination. Immunomodulators occupy the largest revenue pool given their established reimbursement across public hospital formularies, while monoclonal antibodies represent the fastest-expanding category as intravenous infusion centers proliferate in urban Chinese and Indian metros. The injectable administration route still dominates volume, though oral formulations are capturing disproportionate patient preference where out-of-pocket burdens are lower.
Japan's PMDA, Australia's TGA, and South Korea's MFDS enforce divergent stability-testing requirements that fragment regional launch timelines and inflate regulatory compliance costs for multinational sponsors. China's NMPA has tightened pharmacovigilance reporting obligations for imported biologics, creating additional documentation barriers for first-time entrants. Stakeholders must monitor how CDSCO's evolving biosimilar guidelines in India reshape competitive dynamics for originator molecules approaching patent expiry.
Market Dynamics
Regulatory divergence across Japan's PMDA, Australia's TGA, and South Korea's MFDS is fragmenting launch timelines and forcing sponsors to maintain parallel stability-testing protocols for the same biologic molecule.
Growth Catalysts
- Streamlined biosimilar pathways:Australia's TGA and Japan's PMDA have compressed approval timelines for follow-on biologics, accelerating competitive entry and expanding patient access to disease-modifying therapies.
- Infusion center proliferation:Urban hospital networks in Chinese and Indian metros are building dedicated monoclonal antibody infusion capacity, enabling intravenous administration of advanced immunomodulators.
- Reimbursement maturation:South Korea's National Health Insurance Service has expanded formulary coverage for second-line MS therapies, reducing out-of-pocket burdens and driving protocol adoption in tertiary neurology departments.
Market Restraints
- Cold-chain infrastructure gaps:Temperature-controlled distribution at 2-8°C remains inconsistent across Southeast Asian logistics networks, constraining biologics penetration outside major metropolitan hubs.
- Regulatory documentation inflation:China's NMPA pharmacovigilance reporting obligations for imported biologics have created additional compliance barriers, extending time-to-market for first-time entrants.
- Specialist neurologist scarcity:MS diagnosis and treatment initiation requires board-certified neurology expertise that concentrates in Tokyo, Seoul, Sydney, and Shanghai hospital clusters.
Strategic Opportunities
- Oral formulation expansion:Patient preference for non-injectable administration routes creates white space for sphingosine-1-phosphate receptor modulators and other small-molecule immunomodulators in markets with lower out-of-pocket burdens.
- Indian biosimilar manufacturing:CDSCO's evolving biosimilar guidelines position domestic producers to capture share as originator molecules approach patent expiry across the region.
- Home administration models:Self-injectable platforms and remote patient monitoring infrastructure enable therapy continuation outside hospital settings, expanding addressable geography beyond infusion center catchment areas.
Industry Challenges
- Sterile manufacturing certification:Good Manufacturing Practice requirements for biologics production are collapsing the eligible supplier base, forcing sponsors to qualify limited contract manufacturing organizations.
- Stability-testing protocol divergence:Japan, Australia, and South Korea enforce non-harmonized analytical requirements that prevent unified regional submission strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Multiple Sclerosis Drugs Market |
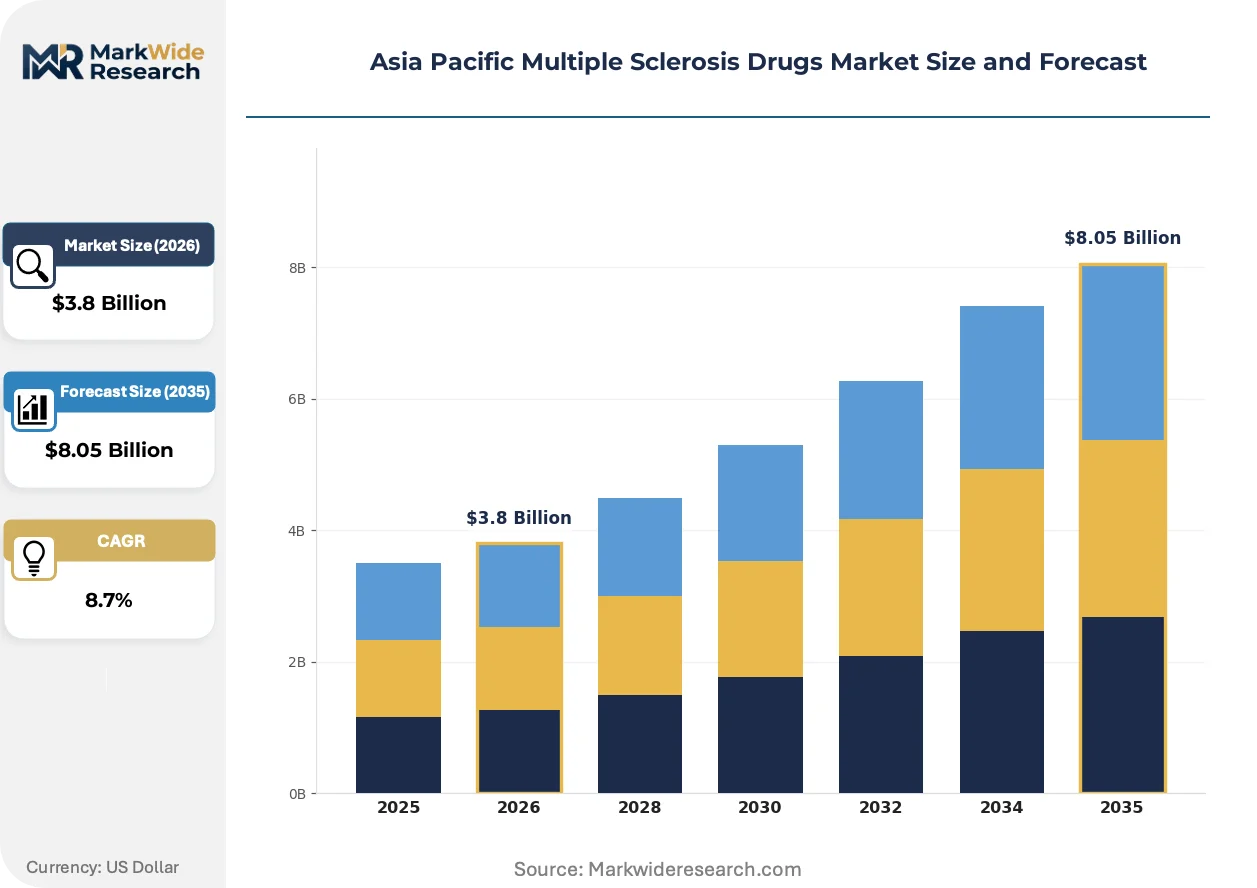
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Immunomodulators, Corticosteroids, Monoclonal Antibodies, Antineoplastics Therapy Area: Relapsing-Remitting, Secondary-Progressive, Primary-Progressive, Clinically Isolated Syndrome End User: Hospitals, Clinics, Outpatient Facilities, Homecare Administration Route: Oral, Injectable, Intravenous, Transdermal |
| Companies Covered | Biogen, Novartis AG, F. Hoffmann-La Roche Ltd, Sanofi, Teva Pharmaceutical Industries Ltd., Pfizer Inc., Bristol-Myers Squibb Company, AbbVie Inc., Bayer AG, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Multiple Sclerosis Drugs Market Trends and Innovations
Biologics manufacturing and patient access models are undergoing simultaneous transformation as cold-chain capabilities expand and regulatory frameworks mature across the Asia Pacific region.
Subcutaneous injection devices are miniaturizing administration burden for relapsing-remitting MS patients. Japanese and Australian hospital systems are adopting autoinjector platforms at accelerating rates. This technology compression is enabling therapy initiation in community clinic settings previously restricted to tertiary infusion centers.
PMDA's 2023 revision to biologics post-approval change management protocols has reduced regulatory friction for manufacturing process modifications. Sponsors can now implement site transfers and scale-up changes with abbreviated notification rather than full variation applications. Multinational manufacturers are consolidating regional supply around single-source production to exploit this streamlined pathway.
Neurology departments are unbundling diagnostic workup from ongoing therapy management, creating distinct purchasing centers for MRI services, lumbar puncture analysis, and drug procurement. Australian public hospital networks have pioneered this separation most aggressively, with separate tender processes now running for imaging versus pharmaceutical budgets. This organizational split is compressing vendor influence over the full patient journey.
Asia Pacific Multiple Sclerosis Drugs Market Segmentation
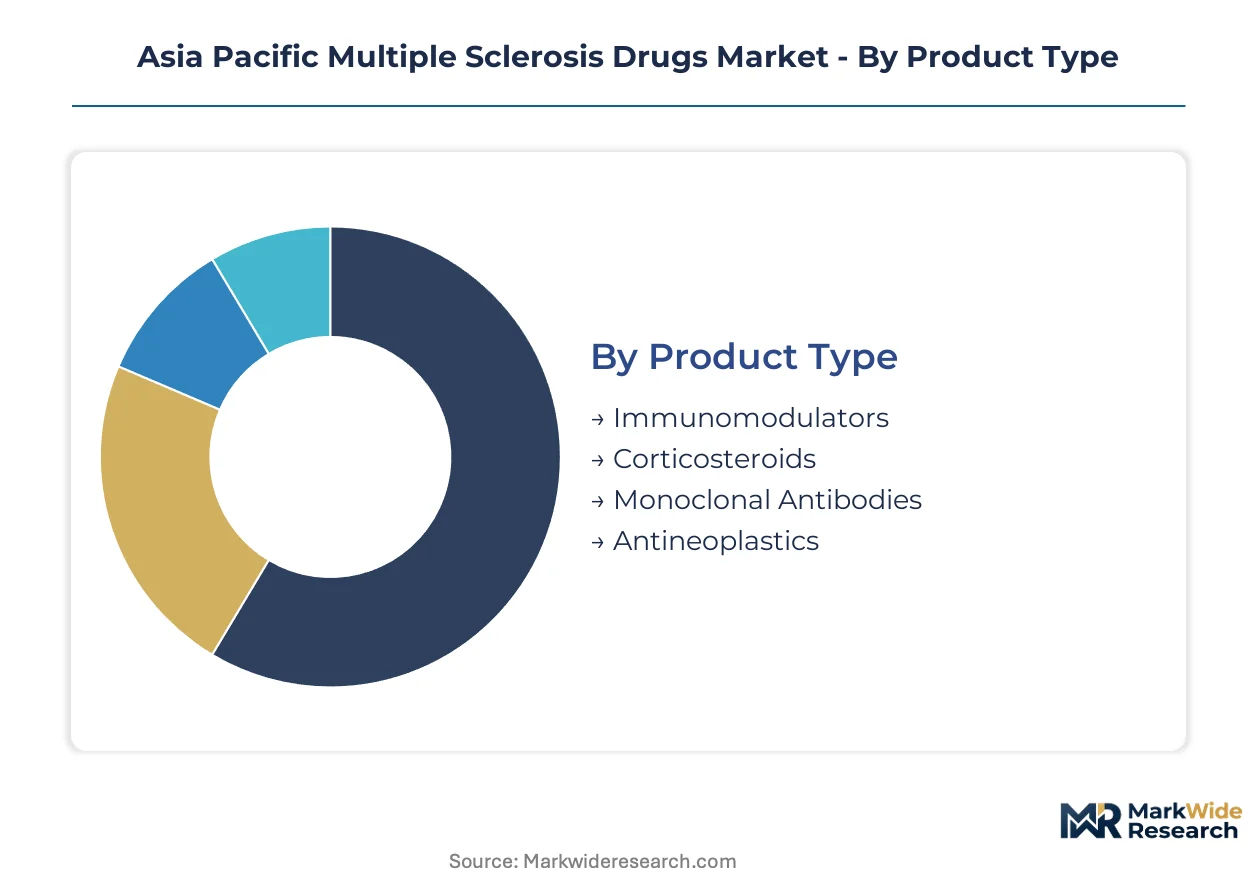
MS drug segmentation in Asia Pacific tracks reimbursement eligibility, cold-chain requirements, and neurologist prescribing authority across divergent healthcare systems. Category boundaries reflect where payers draw coverage lines and where manufacturers can deploy field forces efficiently.
Product Type:
Margin pools concentrate in biologics requiring sterile manufacturing and temperature-controlled distribution, while small-molecule categories compete on pharmacy benefit manager placement.
- Immunomodulators:These agents modulate T-cell and B-cell activity to reduce autoimmune-mediated CNS inflammation. Demand clusters in Japanese and Australian hospital formularies where interferon-beta and glatiramer acetate retain broad reimbursement despite oral alternatives. PMDA's streamlined biosimilar pathways are accelerating follow-on entry.
- Monoclonal Antibodies:Engineered immunoglobulins targeting CD20, integrin, or IL-2 receptor pathways require intravenous or subcutaneous administration. Seoul and Shanghai infusion centers are expanding capacity for natalizumab and ocrelizumab protocols as neurologist referral networks mature. Cold-chain integrity at 2-8°C constrains penetration outside major metros.
- Corticosteroids:Acute relapse management agents prescribed for short-course pulse therapy.
- Antineoplastics:Cytotoxic agents reserved for aggressive progressive phenotypes with limited therapeutic alternatives.
Immunomodulators hold installed capacity. Monoclonal Antibodies is rotating up the share rankings.
Therapy Area:
Prescription volumes track diagnostic coding specificity and MRI reimbursement policies that determine how early patients enter disease-modifying protocols.
- Relapsing-Remitting:Characterized by discrete inflammatory episodes with partial recovery, this phenotype captures the majority of diagnosed cases. Australian and South Korean neurologists initiate disease-modifying therapy earliest, supported by public reimbursement for first-line agents. Diagnostic criteria harmonization through McDonald guidelines is reducing regional variation.
- Secondary-Progressive:Follows an initial relapsing course with steady neurological decline independent of discrete attacks. Tertiary hospitals in Tokyo and Sydney are building dedicated progressive MS clinics as patient survival extends. Siponimod and other sphingosine modulators are gaining formulary traction.
- Primary-Progressive:Continuous disability accumulation from symptom onset without relapsing history.
- Clinically Isolated Syndrome:Single demyelinating event meeting MRI dissemination criteria for early intervention consideration.
Relapsing-Remitting dominates prescription volumes. Secondary-Progressive is climbing the fastest as diagnostic thresholds lower.
End User:
Site-of-care decisions hinge on infusion infrastructure availability, reimbursement for facility fees, and patient mobility constraints across aging demographics.
- Hospitals:Tertiary neurology departments anchor MS care through diagnostic workup, acute relapse management, and biologic infusion. Japan's university hospitals and Australia's public hospital networks maintain the deepest specialist rosters. Separate tender processes for imaging versus pharmaceutical budgets are fragmenting vendor influence.
- Homecare:Self-injectable platforms and remote monitoring enable therapy continuation outside institutional settings. Australian and Japanese patients with lower out-of-pocket burdens are adopting autoinjector devices at accelerating rates. This shift extends addressable geography beyond infusion center catchment areas.
- Clinics:Community neurology practices managing stable patients on oral or injectable regimens.
- Outpatient Facilities:Dedicated infusion centers and day hospitals for biologic administration.
Hospitals retain the majority of biologic infusion volume. Homecare is gaining share fastest as device technology compresses administration burden.
Administration Route:
Route selection intersects with patient preference, payer step-therapy requirements, and cold-chain logistics feasibility in dispersed geographies.
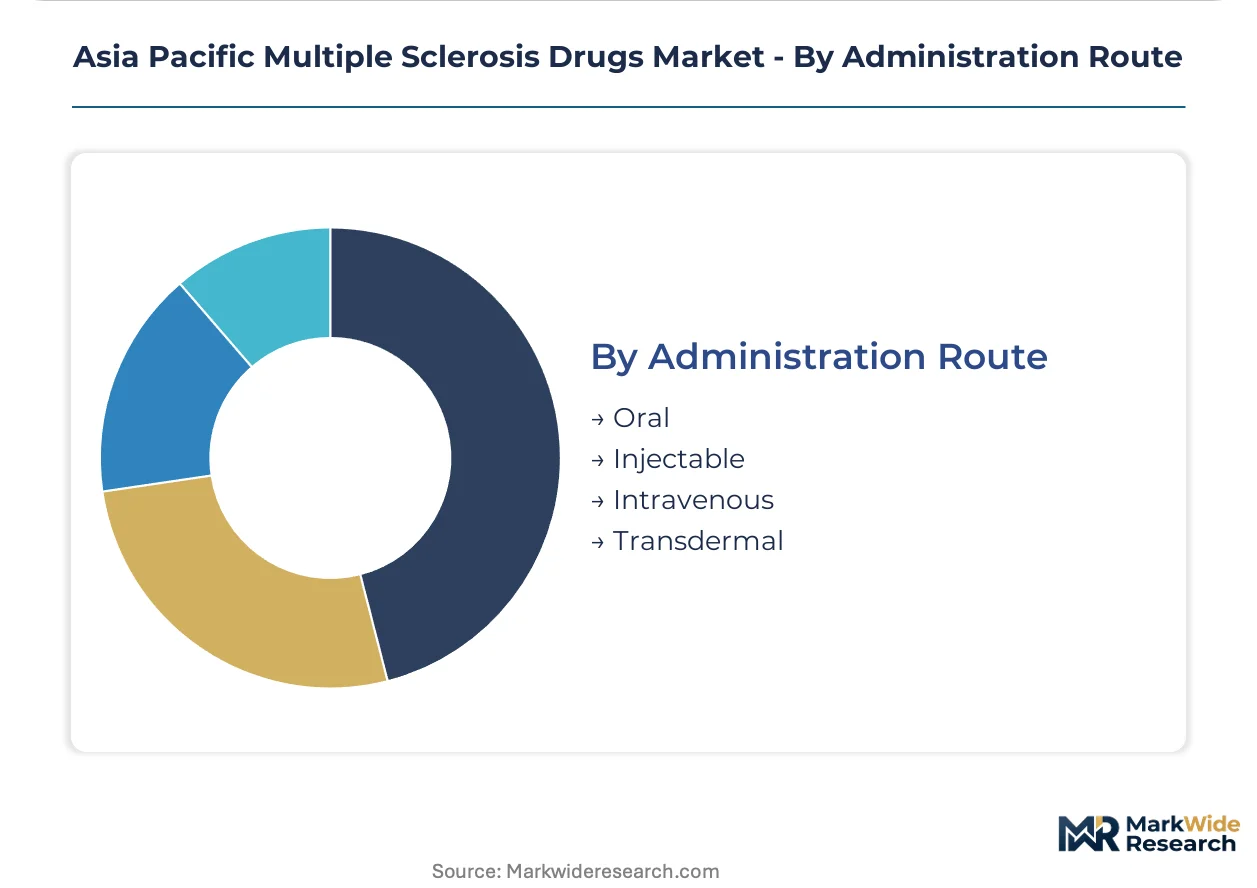
- Injectable:Subcutaneous and intramuscular delivery dominates current volume through interferon and glatiramer platforms. South Korean and Taiwanese hospital systems maintain substantial prefilled syringe and autoinjector procurement. Self-administration training programs reduce nursing burden.
- Oral:Small-molecule immunomodulators eliminate injection burden and enable pharmacy-based dispensing. Fingolimod, dimethyl fumarate, and teriflunomide are capturing disproportionate patient preference where copayment differentials favor non-biologics. China's urban pharmacies are expanding specialty dispensing capacity.
- Intravenous:Hospital-based infusion required for monoclonal antibodies and some high-dose protocols.
- Transdermal:Emerging delivery platforms for continuous symptom management agents.
Injectable holds installed capacity. Oral is rotating up the share rankings as pharmacy networks expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Neurologist prescribing authority concentrates in tertiary hospital clusters across Japan, Australia, and South Korea where reimbursement frameworks for disease-modifying therapies are most mature. Patient access gaps widen across Southeast Asian logistics networks where cold-chain infrastructure at 2-8°C remains inconsistent outside major metropolitan hubs.
Japan
PMDA's streamlined biosimilar approval pathways accelerate competitive entry for follow-on biologics. The 2023 revision to post-approval change management protocols reduced regulatory friction for manufacturing modifications. Tokyo's university hospital networks anchor the deepest specialist rosters and maintain separate tender processes for imaging versus pharmaceutical procurement.
Australia
TGA's compressed biosimilar timelines expand patient access through the Therapeutic Goods Administration's expedited pathways. Public hospital networks have pioneered unbundling diagnostic workup from ongoing therapy management. Sydney and Melbourne tertiary neurology departments drive protocol adoption through dedicated progressive MS clinics.
South Korea
MFDS enforces stability-testing requirements that diverge from neighboring regulators, fragmenting regional launch timelines. The National Health Insurance Service expanded formulary coverage for second-line therapies, reducing out-of-pocket burdens. Seoul's infusion centers are building capacity for monoclonal antibody protocols as referral networks mature.
China
NMPA tightened pharmacovigilance reporting obligations for imported biologics, creating documentation barriers for first-time entrants. Urban metros in Shanghai and Beijing are expanding dedicated monoclonal antibody infusion capacity. Pharmacy networks in tier-one cities are building specialty dispensing infrastructure for oral immunomodulators.
India
CDSCO's evolving biosimilar guidelines reshape competitive dynamics as originator molecules approach patent expiry. Domestic producers are positioning to capture share in a market where specialist neurologist scarcity concentrates diagnosis in Mumbai, Delhi, and Bangalore hospital clusters. Cold-chain gaps constrain biologics penetration outside major urban corridors.
Asia Pacific Multiple Sclerosis Drugs Market Competitive Landscape
Player mix skews toward integrated pharmaceutical conglomerates with established biologics manufacturing networks and deep hospital system relationships. Market structure concentrates around sponsors capable of sustaining sterile production certification and temperature-controlled distribution across fragmented regulatory jurisdictions. Two strategic archetypes dominate: Basel-headquartered multinationals leveraging centralized manufacturing for regional supply continuity, and research-intensive firms anchoring positions through monoclonal antibody specialization. Competitive moves center on manufacturing consolidation around single-source production and autoinjector platform adoption to compress administration burden.
Among the integrated pharmaceutical conglomerates, Novartis AG and F. Hoffmann-La Roche Ltd exemplify the manufacturing-network archetype, while Biogen occupies a position within the research-intensive cluster focused on neurologist relationship infrastructure. These three entities represent the dominant competitive anchors in a market where sterile biologics production capability and cold-chain logistics mastery determine eligible participation.
| Leading Market Players |
|---|
| Biogen |
| Novartis AG |
| F. Hoffmann-La Roche Ltd |
| Sanofi |
| Teva Pharmaceutical Industries Ltd. |
| Pfizer Inc. |
| Bristol-Myers Squibb Company |
| AbbVie Inc. |
| Bayer AG |
| Others |
Pricing and Supply Chain Analysis
Ninety-day cold-chain inventory buffers at 2-8°C anchor pricing power for sterile biologics manufacturers serving Japanese and Australian hospital networks, while Southeast Asian logistics gaps force originator sponsors to absorb distribution cost premiums that compress net realized prices outside metro corridors.
Pricing Analysis
Cost-plus contracts with active pharmaceutical ingredient indexation dominate procurement between multinational sponsors and Australian public hospital networks. Pricing stratifies across originator biologics, designated biosimilars, and follow-on non-comparable products based on PMDA and TGA interchangeability designations. Pricing pressure stems from South Korea's National Health Insurance Service reference pricing for second-line therapies, which compresses margins for non-preferred molecules. Price-sensitive buyers cluster in Indian tertiary hospitals where out-of-pocket burdens drive preference for domestic biosimilar alternatives, while Japanese university hospitals exhibit lowest sensitivity due to protected reimbursement bands for innovator products.
Supply Chain Analysis
Switzerland and Singapore anchor sterile fill-finish capacity for monoclonal antibodies distributed across Asia Pacific markets. Active pharmaceutical ingredients for interferon-beta and glatiramer acetate draw from Chinese and Indian fermentation facilities, while CD20-targeting monoclonal antibodies rely on mammalian cell culture production tethered to Basel-based manufacturing networks. Single-source vulnerability concentrates in temperature-controlled distribution lanes serving Australian and Japanese island geographies, where customs clearance delays risk cold-chain excursions. Distribution runs through hospital-centric direct channels for infused biologics, with pharmacy wholesale networks handling oral small-molecule dispensing in urban Chinese and South Korean markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Device-led service models represent the fastest-expanding revenue layer in this market, with autoinjector training programs and remote patient monitoring subscriptions outpacing molecule-specific revenue growth across Australian and Japanese homecare segments.
For Market Incumbents: Shield formulary position in Tokyo and Sydney tertiary hospitals by deepening neurologist relationship infrastructure and accelerating autoinjector platform adoption before biosimilar entry erodes originator pricing power. Prioritize backward integration into cold-chain distribution to capture margin currently lost to third-party logistics providers in Southeast Asian expansion corridors. For New Entrants and Emerging Players: Anchor in Indian biosimilar manufacturing by qualifying CDSCO-compliant production ahead of originator patent cliffs for glatiramer acetate and interferon-beta. Target South Korean outpatient infusion centers as the most penetrable site-of-care segment, leveraging MFDS abbreviated approval pathways for designated biosimilars to undercut reference product tenders. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because sterile biologics manufacturing certification scarcity collapses the eligible supplier base to a handful of qualified contract organizations. Watch PMDA biosimilar interchangeability determinations as the signal for when originator revenue cliffs accelerate and distressed manufacturing assets become available.| Strategic Initiative | Industry Significance |
|---|---|
| Autoinjector Platform Adoption | Compresses administration burden and extends therapy initiation into community clinic settings. |
| Biosimilar Manufacturing Scale-Up | Positions domestic producers to capture share as PMDA and TGA streamline approval pathways. |
| Cold-Chain Distribution Investment | Enables biologics penetration beyond Tokyo, Seoul, and Sydney metro hospital clusters. |
| Remote Patient Monitoring Development | Creates recurring revenue layer through device subscription models in homecare segments. |
| Neurologist Relationship Infrastructure | Secures protocol adoption in tertiary hospitals where prescribing authority concentrates. |
Research Methodology
A standing panel of drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers provided ongoing calibration throughout the research process. Primary interviews with these stakeholders combined with secondary validation against PMDA approval databases, TGA registration records, ClinicalTrials.gov protocols, and South Korean National Health Insurance Service reimbursement bulletins. Bottom-up patient-volume modeling and top-down revenue triangulation cross-checked segmentation outputs across the analysis window.
Consistency checks validated volume and value outputs against external benchmarks including hospital procurement database trends and GPO contract disclosures. The analytical framework modeled treatment line, administration route, regional regulatory cluster, and cold-chain logistics feasibility across the projection horizon. CAGRs derived from patient population growth, therapy penetration rates, and price trajectory assumptions anchored in payer policy documentation.
Material uncertainties — regulatory approval delays, biosimilar interchangeability determinations, and cold-chain infrastructure investment timing — sit outside the modeled envelope. Forecasts reflect assumptions about reimbursement stability and neurologist workforce expansion that could revise with policy shifts or training pipeline disruptions. Recalibration cycles align with material shifts in national formulary updates and manufacturing site approval decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global RFID in Pharmaceuticals Market
Pharmaceuticals
Wujibaifeng Pills Market
Pharmaceuticals
Global Divalproex Sodium Market
Pharmaceuticals
Asia-Pacific Meglitinide Market
Pharmaceuticals
Global Lidocaine Transdermal Patch Market
Pharmaceuticals
Acetaminophen Market
Pharmaceuticals
Adapalene Market
Pharmaceuticals
Ginkgo Leaf Extract and Dipyridamole Injection Market
Pharmaceuticals
Complex Injectable Market
Pharmaceuticals
Structured Product Label Management Market
Pharmaceuticals
Zoldonat Injection Market
Pharmaceuticals
Global Fluorouracil (5FU) Market
Pharmaceuticals
Global Calcitonin Salmon Market
Pharmaceuticals
Germany Pneumococcal Vaccines Market
Pharmaceuticals
Global Hepatitis a Vaccine Market
Pharmaceuticals
Anti-Vascular Endothelial Growth Factor Therapeutics Market