
 Global Muscle Relaxant Drugs Market | 2026-2036
Global Muscle Relaxant Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Global Muscle Relaxant Drugs Market Foresight
Fixed-dose combination bundling of muscle relaxants with analgesics is realigning how hospital pharmacies evaluate procurement contracts. Pfizer leverages its manufacturing scale to supply bundled anesthesia portfolios across integrated delivery networks. Teva Pharmaceuticals anchors its position through generic neuromuscular blocker production. Ipsen specializes in botulinum toxin formulations for spasticity, occupying a differentiated therapeutic niche.
Muscle relaxant drugs are pharmacological agents that reduce skeletal muscle tone through either neuromuscular junction blockade or central nervous system depression, with formulations spanning oral tablets, intravenous solutions, and intramuscular injections designed for perioperative paralysis or chronic spasticity management. Spasmolytics dominate current prescription volume due to their broad application across orthopedic and neurological conditions, while neuromuscular blockers command concentrated margin pools in surgical settings. The intravenous route leads in acute care revenue contribution, though transdermal delivery systems represent the fastest-growing configuration as manufacturers seek to extend therapy into outpatient pain management.
The FDA oversees approval and post-market surveillance of muscle relaxant products in the United States, while the EMA governs centralized marketing authorization across European Union member states and the NMPA regulates domestic production and importation in China. These frameworks shape demand through bioequivalence requirements for generics, pharmacovigilance obligations for long-acting formulations, and manufacturing quality standards that determine market access eligibility. Stakeholders must monitor evolving regulatory divergence between major jurisdictions as they evaluate portfolio allocation and facility certification strategies.
Market Dynamics
Fixed-dose combination bundling is restructuring procurement economics across hospital systems, forcing standalone neuromuscular blocker suppliers to integrate with anesthesia portfolios or accept margin compression in integrated delivery network contracts.
Growth Catalysts
- Ambulatory Surgical Center Expansion:United States outpatient facility construction is creating concentrated demand for rapid-onset, short-duration neuromuscular blockers that support same-day discharge protocols.
- FDA Streamlined Generic Pathways:The agency's abbreviated approval processes for injectable generics are accelerating competitive entry and expanding formulary options for hospital pharmacies.
- Botulinum Toxin Therapeutic Applications:Spasticity management protocols in neurological rehabilitation centers are extending botulinum toxin use beyond cosmetic indications into chronic movement disorder treatment.
Market Restraints
- Active Pharmaceutical Ingredient Concentration:China dominates synthesis of key neuromuscular blocker precursors, creating supply vulnerability for Western formulators dependent on single-source intermediates.
- REACH Compliance Burden:European chemical registration requirements for novel excipients impose multi-year timelines and substantial documentation costs on transdermal delivery system developers.
- Oral Spasmolytic Substitution:Centrally acting muscle relaxants face displacement by non-pharmacological physical therapy protocols in orthopedic postoperative care pathways.
Strategic Opportunities
- Japan's Aging Demographics:The country's expanding geriatric population and PMDA expedited review pathways for spasticity therapeutics create entry potential for long-acting botulinum toxin formulations.
- Transdermal Delivery Convergence:Microneedle array technology combined with iontophoresis control systems is enabling outpatient migration of chronic spasmolytic therapy from clinic injection to home administration.
- India PLI Scheme Incentives:The government's production-linked incentive framework for pharmaceutical manufacturing is attracting contract development and manufacturing organization investment for generic neuromuscular blocker production.
Industry Challenges
- Pharmacovigilance Specialist Scarcity:Post-market surveillance requirements for long-acting neuromuscular blockers demand rare combinations of clinical pharmacology expertise and regulatory documentation capability that outstrip available talent pools.
- Cold Chain Reconfiguration:Temperature-sensitive biologic muscle relaxant distribution requires capital-intensive infrastructure upgrades as hospital systems consolidate procurement through centralized distribution centers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Muscle Relaxant Drugs Market |
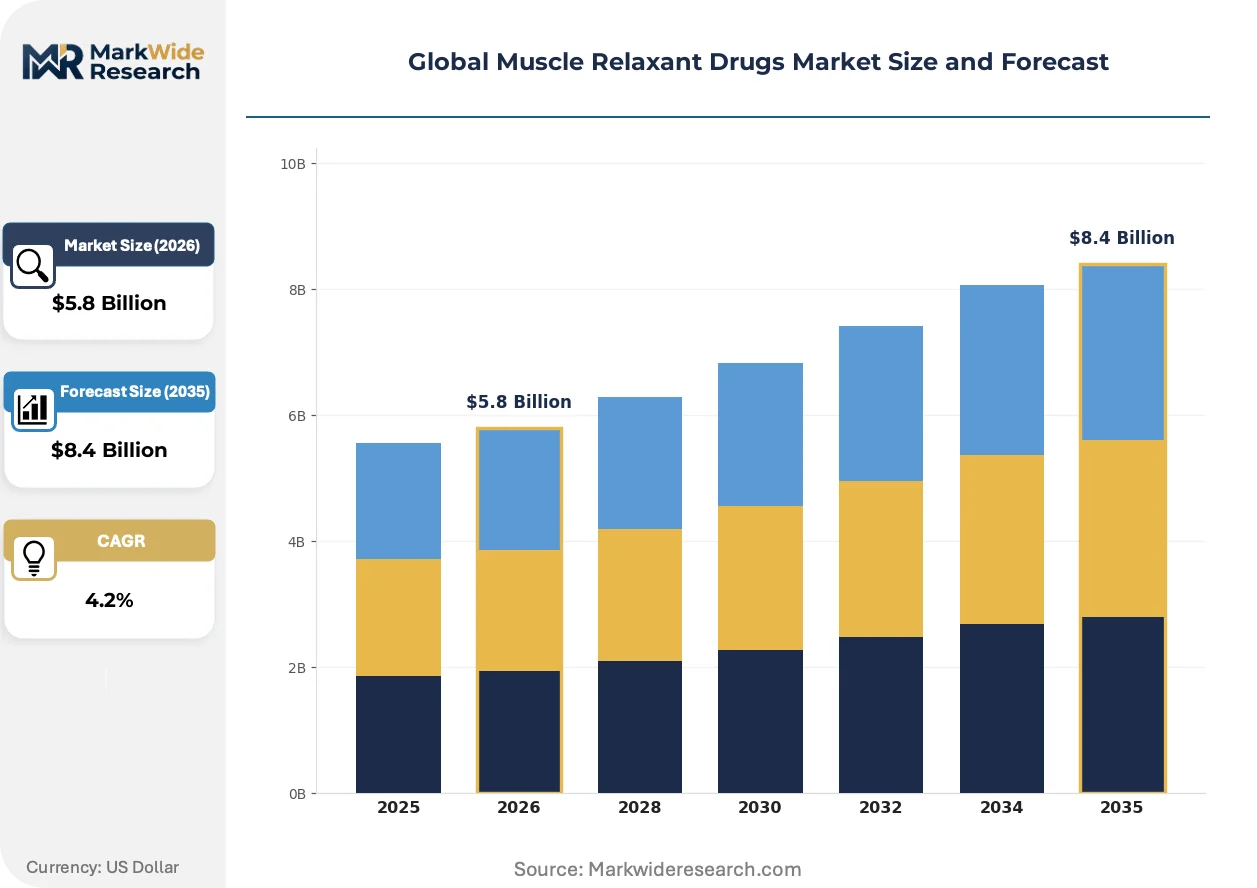
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $8.4 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Neuromuscular Blockers, Spasmolytics, Benzodiazepines, Others Therapy Area: Orthopedic Conditions, Neurological Disorders, Postoperative Care, Pain Management End User: Hospitals, Ambulatory Surgical Centers, Rehabilitation Facilities, Home Care Providers Route of Administration: Oral, Intravenous, Intramuscular, Topical, Transdermal |
| Companies Covered | Pfizer, Teva Pharmaceuticals, Johnson & Johnson, Novartis, Mallinckrodt, Ipsen, Amneal Pharmaceuticals, Zydus Lifesciences, Endo Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Muscle Relaxant Drugs Market Shifts & Advancements
Formulation science and delivery mechanism advances are fragmenting traditional administration settings, enabling therapeutic migration from inpatient surgical suites toward outpatient and home-based care environments.
Targeted microsphere encapsulation of neuromuscular blocking agents is decentralizing acute paralysis management from centralized operating theaters toward ambulatory procedure rooms and office-based surgery suites. Regional anesthesia departments in United States integrated delivery networks are adopting these depot formulations to support same-day orthopedic procedures. The technology is compressing recovery timelines and reallocating revenue from inpatient facility fees toward physician-office reimbursement structures.
EMA's Medical Device Regulation reclassification of drug-device combination products is forcing botulinum toxin manufacturers to resubmit delivery system components for conformity assessment. European spasticity treatment centers face supply interruptions as legacy autoinjector designs undergo renewed technical documentation review. German rehabilitation clinics are diversifying supplier relationships to mitigate approval timeline uncertainty.
Hospital pharmacy consortia are consolidating muscle relaxant procurement through single-source anesthesia bundle contracts that unbundle traditional pharmaceutical purchasing from equipment and service agreements. United States academic medical centers are leading this aggregation, leveraging volume commitments to extract performance guarantees from integrated anesthesia portfolio suppliers. The shift concentrates negotiating leverage with three to five national purchasing organizations.
Global Muscle Relaxant Drugs Market Segmentation
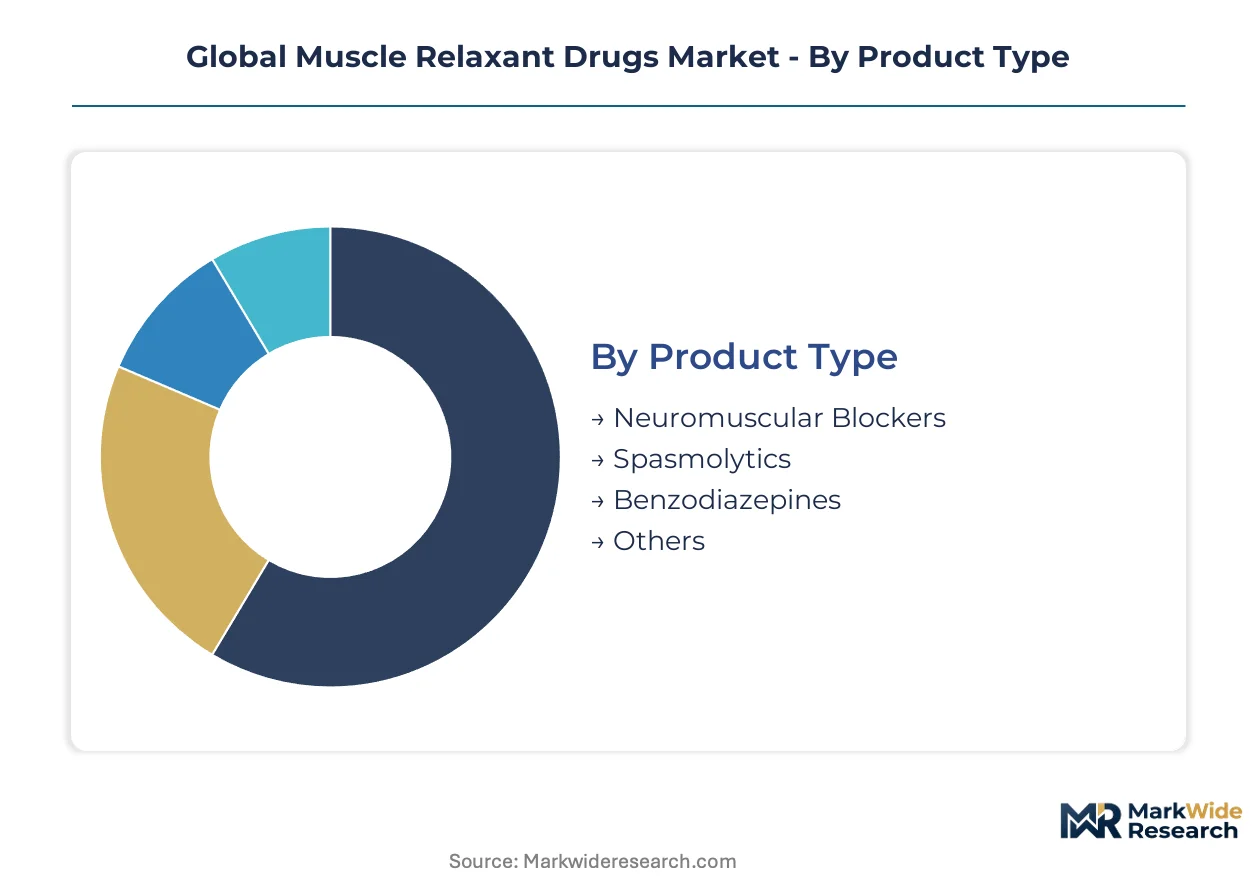
Segmentation in muscle relaxant drugs reveals divergent margin structures across acute surgical and chronic therapeutic settings. Procurement patterns split between high-volume hospital formulary contracts and specialty pharmacy distribution for long-acting formulations.
Product Type:
Neuromuscular blockers command surgical premium pricing while spasmolytics drive prescription volume through primary care channels.
- Neuromuscular Blockers:These agents induce skeletal muscle paralysis through acetylcholine receptor antagonism at the neuromuscular junction, enabling intubation and surgical immobility. Demand concentrates in United States ambulatory surgical centers where rapid-onset, short-duration profiles support same-day discharge protocols and minimize post-anesthesia recovery unit stays.
- Spasmolytics:Centrally acting agents reduce muscle tone through GABA receptor modulation or direct spinal cord depression without paralysis. Prescription volume clusters in orthopedic postoperative pathways across German and Japanese hospital systems where multimodal pain protocols prioritize non-opioid muscle relaxation.
- Benzodiazepines:GABA-A receptor agonists with muscle relaxant properties used adjunctively in spasticity management.
- Others:Direct-acting skeletal muscle relaxants and novel mechanism agents including dantrolene for malignant hyperthermia prophylaxis.
Today's leader: Neuromuscular Blockers. Tomorrow's challenger: Spasmolytics.
Therapy Area:
Orthopedic applications generate consistent volume while neurological indications attract specialty pricing and orphan drug designations.
- Orthopedic Conditions:Muscle relaxants address acute spasms from fractures, dislocations, and degenerative spine disease. United States integrated delivery networks bundle these agents with joint replacement protocols, capturing bundled payment incentives that reward reduced length-of-stay metrics.
- Neurological Disorders:Chronic spasticity from multiple sclerosis, cerebral palsy, and stroke sequelae requires long-acting botulinum toxin or oral baclofen therapy. Japanese rehabilitation centers and German neurorehabilitation clinics drive demand for PMDA- and EMA-approved formulations with established reimbursement pathways.
- Postoperative Care:Perioperative muscle relaxation supports mechanical ventilation and prevents shivering in cardiac and abdominal surgery recovery.
- Pain Management:Adjunctive use in chronic lower back pain and fibromyalgia protocols, though facing displacement by non-pharmacological interventions in United States VA health system formularies.
Orthopedic volume sustains near-term revenue. Neurological specialty applications carry the steepest expansion trajectory.
End User:
Hospital procurement consolidation favors bundled anesthesia portfolios while ambulatory migration creates demand for simplified administration profiles.
- Hospitals:Academic medical centers and community hospital systems purchase through group purchasing organizations that negotiate anesthesia bundle contracts spanning neuromuscular blockers, reversal agents, and infusion pumps. United States health system consolidation concentrates volume with three to five national purchasing organizations.
- Ambulatory Surgical Centers:Freestanding outpatient facilities prioritize rapid reversal and minimal residual paralysis to achieve same-day discharge benchmarks. Medicare reimbursement shifts toward site-neutral payments accelerate United States facility construction and formulary standardization.
- Rehabilitation Facilities:Long-term care hospitals and skilled nursing facilities administer oral and intrathecal spasmolytics for chronic spasticity management.
- Home Care Providers:Visiting nurse services and home infusion specialists deliver botulinum toxin and baclofen pump maintenance for patients with severe mobility limitations.
Hospital systems anchor current procurement economics. Ambulatory surgical centers are gaining share fastest as procedural volume migrates outpatient.
Route of Administration:
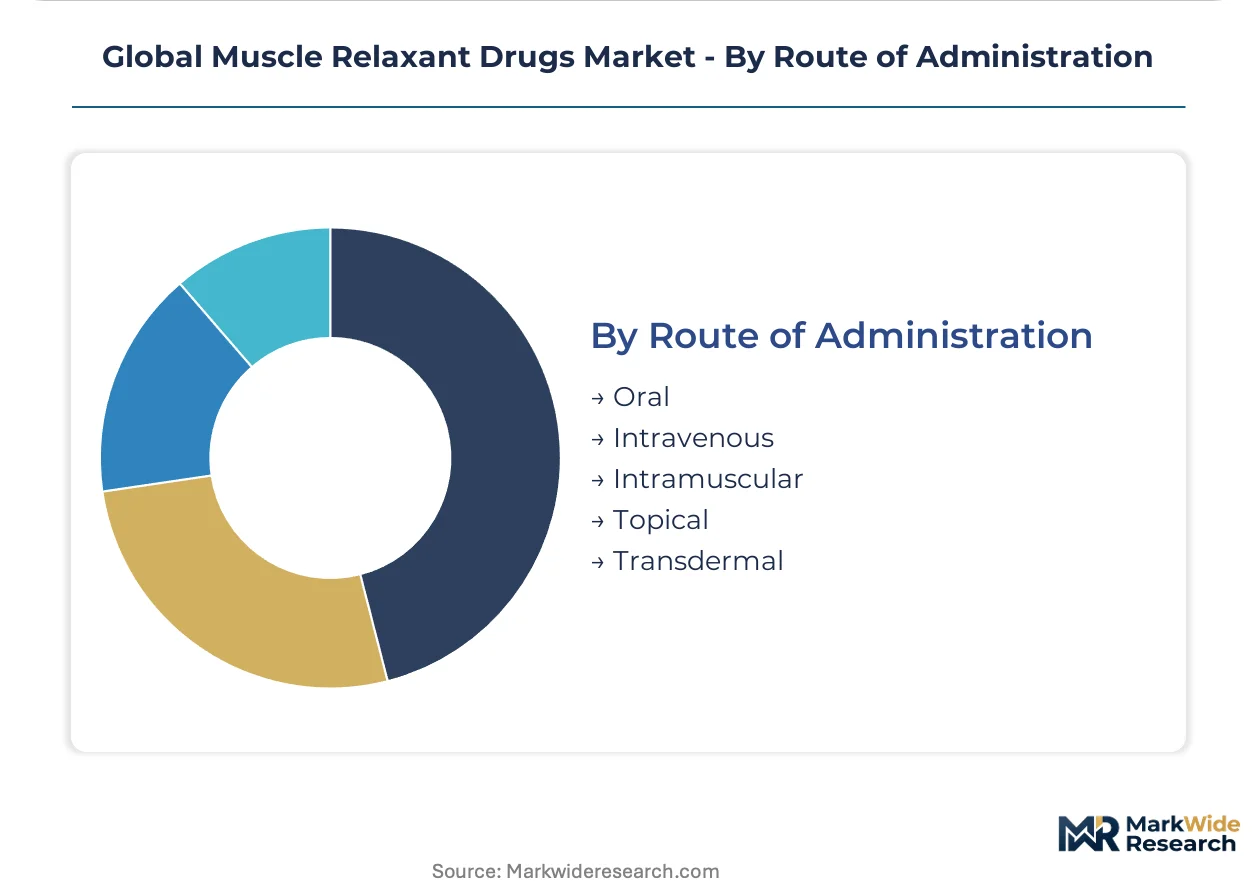
Intravenous delivery dominates acute care revenue while transdermal innovation targets chronic therapy adherence and home administration.
- Oral:Tablets and capsules of cyclobenzaprine, tizanidine, and methocarbamol dominate primary care prescribing for nonspecific back pain. United States retail pharmacy chains process high volumes with generic substitution rates exceeding ninety percent.
- Intravenous:Rocuronium, vecuronium, and succinylcholine solutions enable precise intraoperative paralysis control. Anesthesiology departments in United States and German hospital systems specify these agents in standardized anesthesia protocols with automated dispensing cabinet integration.
- Intramuscular:Depot formulations and emergency muscle relaxation for acute dystonic reactions.
- Topical:Limited application for localized muscle pain with minimal systemic absorption.
- Transdermal:Microneedle arrays and iontophoresis systems under development seek to convert chronic spasmolytic therapy from clinic injection to patient-administered home care, targeting Japanese aging demographics and United States Medicare home health expansion.
Intravenous administration holds current revenue concentration. Transdermal delivery systems represent the most significant configuration shift ahead.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German pharmaceutical houses pioneered modern neuromuscular blocker synthesis during the mid-twentieth century, establishing the industrial foundation that now spans three continents. Today, formulation expertise clusters in discrete national markets with divergent regulatory pathways and procurement structures.
United States
Ambulatory surgical center construction accelerates demand for rapid-onset, short-duration agents that support same-day discharge protocols. The FDA's streamlined approval pathways for generic injectables expand formulary options for hospital pharmacy consortia. Integrated delivery networks in Texas and Florida consolidate procurement through anesthesia bundle contracts that span neuromuscular blockers, reversal agents, and infusion equipment.
Germany
Orthopedic postoperative pathways across Bavarian and North Rhine-Westphalian hospital systems prioritize multimodal pain protocols with non-opioid muscle relaxation. EMA centralized marketing authorization governs botulinum toxin distribution while REACH compliance requirements burden transdermal delivery system developers. Neurorehabilitation clinics in Berlin-Brandenburg diversify supplier relationships to mitigate Medical Device Regulation resubmission uncertainty for legacy autoinjector designs.
Japan
Expanding geriatric populations and stroke sequelae drive demand for long-acting spasticity therapeutics in Kanto and Kansai metropolitan rehabilitation centers. PMDA expedited review pathways for neurological indications attract botulinum toxin portfolio investment. Manufacturing investment concentrates in the Chubu region around Nagoya, where pharmaceutical contract development organizations scale production for Asia-Pacific distribution.
China
Domestic synthesis of key neuromuscular blocker precursors dominates global active pharmaceutical ingredient supply, creating concentration vulnerability for Western formulators. NMPA regulations on domestic production and importation shape market access eligibility for multinational portfolios. Yangtze River Delta pharmaceutical clusters in Shanghai and Jiangsu province anchor contract manufacturing organization capacity for generic injectable exports.
India
Government production-linked incentive schemes attract pharmaceutical manufacturing investment for generic neuromuscular blocker production. CDSCO bioequivalence requirements for generics determine market access timelines for domestic and imported formulations. Gujarat and Maharashtra industrial corridors host expanding contract development and manufacturing organization facilities serving European and North American procurement networks.
Global Muscle Relaxant Drugs Market Competitive Landscape
The competitive structure tilts toward diversified pharmaceutical conglomerates with anesthesia portfolio breadth. Three to five national purchasing organizations in the United States concentrate negotiating leverage with integrated suppliers. Market participants sort into archetypes: diversified conglomerates bundling anesthesia portfolios, generic specialists scaling injectable production, and botulinum toxin niche players occupying neurological rehabilitation channels. Dominant competitive moves include fixed-dose combination bundling to secure hospital formulary placement and transdermal delivery system development to capture outpatient migration.
Within the diversified conglomerate tier, Pfizer leverages manufacturing scale across integrated delivery network contracts. Teva Pharmaceuticals anchors generic neuromuscular blocker supply through high-volume injectable production. Ipsen occupies a differentiated therapeutic position in botulinum toxin formulations for spasticity management. These three represent the structural poles around which procurement consolidation and portfolio specialization revolve.
| Leading Market Players |
|---|
| Pfizer |
| Teva Pharmaceuticals |
| Johnson & Johnson |
| Novartis |
| Mallinckrodt |
| Ipsen |
| Amneal Pharmaceuticals |
| Zydus Lifesciences |
| Endo Pharmaceuticals |
| Others |
Supply & Pricing Matrix
Transdermal microneedle array manufacturing is compressing production costs for chronic spasmolytic delivery while simultaneously fragmenting supply relationships away from sterile injectable specialists toward polymer microfabrication foundries in Taiwan and South Korea. This dual shift is redistributing margin capture from traditional pharmaceutical formulators toward device-integrated solution providers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates originator botulinum toxin formulations from multi-source generic neuromuscular blockers and commodity oral spasmolytics. Price differentiation hinges on FDA bioequivalence certification tier and ambulatory surgical center volume commitments. Cost compression in generic injectables is intensifying because of Teva Pharmaceuticals and Zydus Lifesciences capacity expansion. Ambulatory surgical centers exhibit highest price sensitivity; academic medical centers with bundled anesthesia contracts show lowest.
Supply Chain Analysis
EMA Medical Device Regulation and FDA Quality System Regulation certifications gate entry for drug-device combination products, forcing dual-track qualification timelines on transdermal developers. Active pharmaceutical ingredient synthesis concentrates in China's Yangtze River Delta around Shanghai and Jiangsu, with secondary capacity in India's Gujarat and Maharashtra corridors. Western formulators draw from Chinese precursors for neuromuscular blockers, Indian intermediates for oral spasmolytics, and European biologics for botulinum toxin. Single-source vulnerability in Chinese precursor supply threatens continuity. Distribution runs through hospital pharmacy consortia and specialty pharmacy networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where FDA streamlined generic pathways and EMA Medical Device Regulation reclassification are accelerating competitive turnover and forcing portfolio repositioning.
For Market Incumbents: Deepen backward integration into Chinese precursor supply through joint manufacturing agreements or captive synthesis partnerships to mitigate API concentration risk. Expand transdermal delivery R&D investment to defend against oral spasmolytic displacement by non-pharmacological physical therapy protocols in orthopedic postoperative care. For New Entrants and Emerging Players: Transdermal iontophoresis control systems offer a technology-first wedge into Japanese geriatric spasticity management where PMDA expedited review pathways reduce regulatory barriers. Target India's production-linked incentive scheme for generic neuromuscular blocker manufacturing. Pursue hospital pharmacy consortia with anesthesia bundle proposals rather than standalone product pitches. For Investors and Strategic Acquirers: Valuations sit cheapest among generic injectable specialists with underutilized sterile manufacturing capacity. Long-term viability centers on formulary consolidation resilience and transdermal pipeline optionality. Watch for FDA abbreviated new drug approval acceleration as an inflection signal for generic entry timing and margin compression velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Transdermal Delivery System Development | Microneedle arrays enable patient-administered home therapy migration from clinic injection. |
| Backward Integration into API Synthesis | Captive precursor production mitigates China supply concentration vulnerability for Western formulators. |
| Anesthesia Bundle Contracting | Integrated portfolio offerings secure hospital pharmacy consortia formulary placement against standalone competitors. |
| PMDA Expedited Review Pathway Pursuit | Japan's neurological indication fast-track attracts botulinum toxin investment for aging demographic demand. |
| India PLI Scheme Manufacturing Investment | Government incentives draw CDSCO-compliant generic neuromuscular blocker capacity for export markets. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with anesthesiology department heads, hospital pharmacy directors, regulatory affairs specialists at neuromuscular blocker manufacturers, and rehabilitation clinic formulary managers with secondary validation against FDA Orange Book filings, EMA centralized marketing authorization decisions, ClinicalTrials.gov intervention studies, and CMS Medicare reimbursement schedules. Bottom-up prescription volume modeling and top-down pharmaceutical revenue triangulation anchored market sizing.
Comparable-period anchoring used historical neuromuscular blocker and spasmolytic demand patterns across the analysis window to project forward. The analytical framework modeled segmentation across product type, therapy area, end user, and route of administration dimensions. CAGRs were derived from fitted growth curves calibrated to regulatory approval velocity and ambulatory surgical center construction rates. Forecast inputs incorporated PMDA review timeline assumptions and REACH compliance cost trajectories for transdermal developers.
The model holds under stable FDA generic approval throughput and continued ambulatory surgical center reimbursement parity; deviation in China API export restrictions or EMA Medical Device Regulation enforcement intensity would shift volume and value projections. A model refresh is warranted upon material change in integrated delivery network procurement consolidation patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Ramipril Market
Pharmaceuticals
Global Azithromycin Market
Pharmaceuticals
Metaxalone Market
Pharmaceuticals
Leflunomide Market
Pharmaceuticals
Middle East and Africa Laxative Market
Pharmaceuticals
Long-Acting Monoclonal Antibodies Market
Pharmaceuticals
Unit-Dose Respiratory Medications Market
Pharmaceuticals
Preeclampsia Therapeutics Market
Pharmaceuticals
Acetylcholine Market
Pharmaceuticals
OTC Cough, Cold & Allergy Medicine Market
Pharmaceuticals
Clindamycin Palmitate Hcl Market
Pharmaceuticals
Bendamustin Market
Pharmaceuticals
Prescription Transdermal Patches Market
Pharmaceuticals
Global Hemostasis and Tissue Sealing Agents Market
Pharmaceuticals
Global Exocrine Pancreatic Insufficiency (EPI) Market
Pharmaceuticals
Global Colorectal Cancer Therapeutics Market