
 Global Vaccine Market | 2026-2036
Global Vaccine Market Size, Share, and Industry Trends Forecast 2026-2036
Global Vaccine Market Outlook
Indian contract manufacturers is rebalancing supply networks after pandemic-era concentration risks. Pfizer leverages mRNA manufacturing scale across North American and European facilities. Serum Institute of India anchors affordable supply for low-income country procurement through volume commitments. Sanofi differentiates through recombinant protein platforms in pediatric and influenza portfolios.
Vaccines comprise biologically active preparations containing attenuated pathogens, purified antigens, or nucleic acid constructs formulated to elicit protective immune responses, typically requiring adjuvants and stabilizers to maintain potency through temperature-controlled distribution. Their primary purpose is preventing infectious disease morbidity and mortality in population-level immunization programs. Messenger RNA platforms are capturing expanded development pipelines as regulatory familiarity reduces trial timelines. Live Attenuated formulations retain margin strength in established pediatric schedules despite cold-chain requirements. Government Agencies as procurement channels concentrate volume and pricing power in national tender systems.
FDA, EMA, and WHO prequalification standards collectively determine market access timelines and manufacturing compliance burdens for global suppliers. India's CDSCO and China's NMPA are tightening local clinical data requirements that reshape regional registration strategies. Stakeholders must monitor regulatory divergence between stringent authority pathways and emerging market convergence initiatives to optimize portfolio allocation and facility certification investments.
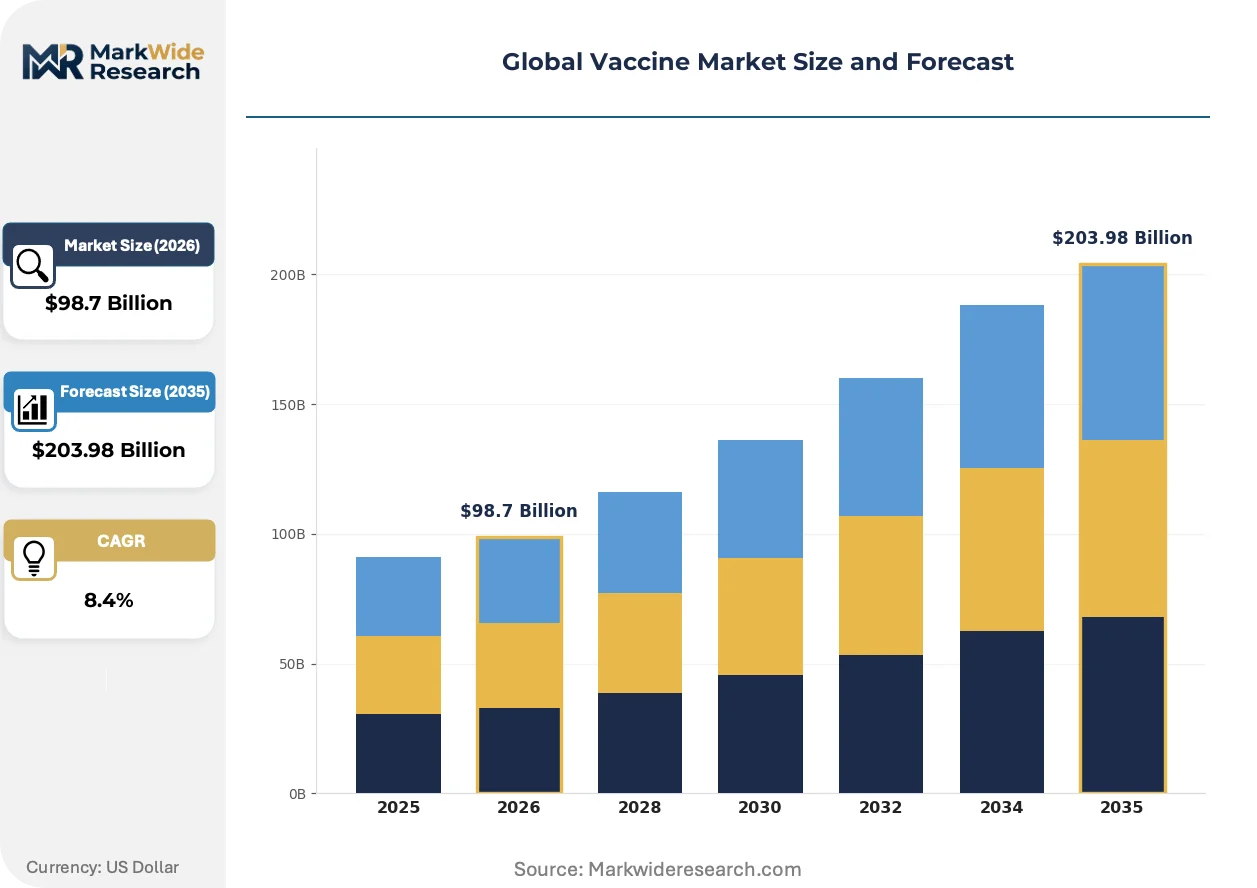
Market Dynamics
mRNA manufacturing platforms are compressing development timelines while cold-chain infrastructure investments reshape distribution economics across high-volume and low-resource settings simultaneously.
Growth Catalysts
- WHO Prequalification Expansion:Accelerated pathways for low-income country procurement are unlocking volume commitments from Gavi-eligible nations. This mechanism reduces registration duplication across multiple stringent authorities.
- India PLI Scheme:Production-linked incentives for domestic biopharmaceutical manufacturing are scaling fill-finish capacity and active pharmaceutical ingredient sourcing within the country's vaccine cluster.
- Combination Vaccine Formulations:Pentavalent and hexavalent pediatric products are reducing injection burden and cold-chain footprint for national immunization programs. These integrated products streamline logistics for health ministries.
Market Restraints
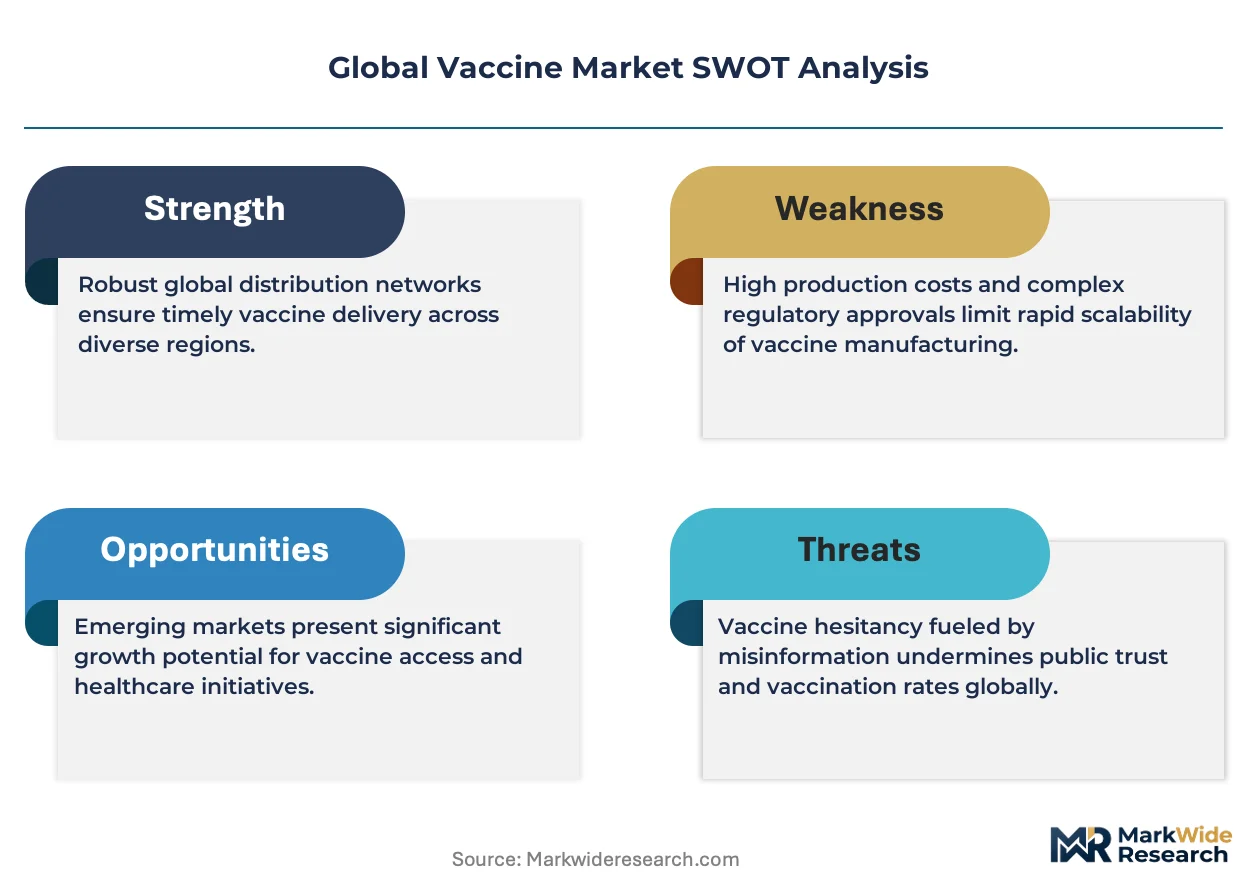
- Lipid Nanoparticle Input Concentration:Four suppliers dominate specialized lipid production for mRNA formulations, creating single-source vulnerability for novel platform scale-up.
- EMA Cold-Chain Validation Requirements:Stability documentation demands for ultra-low temperature distribution are extending registration timelines and freezing out regional manufacturers lacking validation infrastructure.
- Live Attenuated Refrigeration Dependence:Pedestal freezer requirements for measles-rubella and rotavirus products limit last-mile reach in tropical geographies with unreliable electricity.
Strategic Opportunities
- Indonesia Archipelago Distribution:Island geography creates demand for thermostable formulations and drone-enabled cold-chain bridging to replace boat-dependent supply.
- US IRA Price Negotiation Exclusion:Vaccines remain outside Medicare price-setting mechanisms, preserving premium pricing for adult immunization products relative to therapeutic categories.
- AI-Driven Antigen Design:Machine learning prediction of immunogenic epitopes is converging with synthetic biology production to compress preclinical candidate selection from months to weeks.
Industry Challenges
- Cell Culture Technician Scarcity:Mammalian and insect cell propagation expertise remains concentrated in legacy biologics hubs, constraining viral vector manufacturing expansion.
- Legacy Fill-Finish Line Retrofit:Stainless steel equipment conversion to single-use systems for multi-product flexibility demands capital deployment without guaranteed product allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Vaccine Market |
| Market Size in 2026 | $98.7 Billion |
| Market Size in 2035 | $203.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Live Attenuated, Inactivated, Subunit, Messenger RNA Administration Route: Intramuscular, Subcutaneous, Oral, Intranasal End User: Hospitals, Clinics, Pharmacies, Government Agencies Therapy Area: Infectious Diseases, Oncology, Autoimmune Disorders, Allergy |
| Companies Covered | Merck & Co., Pfizer, GSK (GlaxoSmithKline), Sanofi, Moderna, Johnson & Johnson, AstraZeneca, Serum Institute of India, Sinopharm Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Vaccine Market Strategic Shifts
Platform standardization is converging with modular manufacturing architectures to reduce facility-specific validation burdens and enable rapid product switching within shared production networks.
Self-amplifying mRNA constructs are consolidating development pipelines around reduced dose requirements and smaller manufacturing footprints. Large pharmaceutical sponsors are adopting these platforms for respiratory syncytial virus and influenza candidates. The technology is consolidating competitive advantage toward sponsors with integrated formulation and delivery device capabilities.
EMA's revised Good Manufacturing Practice Annex 1 for sterile products is mandating barrier isolation technology and continuous particulate monitoring across European manufacturing sites. Compliance investments are diverting capital from capacity expansion toward quality infrastructure. Fill-finish operators in Germany and Belgium are retrofitting isolator lines ahead of enforcement deadlines.
National tender systems are compressing supplier lists to three-to-four approved vendors per antigen category, concentrating procurement volume and extending contract durations. UNICEF's vaccine procurement pool is shifting from annual bidding to multi-year framework agreements with price adjustment mechanisms. Brazil and Nigeria are adopting similar consolidated purchasing structures for their expanded program on immunization portfolios.
Global Vaccine Market Segmentation
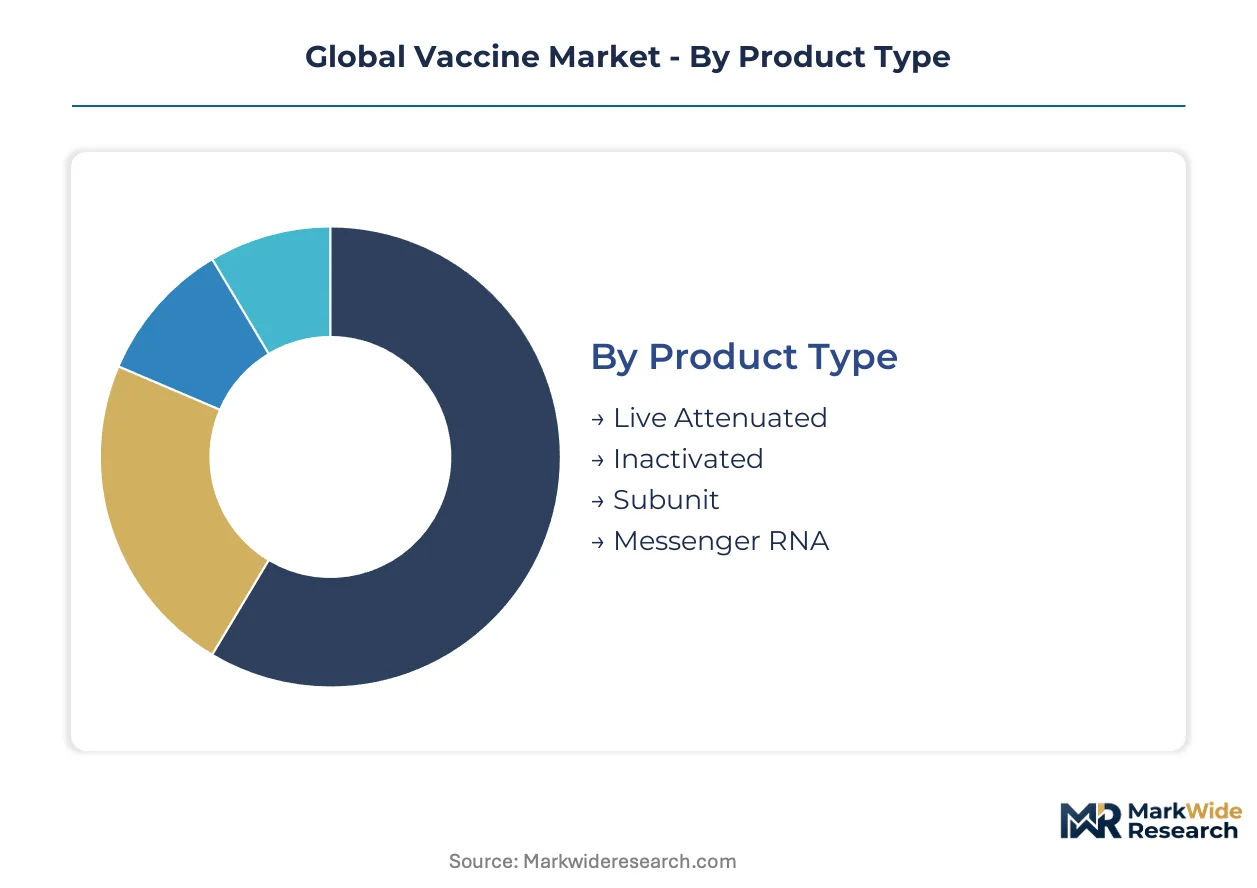
Vaccine market segmentation reveals how manufacturing scale, regulatory pathways, and distribution infrastructure concentrate value capture across distinct product and channel configurations. Platform economics and procurement centralization create divergent margin profiles that reshape portfolio allocation decisions for sponsors and contract manufacturers alike.
Product Type:
Manufacturing complexity and cold-chain requirements concentrate supply capability among sponsors with validated platform infrastructure and regulatory track records.
- Messenger RNA:Synthetic nucleic acid constructs formulated in lipid nanoparticles elicit protein expression for immune priming. Demand concentrates in high-income markets with ultra-low temperature distribution infrastructure, constrained by lipid supplier concentration and EMA stability documentation burdens.
- Live Attenuated:Weakened pathogen strains replicate transiently to stimulate durable cellular and humoral immunity. Pediatric immunization programs in India, Nigeria, and Indonesia drive volume, though last-mile refrigeration limits tropical reach and creates tender price compression.
- Inactivated:Chemically or heat-killed pathogens retain immunogenicity without replication risk. Whole-virion and split-virion formulations anchor influenza and polio supply through established fill-finish networks.
- Subunit:Purified protein antigens combined with adjuvants deliver targeted immune response without intact pathogen. Recombinant expression systems in yeast and insect cells support hepatitis B and HPV manufacturing scale.
Today's leader: Messenger RNA. Tomorrow's challenger: Live Attenuated.
Administration Route:
Route selection determines manufacturing format, stability requirements, and healthcare worker training burdens that cascade through procurement economics.
- Intramuscular:Deep tissue deposition in deltoid or vastus lateralis muscle optimizes antigen presentation through resident dendritic cell populations. National immunization programs standardize on this route for infant and adult schedules, driving prefilled syringe and multi-dose vial demand.
- Oral:Mucosal delivery bypasses needle requirements and cold-chain constraints for select attenuated formulations. Polio eradication campaigns and rotavirus programs in Pakistan and Bangladesh exploit this logistical advantage despite lower immunogenicity.
- Subcutaneous:Shallow tissue deposition in fatty layer suits small-volume adjuvanted products. Yellow fever and measles-rubella campaigns utilize this route for mass vaccination efficiency.
- Intranasal:Mucosal surface application targets respiratory pathogen entry sites with potential for transmission blocking. Development pipelines focus on influenza and COVID-19 candidates with thermostable powder formulations.
Intramuscular dominates procurement volume. Intranasal offers the steepest expansion trajectory through self-administration potential.
End User:
Channel structure determines pricing power, with consolidated procurement creating volume concentration that fragments in retail settings.
- Government Agencies:National immunization programs and Gavi-eligible country procurement aggregate demand through multi-year framework agreements. UNICEF supply division and PAHO revolving fund concentrate purchasing power for pediatric antigens.
- Hospitals:Acute care settings administer adult immunization products and travel vaccines with premium pricing outside tender systems. Institutional formularies in the US and Germany drive combination product preference.
- Clinics:Outpatient facilities bridge preventive care and acute administration for underinsured populations. India's urban primary health centers and Brazil's family health strategy units represent high-volume nodes.
- Pharmacies:Retail channel expansion for influenza and shingles vaccines creates direct-to-consumer access. US IRA price negotiation exclusion preserves margin for adult products in this channel relative to therapeutic categories.
Government Agencies command volume leadership. Pharmacies represent the fastest-climbing channel through retail vaccination convenience.
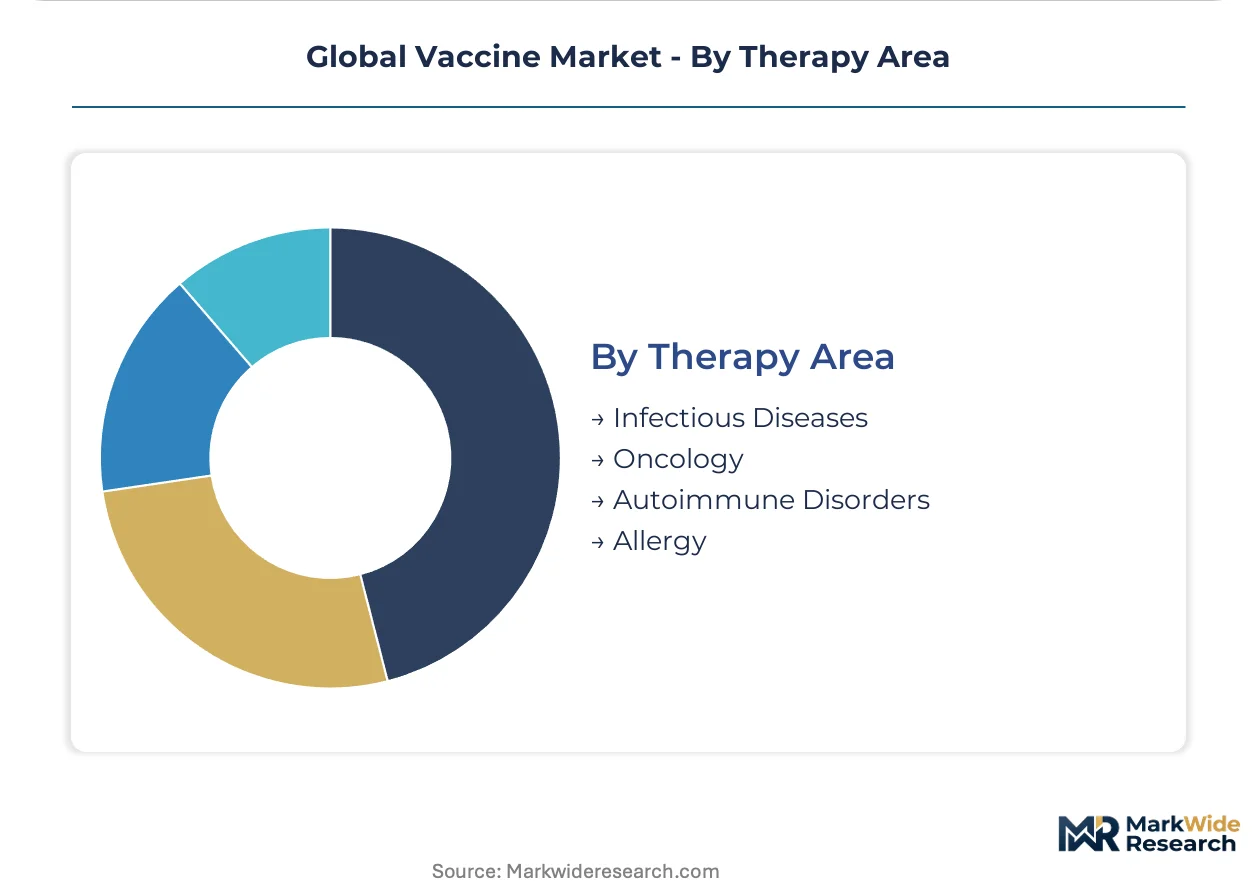
Therapy Area:
Clinical development risk and reimbursement pathways create divergent investment horizons across preventive and therapeutic applications.
- Infectious Diseases:Pathogen-targeted prophylaxis against viral and bacterial agents constitutes the historical core of vaccine revenue. COVID-19, influenza, and pediatric combination products sustain manufacturing base load across Serum Institute, Pfizer, and Sanofi networks.
- Oncology:Tumor-associated antigen and neoantigen platforms redirect immune surveillance against malignancy. mRNA personalized cancer vaccines in melanoma and pancreatic cancer trials represent pipeline concentration at BioNTech and Moderna.
- Autoimmune Disorders:Tolerance-inducing formulations aim to retrain immune response in multiple sclerosis and type 1 diabetes. Early-stage development at academic spinouts faces commercialization uncertainty.
- Allergy:Desensitization through sublingual and subcutaneous allergen immunotherapy addresses IgE-mediated hypersensitivity. European specialists Stallergenes and ALK-Abelló dominate standardized extract supply.
Infectious Diseases anchors revenue. Oncology is gaining share fastest through therapeutic premium pricing and pipeline density.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's export manufacturing capacity is scaling faster than Brazil's domestic procurement consolidation, creating divergent supply-demand dynamics across emerging health systems. National immunization programs in both countries are expanding coverage while cold-chain infrastructure investments reshape last-mile distribution economics.
United States
Adult immunization demand through retail pharmacy channels is preserving premium pricing outside Medicare price negotiation mechanisms. FDA accelerated approval pathways for mRNA platform updates are compressing variant-adapted product timelines. Boston-Cambridge biotech clusters anchor self-amplifying RNA development pipelines.
India
CDSCO tightening of local clinical data requirements is reshaping regional registration strategies for multinational sponsors. PLI scheme production-linked incentives are scaling fill-finish capacity and active pharmaceutical ingredient sourcing within the Pune-Hyderabad vaccine manufacturing corridor. Serum Institute of India anchors affordable supply for Gavi-eligible country procurement through multi-year volume commitments.
Germany
EMA revised Good Manufacturing Practice Annex 1 is mandating barrier isolation technology and continuous particulate monitoring across European manufacturing sites. Fill-finish operators in Belgium and Germany are retrofitting isolator lines ahead of enforcement deadlines. Marburg and Idar-Oberstein facilities represent concentrated mRNA manufacturing scale.
China
NMPA local clinical data requirements are extending registration timelines for foreign sponsors while domestic manufacturers expand export capacity. Sinopharm Group manufacturing networks are scaling inactivated and viral vector production for Belt and Road country procurement. Beijing-Tianjin biopharmaceutical clusters concentrate recombinant subunit platform expertise.
Brazil
ANVISA convergence with WHO prequalification standards is streamlining registration for Gavi-supplied pediatric antigens. National immunization program expansion is consolidating procurement volume through PAHO revolving fund mechanisms. São Paulo state production facilities are retrofitting for combination vaccine fill-finish capacity.
Global Vaccine Market Competitive Environment
North American producers anchor one tier of mRNA platform scale; Indian and European specialists hold complementary positions in live attenuated and recombinant protein supply. The vendor base concentrates around sponsors with validated regulatory track records and multi-product manufacturing flexibility. Three archetypes dominate: platform-technology licensors, high-volume contract manufacturers, and pediatric combination product specialists. Competitive moves center on manufacturing capacity expansion and strategic partnerships for lipid nanoparticle input security.
Within the high-volume contract manufacturing tier, Serum Institute of India and Pfizer Inc. exemplify divergent scale strategies, while Sanofi S.A. occupies a position in recombinant protein platform differentiation. Moderna Inc. represents the mRNA technology archetype with integrated formulation capabilities. These anchors illustrate how regulatory familiarity and cold-chain infrastructure investments are concentrating competitive advantage among sponsors with multi-continental manufacturing footprints.
| Leading Market Players |
|---|
| Merck & Co. |
| Pfizer |
| GSK (GlaxoSmithKline) |
| Sanofi |
| Moderna |
| Johnson & Johnson |
| AstraZeneca |
| Serum Institute of India |
| Sinopharm Group |
| Others |
Value Chain & Pricing Dynamics
Cell culture technician scarcity in the Boston-Cambridge and Basel biotech corridors concentrates skilled labor costs, compressing margin spreads between premium mRNA formulations and economy-tier inactivated products while Indian and Chinese manufacturing clusters exploit wage differentials to capture volume-tier procurement.
Pricing Analysis
Capacity additions in India and China are reshaping price floors for standard pediatric antigens as PLI-subsidized fill-finish operations undercut European cost structures. Three-tier pricing structure across premium, standard, and economy levels stratifies by cold-chain infrastructure requirements and WHO prequalification status. Pricing pressure stems from Gavi-eligible country procurement consolidation into multi-year framework agreements with rigid price adjustment mechanisms. Government agencies exhibit highest price sensitivity through tender aggregation, while hospital retail channels preserve premium pricing for adult immunization products outside Medicare negotiation scope.
Supply Chain Analysis
Lipid nanoparticle input supply rests on four specialty chemical producers concentrated in Germany, Switzerland, and the United States, creating single-source vulnerability for mRNA platform scale-up. Raw material dependencies span purified phospholipids, synthetic cholesterol analogs, and ionizable cationic lipids alongside glass vial and prefilled syringe formats. Tariff exposure on Chinese-sourced adjuvants and stabilizers compounds cost volatility for regional manufacturers. Distribution runs through UNICEF supply division and PAHO revolving fund mechanisms for low-income country procurement, with direct-to-hospital channels serving high-income retail markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EMA Annex 1 barrier isolation mandates and FDA accelerated approval pathways for mRNA platform updates simultaneously elevate compliance costs and compress development timelines for sponsors with validated track records.
For Market Incumbents: Acquire lipid nanoparticle formulation specialists to secure input supply against single-source concentration risk. Retrofit legacy stainless steel fill-finish lines to single-use isolator systems ahead of EMA enforcement deadlines. Pfizer and Moderna manufacturing scale advantages are defensible only through continued regulatory familiarity investment and multi-continental cold-chain infrastructure deployment.
For New Entrants and Emerging Players: Contract research organizations with GMP-certified pilot facilities represent the most accessible channel partner type for technology validation before scale-up commitment. Thermostable formulation development for tropical last-mile distribution offers penetrable white space against incumbent cold-chain dependence. Target Indonesian archipelago procurement through drone-enabled distribution partnerships as an entry wedge against established boat-dependent supply networks.
For Investors and Strategic Acquirers: Large pharmaceutical sponsors with respiratory pipeline gaps are the most active acquirer in this space, seeking self-amplifying mRNA platform access. Five-to-ten year viability concentrates on sponsors with integrated formulation-device capabilities and WHO prequalification track records. Watch Gavi pledge conference commitments as inflection indicator for low-income country procurement volume trajectory.
| Strategic Initiative | Industry Significance |
|---|---|
| Lipid Supplier Diversification | Reduces single-source vulnerability for mRNA platform sponsors dependent on German and Swiss specialty chemical producers. |
| Isolator Line Retrofit | EMA Annex 1 compliance mandates barrier technology investment at fill-finish facilities in Belgium and Germany. |
| Self-Amplifying mRNA Pipeline | Moderna and BioNTech respiratory candidates consolidate competitive advantage through reduced dose manufacturing footprint. |
| PAHO Framework Agreement | Brazil's national immunization program procurement consolidation extends contract duration and volume commitment security. |
| Drone-Enabled Cold-Chain Bridging | Indonesia's island geography creates demand for thermostable distribution alternatives to boat-dependent supply logistics. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with vaccine development executives, regulatory affairs leads at CDSCO and NMPA, UNICEF supply division procurement managers, and hospital formulary directors with secondary validation against FDA filings, EMA submissions, WHO prequalification lists, and ClinicalTrials.gov pipeline databases. Bottom-up manufacturer capacity assessments and top-down national immunization program procurement forecasts were triangulated for convergence.
Segment-weighting applied platform technology, administration route, end-user channel, and regional regulatory cluster dimensions across the projection horizon. CAGRs were derived from modeled volume and value outputs reflecting manufacturing scale economics, tender price trajectories, and cold-chain infrastructure investment cycles. Forecast inputs incorporated lipid supplier concentration indices and Gavi pledge commitment trajectories as industry-specific variables.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to mRNA platform regulatory acceptance timelines and emerging market cold-chain infrastructure buildout rates. Assumptions reflect current procurement consolidation trends and PLI scheme incentive structures. A small set of named triggers—EMA Annex 1 enforcement rigor, Gavi funding pledges, and lipid supplier capacity expansion announcements—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Cough and Cold Preparations Market
Pharmaceuticals
Montelukast Market
Pharmaceuticals
Chemotherapy-Induced Nausea and Vomiting Therapeutics Market
Pharmaceuticals
Famotidine Market
Pharmaceuticals
Gastrointestinal OTC Drugs Market
Pharmaceuticals
Musculoskeletal Disorders Drugs Market
Pharmaceuticals
Granulocyte Macrophage Colony Stimulating Factor Market
Pharmaceuticals
Cough Suppressant Drugs Market
Pharmaceuticals
Aminophylline Market
Pharmaceuticals
Europe Glucagon-Like Peptide-1 (GLP-1) Agonists Market
Pharmaceuticals
Gardasil (HPV Vaccine) Market
Pharmaceuticals
Systemic Antibiotics Market
Pharmaceuticals
Tuberculosis Therapeutics Market
Pharmaceuticals
Plasma Protein Therapeutics Market
Pharmaceuticals
Tinea Versicolor Treatment Market
Pharmaceuticals
Germany Pharmaceutical 3PL Market