
 Global Pharmaceutical Traceability Market | 2026-2036
Global Pharmaceutical Traceability Market Size, Share, and Industry Trends Forecast 2026-2036
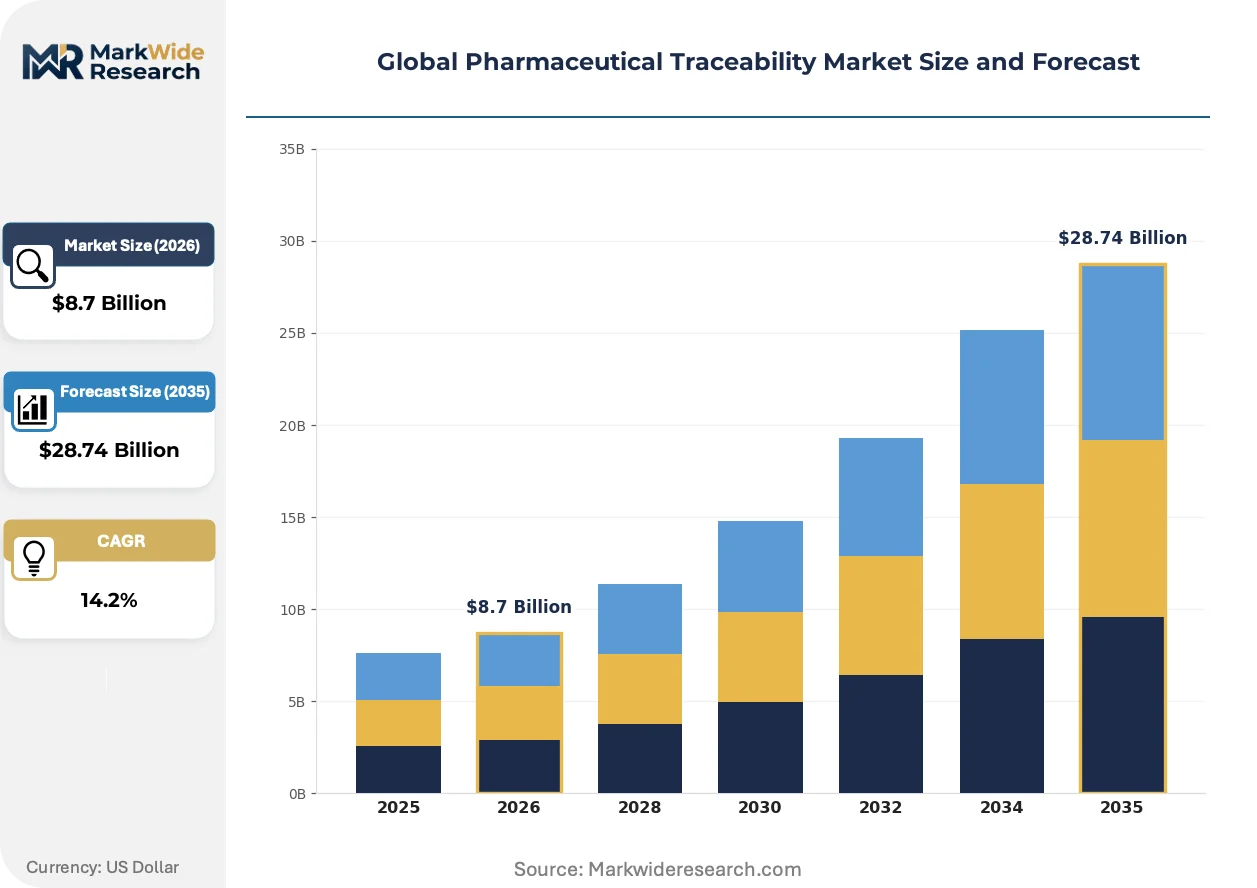
Global Pharmaceutical Traceability Market Outlook
Pharmaceutical wholesale distribution is fragmenting as serialization mandates force tier-one distributors to rebuild verification networks from the ground up. TraceLink leverages cloud-based compliance platforms to anchor multi-enterprise track-and-trace ecosystems across North America and Europe. Optel Group sustains leadership in vision-based inspection and aggregation hardware, competing directly with Systech's print-vision-verification integrated lines. Antares Vision differentiates through end-to-line serialization solutions that extend from packaging to pallet-level aggregation.
Pharmaceutical traceability encompasses the systematic recording, verification, and authentication of drug products through manufacturing, distribution, and dispensing using machine-readable identifiers such as 2D Data Matrix codes, EPCIS event repositories, and cryptographic verification keys. Its primary purpose is to prevent counterfeit medicines from entering legitimate supply chains while enabling rapid, targeted recalls when quality defects emerge. Barcoding technology dominates installed base across prescription drug packaging lines, though blockchain architectures represent the fastest-growing segment as manufacturers seek immutable ledger records for biologics chain-of-custody. RFID-enabled sensor tags command premium positioning in cold-chain vaccines, where temperature excursion logging intersects with location tracking to preserve product integrity.
The FDA's Drug Supply Chain Security Act and the European Medicines Agency's Falsified Medicines Directive together establish interoperable serialization standards that determine market access for any manufacturer selling into the United States or European Union. HIPAA privacy frameworks in the United States add patient-data protection requirements to traceability databases linking dispensers to specific drug lots. India's CDSCO and BIS are developing aligned track-and-trace guidelines for pharmaceutical exports, creating a third compliance jurisdiction that multinational manufacturers must navigate. Stakeholders must decide now whether to build unified global serialization platforms or maintain region-specific systems as regulatory divergence between the FDA's 2023 enhanced distribution requirements and emerging Asia-Pacific standards continues to deepen.
Market Dynamics
Serialization mandates from the FDA and EMA are forcing pharmaceutical manufacturers to rebuild packaging lines around machine-readable identifiers, compressing implementation timelines and concentrating vendor selection authority among compliance officers rather than operations teams.
Growth Catalysts
- EU FMD Enforcement:The European Medicines Agency's Falsified Medicines Directive mandates end-to-end verification across wholesale distribution, compelling German and French manufacturers to deploy aggregation technologies at pallet level.
- Cold-Chain Biologics:Temperature-sensitive vaccines and cell therapies require RFID-enabled sensor tags that log excursion data alongside location, creating dual-function traceability demand from specialty logistics providers.
- Blockchain Pilots:Distributed ledger architectures are securing chain-of-custody records for high-value oncology drugs, with hospital systems in Switzerland and Singapore piloting immutable verification workflows.
Market Restraints
- Copper and Semiconductor Input Costs:RFID inlay production depends on copper antenna etching and specialized ASIC chips, exposing hardware vendors to foundry capacity constraints in Taiwan and Malaysia.
- Legacy Line Retrofit Burden:Brownfield pharmaceutical packaging facilities face mechanical incompatibility between existing cartoners and new print-vision-verification modules, extending commissioning cycles.
- Regulatory Divergence Risk:India's CDSCO track-and-trace guidelines for pharmaceutical exports remain misaligned with FDA DSCSA event data standards, forcing exporters to maintain parallel serialization databases.
Strategic Opportunities
- Brazil ANVISA Alignment:Latin America's largest pharmaceutical market is drafting serialization rules compatible with GS1 standards, creating first-mover advantage for verification system vendors establishing local service presence.
- Direct-to-Patient Dispensing:Specialty pharmacy mail-order channels require unit-level authentication that survives last-mile handling, opening demand for tamper-evident smart labels beyond hospital settings.
- AI-Enhanced Inspection:Machine vision systems are converging with predictive analytics to flag serialization defects before they reach aggregation stations, compressing rework rates at high-speed packaging lines.
Industry Challenges
- EPCIS Architect Shortage:Pharmaceutical manufacturers lack sufficient personnel trained in Electronic Product Code Information Services event repository design, delaying interoperable data exchange with wholesale distributors.
- Multi-Enterprise Integration Complexity:Contract manufacturing organizations must reconcile divergent serialization formats from multiple brand-owner clients, straining IT infrastructure at mid-size packagers.
- Recall Simulation Preparedness:Regulatory agencies now demand documented mock recalls demonstrating lot-level traceability within 24 hours, exposing gaps in downstream dispenser data capture.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Pharmaceutical Traceability Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: RFID, Barcoding, Blockchain, Sensors Product Type: Prescription Drugs, Over-the-Counter Drugs, Biologics, Vaccines End User: Pharmacies, Hospitals, Distributors, Manufacturers Regulatory Standards: DSCSA, EU FMD, HIPAA, ISO 9001 |
| Companies Covered | TraceLink, Optel Group, Systech, Antares Vision, SAP, IBM, rfxcel, AlpVision, Axway, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Pharmaceutical Traceability Market Strategic Shifts
Traceability architectures are converging around cloud-native compliance platforms that aggregate serialization events across contract manufacturers, third-party logistics providers, and hospital pharmacies into unified audit trails.
Blockchain verification is hybridizing pharmaceutical supply chain governance by anchoring immutable timestamp records alongside traditional EPCIS event repositories. Large-molecule biologics manufacturers are piloting these dual-layer systems for gene therapy shipments where chain-of-custody disputes carry million-dollar liability exposure. The structural consequence is a compression of dispute resolution timelines from weeks to hours, as cryptographic proofs replace paper affidavits in customs clearance and insurance claims.
REACH compliance extensions under the EU Green Deal are mandating digital product passports for pharmaceutical packaging materials, forcing serialization vendors to capture resin origin and carbon footprint data alongside lot identifiers. Industrial consequence includes mandatory hardware upgrades to vision systems capable of reading multiple data formats on a single carton. Cold-chain vaccine distributors in Germany and the Netherlands are most affected, reconfiguring line controllers to parse both DSCSA compliance codes and CSRD-mandated sustainability metadata.
Hospital procurement departments are consolidating vendor qualification around pre-certified serialization platforms, displacing point-solution purchases in favor of multi-year enterprise agreements. Group purchasing organizations are embedding traceability readiness into formulary access contracts, rewarding manufacturers with interoperable data exchange capabilities. This concentration is most visible in the United States, where IDN-affiliated health systems now require EPCIS connectivity as a condition of specialty drug distribution contracts.
Global Pharmaceutical Traceability Market Segmentation
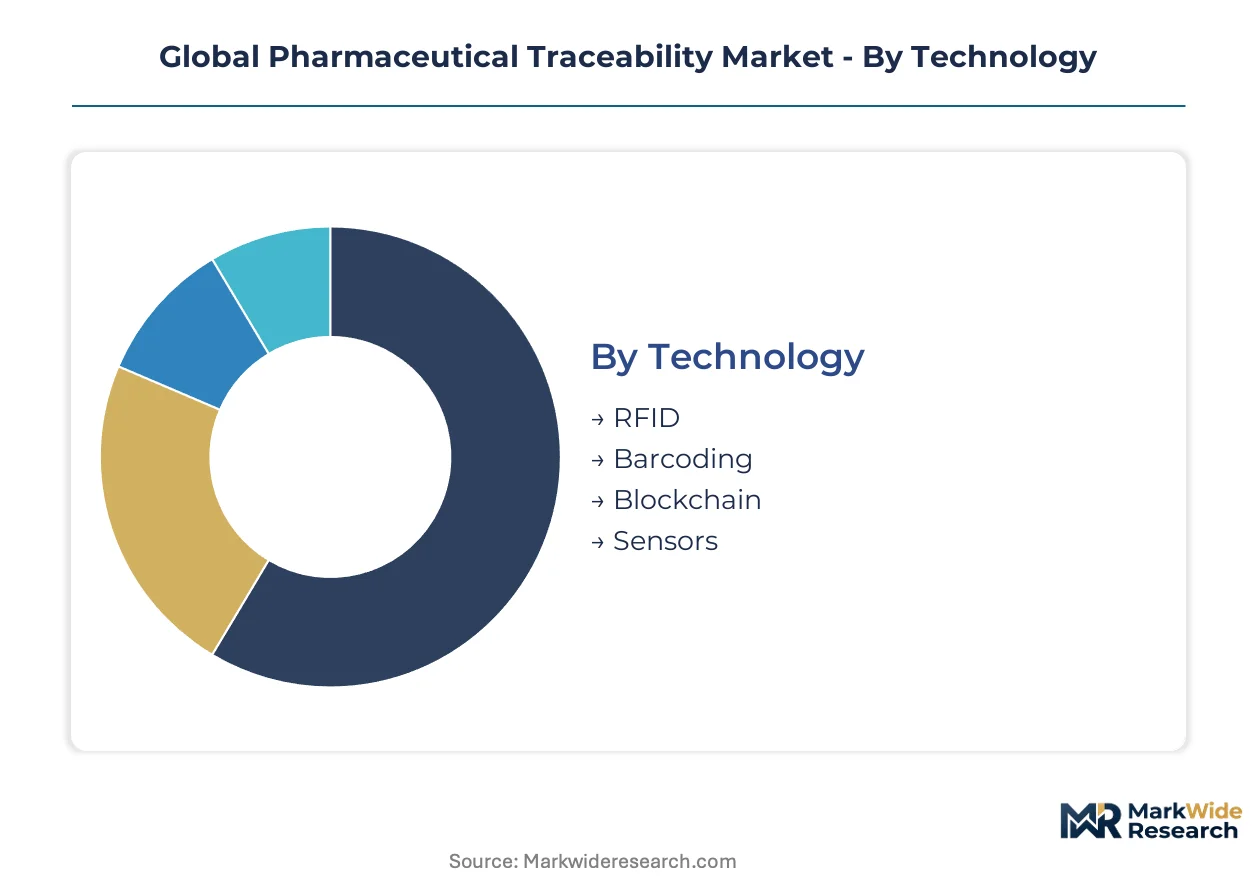
Pharmaceutical traceability deployments fragment across technology generations, product risk profiles, and regulatory jurisdictions. Vendor selection and implementation sequencing vary sharply by segment, with hardware refresh cycles and compliance deadlines driving purchasing concentration in specific quarters.
Technology:
After-sales-service intensity separates hardware-centric segments from software-native architectures, with RFID and sensor deployments requiring field calibration contracts that barcoding vendors rarely match.
- RFID:Radio-frequency identification inlays embed copper antennae and ASIC chips for non-line-of-sight tracking. Cold-chain vaccine distributors in Germany and the Netherlands deploy temperature-logging RFID tags where excursion alerts intersect with location data, though copper price volatility and Taiwan foundry constraints compress hardware margins.
- Barcoding:Two-dimensional Data Matrix codes dominate prescription drug packaging lines through lower unit economics and mature print-vision-verification infrastructure. Brownfield pharmaceutical facilities in the United States retrofit legacy cartoners with aggregation-capable modules, extending commissioning timelines where mechanical incompatibility emerges.
- Blockchain:Distributed ledger architectures anchor immutable timestamp records alongside EPCIS repositories. Swiss hospital systems and Singaporean specialty pharmacies pilot dual-layer verification for high-value oncology shipments where chain-of-custody disputes carry substantial liability exposure.
- Sensors:Multi-parameter environmental monitors log temperature, humidity, and shock events through disposable or reusable form factors. Cell therapy logistics providers in Switzerland integrate sensor telemetry with EPCIS event streams to satisfy Swissmedic documentation requirements.
By volume, Barcoding leads. By growth pace, Blockchain is ahead.
Product Type:
Regulatory scrutiny intensity stratifies segments, with biologics and vaccines commanding multi-layer authentication that over-the-counter products rarely require.
- Prescription Drugs:Small-molecule pharmaceuticals face mandatory serialization under FDA DSCSA and EU FMD mandates. Wholesale distributors in France and Germany rebuild verification networks around aggregation technologies to satisfy end-to-end traceability requirements.
- Biologics:Large-molecule therapies and gene treatments demand chain-of-custody documentation where temperature excursions destroy therapeutic efficacy. Manufacturers in Switzerland and the United States pilot hybrid blockchain-EPCIS architectures to compress dispute resolution timelines.
- Vaccines:Cold-chain distribution requirements intersect with national immunization program procurement, creating dual-function demand for RFID-enabled temperature logging. German and Dutch distributors reconfigure line controllers to parse both compliance codes and CSRD-mandated sustainability metadata.
- Over-the-Counter Drugs:Lower-risk consumer health products face reduced serialization granularity, though India's CDSCO export guidelines increasingly align OTC shipments with track-and-trace documentation for pharmaceutical exports.
Prescription Drugs captures the largest installed base. Biologics shows the steepest expansion trajectory.
End User:
Data capture sophistication and integration burden diverge sharply, with manufacturers bearing upstream serialization encoding and hospitals managing downstream dispenser authentication.
- Manufacturers:Primary packaging facilities deploy print-vision-verification modules and aggregation stations to encode machine-readable identifiers at unit, case, and pallet levels. German pharmaceutical hubs in Frankfurt and Munich anchor regional adoption of line-level serialization systems.
- Distributors:Wholesale operations reconcile heterogeneous serialization formats from multiple brand owners while maintaining interoperable data exchange with downstream dispensers. Mid-size packagers strain IT infrastructure managing divergent client requirements.
- Hospitals:IDN-affiliated health systems in the United States now require EPCIS connectivity as a condition of specialty drug distribution contracts, consolidating procurement around pre-certified platforms.
- Pharmacies:Retail and specialty pharmacy channels perform final authentication before dispensing, with mail-order operations requiring tamper-evident smart labels that survive last-mile handling.
Manufacturers account for the deepest technology penetration. Hospitals are climbing the fastest as procurement requirements tighten.
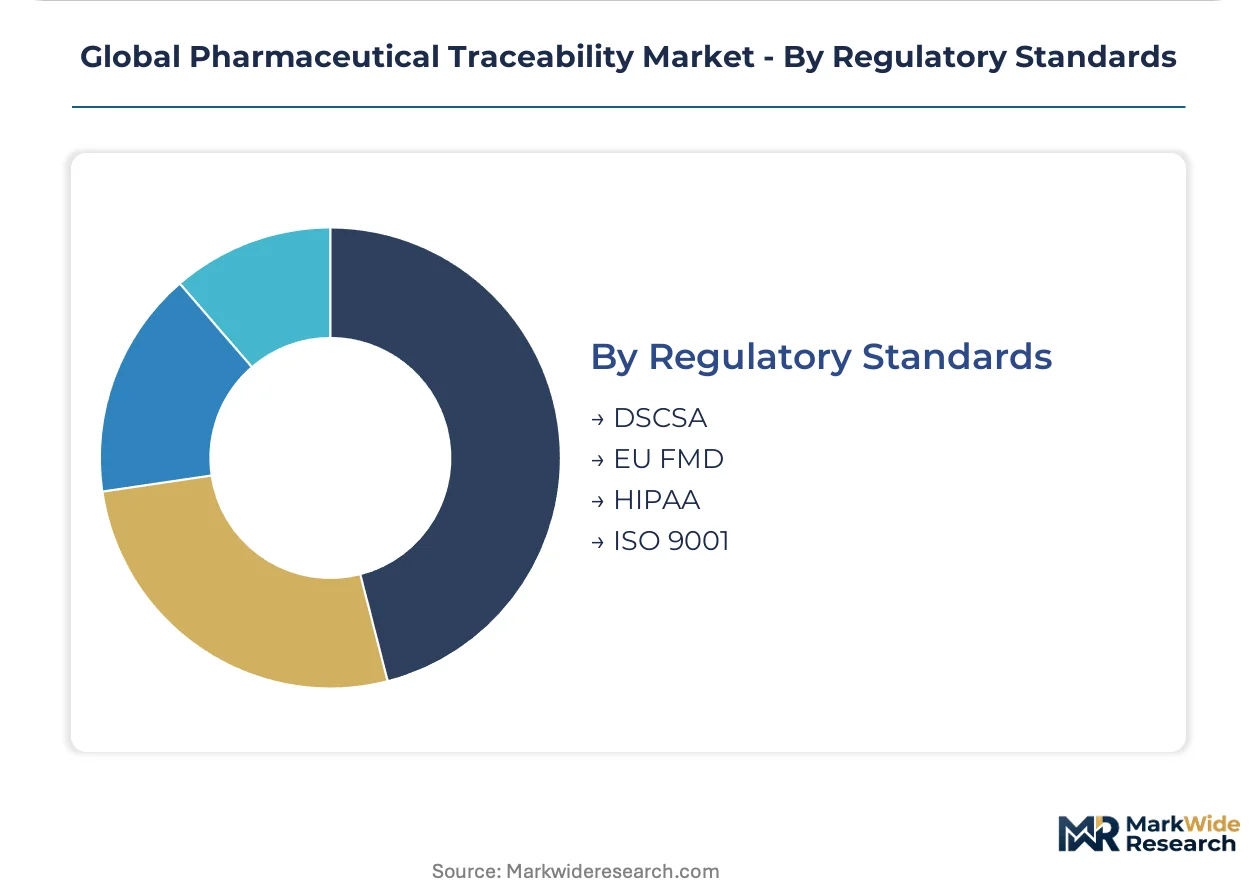
Regulatory Standards:
Compliance architecture complexity and jurisdictional overlap determine vendor qualification costs, with multi-market manufacturers facing parallel database maintenance.
- DSCSA:The FDA's Drug Supply Chain Security Act mandates interoperable serialization standards and enhanced distribution requirements for pharmaceutical products entering the United States. Compliance deadlines compress implementation timelines and concentrate vendor selection authority among regulatory officers.
- EU FMD:The European Medicines Agency's Falsified Medicines Directive establishes end-to-end verification across wholesale distribution, with German and French manufacturers deploying pallet-level aggregation technologies to satisfy enforcement protocols.
- HIPAA:United States privacy frameworks add patient-data protection requirements to traceability databases linking specific drug lots to individual dispensers, constraining cloud architecture design.
- ISO 9001:Quality management certification provides foundational documentation standards that serialization vendors leverage across multiple regulatory jurisdictions, reducing duplicate audit burdens.
DSCSA governs the largest addressable market. EU FMD is expanding most quickly as aggregation requirements deepen.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical traceability vendors command pricing premiums in Switzerland and Germany that distributors in India cannot match, reflecting regulatory stringency gaps and cold-chain infrastructure depth. This asymmetry shapes investment flows and technology tiering across markets.
United States
FDA DSCSA enforcement deadlines compress implementation timelines for wholesale distributors rebuilding verification networks. HIPAA privacy frameworks constrain cloud architecture design for traceability databases linking dispensers to specific drug lots. IDN-affiliated health systems in the Greater Boston and Pacific Northwest corridors now require EPCIS connectivity as a condition of specialty drug distribution contracts.
Germany
EMA Falsified Medicines Directive mandates drive pallet-level aggregation technology adoption among Frankfurt and Munich pharmaceutical hubs. REACH compliance extensions under the EU Green Deal force serialization vendors to capture resin origin data alongside lot identifiers. Cold-chain vaccine distributors in Bavaria reconfigure line controllers to parse both compliance codes and CSRD-mandated sustainability metadata.
Switzerland
Swissmedic documentation requirements for cell therapy logistics create dual-function demand for sensor telemetry integrated with EPCIS event streams. Hybrid blockchain-EPCIS architectures pilot among large-molecule manufacturers seeking to compress dispute resolution timelines. Hospital systems in Zurich and Basel anchor immutable verification workflows for high-value oncology shipments.
India
CDSCO track-and-trace guidelines for pharmaceutical exports misalign with FDA DSCSA standards, forcing exporters to maintain parallel serialization databases. BIS developing aligned standards creates compliance complexity for Mumbai and Ahmedabad manufacturing clusters. Mid-size packagers strain IT infrastructure managing divergent client requirements from multiple brand owners.
Brazil
ANVISA drafting serialization rules compatible with GS1 standards creates first-mover advantage for verification system vendors establishing São Paulo service presence. Temperature-sensitive vaccine distribution through national immunization programs drives RFID-enabled sensor tag demand. Local pharmaceutical packaging lines retrofit legacy cartoners with aggregation-capable modules, extending commissioning cycles.
Global Pharmaceutical Traceability Market Competitive Environment
Cloud-native compliance platforms and hardware-centric vision systems split the market between software-native architectures and integrated print-vision-verification lines. Tier-one distributors concentrate procurement among vendors with multi-enterprise track-and-trace ecosystems. Three strategic archetypes dominate: serialization software specialists, aggregation hardware fabricators, and enterprise IT incumbents with pharmaceutical modules. Competitive moves center on M&A to close capability gaps and strategic partnerships to anchor regional service presence.
Within the cloud-native tier, TraceLink exemplifies multi-enterprise ecosystem orchestration across North American and European compliance environments. Optel Group and Systech occupy positions spanning vision-based inspection hardware and integrated line systems, with Optel representing Canadian aggregation expertise and Systech anchoring print-vision-verification integration. Antares Vision sits within the end-to-line specialization archetype, extending serialization solutions from packaging through pallet-level aggregation for manufacturers in regulated European markets.
| Leading Market Players |
|---|
| TraceLink |
| Optel Group |
| Systech |
| Antares Vision |
| SAP |
| IBM |
| rfxcel |
| AlpVision |
| Axway |
| Others |
Value Chain & Pricing Dynamics
Frankfurt and Munich pharmaceutical hubs anchor European serialization hardware production, where foundry constraints in Taiwan compress RFID inlay availability and concentrate pricing power among copper antenna suppliers serving cold-chain vaccine distributors. This supply concentration amplifies cost pass-through to German and Dutch line controllers parsing dual compliance codes.
Pricing Analysis
Configured-to-order pricing for aggregation-capable print-vision-verification modules commands 40-60% premiums over standard barcoding retrofits, with differentiation driven by FDA DSCSA certification tier and after-sales field calibration bundling. Cost compression in brownfield retrofit tiers is intensifying because mechanical incompatibility extends commissioning cycles. Small-molecule generic manufacturers exhibit highest price sensitivity, while biologics producers accept premium positioning for blockchain-EPCIS hybrid architectures.
Supply Chain Analysis
Tariff exposure between Taiwan and Malaysia dominates supply chain risk for RFID ASIC fabrication, where copper price volatility and foundry capacity constraints intersect. Hardware production draws from Taiwan, Malaysia, and Germany, with specialized vision sensors resting on semiconductor wafers, precision optics, and pharmaceutical-grade stainless steel enclosures. Single-source vulnerability concentrates in Taiwan foundry capacity. Distribution runs through third-party logistics providers reconciling heterogeneous serialization formats.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Blockchain-EPCIS hybrid architectures are disrupting pharmaceutical supply chain governance, with Swissmedic documentation requirements for cell therapy logistics creating immediate capability gaps for incumbent verification vendors.
For Market Incumbents: Insulate core revenue by deepening backward integration into copper antenna supply and securing captive ASIC allocation from Taiwan foundries. Cloud-native compliance platforms face displacement risk from hospital procurement consolidation around pre-certified multi-enterprise ecosystems; defend by embedding AI-enhanced inspection modules that compress rework rates at high-speed lines.
For New Entrants and Emerging Players: Build out white-space presence in Brazil ANVISA pre-implementation markets and direct-to-patient specialty pharmacy channels requiring tamper-evident smart labels. Underpenetrated aggregation hardware service presence in São Paulo offers the most penetrable geographic entry point; pursue GS1 standards alignment as the primary go-to-market credential.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance infrastructure play because serialization mandates deepen across successive jurisdictions with irreversible hardware refresh cycles. Acquisition targets should display EPCIS repository design capability and established FDA-EMA dual certification; watch Brazil ANVISA rule finalization as the signal indicating Latin American demand inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Certification Investment | FDA DSCSA and EU FMD dual certification opens hospital procurement channels for specialty drugs. |
| Backward Integration into ASIC Supply | Captive semiconductor allocation from Taiwan foundries insulates margins against copper price volatility. |
| AI-Enhanced Vision System Launch | Machine learning defect detection compresses rework rates at German pharmaceutical packaging hubs. |
| Strategic Partnership with Hospital IDNs | EPCIS connectivity pre-certification secures multi-year enterprise agreements in United States corridors. |
| Geographic Expansion into Brazil | ANVISA-aligned GS1 verification systems capture first-mover advantage in Latin America's largest market. |
Study Parameters
Initial hypotheses were tested against primary input from regulatory affairs leads, pharmaceutical packaging engineers, wholesale distributor IT directors, and hospital procurement managers and refined through secondary validation against FDA DSCSA guidance documents, EMA FMD implementation reports, Swissmedic cell therapy logistics requirements, and Brazil ANVISA regulatory drafts. Bottom-up and top-down triangulation cross-checked hardware vendor shipment data with national pharmaceutical production statistics.
Demand-supply-balance framing anchored the analytical framework across the analysis window, with segmentation modeled by technology generation, product risk profile, end-user data capture sophistication, and regional regulatory cluster. CAGRs were derived from installed base growth curves and compliance deadline acceleration patterns, incorporating EPCIS event repository adoption rates and cold-chain biologics expansion as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by cloud-native platform entrants or hardware-software consolidators would shift outcomes beyond projected ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Cough Cold and Allergy Hay Fever Remedies in Mexico Market
Pharmaceuticals
India Plasma Fractionation Market
Pharmaceuticals
Middle-East and Africa Diabetes Drugs Market
Pharmaceuticals
Global Atherosclerosis Drugs Market
Pharmaceuticals
Global Plasma Derived Therapy Market
Pharmaceuticals
US Pharmacy Market
Pharmaceuticals
Traumatic Brain Injury Drugs Market
Pharmaceuticals
Otic Drugs Market
Pharmaceuticals
Global Hepatitis B Vaccines Market
Pharmaceuticals
Hepatocellular Carcinoma Drugs Market
Pharmaceuticals
Allergic Rhinitis Drugs Market
Pharmaceuticals
Global Pharmaceutical Contract Manufacturing Market
Pharmaceuticals
Secondary Myelofibrosis Therapeutics Market
Pharmaceuticals
Global 3D Printed Drugs Market
Pharmaceuticals
Exocrine Pancreatic Insufficiency Therapeutics Market
Pharmaceuticals
Anticonvulsants Market