
 Drug Infusion System Market | 2026-2036
Drug Infusion System Market Size, Share, and Industry Trends Forecast 2026-2036
Drug Infusion System Market Analysis
The EU Medical Device Regulation (MDR) is recalibrating design and post-market surveillance obligations for infusion system manufacturers selling into European markets. Becton, Dickinson and Company leverages its installed base of Alaris platforms to sustain recurring revenue through software-enabled service contracts. Fresenius Kabi AG anchors its competitive position through captive manufacturing of infusion consumables and parenteral nutrition solutions. Medtronic differentiates via deep integration of its infusion hardware with continuous glucose monitoring ecosystems in diabetes management.
A drug infusion system comprises electromechanical or gravity-driven apparatus designed to deliver fluids, medications, or nutrients into a patient's circulatory system at controlled rates, typically achieving accuracy within plus or minus five percent of programmed flow rates through peristaltic or syringe driver mechanisms. These systems serve critical therapeutic functions across acute care, chronic disease management, and oncology protocols where precise dosing prevents therapeutic failure or adverse events. Infusion pumps and smart infusion systems command the largest revenue share, with the former representing mature hospital infrastructure and the latter capturing margin expansion through wireless connectivity and dose error reduction software. Ambulatory pumps and portable devices represent the fastest-expanding demand pool, driven by patient preference for home-based chemotherapy and pain management regimens that reduce institutional care costs.
The FDA maintains active premarket notification requirements under 21 CFR 880.5725 for infusion pumps, while the EU MDR mandates clinical evaluation and post-market clinical follow-up for Class IIa and above devices. Health Canada and Japan's PMDA enforce parallel standards for software validation and biocompatibility testing that shape global product development roadmaps. Stakeholders must monitor evolving cybersecurity guidance from multiple regulators, as network-connected infusion systems face escalating scrutiny of vulnerability management and patch deployment protocols.
Market Dynamics
The FDA's renewed cybersecurity guidance for network-connected infusion pumps is forcing manufacturers to rearchitect software stacks and extend validation timelines, while hospital procurement committees prioritize wireless-enabled platforms that integrate with electronic health record systems.
Growth Catalysts
- EU MDR compliance mandates:Class IIa and above infusion devices now require enhanced clinical evaluation and post-market surveillance, creating replacement demand for legacy pump fleets across German and French hospital networks.
- Home-based chemotherapy protocols:Oncology centers in the United States are expanding ambulatory pump programs to reduce institutional bed days and capture bundled payment incentives.
- Peristaltic mechanism advances:Next-generation tubing materials with improved biocompatibility profiles are enabling extended infusion durations for parenteral nutrition applications.
Market Restraints
- Semiconductor supply concentration:Pump motor controllers and wireless modules depend on fabrication capacity concentrated in East Asian foundries, exposing manufacturers to input volatility.
- Polymer resin cost exposure:Medical-grade polycarbonate and silicone formulations for disposable infusion sets track petrochemical feedstock indices with limited hedging instruments.
- Gravity-fed substitute persistence:Simple intravenous drip systems retain cost advantage in resource-constrained clinical settings, capping premium pump penetration in price-sensitive segments.
Strategic Opportunities
- Japan's aging demographic:METI incentives for home medical equipment are expanding reimbursement for portable insulin and analgesic infusion devices outside acute care facilities.
- Continuous glucose monitoring convergence:Integration of infusion hardware with real-time glycemic sensors creates closed-loop therapeutic systems for Type 1 diabetes management.
- Direct-to-health-system distribution:Manufacturers are bypassing traditional medical device distributors to establish service contracts with integrated delivery networks in the United States.
Industry Challenges
- Cybersecurity engineering talent scarcity:FDA premarket submission requirements for software bill of materials and vulnerability disclosure protocols demand specialized firmware security expertise that outstrips current labor supply.
- Legacy fleet interoperability:Health systems operating mixed-vendor pump environments face data integration complexity when deploying centralized dose error reduction software across heterogeneous hardware generations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Drug Infusion System Market |
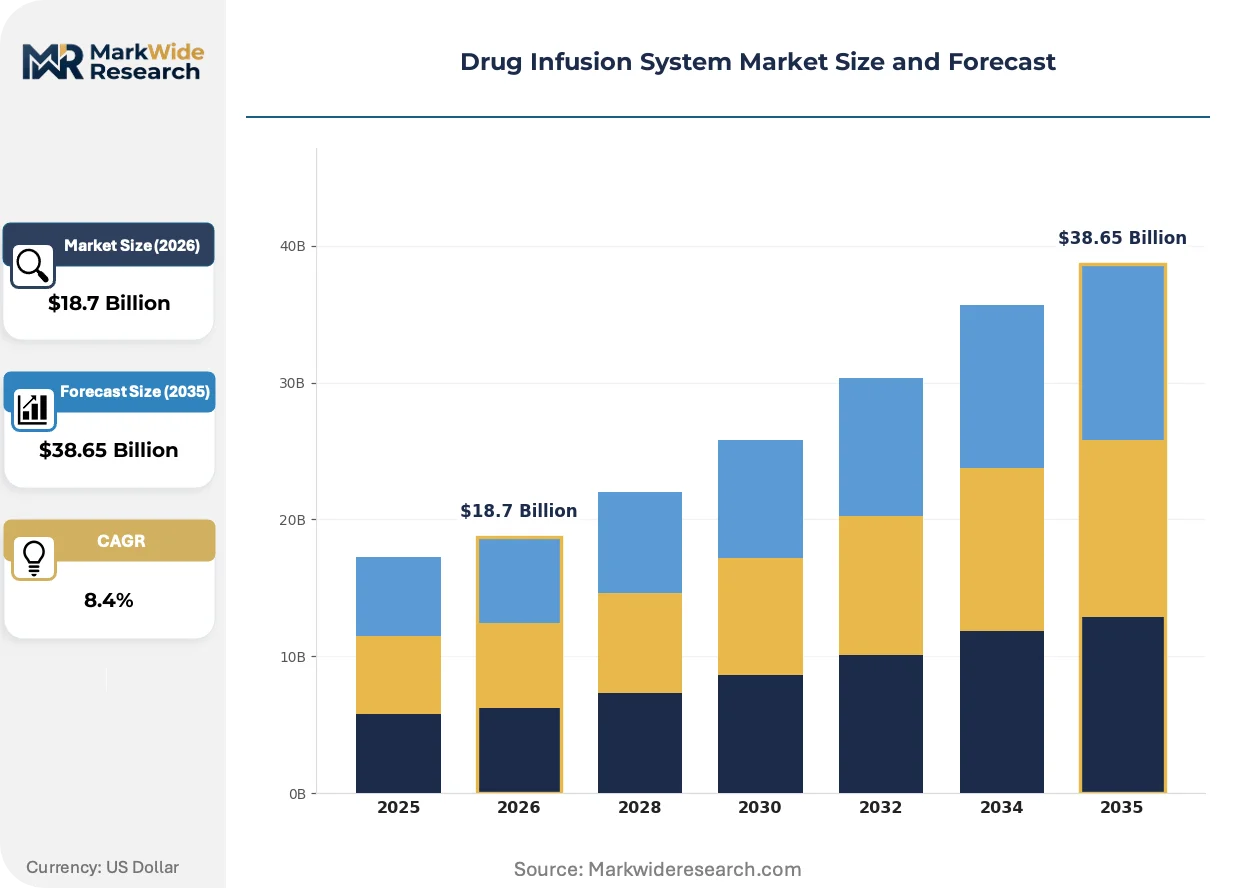
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Infusion Pumps, Syringe Pumps, Volumetric Pumps, Ambulatory Pumps End User: Hospitals, Home Care, Ambulatory Surgical Centers, Long-term Care Facilities Therapy Area: Oncology, Pain Management, Critical Care, Diabetes Technology: Smart Infusion Systems, Electronic Pumps, Portable Devices, Wireless Infusion |
| Companies Covered | B. Braun Melsungen AG, Medtronic, Becton, Dickinson and Company, Fresenius Kabi AG, Baxter International Inc., ICU Medical Inc., Smiths Medical, Terumo Corporation, Tandem Diabetes Care Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Drug Infusion System Market Emerging Trajectories
Wireless connectivity and embedded clinical decision support are redefining infusion system architecture, compressing the gap between hardware delivery and software-enabled service revenue.
Smart infusion platforms with integrated drug libraries and dose error reduction algorithms are electrifying hospital pharmacy workflows. Academic medical centers in the United States are deploying these systems to replace standalone pumps, achieving closed-loop medication verification that reduces adverse drug events and extends platform lifecycle value through recurring software subscriptions.
REACH restrictions on phthalate plasticizers in medical devices are compelling European manufacturers to reformulate infusion set components. The regulation accelerates transition to alternative elastomers, with German and Dutch notified bodies expanding biocompatibility testing capacity to clear backlog in technical documentation reviews for modified product lines.
Hospital procurement committees are unbundling device acquisition from long-term service agreements, compressing vendor switching cycles. Integrated delivery networks in the United States now separate capital equipment purchasing from software maintenance and consumable supply contracts, enabling competitive rebidding of service tiers without full fleet replacement and pressuring incumbent suppliers to demonstrate ongoing clinical value.
Drug Infusion System Market Segmentation
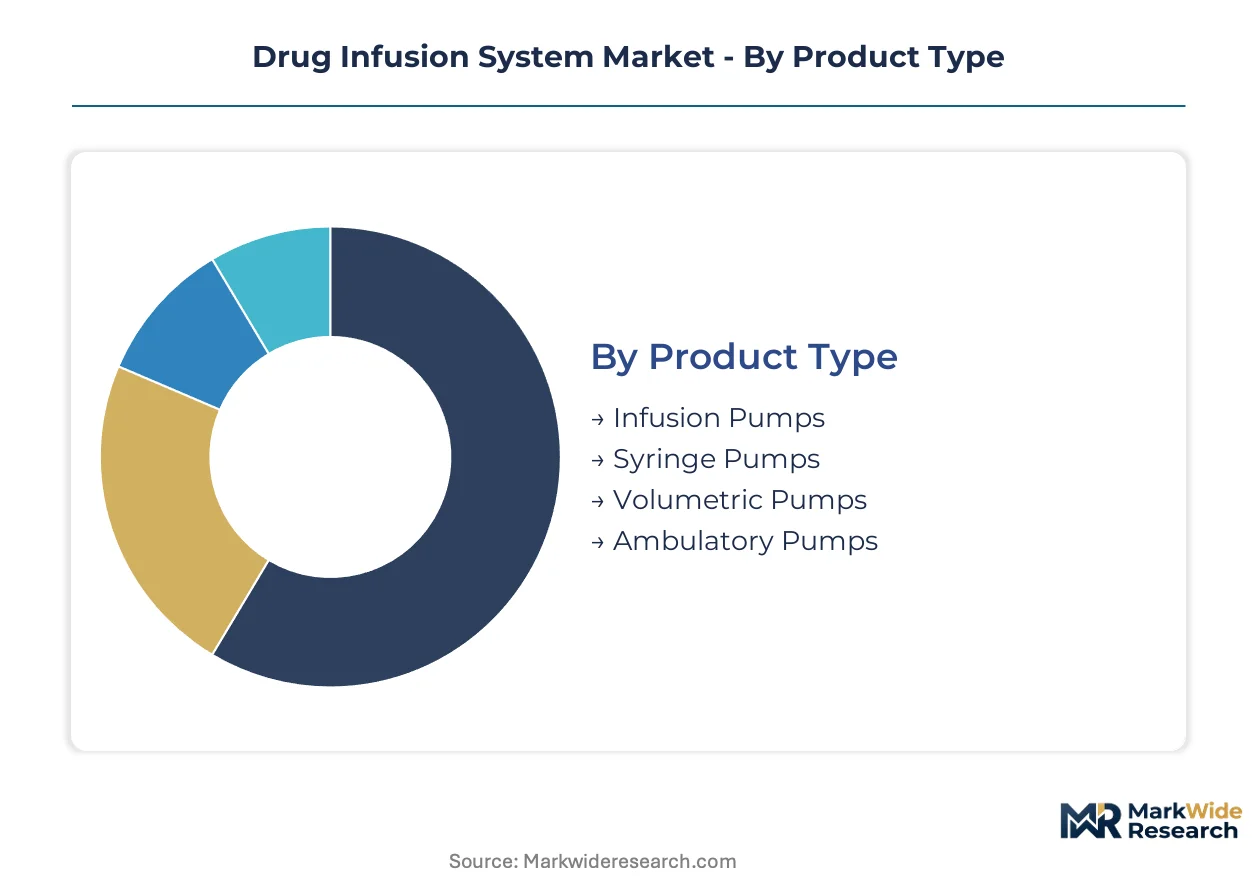
Infusion system manufacturers configure product portfolios across multiple intersecting dimensions. Each segmentation axis carries distinct regulatory burdens, margin profiles, and replacement cycles that shape strategic resource allocation.
Product Type:
FDA premarket notification under 21 CFR 880.5725 applies universally, while EU MDR Class IIa designation triggers enhanced clinical evaluation for pump mechanisms with programmable flow control.
- Infusion Pumps:Electromechanical platforms with peristaltic or piston-driven mechanisms deliver fluids at programmed rates within plus or minus five percent accuracy. Hospital procurement committees in the United States prioritize wireless-enabled units that integrate with electronic health record systems for closed-loop medication verification.
- Syringe Pumps:Precision syringe driver mechanisms enable micro-infusion applications requiring flow rates below one milliliter per hour. Neonatal intensive care units and anesthesia departments concentrate demand for these devices due to their capability for high-accuracy low-volume delivery.
- Volumetric Pumps:Large-volume reservoir systems support extended parenteral nutrition and fluid replacement protocols in acute care settings.
- Ambulatory Pumps:Battery-powered portable devices enable home-based chemotherapy and analgesic regimens. Oncology centers expanding ambulatory pump programs capture bundled payment incentives while reducing institutional bed days.
Leading the category by volume: Infusion Pumps. Growing fastest: Ambulatory Pumps.
End User:
Customer type determines service contract structures, with integrated delivery networks unbundling device acquisition from long-term maintenance agreements.
- Hospitals:Acute care facilities operate mixed-vendor pump fleets that create data integration complexity when deploying centralized dose error reduction software. Smart infusion platforms with embedded drug libraries electrify pharmacy workflows and extend lifecycle value through recurring software subscriptions.
- Home Care:Patients receiving chemotherapy, pain management, or parenteral nutrition outside institutional settings drive portable device demand. METI incentives in Japan expand reimbursement for home medical equipment including insulin and analgesic infusion devices.
- Ambulatory Surgical Centers:Same-day procedure facilities require compact infusion systems with rapid setup protocols.
- Long-term Care Facilities:Extended care settings utilize gravity-fed substitutes and basic electronic pumps for hydration and medication delivery.
Highest service contract attachment rates: Hospitals. Steepest expansion trajectory: Home Care.
Therapy Area:
Clinical application dictates performance specifications, with closed-loop therapeutic systems requiring hardware integration with real-time monitoring sensors.
- Oncology:Chemotherapy protocols demand precise dosing to prevent therapeutic failure or adverse events. Ambulatory pump programs reduce institutional bed days while maintaining treatment continuity.
- Pain Management:Patient-controlled analgesia systems with programmable lockout intervals support postoperative and chronic pain protocols.
- Critical Care:Intensive care units require multi-channel pumps with independent alarm systems and battery backup for life-sustaining infusions.
- Diabetes:Insulin infusion hardware converges with continuous glucose monitoring ecosystems to create automated glycemic control systems for Type 1 diabetes management.
Deepest software integration requirements: Diabetes. Broadest addressable patient population: Oncology.
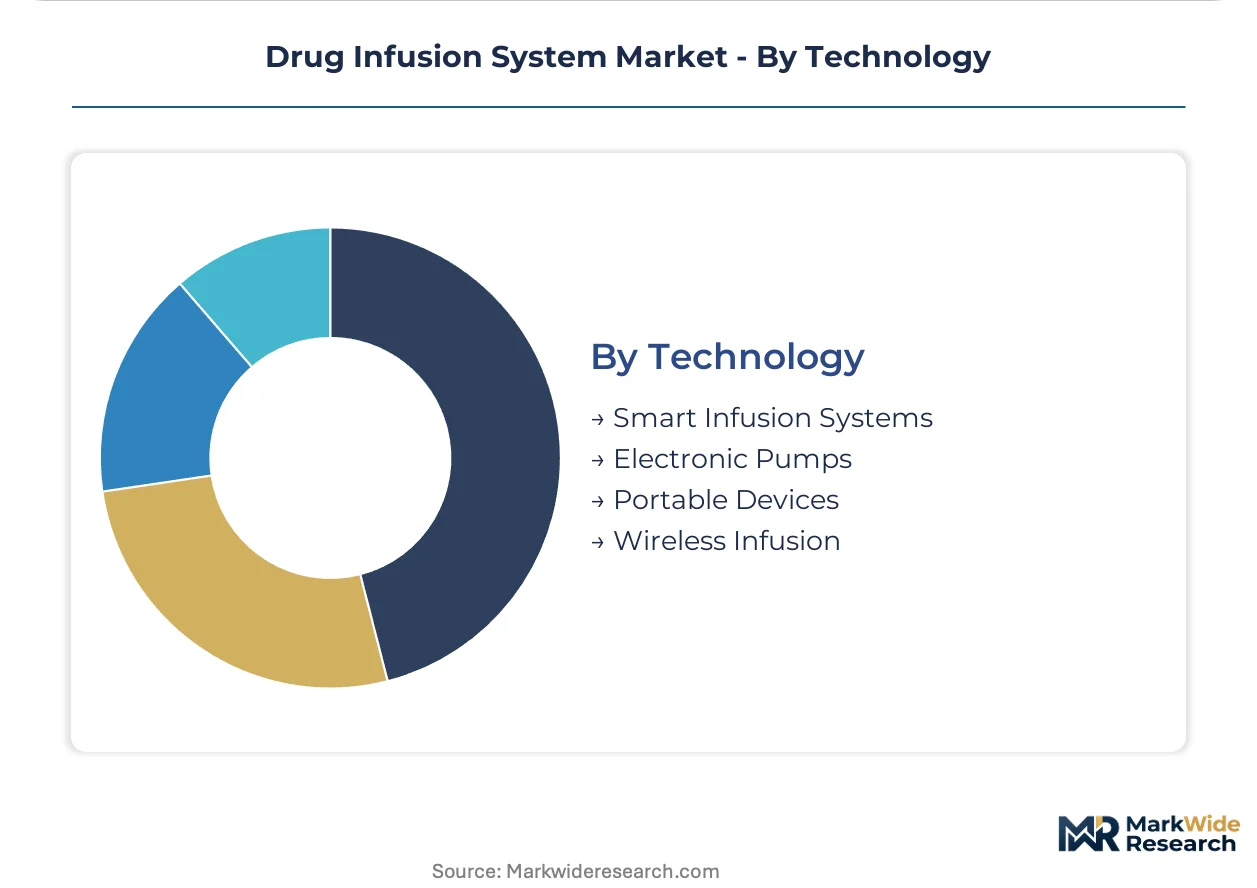
Technology:
Network connectivity features trigger FDA cybersecurity guidance compliance obligations that extend validation timelines and rearchitect software stacks.
- Smart Infusion Systems:Platforms with dose error reduction algorithms and drug libraries command margin expansion through wireless connectivity. Academic medical centers deploy these systems to replace standalone pumps and achieve closed-loop medication verification.
- Electronic Pumps:Microprocessor-controlled flow regulation with tactile interfaces represents mature hospital infrastructure requiring periodic software updates for security patching.
- Portable Devices:Battery-powered lightweight designs with disposable reservoirs enable mobility for home-based therapy administration.
- Wireless Infusion:Network-connected systems face escalating regulatory scrutiny of vulnerability management and patch deployment protocols.
Widest installed base: Electronic Pumps. Gaining share fastest: Smart Infusion Systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Minneapolis-Saint Paul corridor anchors North American infusion system manufacturing, with the Twin Cities metro hosting concentrated medical device engineering talent and FDA-facing regulatory expertise.
United States
Integrated delivery networks in Texas and Florida are unbundling device acquisition from service contracts, accelerating fleet replacement cycles. The FDA's renewed cybersecurity guidance for network-connected pumps extends software validation timelines. Greater Boston's academic medical centers deploy smart infusion platforms with embedded drug libraries to achieve closed-loop medication verification.
Germany
University hospitals in Baden-Württemberg and Bavaria drive demand for Class IIa compliant devices under EU MDR enhanced clinical evaluation mandates. REACH restrictions on phthalate plasticizers compel manufacturers to reformulate infusion set components with alternative elastomers. The Rhine-Main region around Frankfurt hosts notified bodies expanding biocompatibility testing capacity for modified product lines.
Japan
METI incentives for home medical equipment expand reimbursement for portable insulin and analgesic infusion devices outside acute care facilities. The PMDA enforces parallel standards for software validation that shape global product development roadmaps. The Kansai region around Osaka concentrates manufacturing of precision syringe driver mechanisms for neonatal applications.
China
Tier-three hospitals in the Yangtze River Delta upgrade from gravity-fed substitutes to electronic pumps for fluid replacement protocols. The NMPA maintains active premarket notification requirements that align with international standards. The Pearl River Delta hosts contract manufacturers of medical-grade polycarbonate housings for disposable infusion sets.
India
Corporate hospital chains in Maharashtra and Karnataka import smart infusion platforms to replace aging electromechanical fleets. The CDSCO mandates clinical evaluation documentation for programmable flow control devices. The Delhi-NCR corridor attracts distribution partnerships targeting price-sensitive segments with localized service networks.
Drug Infusion System Market Vendor Landscape
Premium-margin players sit above commodity-margin players across software-enabled service contract attachment rates, with recurring revenue models displacing pure hardware transactions. The vendor base clusters around three strategic archetypes: diversified medical technology conglomerates with installed base leverage, captive consumables manufacturers with backward integration into parenteral nutrition, and diabetes-focused specialists with continuous monitoring convergence. Dominant competitive moves include direct-to-health-system distribution bypass and cybersecurity engineering talent acquisition.
Within the diversified conglomerate tier, Becton, Dickinson and Company and Baxter International Inc. occupy positions anchored by legacy installed bases and service contract portfolios. Fresenius Kabi AG exemplifies the captive consumables archetype through in-house production integration. Medtronic sits within the monitoring convergence specialization, representing hardware-sensor ecosystem integration.
| Leading Market Players |
|---|
| B. Braun Melsungen AG |
| Medtronic |
| Becton, Dickinson and Company |
| Fresenius Kabi AG |
| Baxter International Inc. |
| ICU Medical Inc. |
| Smiths Medical |
| Terumo Corporation |
| Tandem Diabetes Care Inc. |
| Others |
Supply Flow & Price Mechanics
Captive manufacturing of infusion consumables anchors both supply security and pricing power for integrated device manufacturers, with in-house production of parenteral nutrition solutions and disposable sets insulating margins from petrochemical feedstock volatility while enabling service-contract bundling that locks hospital procurement committees into recurring revenue streams.
Pricing Analysis
Uptime-based service contracts anchor value capture for smart infusion platforms, with manufacturers pricing hardware acquisition separately from software-enabled dose error reduction subscriptions. Price differentiation rests on cybersecurity certification tiers and wireless EHR integration depth. Pricing pressure stems from unbundled procurement patterns as integrated delivery networks competitively rebid service tiers without full fleet replacement. Price-sensitive long-term care facilities gravitate toward gravity-fed substitutes, while academic medical centers absorb premium tiers for closed-loop medication verification capabilities.
Supply Chain Analysis
Refurbishment flows for legacy pump fleets create secondary supply channels that extend equipment lifecycles and compress new-unit demand in budget-constrained health systems. Manufacturing concentrates in Germany, the United States, and Japan for precision syringe driver mechanisms and smart platform assembly. Medical-grade polycarbonate housings and silicone tubing formulations draw from petrochemical feedstocks with limited hedging instruments. Single-source vulnerability in semiconductor motor controllers exposes manufacturers to East Asian foundry capacity constraints. Distribution runs through direct-to-health-system contracts that bypass traditional medical device distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play as FDA cybersecurity engineering requirements and EU MDR clinical evaluation mandates force capital-constrained regional manufacturers to exit or seek acquisition.
For Market Incumbents: Extend software-enabled service contract attachment rates by embedding predictive maintenance algorithms that reduce hospital biomedical engineering overhead. Acquire specialized cybersecurity firmware talent to accelerate FDA premarket submission timelines and defend against emerging entrants with native secure-by-design architectures. Deepen backward integration into biocompatible elastomer formulations to capture REACH-driven component substitution margins.
For New Entrants and Emerging Players: EU MDR in Germany and France opens a window for Class IIa compliant devices that replace legacy pump fleets in university hospitals facing enhanced post-market surveillance obligations. Target home care ambulatory pump segments where METI incentives in Japan expand reimbursement outside acute care facilities. Pursue direct distribution partnerships with integrated delivery networks in Texas and Florida that have unbundled procurement committees receptive to competitive service-tier rebidding.
For Investors and Strategic Acquirers: Exit pathways concentrate in mid-cap device manufacturers with captive consumables production and established notified body relationships. Long-term viability hinges on recurring revenue ratios exceeding hardware transactional dependence. Acquisition targets should demonstrate installed base leverage convertible to software subscription attach. Monitor FDA cybersecurity guidance enforcement intensity as inflection indicator for validation timeline compression and engineering cost escalation.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Cybersecurity Submission | Accelerates premarket clearance for network-connected pumps with software bill of materials documentation. |
| EU MDR CE Marking Pathway | Unlocks German and French hospital replacement demand through Class IIa clinical evaluation compliance. |
| Hospital System Partnership | Secures long-term service contracts with integrated delivery networks unbundling procurement committees. |
| Software Companion Development | Enables closed-loop medication verification with embedded drug libraries and dose error reduction algorithms. |
| Reimbursement Strategy | Captures METI incentives for home medical equipment expanding portable device coverage in Japan. |
Methodological Framework
Document review covered FDA 510(k) filings, EU MDR technical documentation, and hospital GPO contract databases, complemented by interviews with biomedical engineering directors, hospital pharmacy informaticists, infusion pump service technicians, and medical device regulatory affairs specialists. Secondary validation drew from CMS Medicare reimbursement schedules, notified body biocompatibility testing records, and semiconductor foundry capacity disclosures. Bottom-up unit demand modeling triangulated against top-down health system capital expenditure surveys.
Cross-referencing historical replacement cycle data against panel input from procurement committees and clinical engineering departments shaped the analytical framework across the analysis window. Segmentation dimensions included pump mechanism type, end-user facility category, therapy area application, and network connectivity tier. CAGRs derived from installed base turnover rates and software subscription attach trajectories. Forecast inputs incorporated REACH elastomer transition timelines and METI home medical equipment reimbursement expansion patterns.
The model assumes a particular technology adoption path for wireless-enabled smart infusion platforms; alternative pathways for closed-loop automated glycemic control systems would alter the outlook for diabetes-focused hardware demand. Forecasts reflect assumptions regarding cybersecurity guidance enforcement consistency and EU MDR notified body review capacity. Practitioners should monitor FDA premarket submission backlog indicators and East Asian semiconductor fabrication utilization rates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Equipment
Pharmaceutical Glass Vials and Ampoules Market
Pharmaceutical Equipment
Global Depyrogenated Sterile Empty Vials Market
Pharmaceutical Equipment
Pharmaceutical CDMO Market
Pharmaceutical Equipment
Pharmaceutical Manufacturing Market
Pharmaceutical Equipment
Serum Vials Market
Pharmaceutical Equipment
Lyophilization Equipment and Services Market
Pharmaceutical Equipment
Latin America Pharmaceutical Glass Vials and Ampoules Market
Pharmaceutical Equipment
Asia-Pacific CDMO Market
Pharmaceutical Equipment
Global Central Fill Pharmacy Automation Market
Pharmaceutical Equipment
Pharmaceutical Equipment Testing Market
Pharmaceutical Equipment
Europe Formulation Development Outsourcing Market
Pharmaceutical Equipment
US and Europe Pharmaceutical Manufacturing Market
Pharmaceutical Equipment
Global Rotary Tablet Press Market
Pharmaceutical Equipment
North America Pharmacy Automation Market
Pharmaceutical Equipment
Europe Pharmaceutical Isolator Market
Pharmaceutical Equipment
Pharmerging Contract Manufacturing Market