
 Global Compounding Pharmacy Market | 2026-2036
Global Compounding Pharmacy Market Size, Share, and Industry Trends Forecast 2026-2036
Global Compounding Pharmacy Market Analysis
Patient-specific formulation revenue is rewriting profitability expectations across the value chain. Fresenius Kabi leverages its parenteral nutrition expertise to dominate hospital-centric sterile compounding. Fagron sustains its position through backward integration into active pharmaceutical ingredient sourcing for dermatology and hormone therapies. Wedgewood Pharmacy specializes in veterinary and human custom dosing, anchoring its growth in the specialty pharmacy channel.
Compounding pharmacy encompasses the preparation of customized medications by combining, mixing, or altering ingredients to meet individual patient needs that commercially available drugs cannot address, requiring adherence to United States Pharmacopeia Chapter 795 for non-sterile and Chapter 797 for sterile preparations. The practice serves therapeutic gaps in allergen-free formulations, precise pediatric dosages, and discontinued drug restoration. Oral medications occupy the largest volume share due to their convenience and broad applicability across age groups, though injectable forms capture premium margins driven by hospital outsourcing trends. Hormone replacement therapy represents the fastest-expanding therapy area as bioidentical formulations attract aging populations seeking personalized endocrine management.
The FDA's 503A and 503B designations, alongside USP 795/797 enforcement, shape operational compliance costs and facility investment requirements for compounders. EMA's GMP Annex 1 revisions for sterile manufacturing and WHO's good compounding practices further elevate cross-border quality standards. Stakeholders must monitor regulatory harmonization between FDA and EMA frameworks, as divergence in sterile compounding rules will determine which facilities can serve multi-jurisdictional health systems without redundant certification burdens.
Market Dynamics
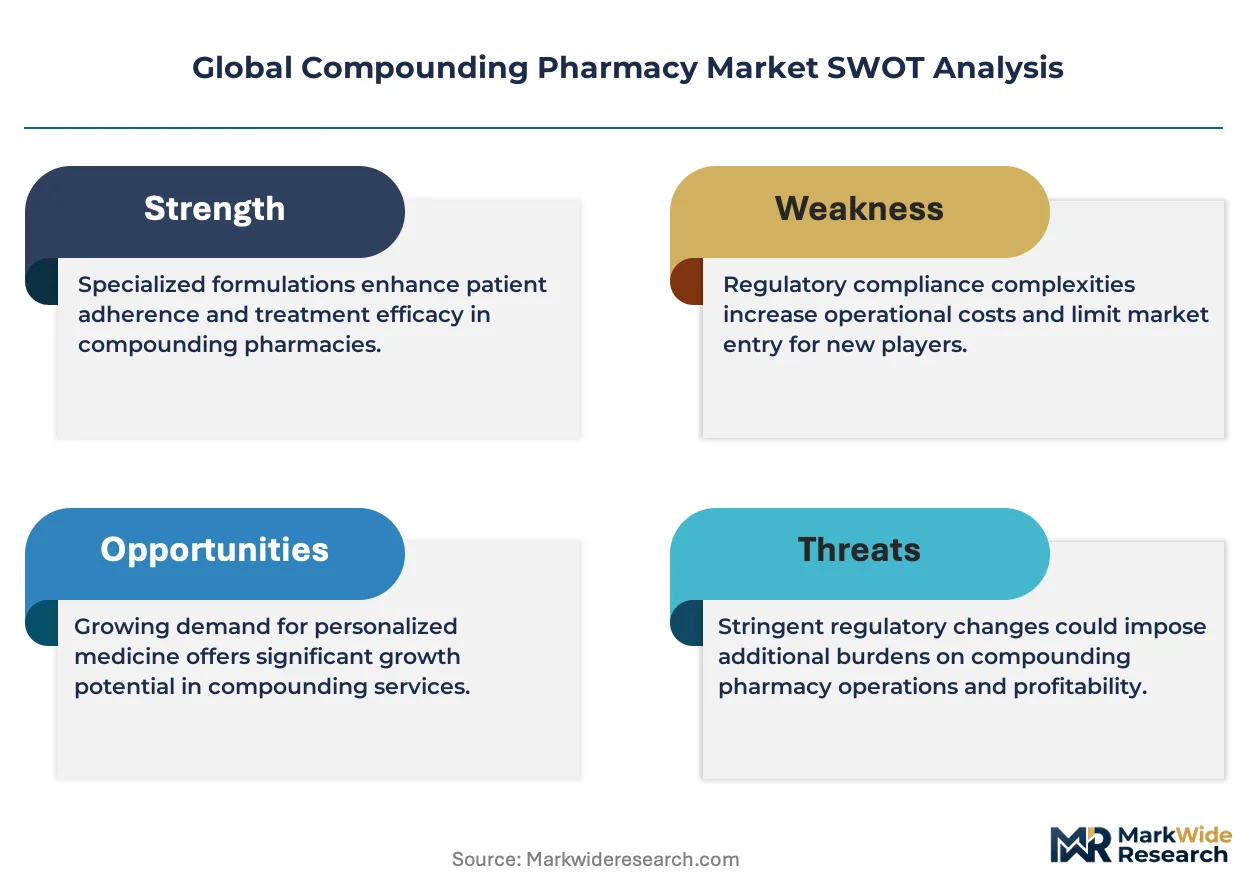
FDA's 503B outsourcing facility guidelines are compressing sterile compounding capacity into fewer certified sites, forcing hospital systems to consolidate supplier relationships and upgrade quality infrastructure to meet tightened USP 797 enforcement.
Growth Catalysts
- Home health care expansion:Post-acute care networks in the United States are embedding compounded therapies into discharge protocols, driving demand for patient-specific dosing outside institutional settings.
- EMA GMP Annex 1 alignment:European facilities upgrading to revised sterile manufacturing standards are capturing cross-border hospital outsourcing contracts previously served by lower-grade compounders.
- Bioidentical hormone therapy protocols:Endocrinology practices are replacing standardized synthetic regimens with customized estradiol and testosterone preparations tailored to individual metabolic profiles.
Market Restraints
- Active pharmaceutical ingredient supply concentration:China controls critical raw material streams for hormone and parenteral nutrition bases, exposing compounders to tariff volatility and export licensing delays.
- Facility certification costs:USP 797 compliance for sterile cleanroom infrastructure requires capital outlays that exclude smaller independent pharmacies from hospital contract bidding.
- Commercial drug restoration limits:FDA restrictions on replicating discontinued mass-market products constrain compounders to narrow therapeutic gaps where no manufacturer maintains production.
Strategic Opportunities
- Veterinary compounding white space:Companion animal practices in Australia and Canada lack specialized dosage form suppliers for exotic species and precision weight-based therapies.
- WHO good compounding practices adoption:Middle Eastern health systems implementing standardized quality frameworks are opening procurement to internationally certified 503B-equivalent facilities.
- Oral-to-transdermal conversion demand:Pediatric and geriatric populations unable to swallow tablets are driving formulation innovation in topical and buccal delivery systems.
Industry Challenges
- Sterile compounding technician scarcity:USP 797 training programs produce insufficient certified personnel to staff expanded outsourcing facility capacity.
- Legacy pharmacy management system integration:Independent compounders face workflow disruption migrating from paper-based batch records to electronic quality management platforms required for 503B registration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Compounding Pharmacy Market |
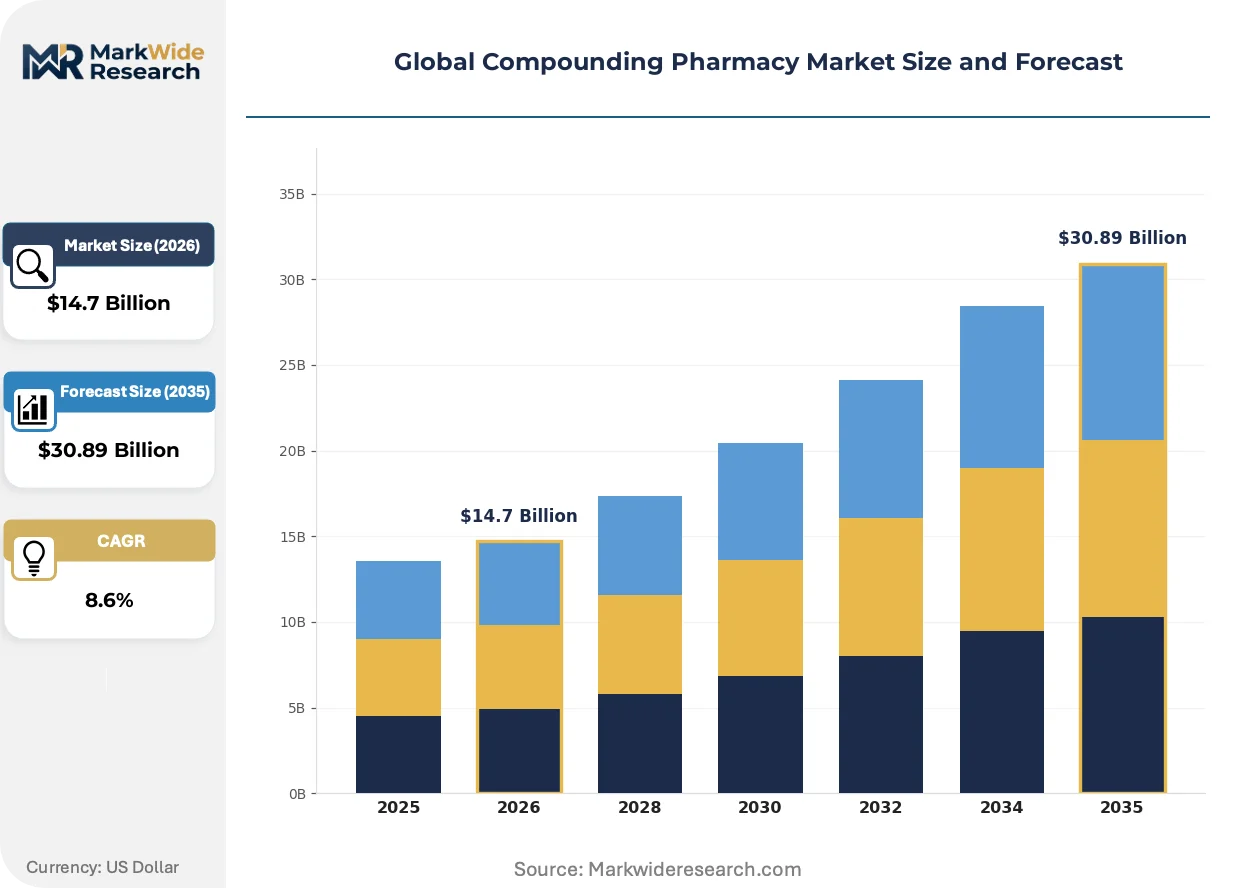
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $30.89 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oral Medications, Topical Solutions, Injectable Forms, Ophthalmic Preparations Therapy Area: Pain Management, Hormone Replacement Therapy, Dermatology, Pediatric Care Delivery Mode: Transdermal, Oral, Intravenous, Inhalation End User: Hospitals, Clinics, Home Health Care, Specialty Pharmacies |
| Companies Covered | Fresenius Kabi, Fagron, B. Braun Medical Inc., Wedgewood Pharmacy, Institutional Pharmacy Solutions, Clinigen Group PLC, Dougherty's Pharmacy, Inc., Lorraine's Pharmacy, PharMEDium Services, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Compounding Pharmacy Market Emerging Trajectories
Digital quality systems and point-of-care diagnostic integration are compressing the gap between patient need identification and customized medication delivery, reshaping how compounders interface with prescribing clinicians.
Electronic batch record systems with integrated environmental monitoring are virtualizing compliance documentation for sterile operations. Hospital-affiliated 503B facilities are deploying these platforms to eliminate paper-based deviations and accelerate FDA inspection readiness. The technology is virtualizing quality assurance labor, allowing a single pharmacist to oversee multiple cleanroom suites simultaneously.
EMA's revised GMP Annex 1 for sterile manufacturing is mandating barrier isolation technology and continuous viable particle monitoring. European compounding facilities must retrofit open-fronted laminar flow hoods with restricted access barrier systems or exit hospital contract markets. German and Swiss outsourcing sites are absorbing these capital requirements fastest, consolidating subcontracting relationships with Southern European compounders unable to fund upgrades.
Direct-to-patient subscription models are displacing traditional wholesale distribution for chronic hormone and dermatology therapies. Telehealth-integrated compounders in the United States are capturing patient relationships previously held by retail pharmacy chains, bypassing intermediary margins. California and Texas have emerged as regulatory laboratories where state boards of pharmacy are testing oversight frameworks for remote prescribing and home delivery of controlled substance compounds.
Global Compounding Pharmacy Market Segmentation
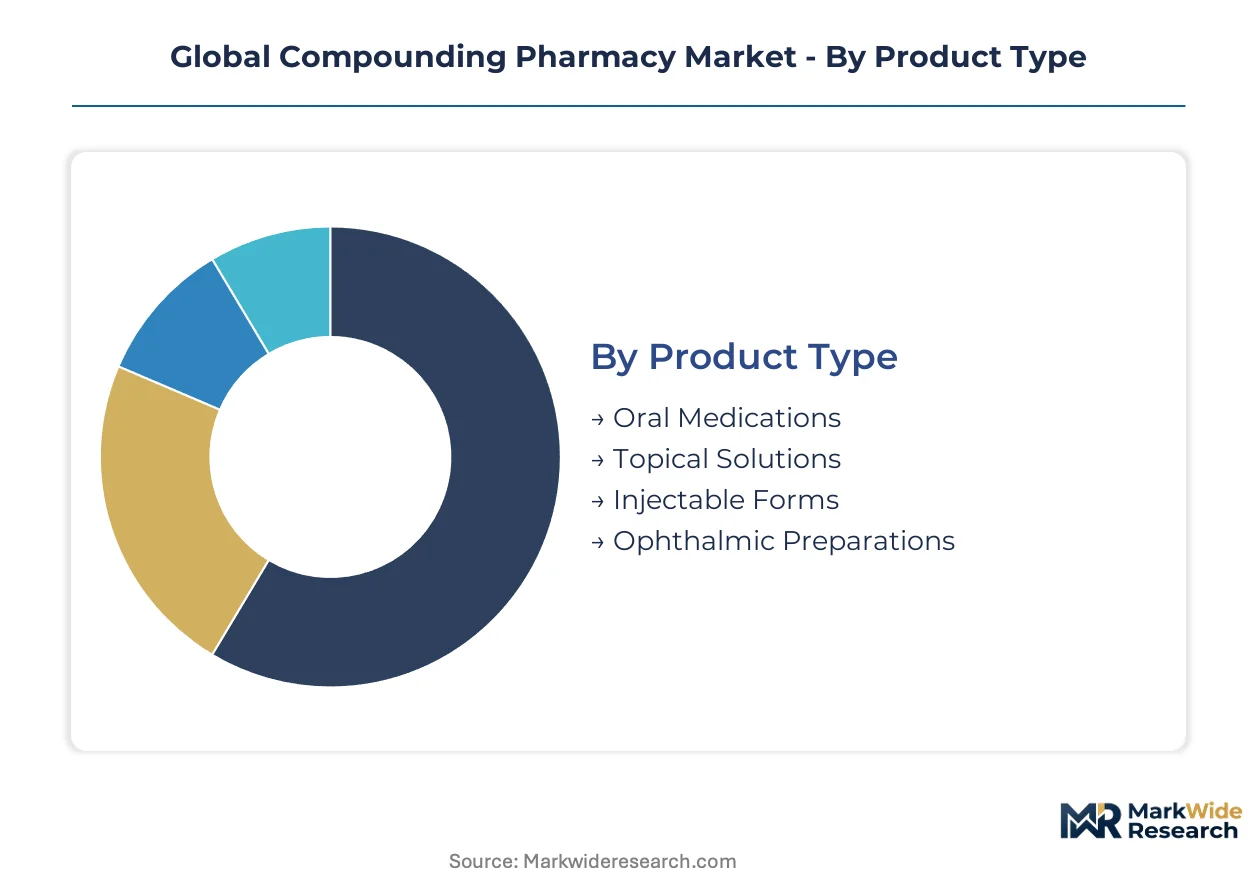
Segmentation in compounding pharmacy reveals distinct operational economics across dosage forms and care settings. Cycle times vary dramatically between hospital-contract sterile batches and home-delivered chronic therapies, reshaping capital allocation and compliance investment priorities across the value chain.
Product Type:
Oral medications turn inventory fastest through retail channels, while sterile injectables tie up capital longest due to batch testing and environmental monitoring requirements.
- Oral Medications:Tablets, capsules, and liquid suspensions formulated with precise active pharmaceutical ingredient ratios for patients requiring allergen-free or strength-adjusted alternatives to commercial products. Demand concentrates in pediatric and geriatric populations across the United States where swallowing difficulties or metabolic variations necessitate custom formulations.
- Injectable Forms:Sterile parenteral solutions prepared under USP 797 guidelines for hospital infusion centers and home infusion patients. United States hospital systems are consolidating procurement around certified 503B outsourcing facilities as FDA enforcement tightens, compressing supplier networks to quality-leaders with barrier isolation technology.
- Topical Solutions:Creams, gels, and ointments delivering localized therapy with minimized systemic absorption for dermatology and pain management applications.
- Ophthalmic Preparations:Sterile eye drops and ointments requiring specialized aseptic processing for patients with preservative sensitivities or rare infection protocols.
Oral medications dominate installed base. Injectable forms are where expansion concentrates.
Therapy Area:
Cost tier stratification separates commodity pain formulations from premium bioidentical hormone protocols with compounding pharmacist consultation bundled into pricing.
- Hormone Replacement Therapy:Customized estradiol, progesterone, and testosterone preparations matched to individual metabolic profiles through saliva or serum testing integration. Endocrinology practices in Germany and the United States are displacing synthetic standardized regimens with bioidentical alternatives, driving formulation complexity and patient monitoring service revenue.
- Pain Management:Topical analgesic combinations and oral opioid alternatives tailored to avoid systemic side effects or drug interactions in polypharmacy patients. United States workers compensation and auto injury markets sustain demand for non-narcotic compounded alternatives amid regulatory pressure on conventional opioid prescribing.
- Dermatology:Customized topical preparations addressing psoriasis, eczema, and cosmetic concerns with patient-specific base compatibility.
- Pediatric Care:Flavor-masked suspensions and precise weight-based dosing for neonatal and childhood populations excluded from adult commercial drug labeling.
Pain management anchors volume throughput. Hormone replacement therapy is climbing the fastest.
Delivery Mode:
Application context determines delivery selection, with acute institutional care favoring intravenous routes and chronic outpatient management shifting toward patient-administered alternatives.
- Oral:Swallowed tablets, capsules, and liquids remain the default for maintenance therapies where first-pass metabolism is acceptable and patient self-administration is prioritized.
- Transdermal:Patches and topical gels bypass hepatic metabolism for hormone and pain applications, with absorption kinetics customized through base vehicle selection.
- Intravenous:Direct vascular administration reserved for hospitalized patients or home infusion programs requiring immediate bioavailability and precise titration.
- Inhalation:Nebulized and intranasal preparations for respiratory and systemic delivery where rapid onset or local pulmonary action is indicated.
Oral delivery retains broadest applicability. Transdermal routes are gaining share fastest in hormone and geriatric segments.
End User:
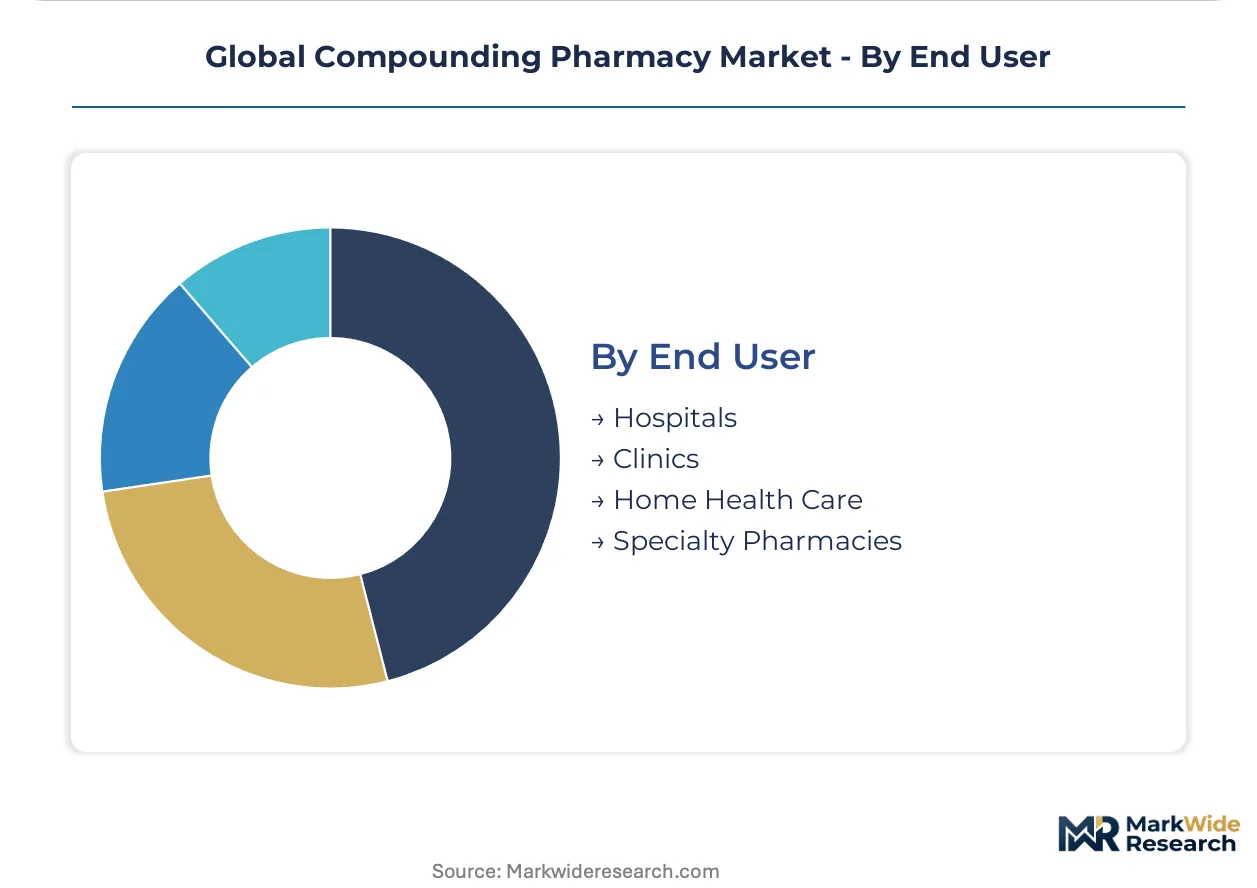
Customer type shapes regulatory burden and margin structure, with hospital contracts demanding 503B certification and home care channels permitting simpler 503A operational models.
- Home Health Care:Discharge planning integration and direct-to-patient subscription models for chronic therapies including hormone replacement and parenteral nutrition. Post-acute networks in Texas and California are embedding compounded therapies into care transition protocols, extending treatment adherence beyond institutional walls.
- Hospitals:Outsourced sterile compounding for operating rooms, oncology infusion centers, and emergency departments requiring immediate availability of patient-specific doses. United States health systems are consolidating supplier relationships to multi-state 503B facilities with demonstrated FDA inspection compliance and redundant manufacturing sites.
- Clinics:Physician office dispensing and procedure-associated formulations for dermatology, pain intervention, and integrative medicine practices.
- Specialty Pharmacies:Focused distribution channels for veterinary, fertility, and rare disease populations requiring consultation-intensive service models.
Hospitals dominate contract value concentration. Home health care is where patient relationship expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. United States patients favor sterile hospital outsourcing and direct-to-home hormone therapies, while European demand tilts toward certified manufacturing for cross-border hospital contracts. Emerging markets in the Middle East and Australia are importing quality frameworks rather than developing indigenous capacity.
United States
Hospital consolidation and home health expansion drive dual demand tracks. FDA 503B enforcement compresses sterile compounding into multi-state outsourcing facilities with redundant manufacturing sites. Texas and California serve as regulatory laboratories where state boards test remote prescribing frameworks for controlled substance home delivery.
Germany
EMA GMP Annex 1 alignment positions German facilities for cross-border hospital procurement. The country's national pharmaceutical regulator mandates barrier isolation technology retrofitting for open-fronted laminar flow hoods. Bavarian and Swiss outsourcing sites absorb capital requirements fastest, consolidating subcontracting relationships with Southern European compounders.
Australia
Companion animal veterinary compounding creates unmet demand for exotic species dosage forms. The Therapeutic Goods Administration maintains strict import parity standards that favor locally certified facilities. Sydney and Melbourne clusters specialize in precision weight-based therapies for veterinary practices lacking specialized suppliers.
Switzerland
Swissmedic certification commands premium positioning in European hospital outsourcing. The country's national pharmaceutical regulator enforces continuous viable particle monitoring exceeding baseline EMA requirements. Basel and Zurich facilities capture subcontracting overflow from German sites at capacity limits.
Saudi Arabia
WHO good compounding practices implementation opens procurement to internationally certified 503B-equivalent facilities. The Saudi Food and Drug Authority harmonizes quality benchmarks with Gulf Cooperation Council standards. Riyadh and Eastern Province health systems pilot standardized frameworks for sterile compounding contract awards.
Global Compounding Pharmacy Market Vendor Landscape
Capability concentration sits with one tier; scale advantage sits with another. Hospital-affiliated 503B facilities and independent specialty compounders divide the market between sterile manufacturing certification and chronic therapy relationship management. Three archetypes dominate: parenteral nutrition specialists, hormone therapy formulators, and veterinary dosage innovators. Competitive moves center on backward integration into active pharmaceutical ingredient sourcing and electronic quality management platform deployment.
Within the parenteral nutrition and hospital outsourcing tier, Fresenius Kabi and B. Braun Medical Inc. exemplify scale-driven manufacturing archetypes. Fagron occupies a position representing backward-integrated sourcing specialists controlling active pharmaceutical ingredient streams for dermatology and hormone applications. Wedgewood Pharmacy anchors the specialty pharmacy channel archetype, concentrating on veterinary and human custom dosing relationships.
| Leading Market Players |
|---|
| Fresenius Kabi |
| Fagron |
| B. Braun Medical Inc. |
| Wedgewood Pharmacy |
| Institutional Pharmacy Solutions |
| Clinigen Group PLC |
| Dougherty's Pharmacy, Inc. |
| Lorraine's Pharmacy |
| PharMEDium Services |
| Others |
Supply Flow & Price Mechanics
China's dominance in active pharmaceutical ingredient production for hormone and parenteral nutrition bases concentrates upstream margin capture, forcing downstream compounders to absorb tariff volatility and export licensing delays into pricing negotiations with hospital systems and home health networks.
Pricing Analysis
Long-term offtake agreements dominate hospital 503B contracting, with subscription models displacing spot purchasing for chronic hormone and dermatology therapies. Pricing stratifies across FDA-certified sterile facilities, 503A specialty compounders, and independent retail pharmacies based on USP 797 compliance grade and barrier isolation technology deployment. Cost compression in sterile injectables intensifies as hospital systems consolidate supplier relationships to multi-state outsourcing facilities with redundant manufacturing sites. Retail channel buyers exhibit highest price sensitivity, while hospital procurement committees prioritize inspection compliance over per-unit cost.
Supply Chain Analysis
Active pharmaceutical ingredient feedstocks draw primarily from China, India, and select European specialty chemical manufacturers, with hormone precursors and parenteral nutrition bases exhibiting highest geographic concentration. Compounding operations hinge on imported estradiol, progesterone, testosterone, and amino acid solutions subject to customs inspection delays and cold-chain integrity requirements. Single-source vulnerability in Chinese export licensing creates supply interruption risk for US and European compounders dependent on just-in-time API replenishment. Distribution runs through wholesale distributors for institutional accounts and direct-to-patient platforms for chronic therapy subscriptions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across patient-specific formulation demand creates niche opportunities for specialized compounders, as home health expansion and bioidentical hormone protocol adoption splinter volume across geographically dispersed prescriber networks.
For Market Incumbents: Insulate sterile compounding margins by accelerating barrier isolation technology deployment ahead of USP 797 enforcement waves, while consolidating backward integration into active pharmaceutical ingredient sourcing to offset Chinese tariff exposure. Defensive certification investments in multi-state 503B registration create switching costs that lock hospital systems into long-term offtake relationships. For New Entrants and Emerging Players: Australia's companion animal veterinary compounding white space offers lowest competitive density, with exotic species dosage forms and precision weight-based therapies underserved by incumbent suppliers. Telehealth-integrated direct-to-patient subscription models bypass wholesale intermediary margins and capture patient relationships previously held by retail pharmacy chains. For Investors and Strategic Acquirers: Capital is best deployed toward 503B-certified sterile facilities with demonstrated FDA inspection compliance and existing hospital system contracts, as regulatory barriers to entry protect long-term viability across the investment horizon. Watch for EMA GMP Annex 1 alignment completion as inflection signal for European cross-border contract consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Barrier Isolation Technology Deployment | USP 797 compliance mandates retrofitting open-fronted laminar flow hoods for hospital contract retention. |
| Backward Integration into API Sourcing | Captive supply of hormone and parenteral nutrition bases mitigates Chinese export licensing volatility. |
| Electronic Quality Management Platform Deployment | FDA 503B registration requires migration from paper-based batch records to virtualized compliance documentation. |
| Direct-to-Patient Subscription Launch | Telehealth integration captures chronic therapy relationships from retail pharmacy chain intermediaries. |
| Multi-State 503B Facility Expansion | Redundant manufacturing sites satisfy hospital system requirements for supply continuity assurance. |
Methodological Framework
Initial hypotheses were tested against primary input from compounding pharmacists, hospital procurement managers, regulatory affairs specialists, and veterinary practice owners and refined through secondary validation against FDA 503B registration databases, USP Chapter 795/797 guidance documents, EMA GMP Annex 1 revision filings, and hospital GPO contract awards. Bottom-up patient volume modeling and top-down pharmaceutical expenditure allocation were triangulated to reconcile segmentation outputs.
Demand-supply balance framing anchored the analytical approach across the projection horizon, with segmentation dimensions spanning dosage form, therapy area, delivery mode, and end-user regulatory cluster. CAGRs were derived from patient population growth trajectories, prescriber protocol adoption curves, and facility capacity expansion schedules, incorporating FDA enforcement intensity and EMA harmonization timelines as scenario variables.
Macroeconomic conditions sit as an overlay; deviation in healthcare reimbursement rates, API import tariff schedules, or sterile compounding technician wage inflation would shift the trajectory from baseline projections. Cross-checking against CMS Medicare Part B drug spending data and hospital 340B program utilization reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Asia-Pacific Fatty Bases for Suppositories Market
Pharmaceuticals
Hepatocellular Carcinoma Drugs Market
Pharmaceuticals
Global Immunosuppressant Drugs Market
Pharmaceuticals
Rupatadine Fumarate API Market
Pharmaceuticals
Ophthalmic Drug Delivery Systems Market
Pharmaceuticals
North America Obsessive-Compulsive Disorder (OCD) Drugs Market
Pharmaceuticals
Hyperphosphatemia Drugs Market
Pharmaceuticals
Global Non-Small Cell Lung Cancer Drugs Market
Pharmaceuticals
Germany Pneumococcal Vaccines Market
Pharmaceuticals
Peptide-Based Cancer Therapeutics Market
Pharmaceuticals
Global Small Molecule Sterile Injectable Drugs Market
Pharmaceuticals
Metoprolol Tartrate Market
Pharmaceuticals
RAS-Acting Agents Market
Pharmaceuticals
Plasma-Derived Protein Therapies Market
Pharmaceuticals
Europe G-CSF/PEG-G-CSF Market
Pharmaceuticals
Smoking Cessation Drugs Market