
 Cannabinoid Drugs Market | 2026-2036
Cannabinoid Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Cannabinoid Drugs Market Outlook
Extraction and formulation technology is tilting toward pharmaceutical-grade purification systems that isolate specific cannabinoid ratios for targeted therapeutic outcomes. Jazz Pharmaceuticals leverages its FDA-approved Epidiolex franchise to anchor epilepsy and seizure disorder markets with rigorous clinical validation. AbbVie sustains competitive presence through its legacy Marinol portfolio while navigating synthetic cannabinoid development pipelines. Tilray Brands differentiates via EU-GMP certified cultivation facilities that supply pharmaceutical-grade inputs to regulated European markets.
Cannabinoid drugs comprise purified or synthesized compounds derived from Cannabis sativa, formulated to precise concentrations typically ranging from 100 mg/mL oral solutions to metered-dose inhalation devices, serving therapeutic modulation of endocannabinoid receptors for pain, seizure, and neuropsychiatric indications. Synthetic cannabinoids occupy the most technically demanding manufacturing tier, requiring multi-step chemical synthesis under current Good Manufacturing Practice conditions that limit supplier pools and protect margin structures. Pain management applications lead volume consumption due to established reimbursement pathways, while neurological disorders represent the fastest-expanding segment driven by pediatric epilepsy protocols and multiple sclerosis spasticity treatments.
The FDA maintains Schedule V classification oversight for approved cannabinoid therapies, while the DEA's rescheduling review of cannabis continues to influence research access and interstate commerce frameworks for drug developers. Health Canada and the EMA operate parallel assessment tracks that shape multinational trial design and commercial launch sequencing for aspiring entrants. Stakeholders must monitor how national pharmaceutical regulators reconcile controlled-substance scheduling with expanding prescription indications across jurisdictions.
Market Dynamics
Pharmaceutical-grade purification systems are concentrating manufacturing capability among EU-GMP certified facilities, creating supply bottlenecks that shape competitive positioning for cannabinoid-based therapies across regulated markets.
Growth Catalysts
- Pediatric epilepsy protocols:Specialized treatment centers in Germany and Australia are expanding cannabinoid prescriptions for refractory seizure disorders, building clinical evidence bases that accelerate regulatory acceptance.
- EMA parallel assessment tracks:The European Medicines Agency's centralized marketing authorization procedures enable simultaneous multi-country launches, reducing commercialization timelines for novel cannabinoid formulations.
- Multiple sclerosis spasticity treatments:Neurological disorder clinics are integrating cannabinoid therapies into standard-of-care protocols, driving volume demand through established reimbursement frameworks.
Market Restraints
- DEA interstate commerce restrictions:The Drug Enforcement Administration's controlled-substance scheduling creates friction for multi-state distribution of cannabis-derived research materials, fragmenting supply chains.
- Multi-step chemical synthesis requirements:Synthetic cannabinoid production demands current Good Manufacturing Practice conditions that limit qualified supplier pools and protect incumbent margin structures.
- Health Canada research access barriers:Stringent licensing requirements for Schedule II substances delay clinical trial initiation and constrain pipeline advancement for developmental candidates.
Strategic Opportunities
- Pain management networks in France:ANSM regulatory pathways for hospital-based cannabinoid dispensing present expansion vectors for pharmaceutical-grade suppliers seeking European market penetration.
- Chronic pain adjacencies:Oncology and palliative care units are adopting cannabinoid co-therapies alongside opioid-sparing protocols, creating new prescription volume pools.
- Supercritical CO2 extraction convergence:Integration of chromatographic purification with automated formulation systems enables real-time cannabinoid ratio adjustment for personalized medicine applications.
Industry Challenges
- EU-GMP certification timelines:Facility validation and batch release procedures for sterile cannabinoid solutions extend 18-24 months, compressing effective patent protection windows.
- Analytical method standardization gaps:Absence of harmonized reference standards across FDA, EMA, and TGA jurisdictions forces redundant stability testing and dossier duplication.
- Endocannabinoid receptor pharmacology expertise:Shortage of medicinal chemists with specialized training in lipid signaling pathways constrains formulation innovation and clinical trial design.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cannabinoid Drugs Market |
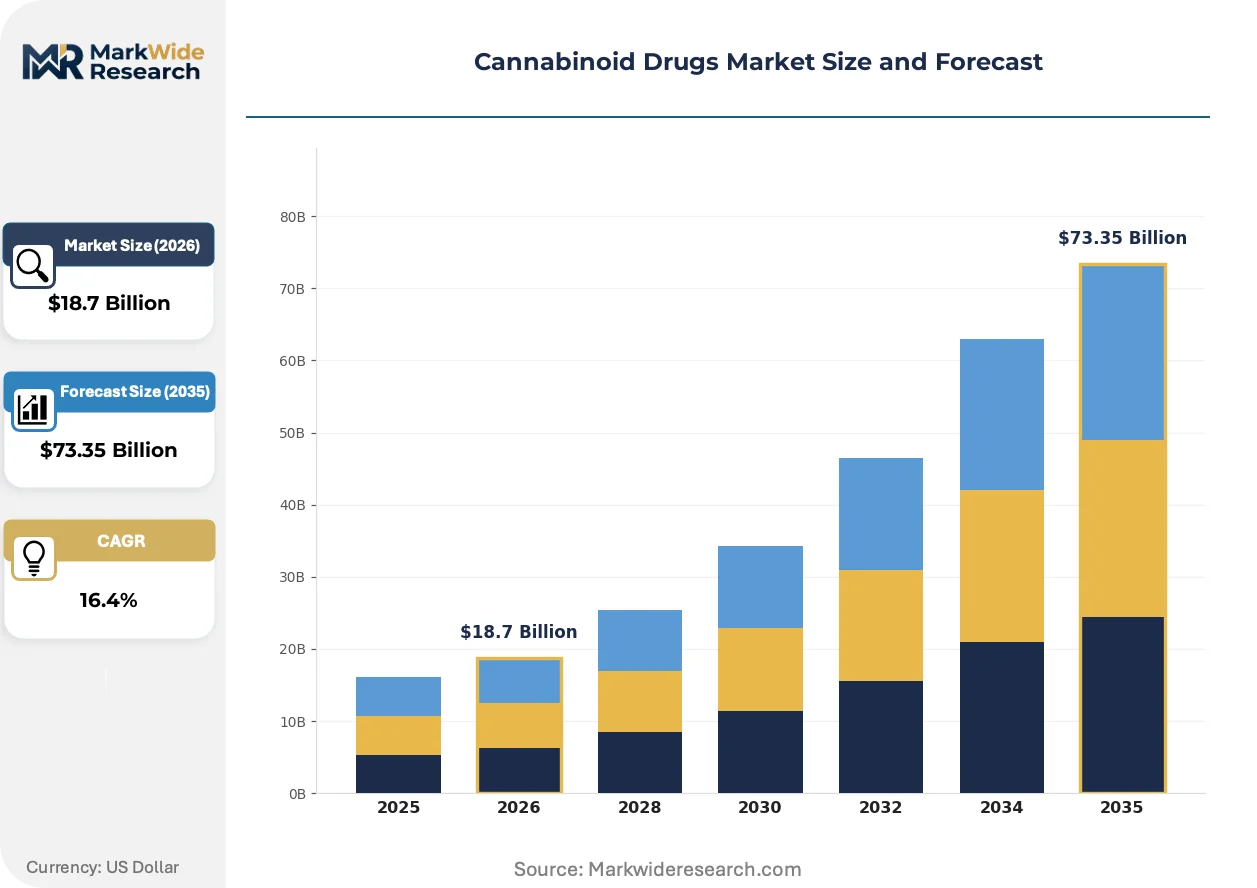
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $73.35 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cannabidiol, Tetrahydrocannabinol, Synthetic Cannabinoids, Full-Spectrum Extracts Application: Pain Management, Neurological Disorders, Oncology, Mental Health Treatments End User: Pharmacies, Hospitals, Homecare Settings, Research Institutions Delivery Mode: Oral, Inhalation, Topical, Sublingual |
| Companies Covered | Jazz Pharmaceuticals, AbbVie, Bausch Health Companies, Canopy Growth Corporation, Tilray Brands, Aurora Cannabis, Curaleaf Holdings, Green Thumb Industries, Cresco Labs, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cannabinoid Drugs Market Strategic Shifts
Continuous processing technologies are displacing batch manufacturing in cannabinoid active pharmaceutical ingredient production, compressing cycle times while tightening quality control tolerances for regulated markets.
Chromatographic isolation systems are hybridizing with in-line spectroscopic monitoring to enable real-time cannabinoid profiling during extraction. Pharmaceutical manufacturers in Switzerland and Germany are deploying these integrated platforms to reduce batch-to-batch variability. This convergence is compressing quality assurance timelines from weeks to hours while enabling certificate-of-analysis documentation that satisfies FDA and EMA inspectorate requirements.
The FDA's Epidiolex approval pathway established a regulatory template that TGA in Australia and Health Canada now reference for cannabinoid new drug applications. This harmonization reduces development redundancy but creates competitive barriers for sponsors lacking prior FDA engagement experience. Pediatric neurology and rare disease designations receive accelerated assessment priority across all three jurisdictions.
Hospital pharmacy committees are consolidating formulary decisions through centralized procurement frameworks that favor single-source contracts with integrated supply guarantees. Academic medical centers in the United States and university hospitals in the United Kingdom are displacing fragmented multi-vendor purchasing with multi-year agreements tied to outcome metrics. This concentration rewards manufacturers with captive cultivation and in-house analytical testing capabilities.
Cannabinoid Drugs Market Segmentation
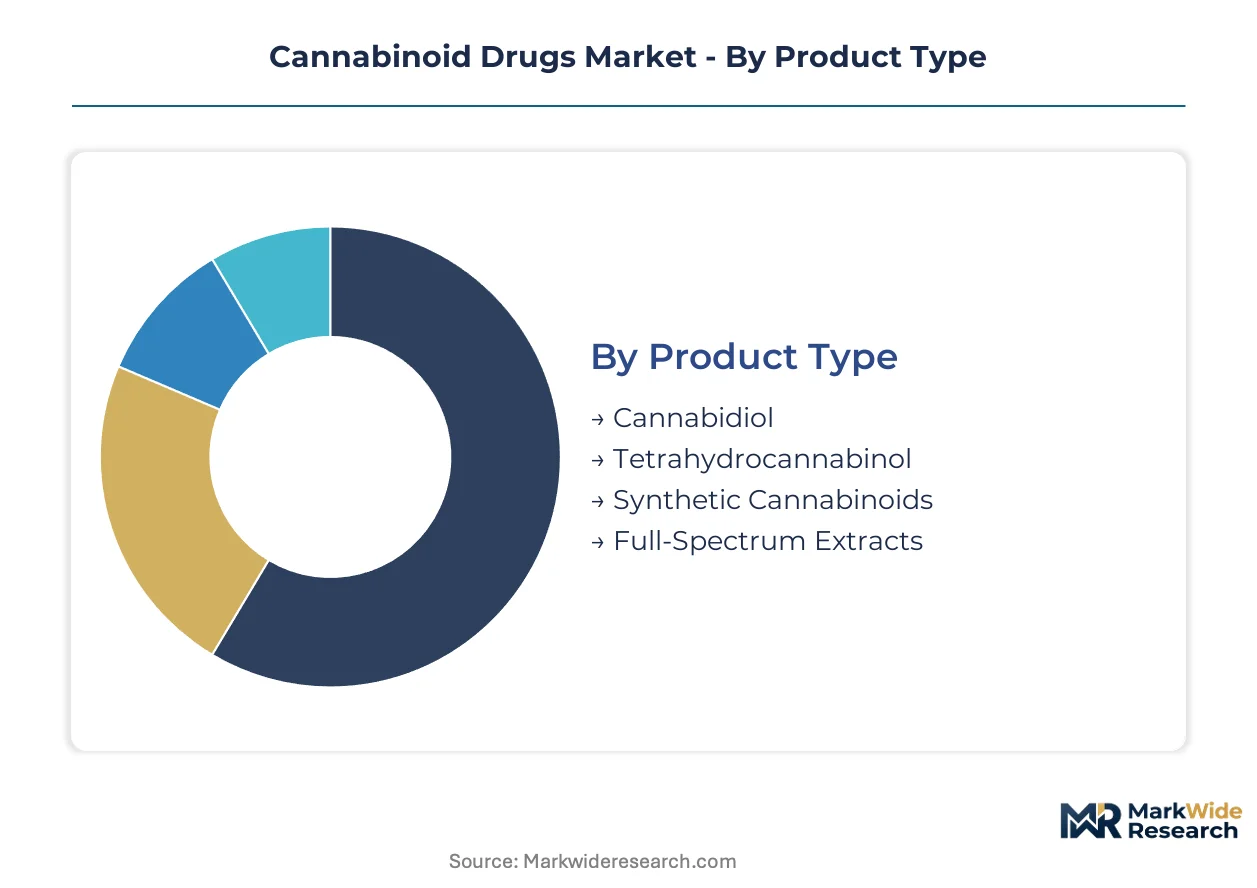
Cannabinoid drugs fragment across four structural dimensions that govern prescription velocity, reimbursement complexity, and regulatory pathway selection. Each segmentation axis carries distinct margin profiles and certification burdens that shape manufacturer resource allocation.
Product Type:
Cycle times vary dramatically: synthetic cannabinoids demand multi-year chemical synthesis validation while plant-derived isolates move through extraction scale-up in months.
- Cannabidiol:Purified non-psychoactive isolate formulated into oral solutions and capsules, typically standardized at 100 mg/mL concentrations. German neurological clinics and Australian pediatric epilepsy centers are expanding prescriptions for refractory seizure disorders, driving volume through established reimbursement frameworks.
- Tetrahydrocannabinol:Psychoactive compound requiring Schedule V or equivalent controlled-substance handling, formulated as synthetic dronabinol or plant-derived extracts. French hospital pharmacy committees are consolidating procurement through ANSM-regulated dispensing protocols, concentrating demand in academic medical centers with captive analytical testing capabilities.
- Synthetic Cannabinoids:Laboratory-synthesized analogs manufactured under current Good Manufacturing Practice conditions with extended batch release timelines.
- Full-Spectrum Extracts:Complex botanical preparations containing multiple cannabinoid ratios and terpene profiles requiring chromatographic standardization.
Cannabidiol anchors the volume base while synthetic cannabinoids gain share at the steepest rate due to patent protection and regulatory exclusivity.
Application:
Cost tiers stratify sharply: pain management commands established reimbursement codes while mental health treatments navigate experimental therapy designation hurdles.
- Pain Management:Chronic and neuropathic pain protocols in oncology and palliative care units, increasingly deployed as opioid-sparing co-therapies. North American hospital systems and European pain networks are integrating cannabinoid adjacencies into standard-of-care pathways with defined outcome metrics.
- Neurological Disorders:Pediatric epilepsy, multiple sclerosis spasticity, and movement disorder indications requiring specialized prescriber certification. The FDA's Epidiolex approval template has accelerated TGA and Health Canada assessment tracks for rare disease designations.
- Oncology:Chemotherapy-induced nausea and cancer-related pain applications with evolving evidence requirements.
- Mental Health Treatments:PTSD and anxiety disorder protocols operating under restricted research access frameworks.
Pain management dominates current prescription volumes while neurological disorders are expanding most quickly through pediatric protocol adoption.
End User:
Customer maturity determines compliance intensity: hospital formularies impose EU-GMP certification mandates while homecare channels navigate decentralized prescribing authority.
- Pharmacies:Retail and hospital-based dispensaries handling Schedule V or equivalent controlled substances with cold-chain and custody documentation.
- Hospitals:Academic medical centers and university hospitals in the United States and United Kingdom consolidating procurement through multi-year single-source contracts tied to outcome metrics.
- Homecare Settings:Patient-administered therapies requiring simplified delivery devices and caregiver training protocols.
- Research Institutions:Clinical trial sponsors and academic investigators facing DEA interstate commerce restrictions and Health Canada licensing delays.
Hospitals anchor procurement volume concentration while homecare settings are climbing the fastest as oral and sublingual formulations simplify self-administration.
Delivery Mode:
Supply concentration favors oral formulations with established analytical methods, while inhalation devices face fragmented device manufacturer ecosystems.
- Oral:Solutions, capsules, and tablets with defined bioavailability profiles and stability testing protocols recognized across FDA, EMA, and TGA jurisdictions.
- Inhalation:Metered-dose devices and vaporization systems requiring device-drug combination product pathways with extended regulatory timelines.
- Topical:Transdermal patches and localized creams for peripheral neuropathy and dermatological indications with limited systemic absorption data requirements.
- Sublingual:Rapid-absorption sprays and tinctures bridging hospital and homecare transitions with simplified titration protocols.
Oral delivery commands the installed prescription base while sublingual formats are gaining share fastest through titration flexibility and patient preference alignment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German pharmaceutical-grade extractors supply cannabinoid APIs to Australian neurological clinics and French hospital networks, creating a trans-Atlantic trade corridor anchored by EU-GMP certification standards.
United States
Academic medical centers in Massachusetts and California are consolidating formulary decisions through multi-year procurement contracts. The FDA maintains Schedule V oversight for approved therapies while DEA rescheduling reviews influence research access frameworks. Hospital pharmacy committees in the Northeast Corridor favor single-source suppliers with integrated cultivation and analytical testing capabilities.
Germany
Neurological disorder clinics in Berlin and Munich are expanding pediatric epilepsy prescriptions for refractory seizure disorders. The BfArM operates parallel assessment tracks that accelerate commercialization timelines for novel formulations. EU-GMP certified facilities in Bavaria and North Rhine-Westphalia concentrate pharmaceutical-grade purification capability for export to regulated European markets.
Australia
Specialized treatment centers in Sydney and Melbourne are building clinical evidence bases for cannabinoid-based therapies. The TGA references the FDA's Epidiolex approval pathway for new drug applications, reducing development redundancy. Research institutions in Victoria face licensing delays for Schedule II substances that constrain pipeline advancement.
Canada
Health Canada regulates research access through stringent licensing requirements that delay clinical trial initiation. Cultivation clusters in British Columbia and Ontario supply pharmaceutical-grade inputs to domestic and export markets. The PMRA operates assessment tracks that shape multinational trial design for aspiring entrants seeking North American commercialization.
Switzerland
Swissmedic oversees centralized marketing authorization procedures that enable simultaneous multi-country launches. Pharmaceutical manufacturers in Basel and Zurich deploy chromatographic isolation systems with in-line spectroscopic monitoring. These integrated platforms reduce batch-to-batch variability while satisfying FDA and EMA inspectorate requirements for certificate-of-analysis documentation.
Cannabinoid Drugs Market Competitive Environment
Channel-controlling players compete with product-specialist players across tiered market positions. The vendor base concentrates around EU-GMP certified manufacturers with captive cultivation capabilities and synthetic chemistry specialists with multi-step synthesis expertise. Three archetypes dominate: vertically integrated pharmaceutical firms with FDA-approved portfolios, EU-GMP certified cultivators supplying regulated inputs, and synthetic cannabinoid developers with patent-protected pipelines. Competitive moves center on M&A for cultivation capacity and strategic partnerships for distribution reach.
Among North American pharmaceutical developers, Jazz Pharmaceuticals and AbbVie exemplify the vertically integrated archetype with established regulatory franchises. Tilray Brands occupies a position within the EU-GMP certified cultivator tier, supplying pharmaceutical-grade inputs to regulated European hospital networks. These three entities represent contrasting strategic paths: synthetic chemistry development, legacy portfolio maintenance, and cultivation-backed supply chain control.
| Leading Market Players |
|---|
| Jazz Pharmaceuticals |
| AbbVie |
| Bausch Health Companies |
| Canopy Growth Corporation |
| Tilray Brands |
| Aurora Cannabis |
| Curaleaf Holdings |
| Green Thumb Industries |
| Cresco Labs |
| Others |
Value Chain & Pricing Dynamics
Bavarian EU-GMP certified facilities concentrate pharmaceutical-grade cannabinoid purification capacity, translating batch-release bottlenecks into sustained pricing power for sterile solution manufacturers serving German hospital networks and Australian neurological clinics.
Pricing Analysis
Batch-process versus continuous-process manufacturing technologies create a pronounced pricing gap, with legacy batch systems commanding 15-25% cost premiums due to extended EU-GMP validation timelines. Pricing stratifies across pharmaceutical-grade certification tiers, with synthetic cannabinoid producers capturing margin premiums through patent-protected exclusivity while plant-derived isolates compete on cultivation scale and chromatographic efficiency. Cost compression in oral solution formulations is intensifying as supercritical CO2 extraction platforms reduce solvent waste and labor intensity. Academic medical centers exhibit the lowest price sensitivity due to single-source procurement mandates tied to outcome guarantees, while retail pharmacies face margin pressure from fragmented multi-vendor purchasing.
Supply Chain Analysis
DEA Schedule II and Health Canada Schedule II export-control regimes restrict interstate and cross-border flows of cannabis-derived research materials, fragmenting supply chains for clinical trial sponsors. Manufacturing gravity centers on Germany, Canada, and Switzerland, with Bavarian and North Rhine-Westphalia facilities supplying APIs to Australian TGA-regulated markets and French hospital networks. Raw material dependencies include pharmaceutical-grade ethanol for extraction, chromatography resins for purification, and synthetic precursor chemicals for dronabinol production. Single-source vulnerability concentrates in EU-GMP certified sterile formulation capacity, where 18-24 month facility validation timelines protect incumbent margin structures. Distribution runs through hospital pharmacy committees consolidating formulary decisions through multi-year single-source contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cannabinoid drugs market functions as a service-attach opportunity where analytical testing and batch certification services expand faster than API production, as hospital procurement committees demand integrated certificate-of-analysis documentation and cold-chain custody guarantees.
For Market Incumbents: Build regulatory dossier moats by advancing parallel FDA-EMA-TGA submission tracks that exhaust emerging sponsors lacking prior agency engagement experience. Deepen backward integration into captive EU-GMP certified cultivation to secure supply guarantees for single-source hospital contracts, while investing in continuous processing technologies that compress batch release timelines and defend margin structures against synthetic cannabinoid patent cliffs. For New Entrants and Emerging Players: Establish a beachhead in French pain management networks where ANSM hospital-based dispensing protocols present lower regulatory barriers than FDA or EMA centralized tracks. Target pediatric epilepsy adjacencies in Australian neurological clinics referencing the Epidiolex approval template, deploying supercritical CO2 extraction partnerships with existing EU-GMP facilities to bypass 18-24 month certification timelines. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-exclusivity play because synthetic cannabinoid pipelines with orphan drug designations command extended market protection and premium pricing power. Acquisition targets should concentrate on medicinal chemistry specialists with lipid signaling pathway expertise and EU-GMP certified cultivators with export capacity to regulated European markets. The signal to watch is DEA rescheduling momentum, which would unlock research access and compress development timelines for developmental candidates.| Strategic Initiative | Industry Significance |
|---|---|
| EU-GMP Certification Investment | Bavarian facility validation enables API exports to Australian TGA-regulated neurological clinics. |
| Continuous Processing Adoption | Chromatographic isolation with in-line spectroscopy reduces batch-to-batch variability for FDA inspectorate compliance. |
| Parallel Regulatory Submission | Simultaneous FDA-EMA tracks accelerate commercialization timelines for pediatric epilepsy protocols. |
| Synthetic Chemistry Pipeline | Patent-protected dronabinol analogs protect margin structures against plant-derived commoditization. |
| Hospital System Partnership | Multi-year single-source contracts with academic medical centers lock in volume through outcome metrics. |
Study Parameters
A standing panel of drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers provided ongoing calibration against secondary validation from FDA filings, EMA submissions, ClinicalTrials.gov, and hospital procurement databases. Primary fieldwork combined structured interviews with synthetic cannabinoid manufacturers and EU-GMP certified cultivators, cross-referenced against customs data and SEC 10-K disclosures from publicly traded pharmaceutical developers. Bottom-up prescription volume modeling and top-down market sizing triangulated across these inputs to constrain estimate variance.
Scenario-bracketing framed demand projections across conservative, baseline, and accelerated regulatory acceptance pathways throughout the forecast period. Segmentation dimensions modeled include product type, application, end user, delivery mode, and regional regulatory cluster. CAGRs were derived from prescription velocity trends in pediatric epilepsy and multiple sclerosis spasticity protocols, weighted by reimbursement pathway maturity and EU-GMP certification penetration rates.
Stress conditions across DEA rescheduling timelines, Health Canada licensing delays, and EU-GMP facility validation backlogs were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions regarding EMA-FDA-TGA regulatory harmonization and synthetic cannabinoid patent cliff sequencing. Material shifts in controlled-substance scheduling or pediatric neurology reimbursement policy would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Nausea Medicine Market
Pharmaceuticals
Plasma-Derived Protein Therapies Market
Pharmaceuticals
Global Alteplase Market
Pharmaceuticals
Novel Drug Delivery Systems in Cancer Therapy Market
Pharmaceuticals
Gemcitabine Hydrochloride Market
Pharmaceuticals
Veterinary Pain Management Drugs Market
Pharmaceuticals
Carbetocin Acetate Market
Pharmaceuticals
Water for Injection Market
Pharmaceuticals
Vutrisiran Market
Pharmaceuticals
India Nicotine Replacement Therapy Market
Pharmaceuticals
Germany Pharmaceutical 3PL Market
Pharmaceuticals
Antibody Therapy Market
Pharmaceuticals
Oral Thin Film Drugs Market
Pharmaceuticals
Antiplatelet Market
Pharmaceuticals
Global Rheumatoid Arthritis Therapeutics Market
Pharmaceuticals
Oral Solid Dosage Pharmaceutical Formulation Market