
 Digital Pharmaceutical Supply Chain Management Market | 2026-2036
Digital Pharmaceutical Supply Chain Management Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Pharmaceutical Supply Chain Management Market Analytics
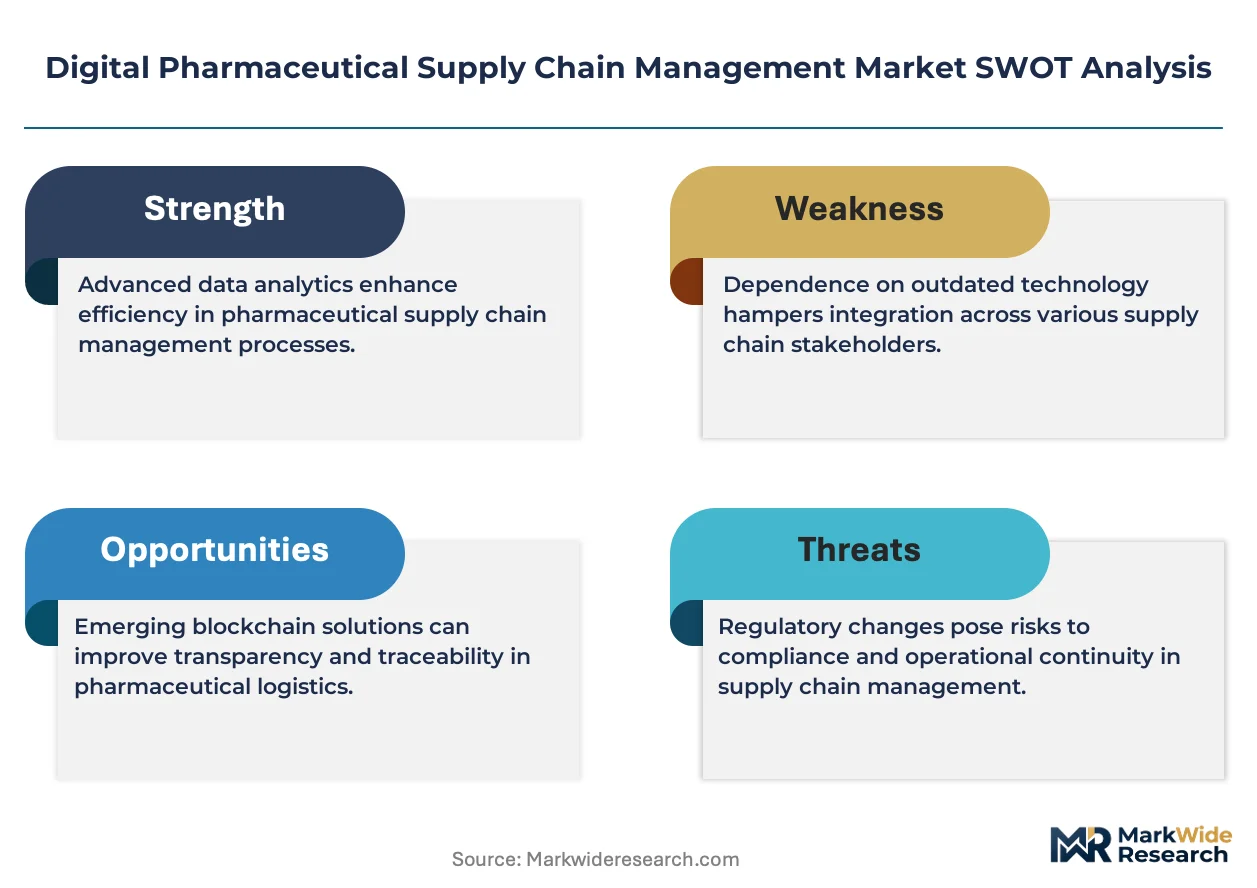
Modular platform bundling is consolidating buyer choice in digital pharmaceutical supply chain management, as vendors combine inventory, logistics, and traceability tools into unified suites rather than standalone modules. Oracle leverages its cloud infrastructure to anchor enterprise deployments across multinational drug manufacturers. SAP competes through deep ERP integration that sustains incumbent relationships with large wholesalers. TraceLink specializes in compliance-centric network architecture that dominates drug traceability mandates in regulated markets.
Digital pharmaceutical supply chain management encompasses software platforms, sensor networks, and data analytics layers that coordinate pharmaceutical inventory flows, temperature monitoring, and regulatory documentation across multi-tier distribution networks. These systems integrate IoT telemetry, blockchain ledgers, and AI-driven demand forecasting to maintain product integrity and serialization compliance from manufacturer to dispenser. Cloud computing deployments lead technology adoption due to scalability requirements across geographically dispersed supply chains, while blockchain applications in drug traceability represent the fastest-growing segment as serialization deadlines tighten. Pharmaceutical companies command the largest end-user spend, though cold chain logistics functionality captures disproportionate margin pools due to specialized sensor hardware and real-time monitoring requirements.
FDA DSCSA enforcement, EU FMD traceability standards, and WHO prequalification protocols collectively shape product requirements and market access conditions for platform vendors. The FDA mandates interoperable electronic track-and-trace systems that force wholesalers and manufacturers to upgrade legacy infrastructure or risk distribution penalties. Stakeholders must monitor regulatory divergence between US serialization rules and EU authentication requirements when architecting cross-border platform deployments.
Market Dynamics
FDA DSCSA enforcement deadlines and EU FMD serialization mandates are compressing technology upgrade cycles across pharmaceutical distribution networks, forcing wholesalers and manufacturers to replace legacy track-and-trace infrastructure with interoperable electronic systems or face operational lockouts.
Growth Catalysts
- Biopharma cold chain expansion:Temperature-sensitive biologics now comprise the fastest-growing pharmaceutical product category, driving demand for real-time IoT sensor networks and automated excursion alerting across distribution lanes.
- FDA DSCSA November 2024 enforcement:The US regulator's mandate for unit-level electronic track-and-trace interoperability compels wholesale distributors to deploy serialization platforms or risk suspension of distribution licenses.
- Cloud infrastructure maturation:Hyperscale computing providers have reduced latency and compliance certification costs for pharmaceutical workloads, enabling mid-tier manufacturers to access enterprise-grade supply chain orchestration tools previously reserved for top-tier drug makers.
Market Restraints
- Semiconductor sensor supply concentration:Specialized temperature and humidity sensors for pharmaceutical cold chain applications source primarily from East Asian fabrication facilities, exposing buyers to geographic concentration risk and extended lead times.
- Blockchain interoperability gaps:Competing ledger protocols and proprietary serialization formats prevent seamless data exchange between pharmaceutical trading partners, fragmenting network effects and inflating integration costs.
- Legacy ERP lock-in:Incumbent pharmaceutical manufacturers operate deeply customized enterprise resource planning systems that resist modular API-based integration with modern supply chain platforms, extending deployment timelines.
Strategic Opportunities
- Cell and gene therapy logistics:Ultra-cold chain requirements for CAR-T and gene editing therapies create premium service tiers for specialized logistics providers capable of maintaining cryogenic conditions through last-mile delivery.
- India pharmaceutical manufacturing:The country's expanding role as a generic drug supplier to regulated markets creates demand for EU FMD-compliant serialization infrastructure among domestic manufacturers seeking European market access.
- AI-driven demand forecasting convergence:Machine learning models trained on real-time distribution data and epidemiological surveillance are enabling pharmaceutical inventory positioning that reduces waste from expiry while preventing stockouts.
Industry Challenges
- Serialization data governance talent:Pharmaceutical companies face acute shortages of professionals capable of managing master data alignment across contract manufacturing organizations, third-party logistics providers, and dispensers under divergent regulatory schemas.
- Multi-enterprise system integration:Harmonizing batch records, quality documentation, and chain-of-custody data across dozens of trading partners with incompatible technology stacks consumes implementation resources and delays value realization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Pharmaceutical Supply Chain Management Market |
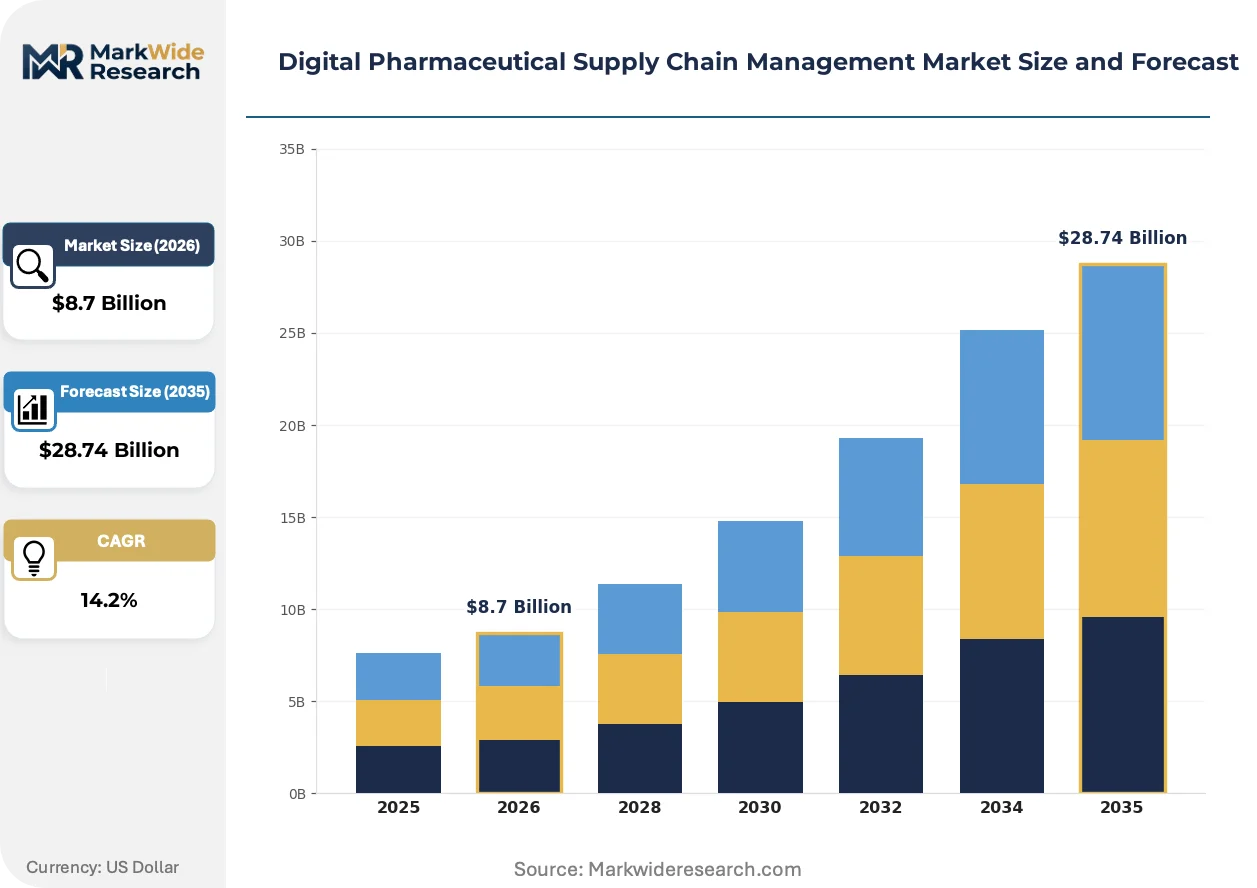
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inventory Management, Order Fulfillment, Logistics Tracking, Quality Control End User: Pharmaceutical Companies, Wholesalers, Distributors, Pharmacies Technology: Blockchain, AI Analytics, IoT Solutions, Cloud Computing Application: Clinical Supply Management, Cold Chain Logistics, Drug Traceability, Risk Management |
| Companies Covered | McKesson Corporation, Oracle, SAP, Palantir Technologies, Infor, Tecsys, InterSystems Corporation, TraceLink, Jump Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Pharmaceutical Supply Chain Management Market Evolving Landscape
Digital pharmaceutical supply chain platforms are absorbing artificial intelligence layers that transform passive track-and-trace compliance into predictive supply orchestration, compressing the gap between regulatory minimums and operational competitive advantage.
Blockchain-based drug traceability architecture is absorbing pharmaceutical industry investment as serialization deadlines tighten, with distributed ledger implementations providing immutable custody records that satisfy FDA DSCSA verification requirements while enabling automated suspect product quarantine. Large molecule manufacturers and specialty pharmacies are adopting these systems fastest, drawn by the combined pressure of regulatory enforcement and biologics counterfeiting risks. The technology is absorbing compliance budget allocations that previously funded manual audit processes, reallocating quality assurance resources toward exception-based intervention.
EMA's evolving guidance on data integrity and computerized systems is forcing pharmaceutical manufacturers to upgrade validation protocols for cloud-hosted supply chain applications, with the European regulator's inspection focus shifting toward audit trails and access controls in multi-tenant software environments. Contract manufacturing organizations serving EU markets face the steepest compliance burden, re-architecting quality management systems to demonstrate continuous data integrity across geographically dispersed server infrastructure. German and French drug makers are responding by consolidating vendor relationships with platforms pre-certified for EU GMP Annex 11 compliance.
Hospital and health system procurement departments are consolidating pharmaceutical supplier relationships around integrated supply chain visibility, with integrated delivery networks now requiring real-time inventory transparency and automated replenishment signals as table stakes for formulary inclusion. This concentration is displacing fragmented purchasing arrangements where multiple wholesalers served single health systems through non-integrated channels. The shift is most pronounced in United States metropolitan markets where vertical integration between payers, pharmacies, and distribution has advanced furthest.
Digital Pharmaceutical Supply Chain Management Market Segmentation
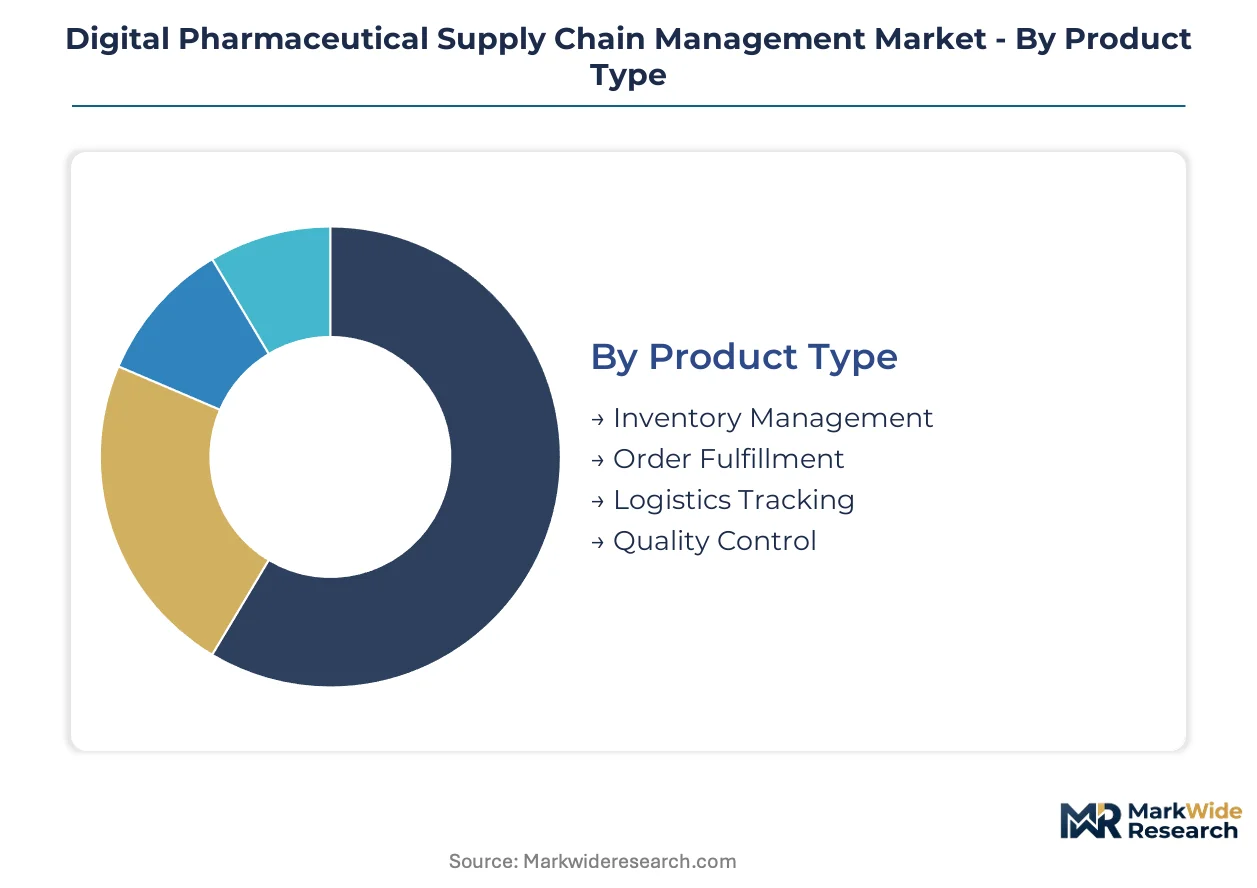
Segmentation in digital pharmaceutical supply chain management reveals how technology specialization and regulatory pressure concentrate investment across distinct operational layers. Platform vendors architect modular capabilities around specific compliance mandates and temperature sensitivity requirements rather than one-size-fits-all deployment.
Product Type:
Technology architecture determines functional depth across product categories, with cloud-native platforms enabling faster iteration than on-premise legacy systems.
- Inventory Management:Real-time batch tracking and expiry monitoring systems coordinate stock positioning across contract manufacturing organizations and third-party logistics networks. Pharmaceutical manufacturers in Germany and the United States deploy these modules first to satisfy EMA and FDA documentation requirements for product recalls.
- Order Fulfillment:Automated allocation engines synchronize demand signals from hospital procurement systems with wholesaler availability, reducing manual intervention in high-volume generic distribution. Japanese pharmaceutical distributors prioritize these capabilities to manage just-in-time delivery contracts with metropolitan health systems.
- Logistics Tracking:Multi-modal shipment visibility platforms aggregate carrier data across air, ocean, and ground transportation lanes.
- Quality Control:Electronic batch record systems enforce deviation management protocols and automated CAPA workflows.
Mature deployment sits with Inventory Management. Newer deployment is concentrated in Quality Control as EMA inspection intensity rises.
End User:
Buyer sophistication and compliance exposure shape procurement patterns across the value chain, with direct regulatory contact driving premium platform investment.
- Pharmaceutical Companies:Originators and generic manufacturers deploy end-to-end orchestration layers spanning manufacturing execution through distribution, absorbing the highest per-seat licensing costs. Large molecule producers in Switzerland and the United States lead adoption of integrated suites combining serialization with cold chain telemetry.
- Wholesalers:Regional and national distributors face the steepest FDA DSCSA interoperability mandates, forcing technology refresh cycles that prioritize verification router service connectivity over advanced analytics.
- Distributors:Specialized logistics providers serving specialty pharmacy channels invest in modular cold chain extensions rather than full platform replacement.
- Pharmacies:Hospital and retail dispensers consume downstream visibility tools through wholesaler-provided portals, with limited direct platform procurement.
Revenue concentration tilts toward Pharmaceutical Companies. Fastest capability expansion is occurring among Wholesalers confronting serialization deadlines.
Technology:
Infrastructure choices determine scalability boundaries and integration complexity, with hybrid architectures dominating regulated pharmaceutical environments.
- Blockchain:Distributed ledger implementations provide immutable chain-of-custody records that satisfy FDA DSCSA verification requirements while enabling automated suspect product quarantine. Specialty pharmacies and large molecule manufacturers in the United States adopt these systems fastest due to biologics counterfeiting exposure.
- AI Analytics:Machine learning models trained on distribution data and epidemiological surveillance enable demand forecasting that reduces expiry waste while preventing stockouts.
- IoT Solutions:Temperature and humidity sensor networks with real-time alerting capabilities protect cold chain integrity for biologics and vaccines.
- Cloud Computing:Hyperscale infrastructure reduces compliance certification costs for pharmaceutical workloads, enabling mid-tier manufacturers to access enterprise-grade orchestration.
Established deployment clusters around Cloud Computing. Steepest investment trajectory belongs to Blockchain as serialization enforcement tightens.
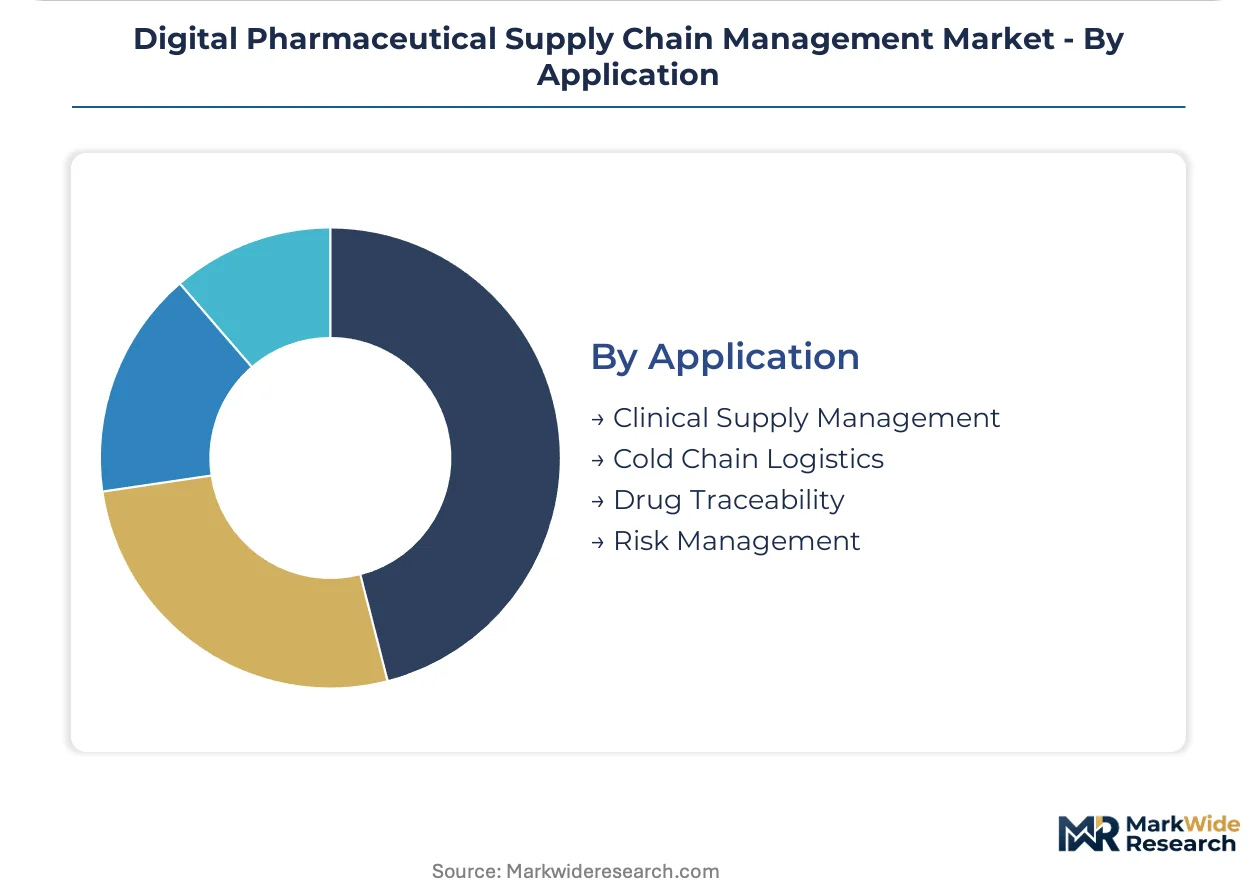
Application:
Operational use cases align with product risk profiles and regulatory touchpoints, with temperature-sensitive categories commanding disproportionate technology spend.
- Cold Chain Logistics:Ultra-low temperature monitoring systems with automated excursion alerting protect cell therapies, vaccines, and biologics through last-mile delivery. CAR-T therapy distributors in the United States and Germany require cryogenic condition maintenance that drives specialized hardware and real-time telemetry investment.
- Drug Traceability:Unit-level serialization and verification systems enforce regulatory compliance across distribution networks, with interoperability mandates forcing platform standardization.
- Clinical Supply Management:Investigator site inventory coordination and patient-specific kit assembly workflows support decentralized trial execution.
- Risk Management:Predictive analytics for supply disruption and counterfeit detection layer across underlying transaction data.
Capability maturity resides in Drug Traceability. Emerging deployment concentrates in Cold Chain Logistics as biologics expand their therapeutic share.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical supply chain technology production concentrates in enterprise software hubs, while consumption spreads across manufacturing and distribution networks in regulated markets. The United States absorbs the largest platform deployment spend, driven by FDA enforcement timelines and complex wholesale consolidation. Germany and Japan follow as serialization mandates reshape distribution infrastructure.
United States
FDA DSCSA November 2024 enforcement deadlines and biopharma cold chain expansion drive platform procurement. The Drug Supply Chain Security Act mandates unit-level electronic track-and-trace interoperability for wholesale distributors. Greater Boston hosts specialized logistics providers serving cell therapy manufacturers with cryogenic monitoring capabilities.
Germany
EU FMD serialization requirements and EMA inspection intensity for data integrity propel technology upgrades. The European Medicines Agency's evolving guidance on computerized systems forces validation protocol revisions for cloud-hosted applications. The Rhine-Ruhr corridor anchors pharmaceutical distribution networks where wholesalers consolidate vendor relationships around pre-certified platforms.
Japan
PMDA traceability standards and just-in-time delivery contracts with metropolitan health systems shape procurement priorities. The Pharmaceuticals and Medical Devices Agency enforces serialization rules aligned with global standards. The Kanto region around Tokyo concentrates pharmaceutical distributors investing in automated allocation engines for hospital procurement systems.
India
Generic drug export growth to regulated markets and CDSCO quality compliance requirements create infrastructure demand. The Central Drugs Standard Control Organization aligns domestic standards with WHO prequalification protocols. Gujarat and Maharashtra host contract manufacturers deploying EU FMD-compliant serialization to secure European market access.
Switzerland
Large molecule manufacturing concentration and Swissmedic oversight of biologics distribution drive premium platform adoption. The national pharmaceutical regulator enforces chain-of-custody documentation for temperature-sensitive therapies. Basel anchors Novartis and Roche supply chain operations where integrated suites combine serialization with cold chain telemetry.
Digital Pharmaceutical Supply Chain Management Market Competitive Landscape
The competitive structure tilts toward enterprise software incumbents with cloud infrastructure scale. Oracle leverages hyperscale computing to anchor multinational drug manufacturer deployments. SAP sustains wholesaler relationships through deep ERP integration. TraceLink dominates compliance-centric network architecture for drug traceability mandates. Strategic moves concentrate on modular platform bundling and M&A to fill capability gaps in cold chain telemetry.
Among enterprise technology providers, Oracle, SAP, and TraceLink exemplify three distinct competitive archetypes. Oracle occupies the cloud-native infrastructure position, anchoring deployments that require global scalability. SAP represents the incumbent ERP extension model, embedding supply chain modules within existing enterprise relationships. TraceLink sits within the specialized compliance network tier, architecting solutions around regulatory verification requirements rather than general operational efficiency.
| Leading Market Players |
|---|
| McKesson Corporation |
| Oracle |
| SAP |
| Palantir Technologies |
| Infor |
| Tecsys |
| InterSystems Corporation |
| TraceLink |
| Jump Technologies |
| Others |
Value Network & Pricing Analysis
FDA DSCSA enforcement deadlines and EU FMD serialization mandates are compressing technology procurement cycles, forcing wholesale distributors and manufacturers to absorb premium platform costs or face operational lockouts from regulated markets. This regulatory stickiness grants pricing power to vendors with pre-certified compliance architectures while squeezing margins for buyers locked into legacy system migrations.
Pricing Analysis
Cost compression in mid-tier manufacturer segments reflects hyperscaler cloud infrastructure maturation, which has democratized access to enterprise-grade orchestration tools previously reserved for top-tier drug makers. Three-tier pricing structure across premium, standard, and economy levels segments by compliance certification depth and cold chain telemetry integration, with FDA DSCSA pre-certification commanding substantial premiums. Pricing pressure stems from semiconductor sensor supply concentration in East Asian fabrication facilities, extending hardware lead times and inflating real-time monitoring module costs. Hospital procurement departments exhibit highest price sensitivity through formulary consolidation, while cell therapy manufacturers show lowest sensitivity due to cryogenic condition requirements.
Supply Chain Analysis
Specialized temperature and humidity sensor fabrication talent concentrates in Taiwan, South Korea, and Japan, creating geographic chokepoints for pharmaceutical cold chain hardware procurement. Component dependencies span precision MEMS sensors, lithium battery cells for IoT telemetry devices, and pharmaceutical-grade packaging substrates. Single-source vulnerability in East Asian semiconductor fabrication exposes buyers to extended lead times and geographic concentration risk. Distribution runs through multinational wholesalers consolidating around pre-integrated platform suites, displacing fragmented purchasing arrangements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The digital pharmaceutical supply chain management market functions as a cost-of-compliance story where FDA DSCSA serialization mandates erect substantial barrier-to-entry moats, privileging vendors with verified interoperability architectures and locking out speculative entrants lacking regulatory certification depth.
For Market Incumbents: To counter modular platform bundling by cloud-native competitors, SAP and Oracle must deepen ERP integration moats through API standardization investments that reduce legacy system replacement friction. Wholesaler consolidation around pre-certified platforms demands defensive certification maintenance in EU GMP Annex 11 and FDA DSCSA verification router service connectivity. Cold chain telemetry capability gaps should be filled through targeted sensor network partnerships rather than organic hardware development. For New Entrants and Emerging Players: Contract manufacturing organizations in India present the most penetrable entry vector, as CDSCO quality compliance requirements and EU FMD export ambitions create demand for affordable serialization infrastructure among generic drug suppliers seeking European market access. White-space concentration sits with AI-driven demand forecasting modules that reduce expiry waste, an area where incumbent platforms remain underdeveloped. Go-to-market execution should anchor in channel partnerships with Indian pharmaceutical export associations and Gujarat-based manufacturing clusters. For Investors and Strategic Acquirers: The window for entry favors specialized compliance network architects with verified FDA DSCSA and EU FMD interoperability, as regulatory enforcement timelines compress upgrade cycles and concentrate buyer spend. Long-term viability hinges on platform consolidation around cloud-native infrastructure with modular cold chain extensions. Acquisition target archetype: mid-tier serialization specialists with pre-certified EMA validation protocols and established wholesaler relationships. The signal to watch is FDA enforcement variance between wholesale distributor verification requirements and dispenser downstream obligations.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies inventory, logistics, and traceability modules into FDA DSCSA-compliant suites for multinational drug manufacturers. |
| Acquisition of Specialist Firm | Fills cold chain telemetry gaps through sensor network providers serving CAR-T therapy distributors in Germany and the United States. |
| Strategic Partnership | Links cloud infrastructure providers with contract manufacturers in Gujarat seeking EU FMD-compliant serialization for European market access. |
| Geographic Expansion | Establishes EU GMP Annex 11 pre-certified operations in the Rhine-Ruhr corridor to capture EMA inspection-driven upgrades. |
| Product Launch | Introduces AI-driven demand forecasting modules trained on epidemiological surveillance to reduce pharmaceutical expiry waste. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced with primary interviews involving supply chain executives at multinational drug manufacturers, regulatory affairs leads at contract manufacturing organizations, wholesale distributor technology officers, and hospital procurement managers. FDA DSCSA implementation timelines, EMA inspection reports, and WHO prequalification protocols supplied external validation benchmarks. Bottom-up platform deployment estimates triangulated against top-down pharmaceutical logistics spend projections.
Granularity-level modeling operated at technology segment, end-user category, and regional regulatory cluster dimensions, with cold chain logistics functionality and drug traceability applications receiving distinct treatment due to divergent hardware and software cost structures. CAGRs across the analysis window derived from regression against pharmaceutical distribution volume growth, biologics cold chain expansion rates, and regulatory enforcement phase-in schedules. Epidemiological surveillance integration and cell therapy logistics requirements informed demand-side elasticity assumptions.
Several conditions sit outside the modeled scope, including potential blockchain protocol standardization breakthroughs, semiconductor fabrication capacity relocation outside East Asia, and fundamental shifts in FDA DSCSA enforcement intensity. Forecasts reflect assumptions regarding regulatory timeline adherence and cloud infrastructure cost trajectories. Material deviation in serialization mandate deadlines, sensor supply chain disruption severity, or AI model regulatory acceptance warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Etomidate Market
Pharmaceuticals
Cervical Cancer Vaccine Market
Pharmaceuticals
Asia-Pacific Over-The-Counter (OTC) Drugs Market
Pharmaceuticals
Schizophrenia Drugs Market
Pharmaceuticals
Omega 3 Prescription Drugs Market
Pharmaceuticals
Skin Cancer Drugs Market
Pharmaceuticals
OX40 Receptor Agonist Market
Pharmaceuticals
North America Novel Drug Delivery Systems (NDDS) Market
Pharmaceuticals
Acetaminophen Injection Market
Pharmaceuticals
Global Postpartum Depression Drugs Market
Pharmaceuticals
Cancer Immunotherapy Drug Discovery Outsourcing Market
Pharmaceuticals
Global Central Nervous System (CNS) Stimulant Drugs Market
Pharmaceuticals
Pregnenolone Market
Pharmaceuticals
Depression and Seasonal Affective Disorder Therapeutics Market
Pharmaceuticals
Canada Specialty Pharmacy Market
Pharmaceuticals
Alirocumab Market