
 China Opioids Market | 2026-2036
China Opioids Market Size, Share, and Industry Trends Forecast 2026-2036
China Opioids Market Insights
The NMPA's 2019 Drug Administration Law is rebalancing distribution accountability toward licensed hospital pharmacies and away from fragmented retail channels. Shanghai Pharmaceuticals leverages its state-backed logistics network to sustain dominance in institutional procurement across eastern provinces. Sinopharm Group anchors national supply security through centralized storage and cold-chain infrastructure. Yangtze River Pharmaceutical Group differentiates via concentrated R&D investment in synthetic opioid analogs with modified-release profiles.
China opioids comprise natural, semi-synthetic, and fully synthetic alkaloid compounds that activate mu-opioid receptors to modulate nociceptive signaling, with purity grades typically exceeding 99.5% for injectable formulations under Chinese Pharmacopoeia standards. These compounds serve primarily as analgesic and anesthetic agents in surgical, oncological, and terminal-care settings where non-opioid alternatives prove inadequate. Fentanyl and its analogs command the fastest-expanding product share due to transdermal patch adoption in chronic cancer pain protocols. Hospitals absorb the dominant volume of morphine and oxycodone consumption, while home care channels represent an emerging but constrained growth vector under strict Narcotic Drug Special Card requirements. Injectable delivery modes retain priority in perioperative anesthesia, though oral formulations gain ground in extended palliative regimens.
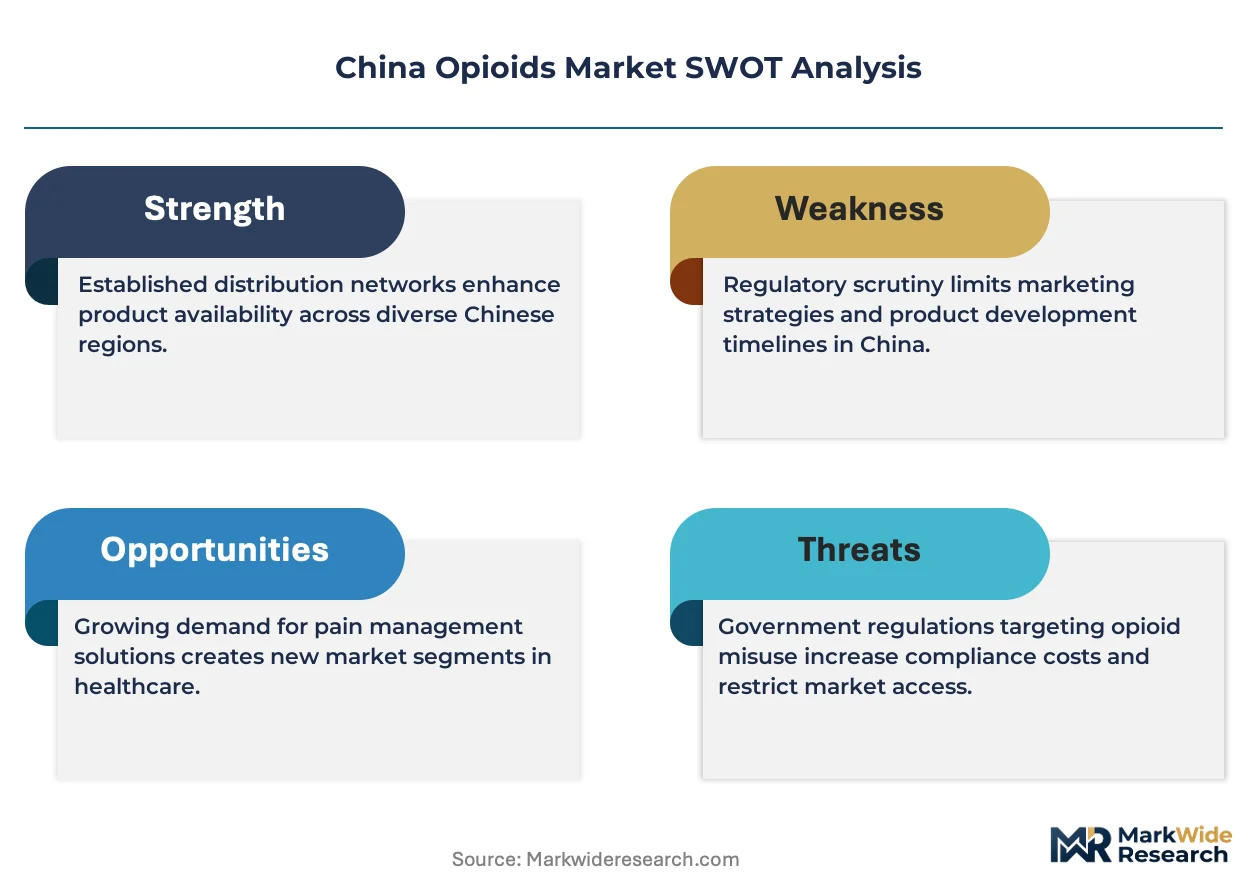
NMPA licensing frameworks, Ministry of Public Security narcotic traceability mandates, and National Health Commission opioid prescription quota systems collectively constrain market entry and channel behavior. MEE environmental discharge standards for active pharmaceutical ingredient manufacturing further elevate compliance costs for domestic producers. Stakeholders must monitor the interplay between centralized procurement price negotiations and sustained R&D incentives for abuse-deterrent formulation development.
Market Dynamics
NMPA's narcotic traceability mandates and centralized procurement reforms are compressing informal distribution channels while concentrating volume through state-affiliated hospital networks.
Growth Catalysts
- Palliative infrastructure expansion:Oncology center construction in Jiangsu and Zhejiang provinces is expanding institutional pain management capacity. Hospital pharmacies in these provinces now handle elevated morphine and fentanyl volumes.
- Modified-release formulation R&D:Synthetic opioid analogs with extended-release profiles are reducing dosing frequency for chronic cancer patients. Domestic manufacturers are prioritizing these profiles over immediate-release generics.
- Narcotic Drug Special Card system:The Ministry of Public Security's patient registration framework is formalizing home-care channel access for terminal cases. This creates controlled expansion beyond acute hospital settings.
Market Restraints
- API environmental compliance:MEE discharge standards for active pharmaceutical ingredient manufacturing are elevating capital requirements for domestic producers. Smaller synthesis facilities face consolidation pressure.
- Prescription quota rigidities:National Health Commission opioid allocation ceilings constrain per-hospital procurement flexibility. Tier-three municipal facilities report quota exhaustion during peak oncology admission periods.
- Import dependency for precursor chemicals:Domestic manufacturers rely on concentrated overseas suppliers for specialized opioid synthesis intermediates. Geopolitical friction disrupts just-in-time precursor availability.
Strategic Opportunities
- Abuse-deterrent formulation development:NMPA's evolving technical guidelines for tamper-resistant products create first-mover advantages. Manufacturers investing in polymer-matrix and agonist-antagonist combinations capture premium positioning.
- Cold-chain distribution infrastructure:Transdermal fentanyl patch expansion requires temperature-controlled logistics networks. Regional distributors with SAMR-certified cold storage capabilities capture emerging channel share.
- Dual carbon alignment:Green synthesis process patents align with national decarbonization targets. Facilities demonstrating carbon-negative API production qualify for preferential licensing review.
Industry Challenges
- Specialized pharmacovigilance talent scarcity:Narcotic adverse event reporting requirements exceed training capacity at provincial regulatory affairs departments. Manufacturers face delayed batch release timelines.
- Legacy ERP integration with traceability platforms:Hospital pharmacy management systems require expensive retrofitting to interface with NMPA's centralized narcotic monitoring database. Implementation timelines extend procurement digitization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Opioids Market |
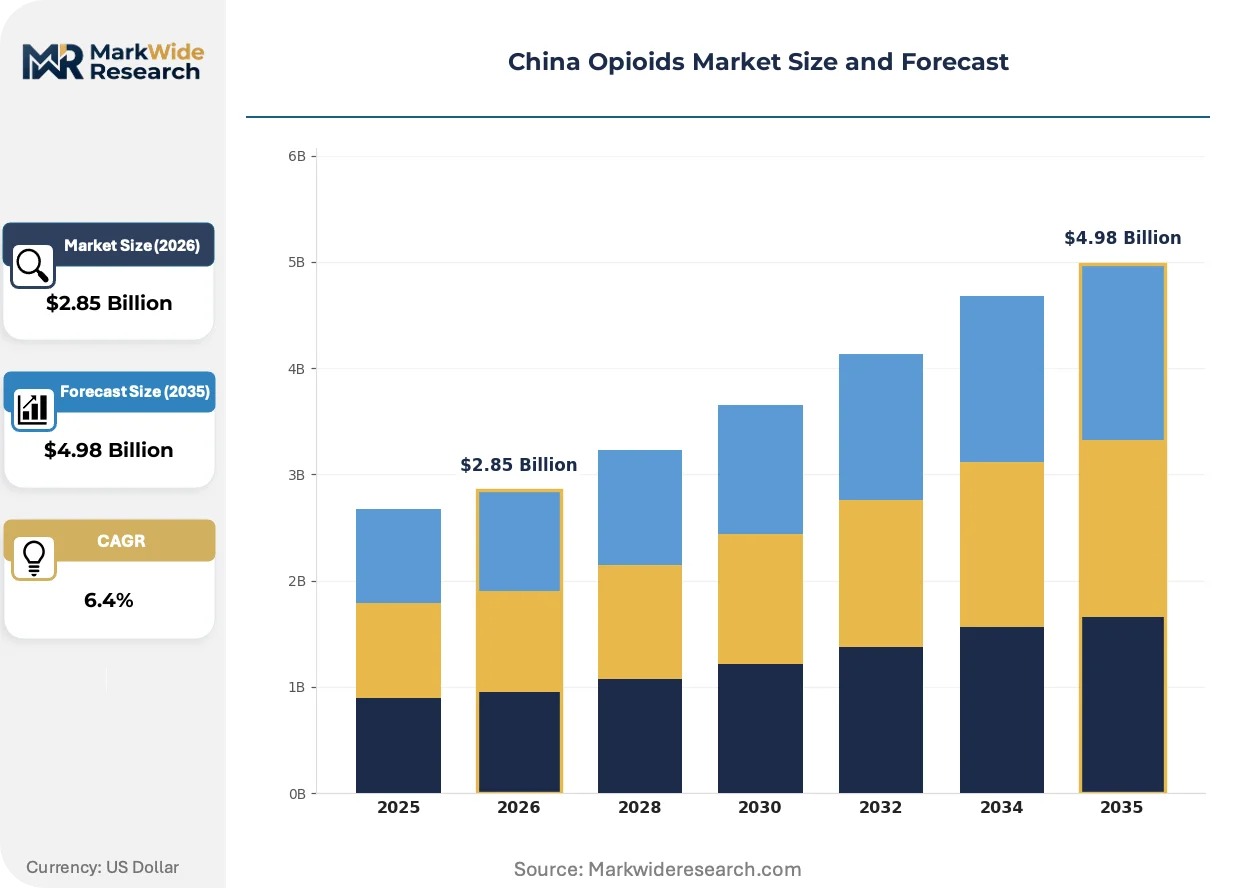
| Market Size in 2026 | $2.85 Billion |
| Market Size in 2035 | $4.98 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Morphine, Codeine, Fentanyl, Oxycodone Therapy Area: Pain Management, Cancer Care, Anesthesia, Palliative Care End User: Hospitals, Clinics, Home Care, Palliative Institutions Delivery Mode: Injectable, Oral, Transdermal, Inhalation |
| Companies Covered | China Resources Pharmaceutical Group, Sinopharm Group, Shanghai Pharmaceuticals, Beijing Tiantan Biological Products, Guangzhou Baiyunshan Pharmaceutical, Henan Yuxing Pharmaceutical, Shandong Xinhua Pharmaceutical, Yangtze River Pharmaceutical Group, Zhuhai United Laboratories, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Opioids Market Trends and Innovations
Formulation chemistry advances and regulatory digitization are restructuring how opioids move from synthesis to patient administration in China's controlled substance environment.
Transdermal fentanyl patch technology is absorbing volume from injectable morphine in chronic cancer pain protocols. Tier-two hospital oncology departments are adopting patch-based regimens at accelerating rates. This shift is absorbing nursing labor previously dedicated to intravenous administration while compressing perioperative morphine procurement.
NMPA's 2019 Drug Administration Law enforcement protocols are tightening real-time narcotic inventory tracking. Licensed hospital pharmacies must now report dispensing events through centralized digital platforms. Oncology wards in eastern provinces are most affected, with facilities investing in barcode-enabled dispensing cabinets to maintain compliance velocity.
Patient advocacy networks are pressuring municipal health commissions to expand Narcotic Drug Special Card eligibility. Terminal cancer patients in home-care settings are accessing transdermal formulations through revised prescription protocols. This behavioral shift concentrates in Zhejiang province, where palliative care reimbursement policies have advanced fastest.
China Opioids Market Segmentation
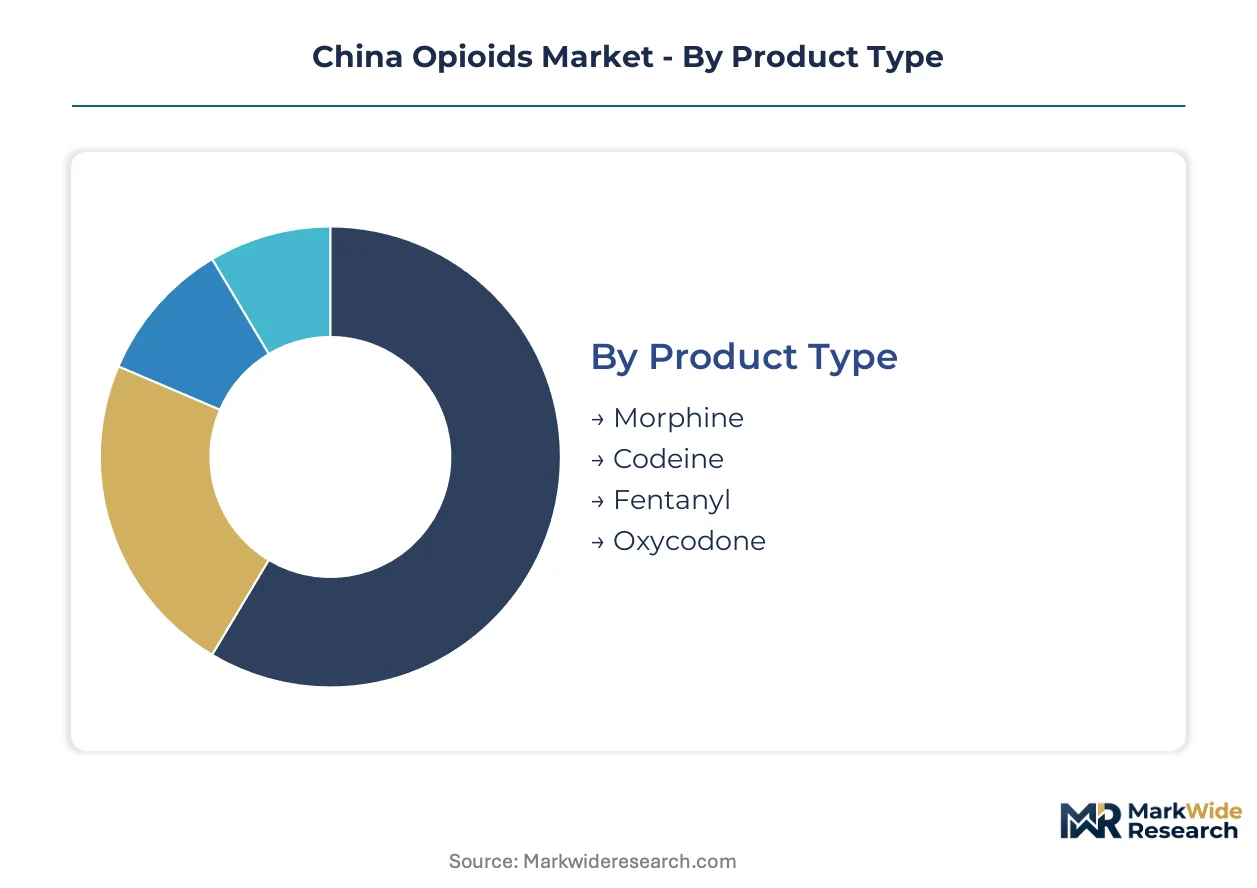
China's opioid market segments reflect the tension between acute hospital protocols and emerging chronic care channels. Each dimension carries distinct regulatory weight and procurement economics that shape manufacturer strategy.
Product Type:
Replacement cycles vary sharply across this category, with synthetic analogs displacing older alkaloid standards in institutional formularies.
- Fentanyl:Synthetic phenylpiperidine with 50-100x morphine potency enables lower-volume dosing in transdermal applications. Jiangsu province oncology centers are absorbing elevated patch volumes under revised NMPA chronic pain protocols.
- Morphine:Natural opium alkaloid remains the reference standard for severe pain under Chinese Pharmacopoeia injectable specifications. Tier-three municipal hospitals exhaust procurement quotas fastest on this segment during peak admission periods.
- Oxycodone:Semi-synthetic thebaine derivative with modified-release oral profiles. Zhejiang palliative institutions are transitioning from immediate-release morphine to extended oxycodone tablets.
- Codeine:Milder opiate alkaloid concentrated in cough suppression and moderate pain combination products. Regulatory scheduling constrains volume expansion relative to pure agonists.
Fentanyl sits at the top of the volume ranking, with oxycodone climbing the fastest.
Therapy Area:
Cost tier stratification separates acute surgical applications from reimbursed chronic care pathways.
- Pain Management:Broad acute and chronic nociceptive intervention spanning post-surgical, trauma, and non-malignant indications. Hospital pharmacies dominate procurement through centralized tender mechanisms.
- Cancer Care:Oncological pain protocols in Jiangsu and Zhejiang drive concentrated fentanyl patch demand. NMPA's narcotic traceability mandates hit this segment hardest due to high-value inventory turnover.
- Anesthesia:Perioperative sedation and analgesia requiring rapid-onset, short-acting synthetic profiles. Injectable fentanyl and remifentanil analogs concentrate in tier-one surgical centers.
- Palliative Care:Terminal symptom control expanding through Narcotic Drug Special Card home-care channels. Zhejiang province leads reimbursement policy advancement for this segment.
Pain Management commands the largest procurement base, while Palliative Care is gaining share fastest.
End User:
Customer type determines regulatory burden intensity and prescription authority scope.
- Hospitals:Licensed pharmacy departments with full narcotic dispensing authority under NMPA 2019 Drug Administration Law. Eastern province tier-two facilities are expanding oncology ward capacity fastest.
- Clinics:Restricted outpatient settings with limited opioid prescribing licenses. Municipal health commissions constrain quota allocations below hospital thresholds.
- Home Care:Emerging channel enabled by Ministry of Public Security Special Card patient registration. Terminal cancer patients in Zhejiang access transdermal formulations through revised protocols.
- Palliative Institutions:Dedicated hospice facilities with specialized pain management staffing. Infrastructure expansion in Jiangsu outpaces national construction rates.
Hospitals anchor procurement volume, with Home Care expanding most quickly.
Delivery Mode:
Supply concentration favors established pharmaceutical manufacturers with formulation technology depth.
- Injectable:Sterile solutions for perioperative and acute breakthrough pain under strict cold-chain requirements. Retains priority in anesthesia protocols despite nursing labor intensity.
- Transdermal:Matrix-adhesive patches enabling 72-hour fentanyl delivery with steady plasma levels. Requires SAMR-certified temperature-controlled logistics infrastructure.
- Oral:Immediate and modified-release tablets and capsules for chronic outpatient regimens. Extended-release oxycodone profiles reduce dosing frequency in palliative settings.
- Inhalation:Nebulized and intranasal formulations for rapid onset in breakthrough cancer pain. Limited formulary penetration relative to established routes.
Injectable formulations retain volume leadership, with Transdermal showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's opioid market traces its institutional roots to the 1950s establishment of state-controlled narcotics manufacturing under the Ministry of Health, with modern distribution networks consolidating after the 2019 NMPA regulatory overhaul centralized hospital pharmacy licensing.
Jiangsu Province
Oncology center construction in Nanjing and Suzhou is expanding institutional pain management capacity faster than national averages. NMPA's narcotic traceability mandates require real-time inventory reporting from hospital pharmacies handling elevated morphine volumes. The Yangtze River Delta cluster concentrates synthetic opioid R&D investment, with modified-release formulation patents filing at accelerated rates.
Zhejiang Province
Palliative care reimbursement policies in Hangzhou and Ningbo are advancing fastest among provincial health commissions, enabling Narcotic Drug Special Card access for terminal cancer patients. The Ministry of Public Security's patient registration framework is formalizing home-care channel expansion for transdermal fentanyl protocols. Wenzhou-based distributors are investing in SAMR-certified cold storage infrastructure for patch-based delivery systems.
Beijing-Tianjin-Hebei
Tier-one surgical centers in Beijing anchor perioperative anesthesia demand for rapid-onset synthetic profiles. National Health Commission opioid allocation ceilings constrain procurement flexibility at municipal facilities during peak admission periods. Tianjin's pharmaceutical logistics hub coordinates northern regional distribution through state-affiliated cold-chain networks.
Guangdong Province
Pearl River Delta hospital networks are retrofitting pharmacy management systems to interface with NMPA's centralized narcotic monitoring database. Guangzhou's oncology wards report accelerated adoption of extended-release oxycodone tablets transitioning from immediate-release morphine. Shenzhen-based manufacturers face MEE environmental discharge compliance costs elevating capital requirements for API synthesis facilities.
Sichuan-Chongqing
Western China palliative infrastructure expansion in Chengdu is absorbing nursing labor previously dedicated to intravenous administration. Provincial regulatory affairs departments report specialized pharmacovigilance talent scarcity delaying batch release timelines for domestic manufacturers. Chongqing's centralized storage facilities anchor regional supply security through state-backed logistics networks.
China Opioids Market Competitive Landscape
Premium-margin players sit above commodity-margin players across formulation technology and distribution licensing dimensions. State-backed pharmaceutical groups with institutional procurement relationships capture concentrated volume through hospital network dominance. Three archetypes define competitive positioning: vertically integrated API-to-formulation manufacturers, regional distributors with cold-chain certification, and synthetic chemistry specialists with polymer-matrix patent portfolios. Capacity expansion and abuse-deterrent formulation licensing represent the dominant competitive moves reshaping tier positioning.
Within the state-affiliated tier, Sinopharm Group and Shanghai Pharmaceuticals exemplify national-scale distribution archetypes, while Yangtze River Pharmaceutical Group occupies a position among synthetic opioid specialists. China Resources Pharmaceutical Group anchors diversified healthcare portfolio positioning across eastern provinces. These entities represent the licensing-concentrated structure where NMPA narcotic distribution permits create defensive moats against unlicensed channel competition.
| Leading Market Players |
|---|
| China Resources Pharmaceutical Group |
| Sinopharm Group |
| Shanghai Pharmaceuticals |
| Beijing Tiantan Biological Products |
| Guangzhou Baiyunshan Pharmaceutical |
| Henan Yuxing Pharmaceutical |
| Shandong Xinhua Pharmaceutical |
| Yangtze River Pharmaceutical Group |
| Zhuhai United Laboratories |
| Others |
Pricing and Supply Chain Analysis
Precursor chemical import costs from concentrated overseas suppliers flow through synthetic opioid manufacturing tiers, compressing margins at domestic API facilities while amplifying price premiums for abuse-deterrent formulations downstream. NMPA licensing scarcity and MEE environmental compliance burdens stratify procurement economics across hospital pharmacy networks.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates SAMR-certified cold-chain distributors from regional logistics operators and informal channel remnants. Price differentiation hinges on NMPA narcotic distribution licensing tier and transdermal patch temperature-control certification. Cost compression in immediate-release morphine generics intensifies as centralized procurement negotiations deepen. Tier-three municipal hospitals exhibit highest price sensitivity; oncology centers in Jiangsu and Zhejiang absorb premium pricing for modified-release profiles.
Supply Chain Analysis
Reverse-logistics constraints on narcotic waste disposal and expired inventory return flow through MEE hazardous substance protocols, adding compliance layers to distribution planning. API synthesis draws from concentrated precursor suppliers in India and specialized intermediate producers in Europe, with domestic formulation filling concentrated in eastern China. Single-source vulnerability in fentanyl precursor availability exposes just-in-time production schedules to geopolitical friction. Distribution runs through state-affiliated hospital pharmacy networks under NMPA 2019 Drug Administration Law traceability mandates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's opioid market functions as a regulatory compounder where NMPA's 2019 Drug Administration Law enforcement deepens licensing moats and concentrates procurement through institutional channels.
For Market Incumbents: Lock in hospital pharmacy relationships through SAMR-certified cold-chain infrastructure investments in Jiangsu and Zhejiang provinces. Deepen backward integration into synthetic opioid API production to offset precursor import dependency risks. Capture premium positioning via abuse-deterrent formulation patents ahead of evolving NMPA technical guidelines. For New Entrants and Emerging Players: Polymer-matrix transdermal delivery technology offers a technology-first wedge into the chronic cancer pain segment where patch-based regimens displace injectable morphine. Target palliative home-care channels enabled by Ministry of Public Security Special Card expansion in Zhejiang province. Lead with green synthesis process patents aligned with national dual carbon targets to accelerate NMPA licensing review. For Investors and Strategic Acquirers: Consolidation pressure builds where MEE environmental discharge standards exceed smaller synthesis facility capital capacity. Five-to-ten-year viability favors vertically integrated API-to-formulation manufacturers with state-backed distribution relationships. Monitor NMPA abuse-deterrent formulation guideline publication as inflection signal for premium pricing capture.| Strategic Initiative | Industry Significance |
|---|---|
| Abuse-Deterrent Formulation Development | NMPA evolving technical guidelines reward first-mover polymer-matrix patent holders with premium positioning. |
| Cold-Chain Distribution Certification | SAMR-certified temperature-controlled infrastructure captures transdermal fentanyl patch expansion in eastern provinces. |
| Green Synthesis Process Patenting | Carbon-negative API production aligns with national dual carbon targets and accelerates licensing review timelines. |
| Hospital Pharmacy System Integration | Barcode-enabled dispensing cabinet deployment satisfies NMPA real-time narcotic traceability mandate compliance. |
| Precursor Supply Backward Integration | In-house production of specialized opioid synthesis intermediates reduces geopolitical disruption exposure. |
Research Methodology
Bottom-up hospital procurement modeling reconciled against top-down API manufacturing tracking forms the analytical core of this study. Primary interviews with regulatory affairs directors, hospital pharmacy managers, oncology formulary leads, and palliative care specialists informed demand-side assumptions. Secondary validation drew from NMPA narcotic licensing databases, Ministry of Public Security traceability disclosures, Chinese Pharmacopoeia standards documentation, and MEE environmental compliance filings. Cross-referencing bottom-up patient-volume estimates with top-down production capacity assessments refined segmentation accuracy.
Input-output matrices mapped synthetic opioid precursor flows through formulation tiers to end-use delivery modes across the projection horizon. Segmentation dimensions included product type, therapy area, end-user channel, and delivery mode, with regional regulatory cluster differentiation. CAGRs were derived from trend-line analysis of historical procurement volumes adjusted for policy intervention effects. Forecast inputs incorporated NMPA licensing trajectory assumptions and palliative infrastructure construction pipelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to NMPA regulatory tightening pace and precursor import geopolitics. Practitioners should monitor Ministry of Public Security Special Card enrollment expansion and MEE discharge standard enforcement intensity for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Opium Tincture Market
Pharmaceuticals
Belgium Pharmaceutical Market
Pharmaceuticals
Alpha-Glucosidase Inhibitors Market
Pharmaceuticals
Penicillin Market
Pharmaceuticals
Italy Diabetes Drugs Market
Pharmaceuticals
Europe Oral Anti-Diabetic Drug Market
Pharmaceuticals
Global Human Rabies Vaccine Market
Pharmaceuticals
Stomach Cancer Drugs Market
Pharmaceuticals
Malaysia Oral Anti-Diabetic Drug Market
Pharmaceuticals
Advanced Parenteral Drug Market
Pharmaceuticals
Pharmaceuticals Lipids Market
Pharmaceuticals
Nesiritide Market
Pharmaceuticals
Global Ebola Virus Vaccine Market
Pharmaceuticals
Urinary Retention Drugs Market
Pharmaceuticals
Saline Laxative Market
Pharmaceuticals
Tunisia Pharmaceutical Market