
 Contrast Injection Lines Market | 2026-2036
Contrast Injection Lines Market Size, Share, and Industry Trends Forecast 2026-2036
Contrast Injection Lines Market Outlook
Modular bundling of disposable lines with high-pressure rated connectors is repositioning procurement patterns across hospital systems. Becton Dickinson & Company leverages its integrated vascular access portfolio to anchor multi-year supply contracts with large imaging networks. Merit Medical Systems Inc. specializes in procedure-specific kits that reduce setup time in busy catheterization labs. Shenzhen Axwei Medical Technology Co. Ltd. competes on manufacturing scale, shipping standardized configurations to cost-sensitive procurement channels across Asia.
Contrast injection lines are sterile, pressure-rated tubing assemblies engineered to deliver iodinated or gadolinium-based contrast media from automated injectors to patient vascular access sites, typically rated for pressures exceeding 300 psi to withstand power injector flow rates. These devices incorporate materials such as polyurethane and polyvinyl chloride selected for kink resistance, chemical compatibility, and compliance with biocompatibility standards including ISO 10993. Disposable lines dominate unit volume due to infection control protocols, while high-pressure lines command premium positioning as cardiac imaging and interventional radiology procedures intensify throughput requirements. Material selection segments reveal polyurethane gaining share in MRI suites where flexibility under magnetic fields matters, whereas stainless steel reinforced configurations serve CT scanning environments demanding maximum burst pressure tolerance.
The FDA enforces 510(k) clearance pathways and quality system regulation under 21 CFR Part 820, compelling manufacturers to maintain validated sterilization processes and design controls. ISO 13485 certification serves as the baseline quality management framework, while the EU Medical Device Regulation imposes stricter clinical evidence requirements for class IIa and IIb devices entering European markets. Stakeholders must monitor evolving pressure-rating harmonization between American and European standards bodies, as divergence in test protocols would fragment product development roadmaps and complicate global registration strategies.
Market Dynamics
Power injector throughput requirements in cardiac catheterization labs are compressing product lifecycles and forcing material upgrades across the supply base. Manufacturers must now validate burst pressure ratings exceeding 1200 psi while maintaining compliance with evolving sterilization protocols from multiple regulatory jurisdictions.
Growth Catalysts
- EU Medical Device Regulation (MDR):Stricter clinical evidence requirements for class IIa and IIb devices are accelerating portfolio consolidation among established suppliers with validated quality systems.
- Cardiac imaging volumes:Hospital systems in the United States and Germany are expanding contrast-enhanced CT and MRI protocols, pulling demand for high-pressure rated disposable configurations.
- Polyurethane material adoption:MRI suite operators favor kink-resistant tubing that maintains flexibility under magnetic fields, creating specification premiums for advanced polymer formulations.
Market Restraints
- Medical-grade polymer supply concentration:Specialized polyurethane and PVC resin production clusters in East Asia create vulnerability to logistics disruptions and input cost volatility.
- 510(k) clearance timelines:FDA quality system regulation under 21 CFR Part 820 extends product development cycles, compressing effective revenue windows before obsolescence.
- Reusable line alternatives:Some cost-constrained outpatient imaging centers in developing markets continue deploying sterilizable metal-reinforced configurations, limiting addressable volume for disposables.
Strategic Opportunities
- China NMPA pathway harmonization:Convergence between Chinese medical device registration requirements and ISO 13485 frameworks is lowering entry barriers for Western manufacturers with existing quality certifications.
- Interventional radiology expansion:Hybrid operating rooms combining surgical and imaging capabilities are creating demand for procedure-specific kits with integrated pressure monitoring.
- Automated injector connectivity:RFID-enabled line identification systems that interface with power injector pumps are opening premium positioning for sensor-embedded disposable configurations.
Industry Challenges
- ISO 10993 biocompatibility testing capacity:Contract laboratory bottlenecks for cytotoxicity and sensitization studies are extending product launch timelines by six to twelve months.
- Sterilization validation complexity:Transition from ethylene oxide to alternative methods such as gamma irradiation requires extensive material compatibility testing and process requalification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Contrast Injection Lines Market |
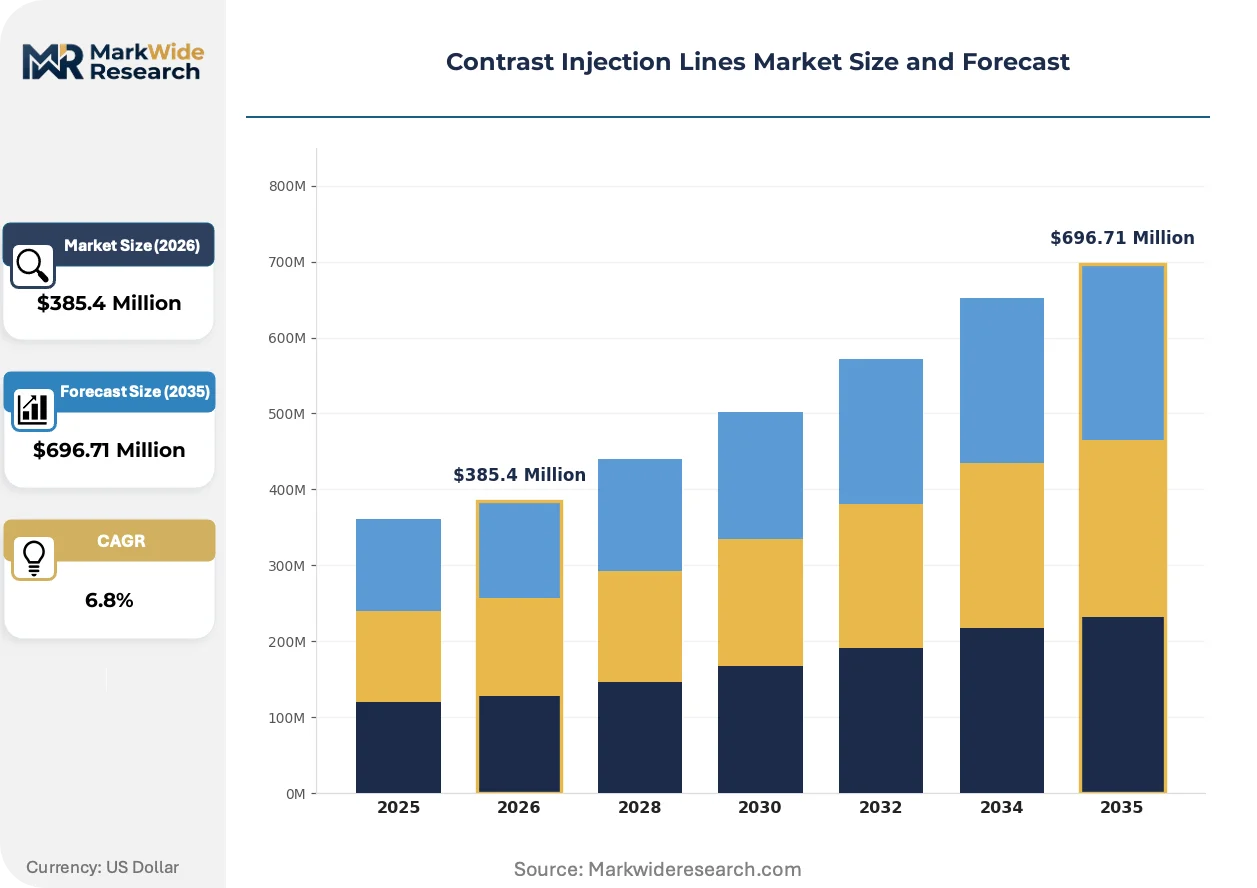
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $696.71 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disposable Lines, Reusable Lines, High-Pressure Lines, Low-Pressure Lines End User: Hospitals, Imaging Centers, Diagnostic Labs, Outpatient Facilities Material: Polyvinyl Chloride, Silicone, Polyurethane, Stainless Steel Application: Cardiac Imaging, MRI Procedures, CT Scanning, Interventional Radiology |
| Companies Covered | Argon Medical Devices Inc., Shenzhen Axwei Medical Technology Co. Ltd., AngioDynamics, George Philips Medical Engineering PVT. Ltd., B. Braun Melsungen AG, Merit Medical Systems Inc., Becton Dickinson & Company, Navilyst Medical Inc., Shenzhen Boon Medical Supply Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Contrast Injection Lines Market Strategic Shifts
Digital integration and material science advances are redefining performance benchmarks across the contrast delivery ecosystem. Suppliers now compete on connectivity, traceability, and pressure tolerance rather than commodity tubing specifications.
Co-extruded multi-layer tubing with embedded stainless steel braid reinforcement is electrifying the high-pressure segment. Cardiac catheterization labs in tertiary hospital networks are specifying these configurations for power injector protocols above 5 mL per second. The technology is compressing market share for single-layer PVC alternatives that fail at burst pressures below 900 psi.
REACH chemical substance restrictions are forcing reformulation of plasticizers and stabilizers used in medical-grade PVC. Compounders serving European device manufacturers must now certify compliance with Substances of Very High Concern (SVHC) candidate list updates. The regulation is accelerating polyurethane substitution in contrast line applications where phthalate-free specifications are mandated.
Consolidated procurement through integrated delivery networks is displacing decentralized purchasing by individual radiology departments. Large United States health systems now negotiate multi-year supply agreements covering contrast media, injection systems, and disposable lines under single vendor relationships. This concentration is most visible in states with dominant hospital networks such as Texas and California, where three suppliers capture the majority of imaging consumables spending.
Contrast Injection Lines Market Segmentation
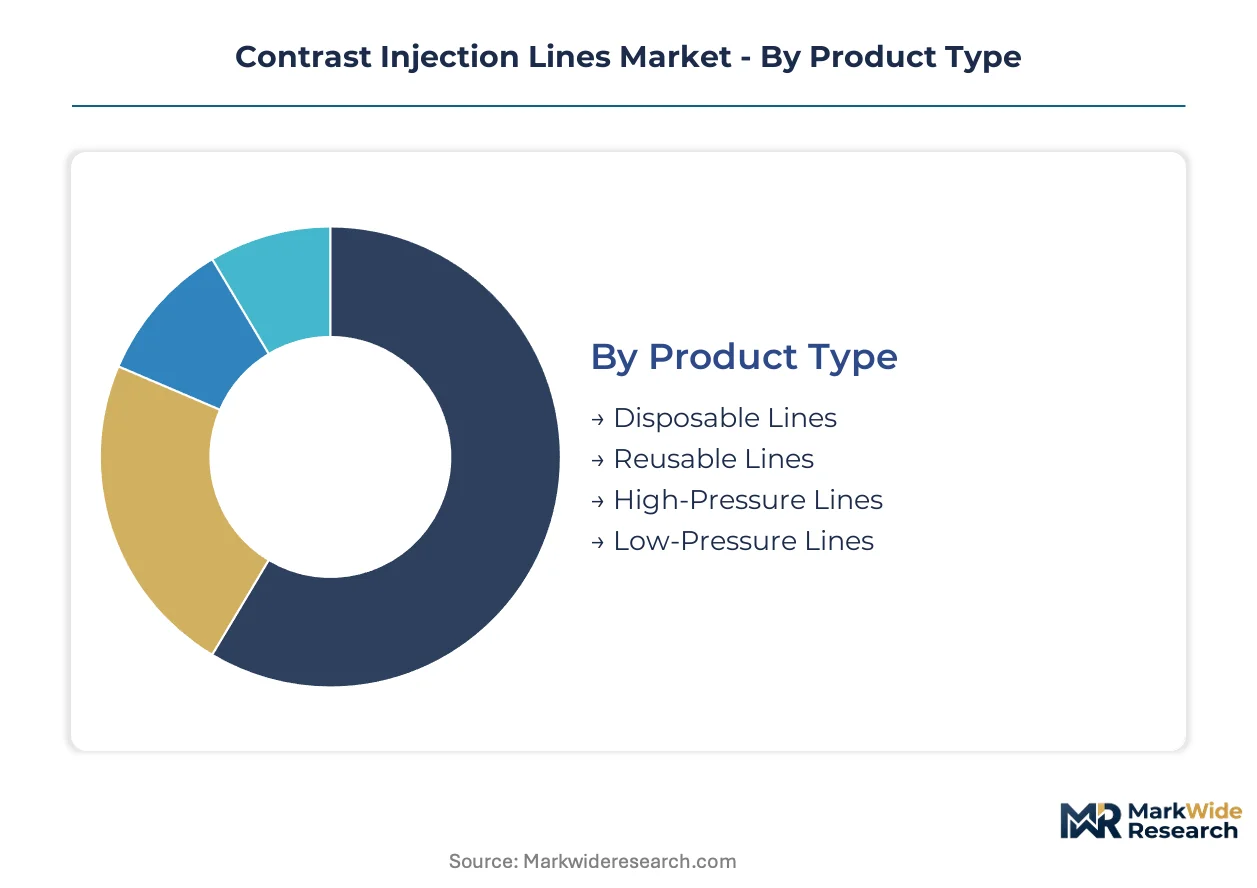
Segmentation in the contrast injection lines market reveals how procurement decisions split between infection control mandates, pressure tolerance requirements, and magnetic compatibility needs. Hospital systems configure their purchasing portfolios differently based on procedure mix, regulatory environment, and capital replacement cycles.
Product Type:
Standardization dominates high-volume disposable configurations, while customization concentrates in specialized pressure-rated assemblies for cardiac catheterization labs.
- Disposable Lines:Single-use sterile tubing assemblies eliminate cross-contamination risks in busy imaging suites. Demand clusters in United States hospital systems where Joint Commission infection protocols and FDA 510(k) clearance requirements reinforce single-patient use. These configurations absorb the majority of unit volume as cardiac imaging throughput rises.
- High-Pressure Lines:Co-extruded multi-layer constructions with stainless steel braid reinforcement withstand power injector protocols exceeding 1200 psi. Cardiac catheterization labs in Germany and China specify these for CT coronary angiography at flow rates above 5 mL per second, where burst tolerance failures carry patient safety liability.
- Reusable Lines:Metal-reinforced sterilizable configurations persist in cost-constrained outpatient settings across India and Southeast Asia where per-procedure economics favor capital equipment amortization over disposable consumption.
- Low-Pressure Lines:Single-layer PVC constructions serve manual injection scenarios and pediatric applications where power injector compatibility is unnecessary.
Most installed capacity flows through Disposable Lines. Expansion is steepest in High-Pressure Lines.
End User:
Procurement authority concentrates in integrated health networks, fragmenting across independent imaging centers and specialized diagnostic facilities.
- Hospitals:Tertiary medical centers with hybrid operating rooms drive specification for procedure-specific kits with integrated pressure monitoring. United States systems in Texas and California negotiate multi-year supply agreements covering contrast media, injectors, and disposable lines under consolidated vendor relationships.
- Imaging Centers:Freestanding facilities prioritize throughput optimization and setup time reduction. These operators favor modular bundling of disposable lines with high-pressure rated connectors to minimize catheterization lab turnaround.
- Diagnostic Labs:Smaller-scale operators concentrate on routine CT and MRI protocols without interventional capabilities, selecting standardized configurations over specialized cardiac assemblies.
- Outpatient Facilities:Cost-sensitive settings in developing markets deploy reusable metal-reinforced lines where sterilization infrastructure supports multi-patient use cycles.
Revenue concentrates in Hospitals. Imaging Centers are climbing the fastest as freestanding networks expand across suburban United States markets.
Material:
Polymer selection tracks application environment, with magnetic field compatibility and chemical resistance driving specification divergence.
- Polyurethane:Kink-resistant formulations maintain flexibility under magnetic fields, making these specifications mandatory in MRI suites. European operators favor phthalate-free polyurethane as REACH Substances of Very High Concern restrictions accelerate PVC substitution.
- Polyvinyl Chloride:Cost-optimized single-layer tubing serves low-pressure manual injection applications where burst tolerance requirements remain modest. Reformulation pressures from EU chemical regulations are compressing addressable volume.
- Silicone:Biocompatible elastomer constructions serve specialized pediatric and neonatal applications where tissue interaction sensitivity exceeds standard requirements.
- Stainless Steel:Reinforcement braids embedded in co-extruded walls provide burst pressure tolerance for power injector protocols in CT coronary angiography.
Polyvinyl Chloride retains the largest installed base. Polyurethane is gaining share fastest as MRI procedure volumes expand and regulatory pressure on plasticizers intensifies.
Application:
Procedure-specific requirements fragment demand across imaging modalities with divergent pressure, timing, and magnetic field constraints.
- Cardiac Imaging:Coronary CT angiography and cardiac catheterization procedures demand the highest pressure ratings and fastest flow rates. United States and German hospital systems specify co-extruded stainless steel reinforced configurations for these applications.
- CT Scanning:Abdominal and neurological contrast protocols require burst tolerance above 300 psi but below cardiac thresholds. Standard high-pressure disposable lines dominate this mid-tier specification band.
- MRI Procedures:Magnetic field compatibility mandates non-ferrous polyurethane constructions without metallic reinforcement. Flexibility under sustained magnetic exposure determines product selection.
- Interventional Radiology:Hybrid operating room environments combining surgical and imaging capabilities create demand for integrated pressure monitoring and procedure-specific kit configurations.
CT Scanning absorbs the largest procedure volume. Interventional Radiology represents the steepest expansion trajectory as hybrid OR installations multiply across tertiary hospital networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Power injector technology for contrast delivery originated in German and American catheterization labs during the 1980s, establishing quality benchmarks that persist across regulatory jurisdictions. Hospital procurement networks now span multiple continents, with imaging protocol standardization driving cross-border equipment specifications.
United States
Cardiac catheterization labs in Texas and California negotiate multi-year supply agreements covering contrast media, injectors, and disposable lines under consolidated vendor relationships. FDA 510(k) clearance pathways under 21 CFR Part 820 enforce validated sterilization processes and design controls. The Joint Commission infection protocols reinforce single-patient use configurations across tertiary medical centers.
Germany
CT coronary angiography volumes in Bavaria and North Rhine-Westphalia pull demand for co-extruded stainless steel reinforced configurations rated above 1200 psi. EU Medical Device Regulation imposes stricter clinical evidence requirements for class IIa and IIb devices entering European markets. REACH Substances of Very High Concern restrictions accelerate phthalate-free polyurethane substitution in medical tubing applications.
China
Cost-sensitive procurement channels across Asia absorb standardized configurations from manufacturing-scale suppliers in Shenzhen and the Pearl River Delta. NMPA pathway harmonization with ISO 13485 frameworks lowers entry barriers for Western manufacturers with existing quality certifications. Hybrid operating room installations in Beijing and Shanghai create demand for procedure-specific kits with integrated pressure monitoring.
Japan
MRI suite operators in Tokyo and Osaka favor kink-resistant polyurethane formulations that maintain flexibility under magnetic fields. PMDA regulatory review processes align with international standards while maintaining distinct documentation requirements. METI industrial policy supports domestic medical device manufacturing clusters in the Kanto region.
India
Outpatient imaging centers in Maharashtra and Karnataka deploy reusable metal-reinforced lines where sterilization infrastructure supports multi-patient use cycles. CDSCO medical device regulations are converging toward global harmonization frameworks. Cost-constrained procurement in diagnostic labs concentrates on routine CT protocols without interventional capabilities.
Contrast Injection Lines Market Competitive Environment
Premium-margin players sit above commodity-margin players across pressure-rating and connectivity specifications. The vendor base stratifies into three tiers: integrated vascular access portfolios anchoring multi-year hospital contracts, procedure-specific kit specialists reducing catheterization lab setup time, and manufacturing-scale suppliers shipping standardized configurations to cost-sensitive channels. Consolidated procurement through integrated delivery networks favors suppliers with validated quality systems spanning multiple regulatory jurisdictions. Two dominant competitive moves include portfolio diversification into sensor-embedded disposable configurations and geographic expansion through NMPA registration in China.
Within the integrated portfolio tier, Becton Dickinson & Company and Merit Medical Systems Inc. represent established suppliers with multi-year supply contract capabilities. Shenzhen Axwei Medical Technology Co. Ltd. occupies a position among manufacturing-scale specialists serving standardized procurement channels. These three companies exemplify the archetype segmentation between premium-tier contract anchoring and cost-optimized volume supply.
| Leading Market Players |
|---|
| Argon Medical Devices Inc. |
| Shenzhen Axwei Medical Technology Co. Ltd. |
| AngioDynamics |
| George Philips Medical Engineering PVT. Ltd. |
| B. Braun Melsungen AG |
| Merit Medical Systems Inc. |
| Becton Dickinson & Company |
| Navilyst Medical Inc. |
| Shenzhen Boon Medical Supply Co. Ltd. |
| Others |
Value Chain & Pricing Dynamics
Integrated delivery networks in Texas and California anchor procurement concentration for contrast injection lines, compressing vendor margins through multi-year supply agreements that bundle contrast media, injectors, and disposable lines under single-source contracts. This buyer consolidation shifts pricing power toward hospital systems with sufficient procedure volume to justify exclusive relationships, while tiered pricing structures separate premium co-extruded stainless steel reinforced configurations from standardized PVC alternatives.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs transaction dynamics, with differentiation driven by burst pressure certification grade and geographic delivery cost to remote imaging centers. Pricing pressure stems from manufacturing-scale suppliers in Shenzhen competing on standardized configurations for cost-sensitive Asian procurement channels. Outpatient facilities in developing markets exhibit highest price sensitivity, whereas tertiary cardiac catheterization labs in Germany and the United States prioritize pressure tolerance over per-unit cost.
Supply Chain Analysis
ISO 13485 certification and FDA 510(k) clearance pathways gate supplier participation, filtering raw material sourcing through validated polymer compounders in Germany, Japan, and the United States. Medical-grade polyurethane and PVC resin production draws from specialized petrochemical clusters in East Asia, creating single-source vulnerability to logistics disruptions at major port hubs. Distribution runs through integrated delivery networks and group purchasing organizations that consolidate hospital procurement across multi-state regions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
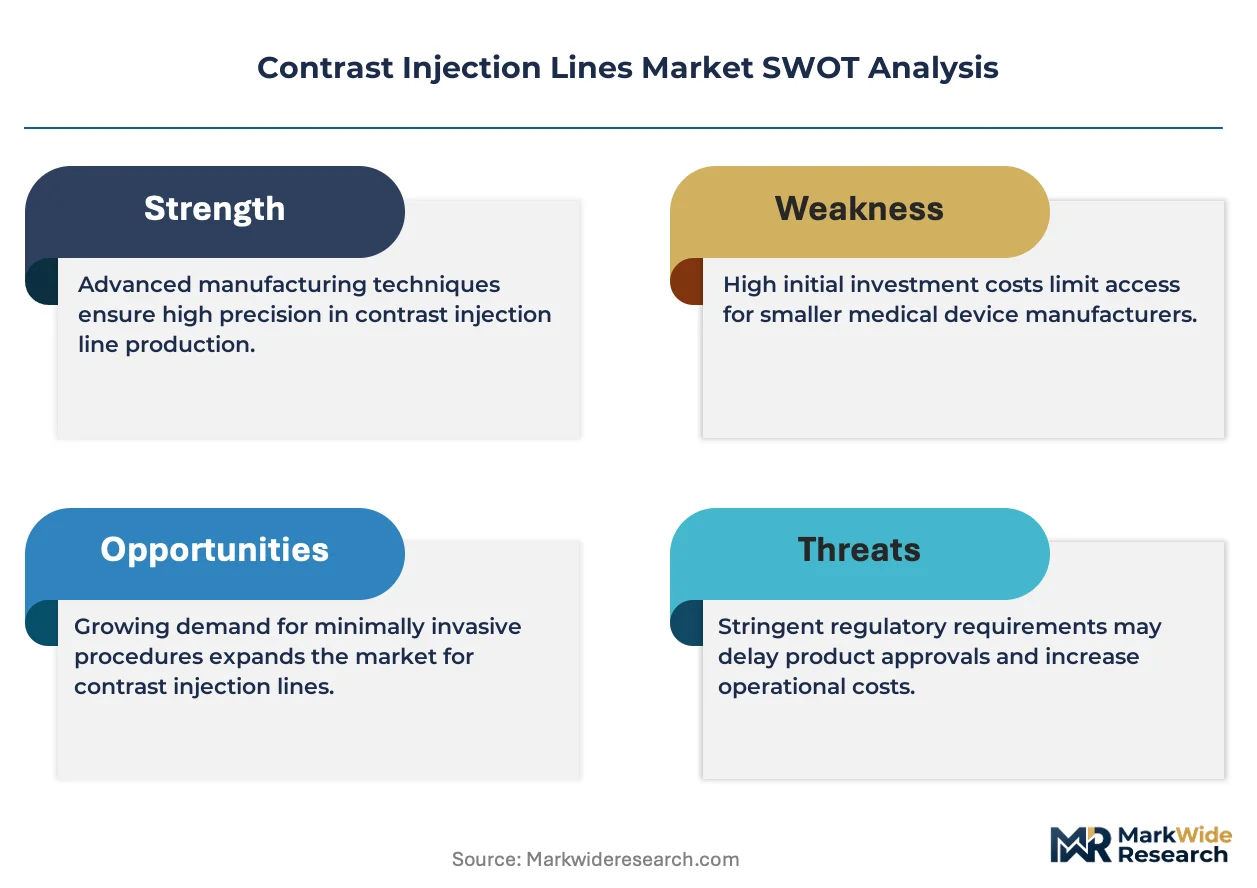
The contrast injection lines market represents a late-cycle quality story as cardiac imaging volumes pull specification upgrades toward co-extruded stainless steel reinforced configurations rated above 1200 psi. Hospital systems now prioritize burst pressure tolerance and magnetic compatibility over commodity tubing economics.
For Market Incumbents: Extend validated quality system coverage across multiple regulatory jurisdictions to defend multi-year supply contracts against emerging manufacturing-scale competitors from Shenzhen. Anchor backward integration into medical-grade polymer compounding to secure input cost stability amid REACH plasticizer restrictions and East Asian resin supply volatility. Prioritize RFID-enabled line identification development to maintain premium positioning as automated injector connectivity becomes standard specification. For New Entrants and Emerging Players: Independent imaging centers in suburban United States markets represent the most penetrable buyer archetype, as these operators prioritize throughput optimization and modular bundling over consolidated vendor relationships. Target cost-optimized polyurethane configurations for MRI suite operators seeking phthalate-free alternatives under EU chemical regulations. Pursue direct distribution partnerships with freestanding diagnostic networks bypassing incumbent GPO channel control. For Investors and Strategic Acquirers: Integrated vascular access portfolio companies are the most active acquirer in this space, seeking procedure-specific kit capabilities to complement existing catheter and guidewire franchises. Long-term viability hinges on regulatory certification breadth spanning FDA, EU MDR, and NMPA pathways. Monitor NMPA registration acceleration for Western manufacturers as signal of competitive inflection toward China market penetration.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Accelerates market entry for co-extruded stainless steel reinforced configurations in United States cardiac catheterization labs. |
| CE Marking Pathway | Unlocks EU MDR compliance for phthalate-free polyurethane lines serving REACH-restricted European MRI suites. |
| Hospital System Partnership | Secures multi-year supply agreements with integrated delivery networks in Texas and California consolidating imaging consumables procurement. |
| Software Companion Development | Enables RFID-enabled line identification systems interfacing with power injector pumps for premium sensor-embedded configurations. |
| Reimbursement Strategy | Aligns procedure-specific kit positioning with cardiac imaging reimbursement codes in United States and German hospital systems. |
Study Parameters
Multiple input streams — structured interviews with catheterization lab directors, procurement managers at integrated delivery networks, biomedical engineers, and GPO contracts specialists — were reconciled against FDA 510(k) filings, EU MDR technical documentation, hospital procurement databases, and customs trade records. Bottom-up unit demand estimates from procedure volume data and top-down market sizing from manufacturer revenue disclosures were triangulated to constrain forecast variance.
Data-stream reconciliation anchored the analytical framework across the projection horizon, with segmentation modeled by product type, material formulation, application modality, end-user facility class, and regional regulatory cluster. CAGRs were derived from logistic adoption curves fitted to power injector installation data and cardiac imaging protocol expansion rates. Sterilization validation timelines and ISO 10993 biocompatibility testing capacity constraints informed launch delay assumptions.
Underlying measurement precision varies by segment; disposable high-pressure lines and polyurethane MRI configurations carry tighter precision than reusable metal-reinforced alternatives in developing markets. Forecasts reflect assumptions regarding NMPA harmonization progress, REACH plasticizer restriction enforcement, and cardiac imaging reimbursement stability. A model refresh is warranted upon material change in FDA 510(k) clearance timelines or East Asian medical-grade polymer supply disruptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Radiofrequency Skin Rejuvenation Devices Market
Medical Devices
Latin America Breast Biopsy Needle Market
Medical Devices
Artificial Vital Organs and Medical Bionics Market
Medical Devices
Pneumology Digital Stethoscope Market
Medical Devices
Global Cardiopulmonary Bypass Accessory Equipment Market
Medical Devices
Contact Lens Lubricant Market
Medical Devices
Electrosurgical Devices Market
Medical Devices
Total Artificial Heart Market
Medical Devices
Catheter Systems Market
Medical Devices
Point-Of-Care Ultrasound (Pocus) Device Market
Medical Devices
Cervical Traction Devices for Home Use Market
Medical Devices
3D Printed Hip and Knee Implants Market
Medical Devices
Organ-On-A-Chip Systems Market
Medical Devices
United States Diabetes Devices Market
Medical Devices
Wireless Breast Pump Market
Medical Devices
Global Photobiostimulation Market