
 Antiplatelet Drugs Market | 2026-2036
Antiplatelet Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Antiplatelet Drugs Market Analysis
Single-source API reliance for clopidogrel active pharmaceutical ingredients is pivoting toward multi-source qualification across top formulators. Sanofi leverages captive manufacturing in Europe to sustain supply continuity for branded antiplatelet portfolios. AstraZeneca anchors its position through ticagrelor specialization and hospital channel dominance. Pfizer competes on geographic breadth, with oral antiplatelet distribution extending into emerging hospital networks.
Antiplatelet drugs inhibit platelet aggregation through irreversible or reversible binding of P2Y12 receptors or cyclooxygenase-1 enzymes, with formulations spanning immediate-release tablets to intravenous cangrelor infusion for catheterization lab settings. The therapeutic application dimension shows coronary artery disease commanding the largest revenue pool while stroke prevention represents the fastest-growing indication as transient ischemic attack protocols expand. Oral administration routes dominate volume, though intravenous segments capture premium pricing in acute coronary syndrome settings where rapid platelet inhibition proves critical.
FDA guidelines on dual antiplatelet therapy duration and EMA pharmacovigilance requirements for bleeding risk disclosure shape product labeling and prescriber education investments across manufacturers. The EU MDR transition demands renewed clinical evidence for Class III antiplatelet devices and combination therapies, elevating regulatory compliance costs for European market participants. Stakeholders must monitor evolving antithrombotic guideline harmonization between cardiology societies and national reimbursement authorities to anticipate formulary positioning shifts.
Market Dynamics
FDA's tightened dual antiplatelet therapy duration guidance is compressing prescribing windows and forcing manufacturers to recalibrate clinical evidence investments around shorter treatment protocols.
Growth Catalysts
- Percutaneous coronary intervention volumes:Hospital-based cardiology units are expanding catheterization lab capacity to accommodate rising PCI procedures, directly expanding the addressable patient pool for acute antiplatelet administration.
- EMA pharmacovigilance requirements:Bleeding risk disclosure mandates are elevating prescriber education standards, creating competitive differentiation for manufacturers with robust safety databases.
- Transient ischemic attack protocol expansion:Neurology departments are broadening secondary stroke prevention criteria, opening new prescriber channels beyond traditional cardiology dominance.
Market Restraints
- Active pharmaceutical ingredient concentration:Single-source reliance for clopidogrel APIs in select Asian manufacturing clusters creates supply vulnerability during geopolitical disruptions or quality enforcement actions.
- EU MDR transition costs:Class III device and combination therapy re-certification demands are elevating compliance expenditures for European market participants without proportional pricing recovery.
- Generic substitution pressure:Patent-expired P2Y12 inhibitors face commoditization in outpatient settings where pharmacy benefit managers drive therapeutic interchange toward lowest-cost equivalents.
Strategic Opportunities
- Intravenous cangrelor penetration:Catheterization lab adoption of rapid-onset IV formulations remains underdeveloped in Latin American hospital networks, offering first-mover positioning for acute coronary syndrome protocols.
- India's PLI scheme for APIs:Domestic pharmaceutical manufacturing incentives are attracting multi-source qualification investments that reduce import dependency for critical antiplatelet raw materials.
- Digital therapeutics integration:Medication adherence monitoring platforms are converging with antiplatelet regimens, enabling outcome-based contracting with integrated delivery networks in United States markets.
Industry Challenges
- Clinical trial recruitment compression:Competing cardiovascular studies are thinning eligible patient pools, extending development timelines for novel antiplatelet candidates.
- Legacy EHR integration:Hospital systems struggle to embed antiplatelet bleeding risk calculators into existing workflow architectures, delaying decision-support tool deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Antiplatelet Drugs Market |
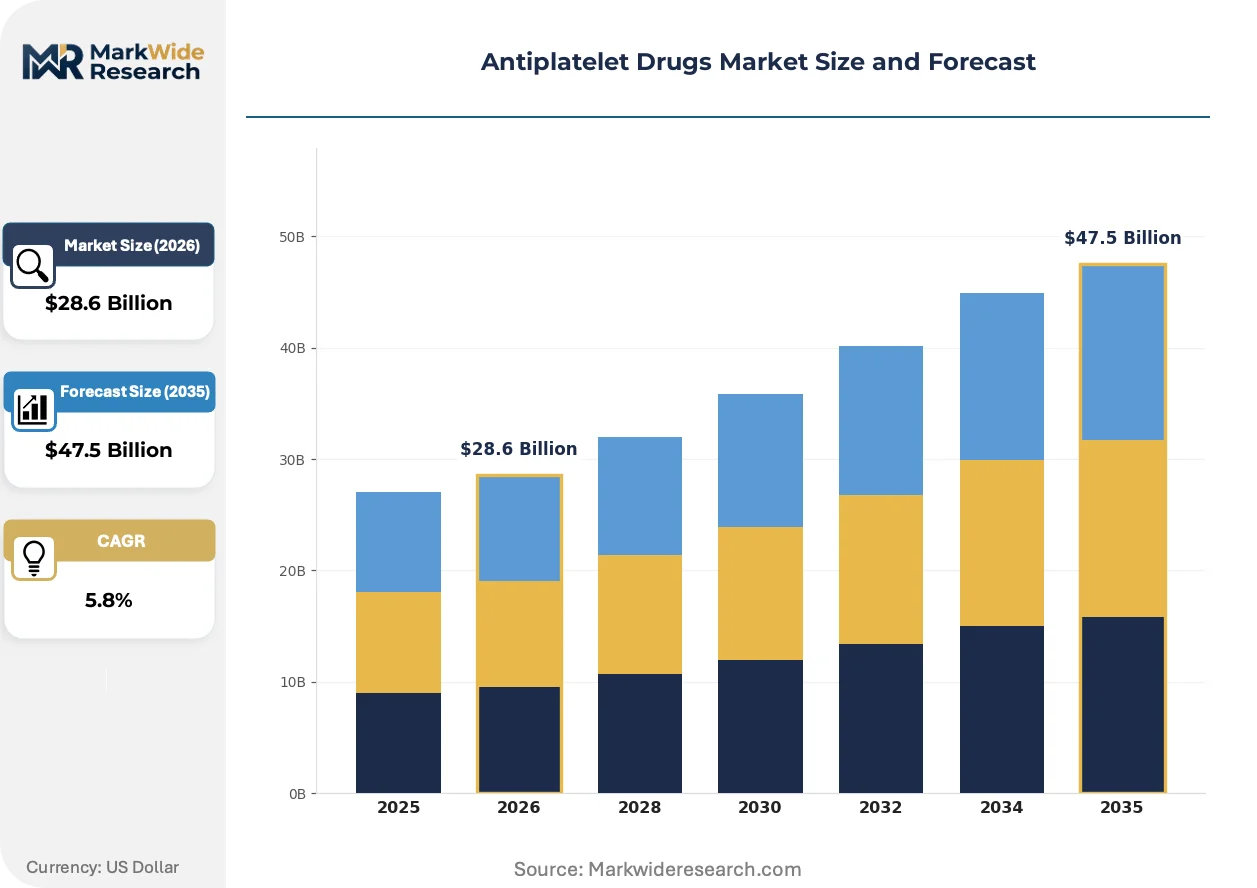
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $47.5 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Drug Type: Aspirin, Clopidogrel, Ticagrelor, Prasugrel Administration Route: Oral, Intravenous, Subcutaneous, Sublingual Therapeutic Application: Coronary Artery Disease, Stroke Prevention, Peripheral Artery Disease, Myocardial Infarction End User: Hospitals, Clinics, Homecare, Pharmacies |
| Companies Covered | Sanofi, Boehringer Ingelheim, AstraZeneca, Merck & Co., Pfizer, Bayer, Daiichi Sankyo, The Medicines Company, Bristol-Myers Squibb, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Antiplatelet Drugs Market Emerging Trajectories
Antiplatelet development is pivoting toward precision dosing and point-of-care genetic testing integration, reshaping how clinicians match P2Y12 inhibitor selection to individual patient metabolizer status.
Pharmacogenomic testing for CYP2C19 polymorphisms is modularizing prescriber decision workflows. Cardiology departments at tertiary hospitals are embedding rapid genetic screening into pre-PCI protocols, compressing the window between diagnosis and optimized therapy selection. This modularization is fragmenting the traditional one-size-fits-all clopidogrel paradigm into stratified treatment pathways.
REACH registration requirements in Europe are tightening environmental exposure documentation for pharmaceutical manufacturing effluents. Active pharmaceutical ingredient producers must now quantify and mitigate solvent discharge footprints, elevating capital requirements for European-sited production. Formulators with existing green chemistry investments are capturing preferential supplier status with EMA-aligned procurement teams.
Hospital pharmacy committees are consolidating antiplatelet purchasing through therapeutic class reviews that bundle acute and chronic formulations under single vendor agreements. This concentration is displacing fragmented physician-level prescribing autonomy in favor of protocol-driven formulary compliance. The shift is most visible in United States integrated delivery networks where value-based contracts penalize therapeutic variation.
Antiplatelet Drugs Market Segmentation
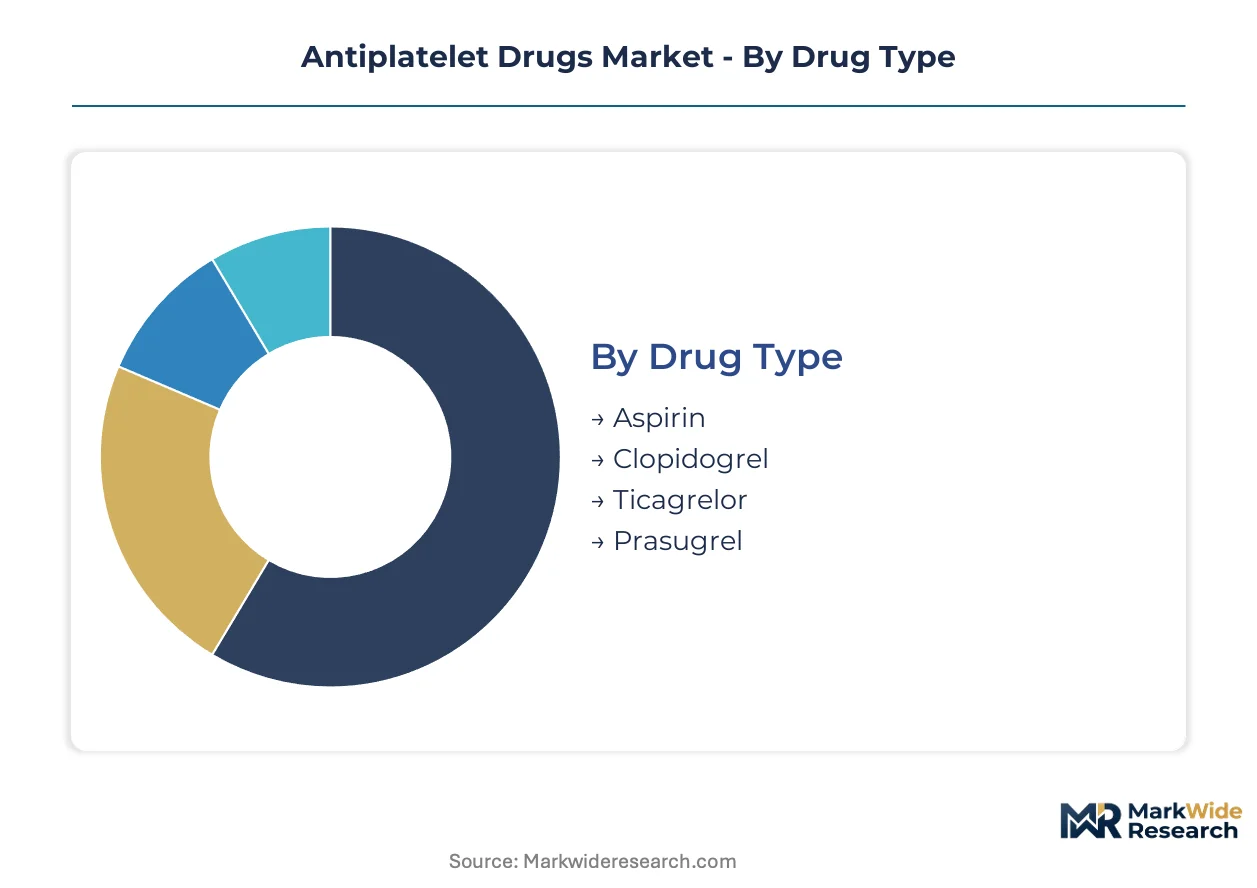
Antiplatelet prescribing patterns fragment sharply across clinical settings and patient acuity levels. Formulary committees stratify procurement by onset speed, bleeding risk profiles, and reimbursement tiers rather than molecule class alone.
Drug Type:
Cost tier stratification separates chronic maintenance regimens from premium acute-intervention therapies.
- Aspirin:Cyclooxygenase-1 inhibition delivers irreversible platelet suppression at the lowest cost per patient-day. Primary demand concentrates in United States outpatient settings where pharmacy benefit managers mandate step-therapy protocols.
- Clopidogrel:Thienopyridine-class P2Y12 receptor antagonism requires hepatic activation via CYP2C19 enzymes, creating metabolizer-dependent efficacy variation. Hospital formularies in Germany and France favor this agent for stable coronary artery disease maintenance due to generic cost compression.
- Ticagrelor:Reversible P2Y12 binding enables faster platelet function recovery post-discontinuation. Acute coronary syndrome protocols at tertiary hospitals in the United States and United Kingdom drive volume.
- Prasugrel:Rapid, irreversible platelet inhibition carries boxed warnings for patients with prior stroke or TIA. Catheterization lab adoption concentrates in Japan and South Korea where rapid-onset requirements dominate procedural planning.
Volume sits with aspirin and clopidogrel; growth tilts toward ticagrelor as dual antiplatelet therapy protocols shorten.
Administration Route:
Speed-to-onset requirements reshape route selection across the care continuum from emergency departments to discharge planning.
- Oral:Immediate-release and enteric-coated tablets dominate chronic maintenance prescribing. United States integrated delivery networks bundle oral formulations into 90-day maintenance protocols for post-PCI patients.
- Intravenous:Cangrelor infusion delivers platelet inhibition within minutes for patients unable to tolerate oral loading. Catheterization labs at Cleveland Clinic and Mayo Clinic anchor United States demand for procedural bridging.
- Subcutaneous:Depot formulations enable outpatient antiplatelet coverage during perioperative windows when oral agents are contraindicated. European hospital-at-home programs in the Netherlands pilot this route for thrombosis prophylaxis.
- Sublingual:Rapid buccal absorption bypasses first-pass metabolism for patients with compromised gastrointestinal motility. Prehospital emergency medical services in Australia evaluate this route for stroke-alert protocols.
Oral administration captures the largest patient volume; intravenous segments command the steepest expansion trajectory in acute settings.
Therapeutic Application:
Indication-specific bleeding-risk tolerances drive molecule selection and treatment duration decisions.
- Coronary Artery Disease:Chronic atherosclerotic plaque management requires indefinite antiplatelet coverage for secondary prevention. United States cardiology practices anchor volume through stable angina and post-revascularization maintenance.
- Stroke Prevention:Transient ischemic attack and cryptogenic stroke protocols are expanding neurologist prescribing beyond cardiology dominance. Secondary prevention guidelines in the United Kingdom and Canada now mandate dual antiplatelet therapy for 21-90 days post-minor stroke.
- Peripheral Artery Disease:Lower-extremity revascularization and claudication management drive chronic therapy. Vascular surgery departments at German university hospitals prioritize ticagrelor for limb-salvage outcomes.
- Myocardial Infarction:STEMI and NSTEMI protocols demand rapid platelet inhibition with precise duration calibration. United States hospital reimbursement penalties for readmission compress prescribing windows toward shorter evidence-based durations.
Coronary artery disease maintains the largest installed base; stroke prevention is gaining share fastest as neurology protocols proliferate.
End User:
Purchasing authority concentration determines contract structure and price realization across settings.
- Hospitals:Catheterization labs and emergency departments capture acute antiplatelet administration with protocol-driven formulary compliance. United States health systems consolidate purchasing through therapeutic class reviews that displace physician-level autonomy.
- Clinics:Outpatient cardiology and neurology practices manage chronic therapy titration and monitoring. Medicare Advantage penetration in Florida and Texas drives volume through risk-adjusted chronic disease management.
- Homecare:Infusion nursing services enable post-discharge IV-to-oral transitions for complex patients. United Kingdom NHS hospital-at-home expansion pilots antiplatelet administration outside traditional facilities.
- Pharmacies:Retail and specialty pharmacy channels handle maintenance prescription fulfillment with generic substitution pressure. United States pharmacy benefit manager formulary tiers drive therapeutic interchange toward lowest-cost equivalents.
Hospital procurement concentrates acute volume; homecare channels are expanding most quickly as post-acute care models shift site of service.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Active pharmaceutical ingredient synthesis for clopidogrel and ticagrelor concentrates in Asian manufacturing clusters, with formulation and commercialization anchored across North American and European hospital networks.
United States
Percutaneous coronary intervention volumes at Cleveland Clinic and Mayo Clinic drive acute antiplatelet demand. FDA tightened dual antiplatelet therapy duration guidance in 2023, compressing prescribing windows toward shorter evidence-based protocols. Integrated delivery networks in Texas and Florida consolidate purchasing through therapeutic class reviews that displace physician-level autonomy.
Germany
Hospital formularies at Charité Berlin and Heidelberg University Hospital favor generic clopidogrel for stable coronary artery disease maintenance. EMA pharmacovigilance requirements mandate bleeding risk disclosure investments from manufacturers. REACH registration requirements tighten environmental exposure documentation for API manufacturing effluents, elevating capital requirements for European-sited production.
Japan
Rapid-onset antiplatelet requirements dominate procedural planning at Tokyo University Hospital and Osaka University Hospital. PMDA reviews prasugrel labeling with boxed warnings for prior stroke or TIA patients. Catheterization lab adoption concentrates in Kanto and Kansai metropolitan clusters where PCI volumes sustain premium pricing for acute formulations.
India
Domestic pharmaceutical manufacturing incentives under the PLI scheme attract multi-source qualification investments for critical antiplatelet raw materials. CDSCO accelerated approval pathways for generic P2Y12 inhibitors expand outpatient access. API production clusters in Hyderabad and Ahmedabad pivot toward captive supply arrangements that reduce import dependency for clopidogrel intermediates.
United Kingdom
Secondary stroke prevention guidelines mandate dual antiplatelet therapy for 21-90 days post-minor stroke, expanding neurologist prescribing beyond cardiology dominance. NHS hospital-at-home programs pilot post-discharge IV-to-oral transitions. Tertiary centers at Oxford and Cambridge embed pharmacogenomic testing for CYP2C19 polymorphisms into pre-PCI protocols.
Antiplatelet Drugs Market Vendor Landscape
Global majors compete with regional champions across hospital channel dominance and API supply security. The vendor base stratifies into three tiers: multinational pharmaceutical conglomerates with captive manufacturing, mid-sized generics specialists with multi-source API qualification, and regional hospital-service providers with localized distribution networks. Dominant competitive moves include backward integration into API production and therapeutic class bundling under single vendor agreements with integrated delivery networks.
Within the multinational tier, Sanofi leverages European captive manufacturing to sustain supply continuity for branded portfolios, while AstraZeneca anchors hospital channel dominance through ticagrelor specialization. Among diversified pharmaceutical conglomerates, Pfizer extends oral antiplatelet distribution into emerging hospital networks across Latin America and Asia-Pacific. These three exemplify distinct strategic archetypes: supply security through vertical control, acute-care protocol anchoring, and geographic breadth expansion.
| Leading Market Players |
|---|
| Sanofi |
| Boehringer Ingelheim |
| AstraZeneca |
| Merck & Co. |
| Pfizer |
| Bayer |
| Daiichi Sankyo |
| The Medicines Company |
| Bristol-Myers Squibb |
| Others |
Supply Flow & Price Mechanics
Synthetic organic chemist concentrations in Hyderabad and Ahmedabad anchor cost differentials that widen spreads between premium branded antiplatelet formulations and economy generic equivalents. Labor arbitrage in Indian API manufacturing clusters compresses production economics for clopidogrel intermediates while European REACH compliance costs elevate pricing floors for captive European-sited production.
Pricing Analysis
Service bundling separates acute-care protocol packages from unbundled outpatient maintenance prescriptions. Three-tier pricing structure across premium, standard, and economy levels stratifies by onset speed and bleeding-risk profile, with catheterization lab formulations commanding premiums over chronic oral tablets. Cost compression in generic clopidogrel intensifies because pharmacy benefit managers drive therapeutic interchange toward lowest-cost equivalents. Outpatient retail channels exhibit highest price sensitivity; hospital procurement committees demonstrate lowest sensitivity due to protocol-driven formulary compliance.
Supply Chain Analysis
Clopidogrel active pharmaceutical ingredient supply rests on manufacturing clusters in India, China, and select European sites. Key inputs include thienopyridine intermediates, specialty solvents for crystallization, and enteric coating polymers for tablet formulations. Single-source vulnerability concentrates in select Asian manufacturing clusters during geopolitical disruptions or quality enforcement actions. Distribution runs through hospital pharmacy committees and integrated delivery network procurement offices that consolidate therapeutic class purchasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around manufacturers with captive API supply and hospital channel dominance, as generic substitution pressure forces margin-dependent formulators toward exit or acquisition.
For Market Incumbents: Acquire multi-source API qualification assets to reduce import dependency for critical antiplatelet raw materials. Secure backward integration into clopidogrel intermediate production in Indian PLI scheme zones. Defend hospital formulary positioning through pharmacogenomic testing platform partnerships that embed branded agents into precision dosing protocols. For New Entrants and Emerging Players: Launch via catheterization lab service partnerships in Latin American hospital networks where intravenous cangrelor penetration remains underdeveloped. Target Brazilian and Mexican tertiary centers with acute coronary syndrome protocol development services. White-space exists in digital therapeutics integration for medication adherence monitoring platforms that enable outcome-based contracting with United States integrated delivery networks. For Investors and Strategic Acquirers: Re-rating potential sits with mid-sized generics specialists possessing multi-source API qualification and EMA-aligned green chemistry investments given REACH registration requirements tightening environmental exposure documentation. Long-term viability favors formulators with hospital channel anchoring and therapeutic class bundling capabilities. Watch FDA dual antiplatelet therapy duration guidance revisions as inflection indicators for prescribing window compression.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Source API Qualification | Reduces supply vulnerability during CDSCO quality enforcement actions in Indian manufacturing clusters. |
| Pharmacogenomic Testing Integration | Embeds branded P2Y12 inhibitors into pre-PCI protocols at Cleveland Clinic and Mayo Clinic. |
| REACH-Aligned Green Chemistry Investment | Captures preferential supplier status with EMA procurement teams at Charité Berlin. |
| Hospital Channel Bundling Agreements | Consolidates acute and chronic antiplatelet purchasing under single vendor contracts with Texas health systems. |
| Digital Adherence Platform Development | Enables outcome-based contracting with Medicare Advantage plans in Florida chronic disease management. |
Methodological Framework
Independent corroboration across hospital formulary directors, regulatory affairs leads at API manufacturers, cardiology department heads, and pharmacy benefit manager access specialists underwrites the qualitative findings. Secondary validation draws from FDA filings, EMA pharmacovigilance databases, ClinicalTrials.gov cardiovascular study registries, and CMS Medicare Part D utilization data. Bottom-up patient-volume modeling and top-down pharmaceutical market sizing triangulate across the analysis window.
Comparable-period anchoring to historical PCI volume trends and dual antiplatelet therapy protocol adoption curves shapes the projection horizon. The analytical framework segments by drug type, administration route, therapeutic application, and end-user procurement authority across the modeling period. CAGRs derive from patient population epidemiology, procedure volume trajectories, and reimbursement policy shifts. Forecast inputs incorporate PMDA labeling reviews, NHS hospital-at-home expansion pilots, and India's PLI scheme uptake rates.
Regulatory guidance revisions, supply chain disruption events, and generic substitution acceleration are the dominant revision risks. Forecasts reflect documented assumptions about PCI volume growth, pharmacogenomic testing penetration, and formulary consolidation trajectories. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Loxoprofen Market
Pharmaceuticals
Global General Anesthesia Drugs Market
Pharmaceuticals
Global Fondaparinux Market
Pharmaceuticals
Herbal Drugs Market
Pharmaceuticals
Metformin HCL Drugs Market
Pharmaceuticals
Nimodipine Market
Pharmaceuticals
Global Pharmaceutical Warehousing Market
Pharmaceuticals
Opium Tincture Market
Pharmaceuticals
Istradefylline API Market
Pharmaceuticals
Global Treatment-Resistant Depression Market
Pharmaceuticals
Oxaliplatin Market
Pharmaceuticals
Tumor Necrosis Factor Alpha Inhibitors Market
Pharmaceuticals
Pharmacovigilance (PV) Market
Pharmaceuticals
Pharmacy and Drug Store Franchises Market
Pharmaceuticals
Global HPMC Capsules Market
Pharmaceuticals
AI Drug Development Market