
 Hydrocortisone Market | 2026-2036
Hydrocortisone Market Size, Share, and Industry Trends Forecast 2026-2036
Hydrocortisone Market Outlook
REACH compliance is realigning the cost-of-entry calculus for European hydrocortisone suppliers, forcing reformulation investments that smaller manufacturers struggle to fund. GlaxoSmithKline plc leverages its dermatology heritage and regulatory dossier depth to sustain premium positioning across topical segments. Pfizer Inc. anchors hospital procurement contracts through injectable supply security, while Sun Pharmaceutical Industries Ltd. competes aggressively on oral generic pricing in emerging markets.
Hydrocortisone is a synthetic glucocorticoid mirroring cortisol's anti-inflammatory and immunosuppressive action, typically formulated at concentrations ranging from 0.5% to 2.5% for topical delivery or as sodium succinate salt for intravenous administration. It suppresses phospholipase A2 activity and cytokine transcription, serving primary commercial purpose in acute adrenal insufficiency, chronic inflammatory disease management, and dermatological symptom control. Topical formulations dominate current revenue pools due to high prescription frequency in eczema and psoriasis, though ophthalmic preparations represent the fastest-growing category as preservative-free unit-dose formats gain specialist preference. Hospital end users still command the largest absolute volume, but homecare channels are capturing disproportionate growth as self-administration protocols expand for maintenance steroid therapy.
FDA bioequivalence requirements for topical corticosteroids, EMA's evolving guidance on inhaled and dermal drug environmental risk, and WHO Essential Medicines List inclusion collectively shape product standards, pricing power, and market access trajectories across jurisdictions. The FDA's in vitro release test protocols and EMA's persistency assessments for aquatic toxicity are raising technical barriers that favor manufacturers with integrated analytical capabilities and established pharmacovigilance systems. Stakeholders must monitor how tightening bioequivalence standards and sustainability-linked procurement criteria reshape competitive moats and partnership requirements.
Market Dynamics
FDA's tightened bioequivalence protocols for topical corticosteroids are elevating technical barriers and consolidating manufacturing advantage among established producers with integrated analytical capabilities. This regulatory compression is reshaping competitive moats across formulation types.
Growth Catalysts
- Homecare expansion:Self-administration protocols for chronic dermatological conditions are extending addressable patient populations beyond hospital-centric models. Homecare channels now capture disproportionate growth in maintenance steroid therapy.
- REACH compliance realignment:European environmental persistency assessments are forcing reformulation investments that favor larger manufacturers with dedicated regulatory dossier depth. Smaller suppliers face exit pressure from elevated cost-of-entry.
- Ophthalmic unit-dose innovation:Preservative-free single-use formats are gaining specialist preference in ocular inflammation management. This delivery innovation opens premium positioning opportunities distinct from commoditized topical segments.
Market Restraints
- API supply concentration:Active pharmaceutical ingredient production clusters in select Asian manufacturing hubs create vulnerability to geopolitical friction or environmental enforcement disruptions.
- Substitution pressure from betamethasone:Alternative corticosteroids with longer half-lives compete for chronic inflammatory indications where patient compliance favors less frequent dosing.
- EMA aquatic toxicity thresholds:Evolving environmental risk guidance for dermal drug metabolites imposes additional analytical burden and lifecycle assessment costs on European market participants.
Strategic Opportunities
- Pediatric formulation gaps:Age-appropriate dosing vehicles and palatable oral suspensions remain underdeveloped relative to adult-standard products. Regulatory incentives for pediatric exclusivity create development pathway advantages.
- Compounding pharmacy collaboration:Customized strength and combination formulations for rare adrenal disorders offer defensible niche positioning outside mass-manufactured generic competition.
- WHO Essential Medicines inclusion:List placement strengthens procurement eligibility for institutional buyers and humanitarian supply programs. This status supports volume commitments from national health systems.
Industry Challenges
- Bioanalytical talent scarcity:In vitro release testing and dermatopharmacokinetic study design require specialized expertise that outpaces current training pipeline output. Contract research organizations report extended queue times for corticosteroid equivalence studies.
- Legacy facility retrofit costs:Containment upgrades for potent hormone manufacturing and dedicated line requirements for hormonal/non-hormonal segregation demand capital deployment that compresses returns on mature products.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydrocortisone Market |
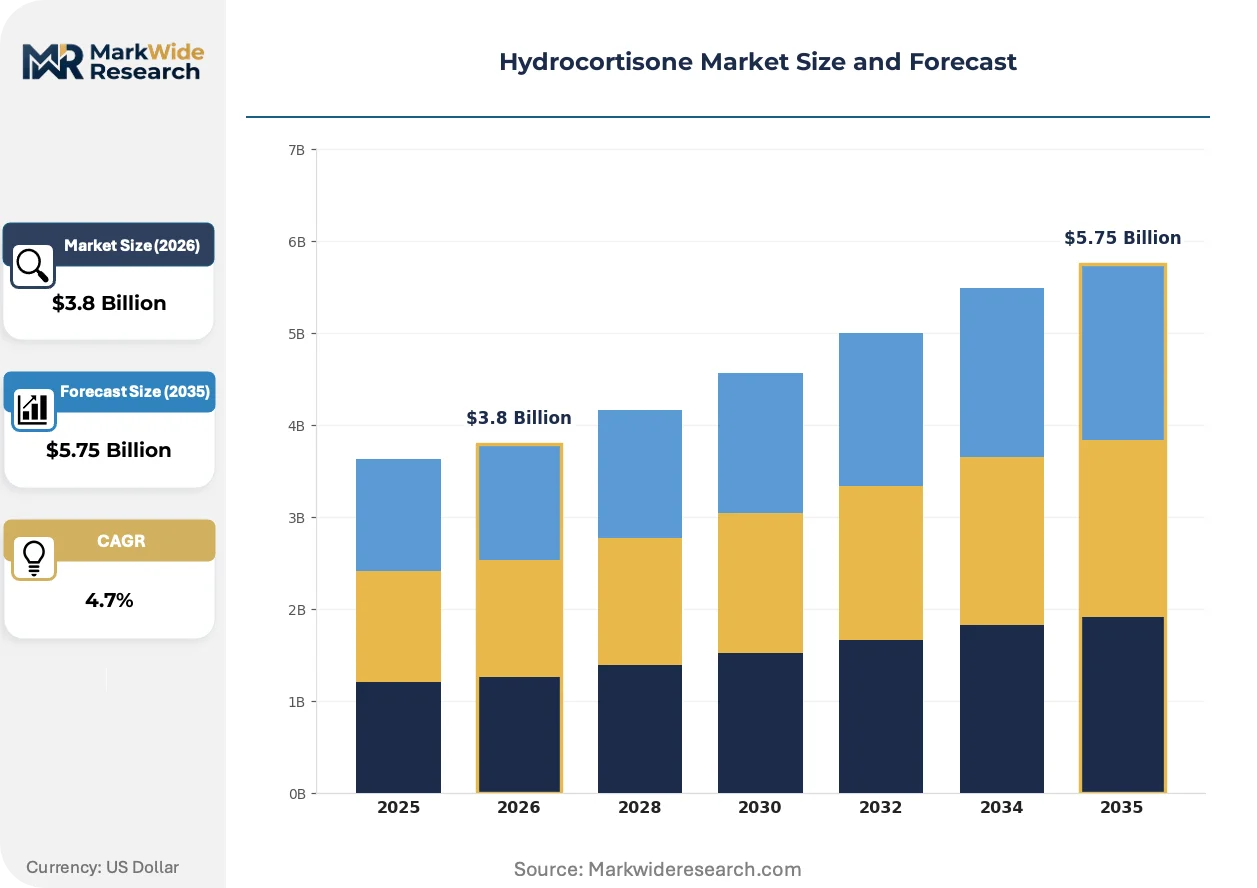
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.75 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Topical, Injectable, Oral, Ophthalmic End User: Hospitals, Clinics, Homecare, Pharmacies Application: Inflammation, Allergies, Autoimmune Disorders, Dermatological Conditions Distribution Channel: Online, Retail, Wholesalers, Distributors |
| Companies Covered | GlaxoSmithKline plc, Teva Pharmaceutical Industries Ltd., Pfizer Inc., Sun Pharmaceutical Industries Ltd., Sandoz AG, Johnson & Johnson, Viatris Inc., Hikma Pharmaceuticals PLC, Bayer AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydrocortisone Market Strategic Shifts
Formulation science and regulatory science are converging to redefine product differentiation in corticosteroid markets. Technical advancement now centers on delivery precision and environmental compatibility rather than molecular modification.
Nanostructured lipid carriers are unifying enhanced dermal penetration with reduced systemic absorption in next-generation topical products. Dermatology specialists in German and Swiss hospital networks are piloting these carriers for recalcitrant plaque psoriasis. The technology is unifying efficacy and safety profiles that previously required trade-offs between potency and side-effect burden.
EMA's evolving guidance on inhaled and dermal drug environmental risk is mandating persistency assessments and aquatic toxicity data packages for marketing authorization renewals. This policy shift imposes multi-year analytical timelines on manufacturers lacking established environmental fate capabilities. European generic applicants are responding by partnering with specialized ecotoxicology contract laboratories or withdrawing from marginal product categories.
Hospital procurement consortia are consolidating purchasing power and unbundling after-sales technical support from product pricing. This behavioral shift compresses supplier margins while elevating service-level agreement requirements. The transformation is most visible in United States group purchasing organization contracts for injectable hydrocortisone sodium succinate, where supply security commitments now outweigh unit price in award criteria.
Hydrocortisone Market Segmentation
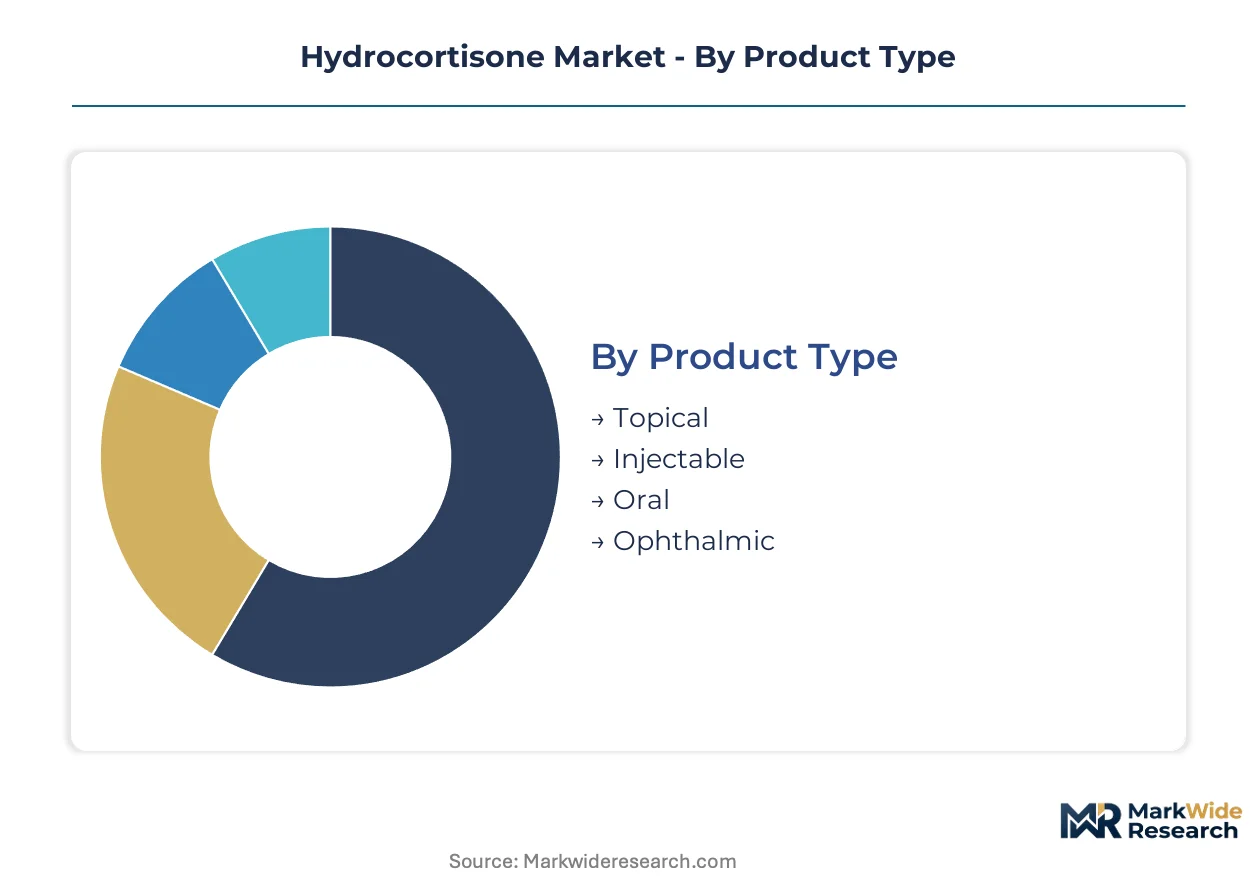
Formulation chemistry and delivery route determine manufacturing complexity, regulatory pathway, and pricing power across hydrocortisone supply. Segment boundaries increasingly blur as nanocarrier technologies enable novel cross-category products.
Product Type:
Supply concentration clusters around facilities with validated sterility assurance and hormonal containment infrastructure.
- Topical:Cream, ointment, and lotion formulations at 0.5% to 2.5% concentration dominate prescription volume for eczema and psoriasis management. United States dermatology practices generate the highest per-capita prescribing intensity, though German hospital networks are piloting nanostructured lipid carriers for recalcitrant plaque psoriasis.
- Injectable:Sodium succinate salt for intravenous administration serves acute adrenal insufficiency and perioperative stress coverage. Hospital procurement consortia in the United States prioritize supply security commitments over unit price in award criteria for this category.
- Oral:Tablet and suspension formats support chronic maintenance therapy for autoimmune conditions. Indian generic manufacturers compete aggressively on pricing in emerging markets where WHO Essential Medicines List placement drives institutional procurement.
- Ophthalmic:Preservative-free unit-dose formats are gaining specialist preference for ocular inflammation management. Swiss and German ophthalmology clinics are early adopters of these premium-positioned delivery innovations.
Topical formulations absorb the bulk of installed capacity; ophthalmic preparations are expanding most quickly.
End User:
Channel economics diverge sharply between institutional procurement and direct-to-patient fulfillment models.
- Hospitals:Command the largest absolute volume through emergency department adrenal crisis protocols and perioperative steroid coverage. Group purchasing organization contracts in the United States unbundle after-sales technical support from product pricing, elevating service-level requirements.
- Homecare:Self-administration protocols for chronic dermatological maintenance are extending addressable populations beyond acute-care settings. United Kingdom and Netherlands home nursing services are expanding reimbursement for patient-managed topical therapy.
- Clinics:Outpatient infusion centers and specialist practices bridge hospital and homecare channels for injectable maintenance dosing.
- Pharmacies:Community and hospital outpatient dispensaries handle the majority of oral and topical prescription fulfillment, with compounding pharmacies serving rare adrenal disorder niches.
Hospitals absorb the bulk of installed capacity; homecare is climbing the fastest as self-administration protocols proliferate.
Application:
Disease prevalence and treatment duration determine volume per indication, with chronic conditions sustaining recurring revenue streams.
- Dermatological Conditions:Eczema, psoriasis, and contact dermatitis generate the highest prescription frequency across all age groups. Pediatric formulation gaps persist despite regulatory incentives for age-appropriate development.
- Autoimmune Disorders:Lupus, rheumatoid arthritis, and inflammatory bowel disease maintenance require long-term oral or intermittent injectable therapy. Substitution pressure from longer-acting corticosteroids like betamethasone challenges compliance in chronic indications.
- Inflammation:Acute and chronic inflammatory states across multiple organ systems drive hospital-based injectable consumption.
- Allergies:Seasonal and perennial allergic manifestations support over-the-counter and prescription topical and oral demand.
Dermatological conditions absorb the bulk of installed capacity; autoimmune disorders are gaining share fastest as maintenance protocols extend treatment duration.
Distribution Channel:
Channel selection reflects patient acuity, reimbursement structure, and regulatory classification of specific formulations.
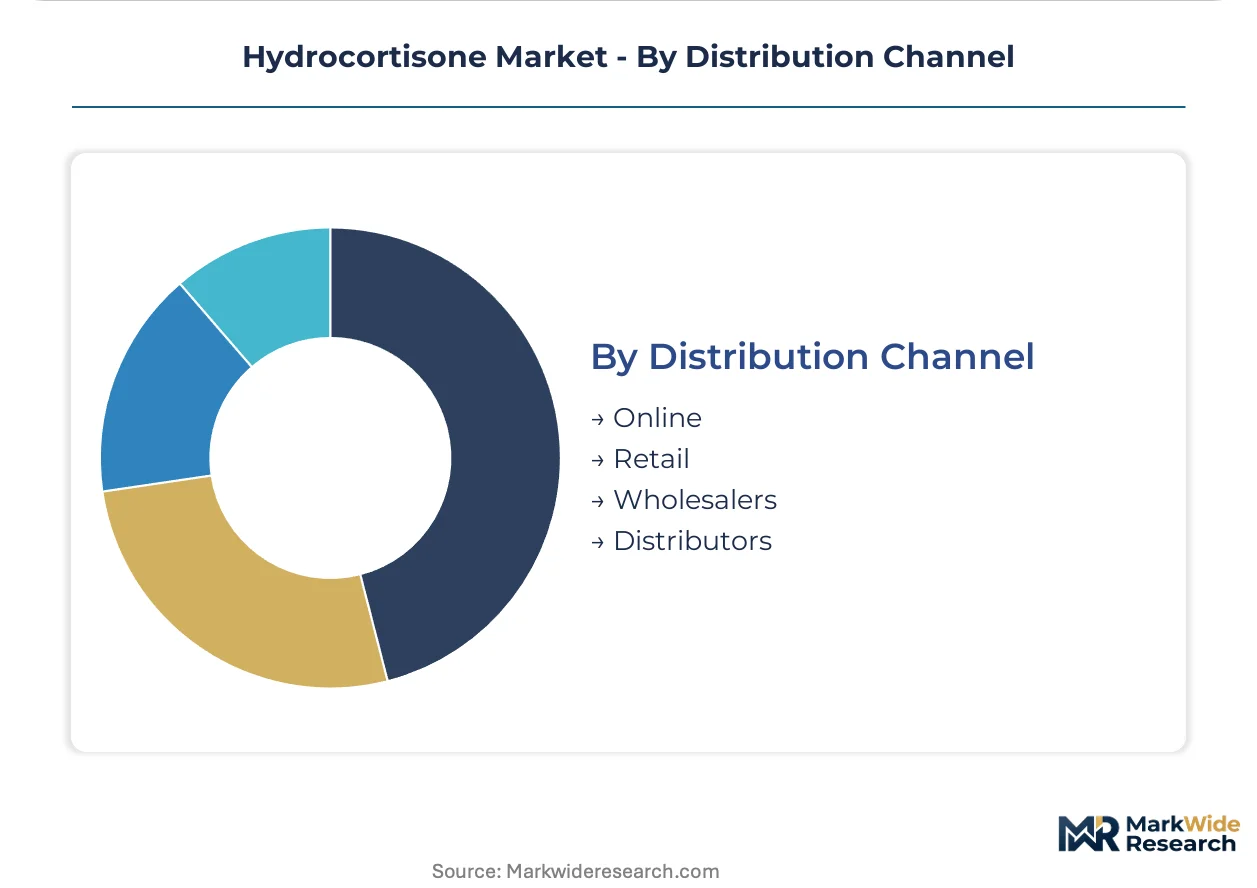
- Wholesalers:Three-step distribution through national pharmaceutical wholesalers dominates hospital and pharmacy supply in the United States and Western Europe. Inventory carrying costs and cold-chain requirements for injectable products favor established logistics networks.
- Retail:Community pharmacy chains and independent dispensaries handle the majority of topical and oral prescription fulfillment, with tiered pricing across premium, standard, and economy product tiers.
- Online:Telehealth-integrated pharmacies and direct-to-patient platforms are capturing disproportionate growth in chronic dermatology maintenance prescriptions. United States and United Kingdom regulatory frameworks are adapting to verify prescriber-patient relationships in digital channels.
- Distributors:Specialized pharmaceutical distributors serve compounding pharmacies and institutional buyers with just-in-time delivery requirements for emergency adrenal insufficiency protocols.
Wholesalers absorb the bulk of installed capacity; online channels are expanding most quickly as telehealth prescribing normalizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Gujarat and Telangana concentrate Indian API manufacturing for corticosteroid supply chains. These designated pharmaceutical corridors attract multinational formulation partnerships through tax holidays and streamlined environmental clearances.
United States
FDA bioequivalence protocols for topical corticosteroids drive reformulation investments among domestic manufacturers. Hospital procurement consortia prioritize supply security commitments over unit pricing for injectable hydrocortisone sodium succinate. New Jersey and North Carolina host the densest clusters of sterile manufacturing facilities serving institutional buyers.
Germany
EMA environmental persistency assessments for dermal drug metabolites impose multi-year analytical timelines on marketing authorization holders. Nanostructured lipid carrier research in Heidelberg and Munich hospital networks pilots enhanced topical delivery for recalcitrant psoriasis. REACH compliance costs favor established producers with dedicated regulatory dossier capabilities.
India
CDSCO manufacturing facility inspections and WHO prequalification requirements shape export eligibility for generic oral formulations. Hyderabad and Ahmedabad API hubs supply corticosteroid intermediates to European and North American formulation sites. Domestic oral generic pricing competition intensifies as local manufacturers expand institutional procurement volumes.
Switzerland
Swissmedic oversight of preservative-free ophthalmic unit-dose formats supports premium positioning in ocular inflammation management. Basel and Zurich specialist clinics drive early adoption of single-use delivery innovations. Environmental risk assessment integration into marketing authorization renewals elevates technical barriers for new entrants.
United Kingdom
MHRA post-Brexit regulatory autonomy maintains alignment with EMA environmental guidance while streamlining pediatric formulation approvals. Home nursing services in Greater London and Manchester expand reimbursement for patient-managed topical therapy. NHS procurement frameworks favor suppliers with established pharmacovigilance systems and UK-based quality control laboratories.
Hydrocortisone Market Competitive Environment
United States and European producers anchor the premium formulation tier; Indian specialists hold dominant positions in API supply and oral generic manufacturing. The market structure consolidates around established players with integrated analytical capabilities and regulatory dossier depth. Three archetypes define competitive positioning: integrated pharmaceutical conglomerates with dermatology heritage, generic manufacturers competing on scale and cost efficiency, and specialized API suppliers controlling upstream corticosteroid chemistry. Capacity expansion and strategic partnerships represent the dominant competitive moves as manufacturers secure supply chain resilience.
Within the integrated pharmaceutical tier, GlaxoSmithKline plc and Pfizer Inc. exemplify archetypes leveraging regulatory expertise and hospital procurement relationships. Sun Pharmaceutical Industries Ltd. occupies a position representing Indian generic scale advantages in oral formulation export markets. These three entities collectively illustrate how geographic origin and corporate structure map to distinct competitive positioning vectors across topical, injectable, and oral segments.
| Leading Market Players |
|---|
| GlaxoSmithKline plc |
| Teva Pharmaceutical Industries Ltd. |
| Pfizer Inc. |
| Sun Pharmaceutical Industries Ltd. |
| Sandoz AG |
| Johnson & Johnson |
| Viatris Inc. |
| Hikma Pharmaceuticals PLC |
| Bayer AG |
| Others |
Value Chain & Pricing Dynamics
Captive integration into API manufacturing anchors both supply security and margin defense for established hydrocortisone producers. Indian and Chinese intermediate suppliers control upstream corticosteroid chemistry, while European and North American formulation sites command premium positioning through FDA-validated sterility assurance and dedicated hormonal containment infrastructure.
Pricing Analysis
Short lead-time premiums separate emergency procurement from scheduled replenishment across hospital and homecare channels. Three-tier pricing structure across premium, standard, and economy levels reflects differentiation by FDA bioequivalence tier, after-sales technical support bundling, and volume scale. Pricing pressure stems from Indian generic manufacturers competing aggressively on oral formulation export pricing. Hospital procurement consortia exhibit lowest price sensitivity due to supply security prioritization; retail pharmacy channels face highest sensitivity from patient co-pay exposure.
Supply Chain Analysis
Domestic-content mandates in United States hospital procurement are reshaping sourcing toward North American sterile manufacturing sites. API production clusters in India and China feed formulation facilities in Germany, Switzerland, and the United States. Corticosteroid intermediate chemistry draws from specialized fermentation and synthetic organic capabilities concentrated in Hyderabad and Ahmedabad. Single-source vulnerability persists for sodium succinate salt used in injectable emergency protocols. Distribution runs through three-step wholesaler networks serving hospital group purchasing organizations and retail pharmacy chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Manufacturing capacity for validated hormonal containment is tightening, propping pricing power for facilities with existing infrastructure. FDA bioequivalence protocol elevation is accelerating exit of undercapitalized competitors.
For Market Incumbents: Hedge against API supply disruption through backward integration into corticosteroid intermediate manufacturing or long-term offtake agreements with Hyderabad and Ahmedabad suppliers. Reinforce hospital procurement relationships by unbundling supply security commitments from unit pricing in GPO negotiations. Betamethasone substitution pressure demands enhanced clinical differentiation through delivery innovation. For New Entrants and Emerging Players: The premium-economy price-point gap in preservative-free ophthalmic unit-dose formats offers accessible entry. Pediatric formulation gaps for age-appropriate oral suspensions present white-space with regulatory exclusivity incentives. Compounding pharmacy collaboration for rare adrenal disorder niches bypasses mass-manufactured generic competition. Target telehealth-integrated dispensing channels for chronic dermatology maintenance prescriptions. For Investors and Strategic Acquirers: Exit pathways concentrate in mid-cap generic manufacturers with WHO prequalification status and established emerging market distribution. Long-term viability hinges on regulatory dossier depth and integrated analytical capabilities rather than commodity scale. Acquisition target archetype: European facilities with REACH-compliant environmental fate assessment infrastructure. Signal to watch: CDSCO enforcement actions disrupting Indian API export eligibility.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Dossier Investment | FDA bioequivalence protocol mastery elevates technical barriers favoring established producers with analytical depth. |
| API Supply Security Agreements | Long-term offtake contracts with Indian intermediate manufacturers mitigate geopolitical and environmental enforcement risks. |
| Pediatric Formulation Development | Regulatory exclusivity incentives create defensible positioning in underdeveloped age-appropriate dosing segments. |
| Ophthalmic Delivery Innovation | Preservative-free unit-dose formats command premium positioning distinct from commoditized topical segments. |
| Compounding Pharmacy Partnership | Customized strength formulations for rare adrenal disorders escape mass-manufactured generic pricing pressure. |
Study Parameters
Document review covered FDA bioequivalence guidance documents, EMA environmental risk assessment frameworks, and WHO Essential Medicines List inclusion criteria, complemented by interviews with regulatory affairs directors at topical formulation manufacturers, hospital procurement managers at United States group purchasing organizations, and pharmacovigilance leads at Indian API exporters. Secondary validation drew from CDSCO facility inspection records, REACH compliance databases, and clinical trial registries. Bottom-up patient-volume modeling and top-down pharmaceutical market sizing were triangulated for consistency.
Segment-level revenue and volume trajectories were generated across formulation type, end-user channel, and application indication throughout the forecast period. CAGRs were derived from patient prevalence projections, prescription frequency trends, and pricing evolution by tier. Modeled inputs included dermatological disease incidence databases, autoimmune disorder maintenance therapy protocols, and hospital adrenal crisis protocol utilization rates by geography.
Underlying measurement precision varies by segment; topical and oral formulations carry tighter precision than ophthalmic and injectable categories due to more mature prescription tracking infrastructure. Forecasts reflect assumptions regarding regulatory timeline adherence, API supply continuity, and reimbursement stability for chronic maintenance indications. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Bone Morphogenetic Protein Market
Pharmaceuticals
Global Caspofungin Market
Pharmaceuticals
Intranasal Migraine Drugs Market
Pharmaceuticals
Adapalene Market
Pharmaceuticals
Latin America Meglitinide Market
Pharmaceuticals
Cervical Cancer Drugs Market
Pharmaceuticals
Global Monoclonal Antibody Therapeutics Market
Pharmaceuticals
Farm Animal Drugs Market
Pharmaceuticals
Omega 3 Prescription Drugs Market
Pharmaceuticals
Anti Obesity Prescription Drugs Market
Pharmaceuticals
Europe Over-The-Counter (OTC) Drugs Market
Pharmaceuticals
Canada Pharmaceutical Market
Pharmaceuticals
Tumor Necrosis Factor Alpha Inhibitors Market
Pharmaceuticals
Angiopoietin Inhibitors Therapeutic Market
Pharmaceuticals
Veterinary Insulin Drugs Market
Pharmaceuticals
Fast Melt Tablets Market