
 Ocular Excipients Market | 2026-2036
Ocular Excipients Market Size, Share, and Industry Trends Forecast 2026-2036
Ocular Excipients Market Analytics
Buyer concentration among contract ophthalmic drug manufacturers is consolidating as large pharmaceutical firms reduce supplier bases to secure excipient traceability. Evonik leverages its lipid nanoparticle expertise to supply controlled-release excipients for glaucoma implants. Millipore Sigma anchors North American distribution through pharma-grade purity certifications and dedicated bioprocessing channels.
Ocular excipients comprise pharmacologically inactive substances formulated with active pharmaceutical ingredients to enhance stability, bioavailability, and patient tolerability in eye-specific delivery systems; these materials must meet stringent endotoxin limits below 0.5 EU per milliliter and osmolality ranges of 250-350 mOsm/kg to prevent corneal irritation. Preservatives dominate product type revenue due to their necessity in multidose ophthalmic solutions, while surfactants represent the fastest-expanding category as lipid-based nanocarrier formulations gain traction for posterior segment drug delivery. Viscosifiers command premium positioning within gel-form applications where carbomer and hyaluronic acid derivatives extend ocular surface residence time.
The FDA enforces Current Good Manufacturing Practice standards for ophthalmic excipients through facility inspections and drug master file reviews, while the EMA's MDR and REACH frameworks impose biocompatibility testing obligations on European suppliers. Japan's PMDA mandates JIS-compliant sterility assurance levels for imported excipients used in intraocular preparations. Stakeholders must monitor evolving pharmacopeial harmonization between USP, EP, and JP monographs to preempt formulation reformulation costs.
Market Dynamics
Regulatory tightening on endotoxin purity and sterility assurance levels is forcing reformulation investments across ophthalmic excipient supply chains, compressing margins for non-compliant suppliers while rewarding certified manufacturers with dedicated bioprocessing infrastructure.
Growth Catalysts
- REACH and MDR frameworks:The EMA's expanded biocompatibility testing obligations for ocular-grade polymers are accelerating supplier consolidation toward pharma-certified producers with dedicated quality systems.
- Lipid nanoparticle delivery systems:Sustained-release formulations for posterior segment glaucoma therapies are pulling demand for specialized surfactants and controlled-release polymers from implant manufacturers.
- Japan's aging demographic:Presbyopia and intraocular pressure management cases are expanding the addressable patient base for multidose preserved formulations requiring benzalkonium chloride alternatives.
Market Restraints
- Carbomer supply concentration:Viscosifier production clusters in select European chemical hubs, exposing formulators to input cost volatility from energy-intensive polymer synthesis.
- Hyaluronic acid purity standards:Animal-derived raw material sourcing faces tightening endotoxin limits, constraining availability of ophthalmic-grade grades below 0.5 EU per milliliter.
- Preservative substitution economics:Stabilized oxychloro complex and polyquaternium alternatives command 40-60% premia over legacy benzalkonium chloride, pressuring generic ophthalmic margins.
Strategic Opportunities
- India's contract manufacturing expansion:CDSCO's streamlined excipient import pathways for ophthalmic applications create entry points for certified suppliers serving domestic generic drug producers.
- Silicone oil viscoelastic convergence:Cataract surgery equipment manufacturers are sourcing dual-function excipients combining vitreous substitution with endothelial protection, opening premium formulation niches.
- Single-use preservative-free unit dose:Blow-fill-seal packaging lines are displacing multidose bottles in dry eye therapies, creating demand for non-preserved excipient systems with extended stability profiles.
Industry Challenges
- Pharmacopeial harmonization complexity:Divergent USP, EP, and JP monograph specifications for polyethylene glycol molecular weight distributions force parallel inventory management and redundant testing protocols.
- Cleanroom capacity constraints:Aseptic excipient finishing requires ISO 5 environment investments exceeding $15 million per facility, limiting mid-scale supplier participation in intraocular-grade segments.
- Analytical method transfer delays:Novel excipient qualification timelines stretch 18-24 months as FDA drug master file reviewers scrutinize impurity profile data for posterior segment delivery systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ocular Excipients Market |
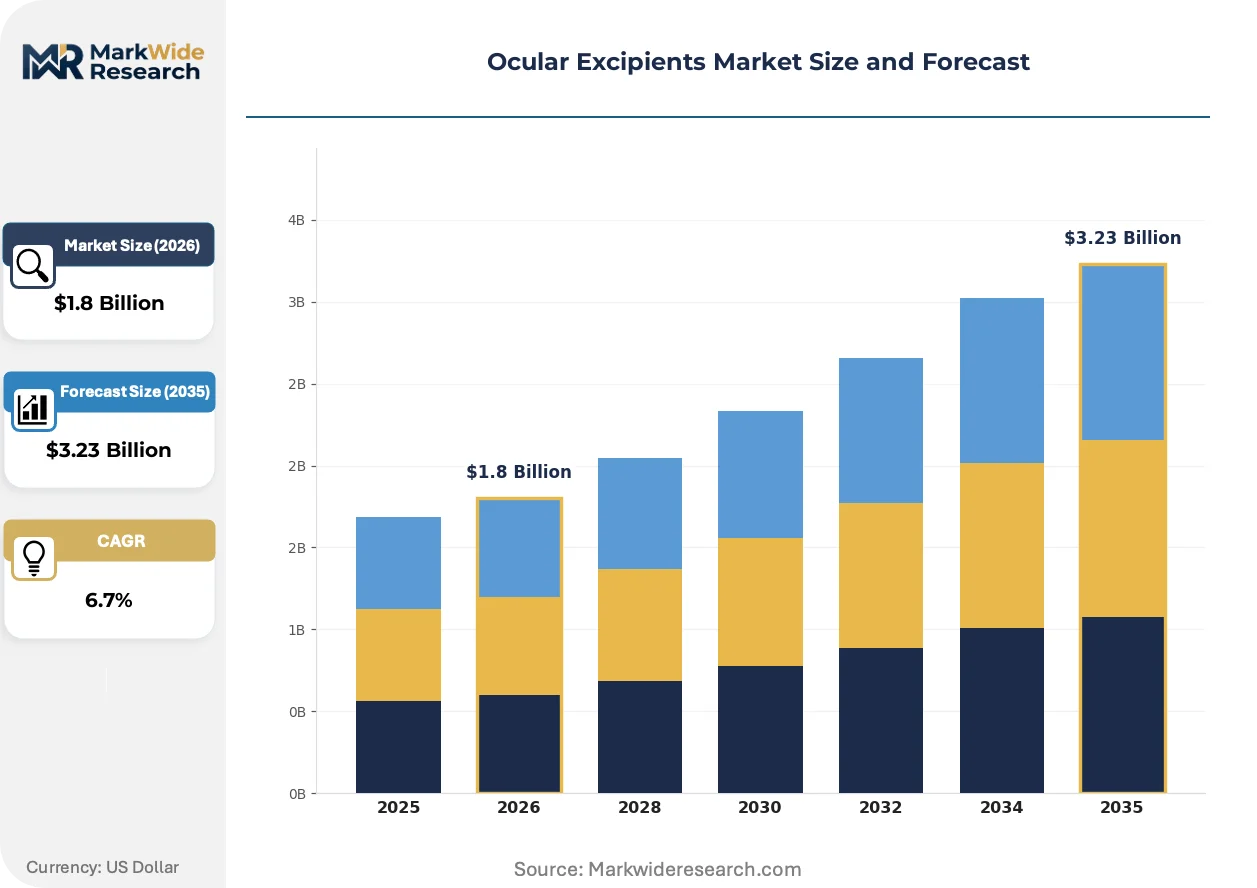
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Preservatives, Viscosifiers, Buffers, Surfactants Application: Ophthalmic Solutions, Eye Drops, Ocular Gels, Contact Lens Solutions Form: Liquid, Gel, Powder, Emulsion End User: Hospitals, Clinics, Pharmacies, Research Laboratories |
| Companies Covered | BASF, Evonik, Innophos, JRS Pharma, Beneo, Fuji Chemical Industries USA, Inc., Mallinckrodt Pharmaceuticals, Millipore Sigma, Anton Paar, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ocular Excipients Market Evolving Landscape
Formulation science is pivoting toward bioadhesive and mucoadhesive excipient platforms that extend ocular surface residence time while eliminating preservatives, driven by corneal toxicity litigation and prescriber preference shifts in chronic therapy categories.
Cyclodextrin complexation technology is consolidating control over poorly soluble active pharmaceutical ingredients in glaucoma and anti-inflammatory eye drops. Generic manufacturers in Germany and Japan are adopting sulfobutylether-beta-cyclodextrin to bypass solubility limitations without cosolvent-induced irritation. This technology is consolidating competitive positioning around intellectual property estates held by specialized chemical suppliers with dedicated ophthalmic application laboratories.
Japan's PMDA has mandated JIS Z 8801-compliant particle size specifications for all imported excipients used in intraocular preparations, effective for new drug applications filed after regulatory notification. This policy is forcing European and North American suppliers to install laser diffraction analytical equipment and revalidate existing batch release protocols. Small-volume parenteral excipient producers without Japan-specific quality systems are exiting the ophthalmic segment entirely.
Contract ophthalmic drug manufacturers are consolidating supplier bases from 12-15 excipient vendors to 3-4 strategic partners with integrated regulatory documentation packages. Large pharmaceutical firms in the United States now require excipient master file cross-referencing, single-source accountability for endotoxin deviations, and dedicated inventory buffers as qualification conditions. This concentration is most visible in Massachusetts and North Carolina clusters where CDMOs serve the presbyopia correction pipeline.
Ocular Excipients Market Segmentation
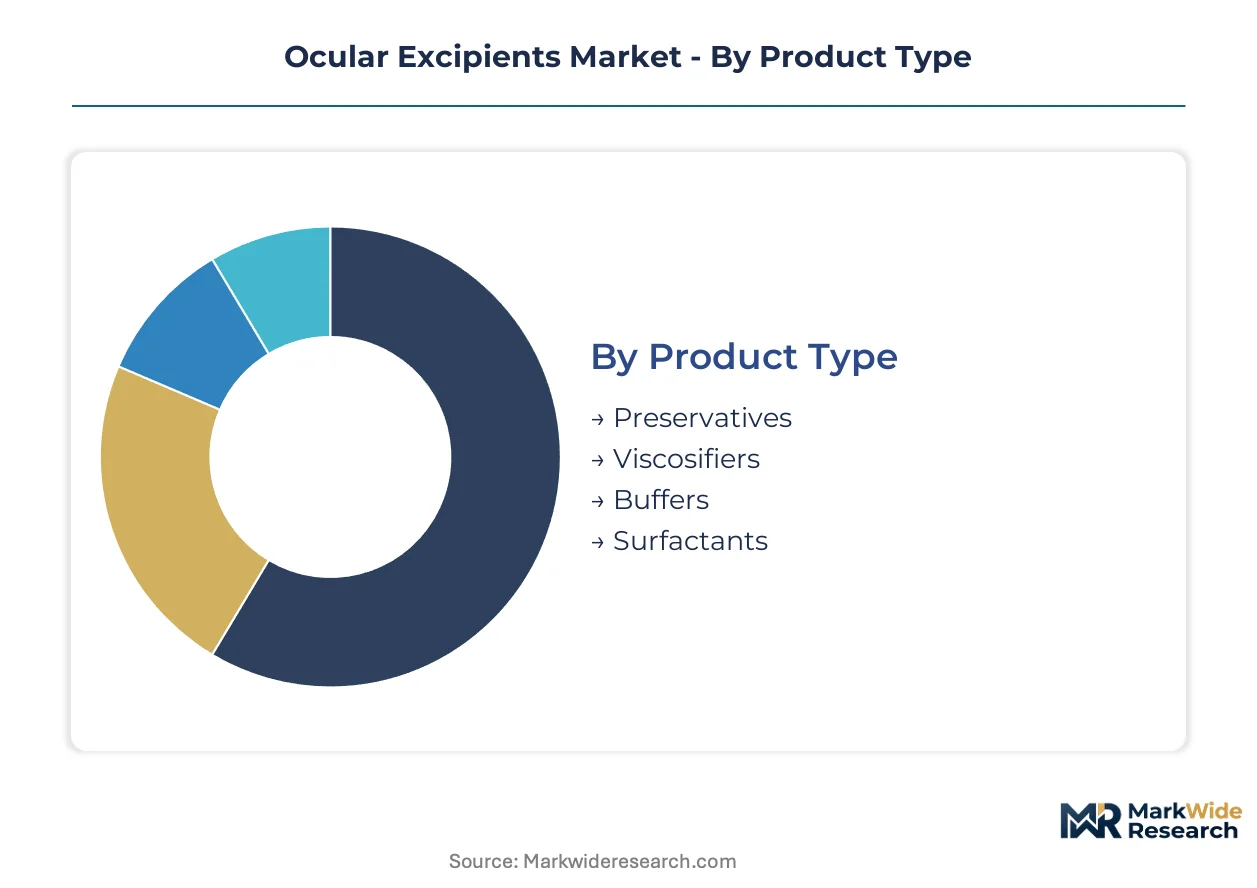
Segmentation in ocular excipients reveals how formulation requirements diverge across delivery modalities and therapeutic categories. Preservative-free unit-dose systems demand entirely different excipient architectures than multidose preserved formulations, while posterior segment implants require specialized surfactant chemistries incompatible with anterior surface applications.
Product Type:
Integration depth varies sharply: preservatives and buffers function as standalone formulation components with direct regulatory scrutiny, while viscosifiers and surfactants embed within complex delivery matrices where their performance depends on synergistic interactions with active pharmaceutical ingredients.
- Preservatives:Benzalkonium chloride alternatives including stabilized oxychloro complex and polyquaternium compounds dominate multidose ophthalmic solutions. Demand concentrates in Japan's presbyopia and glaucoma therapy segments where aging demographics expand the addressable patient base for preserved formulations requiring extended shelf stability.
- Viscosifiers:Carbomer and hyaluronic acid derivatives extend ocular surface residence time in gel-form applications. German and United States manufacturers command premium positioning for endotoxin-compliant grades below 0.5 EU per milliliter, though animal-derived hyaluronic acid sourcing faces tightening purity constraints.
- Buffers:Phosphate and citrate systems maintain pH stability across ophthalmic formulations.
- Surfactants:Lipid-based nanocarrier formulations for posterior segment drug delivery drive specialized demand.
Volume placements concentrate in preservatives; the faster expansion belongs to surfactants.
Application:
Cost tier differentiation separates commodity anterior surface formulations from premium posterior segment systems requiring specialized endotoxin controls and sterility assurance investments.
- Ophthalmic Solutions:Multidose preserved formulations for glaucoma and anti-inflammatory therapies constitute the foundational revenue layer. United States contract manufacturers consolidate supplier bases to secure excipient traceability for these high-volume products.
- Eye Drops:Unit-dose preservative-free formats command formulation premiums in dry eye therapies. Blow-fill-seal packaging lines displace multidose bottles, creating demand for non-preserved excipient systems with extended stability profiles.
- Ocular Gels:Bioadhesive platforms extend residence time through carbomer and cellulose derivatives.
- Contact Lens Solutions:Multipurpose formulations balance antimicrobial efficacy with corneal biocompatibility.
Revenue weight sits with ophthalmic solutions; ocular gels are climbing the fastest.
Form:
Supply concentration patterns align with manufacturing infrastructure requirements: liquid and gel forms demand aseptic processing capabilities, while powder and emulsion formats tolerate alternative sterilization modalities.
- Liquid:Aqueous formulations dominate multidose and unit-dose ophthalmic delivery. FDA Current Good Manufacturing Practice inspections and drug master file reviews enforce stringent endotoxin limits across United States manufacturing facilities.
- Gel:Viscoelastic systems combine prolonged residence with controlled release kinetics. Germany's chemical hubs concentrate carbomer production, exposing formulators to input cost volatility from energy-intensive polymer synthesis.
- Powder:Lyophilized formats serve specialized intraocular preparations.
- Emulsion:Lipid-based carriers enable poorly soluble active pharmaceutical ingredient delivery.
Manufacturing throughput centers on liquid; emulsion formats gain share fastest.
End User:
Customer type determines procurement sophistication: hospital systems demand integrated regulatory documentation packages, while retail pharmacies prioritize cost efficiency and supply security.
- Hospitals:Surgical and intraocular preparation requirements drive premium excipient specifications. Japan's PMDA mandates JIS-compliant sterility assurance levels, forcing suppliers to install laser diffraction analytical equipment and revalidate batch release protocols.
- Clinics:Outpatient ophthalmology practices favor convenient multidose formulations with established safety profiles.
- Pharmacies:Retail distribution channels serve chronic therapy categories including dry eye and allergy management.
- Research Laboratories:Novel excipient qualification timelines stretch 18-24 months as FDA drug master file reviewers scrutinize impurity profile data.
Procurement volume aggregates in hospitals; research laboratories show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Carbomer synthesis clusters in Ludwigshafen and Mannheim anchor European supply for viscosifier-grade polymers, while lipid nanoparticle expertise concentrates in Darmstadt and Tokyo pharmaceutical corridors. These chemical hubs shape input cost structures for formulators worldwide.
United States
Massachusetts and North Carolina CDMO clusters serve the presbyopia correction pipeline with consolidated supplier bases. FDA Current Good Manufacturing Practice inspections enforce endotoxin limits below 0.5 EU per milliliter across ophthalmic excipient facilities. Greater Boston contract manufacturers now require excipient master file cross-referencing and dedicated inventory buffers as standard procurement conditions.
Germany
Glaucoma therapy expansion and sustained-release implant demand pull specialized surfactant volumes through Rhine-Main chemical corridors. EMA REACH and MDR frameworks impose biocompatibility testing obligations that accelerate supplier consolidation toward certified producers. Ludwigshafen polymer synthesis operations expose formulators to energy-intensive production cost volatility.
Japan
Aging demographics expand the addressable patient base for multidose preserved formulations requiring benzalkonium chloride alternatives. PMDA mandates JIS Z 8801-compliant particle size specifications for imported excipients used in intraocular preparations. Tokyo-Osaka pharmaceutical corridors force European and North American suppliers to install laser diffraction analytical equipment and revalidate batch release protocols.
India
Contract manufacturing expansion for generic ophthalmic drug producers creates entry points for certified excipient suppliers. CDSCO streamlined import pathways reduce regulatory friction for ophthalmic-grade materials. Maharashtra and Gujarat pharmaceutical clusters are integrating non-preserved excipient systems for blow-fill-seal packaging lines serving dry eye therapies.
Switzerland
Swissmedic oversight of intraocular-grade materials maintains premium positioning for endotoxin-compliant viscosifier supply. Basel pharmaceutical corridor demand centers on silicone oil viscoelastic convergence for cataract surgery equipment manufacturers. Swiss suppliers command dual-function excipient niches combining vitreous substitution with endothelial protection.
Ocular Excipients Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue lipid nanoparticle specialization and preservative-free formulation architectures. The supplier base compresses toward certified manufacturers with dedicated bioprocessing infrastructure as regulatory tightening on endotoxin purity eliminates marginal participants. Three archetypes dominate: diversified chemical conglomerates with pharma-grade certification, specialized excipient houses with ophthalmic application laboratories, and contract manufacturing organizations with captive excipient supply. Competitive moves concentrate on strategic partnerships for regulatory documentation packages and capacity expansion in ISO 5 cleanroom environments.
Within the diversified chemical tier, BASF and Evonik anchor European supply for polymer and lipid-based delivery systems. Evonik occupies a position exemplifying controlled-release expertise for glaucoma implant applications. Millipore Sigma represents the North American distribution archetype through pharma-grade purity certifications and dedicated bioprocessing channels. These three entities sit within distinct competitive vectors: feedstock integration, formulation science specialization, and regulatory documentation depth.
| Leading Market Players |
|---|
| BASF |
| Evonik |
| Innophos |
| JRS Pharma |
| Beneo |
| Fuji Chemical Industries USA, Inc. |
| Mallinckrodt Pharmaceuticals |
| Millipore Sigma |
| Anton Paar |
| Others |
Value Network & Pricing Analysis
Lipid nanoparticle formulation technology is displacing conventional surfactant chemistries, simultaneously elevating R&D amortization costs for suppliers and compressing margins for non-certified manufacturers lacking dedicated bioprocessing infrastructure. This production-method transition concentrates pricing power with European and Japanese producers possessing integrated quality systems and regulatory documentation depth.
Pricing Analysis
Warranty and service bundling separates premium-tier suppliers from commodity producers, with certified manufacturers offering integrated regulatory documentation packages and dedicated inventory buffers commanding substantial premia. Three-tier pricing structure across pharma-certified, technical-grade, and economy levels reflects endotoxin compliance thresholds and master file availability. Pricing pressure stems from preservative substitution economics, where stabilized oxychloro complex alternatives run 40-60% above legacy benzalkonium chloride. Generic ophthalmic drug manufacturers exhibit highest price sensitivity; implant manufacturers prioritize traceability over unit cost.
Supply Chain Analysis
Reverse-logistics flows remain minimal for ocular excipients given sterility requirements, though batch rejection protocols and requalification cycles create indirect cost burdens for non-compliant shipments. Carbomer synthesis clusters in Germany, hyaluronic acid sourcing draws from animal-derived supply chains in Europe and Asia, and lipid nanoparticle expertise concentrates in Japan. Raw material dependencies include petroleum-derived polymers, animal-derived glycosaminoglycans, and specialized phospholipids. Single-source vulnerability runs through European polymer hubs exposed to energy cost volatility. Distribution runs through pharma-grade distributors with cold-chain capabilities and regulatory documentation management.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ocular excipients sector sits in a formulation-architecture transition, with preservative-free unit-dose systems and lipid-based nanocarriers replacing multidose preserved formulations in chronic therapy categories.
For Market Incumbents: Extend certification portfolios to capture preservative-free formulation demand, adding ISO 5 cleanroom capacity in Massachusetts and North Carolina CDMO corridors. Defensive consolidation around lipid nanoparticle expertise protects against specialized chemical entrants. Backward integration into endotoxin-controlled raw material sourcing secures margin position as hyaluronic acid purity standards tighten.
For New Entrants and Emerging Players: Contract manufacturing organizations in India offer the most penetrable channel partnership pathway, with CDSCO streamlined import pathways reducing regulatory friction for certified suppliers. White-space targets include silicone oil viscoelastic convergence for cataract surgery equipment manufacturers and blow-fill-seal packaging line integration for dry eye therapies. Go-to-market positioning should emphasize JIS-compliant particle size specifications for Japan's intraocular preparation segment.
For Investors and Strategic Acquirers: Re-rating potential sits with specialized excipient houses possessing ophthalmic application laboratories given EMA biocompatibility testing obligations and FDA drug master file review complexity. Long-term viability over the next decade favors producers with captive bioprocessing infrastructure and integrated regulatory documentation capabilities. Monitor pharmacopeial harmonization progress between USP, EP, and JP monographs as an inflection indicator for formulation reformulation cost cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| ISO 5 Cleanroom Capacity Expansion | Enables aseptic excipient finishing for intraocular-grade segments requiring sterility assurance investments. |
| Backward Integration into Polymer Synthesis | Secures carbomer supply against Ludwigshafen energy cost volatility and European hub concentration risk. |
| JIS Z 8801 Compliance Investment | Unlocks Japan's PMDA-mandated particle size specifications for intraocular preparation excipient supply. |
| Preservative-Free Formulation Development | Captures blow-fill-seal packaging line demand in dry eye therapies displacing multidose bottles. |
| Lipid Nanoparticle Expertise Acquisition | Consolidates controlled-release excipient positioning for posterior segment glaucoma implant applications. |
Research Methodology
Document review covered FDA drug master file submissions, EMA REACH compliance registrations, and PMDA JIS standard notifications, complemented by interviews with formulation scientists at contract ophthalmic drug manufacturers, regulatory affairs specialists, and procurement managers at hospital systems. Secondary validation drew from USP monograph updates, EP certification databases, and JP pharmacopeial harmonization working papers. Bottom-up excipient volume modeling triangulated against top-down pharmaceutical formulation demand projections.
Segmented outputs across product type, application, form, and end user dimensions were generated through the projection horizon, with therapeutic category splits for glaucoma, dry eye, and presbyopia segments incorporated. CAGRs were derived from regression analysis of historical excipient pricing and volume trajectories, adjusted for regulatory tightening effects on supplier consolidation. Forecast inputs included endotoxin limit enforcement timelines, cleanroom capacity expansion pipelines, and pharmacopeial harmonization negotiation status.
Several conditions sit outside the modeled scope, including unforeseen regulatory reciprocity agreements, breakthrough non-polymeric delivery technologies, and macroeconomic disruptions to European energy inputs. Forecasts reflect documented assumptions about certification timeline stability and buyer consolidation patterns. Practitioners should monitor EMA MDR enforcement intensity and FDA inspection backlog clearance for early signals of supplier base compression acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Injectable Cytotoxic Drugs Market
Pharmaceuticals
Global Benzodiazepines Market
Pharmaceuticals
Anti-Arrhythmic Drugs Market
Pharmaceuticals
Global Ovulation Inducing Drugs Market
Pharmaceuticals
Prothrombin Complex Concentrate (PCC) Market
Pharmaceuticals
Middle-East and Africa Meglitinide Market
Pharmaceuticals
Global Pharmacy Benefit Management (PBM) Market
Pharmaceuticals
API Contract Manufacturing Market
Pharmaceuticals
Global Parkinson's Disease Drugs Market
Pharmaceuticals
Motilium Market
Pharmaceuticals
Amylin Analogs Market
Pharmaceuticals
Radioligand Therapy (RLT) Market
Pharmaceuticals
Vutrisiran Market
Pharmaceuticals
Smoking Cessation Drugs Market
Pharmaceuticals
Dyslipidemia Therapeutics Market
Pharmaceuticals
Rupatadine Fumarate API Market