
 Josamycin Market | 2026-2036
Josamycin Market Size, Share, and Industry Trends Forecast 2026-2036
Josamycin Market Insights
Hospital procurement channels across East Asia are reconfiguring as centralized tendering systems consolidate antibiotic purchasing volumes. Tosun Pharm leverages its manufacturing scale to anchor supply contracts with provincial health authorities. Guilin Pharma competes through backward integration into fermentation-based active pharmaceutical ingredient production. BioChemPartner specializes in export registrations for emerging markets, extending its geographic footprint beyond domestic boundaries.
Josamycin is a 16-membered macrolide antibiotic produced via Streptomyces narbonensis fermentation, characterized by a C-3 mycarosyl moiety that confers acid stability and distinct pharmacokinetic properties compared to 14-membered macrolides; it functions primarily as a protein synthesis inhibitor targeting bacterial 50S ribosomal subunits for respiratory and soft-tissue infections. Tablet formulations dominate volume due to established oral bioavailability and outpatient prescribing patterns, while injectable delivery modes capture premium positioning in severe inpatient bacterial infections. Research laboratories represent a faster-growing end-user channel as antimicrobial resistance surveillance programs expand reference testing requirements.
China's NMPA maintains bioequivalence standards for generic macrolide approvals, while the WHO prequalification program shapes export eligibility for manufacturers targeting low-income country tenders. India's CDSCO enforces parallel import testing protocols that filter substandard antibiotic shipments. Stakeholders must monitor evolving antimicrobial stewardship regulations that restrict empirical macrolide prescribing in hospital settings.
Market Dynamics
Hospital procurement consolidation across East Asia is compressing supplier margins while amplifying volume concentration effects for macrolide manufacturers with proven bioequivalence documentation.
Growth Catalysts
- Centralized tendering expansion:Provincial health authorities in China are aggregating antibiotic purchases through unified procurement platforms, favoring suppliers with fermentation scale.
- WHO prequalification alignment:Export-oriented manufacturers are restructuring quality management systems to access low-income country tenders requiring international certification standards.
- Antimicrobial resistance surveillance:Reference laboratories in Japan and South Korea are expanding susceptibility testing panels, creating sustained demand for characterized reference compounds.
Market Restraints
- Fermentation input volatility:Soybean meal and corn steep liquor prices fluctuate with agricultural commodity cycles, squeezing margin predictability for bulk API producers.
- Single-region supply concentration:Jiangsu and Zhejiang provinces host disproportionate fermentation capacity, creating geographic vulnerability to environmental compliance shutdowns.
- Macrolide substitution pressure:Fluoroquinolones and beta-lactam alternatives compete for empirical respiratory infection prescribing in outpatient settings.
Strategic Opportunities
- Vietnam procurement liberalization:Decentralized hospital purchasing creates entry points for mid-tier suppliers excluded from China's centralized tenders.
- Injectable formulation premiumization:Severe inpatient infection protocols favor IV delivery modes with higher per-dose economics than oral tablets.
- Dual carbon compliance incentives:China's MEE environmental credits reward fermentation facilities adopting anaerobic digestion for waste stream valorization.
Industry Challenges
- Bioequivalence study capacity:Qualified clinical pharmacology units for macrolide crossover trials remain scarce relative to generic filing volumes.
- Fermentation specialist retention:Streptomyces strain optimization requires tacit knowledge that exits with retiring process engineers at established API houses.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Josamycin Market |
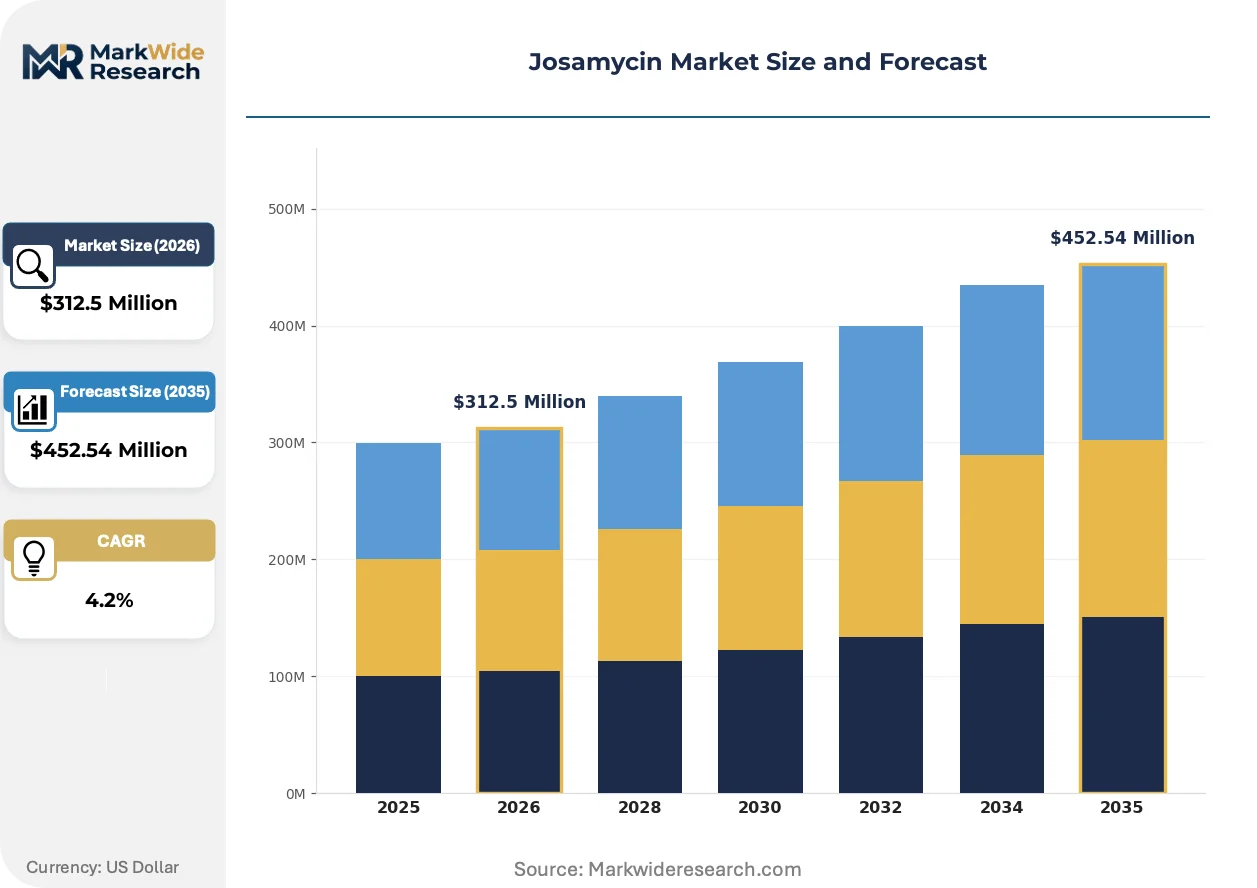
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $452.54 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablets, Capsules, Injectable, Suspension Application: Infectious Diseases, Bacterial Infections, Respiratory Issues, Skin Conditions End User: Hospitals, Clinics, Pharmacies, Research Laboratories Delivery Mode: Oral, Intravenous, Intramuscular, Topical |
| Companies Covered | BioChemPartner, Tosun Pharm, Guilin Pharma, CSPC, Guanghua Pharma, SINE, Minsheng Pharma, SAJA Pharma, Dragon Pharm, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Josamycin Market Trends and Innovations
Continuous processing technologies and regulatory data harmonization are compressing development timelines while reshaping competitive entry barriers for generic macrolide producers.
Single-use bioreactor systems for Streptomyces cultivation are rendering obsolete stainless steel fermentation trains that require lengthy CIP/SIP validation cycles. Mid-scale API manufacturers in South Korea are adopting disposable vessels for clinical batch production, cutting facility turnaround from weeks to days. This shift is rendering obsolete the capital-intensive fixed-asset model that protected incumbent producers with depreciated infrastructure.
China's NMPA bioequivalence waiver pathways for highly variable drugs are tightening documentation requirements for macrolide pharmacokinetic studies. The regulation now mandates reference-scaled average bioequivalence for compounds with within-subject variability exceeding 30 percent. Generic filers are responding by contracting specialized CROs with established positive control data for 16-membered macrolides.
Research laboratories are consolidating antimicrobial susceptibility testing contracts through multi-year framework agreements with preferred suppliers. This behavior shift displaces spot purchasing of reference powders by individual hospital microbiology departments. The pattern is most visible in Japan's prefectural reference centers, where METI-funded AMR surveillance networks centralize reagent procurement.
Josamycin Market Segmentation
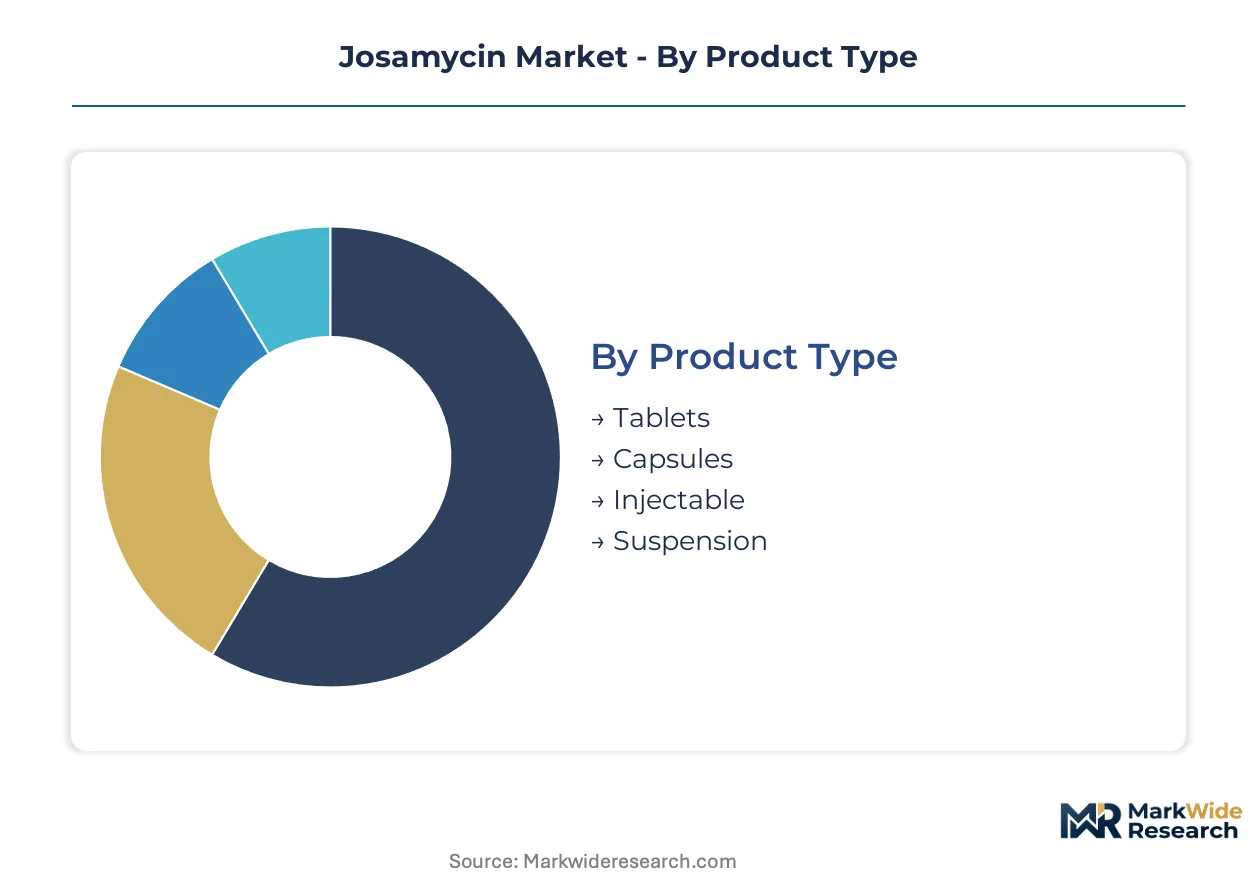
Josamycin market segmentation reveals how formulation chemistry, clinical application, and procurement channel each reshape competitive access. Manufacturers align production assets against these dimensions to defend position in tender-driven procurement environments.
Product Type:
Mature oral solid formats dominate prescription volumes while emerging injectable lines capture inpatient premium economics.
- Tablets:Film-coated compressed dosage forms containing josamycin propionate ester deliver acid-stable pharmacokinetics for outpatient respiratory protocols. Jiangsu province tablet manufacturers anchor hospital formulary contracts through bioequivalence dossiers filed with China's NMPA.
- Injectable:Lyophilized powder for reconstitution enables IV infusion in severe bacterial pneumonia where oral bioavailability is compromised. Tertiary hospitals in Japan's prefectural centers drive demand through empirical sepsis protocols requiring rapid therapeutic plasma levels.
- Capsules:Hard gelatin shells containing micronized API serve pediatric and geriatric populations with swallowing difficulties.
- Suspension:Reconstitutable powder for oral liquid administration addresses weight-based dosing requirements in pediatric otitis media.
Tablets retain volume leadership; injectable holds the steepest expansion curve.
Application:
Cost tier stratification separates high-frequency outpatient prescribing from specialized inpatient indications requiring diagnostic confirmation.
- Respiratory Issues:Community-acquired pneumonia and atypical mycoplasma infections constitute the primary outpatient indication where macrolide monotherapy remains first-line. Zhejiang province manufacturing clusters supply bulk API for domestic tablet production targeting this high-volume segment.
- Bacterial Infections:Soft-tissue and skin structure infections drive empirical prescribing in emergency departments where streptococcal coverage is required. South Korean tertiary hospitals favor josamycin over fluoroquinolones for MRSA-negative cellulitis per MFDS antimicrobial stewardship guidelines.
- Infectious Diseases:Mycobacterial and atypical pathogen protocols in reference laboratories create demand for characterized reference standards.
- Skin Conditions:Acne vulgaris and rosacea off-label prescribing generates pharmacy channel volume in dermatology clinics.
Respiratory applications command the largest prescription base; bacterial infection protocols are expanding most quickly in hospital settings.
End User:
Customer type concentration determines margin structure, with centralized hospital procurement compressing prices while fragmented retail pharmacy sustaining premium positioning.
- Hospitals:Inpatient antibiotic stewardship committees govern empirical macrolide use through restricted formularies. China's provincial centralized tendering platforms aggregate purchasing volume, favoring suppliers with fermentation scale and documented bioequivalence.
- Research Laboratories:AMR surveillance networks in Japan's prefectural reference centers procure characterized reference powders for susceptibility testing panels. METI-funded programs consolidate multi-year framework agreements displacing spot purchasing.
- Clinics:Outpatient respiratory and dermatology practices generate tablet prescriptions reimbursed through national health insurance schemes.
- Pharmacies:Community retail channels capture self-pay demand for topical and oral formulations in markets with partial prescription enforcement.
Hospitals anchor procurement volume; research laboratories are gaining share fastest through surveillance program expansion.
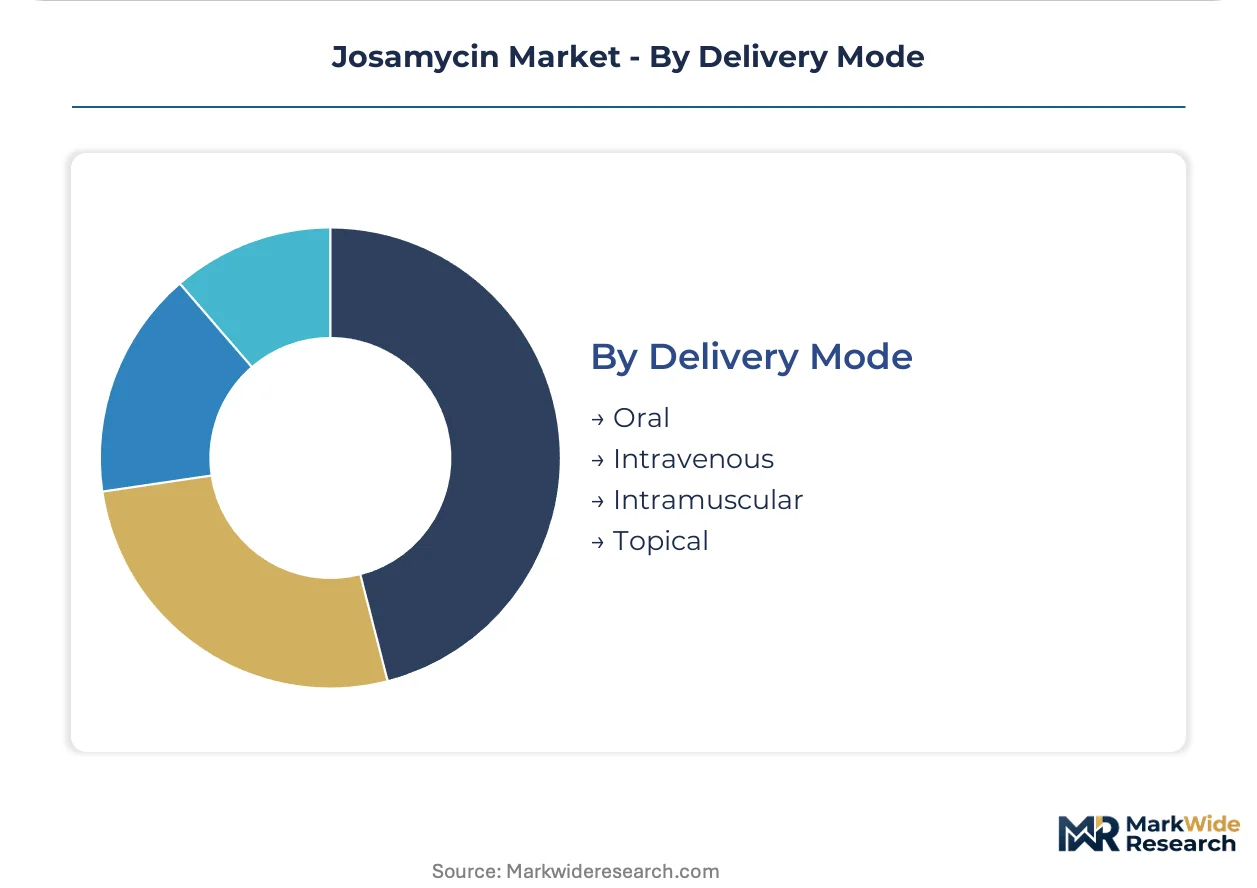
Delivery Mode:
Supply concentration in fermentation-based API production links delivery mode economics to manufacturing geography and environmental compliance exposure.
- Oral:Tablet and suspension formulations leverage established gastric acid stability of the 16-membered macrolide scaffold. Outpatient prescribing patterns in China's eastern provinces sustain volume through pharmacy reimbursement tiers.
- Intravenous:IV infusion protocols in intensive care units require sterile manufacturing capabilities with higher regulatory burden. South Korean manufacturers deploy single-use bioreactor systems to shorten batch turnaround for clinical trial material.
- Intramuscular:Depot injection formulations serve settings with limited IV infrastructure.
- Topical:Cream and gel preparations address localized skin infections with reduced systemic exposure.
Oral delivery retains prescription dominance; intravenous modes are climbing the fastest through inpatient protocol adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Shanghai Yangshan deep-water port anchors East Asian pharmaceutical logistics, enabling just-in-time API shipments to formulation plants across the region. This maritime infrastructure underwrites the geographic concentration of macrolide manufacturing.
China
Jiangsu and Zhejiang provinces host fermentation clusters supplying bulk josamycin API to domestic tablet manufacturers. NMPA bioequivalence waivers for highly variable drugs tighten documentation requirements for generic filers. Taizhou's pharmaceutical industrial park consolidates environmental compliance infrastructure for multiple fermentation facilities.
Japan
Prefectural reference laboratories in Kanto and Kansai regions drive demand for characterized reference powders under METI-funded AMR surveillance networks. PMDA antimicrobial stewardship guidelines restrict empirical macrolide prescribing in tertiary hospitals. Osaka-based research consortia centralize multi-year framework agreements for susceptibility testing reagents.
South Korea
Tertiary hospitals in Seoul Capital Area favor josamycin over fluoroquinolones for MRSA-negative cellulitis per MFDS stewardship protocols. Single-use bioreactor adoption shortens batch turnaround for clinical trial material production. Busan-Ulsan pharmaceutical belt houses sterile manufacturing capabilities for IV formulations.
Vietnam
Decentralized hospital purchasing creates procurement entry points for mid-tier suppliers excluded from China's centralized tenders. The Ministry of Health's national drug procurement reforms gradually consolidate antibiotic purchasing volumes. Ho Chi Minh City pharmaceutical distributors expand cold-chain infrastructure for temperature-sensitive injectable products.
India
CDSCO parallel import testing protocols filter substandard antibiotic shipments entering through Mumbai and Chennai ports. Domestic manufacturers pursue WHO prequalification to access low-income country tenders. Hyderabad's active pharmaceutical ingredient cluster develops fermentation capabilities for macrolide intermediates.
Josamycin Market Competitive Landscape
On the supply side, the industry is consolidating around fermentation-scale manufacturers with documented bioequivalence dossiers. Provincial tendering platforms in China aggregate purchasing volume, compressing margins for suppliers lacking backward integration into API production. Three archetypes dominate: state-affiliated pharmaceutical groups with captive fermentation capacity, export-oriented specialists with WHO prequalification alignment, and regional formulators serving decentralized procurement channels. Capacity expansion and strategic partnerships with clinical pharmacology units represent the dominant competitive moves.
Among Chinese pharmaceutical groups, Tosun Pharm, Guilin Pharma, and BioChemPartner occupy distinct positions within the supplier hierarchy. Tosun Pharm anchors supply contracts through manufacturing scale and provincial health authority relationships. Guilin Pharma exemplifies backward integration into fermentation-based API production. BioChemPartner represents the export-registration specialist archetype, extending geographic reach beyond domestic boundaries through emerging market tender participation.
| Leading Market Players |
|---|
| BioChemPartner |
| Tosun Pharm |
| Guilin Pharma |
| CSPC |
| Guanghua Pharma |
| SINE |
| Minsheng Pharma |
| SAJA Pharma |
| Dragon Pharm |
| Others |
Pricing and Supply Chain Analysis
Fermentation input volatility determines both the spread between API and formulation pricing tiers and the geographic clustering of manufacturing assets. Soybean meal and corn steep liquor price cycles squeeze margin predictability for bulk producers while rewarding backward-integrated suppliers with captive fermentation capacity.
Pricing Analysis
Volume-discount tiering structures separate WHO-prequalified export grades from domestic bioequivalence-tier products and unregistered economy formulations. Price differentiation hinges on NMPA bioequivalence dossier completeness and fermentation scale economies. Cost compression in the economy tier intensifies as provincial tendering platforms aggregate purchasing volumes. Hospital procurement committees exhibit lowest price sensitivity for IV formulations in sepsis protocols, while retail pharmacy channels drive tablet price competition.
Supply Chain Analysis
Export-control regimes for dual-use fermentation technology limit technology transfer to emerging API producers outside established manufacturing clusters. Supply concentrates in China's Jiangsu and Zhejiang provinces, with secondary fermentation capacity in South Korea's Busan-Ulsan belt. Raw material dependencies include pharmaceutical-grade soybean meal, corn steep liquor, and specialized Streptomyces culture media. Single-region concentration creates vulnerability to MEE environmental compliance shutdowns. Distribution runs through Shanghai Yangshan port logistics to formulation plants across East Asia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Centralized tendering expansion constitutes a regulatory inflection that disrupts legacy supplier relationships and rewards manufacturing scale with provincial health authorities.
For Market Incumbents: Entrench position through backward integration into fermentation-based API production and multi-year framework agreements with reference laboratories. Counter macrolide substitution pressure by anchoring hospital formulary contracts with documented bioequivalence dossiers. Prioritize strain optimization knowledge retention as retiring process engineers exit established API houses. For New Entrants and Emerging Players: Pursue Vietnam's decentralized hospital purchasing channels where mid-tier suppliers excluded from China's centralized tenders gain procurement access. Target injectable formulation segments in tertiary hospitals where IV delivery commands premium economics. Enter through specialized CRO partnerships for macrolide crossover trial capacity. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors fermentation-scale manufacturers with documented bioequivalence dossiers. Long-term viability rests on environmental compliance infrastructure and WHO prequalification alignment. Watch for MEE environmental credit policy shifts as inflection indicators for facility valuation.| Strategic Initiative | Industry Significance |
|---|---|
| Fermentation Capacity Expansion | Captive API production insulates margin from agricultural commodity input volatility. |
| Bioequivalence Dossier Investment | NMPA filing completeness determines eligibility for provincial centralized tender participation. |
| WHO Prequalification Alignment | Quality management system restructuring unlocks low-income country tender access. |
| Single-Use Bioreactor Adoption | Disposable vessel systems compress clinical batch turnaround from weeks to days. |
| Reference Laboratory Framework Agreements | METI-funded AMR surveillance networks consolidate multi-year reagent procurement. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across hospital procurement managers, regulatory affairs leads at API manufacturers, formulary directors in tertiary hospitals, and fermentation process engineers. Secondary validation drew from NMPA bioequivalence filings, MFDS antimicrobial stewardship guidelines, METI AMR surveillance program disclosures, and customs trade data for macrolide API shipments. Bottom-up prescription volume modeling triangulated against top-down fermentation capacity assessments.
Calibration against historical tender award data and provincial procurement platform disclosures anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include formulation type, delivery mode, end-user channel, and regional regulatory cluster. CAGRs derived from volume trajectory analysis incorporating antimicrobial resistance surveillance program expansion rates and hospital stewardship protocol adoption curves.
Macroeconomic conditions sit as an overlay; deviation in agricultural commodity prices or environmental enforcement intensity would shift the trajectory. Forecasts reflect documented assumptions about tendering platform consolidation pace and bioequivalence study capacity expansion. Material shifts in NMPA bioequivalence waiver pathways or MEE environmental credit policy would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Vaccine Market
Pharmaceuticals
Congestive Heart Failure Drugs Market
Pharmaceuticals
3D Printing Drug Market
Pharmaceuticals
Propofol Market
Pharmaceuticals
Global Pharmacy Benefit Management (PBM) Market
Pharmaceuticals
Ocular Excipients Market
Pharmaceuticals
Musculoskeletal Disorders Drugs Market
Pharmaceuticals
Asia-Pacific Biguanide Market
Pharmaceuticals
Sympathoimemetic Agents Market
Pharmaceuticals
Complex Injectable Market
Pharmaceuticals
Anti-Platelet Agents Market
Pharmaceuticals
Intranasal Corticosteroids Market
Pharmaceuticals
Live Vaccines Market
Pharmaceuticals
Guaifenesin Market
Pharmaceuticals
Africa Generic Pharmaceutical Market
Pharmaceuticals
Compound Diclofenac Sodium and Chlorphenamine Maleate Tablets Market