
 Molecular Sieves Market | 2026-2036
Molecular Sieves Market Size, Share, and Industry Trends Forecast 2026-2036
Molecular Sieves Market Intelligence
Direct supply from zeolite manufacturers to petrochemical complexes is fragmenting as regional distributors gain leverage in Asia-Pacific procurement. Tosoh Corporation dominates synthetic zeolite production through captive alumina-silicate refining in Japan. Clariant differentiates via specialized catalyst-grade molecular sieves for European polymer plants. BASF SE leverages backward integration into petrochemical feedstocks to control sieve pricing for captive consumption.
Molecular sieves are crystalline metal-aluminosilicates with uniform pore diameters typically ranging from 3 to 10 angstroms, manufactured through hydrothermal crystallization of sodium aluminate and sodium silicate gels; they function as selective adsorbents that separate molecules based on kinetic diameter and polarity. Zeolite products anchor revenue pools due to established demand in refinery catalytic cracking and natural gas dehydration. Pressure Swing Adsorption technology leads unit deployment for hydrogen purification and medical oxygen concentration. Membrane configurations represent the fastest-expanding product category as polymer-zeolite composites displace conventional packed beds in nitrogen generation.
EPA New Source Performance Standards mandate volatile organic compound capture above threshold throughput rates, directly expanding activated carbon and zeolite adsorber installations. REACH registration requirements in Europe restrict certain binder chemistries in sieve formulations, pushing Arkema and Axens toward bio-based aluminosilicate precursors. China's MEE enforces stricter benzene emissions limits at petrochemical facilities, accelerating domestic zeolite replacement cycles. Stakeholders must monitor evolving carbon border adjustment mechanisms that could restructure competitive cost positions between imported and locally manufactured sieve systems.
Market Dynamics
Pressure Swing Adsorption technology is compressing unit economics for hydrogen purification, forcing incumbent packed-bed suppliers to defend margin positions against membrane-zeolite composites that halve footprint requirements.
Growth Catalysts
- EPA New Source Performance Standards:Volatile organic compound capture mandates above threshold throughput rates directly expand activated carbon and zeolite adsorber installations at US petrochemical facilities.
- China's dual carbon goals:MEE enforcement of stricter benzene emissions limits accelerates domestic zeolite replacement cycles and adsorption capacity expansion.
- Polymer-zeolite composites:Membrane configurations displace conventional packed beds in nitrogen generation, creating pull-through demand for specialty aluminosilicate precursors.
Market Restraints
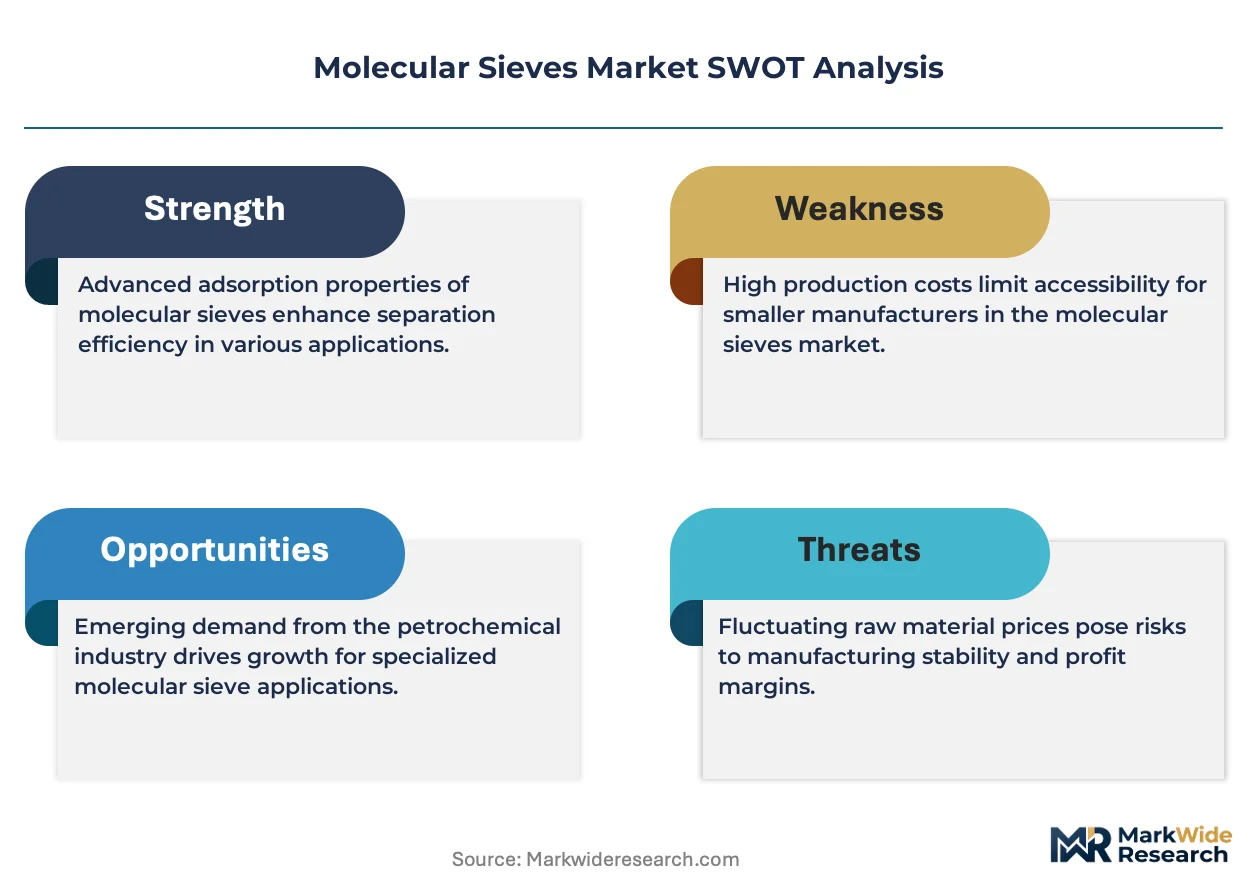
- Sodium aluminate input volatility:Energy-intensive refining of bauxite-derived alumina creates margin pressure for synthetic zeolite manufacturers without captive feedstock control.
- REACH registration friction:ECHA restrictions on certain binder chemistries in sieve formulations force reformulation cycles and delay product launches in European chemical corridors.
- Activated carbon substitution:Lower-cost carbon adsorbents capture solvent recovery applications where selectivity requirements permit, compressing addressable market for 3A and 4A zeolites.
Strategic Opportunities
- Medical oxygen concentration:PSA units for home healthcare and field hospitals represent underpenetrated demand as healthcare systems decentralize respiratory therapy infrastructure.
- Carbon border adjustment mechanisms:Emerging EU trade instruments could restructure competitive cost positions between imported and locally manufactured sieve systems.
- Bio-based aluminosilicate precursors:Arkema and Axens investments in renewable feedstock routes align with EU Green Deal procurement preferences for sustainable materials.
Industry Challenges
- Hydrothermal crystallization expertise:Specialized process engineering talent for controlled pore-size distribution remains concentrated among legacy Japanese and German manufacturers.
- Legacy packed-bed retrofit complexity:Polymer-zeolite membrane integration requires reconfiguration of valve timing, pressure cycling, and regeneration protocols in existing PSA skids.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Molecular Sieves Market |
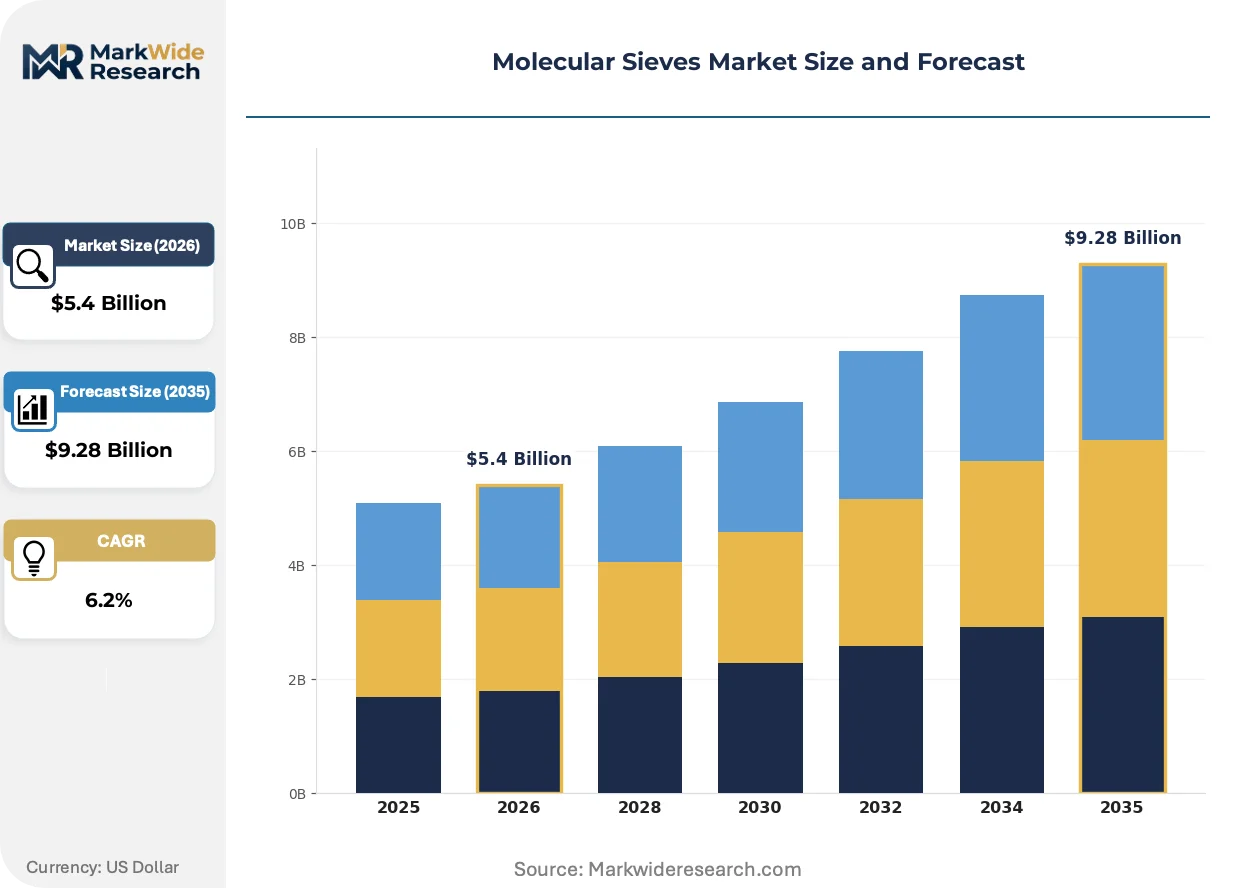
| Market Size in 2026 | $5.4 Billion |
| Market Size in 2035 | $9.28 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Zeolite, Activated Alumina, Membrane, Silica Gel Application: Gas Separation, Adsorption, Catalysis, Drying End User: Chemical Industry, Food & Beverage, Pharmaceuticals, Oil & Gas Technology: Pressure Swing Adsorption, Vacuum Swing Adsorption, Temperature Swing Adsorption, Cryogenic Separation |
| Companies Covered | W. R. Grace & Co., Tosoh Corporation, Honeywell International Inc, Clariant, Axens, Arkema, Zeochem AG, KNT Group, BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Molecular Sieves Market Strategic Shifts & Innovations
Digital twin modeling of adsorption kinetics is compressing pilot-to-production timelines, while regulatory tightening on emissions and material safety is redirecting R&D investment toward bio-based synthesis routes.
Polymer-zeolite composite membranes is virtualizing the separation layer in nitrogen generation and hydrogen purification units. Petrochemical operators in Germany's Ludwigshafen corridor are adopting these configurations to reduce skid footprint and energy consumption. The technology is virtualizing the traditional distinction between membrane and adsorption processes, enabling hybrid architectures that compress capital deployment timelines.
REACH registration requirements are restricting certain binder chemistries in molecular sieve formulations, pushing manufacturers toward bio-based aluminosilicate precursors. ECHA's evolving substance evaluation criteria extend compliance timelines for new product introductions. European polymer plants are responding by consolidating procurement around suppliers with established registration portfolios, concentrating purchasing power among fewer distributors.
Direct supply relationships between zeolite manufacturers and petrochemical complexes are fragmenting as regional distributors gain leverage in Asia-Pacific procurement. Procurement teams at Chinese and Southeast Asian refiners are consolidating volumes through trading houses that manage logistics and customs clearance. This pattern is most visible in ethylene purification adsorbent sourcing, where distributors now intermediate between Japanese synthetic zeolite producers and end-users.
Molecular Sieves Market Segmentation
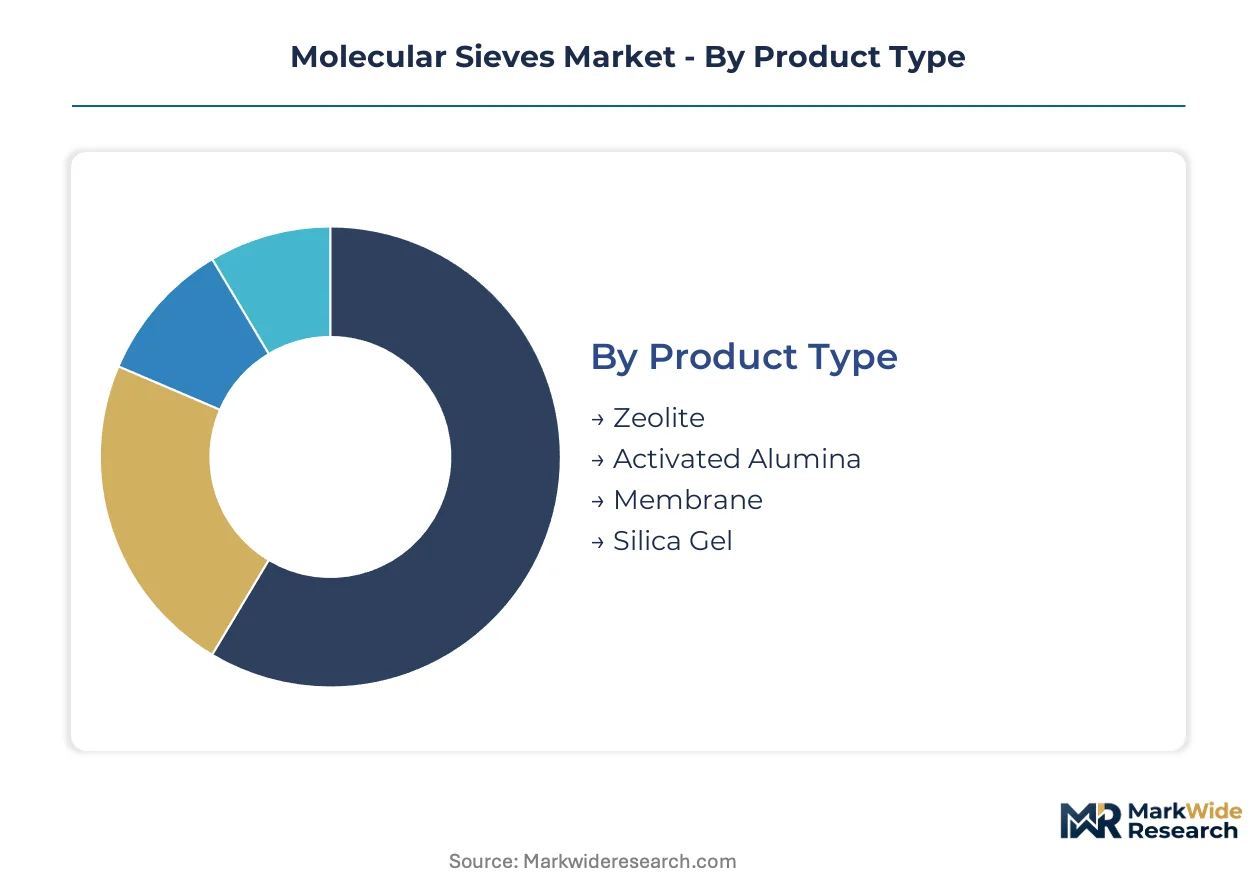
Molecular sieve procurement patterns diverge sharply across product chemistries and separation technologies, with petrochemical operators prioritizing thermal stability while food processors emphasize adsorbent purity certifications. Understanding these segment boundaries clarifies why pricing and supply channels vary by an order of magnitude between refinery catalytic cracking and medical oxygen concentration applications.
Product Type:
Zeolite formulations span synthetic and natural mineral bases, with pore architecture determining suitability for specific molecular kinetic diameters across industrial gas processing.
- Zeolite:Synthetic aluminosilicate crystals with tunable 3-10 angstrom pore apertures manufactured via hydrothermal crystallization. Demand concentrates in United States and China petrochemical corridors where ethylene purification and catalytic cracking operations require thermal regeneration cycles above 300°C.
- Membrane:Polymer-zeolite composite configurations that embed crystalline adsorbents within polyimide or polysulfone matrices. Germany's Ludwigshafen chemical cluster drives adoption for nitrogen generation skids where footprint reduction halves installation costs compared to conventional packed beds.
- Activated Alumina:High-surface-area aluminum oxide spheres deployed primarily for compressed air drying and fluoride removal in water treatment.
- Silica Gel:Amorphous silicon dioxide desiccants serving humidity control in pharmaceutical packaging and electronics manufacturing.
Established volume favors Zeolite; emerging adoption favors Membrane.
Application:
Functional deployment ranges from bulk commodity separation to precision catalysis, with margin profiles inversely correlated to process scale.
- Gas Separation:Selective adsorption of nitrogen from air or hydrogen from refinery off-gases using kinetic diameter discrimination. Pressure Swing Adsorption units at Chinese petrochemical facilities represent the dominant demand concentration as MEE benzene emission limits tighten.
- Adsorption:Contaminant removal from process streams and solvent recovery systems. EPA New Source Performance Standards in the United States mandate volatile organic compound capture above threshold throughput rates, directly expanding zeolite adsorber installations.
- Catalysis:Acid-site-mediated reactions in fluid catalytic cracking and hydrocracking operations.
- Drying:Moisture removal from refrigerants, insulating oils, and natural gas pipelines.
Adsorption commands the widest end-use dispersion; Gas Separation exhibits the steepest expansion trajectory.
End User:
Customer sophistication varies from multinational chemical conglomerates with captive engineering teams to regional food processors outsourcing technical specification.
- Oil & Gas:Upstream dehydration and downstream refinery operations requiring continuous regeneration capability. United States Gulf Coast refiners source synthetic zeolites through direct manufacturer relationships, while Chinese operators increasingly rely on regional distributors for logistics consolidation.
- Chemical Industry:Polymer production and specialty chemical synthesis demanding catalyst-grade sieves with controlled binder chemistries. REACH registration requirements in Europe restrict certain formulations, pushing procurement toward suppliers with established ECHA portfolios.
- Pharmaceuticals:API drying and packaging humidity control with stringent purity documentation.
- Food & Beverage:CO2 purification and ethanol dehydration for beverage carbonation and fuel additive production.
Oil & Gas anchors procurement volume; Pharmaceuticals commands premium pricing tiers.
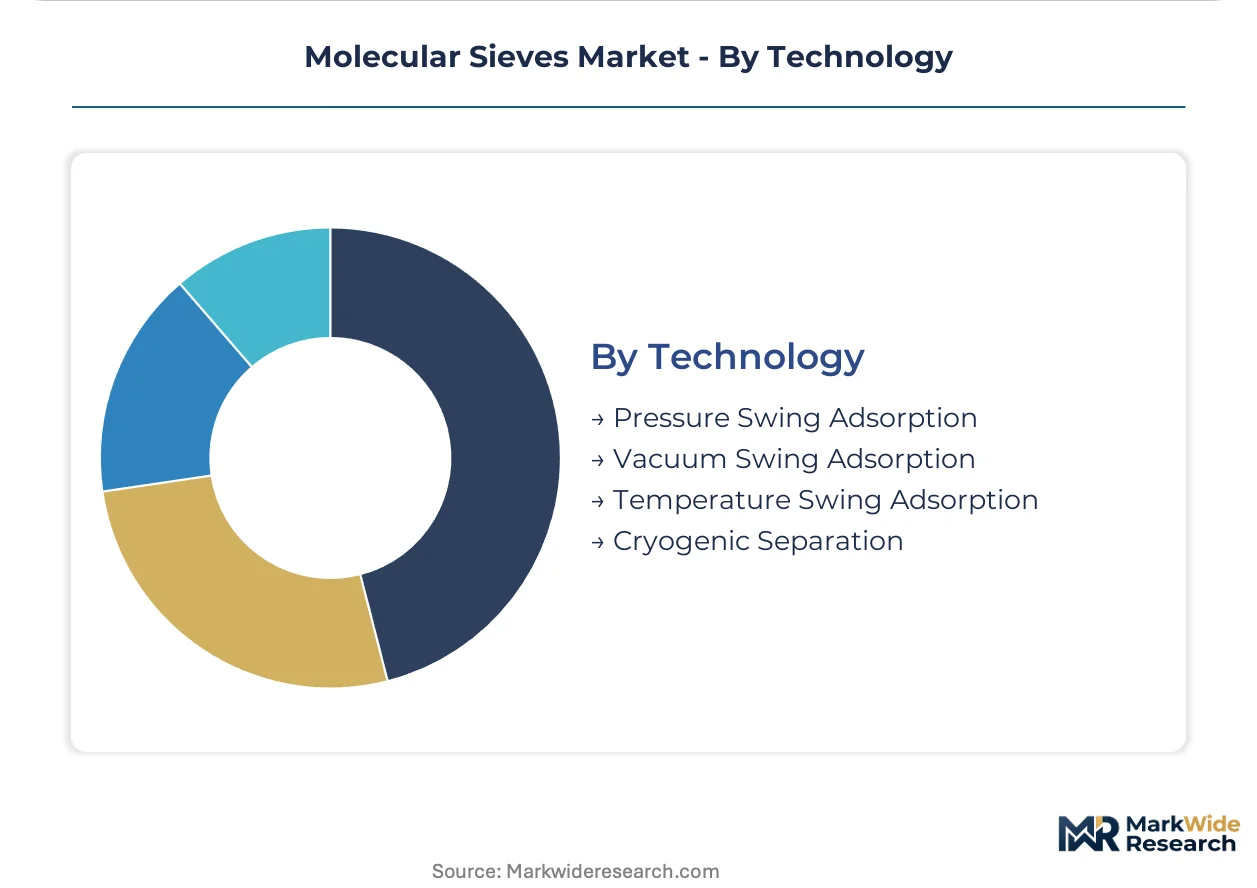
Technology:
Unit configuration determines energy intensity, cycle frequency, and suitability for remote or mobile deployment.
- Pressure Swing Adsorption:Cyclic pressurization and depressurization to separate gases based on differential adsorption affinity. Hydrogen purification units at German chemical plants and medical oxygen concentrators for home healthcare represent the primary demand poles.
- Temperature Swing Adsorption:Thermal regeneration for heavily contaminated streams where pressure cycling proves insufficient. Natural gas dehydration in the United States leverages TSA for high-water-content feedstocks.
- Vacuum Swing Adsorption:Sub-atmospheric desorption for oxygen generation and carbon capture applications.
- Cryogenic Separation:Distillation-based purification at liquefaction temperatures for large-scale air separation.
Pressure Swing Adsorption dominates installed base; Vacuum Swing Adsorption gains share fastest in carbon capture pilots.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates with Japanese and German manufacturers while Chinese distributors capture margin through logistics consolidation. This asymmetry shapes procurement patterns across ethylene purification and hydrogen generation installations.
United States
Petrochemical refiners along the Gulf Coast expand adsorption capacity for ethylene purification. EPA New Source Performance Standards mandate volatile organic compound capture above threshold throughput rates, directly expanding zeolite adsorber installations. Houston and Corpus Christi anchor this demand concentration with direct manufacturer relationships bypassing distributor layers.
China
Petrochemical complexes in Zhejiang and Jiangsu provinces drive zeolite replacement cycles. MEE enforcement of stricter benzene emissions limits accelerates domestic adsorption capacity expansion. Procurement teams increasingly consolidate volumes through regional trading houses that manage logistics and customs clearance.
Germany
The Ludwigshafen and Leverkusen chemical corridor prioritizes catalyst-grade molecular sieves with controlled binder chemistries. REACH registration requirements restrict certain formulations, pushing procurement toward suppliers with established ECHA portfolios. Polymer-zeolite composite membranes displace conventional packed beds in nitrogen generation skids.
Japan
Synthetic zeolite production anchors on captive alumina-silicate refining capabilities. METI industrial policy supports domestic manufacturing of separation materials for hydrogen purification systems. Osaka-based producers supply ethylene purification adsorbents to Asian refiners through distributor intermediaries.
Molecular Sieves Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream with formulation expertise and captive feedstock control. The structure consolidates around legacy Japanese and German manufacturers with hydrothermal crystallization capabilities while regional distributors gain leverage in Asia-Pacific procurement. Two archetypes dominate: backward-integrated chemical conglomerates with petrochemical feedstock control, and specialized zeolite fabricators with tuned pore-size distribution expertise. Competitive moves center on bio-based aluminosilicate precursor development and membrane-zeolite composite technology licensing.
Among Japanese manufacturers, Tosoh Corporation exemplifies the captive-feedstock archetype through integrated alumina-silicate refining. Clariant occupies a position representing European specialty chemical differentiation with catalyst-grade formulations. BASF SE anchors the backward-integrated tier, leveraging in-house production of petrochemical feedstocks to control sieve pricing for captive consumption.
| Leading Market Players |
|---|
| W. R. Grace & Co. |
| Tosoh Corporation |
| Honeywell International Inc |
| Clariant |
| Axens |
| Arkema |
| Zeochem AG |
| KNT Group |
| BASF SE |
| Others |
Cost & Logistics Intelligence
Overcapacity in Chinese synthetic zeolite production is compressing spot pricing for standard-grade 3A and 4A sieves while Japanese and German manufacturers defend premium positions through catalyst-grade specialization. This utilization divergence creates a bifurcated market where procurement teams at US Gulf Coast refiners negotiate long-term offtake contracts while Asian distributors capture margin through logistics arbitrage.
Pricing Analysis
The customization-premium spread separates configured-to-order catalyst-grade sieves from standard dehydration products by a factor of three to five, with REACH-registered formulations commanding additional certification premiums. Contract-based long-term offtake dominates procurement for petrochemical operators seeking regeneration-cycle guarantees, while spot transactions concentrate in commodity 3A grades for natural gas dehydration. Price differentiation rests on thermal stability certification and captive alumina-silicate refining capabilities, with Tosoh and Clariant extracting brand premiums. Cost compression in standard grades intensifies as Chinese capacity expansion outpaces regional demand growth. Food and beverage processors exhibit highest price sensitivity due to lower technical barriers, whereas polymer plants prioritize performance consistency over unit cost.
Supply Chain Analysis
Extended payment terms from Japanese synthetic zeolite producers to Asian distributors have become standard practice, with supply-chain finance facilities now intermediating 60-90 day working capital cycles. Manufacturing concentrates in Japan, Germany, and China, with Osaka-based producers supplying ethylene purification adsorbents through regional trading houses. Raw material dependencies center on bauxite-derived alumina, sodium silicate gels, and specialized binder chemistries restricted under REACH evaluation. Single-source vulnerability runs through Japanese captive alumina-silicate refining capabilities, where hydrothermal crystallization expertise remains concentrated. Distribution runs through direct manufacturer relationships for US Gulf Coast refiners and consolidated trading-house channels across Asia-Pacific procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Molecular sieves sit in early-cycle expansion as polymer-zeolite membrane adoption accelerates replacement demand across nitrogen generation and hydrogen purification installations. Penetration remains below 15 percent for medical oxygen concentrators in decentralized healthcare systems.
For Market Incumbents: Pre-empt membrane-zeolite composite displacement by licensing hybrid PSA configurations to German chemical operators before regional distributors consolidate procurement leverage. Secure backward integration into bio-based aluminosilicate precursors to defend margin positions against Arkema and Axens investments aligned with EU Green Deal preferences. Channel control through direct technical service relationships remains critical as Asian refiners fragment supply relationships. For New Entrants and Emerging Players: Establish a beachhead in medical oxygen concentration PSA units for home healthcare and field hospital deployments, where healthcare system decentralization creates pull-through demand without incumbent technical service lock-in. Target Southeast Asian trading houses as go-to-market partners to bypass Japanese and German manufacturer direct sales organizations, leveraging logistics consolidation trends in Zhejiang and Jiangsu province procurement. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among membrane-zeolite composite technology licensors with established ECHA registration portfolios, where long-term supply agreements for nitrogen generation skids generate predictable service income. Over the projection horizon, acquisition targets should combine hydrothermal crystallization expertise with polymer matrix integration capabilities. Watch for carbon border adjustment mechanism implementation as inflection indicator for competitive cost restructuring between imported and locally manufactured sieve systems.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Based Precursors | Arkema and Axens investments align procurement with EU Green Deal sustainable materials preferences. |
| Membrane-Zeolite Composite Licensing | German polymer plants at Ludwigshafen adopt hybrid configurations to halve nitrogen generation skid footprints. |
| Long-Term Supply Agreement Expansion | US Gulf Coast refiners secure ethylene purification adsorbent volumes through direct manufacturer relationships. |
| Regional Distribution Partnership | Chinese trading houses consolidate Zhejiang and Jiangsu province procurement for logistics and customs efficiency. |
| REACH Registration Portfolio Investment | European chemical corridors restrict binder chemistries, concentrating purchasing power among ECHA-established suppliers. |
Research Approach
A spread of perspectives from plant managers at petrochemical complexes, procurement leads at downstream polymer plants, distribution channel partners in Asia-Pacific trading houses, and technical R&D directors at zeolite manufacturers converged on the working assumptions. These primary insights were validated against customs and trade data, ACC and Cefic industry reports, SEC 10-K filings from listed chemical conglomerates, and EPA enforcement records. Bottom-up unit deployment counts for PSA and TSA installations were triangulated against top-down petrochemical capacity expansion announcements across the analysis window.
Demand-supply balance modeling anchored the forecast framework, with capacity utilization rates at Japanese and Chinese synthetic zeolite facilities informing price trajectory assumptions. Segmentation dimensions included product chemistry grade, end-use industry application, technology configuration, and regional production hub. CAGRs were derived from slope analysis of historical deployment patterns and forward projection of regulatory mandate timelines. Industry-specific inputs incorporated MEE benzene emission enforcement intensity and EPA New Source Performance Standards implementation pace.
Stress conditions across sodium aluminate input cost volatility, REACH registration timeline extensions, and carbon border adjustment mechanism adoption rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about petrochemical capacity expansion, membrane-zeolite composite adoption curves, and healthcare system decentralization patterns. Macroeconomic contraction, regulatory acceleration beyond modeled scenarios, or breakthrough non-zeolite separation technologies would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Automotive Chemicals Market
Industrial Chemicals
Commercial Electronic Detonator Market
Industrial Chemicals
Diphenyl Oxide (DPO) Market
Industrial Chemicals
2-Ethylhexanol (2-EH) Market
Industrial Chemicals
Bulk Explosives Market
Industrial Chemicals
Kraft Lignin Products Market
Industrial Chemicals
Global Ethylene Carbonate Market
Industrial Chemicals
Heat Treating Market
Industrial Chemicals
Global High Throughput Process Development Market
Industrial Chemicals
Aminic Antioxidants Market
Industrial Chemicals
Chlorine Market
Industrial Chemicals
Polyepoxysuccinic Acid Market
Industrial Chemicals
Ceramic Corona Discharge Ozone Generator Market
Industrial Chemicals
Formaldehyde Market
Industrial Chemicals
Sulfolane Market
Industrial Chemicals
Aluminium Production Chemicals Market