
 Ceramic Corona Discharge Ozone Generator Market | 2026-2036
Ceramic Corona Discharge Ozone Generator Market Size, Share, and Industry Trends Forecast 2026-2036
Ceramic Corona Discharge Ozone Generator Market Analytics
Single-source procurement for ceramic dielectrics is realigning toward multi-source strategies as supply constraints persist. Evoqua Water Technologies leverages captive engineering partnerships to secure electrode consistency across installations. SUEZ SA anchors its position through backward integration into ceramic substrate production. Beijing Terao Environmental Protection Technology Co., Ltd. competes on localized fabrication cost structures.
A ceramic corona discharge ozone generator employs a dielectric barrier of alumina or zirconia ceramic between two electrodes, where alternating current ionizes oxygen to produce ozone concentrations typically ranging from 1% to 10% by weight. The device serves primarily to oxidize organic contaminants, deactivate pathogens, and remove color or odor in fluid and gas streams. Modular Systems command the widest deployment footprint due to scalability advantages across variable throughput requirements. Water Treatment generates the deepest margin pools among application categories, driven by compliance-critical installations where failure carries regulatory penalty. Compact Units sustain the fastest expansion trajectory in residential and small commercial air purification deployments.
The EPA enforces maximum contaminant levels for disinfection byproducts under the Safe Drinking Water Act, compelling municipal utilities toward ozone-based pre-oxidation systems. China's MEE implements tightening COD discharge standards for industrial effluent, expanding generator demand across chemical and textile processing clusters. ISO 9001 and CE marking protocols govern equipment qualification for cross-border supply contracts. Stakeholders must weigh ceramic dielectric longevity claims against total lifecycle cost when specifying systems for continuous-duty installations.
Market Dynamics
The ceramic corona discharge ozone generator market is being fundamentally restructured by tightening discharge standards for industrial effluent across China's manufacturing belt, which is forcing generator deployment into chemical processing, textile dyeing, and pharmaceutical production facilities at unprecedented scale.
Growth Catalysts
- EPA Stage 2 Disinfectants Rule:Municipal water treatment utilities across the United States face tightened compliance thresholds for disinfection byproducts, compelling capital investment in ozone-based pre-oxidation infrastructure.
- China MEE COD discharge standards:Industrial wastewater corridors in Jiangsu and Zhejiang provinces confront progressively stricter chemical oxygen demand limits, expanding generator demand across chemical and textile processing clusters.
- Alumina ceramic dielectric advances:Improved thermal shock resistance in engineered ceramic barriers extends electrode service intervals, reducing lifecycle cost for continuous-duty installations.
Market Restraints
- High-purity alumina supply concentration:Ceramic substrate fabrication depends on limited global sources of metallurgical-grade alumina, exposing generator manufacturers to input price volatility and allocation risk.
- UV-C LED substitution threat:Solid-state ultraviolet systems achieve comparable pathogen inactivation in low-flow residential applications at reduced capital cost, compressing addressable market for compact ozone units.
- CE marking protocol complexity:Cross-border equipment qualification requires extensive third-party testing against harmonized EN standards, extending time-to-revenue for European market entry.
Strategic Opportunities
- India industrial wastewater lag:Chemical processing and tannery clusters along the Ganges basin remain underpenetrated by advanced oxidation systems as CPCB enforcement tightens.
- Smart grid integration:Variable-frequency drive coupling with ozone generators enables demand-responsive operation, aligning power consumption with real-time electricity pricing signals.
- ISO 9001 certification premium:Quality management system documentation opens procurement channels to multinational beverage and pharmaceutical firms with vendor qualification mandates.
Industry Challenges
- Electrode alignment precision:Sub-millimeter gap tolerance requirements between ceramic dielectric and metallic electrodes demand specialized fabrication skill sets that remain scarce in regional installation networks.
- Legacy SCADA integration:Municipal water utilities operate decades-old distributed control architectures that resist seamless incorporation of modern generator telemetry and remote diagnostic protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ceramic Corona Discharge Ozone Generator Market |
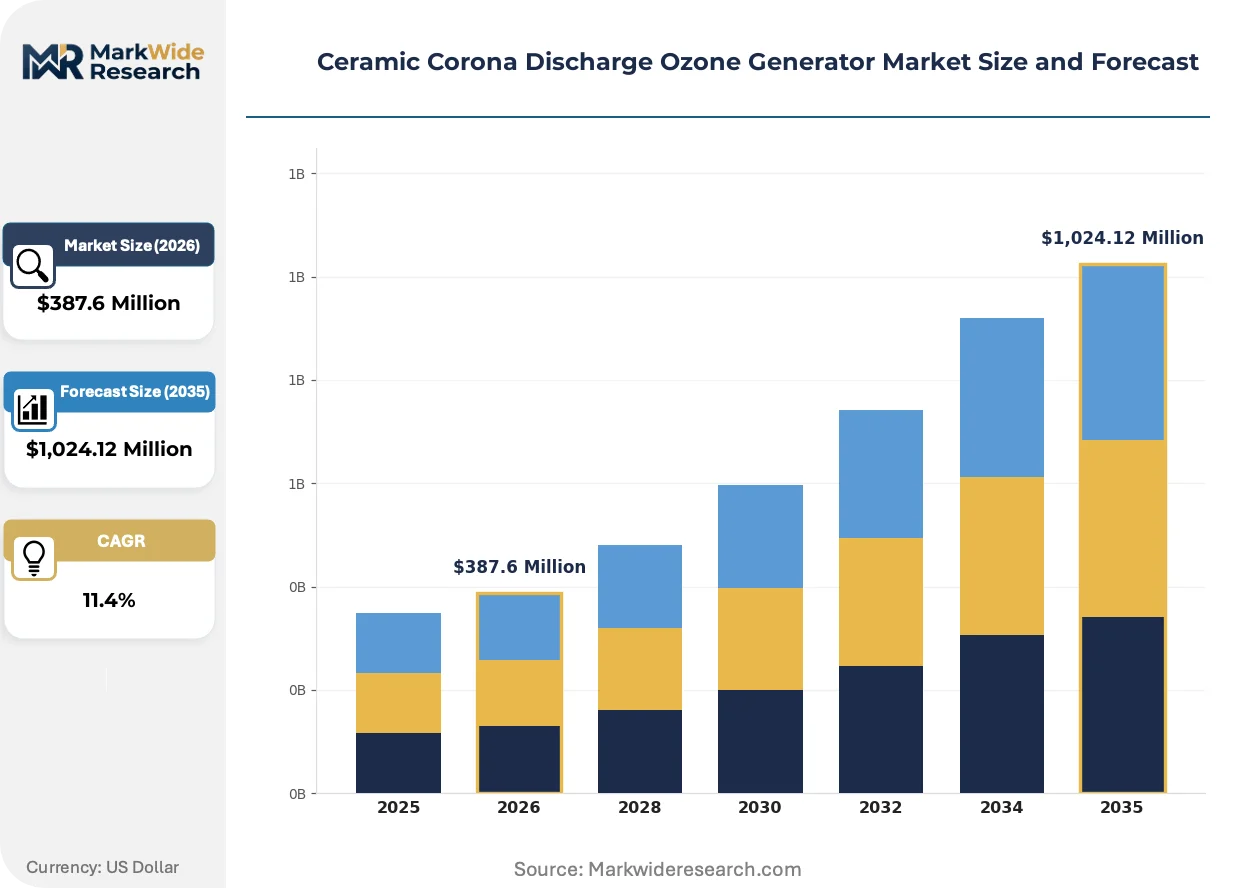
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $1,024.12 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Compact Units, Modular Systems, Industrial Generators, Portable Devices Application: Aquaculture, Air Purification, Water Treatment, Waste Management End User: Food Processing, Healthcare Facilities, Industrial Plants, Residential Users Technology: High Frequency, Atmospheric Pressure, Silent Operation, Low Power Consumption |
| Companies Covered | Evoqua Water Technologies LLC, Ozotech LLC, SUEZ SA, Beijing Terao Environmental Protection Technology Co., Ltd., ClearWater Tech, Inc., Xylem Inc., Jiangsu Tianwang Solar Technology Co., Ltd., Prozone Water Technologies Inc., De Nora S.p.A, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ceramic Corona Discharge Ozone Generator Market Evolving Landscape
Active engineering focus is compressing generator footprint while extending ceramic dielectric operational life, reshaping competitive differentiation around total cost of ownership rather than upfront capital expenditure.
Engineered zirconia-toughened alumina composite dielectrics are absorbing thermal cycling stress in high-frequency corona discharge applications. Municipal utilities with continuous-duty requirements are adopting these materials to extend electrode replacement intervals. The technology is absorbing service contract value that previously flowed to preventive maintenance providers.
China's MEE implements progressively stringent effluent quality standards for heavy metal and persistent organic pollutant discharge. Chemical manufacturing facilities in the Yangtze River Economic Belt must retrofit treatment infrastructure. Generator suppliers with localized fabrication capabilities capture procurement preference from state-owned enterprise buyers.
Equipment-as-a-service contracting is displacing outright purchase in mid-scale industrial applications. Ozone generator vendors bundle hardware, consumables, and remote monitoring into fixed monthly fees. This shift concentrates most visibly among North American food and beverage processors seeking to convert capital expenditure to operational expenditure.
Ceramic Corona Discharge Ozone Generator Market Segmentation
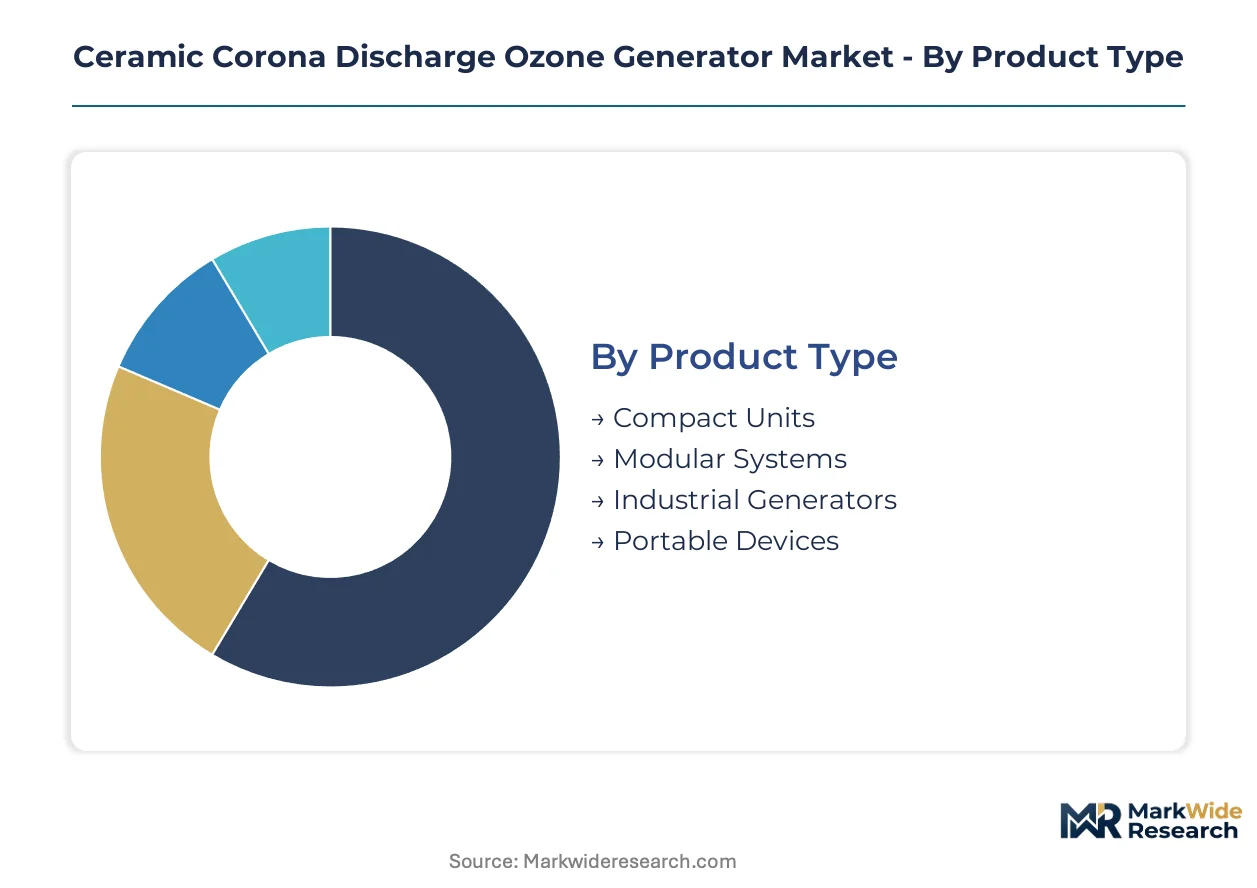
Segmentation in ceramic corona discharge ozone generators reveals distinct upgrade cycles across product architectures and divergent compliance pressures across end-use verticals. Procurement specifications vary sharply between continuous-duty municipal installations and intermittent residential deployments.
Product Type:
Replacement cycles differ markedly across product architectures, with modular systems offering component-level refresh versus full-unit obsolescence in compact formats.
- Modular Systems:Scalable rack-mounted configurations permit individual cell replacement without system shutdown. Municipal water treatment utilities in the United States favor these architectures for their ability to increment capacity alongside EPA Stage 2 compliance deadlines.
- Compact Units:Self-contained residential and small commercial devices with fixed electrode assemblies. Demand clusters in China's tier-two cities where apartment-scale air purification is displacing centralized building systems.
- Industrial Generators:High-throughput systems engineered for chemical processing and textile dyeing operations. Jiangsu and Zhejiang province facilities deploy these for MEE-mandated COD reduction.
- Portable Devices:Mobile ozone generators for temporary remediation and emergency response. Food processing sanitation contracts drive intermittent procurement.
Volume placements concentrate in Modular Systems; the faster expansion belongs to Compact Units.
Application:
Margin structures align with regulatory penalty severity, with water treatment commanding premium pricing due to failure consequences.
- Water Treatment:Pre-oxidation and disinfection byproduct control in municipal and industrial effluent systems. EPA enforcement of maximum contaminant levels sustains capital commitment from US utilities.
- Air Purification:Odor neutralization and pathogen reduction in enclosed environments. China's industrial corridor generates concentrated demand for factory-floor air quality management.
- Aquaculture:Dissolved ozone for hatchery water sterilization and disease control. Coastal farming operations in Shandong province adopt generator-based alternatives to antibiotic protocols.
- Waste Management:Leachate treatment and odor suppression at landfill and composting facilities. European Union landfill directive compliance drives retrofit investment.
Revenue depth pools in Water Treatment; Aquaculture is climbing the fastest.
End User:
Customer sophistication determines specification stringency, with multinational food and pharmaceutical firms imposing vendor qualification protocols.
- Industrial Plants:Chemical, textile, and pharmaceutical manufacturing facilities with continuous effluent treatment requirements. China's state-owned enterprise procurement favors localized fabrication capabilities.
- Food Processing:Beverage bottling and protein processing operations requiring surface and water disinfection. ISO 9001 certification opens procurement channels to multinational buyers.
- Healthcare Facilities:Hospital sterilization and HVAC pathogen control. US acute care networks deploy ozone for Legionella prevention in cooling tower systems.
- Residential Users:Individual consumers acquiring compact units for home air and water treatment. E-commerce penetration in China's consumer markets accelerates unit volume.
Specification complexity peaks in Industrial Plants; Residential Users are gaining share fastest.
Technology:
Performance differentiation centers on dielectric thermal management and power conversion efficiency.
- High Frequency:Alternating current above 1kHz enabling compact electrode geometries and elevated ozone concentration. Engineered zirconia-toughened alumina dielectrics extend service intervals in these configurations.
- Low Power Consumption:Optimized transformer and driver designs reducing kilowatt-hours per gram of ozone produced. Smart grid integration enables demand-responsive operation aligned with real-time electricity pricing.
- Atmospheric Pressure:Ambient-pressure discharge eliminating vacuum system complexity. Simplifies maintenance access for regional installation networks with limited specialized skill sets.
- Silent Operation:Acoustic dampening for residential and healthcare deployments where noise constraints apply. Premium positioning in compact unit segments.
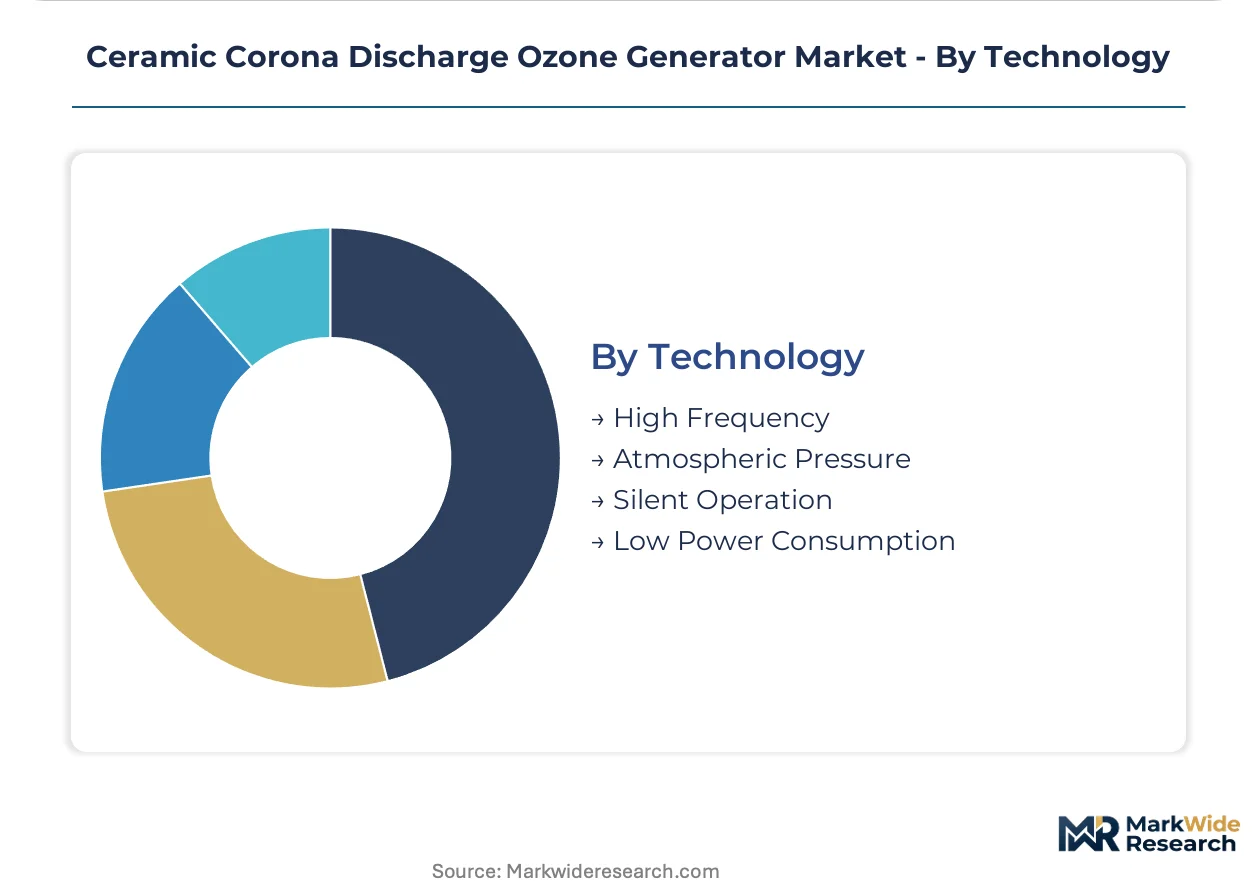
Technology leadership concentrates in High Frequency; Low Power Consumption shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's industrial wastewater corridor concentrates the heaviest generator deployment, while the United States and Germany anchor compliance-driven municipal procurement. India's chemical processing belt and Japan's precision manufacturing regions complete the demand geography.
United States
Municipal water treatment utilities drive capital commitment across the Great Lakes and Southwest regions. The EPA's Stage 2 Disinfectants and Disinfection Byproducts Rule tightens maximum contaminant levels for trihalomethanes and haloacetic acids. Texas and California utilities deploy ozone-based pre-oxidation systems to meet compliance deadlines without plant shutdown.
China
Chemical manufacturing and textile dyeing operations in Jiangsu and Zhejiang provinces generate concentrated demand for high-throughput systems. The MEE enforces progressively stricter COD discharge standards for Yangtze River Economic Belt facilities. State-owned enterprise buyers in Shanghai and Nanjing favor localized fabrication capabilities for retrofit installations.
Germany
Beverage bottling and pharmaceutical manufacturing operations in Bavaria and North Rhine-Westphalia specify ISO 9001-certified equipment. The EU F-Gas Regulation and national implementation frameworks constrain alternative oxidation chemistries. Industrial clusters around Munich and Cologne integrate ozone generators into closed-loop process water systems.
India
Chemical processing and tannery clusters along the Ganges basin confront tightening CPCB effluent enforcement. The Central Pollution Control Board mandates zero liquid discharge for selected industries in Uttar Pradesh and West Bengal. Kanpur and Kolkata facilities retrofit treatment infrastructure to avoid operational suspension.
Japan
Precision electronics and semiconductor fabrication in Kanto and Kansai regions demand ultra-high purity water systems. METI industrial efficiency guidelines encourage advanced oxidation for process water recycling. Osaka and Nagoya manufacturing complexes specify compact high-frequency generators for cleanroom integration.
Ceramic Corona Discharge Ozone Generator Market Competitive Landscape
Backward integration into ceramic substrate production dominates the current landscape as manufacturers secure electrode consistency against alumina supply volatility. The vendor base organizes around three strategic archetypes: multinational water technology conglomerates with captive engineering partnerships, regional specialists with localized fabrication cost structures, and equipment-as-a-service providers converting capital expenditure to operational expenditure. Capacity expansion and quality certification acceleration represent the dominant competitive moves as procurement channels harden around ISO 9001 and CE marking mandates.
Among water technology conglomerates, Evoqua Water Technologies LLC and SUEZ SA exemplify the captive supply chain archetype through in-house production of ceramic dielectrics. Beijing Terao Environmental Protection Technology Co., Ltd. occupies a position within the regional specialist tier, competing on fabrication proximity to China's state-owned enterprise buyers. These three anchors illustrate the divergence between premium-tier quality certification strategies and cost-optimized regional supply models.
| Leading Market Players |
|---|
| Evoqua Water Technologies LLC |
| Ozotech LLC |
| SUEZ SA |
| Beijing Terao Environmental Protection Technology Co., Ltd. |
| ClearWater Tech, Inc. |
| Xylem Inc. |
| Jiangsu Tianwang Solar Technology Co., Ltd. |
| Prozone Water Technologies Inc. |
| De Nora S.p.A |
| Others |
Value Network & Pricing Analysis
Sovereign-backed ceramic substrate producers in China anchor supply discipline through state-directed capacity allocation, compressing margin flexibility for generator assemblers in Europe and North America while concentrating pricing power among integrated manufacturers with captive alumina sourcing.
Pricing Analysis
Volume placements cluster in standard-grade modular systems where procurement tenders prioritize unit cost; premium-tier positioning concentrates in ISO 9001-certified equipment for multinational beverage and pharmaceutical accounts. Three-tier pricing structure across premium, standard, and economy levels separates certified continuous-duty installations from intermittent industrial deployments and compact residential units. Cost compression in the economy tier intensifies because UV-C LED substitution erodes addressable market for compact ozone devices. Municipal water utilities exhibit lowest price sensitivity due to EPA compliance penalty exposure; residential buyers in China's tier-two cities show highest elasticity.
Supply Chain Analysis
Reverse-logistics flows for ceramic dielectric refurbishment remain underdeveloped, forcing premature electrode replacement and inflating lifecycle costs for installations lacking service contract coverage. High-purity alumina fabrication concentrates in China, Germany, and the United States; electrode assembly draws from Japanese precision ceramics and Italian power electronics specialists. Single-source vulnerability in metallurgical-grade alumina exposes generator manufacturers to allocation risk during supply shocks. Distribution runs through regional water technology integrators for municipal accounts and direct e-commerce channels for compact residential units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ceramic corona discharge ozone generator market functions as a cost-of-compliance arena where the EPA's Stage 2 Disinfectants and Disinfection Byproducts Rule erects a regulatory moat that rewards certified incumbents while screening out undercapitalized entrants lacking validation infrastructure.
For Market Incumbents: Lock in multi-year service contracts with US municipal utilities ahead of EPA enforcement deadlines, converting capital expenditure preference into recurring revenue streams. Backward integration into zirconia-toughened alumina substrate production defends margin position against raw material volatility. Counter the UV-C LED substitution threat by emphasizing ozone's superior oxidation chemistry for complex organic contaminant matrices. For New Entrants and Emerging Players: Enter via India's Ganges basin chemical processing belt where CPCB enforcement tightens against fragmented local competitors lacking advanced oxidation capabilities. Target tannery clusters in Kanpur and Kolkata for zero liquid discharge retrofit demand. Pursue equipment-as-a-service contracting to bypass upfront capital barriers among mid-scale food processors. For Investors and Strategic Acquirers: Distressed-cycle entries favor regional specialists with localized fabrication capabilities in China's Yangtze River Economic Belt during MEE-mandated retrofit waves. Long-term viability hinges on ceramic dielectric longevity differentiation rather than generator assembly scale. Monitor alumina spot price volatility and EPA enforcement action intensity as inflection indicators.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ceramic Substrates | SUEZ SA and Evoqua secure electrode consistency against alumina supply shocks. |
| Equipment-as-a-Service Contracting | North American food processors convert capex to opex through bundled remote monitoring. |
| ISO 9001 Certification Acceleration | Quality documentation opens procurement channels to multinational pharmaceutical buyers. |
| Smart Grid Integration Development | Variable-frequency drive coupling aligns power consumption with real-time electricity pricing. |
| Localized Fabrication Expansion | Beijing Terao captures state-owned enterprise preference in Jiangsu and Zhejiang provinces. |
Research Methodology
EPA enforcement bulletins, MEE discharge standard updates, and customs trade records formed the secondary backbone, cross-referenced against primary interviews with municipal water utility procurement directors, industrial plant maintenance engineers, ceramic substrate manufacturing specialists, and ozone generator system integrators. Bottom-up and top-down triangulation validated shipment volumes against installed base estimates and replacement cycle assumptions.
Bottom-up modeling aggregated segment-level unit economics across modular, compact, industrial, and portable product architectures; top-down constraints applied macroeconomic filters for capital expenditure cycles in water infrastructure. Segmentation dimensions included product type, application vertical, end-user sophistication tier, and technology performance class. CAGRs derived from regression against historical compliance-driven investment waves and projected regulatory deadline clustering. Industry-specific inputs incorporated ceramic dielectric replacement intervals and electricity pricing elasticity for demand-responsive operation.
Forecast precision tightens around the base case; tail outcomes carry wider variance under alumina supply disruption scenarios or accelerated UV-C LED cost reduction curves. Practitioners should monitor EPA enforcement action intensity, MEE COD standard revision timing, and high-purity alumina spot price movements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Global Desalting and Buffer Exchange Market
Industrial Chemicals
Lime Manufacturing Market
Industrial Chemicals
Global N-Methyl-2-Pyrrolidone (NMP) Market
Industrial Chemicals
Beneficiation Reagents Market
Industrial Chemicals
Global Chemical Mechanical Planarization Market
Industrial Chemicals
Fischer-Tropsch (FT) Wax Market
Industrial Chemicals
VOC Concentrator Market
Industrial Chemicals
Gypsum Market
Industrial Chemicals
Fabric Starch Market
Industrial Chemicals
Cockroach Gel Baits Market
Industrial Chemicals
Electroelutor Market
Industrial Chemicals
Drum Melters Market
Industrial Chemicals
Butadiene Extraction Market
Industrial Chemicals
1-Octanol Market
Industrial Chemicals
Fatty Amines Market
Industrial Chemicals
Industrial Phenol Market