
 Global Soft Magnetic Composites (Smcs) Market | 2026-2036
Global Soft Magnetic Composites (Smcs) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Soft Magnetic Composites (Smcs) Market Foresight
REACH compliance is repositioning the cost-of-entry calculus for European SMC suppliers, forcing reformulation of epoxy-bonded iron powders to eliminate restricted phthalate plasticizers. Höganäs AB leverages its captive atomization capacity in Sweden to control powder purity from melt to compaction. GKN Powder Metallurgy sustains dual qualification tracks for automotive and aerospace grades through its UK and German facilities. VACUUMSCHMELZE GmbH & Co. KG anchors the high-frequency transformer segment with cobalt-based amorphous composite tapes that outperform conventional powder cores at megahertz switching frequencies.
Soft magnetic composites are engineered materials comprising ferromagnetic particles, typically high-purity iron or iron-silicon alloys, individually insulated with inorganic or organic binders and compacted into three-dimensional shapes with isotropic magnetic properties; these materials exhibit relative permeability ranging from 50 to 600 and core losses below 100 W/kg at 1 T and 400 Hz, serving primarily as core materials for rotating electrical machines and static magnetic components where complex geometries and reduced eddy current losses are required. Molded composites dominate volume consumption in automotive auxiliary motors due to net-shape process economics, while pressed powder cores capture the fastest expansion in photovoltaic inverter inductors where distributed air gaps manage DC bias saturation. Laminated composites retain margin concentration in aerospace generator segments where DO-160 qualification cycles lock in multi-year supply agreements.
The US EPA enforces TSCA Section 5 premanufacture notification for novel polymer binders, while China's GB/T standardization regime mandates electromagnetic compatibility testing for motor cores deployed in grid-tied renewable installations. Japan's METI circular economy directives are accelerating scrap-recycling requirements for rare-earth-free SMC formulations. Stakeholders must monitor the divergence between EU chemical restriction trajectories and Asia-Pacific performance-centric certification paths when allocating R&D budgets across regional product platforms.
Market Dynamics
Electric vehicle powertrain manufacturers are scaling procurement of pressed powder cores for high-frequency motor applications, forcing suppliers to requalify iron-polymer formulations under tightening EU F-Gas Regulation limits on magnetic core losses. This demand surge is compressing qualification timelines while fragmenting the supplier base between automotive-grade and industrial-grade competency tiers.
Growth Catalysts
- EU F-Gas Regulation:Tightening permissible core loss thresholds are accelerating reformulation of iron-polymer binders toward higher-frequency grades, pulling demand from Germany's industrial motor belt.
- Photovoltaic inverter inductors:Distributed air gap architectures in pressed powder cores are displacing ferrite in megawatt-scale solar installations, creating pull-through for high-permeability SMC grades.
- Japan METI circular economy directives:Scrap-recycling mandates for rare-earth-free motor cores are redirecting R&D budgets toward iron-silicon composite formulations with closed-loop atomization.
Market Restraints
- Epoxy resin cost volatility:Phthalate-free binder alternatives carry 15-25% raw material premia, compressing margins for mid-tier compaction houses without captive powder supply.
- Swedish atomization concentration:Captive melt-to-powder capacity at Höganäs AB creates supply-side bottleneck risk for high-purity iron grades qualified in automotive traction stators.
- Amorphous metal substitution:Cobalt-based tape wound cores from VACUUMSCHMELZE outperform powder composites above 100 kHz, capping addressable market in high-frequency transformer segments.
Strategic Opportunities
- India PLI scheme for electric mobility:Domestic motor manufacturing incentives are creating first-mover advantage for SMC suppliers establishing compaction joint ventures near Chennai and Pune automotive clusters.
- Silicon carbide converter convergence:Pairing pressed powder cores with SiC switching devices enables 20-50 kHz motor drives, opening aerospace auxiliary power unit applications previously locked by laminated steel.
- Direct-to-OEM technical sales:Bypassing distributor channels for EV powertrain engineering teams accelerates co-development cycles and captures value from application-specific core geometries.
Industry Challenges
- DO-160 qualification timelines:Aerospace generator segments require 18-36 month validation cycles that lock working capital and freeze formulation iteration.
- GB/T electromagnetic compatibility testing:China's grid-tied renewable certification mandates create parallel track complexity for suppliers serving both European and Asian product platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Soft Magnetic Composites (Smcs) Market |
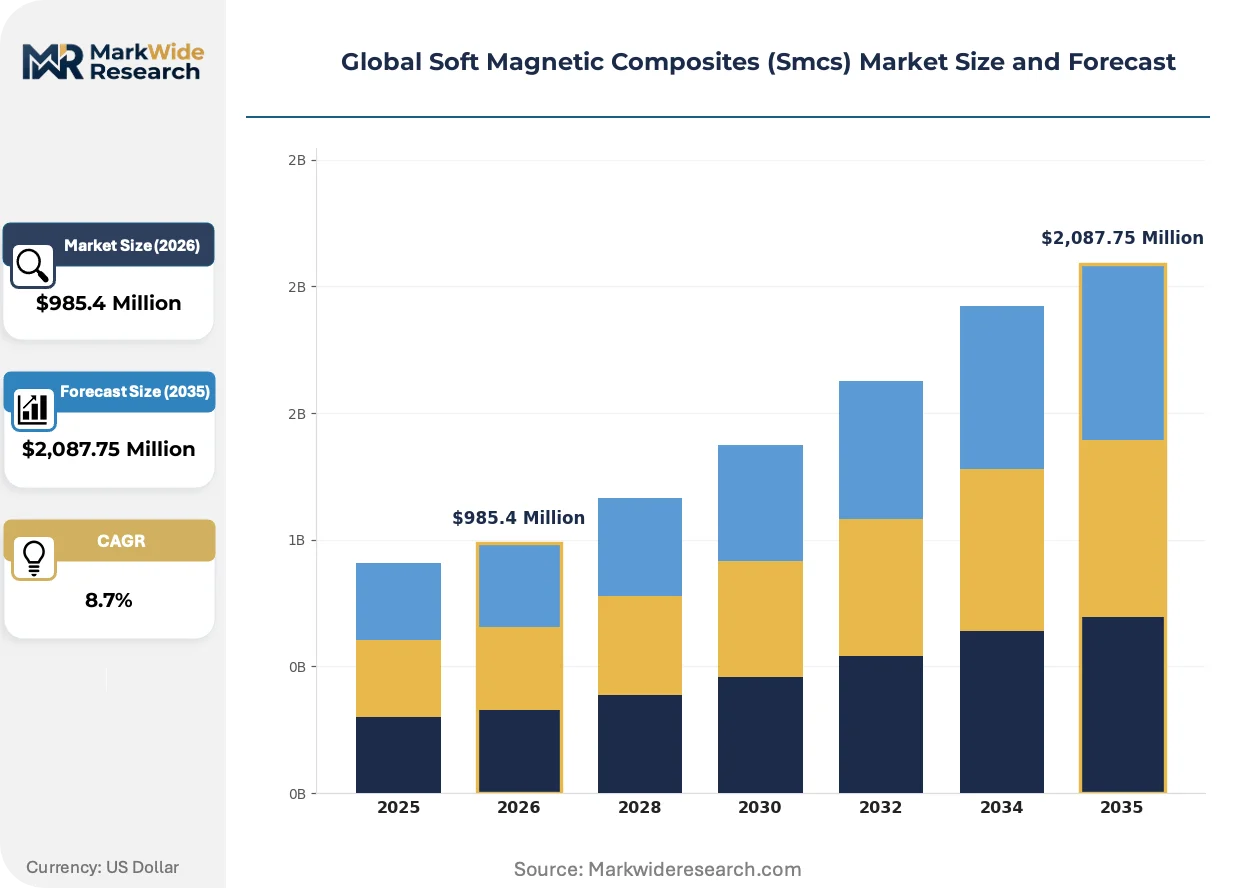
| Market Size in 2026 | $985.4 Million |
| Market Size in 2035 | $2,087.75 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Molded Composites, Laminated Composites, Pressed Powder Cores, Sintered Components Technology: Powder Metallurgy, Composite Bonding, Laser Sintering, Electron Beam Melting Application: Electric Motors, Inductors, Transformers, Sensors, Actuators End User: Consumer Electronics Manufacturers, Renewable Energy Firms, Aerospace Engineers, Electrical Equipment Producers |
| Companies Covered | Höganäs AB, Hitachi Metals Ltd., GKN Powder Metallurgy, Rio Tinto Metal Powders, VACUUMSCHMELZE GmbH & Co. KG, Elna Magnetics, MMG Canada Limited, Steward Advanced Materials, Arnold Magnetic Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Soft Magnetic Composites (Smcs) Market Shifts & Advancements
Formulation science and compaction process control are converging to enable three-dimensional magnetic components with isotropic properties previously achievable only through laminated stacks, compressing the traditional trade-off between core loss and geometric complexity.
Amorphous cobalt-based composite tapes are electrifying high-frequency transformer design by sustaining permeability above 300 at megahertz switching frequencies. Data center power supply architects are specifying these materials for 400 V bus architectures, displacing conventional ferrite in server rack power distribution units. The technology is electrifying margin concentration in the transformer segment by locking in multi-year supply agreements through performance guarantees that powder cores cannot match.
REACH compliance is repositioning the cost-of-entry calculus for European SMC suppliers by mandating elimination of restricted phthalate plasticizers from epoxy-bonded iron powders. ECHA substance evaluation protocols are extending reformulation validation cycles by 8-14 months, forcing smaller compaction houses to outsource binder chemistry development. Automotive auxiliary motor manufacturers in Germany are responding by consolidating supplier panels to those with captive analytical laboratories capable of generating full substance dossiers.
Engineering procurement organizations at EV powertrain divisions are compressing supplier qualification from 24-month automotive timelines toward 12-month industrial-electronics pacing. Tier-1 motor manufacturers are unbundling core supply from stator winding contracts, creating direct specification authority for SMC grades. This behavioral shift is most visible in Germany's Ruhr industrial corridor, where Siemens and Bosch suppliers are establishing dedicated SMC engineering liaison teams with compaction houses.
Global Soft Magnetic Composites (Smcs) Market Segmentation
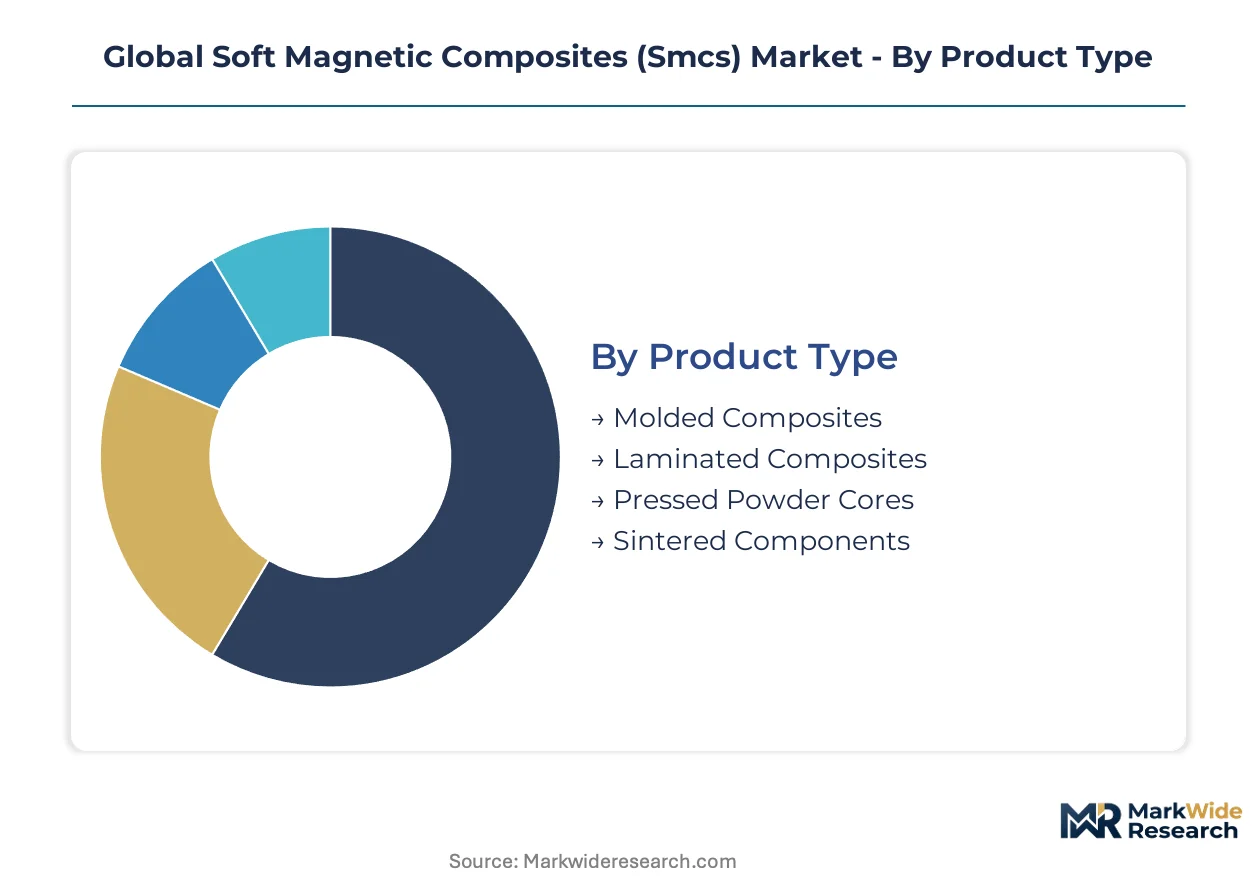
Soft magnetic composites fragment across four distinct dimensions where technical specifications, regulatory thresholds, and end-use performance requirements create non-substitutable demand pockets. Each segmentation axis carries unique margin structures and qualification barriers that reshape supplier positioning.
Product Type:
Volume consumption clusters in automotive auxiliary applications where net-shape economics dominate procurement decisions, while premium capture concentrates in aerospace-qualified grades with extended validation cycles.
- Molded Composites:Epoxy-bonded iron powders compressed into complex three-dimensional geometries with isotropic magnetic properties. Germany's Ruhr industrial corridor anchors demand as Siemens and Bosch suppliers qualify new grades for traction motor stators under tightening EU F-Gas Regulation core loss thresholds.
- Pressed Powder Cores:Distributed air gap architectures manage DC bias saturation in high-frequency applications. Photovoltaic inverter manufacturers in megawatt-scale solar installations are pulling these cores fastest as silicon carbide converter adoption enables 20-50 kHz motor drives.
- Laminated Composites:Thin silicon steel sheets insulated and stacked for directional magnetic properties. DO-160 qualification cycles lock in multi-year supply agreements for aerospace generator segments where margin concentration remains highest.
- Sintered Components:High-temperature densification of iron-silicon powders for structural magnetic parts. Japan's METI circular economy directives are accelerating scrap-recycling requirements for these rare-earth-free formulations.
Today's leader: Molded Composites. Tomorrow's challenger: Pressed Powder Cores.
Technology:
Process selection hinges on geometric complexity tolerance versus electromagnetic performance targets, with powder metallurgy commanding volume leadership and additive methods capturing prototype-to-production transitions.
- Powder Metallurgy:Conventional compaction and sintering of insulated ferromagnetic particles. Höganäs AB's captive atomization capacity in Sweden controls powder purity from melt to compaction for automotive-grade qualification.
- Composite Bonding:Polymer matrix encapsulation of iron particles for three-dimensional isotropic cores. REACH compliance is forcing reformulation of epoxy-bonded iron powders to eliminate restricted phthalate plasticizers, extending validation cycles.
- Laser Sintering:Selective melting of metal powders for complex core geometries without tooling. Aerospace auxiliary power unit applications previously locked by laminated steel are opening as geometric freedom expands design space.
- Electron Beam Melting:Vacuum-based powder bed fusion for high-purity magnetic components. VACUUMSCHMELZE GmbH & Co. KG leverages this technology for cobalt-based amorphous composite tapes outperforming conventional powder cores at megahertz switching frequencies.
Process maturity favors Powder Metallurgy for scale; Electron Beam Melting commands the steepest expansion trajectory in high-frequency transformer segments.
Application:
End-use performance requirements create divergent material specifications where rotating machines prioritize mechanical integrity and static components optimize for frequency response.
- Electric Motors:Rotating machines requiring complex stator geometries with reduced eddy current losses. EV powertrain manufacturers are compressing supplier qualification timelines from 24-month automotive pacing toward 12-month industrial-electronics cycles.
- Inductors:Energy storage components with distributed air gap management. China's GB/T electromagnetic compatibility testing mandates create parallel track complexity for suppliers serving grid-tied renewable installations.
- Transformers:Static magnetic components for voltage conversion and isolation. Data center power supply architects are specifying cobalt-based amorphous tapes for 400 V bus architectures, displacing ferrite in server rack power distribution units.
- Sensors:Precision magnetic detection devices requiring stable permeability characteristics. The US EPA enforces TSCA Section 5 premanufacture notification for novel polymer binders in these sensitive applications.
- Actuators:Electromechanical motion devices with rapid response requirements. India's PLI scheme for electric mobility is creating first-mover advantage for SMC suppliers establishing compaction joint ventures near Chennai and Pune automotive clusters.
Electric Motors absorb the largest volume share; Inductors are climbing the fastest as photovoltaic deployment accelerates.
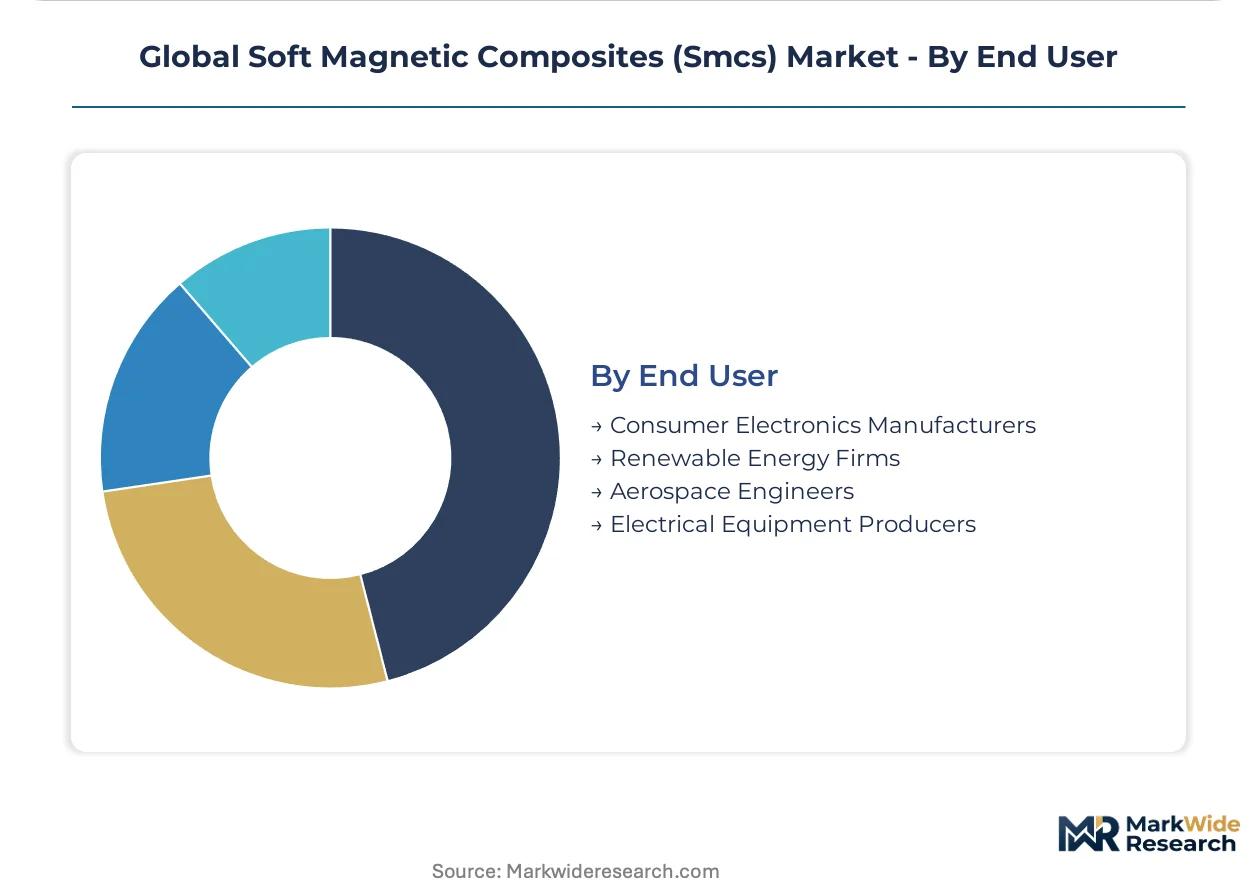
End User:
Customer archetypes stratify by qualification burden and co-development intensity, with aerospace and automotive tiers demanding captive engineering liaison capabilities.
- Consumer Electronics Manufacturers:High-volume, cost-sensitive procurement of standardized core geometries for power supplies and charging infrastructure.
- Renewable Energy Firms:Megawatt-scale solar and wind installations requiring high-permeability grades with grid-tied certification compliance.
- Aerospace Engineers:DO-160 qualified generator and auxiliary power unit specifications with 18-36 month validation timelines that freeze formulation iteration.
- Electrical Equipment Producers:Industrial motor and transformer OEMs consolidating supplier panels to those with captive analytical laboratories capable of generating full REACH substance dossiers.
Aerospace Engineers command premium positioning; Renewable Energy Firms are gaining share fastest as inverter deployment scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized powder metallurgy engineers concentrate in Germany's Ruhr corridor and Sweden's atomization belt, anchoring European supply chains for automotive-grade magnetic cores. Japanese materials scientists dominate cobalt-based amorphous tape development. Indian manufacturing technicians are migrating toward Chennai and Pune as PLI incentives reshape electric motor production geography.
Germany
EV powertrain procurement from Siemens and Bosch suppliers is accelerating qualification of new SMC grades for traction motor stators. The EU F-Gas Regulation tightens permissible core loss thresholds, forcing reformulation of iron-polymer binders. The Ruhr industrial corridor hosts dedicated SMC engineering liaison teams compressing supplier timelines from 24-month automotive pacing toward 12-month industrial-electronics cycles.
Sweden
Höganäs AB's captive atomization capacity controls powder purity from melt to compaction for high-frequency motor applications. ECHA substance evaluation protocols extend reformulation validation cycles by 8-14 months, disadvantaging smaller compaction houses without captive analytical laboratories. The Höganäs production belt creates supply-side bottleneck risk for automotive-grade iron powders qualified in German traction stators.
Japan
VACUUMSCHMELZE anchors the high-frequency transformer segment with cobalt-based amorphous composite tapes outperforming conventional powder cores at megahertz switching frequencies. METI circular economy directives accelerate scrap-recycling requirements for rare-earth-free SMC formulations. Tokyo-based data center power supply architects specify these materials for 400 V bus architectures, displacing ferrite in server rack power distribution units.
China
GB/T electromagnetic compatibility testing mandates create parallel track complexity for suppliers serving grid-tied renewable installations. Photovoltaic inverter manufacturers in megawatt-scale solar installations are pulling high-permeability pressed powder cores fastest. The Yangtze River Delta concentration of motor core fabricators faces divergence between EU chemical restriction trajectories and domestic performance-centric certification paths.
India
The PLI scheme for electric mobility creates first-mover advantage for SMC suppliers establishing compaction joint ventures near Chennai and Pune automotive clusters. Domestic motor manufacturing incentives redirect procurement from imported laminated stacks toward locally pressed powder cores. Maharashtra-based electrical equipment producers are consolidating supplier panels to those capable of generating full REACH substance dossiers for export-qualified grades.
Global Soft Magnetic Composites (Smcs) Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered automotive and industrial competency bands. Market structure concentrates around captive atomization capacity holders and formulation-science leaders with REACH-compliant binder development. Three archetypes dominate: integrated powder-to-core manufacturers controlling melt-to-compaction value chains; specialized compaction houses dependent on merchant powder supply; and high-frequency tape specialists with electron beam melting capabilities. Competitive moves center on dual qualification tracks for automotive and aerospace grades, plus direct-to-OEM technical sales bypassing distributor channels.
Among Sweden-based integrated manufacturers, Höganäs AB exemplifies the captive atomization archetype with in-house powder purity control. German high-frequency specialists VACUUMSCHMELZE GmbH & Co. KG occupy a position representing electron beam melting leadership for cobalt-based amorphous tapes. UK-German dual-facility operator GKN Powder Metallurgy sits within the diversified industrial conglomerate tier, sustaining parallel qualification tracks across automotive and aerospace segments.
| Leading Market Players |
|---|
| Höganäs AB |
| Hitachi Metals Ltd. |
| GKN Powder Metallurgy |
| Rio Tinto Metal Powders |
| VACUUMSCHMELZE GmbH & Co. KG |
| Elna Magnetics |
| MMG Canada Limited |
| Steward Advanced Materials |
| Arnold Magnetic Technologies |
| Others |
Supply & Pricing Matrix
Iron ore and specialty alloy price indices cascade through atomization and compaction stages, compressing margins for merchant-powder-dependent houses while rewarding captive melt-to-core manufacturers with pricing power in automotive qualification tiers.
Pricing Analysis
Bundled core-and-winding contracts are unbundling as EV powertrain procurement teams assume direct SMC specification authority. Three-tier pricing structure across aerospace-qualified, automotive-grade, and industrial-economy levels separates DO-160 validated laminates from F-Gas threshold-compliant molded cores. Cost compression in mid-tier epoxy-bonded grades intensifies because REACH-compliant phthalate-free binders carry raw material premia. Renewable energy inductor buyers exhibit highest price sensitivity; aerospace generator OEMs show least.
Supply Chain Analysis
High-purity iron powder supply rests on Swedish atomization capacity, German compaction expertise, and Japanese amorphous tape metallurgy. Critical inputs span atomized iron powders, cobalt-based alloy feedstocks, and epoxy-polymer binder chemistries. Single-source vulnerability concentrates in Höganäs AB's captive melt-to-powder capacity for automotive traction stator grades. Distribution runs through direct technical sales channels to OEM engineering teams, bypassing traditional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Soft Magnetic Composites Market functions as a stable compounder where electrification infrastructure buildout sustains steady grade-by-grade expansion across motor and transformer applications.
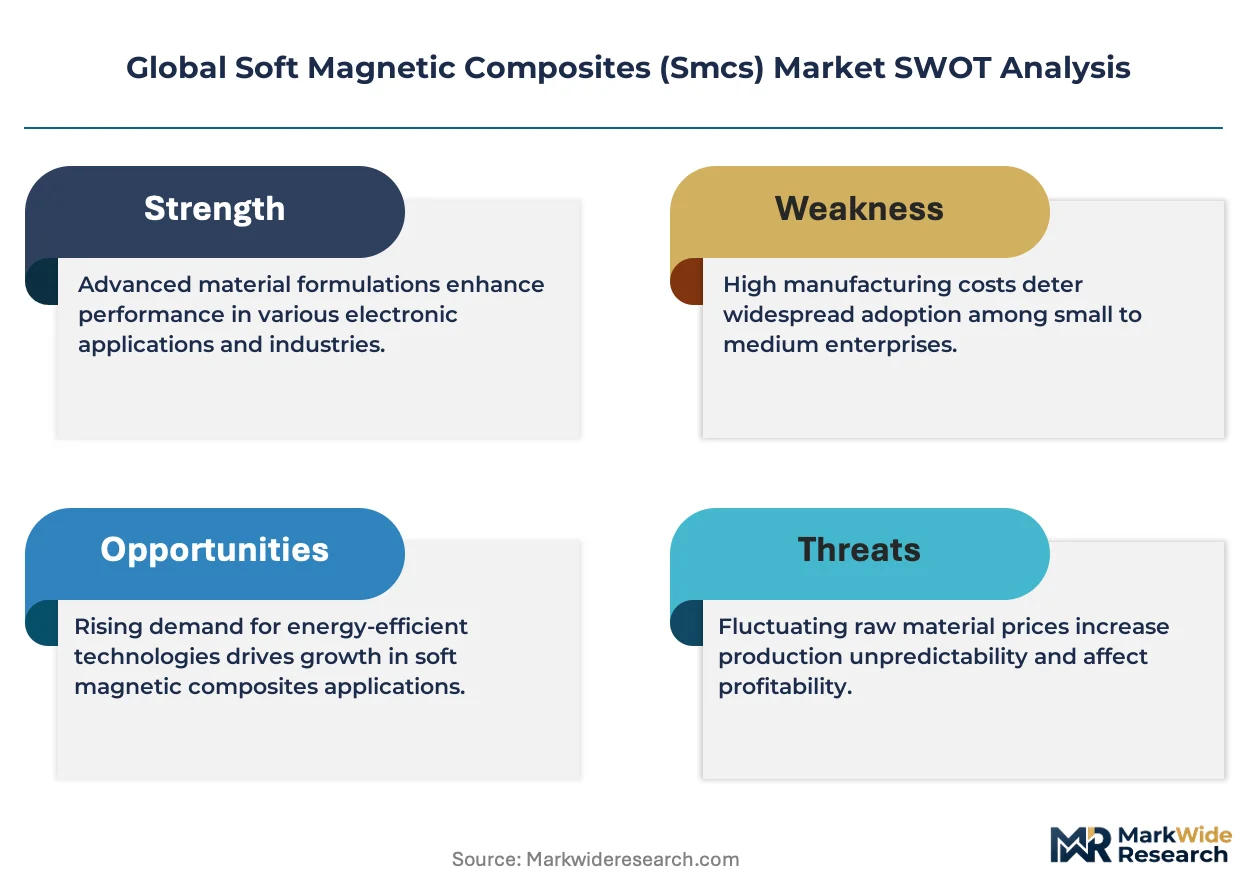
For Market Incumbents: Lock in multi-year aerospace supply agreements before DO-160 qualification cycles extend further, and deepen backward integration into atomization capacity to offset Swedish supply-side bottleneck risk from amorphous metal substitution threats. For New Entrants and Emerging Players: Silicon carbide converter pairing expertise offers a technology-first wedge into aerospace auxiliary power unit segments previously locked by laminated steel, with India's PLI scheme providing the most penetrable geography for compaction joint ventures near Chennai and Pune clusters. For Investors and Strategic Acquirers: Consolidation pressure builds where REACH compliance extends validation cycles beyond 14 months and smaller compaction houses lack captive analytical laboratories; the signal to watch is unbundling of core supply from stator winding contracts accelerating direct specification authority shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Atomization Capacity Expansion | Höganäs AB's Swedish melt-to-powder control insulates automotive-grade pricing from iron ore volatility. |
| REACH-Compliant Binder Reformulation | ECHA substance evaluation protocols force 8-14 month validation extensions, consolidating supplier panels. |
| Direct-to-OEM Technical Sales | Siemens and Bosch suppliers in Germany's Ruhr corridor compress qualification timelines toward 12-month pacing. |
| Dual Automotive-Aerospace Qualification | GKN Powder Metallurgy sustains parallel tracks across UK and German facilities for margin diversification. |
| Amorphous Tape Process Investment | VACUUMSCHMELZE electron beam melting captures megahertz transformer margins powder cores cannot match. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with powder metallurgy plant managers, EV powertrain procurement leads, aerospace generator engineering teams, and epoxy binder R&D directors with secondary validation from SEC filings of listed powder metallurgy groups, ECHA substance evaluation databases, and customs trade data for iron powder movements. Bottom-up grade-by-grade volume builds triangulated against top-down end-use demand assessments.
Segment-weighting distributed value across molded composites, pressed powder cores, laminated stacks, and sintered components by application intensity in electric motors, inductors, transformers, sensors, and actuators. CAGRs derived from fitted adoption curves for silicon carbide converter penetration and F-Gas Regulation threshold compliance timelines across the projection horizon. Industry-specific inputs included atomization capacity utilization rates and DO-160 qualification pipeline status.
The model holds under stable electrification investment trajectories; deviation in EU chemical restriction enforcement intensity or amorphous metal cost-down curves would shift grade-mix assumptions. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Magnetic Materials
Europe Ferrite Magnet Market
Magnetic Materials
Japan Neodymium Iron Boron Magnet Market
Magnetic Materials
Global Soft Magnetic Alloys Market
Magnetic Materials
Ferrofluid Market
Magnetic Materials
Neodymium-Iron-Boron Magnet Market
Magnetic Materials
North America Magnet Market
Magnetic Materials
Magnetic Materials Market
Magnetic Materials
Global Neodymium Magnet Market
Magnetic Materials
Middle East and Africa Magnet Wire Market
Magnetic Materials
Asia-Pacific Magnet Wire Market
Magnetic Materials
Europe Magnet Wire Market
Magnetic Materials
Sintered Magnet Market
Magnetic Materials
Magnetorheological Fluid Market
Magnetic Materials
Amorphous Soft Magnetic Materials Market
Magnetic Materials
Magnetic Carbon Nanofoam Market
Magnetic Materials
Global Iron Powder Market