
 Polyimide Varnish Market | 2026-2036
Polyimide Varnish Market Size, Share, and Industry Trends Forecast 2026-2036
Polyimide Varnish Market Analysis
Specialty chemical distribution in East Asia is rewriting how polyimide varnish reaches tier-one electronics manufacturers. DuPont leverages its fluoropolymer heritage to anchor premium thermal-resistant formulations for aerospace wire insulation. UBE Corporation sustains broad solvent-based capacity while navigating Japan's chemical emissions rules. Kaneka Corporation specializes in water-based polyimide precursors for flexible display substrates.
Polyimide varnish denotes a high-performance aromatic polymer solution, typically comprising pyromellitic dianhydride and 4,4'-oxydianiline in N-methyl-2-pyrrolidone solvent, engineered to form thermally stable coatings with continuous service temperatures exceeding 200°C. Its primary purpose centers on electrical insulation and mechanical protection for windings, circuits, and structural composites in thermally stressed environments. Thermal-resistant formulations occupy the dominant margin pool due to aerospace and EV motor requirements, while water-based technology represents the fastest-expanding segment as electrostatic spray lines in automotive plants convert to reduce volatile organic compound exposure. Electrical insulation applications lead volume consumption, though bonding formulations for copper-clad laminates capture disproportionate value in 5G infrastructure builds.
EPA air quality standards and OSHA permissible exposure limits for N-methylpyrrolidone shape formulation choices for US-based coating operations, pressuring suppliers toward lower-toxicity solvent systems or water-based alternatives. REACH registration requirements and RoHS substance restrictions in Europe enforce full material disclosure and restrict halogenated additives in electrical insulation products destined for EU markets. Stakeholders must monitor regulatory divergence between jurisdictions while building dual-compliant product architectures.
Market Dynamics
East Asian electronics clusters are compressing procurement cycles for polyimide varnish as flexible PCB and display substrate manufacturers demand just-in-time solvent delivery with batch-level purity certification.
Growth Catalysts
- EV Motor Insulation Mandates:NHTSA thermal safety standards for traction motors in the United States are mandating Class 220 insulation systems. Automotive tier-one suppliers are qualifying polyimide varnish formulations for stator winding impregnation.
- REACH Compliance Deadlines:ECHA substance restriction timelines are accelerating solvent substitution programs across European electrical insulation coating operations. Formulators are advancing water-based polyimide precursor development to meet 2027 registration windows.
- 5G Infrastructure Deployment:Copper-clad laminate manufacturers in China's Jiangsu province are scaling high-frequency bonding varnish consumption for low-dielectric-loss substrates. Base station antenna module builds are driving specification tightening for thermal cycling resistance.
Market Restraints
- N-Methylpyrrolidone Price Volatility:Petrochemical feedstock fluctuations and Chinese environmental inspections are creating solvent cost instability. Coating operations face margin compression during NMP supply tightness.
- Japanese Supplier Concentration:Pyromellitic dianhydride monomer production clusters in Japan's Chubu region. Geopolitical friction or logistics disruption risks cascading formulation shortages for non-integrated varnish producers.
- Silicone-Resin Substitution:High-voltage wire harness manufacturers are evaluating silicone-based insulation systems for cost-sensitive automotive applications. Thermal performance gaps are narrowing at service temperatures below 180°C.
Strategic Opportunities
- Indian Electronics Manufacturing:PLI scheme incentives for semiconductor and display fabrication are attracting PCB laminate investments in Gujarat and Tamil Nadu. Domestic varnish formulation capacity remains underdeveloped.
- Solid-State Battery Cell Encapsulation:In-situ polymerized polyimide coatings are emerging as thermal runaway barriers for lithium-metal anode architectures. Cell manufacturers are evaluating spray-deposited varnish precursors for pouch cell edge sealing.
- EU Green Deal Procurement Rules:Public tender guidelines for rail and aerospace infrastructure are incorporating lifecycle carbon thresholds. Bio-based dianhydride feedstocks are qualifying for preferential supplier status.
Industry Challenges
- Formulation Chemist Shortage:Polyimide synthesis expertise concentrates among aging specialists in Japan and the United States. Academic polymer chemistry programs are producing fewer candidates with aromatic heterocycle experience.
- UL 1446 Certification Timelines:Thermal class qualification for electrical insulation systems requires 12-18 month accelerated aging protocols. Product development cycles misalign with customer sample-to-production demands.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polyimide Varnish Market |
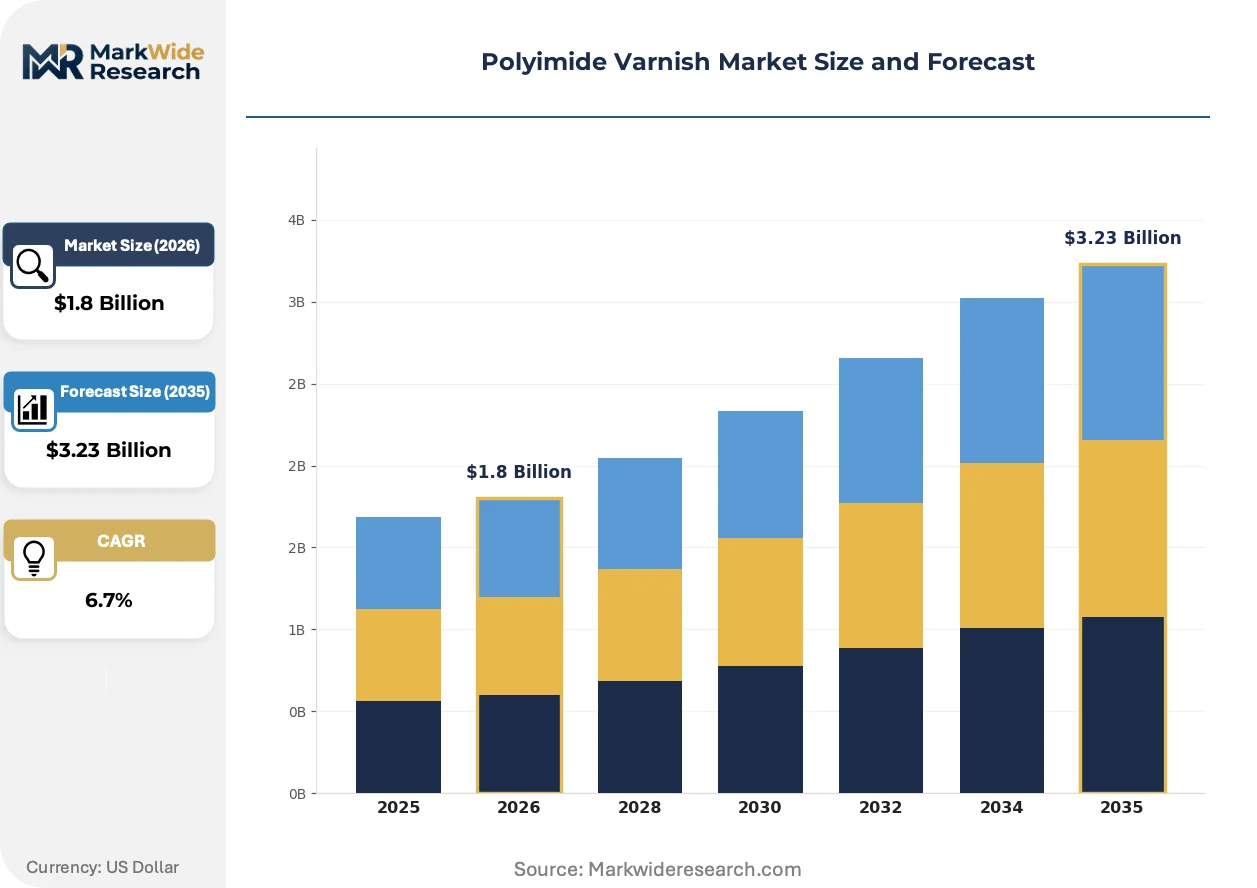
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermal-Resistant, Adhesive-Base, Paint-Compatible, Electrical Insulation End User: Aerospace, Automotive, Electronics, Defense Application: Insulation Coating, Surface Protection, Bonding, Electrical Components Technology: Solvent-Based, Water-Based, UV-Cured, Electrostatic Spray |
| Companies Covered | DuPont, Elantas PDG, UBE Corporation, Suzhou Jufeng Electrical Insulating System, PI Advanced Materials, Mitsubishi Gas Chemical, Kaneka Corporation, Toray Industries, IST Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polyimide Varnish Market Emerging Trajectories
Photocurable polyimide varnish formulations are collapsing traditional thermal cure cycles from hours to minutes. This chemistry shift is restructuring coating line economics across automotive and electronics manufacturing.
Photoinitiated cyclization of polyamic acid esters is rendering obsolete conventional thermal imidization ovens in roll-to-roll flexible electronics manufacturing. Korean display panel producers are retrofitting coating lines with UV-LED curing stations. Capital equipment payback periods are compressing from five years to eighteen months as throughput rates triple.
EPA air quality standards for hazardous air pollutants are tightening N-methylpyrrolidone emission limits for coating operations. US-based electrical insulation manufacturers are investing in solvent recovery systems and water-based formulation transitions. Aerospace wire harness suppliers face the steepest compliance costs due to low-volume, high-purity requirements.
Direct supplier relationships are displacing traditional specialty chemical distribution for high-volume electronics varnish buyers. PCB laminate manufacturers in Guangdong province are negotiating multi-year offtake agreements with Japanese monomer producers. Channel consolidation is most pronounced where batch consistency certification and technical service integration are valued over price competition.
Polyimide Varnish Market Segmentation
Polyimide varnish specifications diverge sharply across thermal class requirements and solvent toxicity profiles. Procurement teams in electronics and automotive sectors weight formulation choices against cure cycle economics and regulatory compliance burdens.
Product Type:
Cost tier stratification separates aerospace-grade thermal endurance from commodity electrical insulation grades.
- Thermal-Resistant:Formulations engineered for continuous service above 220°C using fluorinated co-monomers and rigid aromatic backbones. Aerospace wire harness manufacturers in France and Germany specify these grades for engine nacelle applications where FAA thermal safety mandates apply.
- Electrical Insulation:Standard polyamic acid solutions in N-methyl-2-pyrrolidone targeting Class 180-200 insulation systems. EV motor manufacturers in Michigan and South Carolina are qualifying these formulations for stator winding impregnation under NHTSA traction motor safety rules.
- Adhesive-Base:Tackified precursors for copper-clad laminate bonding in high-frequency PCB builds.
- Paint-Compatible:Modified surface energy formulations for topcoat adhesion in industrial equipment.
Thermal-Resistant holds installed capacity. Electrical Insulation is rotating up the share rankings.
End User:
Application maturity varies from qualified aerospace specifications to emerging EV motor platforms.
- Electronics:Flexible PCB and display substrate manufacturers drive volume consumption. Korean panel producers in Gyeonggi-do province are converting coating lines to water-based precursors for roll-to-roll manufacturing.
- Automotive:Traction motor insulation and high-voltage wire harness coatings represent the steepest expansion trajectory. Tier-one suppliers in Germany's Baden-Württemberg region are building dedicated impregnation lines for 800V architectures.
- Aerospace:Wire insulation for commercial and defense aircraft with rigorous FAA and EASA flame-smoke-toxicity certification.
- Defense:Harsh-environment specifications for naval and ground vehicle electronics.
Electronics holds installed capacity. Automotive is rotating up the share rankings.
Application:
Functional role determines cure chemistry selection and thickness deposition parameters.
- Insulation Coating:Thin-film impregnation of motor windings and transformer coils. Chinese manufacturers in Jiangsu province operate continuous dip lines processing thousands of stators daily for domestic EV brands.
- Bonding:Adhesion promotion for copper-clad laminates in 5G infrastructure substrates. Japanese laminate producers in Shizuoka prefecture specify low-dielectric-loss formulations for base station antenna modules.
- Surface Protection:Abrasion and chemical barriers for industrial equipment exposed to harsh environments.
- Electrical Components:Encapsulation of capacitors, resistors, and connectors for thermal cycling resistance.
Insulation Coating holds installed capacity. Bonding is rotating up the share rankings.
Technology:
Solvent toxicity and cure energy requirements are restructuring formulation R&D priorities.
- Water-Based:Polyamic acid dispersions eliminating N-methyl-2-pyrrolidone exposure. Automotive plants in Bavaria are retrofitting electrostatic spray lines to meet ECHA REACH registration deadlines and reduce volatile organic compound emissions.
- UV-Cured:Photoinitiated cyclization collapsing thermal cure cycles from hours to minutes. Korean display manufacturers are achieving eighteen-month equipment payback through tripled throughput rates.
- Solvent-Based:Conventional N-methylpyrrolidone solutions with established supply chains and proven reliability records.
- Electrostatic Spray:Application method optimization for uniform thin-film deposition on complex geometries.
Solvent-Based holds installed capacity. Water-Based is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Shanghai anchors East Asian polyimide varnish distribution, with dedicated chemical terminals handling N-methyl-2-pyrrolidone bulk imports for Jiangsu and Guangdong electronics clusters. European demand flows through Rotterdam's liquid bulk facilities, connecting German automotive wire harness plants to Asian monomer supply chains.
China
Flexible PCB manufacturers in Shenzhen and Dongguan consume half of regional polyimide varnish volumes for smartphone and tablet substrate production. MIIT's dual carbon goals are pressuring solvent-based coating operations toward water-based reformulation. The Yangtze River Delta cluster around Suzhou operates the world's densest concentration of copper-clad laminate bonding varnish lines.
Japan
Chubu region pyromellitic dianhydride producers supply aromatic monomers to global varnish formulators under METI chemical emissions guidelines. Kaneka Corporation's water-based precursor development exemplifies domestic response to tightening environmental rules. Osaka-based insulation specialists are qualifying formulations for 800V EV motor architectures bound for European export markets.
Germany
Baden-Württemberg automotive tier-one suppliers are building dedicated polyimide impregnation lines for traction motor stator windings under KBA safety oversight. ECHA REACH registration deadlines are accelerating solvent substitution investments across coating operations. Bavarian electrostatic spray plants are retrofitting lines to meet 2027 volatile organic compound reduction targets.
South Korea
Gyeonggi-do display panel producers are converting roll-to-roll coating lines to UV-cured polyimide precursors, collapsing thermal cure cycles from hours to minutes. MFDS chemical safety standards are shaping formulation disclosure requirements for electronics manufacturing. Seoul-based flexible substrate specialists are negotiating direct offtake agreements with Japanese monomer producers to secure batch-level purity certification.
United States
Michigan and South Carolina EV motor plants are qualifying Class 220 insulation systems under NHTSA thermal safety mandates. EPA air quality standards for N-methylpyrrolidone are pressuring coating operations toward solvent recovery investments. Aerospace wire harness manufacturers in Connecticut face the steepest compliance costs due to low-volume, high-purity FAA certification requirements.
Polyimide Varnish Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in monomer and precursor supply. The vendor base stratifies across three tiers: integrated chemical conglomerates with captive dianhydride production, independent formulators relying on merchant monomer supply, and regional coating operations serving single-industry niches. Dominant competitive moves include backward integration into pyromellitic dianhydride production and technology licensing for water-based formulation platforms.
Among Japanese chemical conglomerates, UBE Corporation and Kaneka Corporation occupy positions spanning monomer production through formulated varnish supply. DuPont anchors the North American premium tier, leveraging fluoropolymer heritage for thermal-resistant aerospace specifications. Mitsubishi Gas Chemical exemplifies the specialty chemical archetype, concentrating on high-purity aromatic intermediates for electronics-grade applications. These three represent distinct strategic postures: vertical integration, materials science platform extension, and intermediate specialization.
| Leading Market Players |
|---|
| DuPont |
| Elantas PDG |
| UBE Corporation |
| Suzhou Jufeng Electrical Insulating System |
| PI Advanced Materials |
| Mitsubishi Gas Chemical |
| Kaneka Corporation |
| Toray Industries |
| IST Corporation |
| Others |
Supply Flow & Price Mechanics
Jiangsu province's copper-clad laminate cluster concentrates solvent-based polyimide varnish capacity, granting integrated Japanese formulators outsized leverage over spot pricing for non-contract buyers in Guangdong's flexible PCB sector. This geographic concentration amplifies margin capture during N-methylpyrrolidone supply tightness, while water-based alternatives face cost penalties from electrostatic spray line retrofits.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates aerospace-grade fluorinated formulations from automotive EV motor grades and commodity electrical insulation. Price differentiation rests on UL 1446 thermal class certification and captive pyromellitic dianhydride supply. Cost compression in standard grades is intensifying because silicone-resin substitution narrows performance gaps below 180°C. Automotive tier-one suppliers exhibit highest price sensitivity due to volume procurement mandates, while aerospace wire harness manufacturers accept premium positioning for FAA-compliant flame-smoke-toxicity systems.
Supply Chain Analysis
Contract manufacturing concentration among Japanese Chubu region monomer producers and Korean Gyeonggi-do display panel coaters shapes procurement access for non-integrated formulators. Geographic supply concentration centers on Japan, China, and South Korea for aromatic dianhydride production and downstream varnish formulation. Raw material dependencies draw from petrochemical feedstocks for N-methylpyrrolidone and specialized pyromellitic dianhydride catalysts. Single-source vulnerability clusters around Japanese pyromellitic dianhydride output. Distribution runs through direct supplier relationships displacing traditional specialty chemical channels for high-volume electronics buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment. UL 1446 thermal class certification timelines and REACH registration windows create structural barriers that extend incumbent advantage over challengers lacking qualified formulation archives.
For Market Incumbents: Build certification-archive depth by accelerating water-based precursor qualification ahead of ECHA registration deadlines. Secure backward integration into pyromellitic dianhydride production to insulate margin structures from Japanese supplier concentration risk. Channel control through direct offtake agreements with Guangdong PCB laminate manufacturers reinforces switching-cost architecture against emerging Indian competitors. For New Entrants and Emerging Players: India's Gujarat and Tamil Nadu electronics manufacturing zones offer underpenetrated varnish formulation capacity as PLI scheme incentives attract semiconductor and display fabrication investments. Target domestic Indian supply to bypass established East Asian procurement relationships. A technical-service-heavy go-to-market model compensates for absence of qualified formulation archives by embedding application engineering with emerging EV motor plants. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialty chemical platforms with water-based formulation licensing capabilities over commodity solvent-based capacity. Long-term viability across the analysis window hinges on regulatory compliance architecture rather than scale economics alone. Acquisition target archetype: independent formulators with captive dianhydride supply and active ECHA registration pipelines. Monitor Japanese METI chemical emissions guideline revisions as inflection indicator for accelerated solvent substitution timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Captive pyromellitic dianhydride production insulates margins from Chubu region supply shocks. |
| Water-Based Formulation Transition | ECHA REACH deadlines in Bavaria and Baden-Württemberg accelerate electrostatic spray line retrofits. |
| Direct Supplier Relationship | Guangdong PCB manufacturers negotiate multi-year offtake agreements bypassing distribution markups. |
| UV-Cured Technology Licensing | Korean display producers achieve eighteen-month equipment payback through tripled throughput rates. |
| Indian Manufacturing Partnership | Gujarat and Tamil Nadu PLI incentives attract formulation capacity for underserved domestic electronics clusters. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with varnish formulation chemists, automotive tier-one procurement directors, PCB laminate plant managers, and aerospace wire harness quality engineers. Secondary validation drew from EPA air quality enforcement records, ECHA REACH registration databases, SEC 10-K chemical segment disclosures, and Japanese METI chemical production statistics. Bottom-up volume estimates from individual coating line capacities were triangulated against top-down value projections from trade flow analysis.
Calibration against historical thermal class qualification timelines and solvent substitution program announcements anchored projection parameters across the analysis window. Segmentation dimensions modeled include thermal resistance grade, end-use industry, cure chemistry technology, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand curves incorporating EV motor insulation mandates and 5G infrastructure deployment schedules. Industry-specific forecast inputs encompass NHTSA traction motor safety rule adoption curves and ECHA substance restriction timeline enforcement patterns.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese state-backed chemical conglomerates or accelerated silicone-resin substitution programs would shift outcomes beyond modeled ranges. Quarterly review of ECHA registration window progress, Japanese pyromellitic dianhydride export volumes, and Indian PLI scheme disbursement rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Biocides for Leather Market
Specialty Chemicals
Catharanthine Market
Specialty Chemicals
Europe Non-Phthalate Plasticizers Market
Specialty Chemicals
Allantoin Market
Specialty Chemicals
Sizing and Thickening Market
Specialty Chemicals
Specialty Oxidants Market
Specialty Chemicals
Methyltrimethoxysilane Market
Specialty Chemicals
4-Benzoylbutyric Acid Market
Specialty Chemicals
UV/IR Blocker Market
Specialty Chemicals
Multimodal Chromatography Columns Market
Specialty Chemicals
Global Release Agents Market
Specialty Chemicals
Global Anti-Static Agents Market
Specialty Chemicals
Methyl Salicylate Market
Specialty Chemicals
Cellulose Ether Market
Specialty Chemicals
Microcrystalline Wax Market
Specialty Chemicals
Middle East and Africa Amino Acids Market